
 Motorized Decoiler Machine Market | 2026-2036
Motorized Decoiler Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Motorized Decoiler Machine Market Outlook
High-torque servo-controlled specifications is reorganizing competitive dynamics among motorized decoiler suppliers. The Bradbury Co., Inc. leverages its integrated roll forming ecosystem to bundle decoilers with downstream line equipment. Heinrich Georg GmbH anchors premium positioning through precision tension control systems for automotive strip processing. Schuler AG dominates large-capacity installations serving OEM press shops across European automotive corridors.
A motorized decoiler machine is an electromechanical unwinding apparatus that maintains controlled tension on coiled metal strip, typically handling coil weights from 500 kg to 30 tonnes at line speeds up to 200 m/min, feeding continuous material into stamping presses, roll formers, or cut-to-length lines. Electric decoilers are capturing share from hydraulic alternatives as manufacturers prioritize energy efficiency and precise speed synchronization with servo feeds. Automotive end users represent the densest margin pool, with Tier-1 Suppliers driving volume through standardized platform specifications while OEMs demand custom-built integrated lines for proprietary stamping operations.
EU machinery directives under CE marking and the EU Green Deal's energy efficiency mandates are reshaping motor and drive system requirements for decoiler equipment sold into Europe. China's SAMR enforces GB standards on industrial machinery safety that affect decoiler guarding and emergency stop protocols in domestic and export-bound production. India's BIS certification requirements for imported metalworking machinery are tightening market access conditions. Stakeholders must monitor how regional efficiency mandates and safety standard convergence affect platform development costs and retrofit obligations across their installed base.
Market Dynamics
Servo-controlled torque management systems are compressing the performance gap between mid-tier and premium decoiler equipment, forcing suppliers to differentiate through integrated line architecture rather than standalone mechanical specifications.
Growth Catalysts
- EU Green Deal energy mandates:The directive tightens motor efficiency thresholds for industrial equipment sold into European automotive stamping corridors, accelerating replacement cycles in Germany's Ruhr industrial belt.
- Automotive OEM platform standardization:Tier-1 suppliers are consolidating decoiler specifications across multi-site stamping operations, creating volume pull for standardized high-torque models serving Volkswagen and BMW supply chains.
- China's Yangtze River Delta cluster expansion:Metalworking capacity additions in Jiangsu and Zhejiang provinces are driving concentrated demand for 15-30 tonne capacity decoilers with automated coil car integration.
Market Restraints
- Copper and rare-earth magnet cost volatility:Permanent magnet servo motors depend on neodymium supply concentrated in Chinese processing facilities, creating input cost uncertainty for torque-dense decoiler designs.
- CE marking compliance complexity:The EU machinery directive's 2023 updates to guarding and emergency stop protocols impose documentation burdens that extend sales cycles for non-European suppliers.
- Hydraulic system residual value:Existing installed base of hydraulic decoilers in mature automotive press shops creates inertia against electric conversion despite operating cost advantages.
Strategic Opportunities
- India's PLI scheme for automotive manufacturing:Production-linked incentives for component localization are attracting stamping line investments in Tamil Nadu and Gujarat, opening white space for decoiler vendors without established local presence.
- Retrofit servo drive kits:Modular torque control upgrades allow Tier-2 metalformers to extend mechanical decoiler life while achieving precision synchronization with modern servo feeds.
- Cloud-based predictive maintenance:Vibration and torque monitoring via industrial IoT platforms enables service contract monetization and reduces unplanned downtime for high-volume automotive stampers.
Industry Challenges
- Servo tuning expertise scarcity:Field service engineers capable of calibrating closed-loop tension control across varying coil metallurgy and thickness ranges command premium compensation and limit vendor scaling.
- Legacy press line integration:Mechanical decoilers from 1990s-era installations often lack compatible control interfaces, forcing costly custom engineering for hybrid line configurations.
- ISO 13849 safety certification timelines:Validation of programmable safety controllers for decoiler guarding systems extends product development cycles by 8-14 months for new platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorized Decoiler Machine Market |
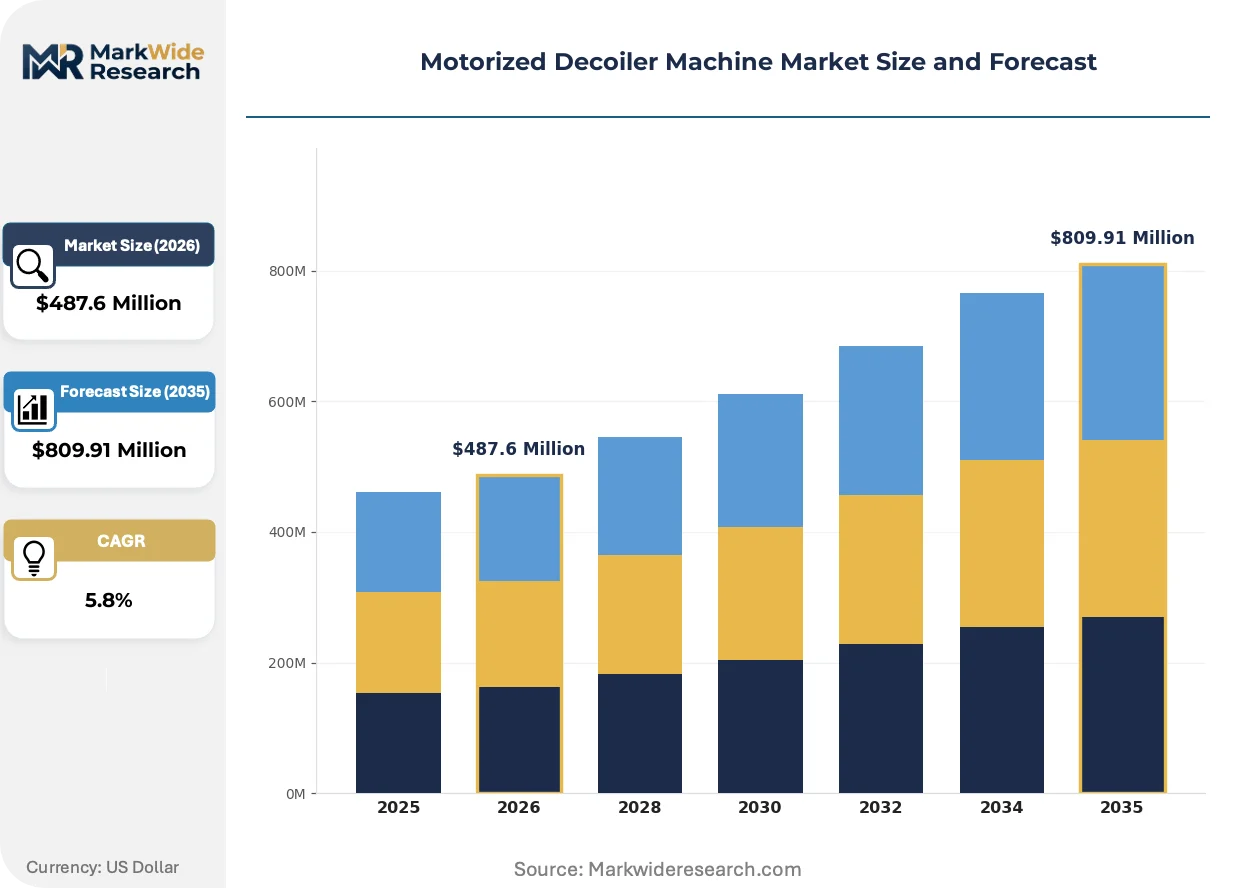
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Decoiler, Electric Decoiler, Manual Decoiler, Automatic Decoiler Industry Vertical: Manufacturing, Automotive, Aerospace, Metalworking End User: OEMs, Tier-1 Suppliers, Contract Manufacturers, Fabricators Installation Type: Standalone, Integrated, Custom-Built, Portable |
| Companies Covered | The Bradbury Co., Inc., KMT Maschinenbau, COE Press Equipment, Heinrich Georg GmbH, Schuler AG, Formtek Group, Dimeco Group, Red Bud Industries, Samco Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorized Decoiler Machine Market Strategic Shifts
Digital torque sensing and edge-computing control architectures are redefining performance benchmarks across the motorized decoiler category. These advances compress setup times while enabling real-time adaptation to coil variability.
Brushless permanent magnet servo motors with integrated encoders are fragmenting the traditional distinction between standard and precision decoiler tiers. Automotive stampers in Stuttgart and Wolfsburg are specifying these drives for lines running advanced high-strength steels. The technology is fragmenting supplier margins by collapsing the premium pricing umbrella that once shielded German and Japanese torque-control specialists.
China's GB standards enforcement through SAMR is tightening emergency-stop response time requirements for industrial machinery. Domestic manufacturers in Suzhou and Ningbo are accelerating redesigns to meet sub-500-millisecond braking specifications. Export-oriented suppliers face parallel compliance obligations for equipment bound to European automotive OEMs with dual-certificate requirements.
Stamping shops are unbundling after-sales service from capital equipment purchases, preferring subscription-based preventive maintenance to traditional warranty extensions. Tier-1 suppliers in Detroit and Chattanooga are negotiating multi-year service agreements with uptime guarantees rather than per-incident repair contracts. This shift is most pronounced in North American automotive corridors where line utilization rates exceed 85 percent.
Motorized Decoiler Machine Market Segmentation
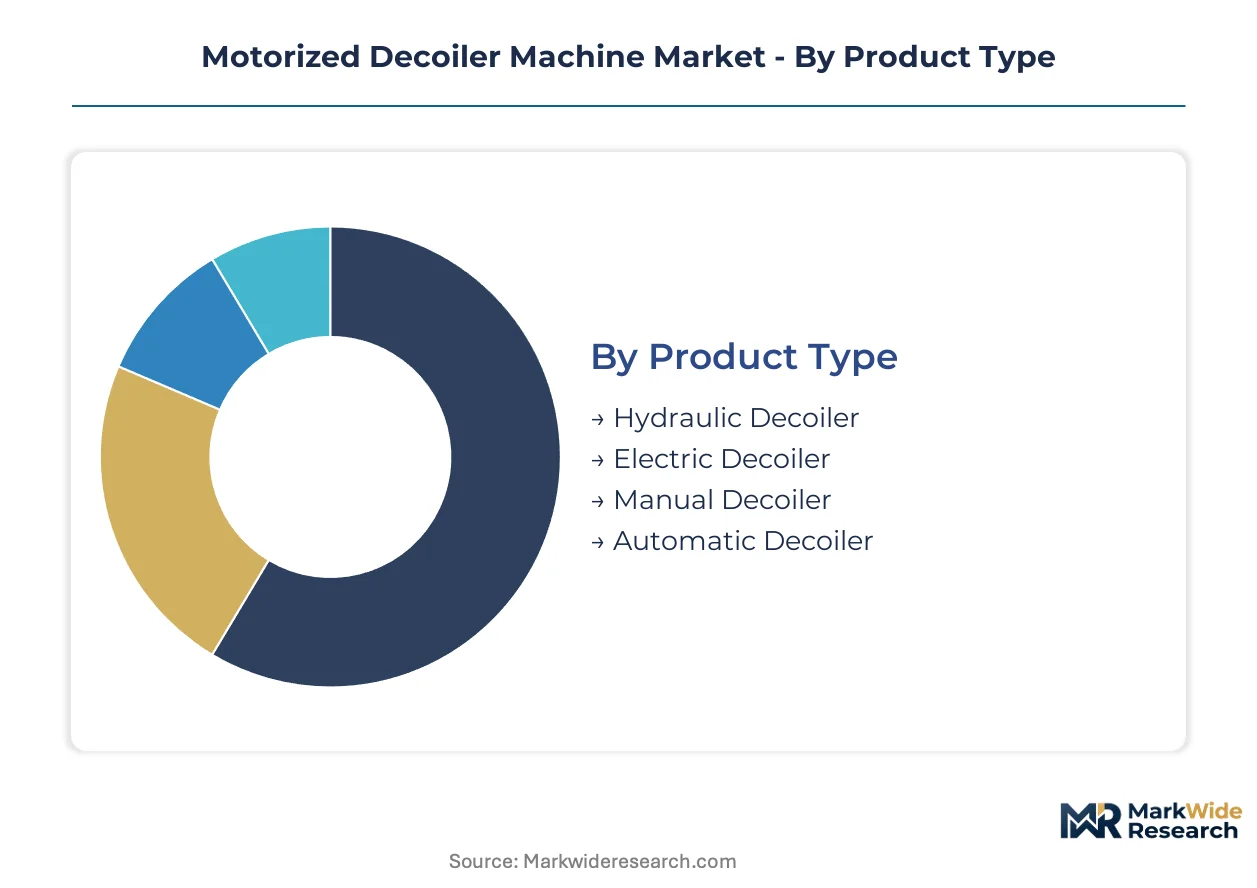
Motorized decoiler configurations diverge sharply across torque density requirements and automation integration depth. Regulatory pressure on energy efficiency and safety guarding reshapes how each segment captures value across automotive stamping corridors and metalworking clusters.
Product Type:
CE marking under EU machinery directives and China's GB standards through SAMR enforce divergent motor efficiency and emergency-stop protocols across hydraulic and electric architectures.
- Electric Decoiler:Brushless permanent magnet servo motors with integrated encoders deliver precise tension control for advanced high-strength steel processing. Stuttgart and Wolfsburg automotive stampers specify these drives for lines requiring synchronization with servo feeds at speeds up to 200 m/min.
- Hydraulic Decoiler:Fluid power systems retain installed base dominance in mature press shops where capital replacement cycles lag operating cost advantages. Ruhr industrial belt facilities face EU Green Deal mandates accelerating displacement despite residual asset value.
- Automatic Decoiler:Coil car integration and automated threading reduce setup intervals for high-changeover environments.
- Manual Decoiler:Low-capacity units serve job shops and prototype fabrication with minimal automation requirements.
Electric decoilers handle the majority of new order throughput; automatic configurations are expanding most quickly on share as Yangtze River Delta metalworking clusters prioritize labor reduction.
Industry Vertical:
End-use concentration determines specification intensity, with automotive OEMs demanding custom integrated lines while metalworking fabricators prioritize standardized platform economics.
- Automotive:Tier-1 suppliers consolidate decoiler specifications across multi-site stamping operations serving Volkswagen and BMW supply chains. Precision tension control systems process advanced high-strength steels for lightweighting programs.
- Metalworking:Jiangsu and Zhejiang province capacity additions drive concentrated demand for 15-30 tonne capacity units with automated coil car integration in cut-to-length and slitting operations.
- Manufacturing:General industrial applications span appliance, electronics, and construction material production with moderate torque requirements.
- Aerospace:Titanium and aluminum strip processing demands ultra-precise tension control for thin-gauge material handling.
Automotive commands the densest margin pool; metalworking delivers the steepest expansion trajectory as China's industrial cluster investments accelerate.
End User:
Procurement authority and technical specification control separate OEM direct purchases from supplier-tier volume aggregation.
- Tier-1 Suppliers:Standardized platform specifications across multi-site operations create volume pull for high-torque electric models with integrated safety controllers.
- OEMs:Proprietary stamping operations demand custom-built integrated lines with dedicated engineering resources and extended validation cycles.
- Contract Manufacturers:Flexible capacity requirements favor modular configurations with rapid changeover capabilities.
- Fabricators:Price-sensitive procurement prioritizes standalone units over integrated line architectures.
Tier-1 suppliers concentrate equipment throughput; contract manufacturers are climbing the fastest on share as automotive outsourcing deepens.
Installation Type:
System architecture determines field service complexity and aftermarket revenue capture potential across deployment models.
- Integrated:Decoilers bundled with downstream roll formers, servo feeds, and press lines dominate European automotive corridor investments requiring synchronized control architectures.
- Custom-Built:OEM proprietary lines in Detroit and Chattanooga specify dedicated engineering for hybrid configurations with legacy press integration.
- Standalone:Independent units serve retrofit applications and job shops with existing line infrastructure.
- Portable:Mobile configurations address temporary capacity needs and construction-site metal forming.
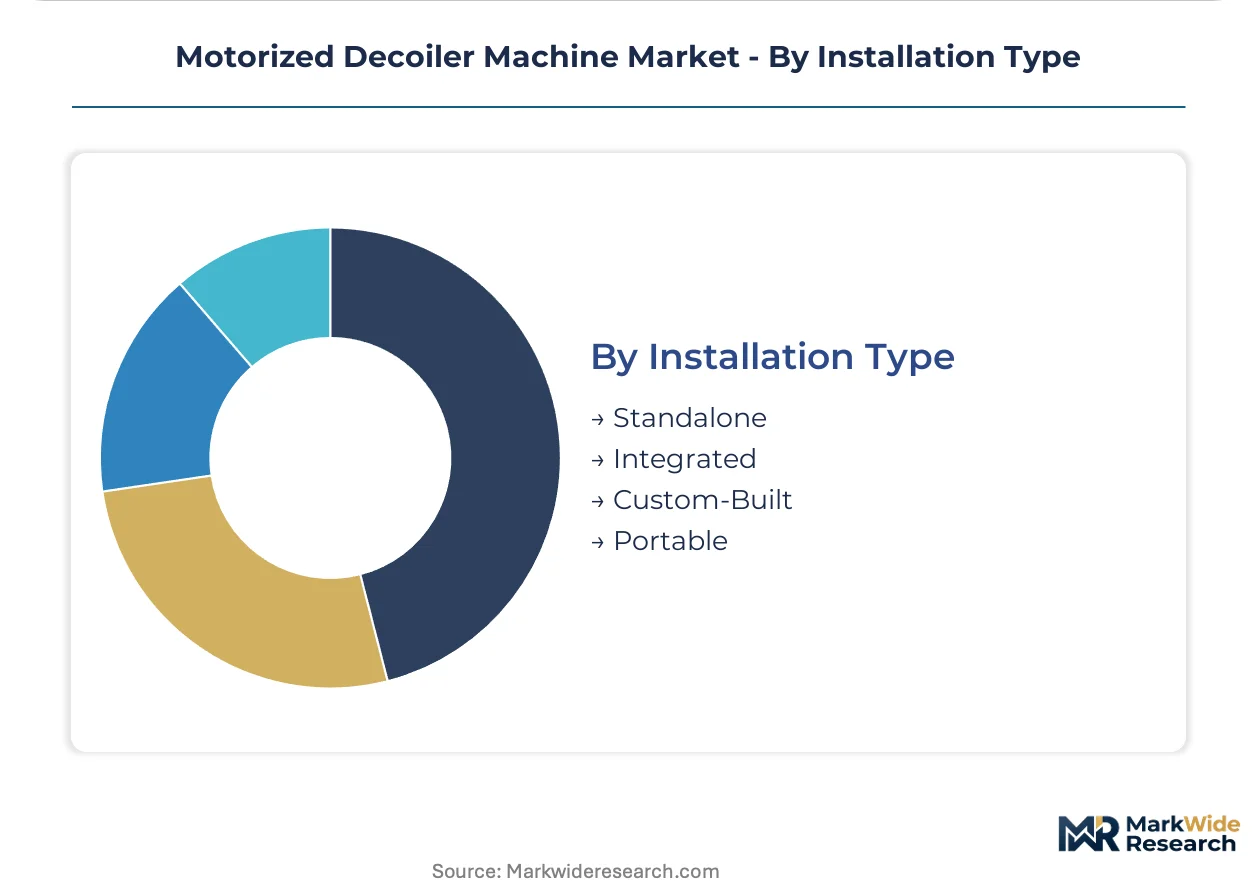
Integrated installations handle the majority of capital deployment; custom-built lines are gaining share fastest as OEMs insource critical stamping operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing clusters for motorized decoilers concentrate in Germany's automotive belt, China's Yangtze River Delta metalworking corridor, and the US Southeast stamping region. These three countries anchor supply-side capacity while setting divergent regulatory baselines for torque control and safety guarding systems.
Germany
Automotive OEMs in Stuttgart and Wolfsburg drive precision stamping line investments requiring servo-controlled tension systems. EU Green Deal energy efficiency mandates through CE marking tighten motor efficiency thresholds for equipment sold into Ruhr industrial belt facilities. Baden-Württemberg's metalworking cluster sees accelerated replacement cycles as Tier-1 suppliers consolidate multi-site specifications.
China
Yangtze River Delta capacity additions in Jiangsu and Zhejiang provinces generate concentrated demand for 15-30 tonne automated decoiler configurations. SAMR enforcement of GB standards on emergency-stop response times below 500 milliseconds forces redesigns among Suzhou and Ningbo manufacturers. Domestic suppliers capture share in metalworking clusters while export-oriented producers face dual-certificate obligations for European automotive clients.
United States
Tier-1 automotive suppliers in Detroit and Chattanooga negotiate multi-year service agreements with uptime guarantees exceeding 85 percent line utilization. OSHA machinery guarding standards intersect with customer-mandated safety protocols from Volkswagen and BMW supply chain audits. Southeast stamping corridor investments favor integrated line architectures bundling decoilers with downstream servo feeds.
India
PLI scheme incentives for automotive component localization attract stamping line investments in Tamil Nadu and Gujarat manufacturing zones. BIS certification requirements for imported metalworking machinery tighten market access conditions for foreign equipment vendors. Domestic fabricators in Pune and Chennai expand cut-to-length capacity using mid-tier electric decoiler configurations.
Motorized Decoiler Machine Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the motorized decoiler category. The vendor base organizes into three tiers: integrated line specialists commanding premium positioning, regional fabricators competing on delivery speed and customization flexibility, and emerging Asian manufacturers scaling through standardized platform economics. Dominant competitive moves include vertical integration into downstream roll forming equipment and geographic expansion through distribution partnerships in underserved automotive corridors.
Within the integrated line specialist tier, Schuler AG and Heinrich Georg GmbH exemplify precision-focused positioning anchored in European automotive supply relationships. KMT Maschinenbau occupies a position among mid-scale German fabricators serving regional metalworking demand. The Bradbury Co., Inc. represents North American bundled-equipment strategy, leveraging roll forming ecosystem integration to capture downstream line economics. COE Press Equipment and Red Bud Industries sit within the North American mid-tier, competing on custom engineering capabilities for hybrid legacy press configurations.
| Leading Market Players |
|---|
| The Bradbury Co., Inc. |
| KMT Maschinenbau |
| COE Press Equipment |
| Heinrich Georg GmbH |
| Schuler AG |
| Formtek Group |
| Dimeco Group |
| Red Bud Industries |
| Samco Machinery |
| Others |
Value Chain & Pricing Dynamics
Long-term service contracts with uptime guarantees anchor procurement relationships between Tier-1 automotive suppliers and decoiler vendors, locking in supply access while flattening price volatility across multi-year engagements in Detroit and Chattanooga stamping corridors.
Pricing Analysis
CE marking under EU machinery directives dictates the pricing tier structure across motorized decoiler equipment. Three-tier pricing structure across premium, standard, and economy levels separates integrated line specialists from regional fabricators and emerging Asian manufacturers. Price differentiation rests on ISO 13849 safety certification grade and after-sales service bundling intensity. Cost compression in mid-tier electric configurations is intensifying because brushless servo motor commoditization erodes mechanical differentiation. Fabricators exhibit highest price sensitivity; OEMs purchasing custom-built integrated lines show lowest sensitivity due to engineering validation requirements.
Supply Chain Analysis
Neodymium processing concentration in Chinese refining facilities creates a chokepoint for permanent magnet servo motors specified in high-torque decoiler designs. Component sourcing draws from Germany for precision tension control systems, China for motor drives and structural fabrication, and Japan for encoder and sensor modules. Raw material dependencies include copper windings, rare-earth magnets, and high-grade steel for coil mandrels. Single-source vulnerability in magnet supply chains exposes torque-dense equipment manufacturers to input cost volatility. Distribution runs through direct OEM procurement teams for integrated lines and regional distributor networks for standalone retrofit units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes the motorized decoiler category as automotive OEMs accelerate platform standardization and China's Yangtze River Delta metalworking clusters drive capacity additions requiring automated coil handling systems.
For Market Incumbents: Compound defensive positioning through backward integration into servo drive manufacturing to capture margin compression from motor commoditization, while embedding cloud-based predictive maintenance capabilities to monetize service contracts and raise switching costs against emerging Asian competitors threatening standardized platform economics. For New Entrants and Emerging Players: Anchor in India's PLI scheme corridors around Tamil Nadu and Gujarat where BIS certification barriers have slowed established vendor penetration, targeting mid-tier electric decoiler configurations for contract manufacturers seeking flexible capacity with rapid changeover capabilities and modular retrofit servo drive kits. For Investors and Strategic Acquirers: Regional fabricators with custom engineering capabilities for hybrid legacy press configurations represent attractive acquisition targets as OEM insourcing trends accelerate demand for bespoke integrated line architectures. Long-term viability frames around 5-10 year service contract monetization and aftermarket parts capture. Monitor CE marking documentation burden timelines as inflection indicator for non-European supplier displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Drive Manufacturing | Captures margin erosion from motor commoditization while tightening control over torque calibration IP. |
| Cloud-Based Predictive Maintenance Platform Launch | Enables subscription revenue streams with automotive stampers demanding 85 percent uptime guarantees. |
| CE Marking and GB Standards Dual Certification | Unlocks European automotive OEM procurement and Yangtze River Delta export opportunities simultaneously. |
| Retrofit Servo Drive Kit Development | Extends addressable market to Tier-2 metalformers seeking precision synchronization without capital replacement. |
| Joint Venture with India's Domestic Fabricators | Accelerates BIS certification navigation and local assembly capacity for PLI scheme contract capture. |
Study Parameters
The analysis maps electric, hydraulic, automatic, and manual decoiler configurations, each validated through maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads at Tier-1 suppliers and metalworking fabricators. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, customs and trade data for coil handling equipment, and industry association reports from metalforming technology institutes. Bottom-up unit economics triangulated against top-down market sizing across product type, industry vertical, end user, and installation type segmentation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled torque density requirements, automation integration depth, and regional regulatory cluster adoption patterns. CAGRs derived from segment-level growth rate synthesis weighted by automotive OEM capital expenditure cycles and metalworking capacity investment trajectories. Forecast inputs incorporated EU Green Deal motor efficiency mandate compliance costs and SAMR GB standards enforcement timelines affecting platform development cycles.
Material uncertainties — rare-earth magnet supply disruptions, CE marking protocol revisions, and automotive platform consolidation shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding standard adoption curves and replacement cycle acceleration. Practitioners should keep alternative scenarios live as China's dual carbon goals and India's PLI scheme disbursement rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Bulk Material Handling Products and Technologies Market
Material Handling Equipment
Australia Forklift Rental Market
Material Handling Equipment
Cherry Picker Forklift Market
Material Handling Equipment
Global Metal Shredder Machine Market
Material Handling Equipment
Global Industrial Lifting Equipment Market
Material Handling Equipment
Pug Mill Mixers Market
Material Handling Equipment
Crushing Screening Equipment Market
Material Handling Equipment
Dry Bulk Handling System Market
Material Handling Equipment
Industrial Bag Dust Filter Market
Material Handling Equipment
Elevator Ropes Market
Material Handling Equipment
Gantry Crane Market
Material Handling Equipment
Wagon Tipplers Market
Material Handling Equipment
Global Hopper Loader Market
Material Handling Equipment
Telescopic Crane Market
Material Handling Equipment
East Africa Elevator and Escalator Market
Material Handling Equipment
Global Metal Expansion Joints Market