
 Air Hose Market | 2026-2036
Air Hose Market Size, Share, and Industry Trends Forecast 2026-2036
Air Hose Market Analytics
ISO 2398 certification for rubber air hoses is unwinding the competitive set, forcing smaller compounders to either upgrade testing infrastructure or exit industrial supply chains. Continental leverages captive polymer blending capacity across German and Chinese plants to sustain margin on high-pressure constructions. Gates Corporation anchors North American aftermarket channels through distributor exclusivity agreements with fleet maintenance networks.
An air hose is a flexible, reinforced conduit manufactured from extruded elastomer or thermoplastic compounds, typically rated for working pressures between 150 and 500 psi, engineered to convey compressed air from stationary compressors to pneumatic tools, actuators, and spray equipment. Rubber constructions still dominate heavy manufacturing applications where abrasion resistance and temperature tolerance justify material cost, while polyurethane formulations are capturing share in automotive final assembly for their lighter weight and tighter bend radius. The 3/8 inch and 1/2 inch diameter categories occupy the thickest margin pools because they balance flow capacity with handling ergonomics across construction and industrial end users.
EPA enforcement of volatile organic compound limits on hose manufacturing affects compound selection and curing processes in United States-based production. REACH substance restrictions in Europe, administered by ECHA, are phasing out certain plasticizers and accelerators used in PVC and rubber hose formulations, redirecting formulation R&D toward bio-based plasticizers and peroxide curing systems. ISO, OSHA, and ECHA frameworks collectively determine which compound technologies qualify for cross-border supply contracts. Stakeholders must monitor how rapidly Chinese GB standards converge with ISO pressure ratings, as divergence would fragment tooling compatibility and force parallel inventory strategies.
Market Dynamics
Supplier consolidation around certified compound producers in China's eastern manufacturing corridor is compressing pricing power for uncertified regional manufacturers while elevating technical barriers to cross-border contract qualification.
Growth Catalysts
- Automotive fleet expansion:Assembly plants in Mexico and Southeast Asia are scaling pneumatic tool deployments, generating pull-through demand for 3/8 inch and 1/2 inch diameter constructions rated for 150-500 psi working pressures.
- REACH compliance deadlines:ECHA substance restrictions are redirecting formulation R&D toward bio-based plasticizers and peroxide curing systems, creating first-mover advantage for compounders with upgraded testing infrastructure.
- ISO 2398 certification:The standard is forcing smaller compounders to exit industrial supply chains, concentrating volume among producers with captive polymer blending capacity.
Market Restraints
- Raw material volatility:Synthetic rubber and specialty polymer feedstocks face price instability tied to petrochemical supply fluctuations, compressing margin on high-pressure hose constructions.
- Geographic supply concentration:Certified compound production clusters in Germany and China create vulnerability to regional logistics disruptions or trade policy shifts affecting cross-border tooling compatibility.
- Substitution pressure:Thermoplastic polyurethane formulations are capturing automotive final assembly share from rubber constructions where lighter weight and tighter bend radius outweigh abrasion resistance requirements.
Strategic Opportunities
- Underpenetrated Southeast Asian manufacturing:Vietnam and Indonesia industrial zones lack established certified hose supply chains, creating entry points for producers with ECHA-aligned formulations.
- EPA regulatory tailwind:Enforcement of volatile organic compound limits on United States-based production favors domestic compounders with compliant curing processes over importers facing compliance lag.
- Channel digitization:Fleet maintenance networks are consolidating procurement through distributor exclusivity platforms, enabling direct technical specification lock-in with end users.
Industry Challenges
- Certification timeline compression:ISO 2398 testing infrastructure upgrades require 18-24 month capital deployment cycles, straining mid-tier compounders facing immediate contract qualification deadlines.
- Formulation IP complexity:REACH-compliant bio-based plasticizer patents are concentrated among German and Japanese chemical suppliers, creating licensing friction for independent hose manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Hose Market |
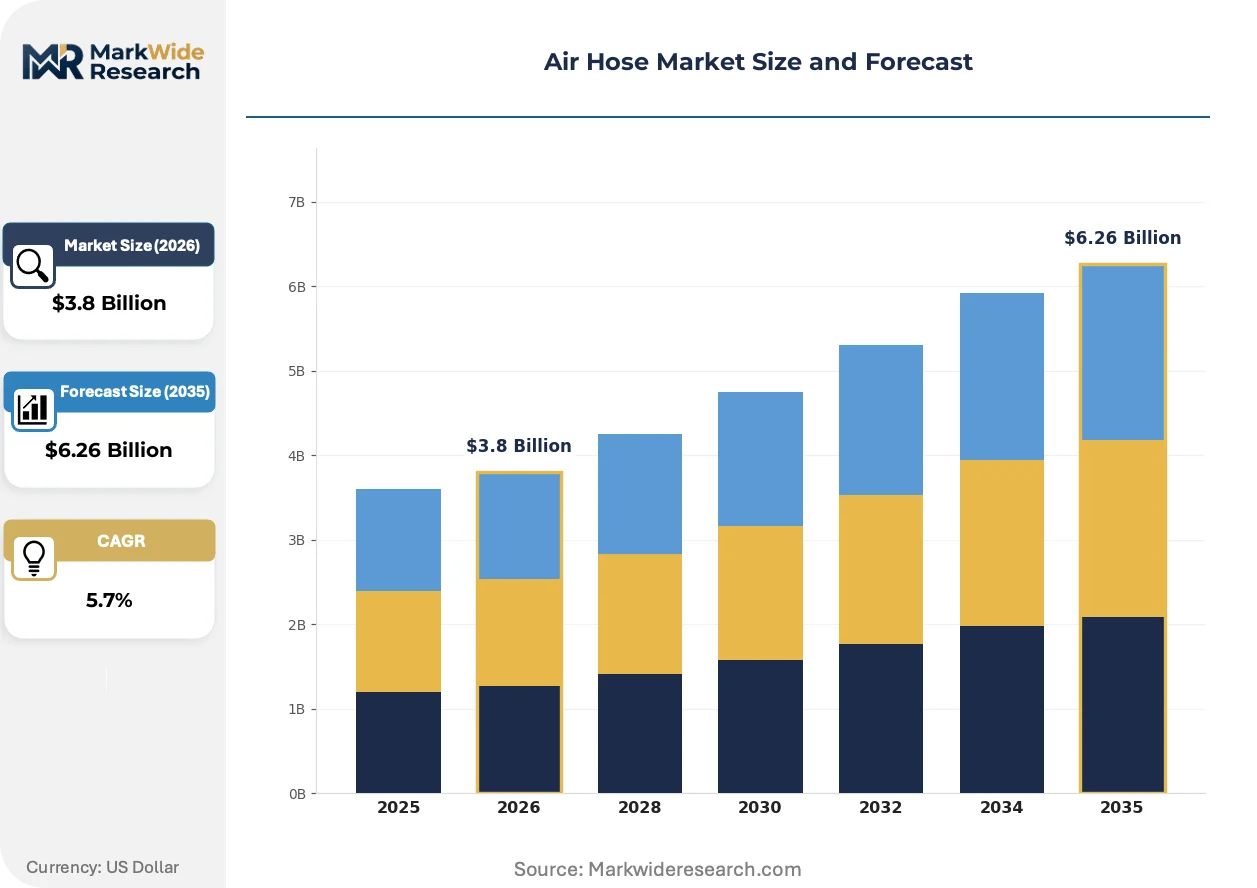
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Rubber, PVC, Nylon Application: Automotive, Construction, Manufacturing, Aerospace Size: 3/8 inch, 1/4 inch, 1/2 inch, 3/4 inch End User: Industrial, Commercial, Residential, Agricultural |
| Companies Covered | Continental, Gates Corporation, Parker Hannifin, Eaton Corporation, Flexzilla, Goodyear Rubber Products, Dixon Valve & Coupling Company, Kuriyama of America, Anchor Rubber Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Hose Market Evolving Landscape
Material science convergence with regulatory chemistry is redefining compound performance benchmarks while procurement centralization among fleet operators is reshaping channel economics.
Peroxide curing systems for synthetic rubber compounds are replacing sulfur-based accelerators phased out under REACH restrictions. Tier-one automotive suppliers in Germany and Japan are qualifying these constructions for under-hood pneumatic applications. The technology is miniaturizing batch-to-batch variability, enabling tighter tolerance specifications for high-pressure assemblies.
ECHA enforcement of plasticizer substance restrictions is eliminating certain phthalate formulations from PVC hose compounds used in European industrial distribution. Compounders with bio-based alternatives are securing multi-year supply agreements with German automotive OEMs. Construction-grade rubber hoses face delayed compliance timelines due to abrasion resistance requirements that current bio-based formulations cannot satisfy.
Fleet maintenance networks are consolidating pneumatic tool procurement through distributor exclusivity agreements that bundle hose replacement schedules with compressor service contracts. Construction and industrial end users in the United States are migrating from spot purchasing to multi-year technical supply agreements. This consolidation is most visible in North American aftermarket channels where Gates Corporation anchors coverage through maintenance network partnerships.
Air Hose Market Segmentation
Air hose procurement decisions pivot on pressure ratings, chemical compatibility, and regulatory compliance rather than brand preference alone. Compound selection determines which segments qualify for cross-border contracts under REACH, EPA, and ISO frameworks.
Product Type:
REACH substance restrictions and EPA volatile organic compound limits are fragmenting qualification pathways by compound chemistry.
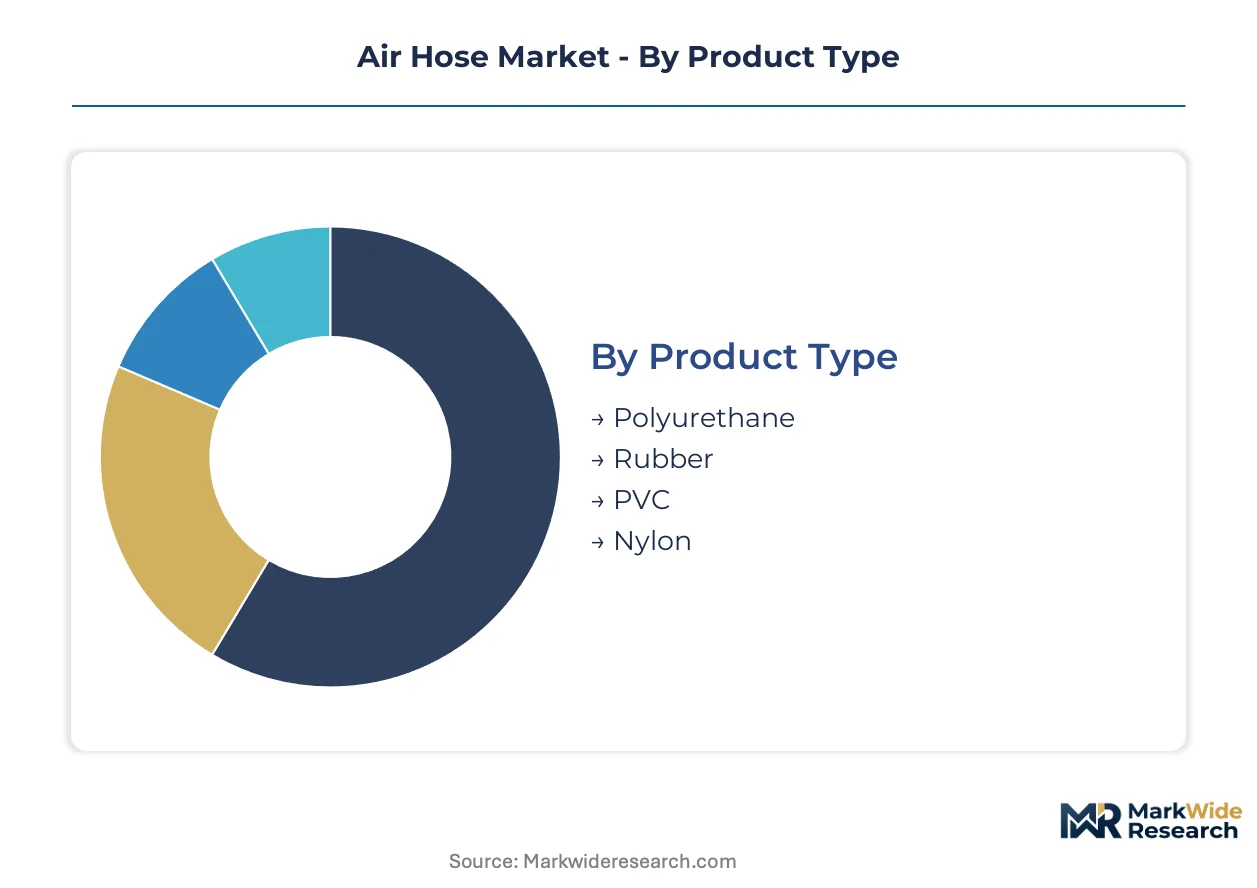
- Rubber:Synthetic elastomer constructions reinforced with textile or wire braiding withstand temperatures exceeding 200°F and resist abrasion in heavy manufacturing environments. German automotive OEMs and Chinese construction equipment fleets specify sulfur-cured or peroxide-cured rubber hoses for ISO 2398 compliance. REACH phase-out of certain accelerators is redirecting formulation R&D toward peroxide curing systems.
- Polyurethane:Thermoplastic elastomer extrusions offer 40% weight reduction versus rubber equivalents and bend radii tight enough for robotic routing in automotive final assembly. Southeast Asian automotive plants in Thailand and Vietnam are scaling polyurethane deployments for ergonomic handling alongside pneumatic tool fleets.
- PVC:Plasticized polyvinyl chloride compounds serve light-duty commercial and residential applications where cost sensitivity outweighs temperature tolerance. ECHA restrictions on phthalate plasticizers are eliminating certain European formulations.
- Nylon:Semi-crystalline polyamide constructions deliver high pressure ratings with minimal wall thickness for aerospace pneumatic systems and compact industrial machinery. Japanese precision equipment manufacturers specify nylon for space-constrained installations.
Rubber handles the majority of throughput; polyurethane is expanding most quickly on share.
Application:
End-use specifications diverge sharply on pressure cycling frequency, chemical exposure, and certification requirements.
- Automotive:Assembly plants in Mexico, Thailand, and Germany require hoses rated for 150-500 psi with tight bend radii for robotic tool positioning. Tier-one suppliers qualify constructions under ISO 2398 and OEM-specific durability protocols.
- Construction:Pneumatic nailers, concrete vibrators, and demolition tools demand abrasion-resistant rubber constructions with crush-resistant couplings. United States infrastructure spending is concentrating demand in Texas and Florida metropolitan construction corridors.
- Manufacturing:General industrial pneumatic systems prioritize interchangeability and inventory standardization across 3/8 inch and 1/2 inch diameters. Chinese eastern manufacturing corridor procurement is consolidating around certified compound producers.
- Aerospace:FAA-certified assemblies for aircraft ground support and MRO operations require flame-resistant compounds with traceable batch documentation. Qualification timelines extend 18-24 months.
Automotive commands the thickest margin pool; construction delivers the highest unit volume.
Size:
Flow capacity and handling ergonomics trade off across diameter categories, with procurement patterns clustering around tool compatibility standards.
- 3/8 inch:The dominant specification for general industrial pneumatic tools balances air delivery with maneuverability. Mexican automotive assembly plants and United States construction fleets standardize on this diameter for inventory rationalization.
- 1/2 inch:Higher flow capacity serves high-consumption tools like impact wrenches and sandblasting equipment in heavy manufacturing and shipyard applications. German industrial distributors stock this diameter for MRO replacement demand.
- 1/4 inch:Compact diameter for precision instruments, spray guns, and small assembly tools where hose bulk impedes operator dexterity. Japanese electronics manufacturing specifies 1/4 inch for cleanroom pneumatic systems.
- 3/4 inch:Large-bore constructions for high-volume compressed air distribution and stationary equipment feed lines. Chinese steel mills and petrochemical plants deploy 3/4 inch hoses for main line extensions.
3/8 inch handles the majority of throughput; 1/2 inch is climbing the fastest on specification upgrades.
End User:
Procurement sophistication and compliance sensitivity stratify sharply across customer categories.
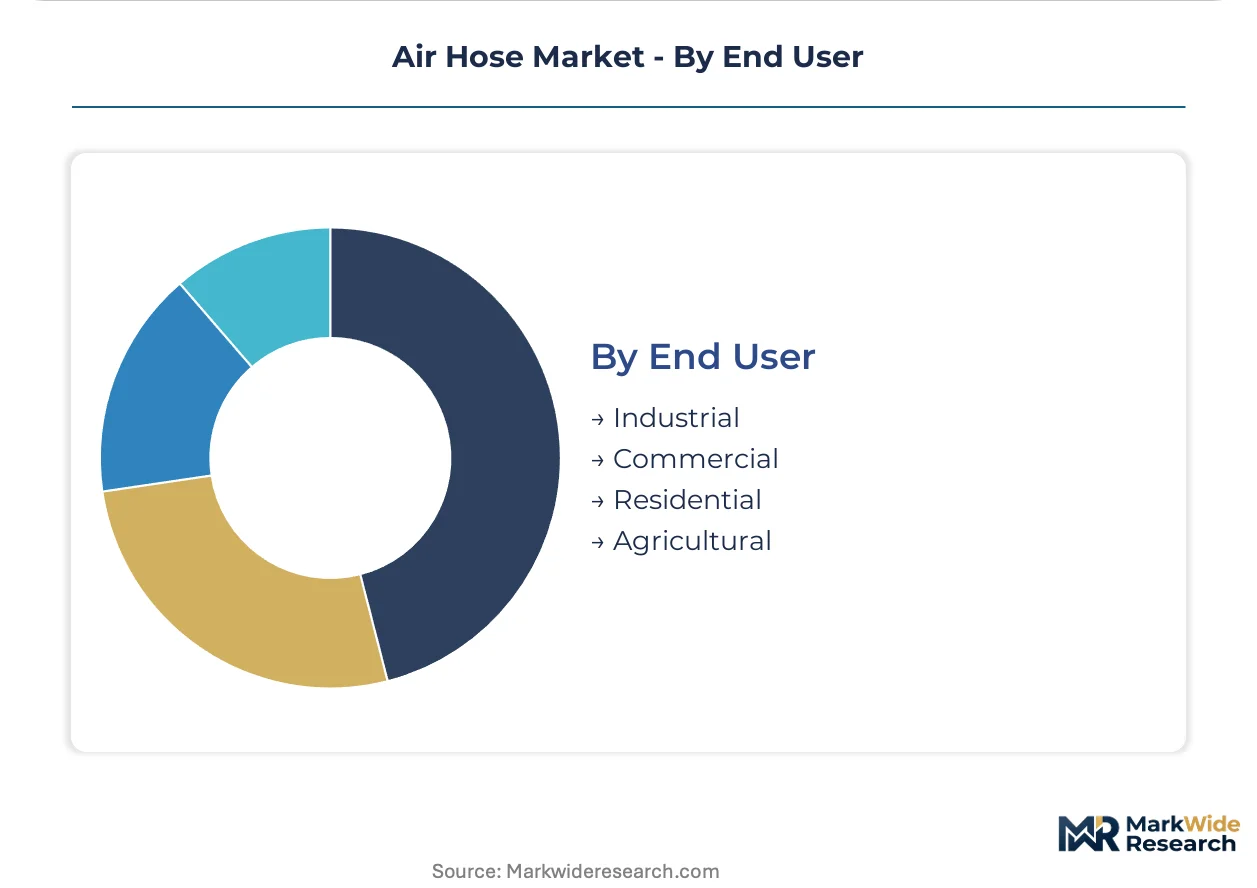
- Industrial:Fleet operators with centralized maintenance programs negotiate multi-year technical supply agreements bundling hose replacement schedules with compressor service contracts. United States fleet maintenance networks are consolidating procurement through distributor exclusivity platforms.
- Commercial:Small contractors and service businesses purchase through retail and distribution channels with spot-buying patterns and price sensitivity. Indonesian and Vietnamese construction markets lack established certified supply chains.
- Residential:DIY consumers and home workshop owners prioritize retail availability and price over performance specifications. E-commerce channels are capturing share from hardware store distribution.
- Agricultural:Farm equipment pneumatic systems for implements and grain handling require UV-resistant and weatherproof constructions. Brazilian and Australian agricultural equipment dealers specify agricultural-grade compounds.
Industrial captures the dominant revenue share; commercial is gaining volume fastest in underpenetrated Southeast Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement of volatile organic compound limits and ECHA substance restrictions are redirecting manufacturing investment toward compliant production clusters. Mexico's automotive assembly expansion and China's supplier consolidation are redrawing procurement geography. German compounders leverage peroxide curing patents to defend technical supply positions.
United States
Construction corridors in Texas and Florida are concentrating pneumatic tool deployment for infrastructure spending. EPA industrial emissions rules tighten material specifications for hose compounds manufactured domestically. Fleet maintenance networks in the Midwest and Southeast are consolidating procurement through distributor exclusivity platforms bundling compressor service contracts.
Germany
Tier-one automotive suppliers in Baden-Württemberg and Bavaria qualify peroxide-cured rubber constructions for under-hood pneumatic applications. ECHA administration of REACH substance restrictions phases out certain accelerators from PVC and rubber formulations. Continental leverages captive polymer blending capacity across domestic plants to sustain margin on high-pressure hose constructions.
China
Manufacturing demand concentrates in the eastern corridor where supplier consolidation accelerates around certified compound producers. GB standards convergence with ISO pressure ratings remains incomplete, threatening tooling compatibility fragmentation. Zhejiang and Jiangsu provinces host the dominant certified compound production clusters serving domestic automotive and construction equipment fleets.
Mexico
Automotive assembly plants in Nuevo León and Guanajuato are scaling pneumatic tool fleets generating pull-through demand for 3/8 inch and 1/2 inch diameter constructions. Nearshoring incentives from the Mexican federal government attract tier-one supplier investment. Querétaro's industrial corridor lacks established certified hose supply chains, creating entry vulnerability for ECHA-aligned compounders.
Vietnam
Industrial zones in Bình Dương and Đồng Nai provinces lack established certified hose supply chains despite expanding manufacturing investment. The country's national industrial standards regulator has not yet converged testing protocols with ISO 2398, delaying contract qualification for cross-border suppliers. Thai and Indonesian construction markets face similar underpenetration, though Vietnam's automotive final assembly growth outpaces regional peers.
Air Hose Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive polymer operations alongside specialized hose fabricators dependent on external compound supply. Market structure concentrates volume among producers with ISO 2398 certification infrastructure, while uncertified regional manufacturers face contract qualification barriers. Two strategic archetypes dominate: integrated compounders controlling upstream polymer blending and channel-anchored distributors locking fleet maintenance networks into technical supply agreements. Competitive moves center on certification timeline acceleration and distributor exclusivity expansion.
Among diversified industrial conglomerates, Continental and Gates Corporation exemplify divergent positioning strategies. Continental represents the integrated compounder archetype with polymer blending capacity spanning German and Chinese production footprints. Gates Corporation anchors the channel-focused vector through North American aftermarket distributor partnerships. Parker Hannifin occupies a hybrid position between captive compound technology and diversified fluid power portfolio breadth. These three entities collectively illustrate how certification infrastructure and procurement channel control determine competitive viability under tightening regulatory chemistry requirements.
| Leading Market Players |
|---|
| Continental |
| Gates Corporation |
| Parker Hannifin |
| Eaton Corporation |
| Flexzilla |
| Goodyear Rubber Products |
| Dixon Valve & Coupling Company |
| Kuriyama of America |
| Anchor Rubber Products |
| Others |
Value Network & Pricing Analysis
ISO 2398 certification gates both supply qualification and price differentiation simultaneously, concentrating volume among compounders with captive polymer blending capacity while compressing margins for uncertified regional manufacturers facing immediate contract exclusion. This regulatory threshold stratifies the market into certified premium tiers and spot-market economy tiers with limited cross-border mobility.
Pricing Analysis
Cost-plus contracts with synthetic rubber indexation dominate procurement between tier-one automotive suppliers and certified compounders in Germany and China. Price differentiation rests on ISO 2398 certification grade and volume scale, with three-tier pricing structure across premium, standard, and economy levels. Cost compression in the economy tier is intensifying because uncertified Chinese regional manufacturers face immediate contract qualification barriers. Commercial contractors in Southeast Asia exhibit the highest price sensitivity, while industrial fleet operators in the United States prioritize technical specification compliance over unit cost.
Supply Chain Analysis
Inbound logistics costs from Port of Shanghai congestion and Asia-Europe container availability constraints are elevating landed costs for European distributors sourcing certified compounds. Geographic supply concentrates in Germany, China, and the United States, with raw material dependencies on synthetic rubber feedstocks, textile braiding, and specialty peroxide curing agents. Single-source vulnerability around German peroxide curing patent holders creates licensing friction for independent manufacturers. Distribution runs through distributor exclusivity platforms bundling hose replacement with compressor service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air hose market sits in early-cycle expansion as automotive assembly plants in Mexico and Southeast Asia scale pneumatic tool fleets, generating pull-through demand that outpaces established certified supply capacity.
For Market Incumbents: Consolidate certification infrastructure advantage by accelerating ISO 2398 testing capacity deployment in underpenetrated corridors like Querétaro and Bình Dương before mid-tier compounders complete 18-24 month upgrade cycles. Defend margin position through captive polymer blending capacity expansion rather than spot-market compound sourcing, as raw material volatility threatens high-pressure construction profitability. For New Entrants and Emerging Players: Differentiate on REACH-aligned bio-based plasticizer formulations to capture first-mover advantage as ECHA enforcement eliminates phthalate alternatives from European distribution. Target Vietnam's industrial zones in Đồng Nai and Bình Dương provinces where national standards have not yet converged with ISO 2398, enabling technical qualification before incumbent certification timelines complete. Anchor go-to-market through fleet maintenance network partnerships rather than spot distribution. For Investors and Strategic Acquirers: REACH compliance deadlines reshape the acquisition landscape toward compounders with upgraded testing infrastructure and peroxide curing system patents. Long-term viability centers on producers with backward integration into polymer blending and established distributor exclusivity platforms. The signal to watch is GB standards convergence with ISO pressure ratings in China, which would either accelerate supplier consolidation or fragment tooling compatibility and parallel inventory strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Peroxide Curing System Patent Licensing | Secures formulation IP advantage under REACH accelerator phase-out timelines in Germany. |
| ISO 2398 Testing Infrastructure Expansion | Accelerates contract qualification in Mexico and Vietnam before competitor upgrade cycles complete. |
| Distributor Exclusivity Platform Consolidation | Locks fleet maintenance networks into multi-year technical supply agreements bundling replacement schedules. |
| Backward Integration into Polymer Blending | Insulates margin from synthetic rubber feedstock volatility through captive compound production. |
| Bio-Based Plasticizer Formulation Development | Captures German automotive OEM multi-year supply agreements as ECHA eliminates phthalate alternatives. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with plant managers at automotive assembly facilities, procurement leads at tier-one pneumatic tool OEMs, distribution channel partners in North American aftermarket networks, and technical R&D directors at compound producers; and secondary validation through customs and trade data, SEC filings from diversified industrial conglomerates, ISO certification registries, and ECHA substance restriction documentation. Bottom-up demand modeling triangulated against top-down supply capacity assessments.
Across the analysis window, the forecast framework modeled segmentation dimensions including compound chemistry tier, end-use application, diameter specification, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and supply capacity buildout timelines. Industry-specific inputs incorporated automotive production forecasts for Mexico and Southeast Asia, REACH compliance deadline schedules, and EPA enforcement intensity patterns for volatile organic compound limits.
Material uncertainties — synthetic rubber feedstock price volatility, GB standards divergence from ISO pressure ratings, and ECHA enforcement acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding certification timeline completion and distributor exclusivity platform consolidation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Industrial Bag Dust Filter Market
Material Handling Equipment
Pharmaceutical Material Handling Equipment Market
Material Handling Equipment
North America Forklift Market
Material Handling Equipment
Middle East and Africa Automated Material Handling Market
Material Handling Equipment
Global Tension Control Market
Material Handling Equipment
Global Rolling Mill Rolls Market
Material Handling Equipment
Hot-Rolling Mill and Cold-Rolling Mill Market
Material Handling Equipment
Pipe Wrapping Machines Market
Material Handling Equipment
Asia-Pacific Forklift Rental Market
Material Handling Equipment
Global Metal Shredder Machine Market
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Wire Rope Sling Market
Material Handling Equipment
Pneumatic Caster Market
Material Handling Equipment
Hydraulic Seals Market
Material Handling Equipment
Eye and Eye Turnbuckle Market
Material Handling Equipment
Conveying Equipment Market