
 Japan AI in Oil and Gas Market | 2026-2036
Japan AI in Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Japan AI in Oil and Gas Market Insights
Domestic technology partnerships is fragmenting as Japanese energy conglomerates diversify their AI vendor relationships beyond traditional oilfield service providers. SoftBank Group leverages its capital depth and AI infrastructure investments to compete for upstream analytics contracts. ENEOS Holdings anchors its position through captive R&D in predictive maintenance systems for refining operations. Idemitsu Kosan differentiates by specializing in exploration optimization algorithms tailored to Japan's complex offshore geology.
Japan AI in Oil and Gas encompasses machine learning systems, neural network architectures, and advanced data analytics platforms deployed to optimize hydrocarbon discovery, extraction, and distribution processes. These technologies process seismic datasets exceeding petabyte scale to identify reservoir characteristics and automate drilling parameter adjustments in real time. Predictive maintenance commands the largest service type revenue pool due to aging refinery infrastructure requiring continuous monitoring. Reservoir modeling represents the fastest-expanding segment as marginal field economics improve through simulation accuracy gains. Machine learning dominates technology deployment, though natural language processing adoption is accelerating for regulatory document analysis and operational knowledge management.
METI enforces energy security mandates that shape capital allocation toward domestic production enhancement technologies, while JIS standards govern AI system reliability certification for hazardous environments. The country's national pharmaceutical regulator framework does not directly apply, though analogous functional safety protocols from industrial automation regulators constrain deployment timelines. Stakeholders must monitor how METI's evolving carbon accounting rules will redefine AI investment priorities between efficiency gains and emissions reduction verification.
Market Dynamics
METI's carbon neutrality mandates are forcing petroleum conglomerates to redirect AI capital from pure production optimization toward dual-use systems that simultaneously cut emissions and extract hydrocarbons. This regulatory pressure is compressing vendor selection cycles and privileging platforms with embedded carbon accounting modules.
Growth Catalysts
- Offshore decommissioning liabilities:Aging platforms in the Niigata and Akita basins require AI-driven structural integrity monitoring to extend operational life while meeting JIS safety standards.
- METI's GX League transition framework:Corporate decarbonization pledges under this policy are mandating AI deployment for Scope 3 emissions tracking across refining and distribution networks.
- Seismic data explosion:Petabyte-scale 4D seismic surveys around the Sea of Japan are overwhelming conventional interpretation workflows and pulling machine learning adoption forward.
Market Restraints
- Specialized compute hardware costs:GPU clusters optimized for reservoir simulation carry 40-60% import premiums due to yen depreciation and concentrated supply from Taiwan-based foundries.
- JIS certification timelines:Functional safety validation for AI systems in hazardous zone 0 environments extends deployment cycles by 18-24 months.
- Geological complexity:Japan's fractured basement formations and volcanic intrusions degrade standard neural network training data quality, forcing costly model customization.
Strategic Opportunities
- Hokkaido marginal field revival:Abandoned onshore concessions in the Kushiro basin present retrofit opportunities for low-cost AI-enhanced enhanced oil recovery.
- CCUS integration:Carbon capture utilization and storage projects off Tomakomai are creating demand for AI systems that optimize CO2 injection patterns alongside hydrocarbon extraction.
- Digital twin convergence:Combining physics-based simulation with machine learning is opening new service lines for real-time refinery optimization under METI's energy efficiency mandates.
Industry Challenges
- Upstream data science talent scarcity:Petroleum geoscientists with production engineering backgrounds and Python proficiency command 2.5x median IT salaries, constraining in-house model development.
- Legacy SCADA integration friction:Refineries in the Keiyo industrial zone operate 1990s-era distributed control systems that resist API-based data extraction for AI training pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan AI in Oil and Gas Market |
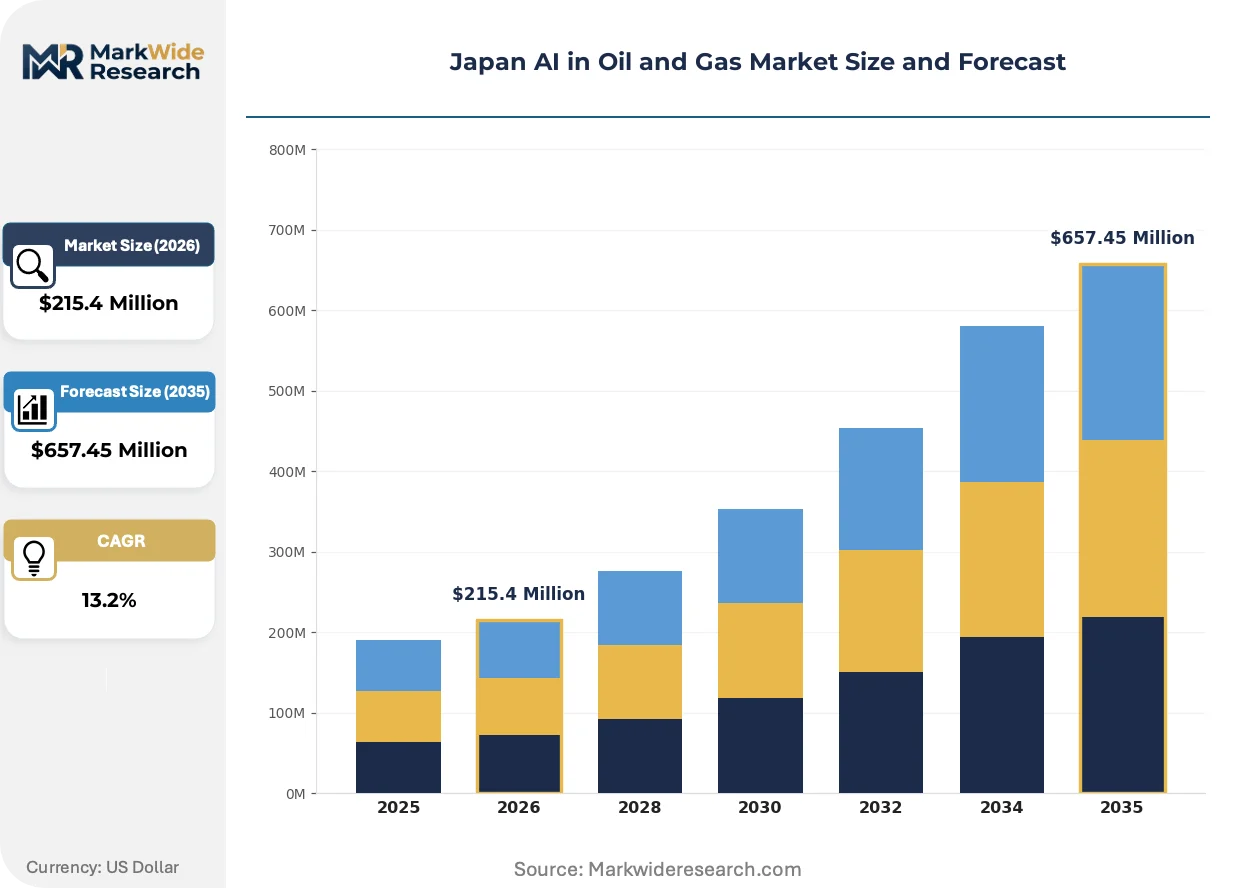
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $657.45 Million |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Predictive Maintenance, Reservoir Modeling, Exploration Optimization, Drilling Automation Application: Oil Field Management, Production Enhancement, Supply Chain Management, Asset Tracking Technology: Machine Learning, Neural Networks, Data Analytics, Natural Language Processing End User: Exploration Companies, Production Firms, Service Providers, Regulatory Agencies |
| Companies Covered | SoftBank Group, Japan Petroleum Exploration, ENEOS Holdings, Baker Hughes, Schlumberger, Idemitsu Kosan, Itochu Enex, IBM, Tokyo Gas, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan AI in Oil and Gas Market Trends and Innovations
Foundation models trained on proprietary seismic and well log datasets are compressing the traditional vendor-client knowledge asymmetry. This shift is redistributing analytical capability from specialized service firms toward operator-owned AI centers.
Physics-informed neural networks are hybridizing conventional reservoir simulation with deep learning pattern recognition. ENEOS and Idemitsu pilot programs in the Tokyo Bay cluster are validating these hybrid architectures for forecasting water breakthrough in heterogeneous carbonate formations. The technology is compressing simulation runtimes from weeks to hours without sacrificing geological fidelity.
METI's 2023 Carbon Accounting Guidelines are mandating granular emissions disclosure across Scope 1, 2, and 3 categories. Refinery operators must now deploy continuous monitoring AI to satisfy verification protocols under the GX League framework. The regulation is accelerating procurement of edge-computing sensor networks in the Osaka-Kobe industrial corridor.
Subscription-based AI service contracts are displacing perpetual license models for exploration analytics. National oil companies in the Chubu region are consolidating vendor relationships through multi-year platform agreements that bundle software, compute, and geoscientist support. This procurement evolution is concentrating contract value with providers offering vertically integrated data infrastructure.
Japan AI in Oil and Gas Market Segmentation
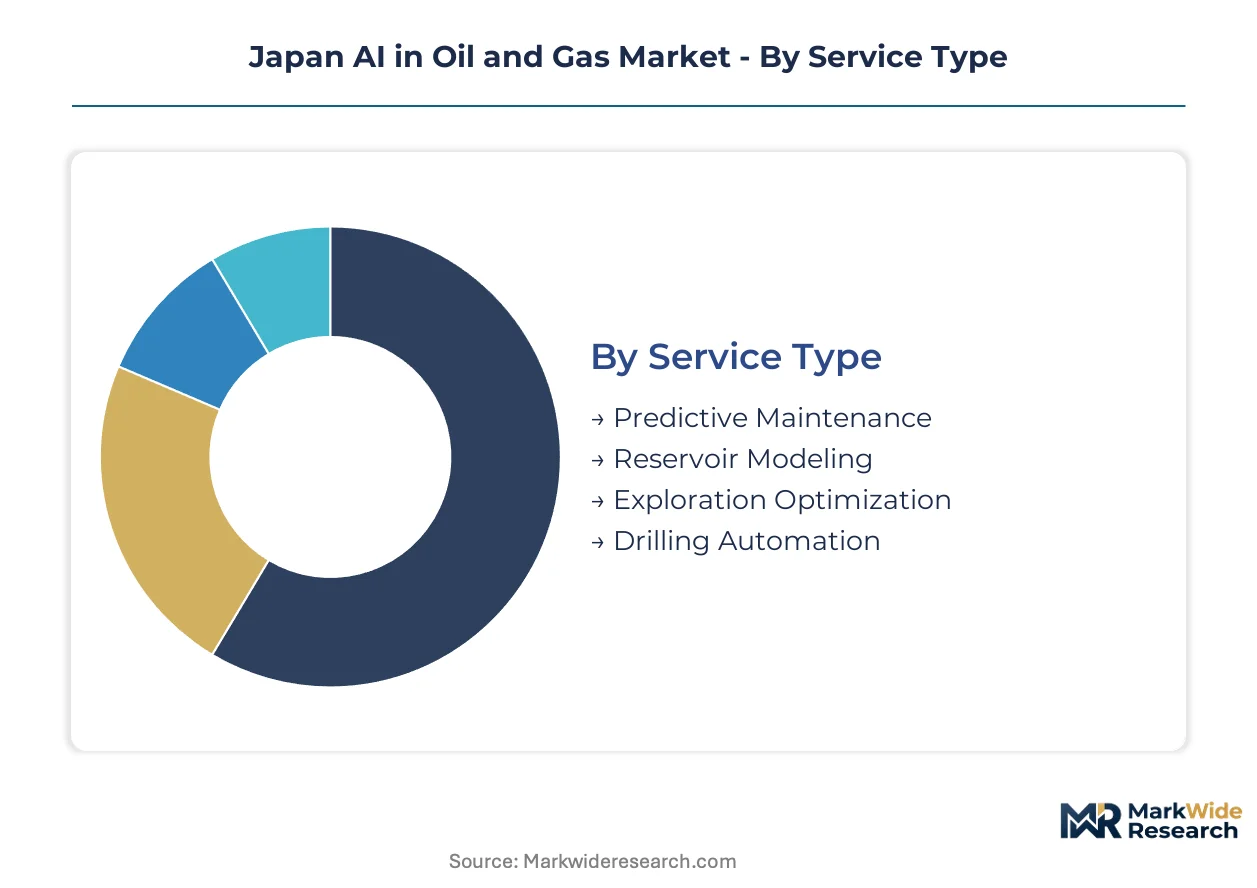
Segmentation reveals how METI policy pressure and geological constraints reshape procurement priorities across Japan's petroleum value chain. Each dimension exposes distinct technology gaps and vendor positioning opportunities.
Service Type:
Application focus determines contract value and renewal rates, with upstream operators prioritizing risk reduction over pure production gains.
- Predictive Maintenance:Continuous monitoring systems analyze vibration, thermal, and acoustic signatures from rotating equipment in refineries and offshore platforms. Demand concentrates in the Keiyo industrial zone where aging infrastructure requires JIS-compliant anomaly detection to prevent unplanned shutdowns. METI energy efficiency mandates accelerate sensor network deployment.
- Reservoir Modeling:Machine learning architectures process 4D seismic and well log data to simulate fluid flow through Japan's fractured basement formations. Exploration companies in the Niigata basin deploy these systems to improve recovery factors from marginal fields with complex volcanic intrusions.
- Exploration Optimization:Algorithms rank drilling targets using multi-attribute analysis of historical production and geophysical surveys.
- Drilling Automation:Real-time parameter adjustment systems reduce non-productive time in deepwater Sea of Japan wells.
Predictive Maintenance holds installed capacity. Reservoir Modeling is rotating up the share rankings.
Application:
End-use priorities reflect the tension between hydrocarbon extraction and carbon accountability under GX League frameworks.
- Oil Field Management:Integrated platforms coordinate wellhead monitoring, artificial lift optimization, and facility maintenance across dispersed assets. Production firms in the Akita basin deploy these systems to manage declining output from mature concessions while documenting emissions for METI verification.
- Production Enhancement:AI-driven secondary and tertiary recovery methods extend field life through pattern recognition in historical injection-production relationships. The technology gains traction in Hokkaido's Kushiro basin where low-cost EOR revival depends on precise reservoir characterization.
- Supply Chain Management:Demand forecasting and logistics optimization reduce inventory carrying costs for refined product distribution.
- Asset Tracking:RFID and satellite-based monitoring systems locate mobile equipment across offshore platforms and coastal terminals.
Oil Field Management anchors current deployment. Production Enhancement is climbing the fastest as marginal field economics improve.
Technology:
Computational approach selection depends on data availability, latency requirements, and interpretability needs for JIS certification.
- Machine Learning:Supervised and unsupervised algorithms dominate deployment, processing structured sensor feeds and unstructured maintenance records. The technology saturates refinery operations in the Osaka-Kobe corridor where historical failure data enables robust model training.
- Neural Networks:Deep learning architectures extract features from raw seismic traces without manual preprocessing. Physics-informed variants are gaining adoption in Tokyo Bay pilot programs for water breakthrough forecasting.
- Data Analytics:Descriptive and diagnostic platforms aggregate operational metrics for executive dashboards.
- Natural Language Processing:Document analysis systems extract requirements from regulatory filings and operational manuals.
Machine Learning commands the technology base. Neural Networks are expanding most quickly through hybrid physics-ML architectures.
End User:
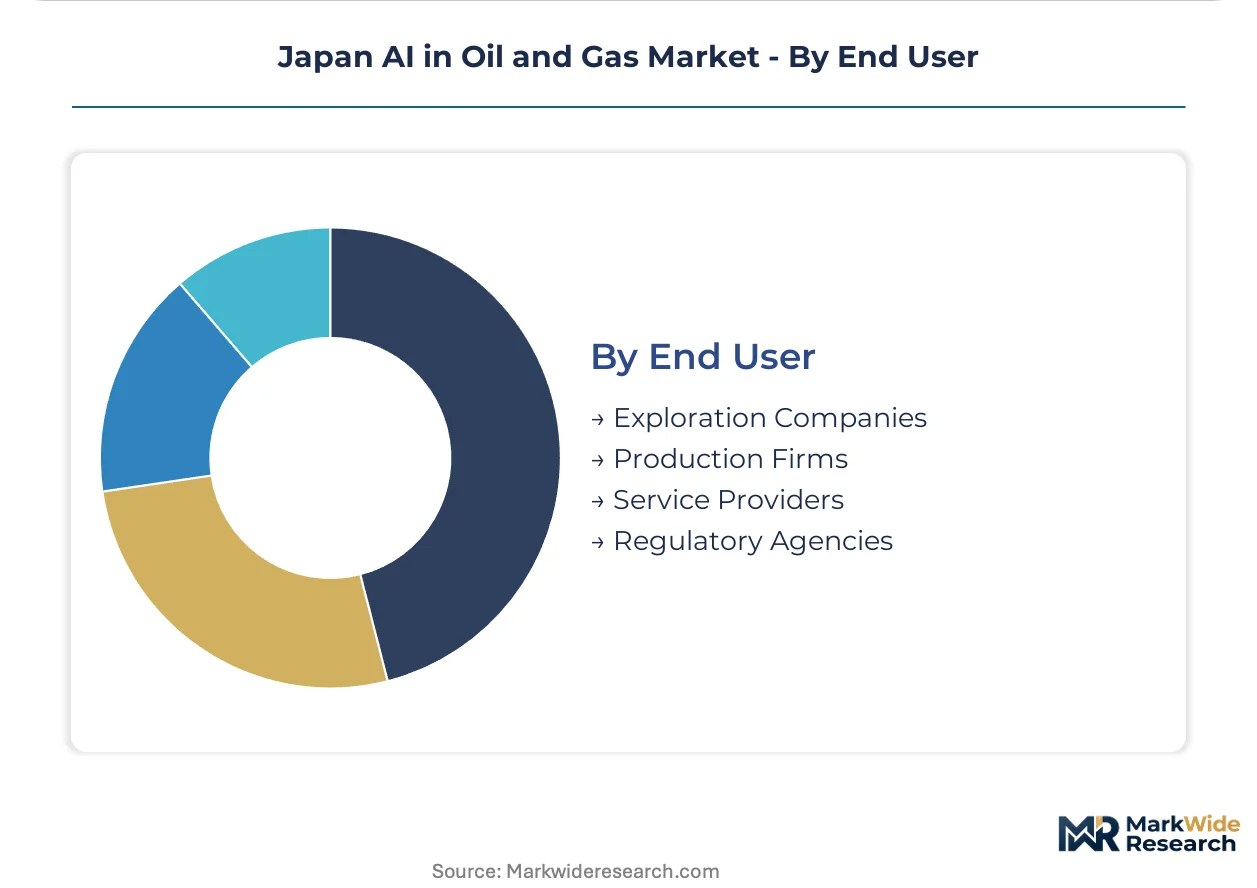
Procurement authority and technical sophistication vary sharply across buyer categories, shaping vendor engagement models.
- Exploration Companies:Upstream operators with proprietary seismic libraries prioritize reservoir characterization accuracy over cost minimization. These buyers in the Sea of Japan concession blocks negotiate multi-year platform agreements bundling software, compute, and geoscientist support.
- Production Firms:Operating companies managing mature assets focus on opex reduction and regulatory compliance. Their procurement concentrates on predictive maintenance and emissions monitoring systems for GX League disclosure requirements.
- Service Providers:Oilfield contractors purchase AI tools to differentiate technical proposals and improve project execution metrics.
- Regulatory Agencies:METI and prefectural authorities deploy analytics for production auditing and carbon verification.
Exploration Companies control the premium segment. Production Firms are gaining procurement volume through efficiency mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Keiyo industrial corridor's petroleum refining complex and the Tokyo Bay offshore pipeline network anchor Japan's AI deployment infrastructure. METI's GX League carbon accounting protocols flow through this physical backbone, concentrating digital investment in Kanto and Kansai industrial zones.
Kanto/Tokyo
Exploration companies cluster around the Tokyo Bay offshore concessions, deploying machine learning for 4D seismic interpretation. METI's 2023 Carbon Accounting Guidelines mandate continuous emissions monitoring here. The Keiyo industrial zone refineries operate predictive maintenance systems under JIS functional safety certification.
Kansai/Osaka
Production firms manage aging onshore assets through AI-driven secondary recovery optimization. The country's national energy regulator enforces GX League disclosure requirements across the Osaka-Kobe refining corridor. Idemitsu Kosan anchors exploration algorithm development for Japan's fractured basement formations.
Chubu/Nagoya
Service providers concentrate in this manufacturing hub, supplying sensor networks and edge computing hardware to upstream operators. METI energy efficiency mandates accelerate digital twin procurement for regional refineries. The Yokkaichi complex represents a testbed for physics-informed neural network deployment.
Hokkaido
Abandoned Kushiro basin concessions attract low-cost AI-enhanced EOR revival projects. Prefectural authorities coordinate with METI on marginal field economics improvement. The Tomakomai CCUS pilot creates demand for CO2 injection pattern optimization systems.
Niigata and Akita Basins
Offshore platform decommissioning liabilities drive structural integrity monitoring AI adoption. JIS safety standards govern zone 0 hazardous environment deployments. Japan Petroleum Exploration operates reservoir characterization systems for volcanic intrusion geology.
Japan AI in Oil and Gas Market Competitive Landscape
On the supply side, the industry is bifurcating between capital-heavy infrastructure providers and specialized algorithm developers. Domestic energy conglomerates diversify vendor relationships beyond traditional oilfield service providers. Two strategic archetypes dominate: integrated technology platforms bundling compute and analytics, and captive R&D divisions of petroleum operators. Competitive moves concentrate on multi-year platform agreements and physics-ML hybrid architecture development.
Within the integrated technology tier, SoftBank Group leverages capital depth and AI infrastructure investments to compete for upstream analytics contracts. ENEOS Holdings anchors its position through captive R&D in predictive maintenance systems for refining operations. Idemitsu Kosan exemplifies the specialization archetype, occupying a position in exploration optimization algorithms tailored to Japan's complex offshore geology.
| Leading Market Players |
|---|
| SoftBank Group |
| Japan Petroleum Exploration |
| ENEOS Holdings |
| Baker Hughes |
| Schlumberger |
| Idemitsu Kosan |
| Itochu Enex |
| IBM |
| Tokyo Gas |
| Others |
Pricing and Supply Chain Analysis
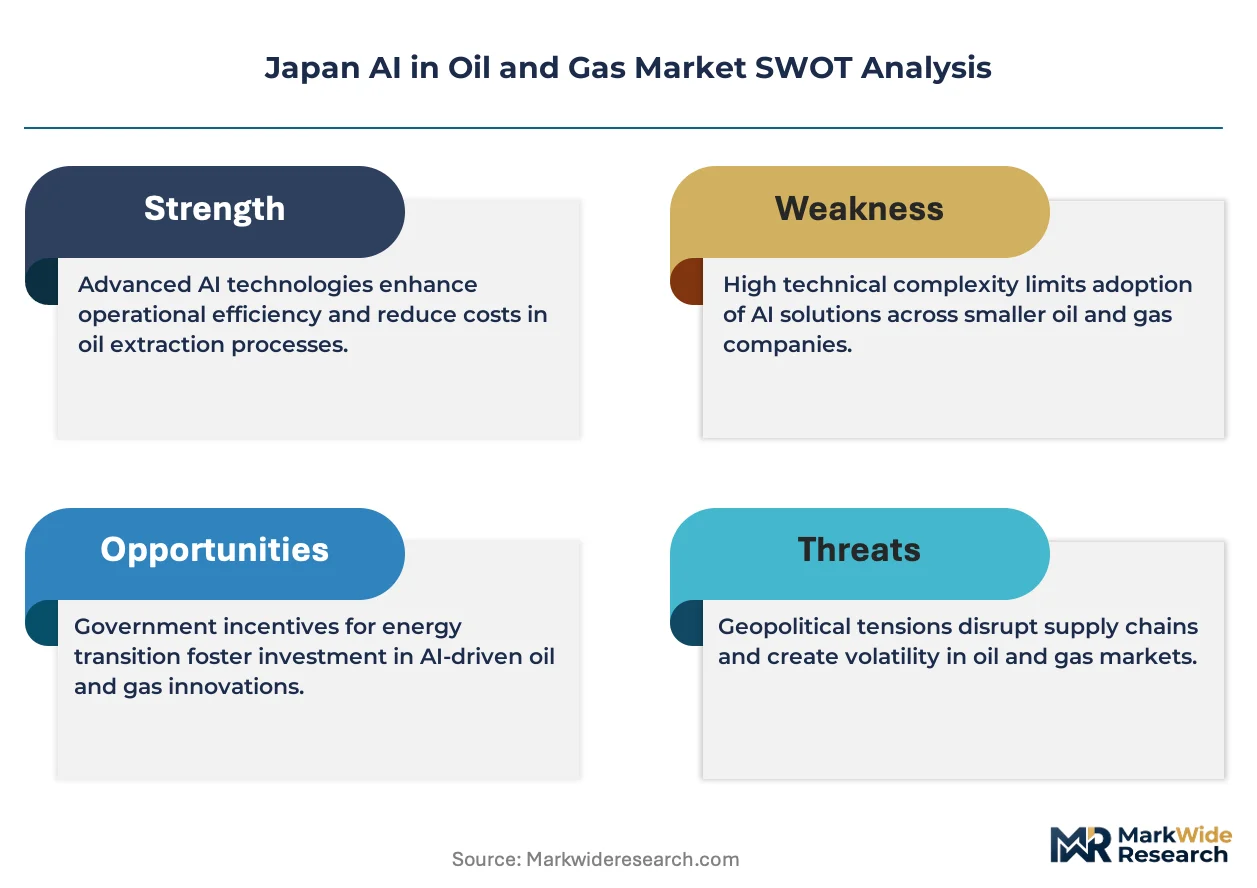
GPU cluster supply from Taiwan-based foundries concentrates upstream hardware procurement, pushing margin pools toward systems integrators who bundle compute infrastructure with reservoir simulation software. Japanese petroleum operators absorb 40-60% import premiums on specialized AI accelerators, compressing vendor margins while elevating total contract values for vertically integrated platform providers.
Pricing Analysis
Volume-discount tiering structures dominate procurement, with national oil companies negotiating multi-year platform agreements that bundle software licenses, cloud compute, and embedded geoscientist support. Pricing stratifies across premium certified-JIS tiers for zone 0 hazardous environments, standard API-integrated configurations, and economy sensor-only packages for non-critical refinery assets. Cost compression in the economy tier is intensifying because SoftBank Group and domestic conglomerates are subsidizing AI infrastructure deployment to capture downstream analytics revenue. Production firms managing mature assets exhibit highest price sensitivity due to opex constraints, while exploration companies prioritize reservoir characterization accuracy over cost minimization.
Supply Chain Analysis
Export-control regimes restricting advanced GPU and AI accelerator shipments from the United States and Taiwan constrain hardware availability for Japanese upstream operators. Supply chains draw from Taiwan for semiconductor fabrication, the United States for specialized seismic processing software, and domestic Japanese manufacturers for JIS-certified edge computing enclosures. Single-source vulnerability around Taiwan-based foundry capacity presents structural risk given yen depreciation and geopolitical friction. Distribution runs through systems integrators who combine imported hardware with localized software customization and METI compliance certification services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's AI in oil and gas market represents high-growth disruption as METI's GX League carbon accounting mandates force petroleum conglomerates to redirect capital toward dual-use systems that simultaneously extract hydrocarbons and verify emissions reductions.
For Market Incumbents: Harden defensive positions by deepening captive R&D in physics-informed neural networks for reservoir simulation, protecting against SoftBank Group's capital-backed entry into upstream analytics. Secure JIS certification pipelines for zone 0 hazardous environment deployments to extend deployment cycle advantages over emerging entrants lacking regulatory relationships.
For New Entrants and Emerging Players: Build out specialized algorithm development capabilities targeting Hokkaido's marginal field revival segment, where abandoned Kushiro basin concessions offer low-cost entry points for AI-enhanced enhanced oil recovery. Capture procurement volume through subscription-based service contracts that displace perpetual license models among production firms facing opex constraints.
For Investors and Strategic Acquirers: Capital is best deployed toward hybrid physics-ML architecture developers with demonstrated pilot validation in Tokyo Bay or Yokkaichi refinery complexes, positioning for long-term viability as foundation models compress traditional vendor-client knowledge asymmetry. Monitor METI's evolving carbon accounting rules as the critical inflection signal that will redefine AI investment priorities between efficiency gains and emissions reduction verification.
| Strategic Initiative | Industry Significance |
|---|---|
| Physics-Informed Neural Network Development | ENEOS and Idemitsu pilot programs validate hybrid architectures for water breakthrough forecasting in heterogeneous carbonate formations. |
| JIS Functional Safety Certification Investment | Certification pipelines for zone 0 hazardous environments extend deployment cycles and protect incumbent market positions. |
| CCUS-AI Integration Partnership | Tomakomai carbon capture projects create demand for CO2 injection pattern optimization alongside hydrocarbon extraction systems. |
| Foundation Model Training on Proprietary Seismic Data | Operator-owned AI centers redistribute analytical capability from specialized service firms toward petroleum conglomerates. |
| Edge Computing Sensor Network Deployment | METI's GX League disclosure requirements accelerate procurement in Osaka-Kobe and Keiyo industrial corridors. |
Research Methodology
The analysis maps predictive maintenance systems, reservoir modeling platforms, exploration optimization algorithms, and drilling automation technologies, each validated through petroleum geoscientists, refinery operations directors, METI energy policy officials, and AI systems procurement leads. Primary interviews with upstream operators and technology vendors combined with secondary validation from METI policy filings, JIS standards documentation, EIA energy data, and petroleum concession production records. Bottom-up segment sizing triangulates against top-down market envelope estimates derived from capital expenditure disclosures across the Tokyo-Osaka industrial corridor.
Assumption sets held METI's GX League framework and carbon neutrality mandates fixed while varying AI adoption rates across upstream, midstream, and downstream segments over the projection horizon. Segmentation dimensions modeled include service type, application focus, computational approach, and end-user procurement authority, with particular attention to exploration company versus production firm buying behavior. CAGRs derive from installed base expansion curves and replacement cycle analysis, incorporating seismic data volume growth and refinery infrastructure age profiles as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler-backed entrants or state-affiliated technology platforms would shift outcomes. Material shifts in METI's carbon accounting protocols, JIS certification timelines, or Taiwan semiconductor export controls would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Japan LNG Bunkering Market
Oil & Gas
Global LNG Liquefaction Equipment Market
Oil & Gas
Land Drilling Rig Market
Oil & Gas
Hydrocracking Market
Oil & Gas
Workover Rigs Market
Oil & Gas
Seismic Survey Equipment Market
Oil & Gas
Thailand Oil and Gas Upstream Market
Oil & Gas
Mud Mixers Market
Oil & Gas
Oil and Gas Separation Equipment Market
Oil & Gas
Global Fracking Fluids and Chemicals Market
Oil & Gas
LNG Loading Skid Market
Oil & Gas
Central Asia Oil and Gas Market
Oil & Gas
North America Wireline Logging Services Market
Oil & Gas
3D Printing in Oil and Gas Market
Oil & Gas
Italy Oil and Gas Downstream Market
Oil & Gas
Smart Pipeline Pigging Market