
 Denmark Oil and Gas Midstream Market | 2026-2036
Denmark Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Oil and Gas Midstream Market Outlook
Buyer concentration among Danish power utilities and industrial off-takers is recalibrating contract structures across the midstream value chain. Energinet leverages its monopoly over national gas transmission to anchor long-term throughput agreements. TotalEnergies SE competes through integrated offshore-to-terminal logistics spanning Danish North Sea fields. Equinor ASA specializes in high-pressure pipeline corridors linking Norwegian upstream assets to Danish processing nodes.
Denmark oil and gas midstream encompasses the transportation, storage, and processing infrastructure bridging extraction points to refineries and end-use facilities, typically operating at pressures between 70-150 bar for offshore pipelines and maintaining cryogenic conditions at LNG terminals. The sector's primary purpose is to condition raw hydrocarbons into pipeline-quality natural gas and stabilized crude while managing flow intermittency from declining North Sea reservoirs. Pipelines dominate installed asset value, though processing plants capture disproportionate margin pools through NGL extraction and sulfur recovery. Storage facilities face structural pressure from Denmark's gas storage mandate under EU security-of-supply rules, while monitoring systems within the technology segment are gaining traction as operators digitize pipeline integrity management.
The Danish Energy Agency enforces offshore safety case requirements under the EU Offshore Safety Directive, compelling operators to demonstrate blowout prevention and emergency response capabilities before production consent. Energinet's technical codes align with EU Network Codes on gas capacity allocation and interoperability, shaping how third-party access terms structure midstream revenue models. Stakeholders must weigh stranded asset risk against repurposing timelines as Denmark's 2040 climate neutrality target accelerates debates over pipeline conversion to hydrogen or CO2 service.
Market Dynamics
The Danish Energy Agency's North Sea transition framework is forcing midstream operators to reconfigure pipeline networks for carbon capture integration while maintaining hydrocarbon throughput. This regulatory pressure is compressing capital allocation timelines and accelerating infrastructure repurposing debates.
Growth Catalysts
- Power plant expansion:Gas-fired capacity additions along the Jutland peninsula are pulling additional throughput through Energinet's transmission network. These facilities require firm delivery contracts to balance intermittent renewable output.
- EU security-of-supply mandates:Denmark's gas storage obligations under EU Network Codes are sustaining minimum storage facility utilization rates. This regulatory floor protects storage asset revenues against demand volatility.
- Offshore processing integration:Subsea tieback technologies are extending the productive life of marginal Danish North Sea fields. Pipeline operators capture incremental volumes from fields that would otherwise decommission.
Market Restraints
- Reservoir decline curves:Mature Danish North Sea fields exhibit accelerating production decline rates. Pipeline operators face underutilization risk as connected fields reach end-of-life.
- Electrification substitution:District heating networks and industrial heat pumps are displacing gas-fired thermal demand in Copenhagen and Aarhus metropolitan zones.
- EU methane regulations:The EU Methane Regulation imposes measurement, reporting, and verification requirements on midstream fugitive emissions. Compliance costs compress margins at processing and compression facilities.
Strategic Opportunities
- Carbon transport infrastructure:The Danish Energy Agency's CO2 storage licensing framework positions depleted offshore reservoirs for carbon sequestration. Existing pipeline corridors can convert to CO2 service with compressor modifications.
- Hydrogen backbone conversion:Energinet's technical codes are being adapted for hydrogen blending and pure hydrogen transport. Steel pipeline segments on the Jutland trunk line are candidates for hydrogen repurposing.
- Esbjerg port cluster expansion:Offshore wind manufacturing and Power-to-X facilities are concentrating demand at Denmark's primary hydrocarbon gateway. Multi-service terminal operators can diversify revenue streams beyond oil and gas.
Industry Challenges
- Asset stranding timelines:Denmark's 2040 climate neutrality target compresses the economic life of hydrocarbon-dedicated infrastructure. Operators must recover invested capital within shortened depreciation windows.
- Cross-commodity engineering standards:Pipeline materials certified for natural gas service require reassessment for hydrogen embrittlement risks. Retrofit engineering extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Oil and Gas Midstream Market |
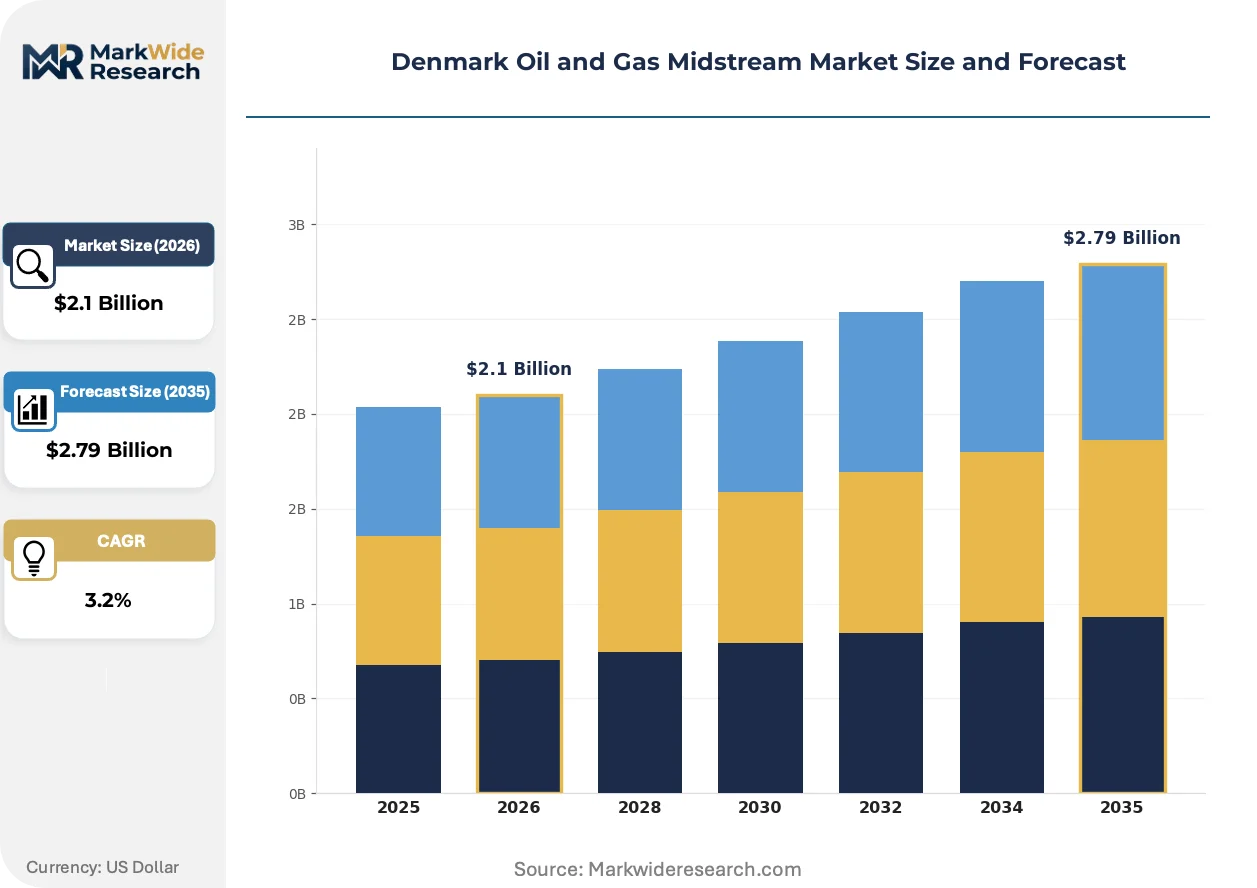
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.79 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pipelines, Storage Facilities, Terminals, Processing Plants Service Type: Transportation, Storage, Processing, Distribution Technology: Compression Systems, Heating Systems, Monitoring Systems, Filtering Systems End User: Refineries, Power Plants, Industrial Users, Traders |
| Companies Covered | Orsted A/S, TotalEnergies SE, Shell PLC, Engie SA, Chevron Corporation, Equinor ASA, Energinet, Norwegian Energy Company ASA, Wintershall Dea GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Oil and Gas Midstream Market Strategic Shifts
Digitalization and decarbonization mandates are converging to transform how Danish midstream operators manage asset integrity and contract structures. Technology deployment is accelerating faster than regulatory frameworks can adapt.
Advanced pipeline monitoring systems incorporating distributed acoustic sensing and satellite-based methane detection are rewriting integrity management economics. Energinet is deploying these technologies across high-pressure corridors to reduce manual survey requirements. The shift is compressing leak response times from days to hours while enabling predictive maintenance scheduling.
The EU Offshore Safety Directive's implementation through the Danish Energy Agency's safety case regime is tightening blowout prevention and emergency response requirements. Operators must demonstrate subsea isolation capability and capping stack availability before production consent. Offshore pipeline segments and platform tie-ins face heightened scrutiny, with third-party verification now mandatory for safety-critical systems.
Danish power utilities are consolidating procurement through long-term capacity contracts rather than spot market purchases. Energinet's monopoly position allows it to anchor throughput agreements that guarantee minimum revenue streams for pipeline operators. This buyer concentration is visible across the Jutland peninsula, where regional utilities have pooled demand to negotiate firmer delivery terms.
Denmark Oil and Gas Midstream Market Segmentation
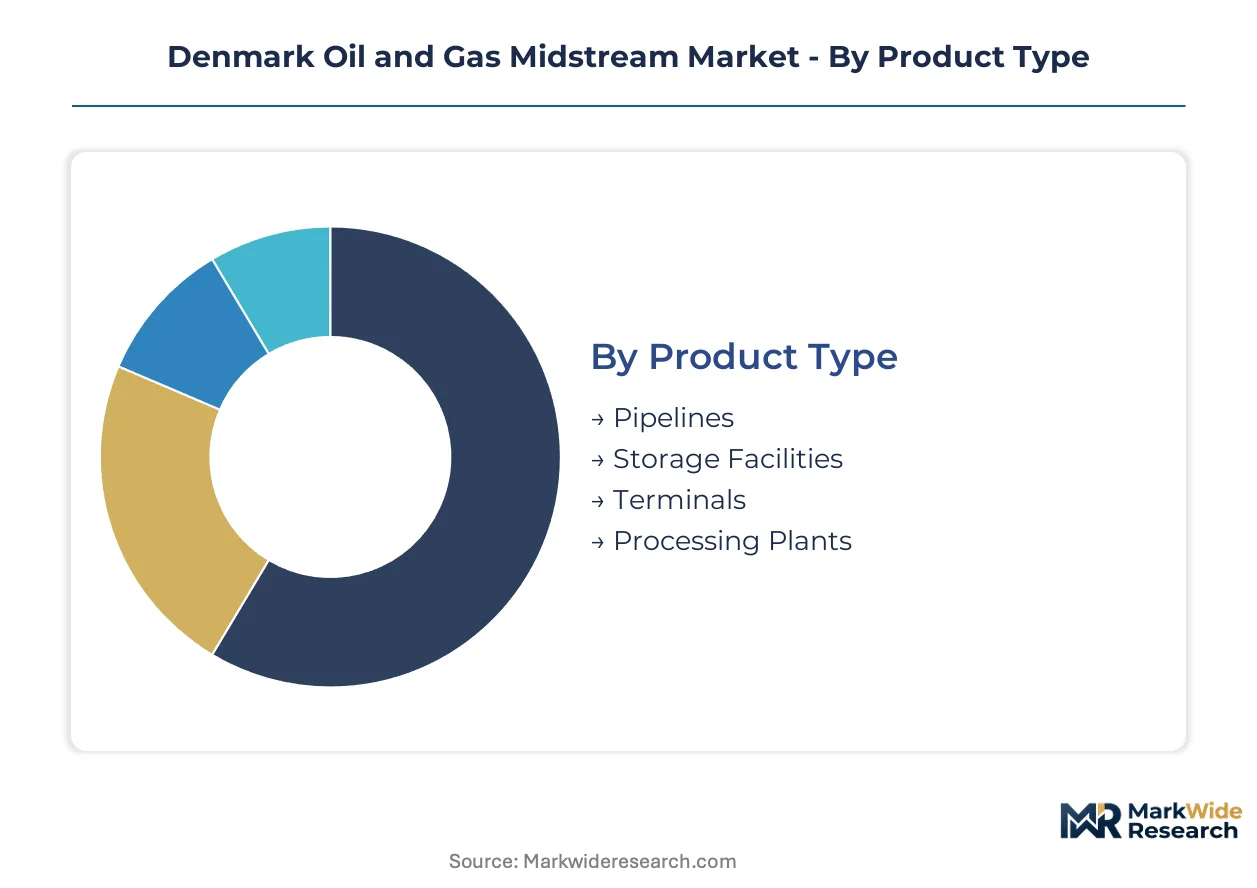
Segmentation in Denmark's oil and gas midstream market reveals how infrastructure economics divide between capital-intensive fixed assets and service-based revenue streams. Each dimension exposes different vulnerability profiles to the country's 2040 climate neutrality timeline and North Sea depletion curves.
Product Type:
Pipelines concentrate the bulk of installed asset value across Denmark's midstream infrastructure, with ownership structures reflecting long-term throughput commitments from declining North Sea fields.
- Pipelines:High-pressure steel corridors operating at 70-150 bar connect offshore platforms to onshore processing nodes. Energinet's Jutland trunk line anchors national transmission capacity while facing hydrogen repurposing engineering assessments.
- Storage Facilities:Underground salt caverns and depleted reservoir formations maintain strategic reserves under EU security-of-supply mandates. Minimum utilization floors protect revenues despite demand volatility from district heating electrification.
- Terminals:The Esbjerg port cluster handles offshore pipeline landfalls and LNG import flexibility. Multi-service operators are diversifying into offshore wind manufacturing logistics.
- Processing Plants:NGL extraction and sulfur recovery units capture disproportionate margin pools through conditioning raw hydrocarbons to pipeline-quality specifications.
Today's leader: Pipelines. Tomorrow's challenger: Processing Plants.
Service Type:
Service segmentation tracks how revenue models align with Denmark's shifting commodity flows and regulatory pressure for infrastructure repurposing.
- Transportation:Third-party access terms under EU Network Codes structure capacity allocation auctions and long-term booking arrangements. Energinet's monopoly position shapes tariff methodologies across the national grid.
- Storage:Injection and withdrawal services face structural pressure from renewable substitution in Copenhagen and Aarhus heating networks. EU storage obligations provide regulatory revenue floors.
- Processing:Conditioning raw gas through dehydration, compression, and NGL fractionation commands premium margins where field-specific chemistry requires customized treatment trains.
- Distribution:Last-mile delivery to industrial off-takers and power utilities is consolidating through buyer pooling arrangements along the Jutland peninsula.
Transportation commands current revenue share. Processing offers the steepest expansion trajectory as marginal fields demand complex conditioning.
Technology:
Technology segmentation distinguishes between mechanical systems with established depreciation profiles and digital monitoring assets gaining traction under methane regulation compliance.
- Compression Systems:Centrifugal and reciprocating units maintain pipeline pressure across Denmark's subsea corridors and onshore trunk lines. CO2 service conversion requires re-rating for denser gas properties.
- Heating Systems:Line heaters and regeneration units prevent hydrate formation in offshore gathering lines. Operating costs track natural gas price exposure.
- Monitoring Systems:Distributed acoustic sensing and satellite-based methane detection are compressing leak response timelines. The EU Methane Regulation's measurement and verification requirements accelerate deployment.
- Filtering Systems:Coalescing and particulate removal equipment protects downstream compression and processing assets from reservoir-produced solids and liquids.
Compression Systems anchor capital budgets. Monitoring Systems are climbing the fastest on regulatory compliance spending.
End User:
End-user concentration among Danish power utilities is restructuring contract tenors toward firm capacity commitments that guarantee infrastructure utilization.
- Refineries:Stabilized crude delivery to Fredericia and Kalundborg processing complexes maintains steady pipeline demand despite overall North Sea decline.
- Power Plants:Gas-fired capacity expansion along the Jutland peninsula is pulling firm delivery contracts to balance intermittent renewable output. Buyer pooling strengthens negotiation leverage.
- Industrial Users:Chemical and manufacturing facilities in Copenhagen and Aarhus metropolitan zones face electrification substitution from heat pump deployment.
- Traders:Wholesale market participants exploit storage arbitrage and cross-border capacity at the Danish-German interconnector.
Power Plants dominate throughput commitments. Traders represent the most price-sensitive demand segment with spot-market exposure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway's pipeline corridors supply more hydrocarbon volume to Danish processing nodes than Germany's intermittent LNG deliveries, revealing how North Sea geology shapes infrastructure economics differently than continental import dependence.
North Jutland
Offshore pipeline landfalls at Hirtshals and Frederikshavn anchor natural gas receipts from Norwegian North Sea fields. The Danish Energy Agency's safety case requirements under the EU Offshore Safety Directive govern platform tie-in approvals. Aalborg's industrial zone processes these volumes for regional power utilities expanding gas-fired capacity.
Mid Jutland
Energinet's national transmission trunk line bisects this sub-region, maintaining 70-150 bar pressure corridors toward German interconnectors. EU Network Codes on capacity allocation structure third-party access tariffs. Randers and Viborg host compression stations undergoing engineering assessment for hydrogen service conversion.
South Jutland
The Danish-German border zone concentrates cross-border capacity trading and storage arbitrage activity. EU security-of-supply mandates sustain minimum utilization at underground salt cavern facilities. Kolding and Esbjerg's port cluster handles offshore wind manufacturing logistics alongside hydrocarbon terminal operations.
Zealand
Copenhagen metropolitan demand faces electrification pressure from district heating network conversions and industrial heat pump deployment. The Danish Energy Agency's 2040 climate neutrality target accelerates infrastructure repurposing debates. Kalundborg's refinery complex maintains stabilized crude demand through pipeline connections to North Sea production.
Funen
Odense's manufacturing base represents declining industrial gas demand as process electrification advances. The Danish Energy Agency's CO2 storage licensing framework positions depleted offshore reservoirs near the island for carbon sequestration service. Local pipeline segments face underutilization risk as connected fields reach end-of-life.
Denmark Oil and Gas Midstream Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Denmark's midstream infrastructure, creating a tiered structure where integrated energy majors leverage upstream-downstream coordination against national transmission monopolies. State-affiliated entities anchor baseline capacity provision through regulated asset bases. Strategic moves concentrate on infrastructure repurposing partnerships and carbon transport corridor development as hydrocarbon throughput declines.
Within the integrated multinational tier, TotalEnergies SE and Equinor ASA occupy positions shaped by their North Sea upstream heritage and cross-border pipeline ownership. Energinet anchors the regulated utility segment as Denmark's national transmission system operator. Orsted A/S exemplifies the energy transition pivot, having repositioned from hydrocarbon dominance toward offshore wind and Power-to-X infrastructure.
| Leading Market Players |
|---|
| Orsted A/S |
| TotalEnergies SE |
| Shell PLC |
| Engie SA |
| Chevron Corporation |
| Equinor ASA |
| Energinet |
| Norwegian Energy Company ASA |
| Wintershall Dea GmbH |
| Others |
Value Chain & Pricing Dynamics
Steel grade specifications for high-pressure pipeline construction feed directly into capacity pricing tiers across Danish midstream infrastructure. API 5L X65 and X70 material costs flow through Energinet's regulated tariff methodology to shape contract structures for power utilities along the Jutland corridor.
Pricing Analysis
Capacity additions in Esbjerg's multi-service terminal cluster are reshaping price floors for processing and storage services. Long-term offtake contracts dominate revenue models, with price differentiation hinging on firm capacity commitments versus interruptible service tiers and carbon intensity certification levels. Pricing pressure stems from hydrogen repurposing engineering assessments extending project timelines. Power utilities demonstrate lowest price sensitivity due to buyer pooling arrangements, while wholesale traders exhibit highest spot-market responsiveness.
Supply Chain Analysis
Regional distribution centers at Esbjerg and Fredericia anchor hub-and-spoke patterns for pipeline components and compression equipment. Manufacturing concentrates in Germany, Norway, and the Netherlands for subsea tieback systems and high-pressure valves. Raw material dependencies include specialized steel alloys, corrosion-resistant coatings, and subsea umbilical cables. Single-source vulnerability runs through Norwegian pipeline corridor ownership structures. Distribution runs through Energinet's national grid with third-party access terms under EU Network Codes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Danish Energy Agency's 2040 climate neutrality mandate compounds infrastructure repurposing decisions, accelerating the shift from hydrocarbon throughput to carbon transport and hydrogen backbone conversion.
For Market Incumbents: Extend asset utilization through CO2 service conversion engineering at depleted North Sea reservoir connections. Secure long-term carbon transport agreements under the Danish Energy Agency's storage licensing framework before pipeline decommissioning deadlines compress depreciation windows. Vertical integration into offshore wind manufacturing logistics at Esbjerg diversifies revenue beyond hydrocarbon terminal operations. For New Entrants and Emerging Players: Enter via carbon capture transport infrastructure partnerships with depleted field operators seeking sequestration solutions. The hydrogen backbone conversion segment offers lowest competitive density, with Jutland trunk line steel segments requiring embrittlement-resistant material assessments. A go-to-market angle anchored in EU Methane Regulation compliance technology addresses monitoring system deployment gaps. For Investors and Strategic Acquirers: Consolidation pressure builds where pipeline operators face overlapping hydrogen repurposing engineering timelines and stranded asset risk. Long-term viability favors entities with diversified terminal operations spanning hydrocarbon, offshore wind, and Power-to-X logistics. Target acquisition archetypes include regional storage facility operators with salt cavern assets adaptable to hydrogen service. The signal to watch is Danish Energy Agency CO2 storage license issuance velocity as inflection indicator for carbon transport infrastructure valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Pipeline Conversion to CO2 Service | Repositions depleted North Sea corridors under Danish Energy Agency carbon storage licensing. |
| Hydrogen Backbone Engineering Assessment | Adapts Jutland trunk line steel segments for embrittlement-resistant transport under Energinet codes. |
| Multi-Service Terminal Diversification | Expands Esbjerg port cluster into offshore wind manufacturing logistics beyond hydrocarbon handling. |
| Digital Monitoring System Deployment | Addresses EU Methane Regulation compliance through distributed acoustic sensing across high-pressure corridors. |
| Long-Term Capacity Contract Structuring | Anchors revenue streams via Energinet monopoly position and buyer pooling among Jutland power utilities. |
Study Parameters
Direct dialogue with pipeline integrity engineers, Energinet regulatory affairs specialists, offshore platform project managers, and carbon storage licensing officers grounded qualitative findings. Secondary validation drew from Danish Energy Agency safety case filings, EU Network Codes implementation documents, Energinet technical code revisions, and North Sea decommissioning databases. Bottom-up field-level throughput estimates triangulated against top-down infrastructure capacity assessments.
Bottom-up modeling of pipeline utilization rates, storage facility injection cycles, and processing plant throughput volumes converged with top-down national energy demand projections across the analysis window. Segmentation dimensions included product type, service category, technology system, and end-user concentration. CAGRs were derived from infrastructure investment schedules and regulatory repurposing timelines. Forecast inputs incorporated North Sea production decline curves and EU security-of-supply mandate enforcement patterns.
Inputs from Energinet operational disclosures and Danish Energy Agency licensing records were available through the study window; gaps in private terminal operator financials introduce uncertainty bands around revenue allocation estimates. Forecasts reflect documented assumptions regarding hydrogen blending timeline adoption and carbon capture project sanctioning rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Hose Assemblies Market
Oil & Gas
Oilfield Equipment Rental Services Market
Oil & Gas
Offshore Oil and Gas Paints and Coatings Market
Oil & Gas
North America Perforating Gun Market
Oil & Gas
Oil & Gas Static and Rotating Equipment Market
Oil & Gas
Sudan Oil and Gas Market
Oil & Gas
Southeast Asia Oil and Gas Downstream Market
Oil & Gas
Europe Oilfield Equipment Rental Services Market
Oil & Gas
India LNG Bunkering Market
Oil & Gas
Oilfield Roller Chain Market
Oil & Gas
GCC Natural Gas Market
Oil & Gas
Unconventional Gas Market
Oil & Gas
North America Wireline Logging Services Market
Oil & Gas
HPHT Cubic Press Market
Oil & Gas
Cuttings Re-Injection Services Market
Oil & Gas
Algeria Oil and Gas Market