
 Battery Grade Lithium Chloride Market | 2026-2036
Battery Grade Lithium Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Grade Lithium Chloride Market Insights
China's GB/T standards for battery-grade lithium salts is recalibrating the cost-of-entry calculus for new producers seeking domestic qualification. Albemarle Corporation leverages its Kings Mountain processing complex to sustain North American supply continuity for qualified automakers. Jiangxi Ganfeng Lithium anchors its position through captive brine-to-cathode integration across Argentina and China. Tianqi Lithium controls the world's highest-grade spodumene feedstock at Greenbushes, translating into superior chloride purity metrics.
Battery grade lithium chloride denotes lithium chloride refined to purity levels exceeding 99.5 percent, with controlled sodium, potassium, and magnesium impurities below 50 parts per million, produced via crystallization and ion-exchange purification for electrolyte formulation in lithium-metal and solid-state cells. The electrolyte application segment dominates current volume flows, while the additive segment for silicon-anode stabilization exhibits the fastest structural expansion as manufacturers pursue energy density above 400 watt-hours per kilogram. Battery manufacturers as an end-user category occupy the deepest margin pools, though automotive OEMs are extending captive offtake agreements to lock in five-year chloride supply corridors.
China's NMPA and SAMR jointly enforce evolving purity benchmarks under the national GB standards framework, while the EU's REACH and Battery Regulation impose traceability and carbon-intensity disclosure requirements on imported lithium chemicals entering European cell plants. The US EPA and OSHA maintain overlapping jurisdiction over chloride handling and worker exposure limits at domestic conversion facilities. Stakeholders must monitor regulatory divergence between Chinese certification protocols and emerging EU battery passport rules to avoid stranded inventory in cross-border supply chains.
Market Dynamics
Solid-state battery chemistry is restructuring procurement priorities across the lithium chloride value chain, as automakers and cell manufacturers recalibrate electrolyte specifications for next-generation energy density targets.
Growth Catalysts
- GB/T Standard Tightening:China's NMPA and SAMR are elevating purity thresholds for battery-grade lithium salts, forcing feedstock upgrades across the domestic processing base and redirecting import flows toward certified suppliers.
- Solid-State Electrolyte Demand:Lithium-metal anode architectures require ultra-pure chloride formulations with sub-50 ppm alkali metal contamination, creating a premium tier distinct from conventional lithium-ion feedstock.
- Jiangsu Processing Corridor:Concentrated chemical conversion capacity near Changzhou and Taixing is attracting downstream cell manufacturers seeking integrated chloride-to-electrolyte supply chains.
Market Restraints
- Spodumene Feedstock Concentration:Greenbushes and limited hard-rock alternatives dominate high-grade lithium source material, exposing chloride refiners to concentrated upstream pricing power.
- Energy-Intensive Crystallization:Ion-exchange purification and multi-stage recrystallization consume substantial thermal and electrical inputs, compressing margins when energy costs spike.
- REACH Traceability Burden:The EU Battery Regulation mandates carbon-intensity disclosure and supply chain documentation, adding compliance overhead for exporters serving European cell plants.
Strategic Opportunities
- Silicon-Anode Stabilization Additives:High-energy-density cell designs incorporating silicon require chloride-derived electrolyte modifiers, opening a faster-growing application segment beyond standard electrolyte volumes.
- Argentina Brine Integration:Direct extraction and captive conversion assets in South American salares offer chloride producers pathway to lower-carbon feedstock qualifying for EU battery passport requirements.
- Automotive OEM Captive Offtake:Five-year supply corridors with direct automaker contracting bypass merchant market volatility and secure volume commitments for qualified producers.
Industry Challenges
- Electrochemical Purity Talent Scarcity:Specialized expertise in trace-element control and crystallization engineering remains concentrated among a limited pool of process chemists, constraining facility commissioning timelines.
- Dual Certification Complexity:Producers must simultaneously satisfy China's GB/T protocols and emerging EU battery passport rules to avoid stranded inventory in trans-Pacific supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Grade Lithium Chloride Market |
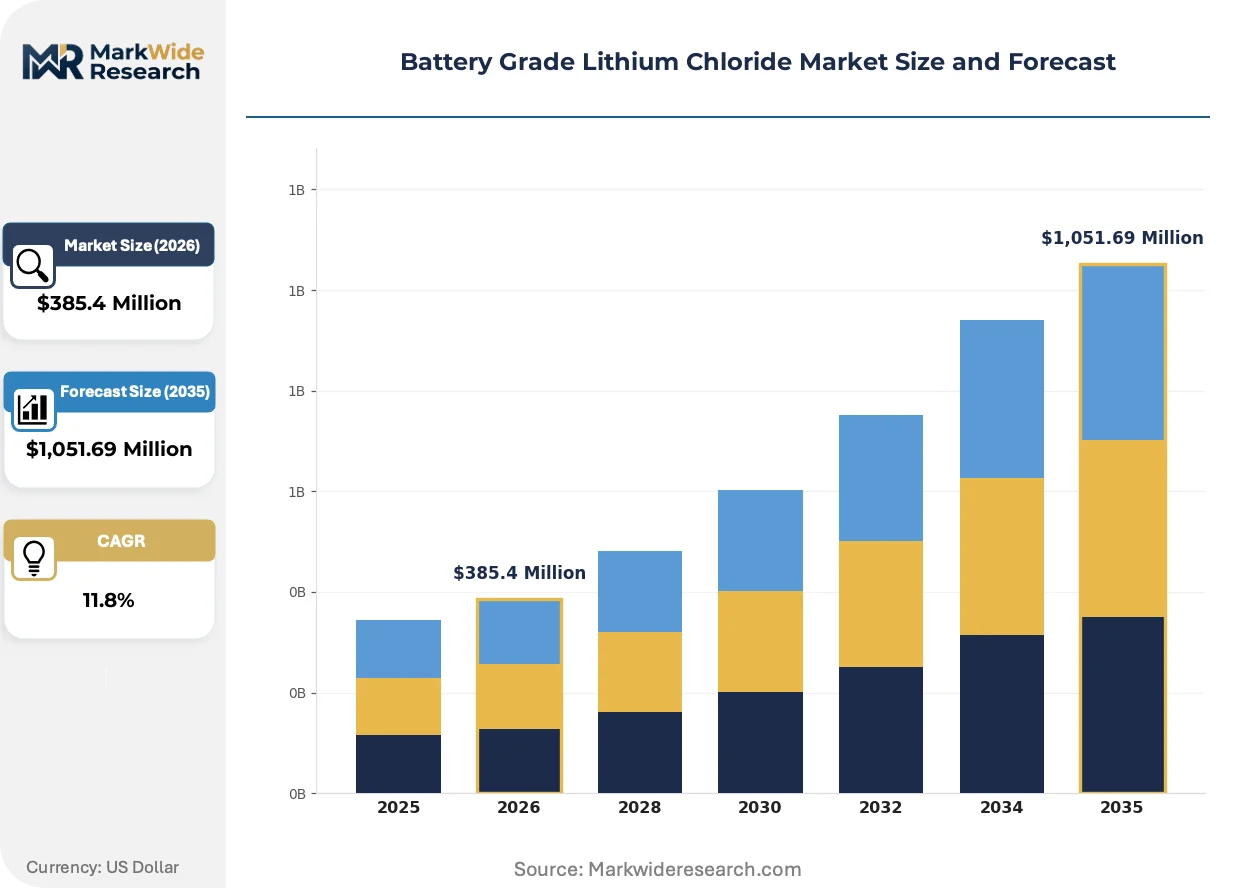
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,051.69 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Industrial Grade, Battery Grade, Reagent Grade Application: Electrolyte, Catalyst, Lithium Extraction, Additive End User: Battery Manufacturers, Automotive OEMs, Electronics Industry, Renewable Energy Sector Packaging Type: Bulk Bags, Drums, Bags, Containers |
| Companies Covered | Albemarle Corporation, Jiangxi Ganfeng Lithium, Tianqi Lithium, SQM, Livent, Leverton-Clarke, Nippon Chemical Industrial, Shenzhen Chengxin Lithium Group, Jiangsu Changjili New Energy Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Grade Lithium Chloride Market Trends and Innovations
Electrolyte formulation chemistry is diverging along performance-tier lines, with solid-state architectures demanding fundamentally different purity profiles than conventional liquid-electrolyte cells.
Sulfide-based solid electrolytes are overtaking oxide alternatives in automotive qualification programs due to superior ionic conductivity at room temperature. Cell manufacturers in South Korea and Japan are accelerating sulfide electrolyte pilot lines, compressing development timelines for compatible ultra-pure chloride feedstock. This chemistry shift is overtaking legacy carbonate-based electrolyte procurement patterns and reshaping supplier qualification criteria.
REACH and the EU Battery Regulation are imposing mandatory carbon-intensity disclosure on imported lithium chemicals entering European conversion facilities. This regulatory layering is diverting investment toward brine-based and direct-extraction feedstock with verifiable emissions profiles. European cell plants are now prioritizing chloride suppliers with certified low-carbon production pathways.
Automotive OEMs are consolidating electrolyte procurement through direct five-year offtake agreements rather than merchant market spot purchasing. This contractual shift is compressing intermediary trading margins and privileging producers with demonstrated purity consistency and integrated logistics capabilities. The transformation is most visible in German and South Korean battery manufacturing clusters where automaker-cell maker joint ventures dominate capacity planning.
Battery Grade Lithium Chloride Market Segmentation
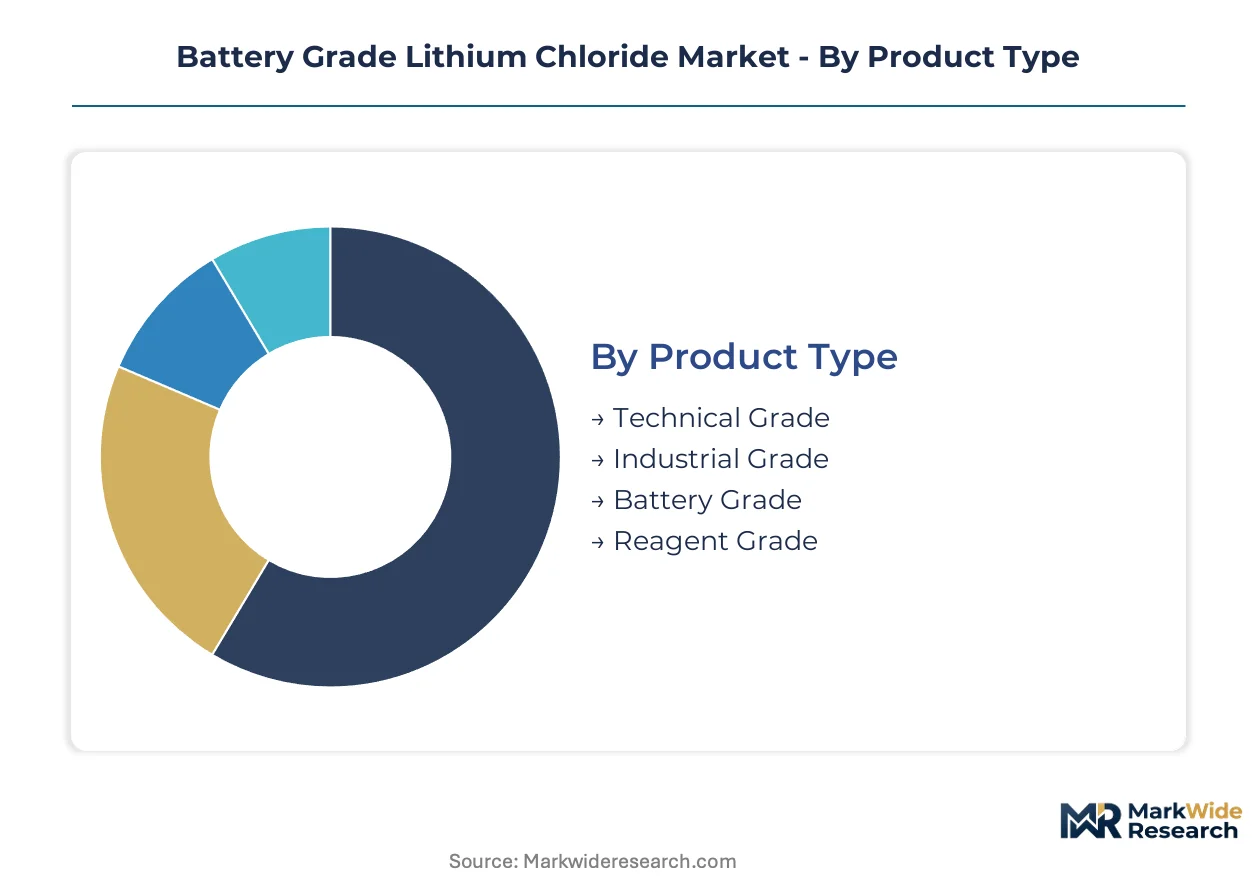
Segmentation in battery-grade lithium chloride reflects divergent purity requirements across cell chemistries and end-use specifications. Buyers prioritize electrochemical consistency over commodity pricing, fragmenting procurement patterns along application lines.
Product Type:
Buyers segment procurement by electrochemical specification thresholds, with battery-grade commanding premium qualification protocols.
- Battery Grade:Refined to exceed 99.5% purity with sodium, potassium, and magnesium impurities controlled below 50 ppm. Jiangsu province's processing corridor near Changzhou concentrates demand for this tier as solid-state battery developers accelerate qualification programs.
- Technical Grade:Moderate purity specifications serve industrial catalyst and metallurgical applications outside electrochemical uses. Demand concentrates in chemical manufacturing clusters where cost sensitivity outweighs trace-element control requirements.
- Industrial Grade:Standard purity for general chemical synthesis and dehumidification systems. Procurement flows through bulk chemical distributors serving construction and HVAC sectors.
- Reagent Grade:Ultra-high purity for analytical and laboratory applications requiring precise stoichiometric control. Life sciences and materials research institutes in Germany and Japan anchor demand.
Battery Grade leads on scale; Reagent Grade leads on momentum.
Application:
Application segmentation tracks chemistry evolution from liquid-electrolyte lithium-ion toward solid-state architectures.
- Electrolyte:Dominant volume segment supplying lithium salt precursors for liquid and polymer electrolyte formulations. South Korean cell manufacturers in Gyeonggi-do province sustain the deepest procurement corridors.
- Additive:Chloride-derived surface modifiers stabilize silicon-anode interfaces in high-energy-density designs. This segment climbs fastest as manufacturers pursue energy density above 400 Wh/kg.
- Lithium Extraction:Feedstock for direct lithium extraction and brine concentration processes. Argentina's Salar del Hombre Muerto anchors captive demand from integrated producers.
- Catalyst:Chemical synthesis applications in pharmaceutical and fine chemical production. Batch-scale procurement from European specialty chemical manufacturers characterizes this niche.
Electrolyte maintains volume dominance; Additive captures the steepest expansion trajectory.
End User:
End-user segmentation reveals margin stratification between merchant chemical buyers and captive automotive supply chains.
- Battery Manufacturers:Direct procurement of qualified chloride feedstock for electrolyte blending operations. CATL and LG Energy Solution operations in Jiangsu and Gyeonggi-do concentrate demand.
- Automotive OEMs:Volkswagen, BMW, and Hyundai are extending five-year offtake agreements to lock in supply corridors. Direct contracting bypasses merchant market volatility.
- Electronics Industry:Consumer battery and capacitor manufacturers requiring consistent batch-to-batch purity. Procurement scales with portable electronics assembly in Vietnam and Mexico.
- Renewable Energy Sector:Grid-scale storage system integrators sourcing chloride for lithium-metal battery development. Project developers in Texas and South Australia drive emerging demand.
Battery Manufacturers lead on scale; Automotive OEMs lead on contract duration.
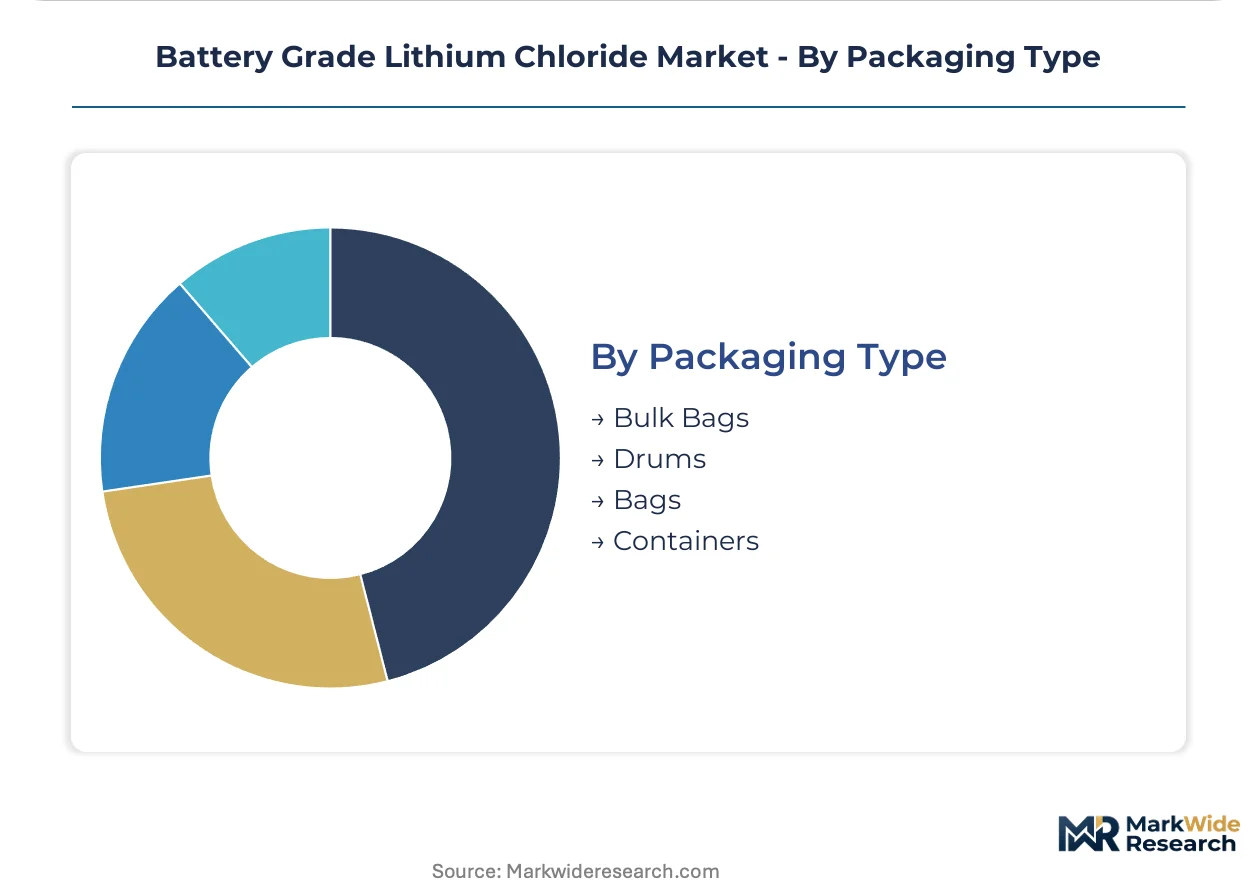
Packaging Type:
Packaging selection balances contamination risk against logistics economics across supply chain configurations.
- Bulk Bags:Ton-scale flexible containers for integrated chloride-to-electrolyte facilities. Jiangsu's Changzhou industrial zone favors this format for captive consumption.
- Drums:Steel or fiber drums for qualified battery-grade material requiring moisture exclusion. German and South Korean cell plants specify drum packaging for import shipments.
- Bags:Multi-layer polymer bags for technical and industrial grades. Chemical distributors in India and Southeast Asia prefer this format for break-bulk distribution.
- Containers:ISO tank containers for large-volume liquid chloride solutions. Maritime routes from Argentina to European conversion facilities utilize this configuration.
Bulk Bags lead on scale; Containers lead on cross-border logistics efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial lithium chloride refining originated in Germany's chemical corridor during the early twentieth century, establishing quality benchmarks that persist in today's electrochemical specifications. Contemporary production geography reflects the migration of battery manufacturing toward East Asian cell clusters and South American brine resources.
China
Jiangsu province's Changzhou-Taixing industrial corridor hosts the densest concentration of chloride-to-electrolyte conversion capacity worldwide. NMPA and SAMR jointly enforce escalating GB/T purity thresholds that redirect import flows toward certified feedstock suppliers. Tianqi Lithium anchors upstream supply through its Greenbushes spodumene offtake, feeding refineries in the Yangtze River Delta.
United States
Albemarle Corporation's Kings Mountain processing complex sustains North American supply continuity for qualified automakers seeking domestic qualification. EPA and OSHA maintain overlapping jurisdiction over chloride handling and worker exposure limits at conversion facilities. The Southeast battery belt spanning Georgia and Tennessee is attracting electrolyte blending operations to serve regional cell plants.
Germany
REACH and the EU Battery Regulation impose mandatory carbon-intensity disclosure and traceability requirements on imported lithium chemicals entering European conversion facilities. ECHA oversees compliance frameworks that privilege suppliers with verifiable low-carbon production pathways. The country's chemical manufacturing tradition in Ludwigshafen and Leverkusen sustains specialized reagent-grade chloride demand for materials research.
South Korea
Gyeonggi-do province concentrates the deepest procurement corridors for electrolyte-grade chloride serving lithium-ion cell manufacturers. MFDS and METI-aligned standards govern import qualification protocols for battery material feedstock. Samsung SDI and LG Energy Solution operations in Suwon and Ochang are extending direct offtake agreements to secure five-year supply corridors.
Argentina
Salar del Hombre Muerto and Cauchari-Olaroz brine resources offer integrated producers a pathway to lower-carbon chloride qualifying for EU battery passport requirements. The national mining secretariat oversees lithium export licensing frameworks that favor captive conversion investments. Jiangxi Ganfeng Lithium's operations in Catamarca province exemplify the brine-to-cathode integration model reshaping regional supply economics.
Battery Grade Lithium Chloride Market Competitive Landscape
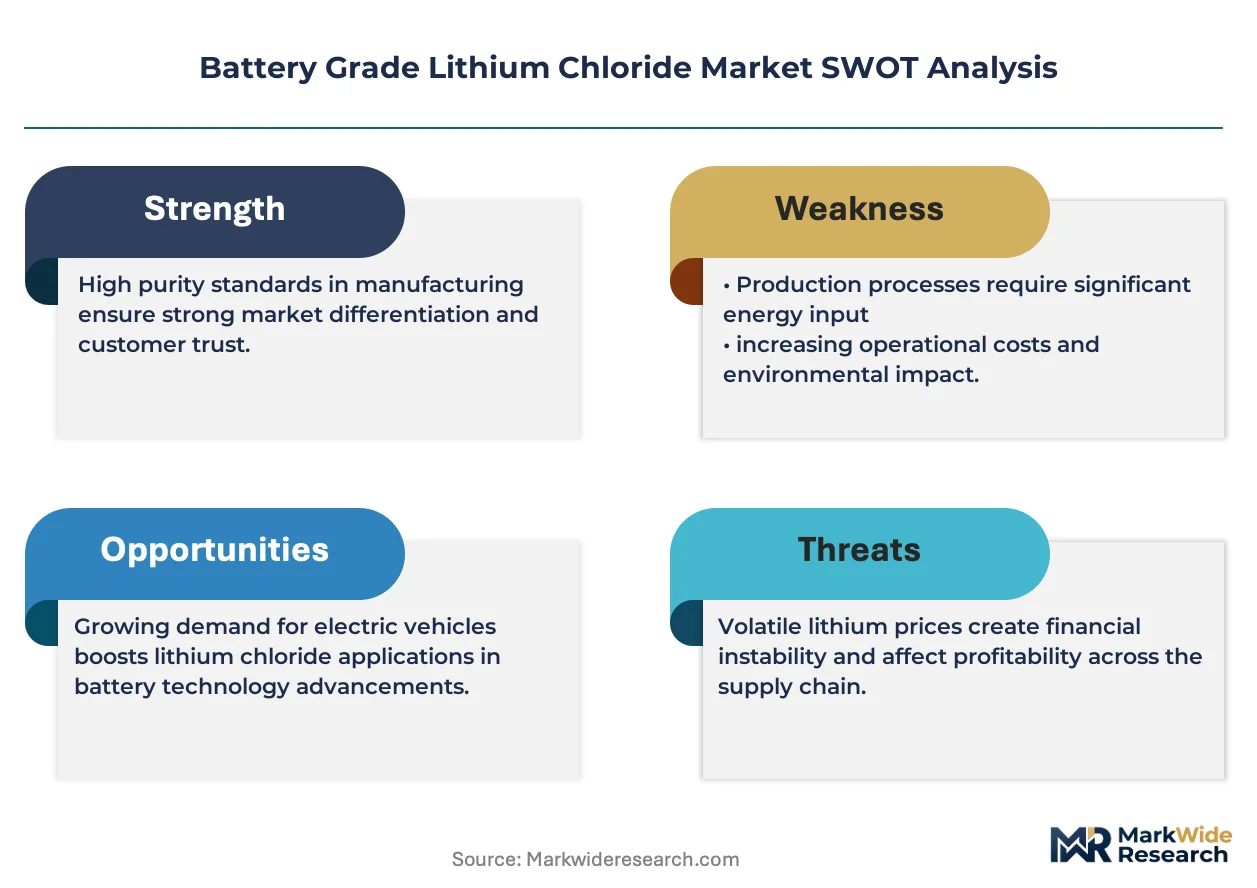
The competitive structure tilts toward integrated resource holders with captive upstream feedstock and qualified downstream offtake relationships. Tiered positioning separates producers with spodumene or brine integration from merchant refiners exposed to spot feedstock volatility. Three archetypes dominate: hard-rock integrated majors, South American brine operators, and regional Chinese conversion specialists. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with producers securing automaker offtake agreements to bypass merchant market exposure.
Among integrated majors, Albemarle Corporation exemplifies the North American qualification-focused archetype through its Kings Mountain complex. Jiangxi Ganfeng Lithium and Tianqi Lithium occupy positions within the Chinese integrated tier, each leveraging distinct upstream configurations—Ganfeng through Argentine brine assets and Tianqi through Greenbushes spodumene dominance. SQM represents the South American brine-integrated model with operations spanning Chile's Atacama salar. These four entities anchor the competitive landscape through control of finite high-grade feedstock sources and established automaker qualification pathways.
| Leading Market Players |
|---|
| Albemarle Corporation |
| Jiangxi Ganfeng Lithium |
| Tianqi Lithium |
| SQM |
| Livent |
| Leverton-Clarke |
| Nippon Chemical Industrial |
| Shenzhen Chengxin Lithium Group |
| Jiangsu Changjili New Energy Technology |
| Others |
Pricing and Supply Chain Analysis
Solid-state electrolyte qualification requirements are compressing cost economics across the lithium chloride value chain while simultaneously concentrating supply relationships around certified producers with demonstrated purity consistency. Ion-exchange purification and multi-stage recrystallization consume substantial thermal and electrical inputs, forcing merchant refiners to absorb margin pressure or exit the premium tier entirely.
Pricing Analysis
Bundled long-term offtake agreements with integrated logistics and certification support command substantial premiums over unbundled spot market transactions. Price differentiation hinges on GB/T certification tier and automaker qualification status, with battery-grade material carrying measurable premiums against technical-grade alternatives. Cost compression in the merchant refiner tier is intensifying because Greenbushes spodumene offtake concentrates upstream pricing power among integrated majors. Battery manufacturers exhibit the deepest price insensitivity due to electrolyte qualification lock-in, while industrial chemical buyers retain flexibility to substitute technical grades.
Supply Chain Analysis
China's evolving domestic-content thresholds under NMPA certification protocols are redirecting import flows toward qualified suppliers with established Yangtze River Delta processing footprints. Geographic supply concentration centers on China, Argentina, and Australia, with Jiangsu province's Changzhou-Taixing corridor hosting the densest conversion capacity. Raw material dependencies rest on spodumene concentrate from Western Australia, brine from Argentine salares, and sulfuric acid for leaching operations. Single-source vulnerability around Greenbushes feedstock exposes chloride refiners to concentrated upstream pricing power. Distribution runs through integrated chloride-to-electrolyte facilities serving captive cell manufacturer demand, supplemented by drum-packaged imports for qualified European and South Korean plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in the solid-state electrolyte premium tier, where energy-intensive purification processes create natural barriers against commodity-grade competition. Direct extraction and captive brine conversion in Argentina offer the most credible cost-down pathway for new capacity.
For Market Incumbents: Anticipate sulfide-based solid electrolyte chemistry shifts by securing five-year automaker offtake corridors before qualification windows close. Defensive moves center on backward integration into Argentine brine assets to satisfy EU battery passport carbon-intensity requirements, and capacity additions in Jiangsu province to maintain proximity to CATL and LG Energy Solution demand clusters. Certification investment in dual GB/T and REACH compliance represents the critical lever against stranded inventory risk.
For New Entrants and Emerging Players: Enter via silicon-anode stabilization additive supply, the fastest-expanding application segment with less entrenched qualification barriers than standard electrolyte volumes. White-space targets include direct lithium extraction feedstock supply to European cell plants seeking verifiable low-carbon pathways, and reagent-grade chloride for materials research institutes in Germany and Japan. A go-to-market angle anchored in carbon-intensity disclosure and supply chain traceability documentation bypasses incumbent volume advantages.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional Chinese conversion specialists lacking captive upstream feedstock but possessing NMPA certification and Jiangsu corridor logistics access. Long-term viability over the projection horizon favors producers with demonstrated dual-certification capability and integrated brine or spodumene supply. The signal to watch is automaker direct contracting velocity, as five-year supply corridor announcements indicate qualification tier consolidation ahead of merchant market displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Assets | Captive Argentine salar feedstock satisfies EU battery passport carbon thresholds for European cell plants. |
| Dual Certification Investment | Simultaneous GB/T and REACH compliance prevents stranded inventory in trans-Pacific supply chains. |
| Silicon-Anode Additive Capacity | Surface modifier production captures the steepest expansion trajectory in high-energy-density cell designs. |
| Automotive OEM Direct Offtake | Five-year supply corridors with Volkswagen or Hyundai bypass merchant market volatility and secure volume. |
| Jiangsu Corridor Expansion | Changzhou-Taixing proximity to CATL and LG Energy Solution operations minimizes logistics contamination risk. |
Research Methodology
Bottom-up electrolyte demand modeling reconciled against top-down spodumene and brine supply tracking forms the analytical core of this study. Primary interviews with solid-state battery development leads, NMPA certification officers, electrolyte procurement managers at cell manufacturers, and Argentine mining secretariat officials were cross-validated against secondary sources including customs and trade data, SEC filings from integrated lithium majors, GB/T standard documentation, and EU Battery Regulation implementation guidance. Triangulation between end-use consumption estimates and feedstock conversion capacity assessments ensures coherence across the value chain.
Input-output matrices map lithium chloride production across grade tiers, application segments, and regional processing hubs throughout the forecast period. Segmentation dimensions modeled include product purity specification, electrolyte versus additive end-use, battery manufacturer versus automotive OEM procurement channel, and packaging format for contamination control. CAGRs were derived from elasticity-adjusted demand projections and capacity commissioning timelines. Industry-specific forecast inputs incorporate solid-state battery pilot line announcements, automaker offtake contract disclosures, and NMPA certification timeline revisions.
Inputs from primary fieldwork and regulatory filing databases were available through the study window; gaps in real-time automaker qualification status and confidential offtake pricing introduce uncertainty bands around volume and value estimates. Forecasts reflect documented assumptions regarding sulfide electrolyte chemistry adoption velocity, GB/T standard implementation timing, and EU battery passport enforcement stringency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
North America Calcium Carbonate Market
Bulk Chemicals
2-Ethylhexanoyl Chloride Market
Bulk Chemicals
Glyceryl Triacetate (Triacetin) Market
Bulk Chemicals
Bulk Ingredients Market
Bulk Chemicals
Banlangen Granules Market
Bulk Chemicals
Europe Lime Market
Bulk Chemicals
Putty Powder Market
Bulk Chemicals
Acetyl Tributyl Citrate Market
Bulk Chemicals
Dimethyl Disulphide (DMDS) Market
Bulk Chemicals
Zinc L-Pidolate Market
Bulk Chemicals
Phenylalanine Market
Bulk Chemicals
Sodium Tungstate Dihydrate Market
Bulk Chemicals
Brazil Magnesium Phosphate Market
Bulk Chemicals
Ammonium Molybdate Market
Bulk Chemicals
Carbamide Market
Bulk Chemicals
Global Basic Chemicals Market