
 Nahcolite Market | 2026-2036
Nahcolite Market Size, Share, and Industry Trends Forecast 2026-2036
Nahcolite Market Outlook
ISO 22000 food safety certification is bifurcating competitive access as processors without verified supply chain traceability lose shelf space to qualified rivals. Natural Soda Holdings Inc leverages its captive Wyoming mining assets to anchor North American supply security. Solvay SA sustains European market presence through synthetic nahcolite capacity that competes on purity consistency. Tata Chemicals Ltd operates integrated soda ash-nahcolite complexes in India, extending cost advantages across Asian pharmaceutical channels.
Nahcolite is a naturally occurring sodium bicarbonate mineral with chemical formula NaHCO₃, typically mined from evaporite deposits and processed to purity grades ranging from industrial feedstock to USP/FCC-compliant fine powders for direct consumption. Its primary commercial purpose centers on acid neutralization, thermal decomposition to release CO₂, and pH buffering across food, pharmaceutical, and chemical applications. Natural nahcolite dominates volume flows into industrial flue gas treatment and animal feed buffering, while purified nahcolite captures margin concentration in pharmaceutical tablet formulations and injectable-grade bicarbonate solutions. Specialty nahcolite grades engineered for controlled particle size distribution are gaining traction in high-performance chemical synthesis where batch reproducibility commands price premiums.
EPA emissions standards for coal-fired utilities and industrial boilers are mandating dry sorbent injection systems, directly expanding nahcolite consumption as a lower-cost alternative to lime-based scrubbing. FDA food additive regulations under 21 CFR 184.1736 and evolving EFSA purity specifications for sodium bicarbonate in processed foods are reshaping qualification requirements for suppliers seeking multi-jurisdictional market access. REACH registration obligations for imported bicarbonate derivatives further filter the European vendor base toward integrated producers with analytical documentation capabilities. Stakeholders must monitor regulatory divergence between US and EU purity thresholds to avoid compliance-driven supply fragmentation that could reshape sourcing strategies.
Market Dynamics
EPA emissions mandates for coal-fired utilities are accelerating dry sorbent injection adoption, anchoring nahcolite demand in flue gas desulfurization while food-grade purity requirements bifurcate supplier tiers across North American and European markets.
Growth Catalysts
- Utility Emissions Compliance:EPA Mercury and Air Toxics Standards mandate dry sorbent injection systems at coal-fired power plants, expanding nahcolite consumption as a lower-cost alternative to lime-based scrubbing technologies.
- Natural Leavening Demand:Food and beverage manufacturers are reformulating processed products with sodium bicarbonate to replace synthetic additives, tightening supply qualification requirements under FDA 21 CFR 184.1736.
- Green River Supply Security:Wyoming's nahcolite deposits anchor North American supply chains, reducing import dependency for industrial feedstock and pharmaceutical-grade material.
Market Restraints
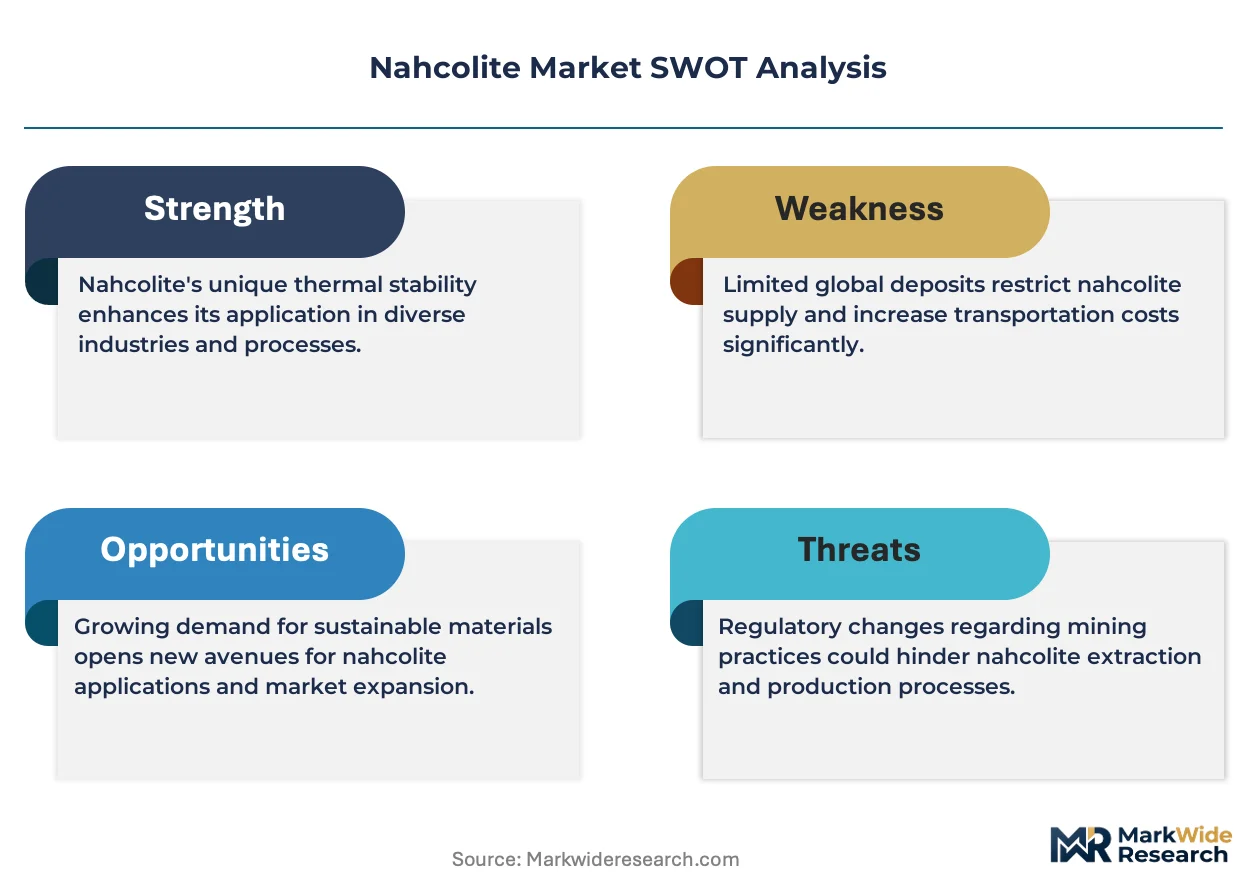
- Input Energy Volatility:Natural gas and electricity costs drive synthetic nahcolite production economics, compressing margins for Solvay SA's European capacity during price spikes.
- Wyoming Concentration Risk:Overreliance on the Green River Formation creates single-point-of-failure exposure for North American industrial consumers during rail or labor disruptions.
- Lime Substitution Threat:Calcium-based scrubbing technologies retain cost advantages in high-sulfur applications, limiting nahcolite penetration in certain utility retrofit scenarios.
Strategic Opportunities
- Indian Pharmaceutical Expansion:CDSCO manufacturing incentives and export-oriented production hubs create demand for USP-grade nahcolite in generic drug formulations.
- Carbon Capture Integration:Thermal decomposition properties position nahcolite as a regenerable sorbent in emerging direct air capture systems under development.
- Specialty Chemical Synthesis:Controlled particle size distribution grades command price premiums in high-performance batch processes where reproducibility determines contract awards.
Industry Challenges
- REACH Documentation Burden:ECHA registration requirements for imported bicarbonate derivatives filter European vendor bases toward integrated producers with analytical capabilities.
- ISO 22000 Certification Timeline:Food safety verification processes extend 12-18 months, locking out unqualified processors from retail channel access.
- Mining Equipment Lead Times:Long-delivery capital equipment for underground nahcolite extraction constrains capacity expansion responses to demand spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nahcolite Market |
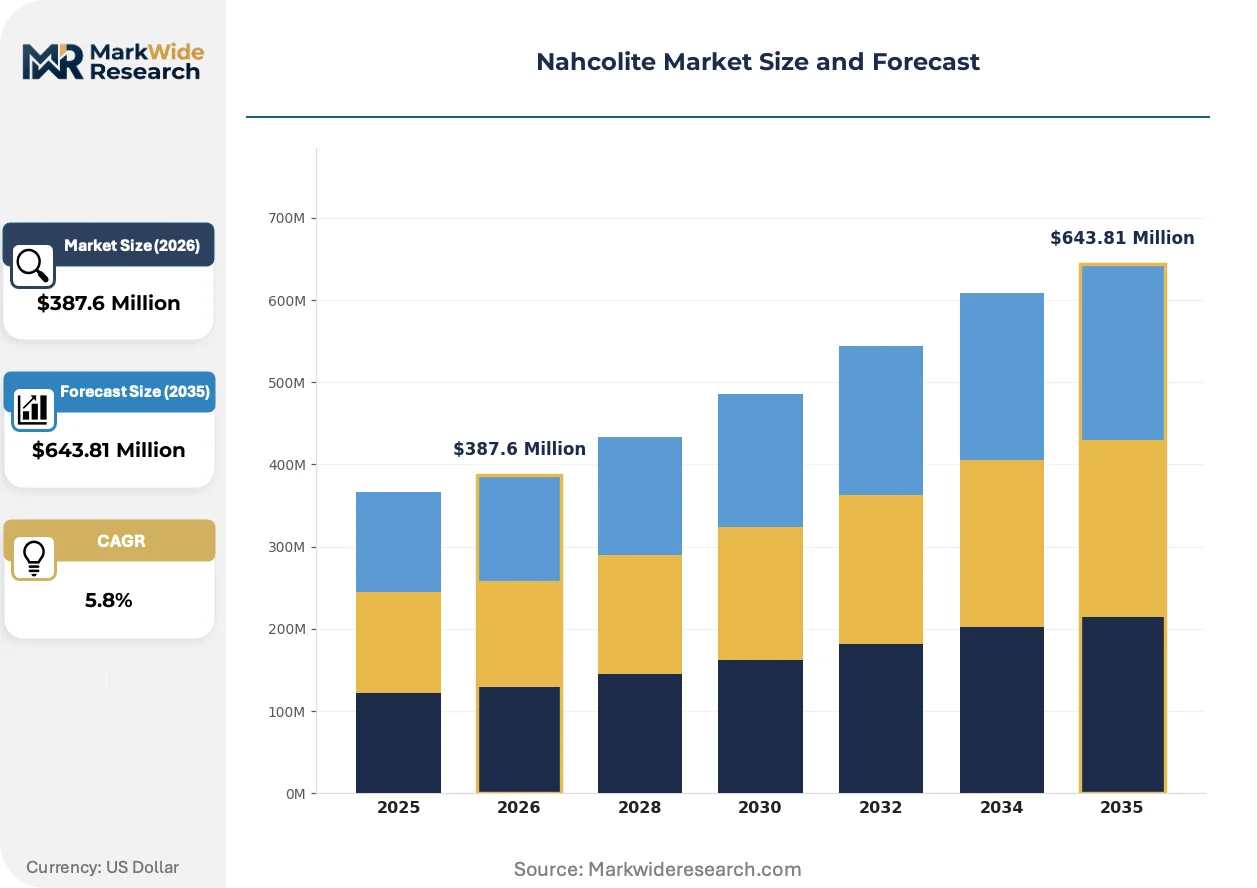
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Nahcolite, Synthetic Nahcolite, Purified Nahcolite, Specialty Nahcolite Application: Food Additives, Pharmaceuticals, Chemical Processing, Water Treatment End Use Industry: Food & Beverage, Healthcare, Agriculture, Industrial Packaging Type: Bulk Bags, Drums, Bags, Pallets |
| Companies Covered | Natural Soda Holdings Inc, Natrium Products Inc, Seqens Minerals, FMC Corporation, Solvay SA, Church and Dwight Co Inc, Tata Chemicals Ltd, Tosoh Corporation, Asahi Kasei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nahcolite Market Strategic Shifts
Process intensification in mining and purification is compressing production economics while regulatory divergence between US and EU purity thresholds reshapes multi-jurisdictional sourcing strategies.
Micronization technology for controlled particle size distribution is miniaturizing batch variability in pharmaceutical and specialty chemical applications. Contract manufacturers serving generic drug formulators are adopting sub-50-micron grades to reduce tablet weight variation. This capability compression is enabling domestic suppliers to displace imported sodium bicarbonate in precision-critical synthesis workflows.
REACH registration obligations for bicarbonate derivatives are tightening European vendor qualification requirements. ECHA documentation mandates filter import channels toward integrated producers with in-house analytical capabilities. Pharmaceutical-grade suppliers are responding by consolidating multi-site certification under centralized quality management systems.
Food manufacturers are consolidating sodium bicarbonate procurement under direct-supplier contracts with verified Wyoming traceability. Large retail chains are displacing distributor intermediaries to secure ISO 22000-compliant material with documented Green River origin. This channel compression is most visible in North American private-label processed food production.
Nahcolite Market Segmentation
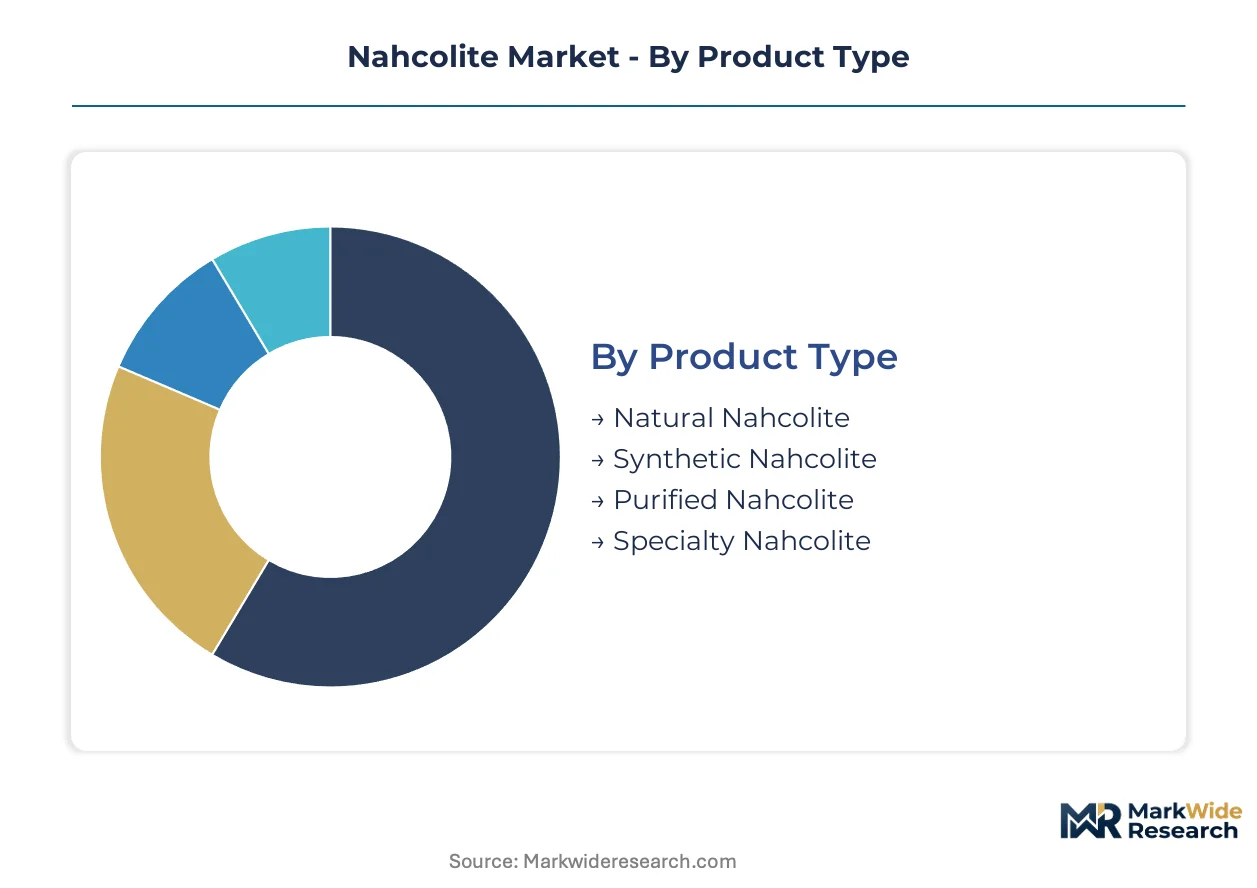
Nahcolite market segmentation reveals divergent margin structures across extraction methods, regulatory grades, and delivery formats. Understanding these tiered value pools enables suppliers to prioritize qualification investments and channel strategies.
Product Type:
Purified and specialty grades command the steepest margin premiums due to multi-stage processing and certification documentation burdens.
- Natural Nahcolite:Mined directly from evaporite deposits with minimal processing, typically 85-95% purity. Demand concentrates in flue gas desulfurization at US coal-fired utilities under EPA Mercury and Air Toxics Standards compliance timelines.
- Synthetic Nahcolite:Manufactured through Solvay process carbonation, delivering consistent 99%+ purity. European chemical processors favor this grade for batch reproducibility despite energy cost volatility compressing producer margins.
- Purified Nahcolite:USP/FCC-compliant material for pharmaceutical and food applications.
- Specialty Nahcolite:Engineered particle size distributions for precision synthesis.
The dominant share belongs to natural nahcolite, while specialty grades are closing the gap fastest.
Application:
Pharmaceutical and food additive channels absorb disproportionate value through regulatory certification requirements that filter supplier participation.
- Food Additives:Leavening agent and pH buffer in processed foods under FDA 21 CFR 184.1736. Large North American retail chains now mandate ISO 22000 traceability with documented Wyoming origin, displacing distributor intermediaries.
- Pharmaceuticals:Tablet formulations, antacid preparations, and injectable-grade bicarbonate solutions. Indian CDSCO manufacturing incentives are expanding demand for USP-grade material in generic drug export hubs.
- Chemical Processing:Feedstock for soda ash derivatives and specialty synthesis.
- Water Treatment:pH adjustment and alkalinity control in municipal systems.
Food additives retain volume leadership, though pharmaceutical applications are climbing the fastest.
End Use Industry:
Healthcare and food sectors concentrate purchasing power through consolidated procurement under direct-supplier contracts with verified certification.
- Food & Beverage:Natural leavening demand is tightening supply qualification as manufacturers reformulate away from synthetic additives.
- Healthcare:Hospital and clinical consumption of pharmaceutical-grade bicarbonate for metabolic acidosis treatment and dialysis.
- Agriculture:Animal feed buffering to optimize rumen pH in dairy operations.
- Industrial:Flue gas treatment, chemical synthesis, and metallurgical applications.
Industrial offtake dominates current volumes, yet healthcare is gaining share fastest.
Packaging Type:
Format selection tracks customer scale and handling infrastructure, with bulk formats capturing industrial flows and unitized packaging serving fragmented downstream channels.
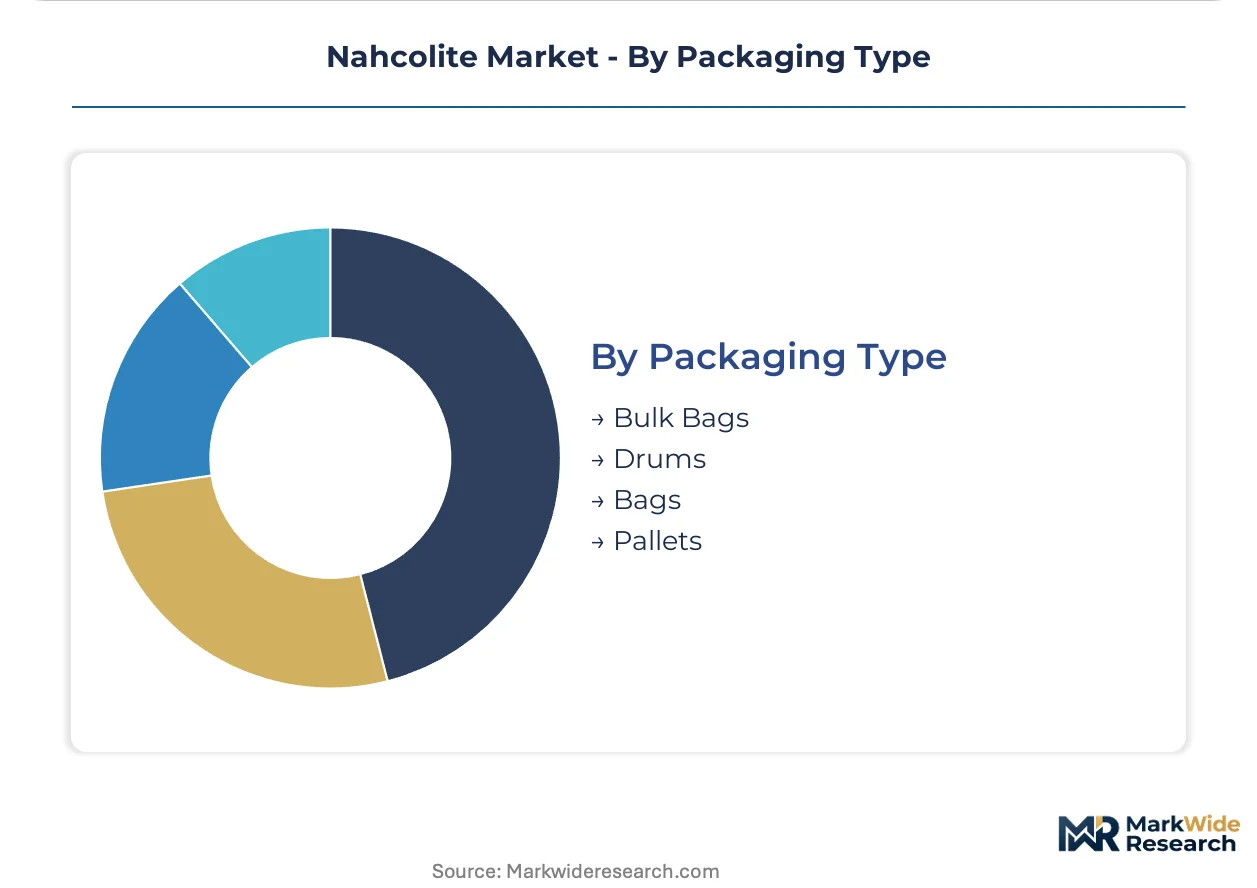
- Bulk Bags:1-2 ton flexible intermediate bulk containers for utility and chemical plant direct delivery. Wyoming mine-mouth loading to rail reduces handling costs for high-volume industrial consumers.
- Drums:200-250 liter steel or fiber containers for pharmaceutical and food-grade material requiring contamination protection.
- Bags:25-50 kg woven polypropylene for mid-scale food processors and agricultural distributors.
- Pallets:Unitized loads for warehouse efficiency in retail-facing supply chains.
Bulk bags command the dominant share, while drums are expanding most quickly on pharmaceutical grade demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Union Pacific rail corridor from Wyoming's Green River Basin to Chicago underwrites North American nahcolite supply security, anchoring industrial distribution networks that serve utility and food-grade consumers across the continent.
United States
Wyoming's Green River Formation hosts the world's largest nahcolite deposits, supplying dry sorbent injection systems at coal-fired utilities under EPA Mercury and Air Toxics Standards. FDA 21 CFR 184.1736 compliance requirements are tightening food-grade qualification timelines. Mine-mouth rail loading at Rock Springs anchors cost-efficient bulk distribution to Midwestern power plants and Gulf Coast chemical processors.
India
CDSCO manufacturing incentives are expanding demand for USP-grade nahcolite in generic drug export hubs around Hyderabad and Ahmedabad. FSSAI purity specifications for food additives are converging with international standards. Tata Chemicals' integrated Mithapur complex supplies pharmaceutical channels across South Asia with backward-integrated soda ash-nahcolite production.
Germany
Synthetic nahcolite capacity in the Rhine-Ruhr industrial cluster serves European chemical processors requiring batch reproducibility. ECHA REACH registration obligations filter import channels toward integrated producers with analytical documentation. BASF Ludwigshafen and surrounding chemical parks absorb specialty grades for precision synthesis applications.
Japan
PMDA pharmaceutical-grade specifications drive demand for high-purity sodium bicarbonate in Osaka-Kobe drug formulation clusters. METI industrial emissions guidelines are expanding utility sorbent consumption. Tosoh Corporation's Nanyo complex supplies injectable-grade material for dialysis and metabolic acidosis treatment.
China
MIIT industrial emissions standards are mandating flue gas treatment upgrades at coal-fired plants in the Yangtze River Delta. NMPA pharmaceutical regulations are tightening purity benchmarks for domestic drug manufacturers. Shandong and Hebei provinces host synthetic nahcolite capacity serving both industrial desulfurization and food additive channels.
Nahcolite Market Competitive Environment
Listed leaders compete with private specialists across certification depth and supply chain control dimensions. The vendor base organizes around three tiers: integrated miners with captive Wyoming assets, synthetic producers with energy-cost exposure, and pharmaceutical specialists with USP-grade purification capabilities. Strategic moves concentrate on ISO 22000 certification acceleration and direct-supplier contract consolidation with large food retailers.
Within the integrated mining tier, Natural Soda Holdings Inc represents captive supply security through Wyoming asset control, while Solvay SA exemplifies synthetic production economics dependent on European energy pricing. Tata Chemicals Ltd occupies a position bridging mining and chemical integration across Asian markets. These three anchors illustrate divergent competitive positions: geographic concentration versus purity consistency versus backward-integrated cost structure.
| Leading Market Players |
|---|
| Natural Soda Holdings Inc |
| Natrium Products Inc |
| Seqens Minerals |
| FMC Corporation |
| Solvay SA |
| Church and Dwight Co Inc |
| Tata Chemicals Ltd |
| Tosoh Corporation |
| Asahi Kasei Corporation |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Wyoming's Green River mines anchors North American price floors, as scale economies in underground extraction compress unit costs below synthetic alternatives and concentrate bargaining power among integrated producers serving EPA-mandated utility buyers.
Pricing Analysis
Certification level creates the primary spread between industrial feedstock and USP-grade material. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 21 CFR 184.1736 compliance burdens, ISO 22000 traceability investments, and volume-scale discounts for utility offtake agreements. Cost compression in synthetic production is intensifying because European natural gas volatility squeezes Solvay-process margins. Coal-fired utilities exhibit highest price sensitivity due to regulatory compliance cost absorption, while pharmaceutical formulators accept premium tiers for batch reproducibility assurance.
Supply Chain Analysis
Inventory lead times for underground mining equipment extend 18-24 months, constraining rapid capacity response to demand spikes and tethering expansion timelines to long-delivery capital cycles. Supply concentrates in the United States, India, and Germany, with Wyoming's Green River Formation anchoring natural extraction and the Rhine-Ruhr cluster hosting synthetic capacity. Critical inputs include natural gas for Solvay-process carbonation, specialized continuous mining machinery, and railcar fleets for bulk distribution. Single-source vulnerability pervades North American industrial channels dependent on Union Pacific corridor access. Distribution runs through mine-mouth rail loading to direct-supplier contracts with large food retailers and utility procurement desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is materializing as ISO 22000 certification becomes a gatekeeper credential for retail channel access, with interoperability between Wyoming traceability systems and buyer quality management platforms determining supplier survival.
For Market Incumbents: Fortify captive Wyoming asset control through long-term railcar leasing commitments and ISO 22000 certification acceleration ahead of 12-18 month qualification windows. Synthetic nahcolite substitution from European energy-cost volatility threatens margin stability in pharmaceutical channels; respond with backward integration into micronization capabilities for sub-50-micron specialty grades. For New Entrants and Emerging Players: Contract micronization services for pharmaceutical formulators represent the most penetrable service-layer gap, as incumbent miners under-invest in precision particle engineering. Target Indian CDSCO-registered generic drug export hubs around Hyderabad with USP-grade material sourced through tolling arrangements with Wyoming miners. Pursue direct-supplier positioning with mid-scale food processors bypassing distributor intermediaries. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated miners with certification depth over synthetic producers exposed to energy cost volatility. Long-term viability rests on regulatory durability of EPA emissions mandates and FDA food-grade purity convergence. Acquisition target archetype: Wyoming-based miners with unexploited specialty-grade purification capacity. Watch for EPA MATS enforcement acceleration as inflection signal for utility demand durability.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 22000 Certification Acceleration | Locks in retail channel access as large chains mandate documented traceability. |
| Backward Integration into Micronization | Captures pharmaceutical-grade premiums through controlled particle size distribution. |
| Long-term Railcar Leasing Commitments | Secures Union Pacific corridor capacity against logistics chokepoint exposure. |
| Direct-Supplier Contract Consolidation | Displaces distributor intermediaries in North American private-label food production. |
| Indian Pharmaceutical Channel Entry | Exploits CDSCO manufacturing incentives in generic drug export hubs. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with mine operations managers, utility procurement officers, pharmaceutical formulation scientists, and food safety quality directors; and secondary validation through EPA enforcement databases, FDA 21 CFR guidance documents, ECHA REACH registration filings, and customs trade flow records. Bottom-up triangulation across producer capacity disclosures and top-down demand modeling from end-use consumption patterns ensured cross-verified outputs.
Across the projection horizon, the analytical framework modeled nahcolite market evolution through grade-tier segmentation, end-use industry absorption rates, packaging format preferences, and regional production hub economics. CAGRs were derived from elasticity-adjusted demand curves incorporating EPA compliance timeline acceleration, FDA purity threshold evolution, and energy cost pass-through dynamics in synthetic production.
Forecasts assume regulatory continuity in EPA Mercury and Air Toxics Standards enforcement and FDA 21 CFR 184.1736 food additive specifications; material policy shifts in emissions mandate stringency or pharmaceutical purity benchmarks would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Lithium Chloride Market
Bulk Chemicals
Zinc Acetate Market
Bulk Chemicals
Encapsulated Sodium Bicarbonate Market
Bulk Chemicals
Sodium Sulphate Market
Bulk Chemicals
Benzyl Chloride Market
Bulk Chemicals
Global Sodium Borohydride Market
Bulk Chemicals
Global Cyclopentane Market
Bulk Chemicals
Global Tetrahydrofuran Market
Bulk Chemicals
4-Diisopropylbenzene Market
Bulk Chemicals
Brassylic Acid Market
Bulk Chemicals
Bio Based Paraxylene Market
Bulk Chemicals
Bulk Molding Compounds Market
Bulk Chemicals
Mancozeb Market
Bulk Chemicals
Fine Hydrate Market
Bulk Chemicals
Potassium Chloride Market
Bulk Chemicals
Bulk Chemical Packaging Market