
 Lithium Chemicals Market | 2026-2036
Lithium Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Chemicals Market Intelligence
Australian spodumene concentrate expansion is tilting the upstream supply balance for lithium feedstock. Albemarle Corporation leverages its diversified asset base across both brine and hard rock sources. Sociedad Química y Minera de Chile sustains a cost-advantaged position from its Atacama Desert brine operations. Ganfeng Lithium specializes in converting raw lithium into high-purity battery-grade compounds for the electronics and automotive sectors.
Lithium chemicals are inorganic compounds derived from lithium-bearing minerals or brines. These products, such as lithium hydroxide and lithium carbonate, are refined to high purity levels, often exceeding 99.5% for battery applications. Their primary purpose is to serve as a critical cathode and electrolyte material in rechargeable lithium-ion batteries. Within product types, lithium hydroxide is gaining preference for high-nickel cathode chemistries, while the batteries application overwhelmingly dominates all other uses like glass and ceramics.
The European Union’s Critical Raw Materials Act and the US Inflation Reduction Act (IRA) are reshaping supply chains by incentivizing local processing. Concurrently, China's GB standards for battery materials define market access and quality benchmarks for all producers. Securing long-term, ethically sourced supply contracts remains a central strategic challenge for downstream consumers in the automotive and energy storage sectors.
Market Dynamics
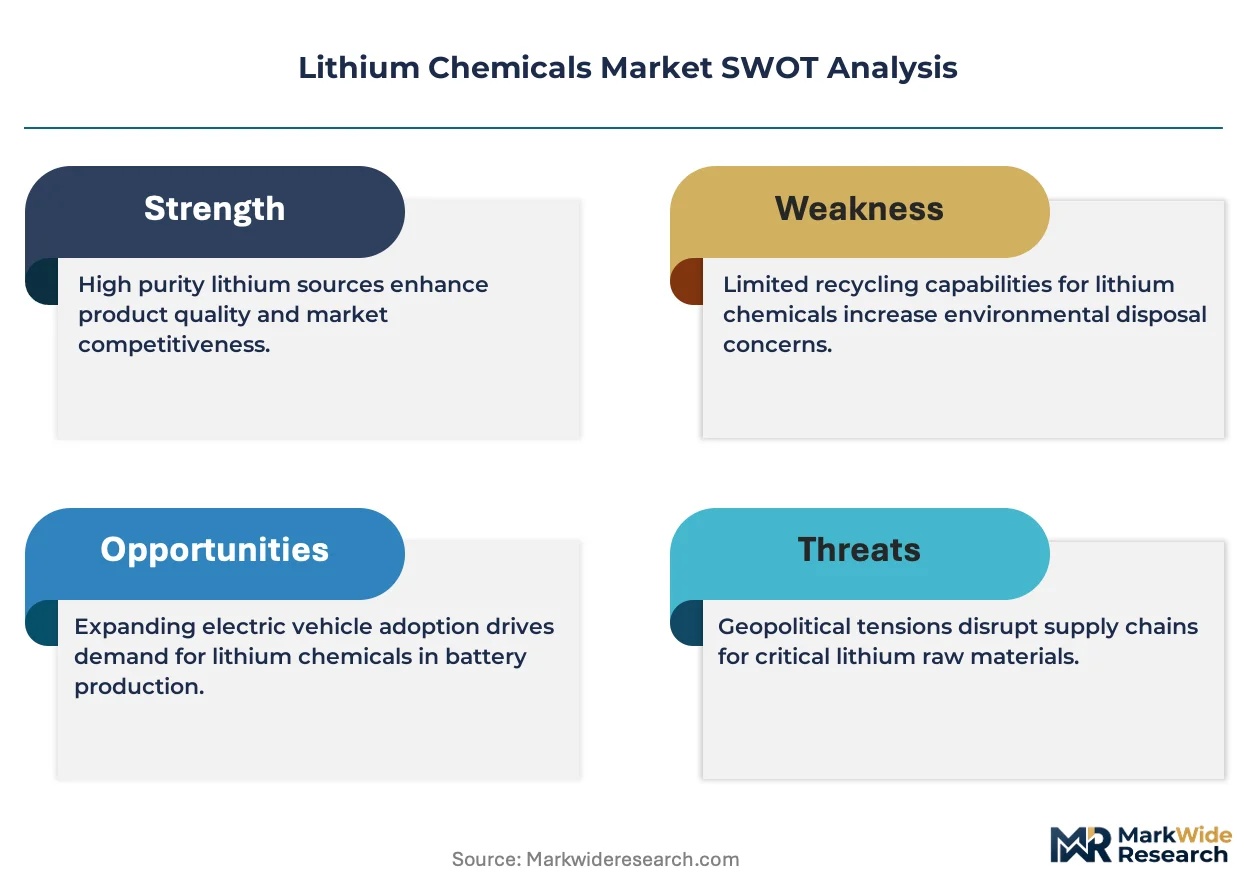
The central dynamic in the lithium chemicals market is the geopolitical tension between China's established dominance in refining and Western policy initiatives, like the US IRA, which are actively reshaping supply chains to favor domestic and allied production.
Growth Catalysts
- Government Incentives:The US Inflation Reduction Act provides significant tax credits for electric vehicles with batteries containing materials sourced from North America or free-trade partners, directly stimulating regional demand for lithium processing.
- Cathode Technology Evolution:The automotive industry's shift towards high-nickel cathode chemistries (NCM, NCA) for long-range EVs requires lithium hydroxide over carbonate, driving a specific product-grade demand profile.
- Upstream Feedstock Supply:Expansions in Australian spodumene concentrate mining are increasing the global availability of hard-rock feedstock, enabling more conversion capacity to be built outside of traditional brine-heavy regions.
Market Restraints
- Refining Bottlenecks:A high concentration of lithium conversion and refining capacity within China creates a strategic vulnerability and potential supply chokepoint for automotive manufacturers in Europe and North America.
- Long Project Lead Times:The development of new greenfield lithium projects, both brine and hard rock, involves extensive permitting, high capital expenditure, and multi-year construction timelines, slowing the supply response to demand signals.
- Substitution Threat:While currently lower in energy density, the development of sodium-ion batteries poses a long-term substitution risk, particularly for stationary energy storage and low-cost EV segments.
Strategic Opportunities
- Direct Lithium Extraction (DLE):DLE technologies offer a pathway to unlock unconventional brine resources in North America and Europe with a smaller environmental footprint and faster processing times than traditional evaporation ponds.
- Stationary Energy Storage:The utility-scale battery energy storage system (BESS) market provides a distinct and fast-growing demand segment for lithium chemicals, diversifying consumption away from exclusive reliance on the automotive sector.
- Circular Economy Development:The EU's Critical Raw Materials Act creates mandates and incentives for building a robust battery recycling infrastructure, opening opportunities in black mass processing and recovery of battery-grade lithium.
Industry Challenges
- Divergent Quality Standards:Producers must navigate differing regulatory and quality benchmarks, such as China's GB standards for battery materials and emerging EU battery passport requirements, complicating global trade and product qualification.
- Capital Intensity:The immense capital required to fund new extraction and conversion facilities presents a significant hurdle, especially for junior miners and processors facing volatile lithium pricing and high interest rates.
- Specialized Talent Shortages:A global scarcity of experienced metallurgists, geologists, and chemical engineers with specific expertise in lithium processing limits the speed at which new projects can be designed, built, and commissioned.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Chemicals Market |
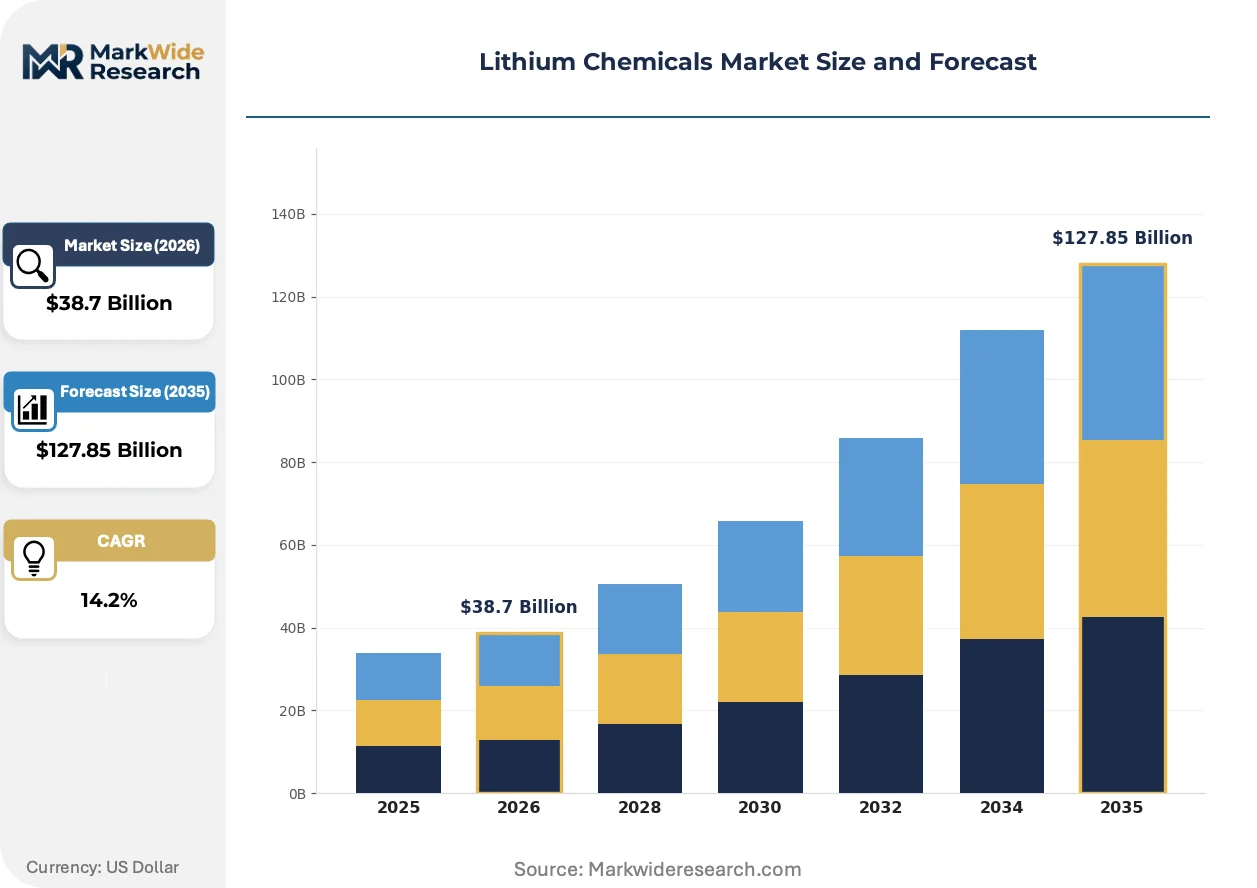
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium Carbonate, Lithium Hydroxide, Lithium Chloride, Lithium Oxide Application: Batteries, Glass & Ceramics, Lubricating Greases, Pharmaceuticals End User: Aerospace, Electronics, Automotive, Energy Storage Distribution Channel: Direct Sales, Online Sales, Retail Sales, Distributors |
| Companies Covered | Pilbara Minerals, Livent, Albemarle Corporation, Orocobre, Allkem, Sociedad Química y Minera de Chile, Tianqi Lithium, Arcadium Lithium, Ganfeng Lithium, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Chemicals Market Strategic Shifts & Innovations
Technological innovation in extraction and policy-driven supply chain realignment are the primary forces defining market evolution. The industry is moving from a geographically concentrated model to a more distributed and politically aligned production and procurement ecosystem.
Direct Lithium Extraction (DLE) is a suite of technologies designed to selectively extract lithium from brines, bypassing large evaporation ponds. Pilot projects and early-stage commercial plants in the Americas and Europe are testing various DLE methods. This innovation is virtualizing the upstream footprint of brine projects, compressing development timelines and reducing the environmental impact compared to conventional methods.
The European Union’s Critical Raw Materials Act (CRMA) establishes ambitious targets for domestic extraction, processing, and recycling of strategic materials, including lithium. This policy directly incentivizes investment in a regional lithium supply chain to reduce dependency on single sources. Automotive and battery cell manufacturers are most affected, now compelled to help finance and secure offtake from emerging European projects.
Automotive OEMs are altering their procurement models, moving from transactional purchases to direct strategic investments and long-term offtake agreements with lithium producers. This shift frequently disintermediates traditional chemical traders for large, strategic volumes, granting automakers greater control and visibility over their supply. This trend is most visible among US and EU automakers seeking to secure supply that qualifies for regional content incentives.
Lithium Chemicals Market Segmentation
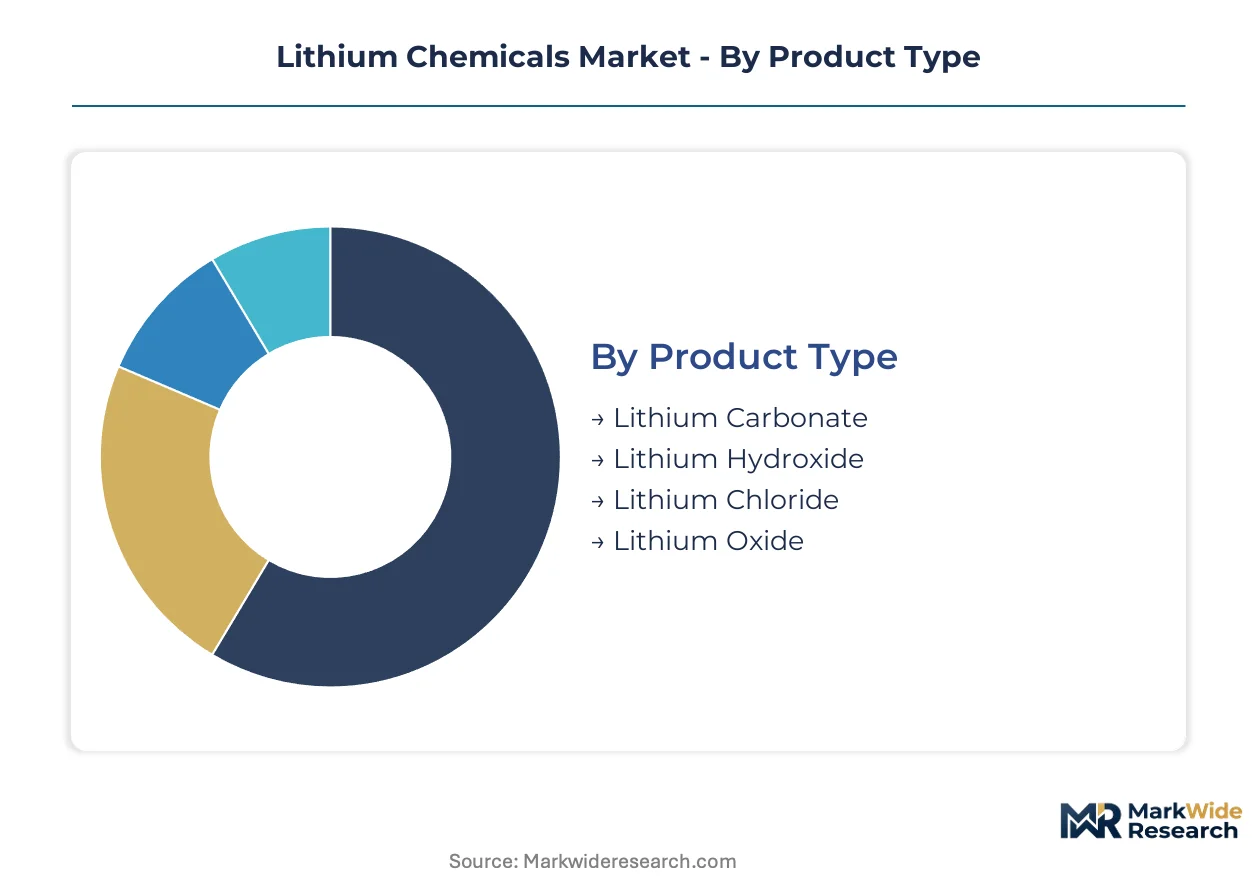
Segmentation provides a granular view of the lithium chemicals market, revealing how diverse product forms, applications, end-users, and distribution channels shape its structure. Understanding these segments is critical for identifying specific demand drivers and strategic opportunities across the value chain.
Product Type:
The market's product type segmentation highlights the diverse chemical forms tailored for specific industrial applications and performance requirements.
- Lithium Hydroxide:This inorganic compound is typically refined to over 99.5% purity, featuring a higher lithium content per unit mass compared to carbonate. Demand concentrates within the automotive sector for high-nickel cathode chemistries (NCM, NCA) in long-range electric vehicle batteries.
- Lithium Carbonate:A key lithium compound, often produced from brines, it serves as a precursor for various lithium derivatives and battery materials. Its primary demand comes from LFP battery chemistries and is also used in glass, ceramics, and pharmaceutical applications.
- Lithium Chloride:This highly soluble salt finds use in air conditioning systems, as a desiccant, and in the production of metallic lithium.
- Lithium Oxide:Utilized in specialized glass and ceramic formulations, this compound enhances thermal shock resistance and optical properties.
The dominant share belongs to Lithium Hydroxide, while Lithium Carbonate is gaining share fastest for diverse battery chemistries.
Application:
Volume concentration across lithium chemical applications reflects the scale of demand from energy storage solutions and traditional industrial uses.
- Batteries:Lithium chemicals are crucial as cathode and electrolyte materials in rechargeable lithium-ion batteries, enabling energy storage. This application overwhelmingly dominates consumption, driven by electric vehicles and grid-scale energy storage systems globally.
- Glass & Ceramics:Lithium compounds, including carbonate and oxide, act as fluxing agents, lowering melting points and improving material strength. Demand is stable across specialized glass production for cookware and technical ceramics, providing thermal stability.
- Lubricating Greases:Lithium stearate and other lithium soaps are key thickeners, providing high-temperature stability and water resistance to industrial greases.
- Pharmaceuticals:Lithium carbonate is a recognized mood stabilizer, while other lithium compounds are explored for various medicinal and research purposes.
Batteries represent the largest application segment, with Glass & Ceramics maintaining a stable, albeit smaller, consumption profile.
End User:
Customer type differentiation across end-user industries showcases distinct purchasing patterns and technical specifications for lithium chemical procurement.
- Automotive:The automotive industry consumes battery-grade lithium chemicals for electric vehicle (EV) powertrains, particularly in cathode manufacturing. Government incentives like the US Inflation Reduction Act directly stimulate regional demand for EV battery material processing.
- Energy Storage:Utility-scale battery energy storage systems (BESS) require significant volumes of lithium chemicals for grid stabilization and renewable energy integration. This sector represents a distinct and fast-growing demand segment, diversifying consumption away from exclusive automotive reliance.
- Aerospace:Specialized lithium alloys are used for lightweighting aircraft components, while lithium-ion batteries power auxiliary systems in aerospace applications.
- Electronics:Portable electronics, including smartphones and laptops, rely on compact lithium-ion batteries, consuming high-purity lithium chemicals.
The automotive sector drives substantial demand, complemented by significant growth from utility-scale energy storage systems.
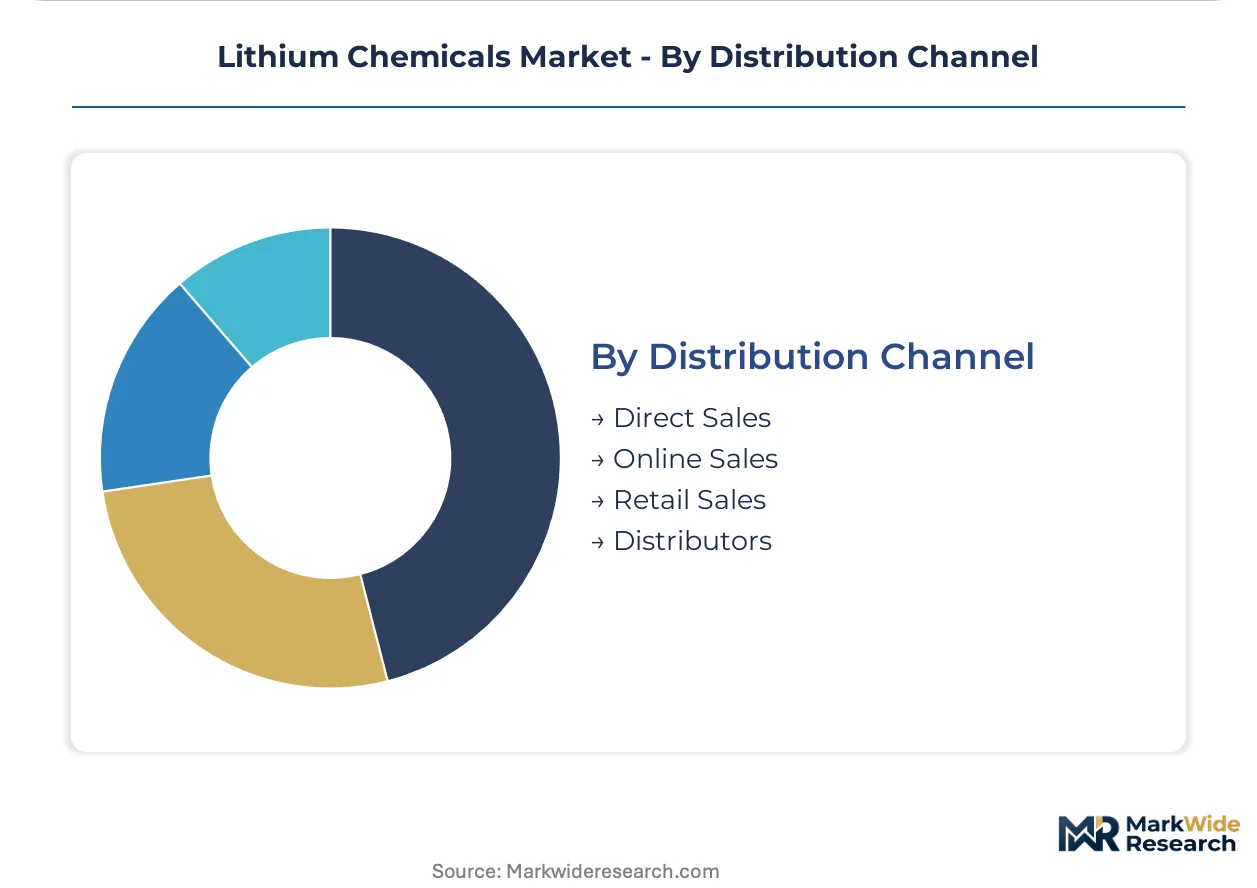
Distribution Channel:
Supply concentration within distribution channels determines the efficiency and reach of lithium chemical delivery to diverse industrial clients.
- Direct Sales:This channel involves direct contracts between lithium chemical producers and large-scale industrial consumers, especially battery manufacturers. Automakers are increasingly leveraging direct strategic investments and long-term offtake agreements to secure supply.
- Distributors:Distributors serve as intermediaries, managing logistics and inventory for a wide range of smaller and specialized industrial clients. They provide market access for producers to reach diverse end-users in glass, ceramics, and pharmaceutical sectors globally.
- Online Sales:Emerging as a channel for smaller volume purchases and specialized chemicals, online platforms offer convenience for niche buyers.
- Retail Sales:This channel is less prominent for bulk lithium chemicals but applies to consumer-facing products containing lithium, like certain batteries.
Direct Sales channels manage large-volume contracts, while Distributors serve a broader base of smaller and specialized buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global lithium chemicals market exhibits a significant consumption-mix differential, particularly between established refining hubs and emerging processing regions. China's demand concentrates heavily on battery-grade lithium for its gigafactory ecosystem, while Western markets prioritize securing ethically sourced materials. This divergence shapes investment and supply chain strategies across continents.
China
China's extensive gigafactory ecosystem drives immense demand for battery-grade lithium chemicals. The country's GB standards for battery materials define critical market access and quality benchmarks. Major conversion and refining capacities concentrate in regions like the Yangtze River Delta and Sichuan, supporting its dominant position in global battery manufacturing.
United States
United States demand for lithium chemicals expands rapidly due to electric vehicle manufacturing and battery plant investments. The US Inflation Reduction Act provides significant tax credits for EV batteries with North American-sourced materials. New DLE projects and battery component factories are emerging in states such as Nevada and North Carolina to meet this localized demand.
Australia
Australian spodumene concentrate expansion significantly tilts the upstream supply balance for global lithium feedstock. Environmental permitting processes regulate the development of new mining projects. Western Australia, particularly the Pilbara and Greenbushes regions, hosts extensive hard-rock mining operations that supply raw lithium to international markets.
Chile
Chile sustains a cost-advantaged position in lithium production due to its vast brine operations in the Atacama Desert. The country's mining and water usage regulations govern the extraction of this critical resource. Major producers leverage these operations to supply lithium carbonate globally, primarily from the Atacama region.
Germany
Germany's automotive industry drives substantial European demand for lithium chemicals, particularly for EV battery cell manufacturing. The European Union’s Critical Raw Materials Act incentivizes domestic processing and recycling. New gigafactories and battery material facilities are developing in regions like Saxony and Brandenburg, creating localized processing demand.
Lithium Chemicals Market Key Industry Players
Capability concentration sits with one tier of specialized refiners, while scale advantage sits with integrated mining and chemical processing giants. The lithium chemicals market exhibits a tiered structure, ranging from upstream resource holders to downstream battery material converters. Strategic archetypes include diversified producers with both brine and hard-rock assets, and specialized refiners focused on high-purity battery-grade compounds. Capacity expansion and strategic partnerships remain dominant competitive moves across the value chain.
Among the diversified producers, Albemarle Corporation exemplifies the strategic advantage of controlling both brine and hard rock sources globally. Santiago-based Sociedad Química y Minera de Chile (SQM) occupies a cost-advantaged position through its extensive Atacama Desert brine operations, primarily supplying lithium carbonate. Meanwhile, Ganfeng Lithium, a Chinese company, represents the specialized refining archetype, focusing on converting raw lithium into high-purity battery-grade compounds for electronics and automotive sectors. These entities collectively anchor different segments of the complex lithium chemicals value chain, demonstrating varied approaches to resource and processing control.
| Leading Market Players |
|---|
| Pilbara Minerals |
| Livent |
| Albemarle Corporation |
| Orocobre |
| Allkem |
| Sociedad Química y Minera de Chile |
| Tianqi Lithium |
| Arcadium Lithium |
| Ganfeng Lithium |
| Others |
Cost & Logistics Intelligence
The Trans-Pacific shipping lanes' cost dynamics directly influence lithium chemical supply concentration and subsequent downstream battery material price differentiation. Geopolitical tensions, particularly regarding trade routes, further compound these logistical challenges for global procurement teams.
Pricing Analysis
Long-term offtake agreements define the predominant pricing model for battery-grade lithium chemicals, especially for large automotive manufacturers. Quality grade, particularly purity levels exceeding 99.5%, and volume scale drive significant price differentiation across the market. Pricing pressure stems from increased upstream feedstock supply from Australian spodumene, particularly for lithium carbonate conversion. Automotive OEMs are generally less price-sensitive compared to smaller-scale glass and ceramics manufacturers.
Supply Chain Analysis
Single-source vulnerability within China's refining capacity creates a significant supply chain risk for Western automakers. Lithium chemical supply concentrates heavily in China for conversion, with raw material dependencies on Australia for spodumene and Chile for brine. Regulatory restrictions like the US Inflation Reduction Act reshape procurement patterns. Direct sales channels dominate the downstream distribution for large-volume battery manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lithium chemicals market presents a service-attach opportunity, with battery recycling and black mass processing expanding faster than primary chemical production. This creates new revenue streams beyond initial material sales for integrated players.
For Market Incumbents: Pre-empt market share erosion from new Direct Lithium Extraction (DLE) technologies by actively investing in sustainable extraction R&D and securing long-term offtake agreements with emerging projects. Consolidate conversion capacity outside China to mitigate geopolitical supply chain risks, leveraging the US Inflation Reduction Act incentives. This defends against potential supply chokepoints.
For New Entrants and Emerging Players: Establish a foothold in specialized lithium chemical processing for niche applications like aerospace alloys or high-purity pharmaceutical grades. Target European and North American markets where policy incentives, such as the EU Critical Raw Materials Act, favor regional production. A go-to-market angle focused on certified ethical sourcing and reduced environmental footprint will resonate with downstream buyers.
For Investors and Strategic Acquirers: Vertically integrated processors with proven DLE technology represent attractive acquisition targets for long-term growth. The five-to-ten-year outlook favors companies controlling both upstream resource access and downstream conversion capabilities. Watch for successful commercial scale-up of DLE projects as an inflection indicator for new investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in North America | This initiative leverages IRA incentives to build regional processing resilience for EV battery materials. |
| DLE Technology Investment | Direct Lithium Extraction reduces environmental impact and shortens project lead times for new brine resources. |
| Long-term Offtake Agreements | Securing future supply provides stability for automotive and energy storage manufacturers globally. |
| Battery Recycling Infrastructure | Developing black mass processing facilities supports circular economy mandates in Europe and North America. |
| High-Purity Product Diversification | Expanding into specialized grades addresses demand from aerospace and pharmaceutical sectors. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary research. Interviews included metallurgists, EV battery procurement leads, chemical plant managers, and regulatory affairs specialists. Secondary data sources comprised customs trade data, company 10-K filings, and reports from the USGS and IEA, enabling bottom-up and top-down triangulation.
Forecast inputs considered product type, application, end-user, distribution channel, and regional supply-demand balances. The analytical framework modeled these segmentation dimensions across the projection horizon, with compound annual growth rates derived from historical trends and future capacity additions. Key inputs included announced gigafactory capacities and DLE project timelines for resource development.
Stress conditions across raw material price volatility and regulatory policy shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions concerning technological adoption and geopolitical stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Dioctyl Phthalate Market
Organic Chemicals
Behenyl Alcohol Market
Organic Chemicals
Isophthalic Acid Market
Organic Chemicals
Oxo Chemicals Market
Organic Chemicals
2,5-Dimethyl-2,4-Hexadiene Market
Organic Chemicals
Organocatalyst Market
Organic Chemicals
Benzyl Cyanide Market
Organic Chemicals
US Humate Market
Organic Chemicals
DMDM Hydantoin Market
Organic Chemicals
Terephthalic Aldehyde Market
Organic Chemicals
Acetaldehyde Market
Organic Chemicals
Synthetic Antioxidants Market
Organic Chemicals
Global Benzoic Acid Market
Organic Chemicals
2,6-Dichloro Aniline Market
Organic Chemicals
North America Organic Acid Market
Organic Chemicals
Organic Polysulfide Market