
 Global Dicyandiamide Market | 2026-2036
Global Dicyandiamide Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dicyandiamide Market Foresight
Chinese carbide-to-cyanamide producers is realigning capacity toward higher-purity dicyandiamide streams for electronics-grade applications. AlzChem Group AG anchors European supply through its Trostberg complex, leveraging backward integration into lime and carbide feedstocks. Ningxia Darong Industry Group Co., Ltd. competes on scale from the Ningxia coal-chemistry corridor, while Nippon Carbide Industries Co., Inc. differentiates through pharmaceutical-grade certification and JIS-standard process discipline.
Dicyandiamide (C2H4N4), a cyclic guanidine derivative with melting point 207-209°C, serves primarily as a latent curing agent for epoxy resins and as an intermediate for melamine synthesis. Industrial production proceeds via calcium cyanamide hydrolysis followed by polymerization, with purity grades spanning technical (85-93%) through refined (99%+) specifications. Powder formulations dominate volume throughput in adhesives and construction materials, where cost sensitivity favors bulk handling, while crystal grades command premium positioning in pharmaceutical and electronics applications where trace metal content must fall below 10 ppm. Granule formats are gaining traction in agrochemical blending operations where dust control and flow properties reduce formulation losses.
REACH registration in Europe mandates full toxicological dossiers for dicyandiamide imports, while China's MEE enforces wastewater discharge limits on cyanamide-based processes that raise compliance costs for Ningxia producers. FDA and EMA oversight of pharmaceutical-grade material restricts sourcing to qualified suppliers with DMF or CEP filings. Buyers must monitor regulatory divergence between EU Green Deal chemical restrictions and Asia-Pacific industrial growth policies to secure supply continuity without stranded inventory.
Market Dynamics
Upstream cyanamide capacity concentration in China's Ningxia coal-chemistry corridor is reshaping global supply security for electronics-grade dicyandiamide, forcing downstream buyers to requalify alternative sources as REACH compliance tightens in Europe and dual carbon enforcement raises process costs.
Growth Catalysts
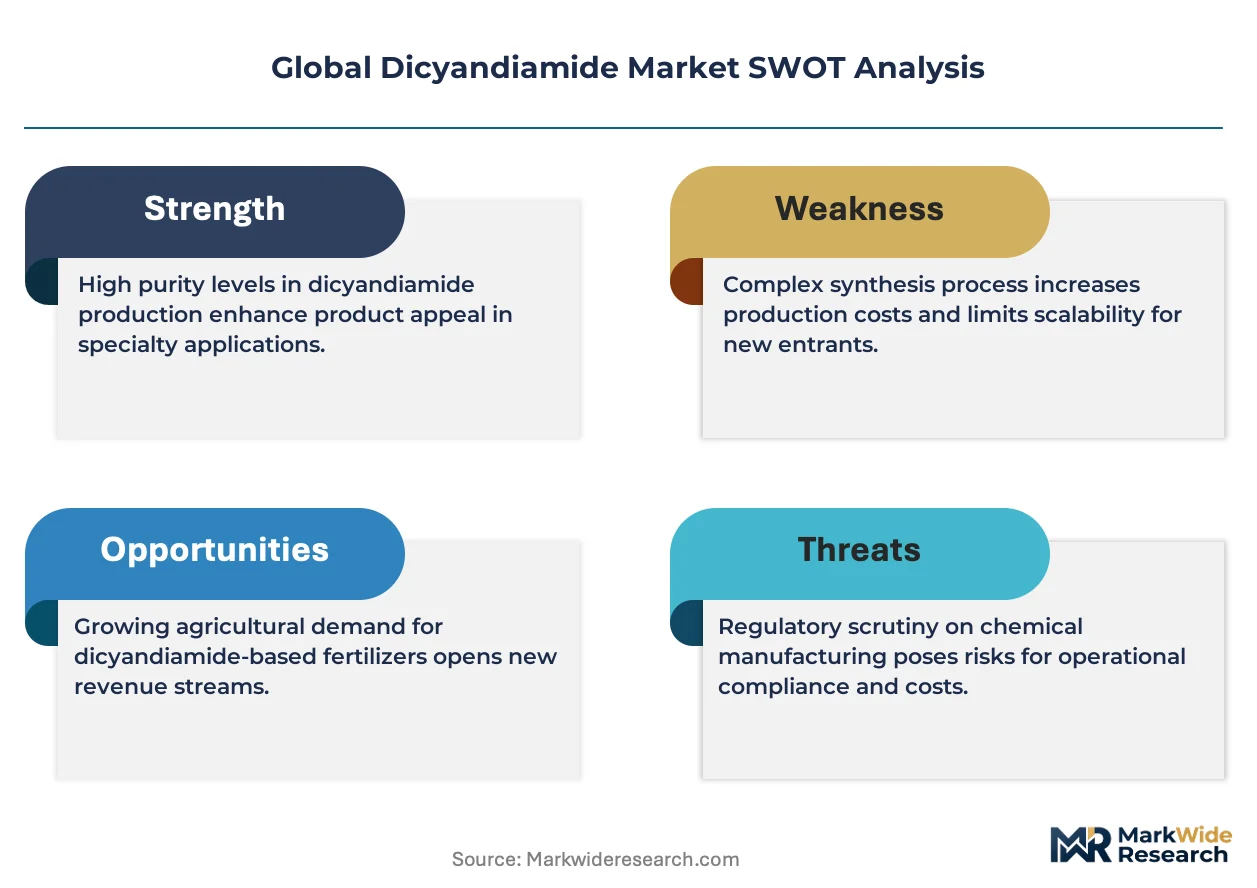
- REACH registration mandates:Full toxicological dossier requirements in Europe are filtering out marginal producers and consolidating demand around qualified suppliers with established compliance infrastructure.
- Epoxy laminate board demand:Electronics manufacturers in South Korea and Taiwan are expanding high-purity dicyandiamide procurement for multilayer PCB production serving AI server and advanced packaging applications.
- Granule format adoption:Agrochemical blenders are converting from powder to dust-controlled granule formulations, reducing handling losses and expanding addressable market in precision farming operations.
Market Restraints
- Calcium carbide input volatility:Energy-intensive carbide production exposes Ningxia producers to electricity price swings and carbon allowance costs under China's MEE discharge limits.
- Single-region supply concentration:Overreliance on Chinese cyanamide integration creates vulnerability to export license delays and geopolitical friction affecting electronics supply chains.
- Imidazole substitution threat:Alternative latent curing agents are displacing dicyandiamide in certain fast-cure epoxy formulations where pot life requirements are less stringent.
Strategic Opportunities
- Pharmaceutical-grade certification:FDA and EMA DMF filing pathways enable premium positioning for producers meeting trace metal thresholds below 10 ppm in active pharmaceutical intermediate applications.
- EU Green Deal chemical restrictions:Carbon border adjustment mechanisms and sustainable process incentives favor European producers with lime-carbide backward integration and renewable energy sourcing.
- Digital platform procurement:Specialty chemical marketplaces are disintermediating traditional distributor networks for technical-grade material, compressing transaction costs and expanding spot market liquidity.
Industry Challenges
- Process analytical chemistry talent scarcity:Electronics-grade production requires specialists capable of maintaining sub-ppm trace metal control, with limited training pipeline in traditional chemical engineering programs.
- Dual qualification timelines:Semiconductor laminate manufacturers demand 18-24 month validation cycles for new dicyandiamide sources, locking in incumbent relationships and delaying market share shifts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dicyandiamide Market |
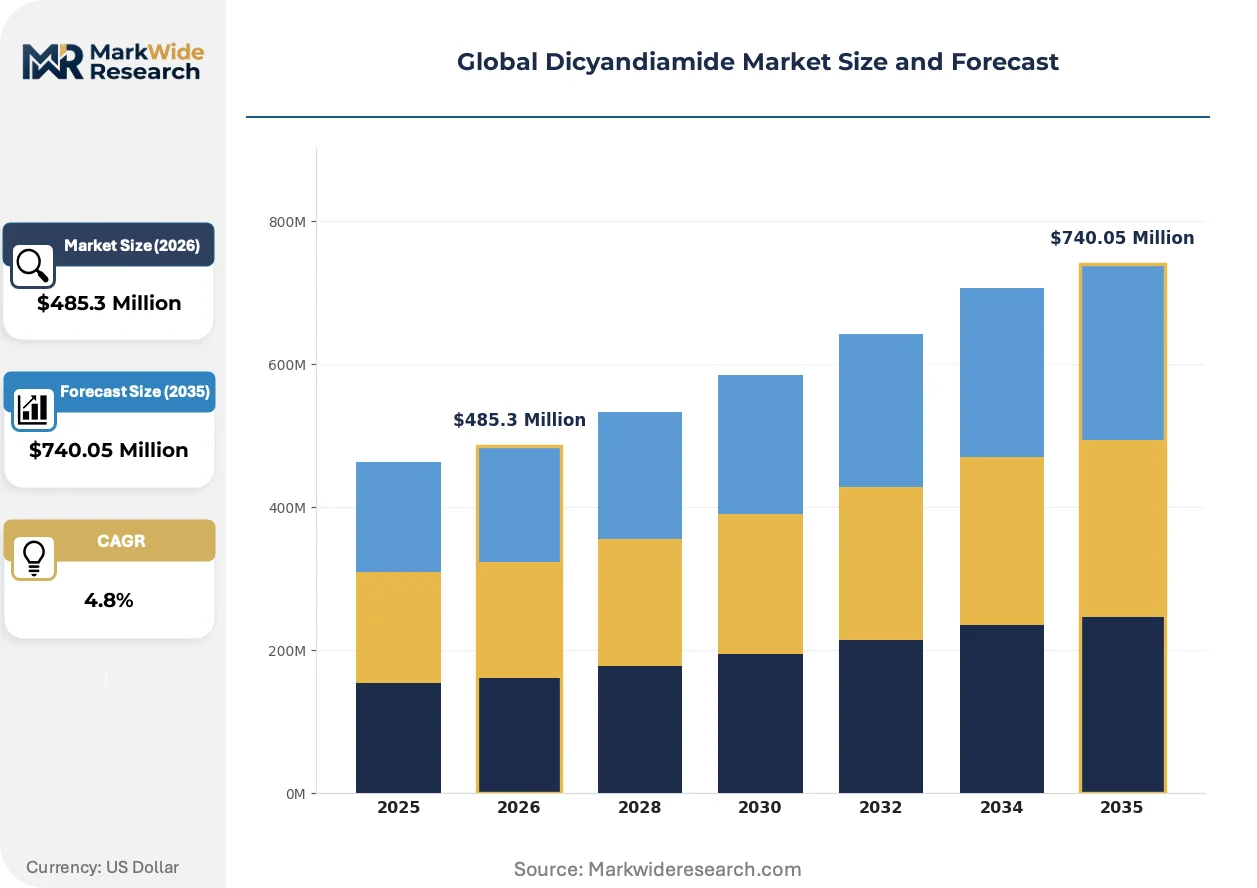
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $740.05 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Crystals, Solution Application: Epoxy Curing Agent, Adhesives, Flame Retardants, Pharmaceuticals, Agrochemicals End Use Industry: Electronics Manufacturing, Coatings, Agricultural Chemicals, Pharmaceuticals Production, Construction Materials Packaging Type: Bag Packaging, Drum Packaging, Bulk Packaging, Intermediate Bulk Containers |
| Companies Covered | AlzChem Group AG, Nippon Carbide Industries Co., Inc., Ningxia Darong Industry Group Co., Ltd., Ningxia Jiafeng Chemicals Co., Ltd., Ningxia Sunnyfield Chemical Co., Ltd., HELM AG, Ningxia Yinglite Chemicals Co., Ltd., Shizuishan Pengsheng Chemical Co., Ltd., Emerald Performance Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dicyandiamide Market Shifts & Advancements
Process intensification and purity verification technologies are compressing the gap between technical and electronics-grade production economics, while regulatory divergence between jurisdictions is fragmenting compliance strategies across supplier bases.
Continuous flow cyanamide hydrolysis is converging with in-line spectroscopic monitoring to enable real-time purity adjustment, reducing off-spec batches and energy consumption. Electronics laminate manufacturers in Taiwan are piloting these systems for just-in-time high-purity supply. The technology is converging with predictive maintenance platforms to minimize unplanned downtime in carbide-fed operations.
China's MEE wastewater discharge limits on cyanamide-based processes are forcing Ningxia producers to install ammonia recovery and zero-liquid-discharge systems. Compliance investments are raising marginal production costs and accelerating consolidation toward integrated carbide-cyanamide-dicyandiamide complexes. Smaller standalone producers without captive lime and carbide supply are exiting or seeking acquisition.
Buyers in South Korean electronics clusters are consolidating supplier lists and demanding multi-site qualification to reduce concentration risk. Long-term contracts with volume commitments and price collars are displacing spot procurement for electronics-grade material. This behavioral shift is most visible in Seoul-Incheon corridor laminate board operations serving Samsung and SK Hynix supply chains.
Global Dicyandiamide Market Segmentation
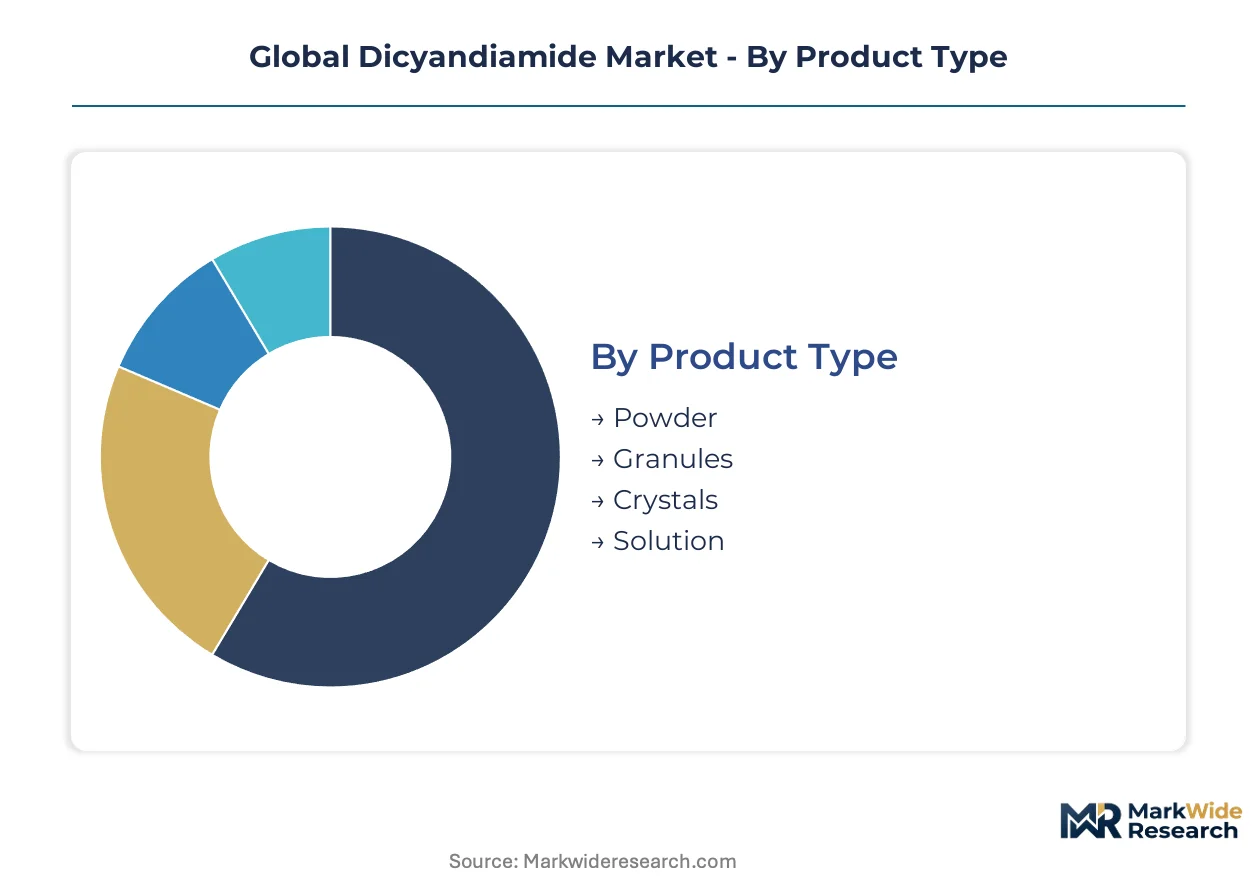
Dicyandiamide procurement decisions hinge on purity thresholds, handling economics, and regulatory compliance rather than commodity pricing alone. Electronics manufacturers demand sub-10 ppm trace metal grades, while agrochemical blenders prioritize dust-controlled flow properties over absolute purity.
Product Type:
Buyers select physical forms based on handling infrastructure, dissolution requirements, and contamination risk tolerance across their production environments.
- Powder:Fine particulate with high surface area enables rapid dissolution in aqueous epoxy formulations. Construction adhesives and laminate board producers in China's Pearl River Delta consume bulk volumes where pneumatic conveying systems minimize handling labor.
- Granules:Dust-suppressed spherical particles reduce respiratory exposure and static accumulation during agrochemical blending. Precision farming operations in the US Corn Belt are converting from powder to granule formats to cut formulation losses during metered dispensing.
- Crystals:High-purity solid with controlled morphology meets pharmaceutical intermediate specifications requiring DMF filings with FDA or CEP documentation with EMA.
- Solution:Pre-dissolved aqueous concentrate eliminates dissolution equipment for small-batch pharmaceutical synthesis and analytical reagent preparation.
Powder leads on scale; granules lead on momentum.
Application:
Functional performance requirements and regulatory exposure determine margin capture across downstream uses.
- Epoxy Curing Agent:Latent hardener for one-component epoxy systems enabling extended pot life with elevated-temperature activation. Multilayer PCB manufacturers in Taiwan and South Korea specify electronics-grade material for AI server laminate production.
- Adhesives:Structural bonding applications in construction and transportation equipment favor technical-grade powder for cost-sensitive formulated systems.
- Flame Retardants:Nitrogen-rich char-former synergizes with phosphorus compounds in intumescent coatings for steel protection.
- Pharmaceuticals:Active pharmaceutical intermediate for diabetes therapeutics and antiviral synthesis requires GMP compliance and sub-10 ppm heavy metal certification.
- Agrochemicals:Slow-release nitrogen source in specialty fertilizers and synthesis intermediate for guanidine-based pesticides.
Epoxy curing agents dominate revenue contribution; pharmaceutical applications command the steepest expansion trajectory.
End Use Industry:
Industry-specific quality systems and supply security requirements fragment procurement patterns across customer bases.
- Electronics Manufacturing:Laminate board producers demand 18-24 month supplier qualification cycles with locked process parameters. Seoul-Incheon corridor operations serving Samsung and SK Hynix supply chains are consolidating approved vendor lists.
- Coatings:Industrial and protective coating formulators prioritize technical-grade material with flexible delivery scheduling over purity certification.
- Agricultural Chemicals:Fertilizer blenders and pesticide manufacturers specify granule formats for dust-controlled handling in open-air blending operations.
- Pharmaceuticals Production:API manufacturers require DMF or CEP documentation, forcing dual sourcing from qualified suppliers with validated analytical methods.
- Construction Materials:Adhesive and sealant compounders consume technical-grade powder through distributor networks with minimal regulatory documentation.
Electronics manufacturing leads on scale; pharmaceuticals production leads on momentum.
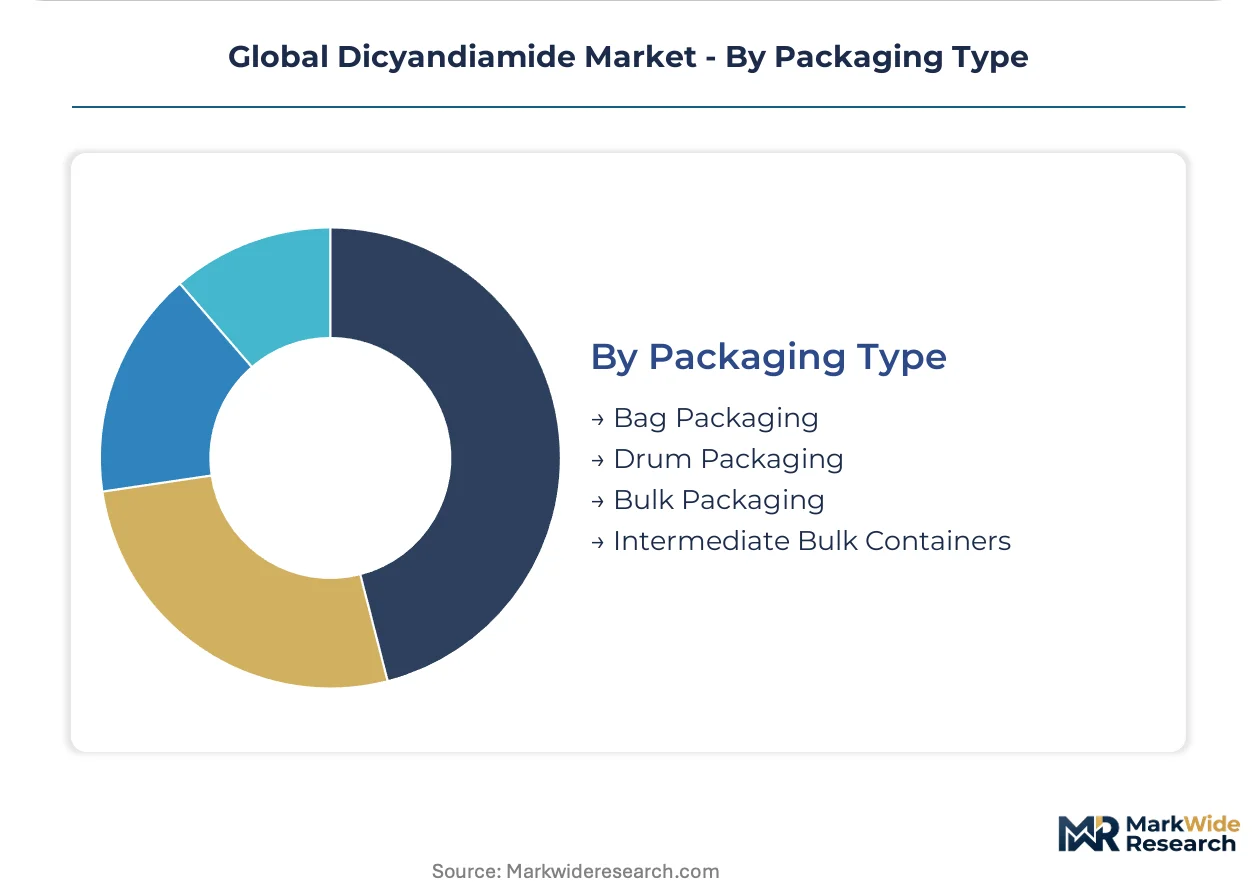
Packaging Type:
Logistics economics and contamination risk govern format selection from production through point-of-use.
- Bag Packaging:Multi-wall paper or polyethylene sacks for 25-50 kg technical-grade powder shipments to construction adhesive compounders with manual handling capabilities.
- Drum Packaging:Steel or fiber drums with sealed closures protect electronics-grade crystals and pharmaceutical material from moisture and cross-contamination during international transport.
- Bulk Packaging:Pneumatic tanker or hopper truck delivery for high-volume powder consumers with silo storage and automated batching systems.
- Intermediate Bulk Containers:500-1000 liter flexible or rigid IBCs bridge bulk efficiency with reduced minimum order quantities for mid-volume specialty chemical processors.
Bag packaging leads on scale; intermediate bulk containers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between Europe's REACH compliance costs and Asia's dual carbon enforcement is reshaping where dicyandiamide production migrates, with compliance gaps favoring integrated producers in China's Ningxia corridor over standalone European facilities facing carbon border adjustments.
China
Ningxia's coal-chemistry corridor supplies the majority of global cyanamide feedstock for electronics-grade dicyandiamide. MEE wastewater discharge limits are forcing ammonia recovery investments that raise marginal costs for smaller producers. Integrated carbide-cyanamide-dicyandiamide complexes in Shizuishan are consolidating capacity as standalone operators exit.
Germany
AlzChem's Trostberg complex anchors European supply through captive lime and carbide backward integration. EU Green Deal chemical restrictions and carbon border adjustment mechanisms favor this facility over import-dependent competitors. Bavarian operations serve REACH-registered customers requiring full toxicological dossiers for pharmaceutical and electronics applications.
South Korea
Seoul-Incheon corridor laminate board producers are expanding high-purity dicyandiamide procurement for multilayer PCB production serving Samsung and SK Hynix AI server supply chains. MFDS pharmaceutical oversight restricts qualified supplier pools for API intermediate applications. Buyers are consolidating approved vendor lists and demanding multi-site qualification to reduce concentration risk.
Japan
Nippon Carbide Industries differentiates through pharmaceutical-grade certification and JIS-standard process discipline for diabetes therapeutic intermediates. METI industrial policy supports domestic production of high-trace-metal-control material. Osaka-based operations maintain qualification relationships with semiconductor laminate manufacturers requiring 18-24 month validation cycles.
United States
Agrochemical blenders in the US Corn Belt are converting from powder to granule formats to cut formulation losses during metered dispensing for precision farming. EPA oversight of cyanamide-based process emissions affects import sourcing from Ningxia producers. Emerald Performance Materials serves construction adhesive compounders through distributor networks with flexible delivery scheduling.
Global Dicyandiamide Market Competitive Landscape
Chinese producers anchor the scale-driven tier; European and Japanese specialists hold premium-grade positioning through regulatory certification. The vendor base stratifies between integrated carbide-cyanamide complexes and standalone dicyandiamide refiners facing feedstock cost pressure. Three archetypes dominate: backward-integrated coal-chemistry operators, lime-carbide integrated European incumbents, and pharmaceutical-grade certification specialists. Capacity consolidation and multi-site qualification partnerships represent the dominant competitive moves as buyers seek supply security.
Within the integrated Chinese tier, Ningxia Darong Industry Group Co., Ltd. and Ningxia Sunnyfield Chemical Co., Ltd. exemplify scale-based positioning from the Ningxia coal corridor. Among European specialists, AlzChem Group AG occupies the backward-integrated archetype with captive feedstock control. At the certification-focused end, Nippon Carbide Industries Co., Inc. represents pharmaceutical-grade process discipline meeting JIS and FDA filing requirements.
| Leading Market Players |
|---|
| AlzChem Group AG |
| Nippon Carbide Industries Co., Inc. |
| Ningxia Darong Industry Group Co., Ltd. |
| Ningxia Jiafeng Chemicals Co., Ltd. |
| Ningxia Sunnyfield Chemical Co., Ltd. |
| HELM AG |
| Ningxia Yinglite Chemicals Co., Ltd. |
| Shizuishan Pengsheng Chemical Co., Ltd. |
| Emerald Performance Materials |
| Others |
Supply & Pricing Matrix
Calcium carbide spot indices in China's Ningxia corridor cascade through cyanamide integration costs into three distinct pricing tiers for dicyandiamide buyers. Electronics-grade crystals command premiums tied to sub-10 ppm trace metal certification, while technical-grade powder tracks feedstock volatility more closely.
Pricing Analysis
Distributor margins of 12-18% separate direct-to-OEM contract pricing from spot market transactions for technical-grade material. Three-tier pricing structure across pharmaceutical-grade, electronics-grade, and technical-grade levels reflects certification investment and analytical control intensity. Cost compression in the technical tier is intensifying because Ningxia producers face MEE wastewater compliance investments. Construction adhesive compounders exhibit highest price sensitivity, while semiconductor laminate manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Refurbishment and requalification flows for pharmaceutical-grade material extend supplier validation timelines when primary sources face disruption. Production concentrates in China, Germany, and Japan, with cyanamide feedstock anchored in Ningxia's coal-chemistry corridor. The supply chain draws from calcium carbide, lime, and ammonia inputs with energy-intensive process steps. Single-region concentration in Ningxia creates vulnerability to export license friction. Distribution runs through specialty chemical distributors for technical-grade material and direct contracts for electronics and pharmaceutical grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Dicyandiamide Market functions as a stable compounder anchored by electronics-grade demand from AI server laminate production, where 18-24 month qualification cycles lock in incumbent relationships.
For Market Incumbents: Lock in multi-site qualification partnerships with Seoul-Incheon corridor laminate producers to defend against imidazole substitution in fast-cure epoxy formulations. Secure captive carbide supply through backward integration into lime and energy assets in Ningxia or renewable-sourced equivalents in Europe. Prioritize FDA and EMA DMF filing maintenance for pharmaceutical-grade positioning.
For New Entrants and Emerging Players: Specialty chemical marketplaces offer the lowest-friction route to technical-grade procurement relationships with construction adhesive compounders. Target agrochemical granule conversion demand in the US Corn Belt, where dust-control specifications are less stringent than electronics-grade thresholds. Lead with formulation support services to differentiate from established powder suppliers.
For Investors and Strategic Acquirers: Asymmetric upside sits with pharmaceutical-grade certification specialists possessing validated analytical methods and existing DMF filings. The five-to-ten year viability window favors producers with demonstrated sub-10 ppm trace metal control and locked relationships with diabetes therapeutic API manufacturers. Monitor MFDS and FDA inspection schedules for qualification pipeline signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Carbide | AlzChem's Trostberg complex demonstrates margin protection against Ningxia electricity volatility. |
| Pharmaceutical-Grade Certification Investment | FDA and EMA DMF filings enable premium positioning in diabetes therapeutic intermediate supply. |
| Multi-Site Qualification Partnerships | Samsung and SK Hynix supply chains demand dual-source validation to reduce concentration risk. |
| Granule Format Capacity Expansion | Precision farming operations in the US Corn Belt are converting from powder to reduce handling losses. |
| Continuous Flow Process Technology | Taiwanese laminate manufacturers pilot in-line spectroscopic monitoring for just-in-time high-purity supply. |
Research Methodology
Coverage spans China, Germany, South Korea, Japan, and the United States, with primary inputs from each territory's production and consumption clusters. The research combines structured interviews with plant managers at carbide-cyanamide complexes, procurement leads at electronics laminate manufacturers, distribution channel partners serving construction adhesive compounders, and technical R&D directors at pharmaceutical API producers. Secondary validation draws from customs and trade data, SEC and ECHA filings, ACC and Cefic industry reports, and MFDS regulatory disclosures. Bottom-up capacity and consumption estimates triangulate against top-down market sizing derived from end-use industry production indices.
Rate-of-change decomposition separates volume growth from price and mix effects across the projection horizon. The analytical framework models segmentation across purity grade tiers, end-use industries spanning electronics and pharmaceuticals, packaging formats from bulk tankers to sealed drums, and regional production hubs in Ningxia and Bavaria. CAGRs derive from trend extrapolation of laminate board production, agrochemical formulation conversion rates, and pharmaceutical intermediate demand, cross-referenced against carbide capacity expansion announcements and MEE compliance cost trajectories.
Regulatory enforcement intensity in China, REACH dossier renewal timelines in Europe, and imidazole substitution rates in fast-cure epoxy are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about qualification cycle durations, carbon allowance cost pass-through, and electronics capital expenditure continuity. Practitioners should monitor MEE inspection schedules, EU carbon border adjustment implementation, and semiconductor fab equipment delivery backlogs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Lithium Chloride Market
Bulk Chemicals
Global Butyl Acrylate Market
Bulk Chemicals
Tributyl Citrate Market
Bulk Chemicals
Sodium Sulphate Market
Bulk Chemicals
Global Sodium Percarbonate Market
Bulk Chemicals
Ammonium Nitrate Market
Bulk Chemicals
Metallurgical Coke Market
Bulk Chemicals
Ethyl Mercaptan Market
Bulk Chemicals
Sodium Hydrogen Sulphite Market
Bulk Chemicals
Gluconic Acid Market
Bulk Chemicals
Formic Acid Market
Bulk Chemicals
Vacuum Salts Market
Bulk Chemicals
Europe Acetic Acid Market
Bulk Chemicals
Activated Bleaching Earth Market
Bulk Chemicals
North America Acetic Acid Market
Bulk Chemicals
Encapsulated Sodium Bicarbonate Market