
 Global Ammonium Sulphate Market | 2026-2036
Global Ammonium Sulphate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ammonium Sulphate Market Foresight
Subscription-based soil testing and prescription agronomy services is shifting how ammonium sulphate reaches end users, bundling nutrient recommendations with bulk delivery contracts. BASF SE leverages its caprolactam-integrated production footprint to anchor supply security for European fertilizer distributors. Nutrien dominates North American distribution through its agricultural retail network, while AdvanSix competes on merchant-grade volume from its Virginia manufacturing complex.
Ammonium sulphate is an inorganic salt with the chemical formula (NH₄)₂SO₄, containing approximately 21% nitrogen and 24% sulphur by weight, typically manufactured through direct synthesis of ammonia and sulphuric acid or recovered as a by-product from caprolactam production; its primary purpose is to deliver nitrogen and sulphur nutrients to alkaline soils where pH correction accompanies fertilization. Granular grades occupy the largest volume share due to mechanical spreading compatibility and reduced dust generation during field application. Crystalline ammonium sulphate leads margin pools in pharmaceutical and food additive applications where purity specifications exceed agricultural standards, while powder forms sustain demand from water treatment utilities requiring rapid dissolution.
The EPA oversees environmental release thresholds for ammonium sulphate manufacturing facilities in the United States, while REACH registration requirements in Europe govern chemical safety documentation for imported grades; China's MEE enforces emission controls on caprolactam by-product recovery plants, collectively shaping where purification investments flow and which production routes achieve market access. India's FSSAI and BIS standards create parallel compliance tracks for food-grade and fertilizer-grade imports respectively. Stakeholders must monitor how sulphur recovery economics from petroleum refining interact with ammonia price volatility to determine whether direct synthesis or by-product routes deliver cost advantages through the forecast horizon.
Market Dynamics
Sulphur recovery economics from petroleum refining are diverging from ammonia price volatility, forcing producers to reevaluate whether direct synthesis or caprolactam by-product routes deliver sustainable cost positions through the forecast horizon.
Growth Catalysts
- EU Fertilizing Products Regulation:Tightening contaminant thresholds in Europe are pushing producers toward purified crystalline grades, creating premium product demand.
- Brazilian commercial farming:Growers in Mato Grosso and Goiás states are seeking sulphur-enriched soil amendments for soybean-corn rotation systems.
- Caprolactam by-product streams:Integrated chemical corridors in East Asia are supplying captive fertilizer networks with low-cost ammonium sulphate feedstock.
Market Restraints
- Ammonia price volatility:Natural gas cost swings directly compress margins for direct synthesis producers in North America and Europe.
- REACH registration friction:European chemical safety documentation requirements create non-tariff barriers for imported grades from non-registered facilities.
- Urea substitution threat:Higher nitrogen concentration in urea formulations displaces ammonium sulphate in price-sensitive bulk fertilizer markets.
Strategic Opportunities
- Subscription agronomy services:Soil testing and prescription nutrient platforms in North America are bundling ammonium sulphate delivery with data-driven recommendations.
- Indian food-grade certification:FSSAI standards for food additive applications create margin expansion potential beyond agricultural commodity pricing.
- Water treatment powder grades:Municipal utilities requiring rapid dissolution specifications represent an underpenetrated application channel.
Industry Challenges
- Dual certification timelines:Producers seeking both fertilizer-grade BIS and food-grade FSSAI approvals in India face extended regulatory review cycles.
- Legacy equipment retrofit costs:Crystallization line upgrades to meet EU contaminant thresholds demand capital deployment without guaranteed offtake premiums.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ammonium Sulphate Market |
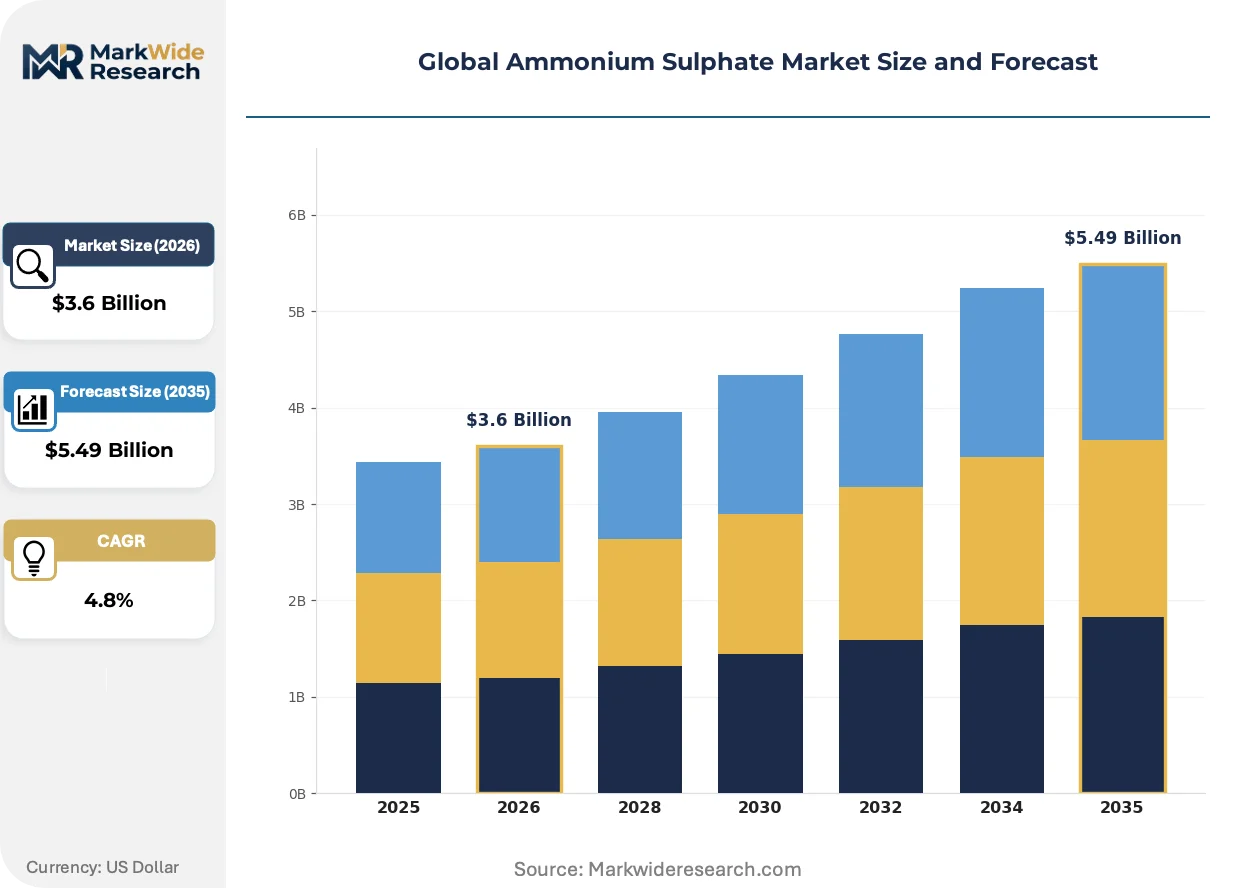
| Market Size in 2026 | $3.6 Billion |
| Market Size in 2035 | $5.49 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Crystalline, Liquid, Micronized Application: Fertilizers, Food Additives, Pharmaceutical, Water Treatment, Flame Retardants End User Industry: Commercial Farming, Food Processing, Chemical Manufacturing, Water Utilities, Textile Production Packaging Type: Bulk Bags, Paper Bags, Plastic Bags, Drums, Loose Cargo |
| Companies Covered | BASF SE, Evonik Industries, Sumitomo Chemical, Lanxess, Domo Chemicals, Arkema, Fibrant, AdvanSix, Nutrien, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ammonium Sulphate Market Shifts & Advancements
Digital agronomy platforms are rewiring how bulk fertilizer reaches farm gate, embedding nutrient recommendations into procurement workflows and compressing traditional distributor margins.
Membrane filtration technology is integrating into caprolactam by-product recovery plants, enabling producers to extract pharmaceutical-grade ammonium sulphate from previously lower-value waste streams. BASF SE and integrated chemical manufacturers in Germany and China are deploying these systems to serve food additive and laboratory chemical buyers. The technology is integrating crystallization and purification steps, collapsing the capital intensity gap between by-product and direct synthesis routes.
China's MEE emission controls on caprolactam recovery facilities are tightening discharge standards for ammonia nitrogen and sulphur dioxide, forcing plant retrofits or closures in Shandong and Zhejiang provinces. Producers with compliant gas scrubbing and wastewater treatment infrastructure are capturing displaced volume. The regulation is accelerating consolidation toward state-owned enterprise complexes with environmental compliance capabilities.
Commercial farming cooperatives in Brazil are consolidating input purchasing through digital platforms that aggregate volume and negotiate delivered pricing directly with manufacturers. These buyer alliances are bypassing traditional agricultural retail networks that previously controlled distribution in Paraná and Rio Grande do Sul. The channel shift is concentrating procurement power among fewer decision-makers and compressing payment terms for suppliers.
Global Ammonium Sulphate Market Segmentation
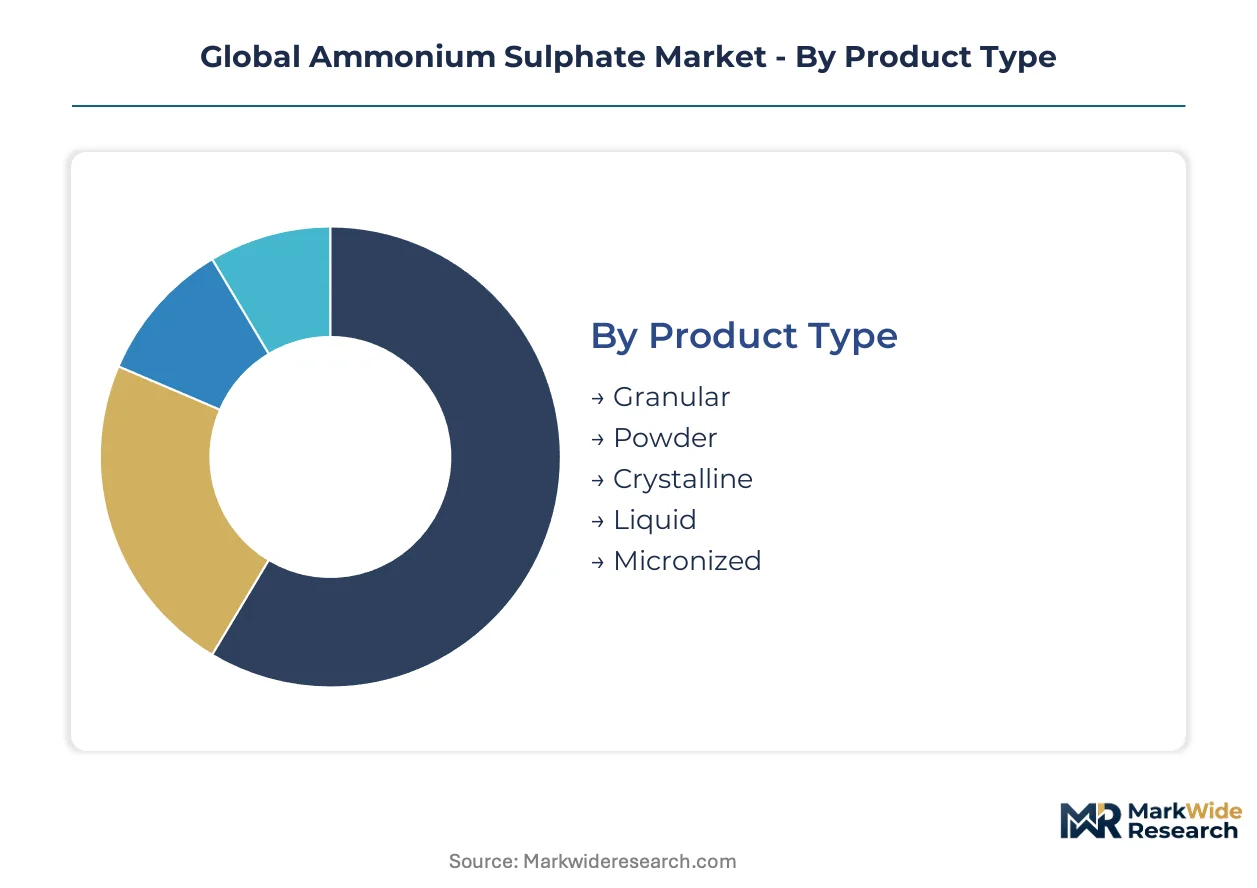
Certification requirements fragment the ammonium sulphate landscape into parallel supply chains, where fertilizer-grade BIS approvals, food-grade FSSAI standards, and pharmaceutical-grade GMP compliance create non-interchangeable product tiers with diverging margin structures.
Product Type:
Fertilizer-grade crystalline and granular forms carry distinct regulatory burdens: crystalline demands REACH registration for EU import, while granular faces EPA discharge compliance for US manufacturing facilities.
- Granular:Spherical particles sized 2-4mm enable mechanical spreading compatibility with standard farm equipment. Commercial farming operations in Brazil's Mato Grosso state specify this grade for soybean-corn rotation systems where sulphur deficiency limits yield potential.
- Crystalline:High-purity monoclinic crystals exceeding agricultural contamination thresholds serve pharmaceutical and food additive channels. EU Fertilizing Products Regulation tightening pushes producers toward this grade despite crystallization line retrofit costs.
- Powder:Rapid-dissolution specification for water treatment utilities requiring immediate ionic availability.
- Liquid:Pre-diluted solutions for precision fertigation systems in controlled-environment agriculture.
- Micronized:Sub-100 micron particles for specialty flame retardant applications in polymer compounding.
Volume sits with Granular; growth tilts toward Crystalline.
Application:
Cost tier separation runs deepest here, with fertilizer applications trading at commodity margins while pharmaceutical and food additive certifications capture 3-5x price multiples.
- Fertilizers:Primary nitrogen-sulphur delivery mechanism for alkaline soil pH correction. East Asian chemical manufacturing corridors supply integrated fertilizer networks through caprolactam by-product streams, compressing delivered costs.
- Food Additives:Leavening agent and dough conditioner applications governed by FSSAI purity specifications in India. Membrane filtration technology now extracts pharmaceutical-grade material from previously lower-value waste streams.
- Pharmaceutical:Laboratory reagent and excipient uses requiring GMP documentation.
- Water Treatment:Municipal utilities specify powder grades for rapid dissolution in pH adjustment protocols.
- Flame Retardants:Intumescent coating formulations leveraging nitrogen release characteristics.
Revenue concentrates in Fertilizers; margin expansion concentrates in Food Additives.
End User Industry:
Customer type determines procurement modality, with commercial farming cooperatives aggregating volume through digital platforms while water utilities issue specification-tender contracts.
- Commercial Farming:Brazilian cooperatives in Paraná and Rio Grande do Sul bypass traditional agricultural retail networks through buyer alliances that negotiate delivered pricing directly with manufacturers. Sulphur-enriched soil amendments strengthen adoption in sulphur-deficient tropical soils.
- Food Processing:Bakeries and confectionery manufacturers require FSSAI-certified crystalline grades with documented heavy metal limits below agricultural thresholds.
- Chemical Manufacturing:Caprolactam producers with integrated ammonium sulphate recovery serve captive fertilizer networks.
- Water Utilities:Municipal treatment plants issue rapid-dissolution specifications for pH adjustment operations.
- Textile Production:Dyeing auxiliary applications in synthetic fiber processing.
Procurement power concentrates with Commercial Farming; specification intensity peaks with Food Processing.
Packaging Type:
Supply chain configuration determines packaging economics, with coastal export facilities favoring bulk cargo while inland distribution requires bagged flexibility.
- Bulk Bags:One-tonne flexible intermediate bulk containers dominate ocean freight from Chinese caprolactam recovery plants to Brazilian port terminals.
- Paper Bags:25-50kg multiwall sacks for European agricultural retail networks facing plastic reduction mandates.
- Plastic Bags:Moisture-barrier specifications for humid climate storage in Southeast Asian distribution.
- Drums:Pharmaceutical and laboratory chemical channels requiring sealed containment.
- Loose Cargo:Vessel-hold loading for integrated chemical complexes with dedicated handling infrastructure.
Freight efficiency favors Bulk Bags; regulatory pressure elevates Paper Bags.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces the majority of caprolactam-derived ammonium sulphate while Brazil absorbs the largest agricultural import volumes. This production-consumption divide shapes freight economics and regulatory arbitrage across trade corridors.
China
Caprolactam recovery plants in Shandong and Zhejiang provinces supply East Asian fertilizer networks through membrane filtration upgrades. MEE emission controls on ammonia nitrogen discharge are forcing plant retrofits or closures, consolidating output toward state-owned enterprise complexes. Integrated chemical corridors in these coastal provinces now serve pharmaceutical-grade extraction channels.
Brazil
Commercial farming cooperatives in Mato Grosso and Goiás states drive sulphur-enriched soil amendment demand for soybean-corn rotations. ANVISA oversees import registration for food-grade applications alongside MAPA fertilizer quality protocols. Digital buyer alliances in Paraná and Rio Grande do Sul are bypassing traditional agricultural retail networks to negotiate direct manufacturer pricing.
Germany
BASF SE leverages its Ludwigshafen caprolactam-integrated footprint to anchor European supply security for fertilizer distributors. REACH registration requirements create non-tariff barriers for imported grades from non-registered facilities. The Rhine-Ruhr chemical cluster maintains crystallization capacity for pharmaceutical and food additive purity tiers.
United States
AdvanSix operates a Virginia manufacturing complex serving merchant-grade volume demand, while Nutrien dominates agricultural retail distribution networks. EPA discharge thresholds govern environmental releases from direct synthesis facilities. The Gulf Coast petrochemical corridor interacts with ammonia price volatility to determine cost competitiveness against by-product imports.
India
Fertilizer-grade BIS and food-grade FSSAI certification tracks create parallel compliance pathways for importers. Dual certification timelines extend regulatory review cycles for producers seeking both agricultural and food additive market access. Gujarat and Maharashtra industrial zones concentrate import handling infrastructure for crystalline grades.
Global Ammonium Sulphate Market Competitive Landscape
Top-tier vendors anchor integrated chemical production, while merchant-grade specialists compete on volume flexibility. The vendor base stratifies across three tiers: caprolactam-integrated chemical majors, standalone nitrogen fertilizer producers, and regional import distributors. Two strategic archetypes dominate: backward-integrated petrochemical players with captive ammonia supply, and distribution-heavy agricultural retailers with farm-gate delivery networks. Capacity expansion in East Asian caprolactam corridors and crystallization line upgrades for EU contaminant compliance represent the primary competitive vectors.
Among European chemical majors, BASF SE exemplifies the integrated production archetype through its caprolactam-derived ammonium sulphate recovery systems. Nutrien occupies a position within the agricultural retail tier, leveraging its North American distribution infrastructure. AdvanSix represents the standalone merchant-grade manufacturer archetype with its Virginia-based direct synthesis complex.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries |
| Sumitomo Chemical |
| Lanxess |
| Domo Chemicals |
| Arkema |
| Fibrant |
| AdvanSix |
| Nutrien |
| Others |
Supply & Pricing Matrix
Sovereign-backed producers in China's Shandong and Zhejiang provinces anchor supply concentration, translating captive caprolactam recovery streams into pricing discipline that resists ammonia volatility elsewhere. State-owned enterprise complexes with environmental compliance capabilities extract premiums from displaced volume as MEE emission controls force competitor closures.
Pricing Analysis
Margin tightening in fertilizer-grade granular reflects urea substitution pressure and natural gas cost swings compressing direct synthesis economics. Three-tier pricing structure across pharmaceutical-grade crystalline, food-grade certified, and agricultural commodity tiers separates margin pools by certification burden. Price differentiation tracks REACH registration status and FSSAI purity thresholds. Brazilian commercial farming cooperatives exhibit highest price sensitivity through digital buyer alliances, while pharmaceutical and food additive channels absorb premiums for GMP documentation.
Supply Chain Analysis
Skilled technician availability constraints in Germany's Rhine-Ruhr chemical cluster and China's coastal provinces limit crystallization line expansion pace. Manufacturing concentrates in China, Germany, and the United States. Feedstock draws from caprolactam by-product streams, natural gas-derived ammonia, and petroleum-refined sulphur recovery. Single-source vulnerability concentrates in East Asian caprolactam corridors where MEE compliance consolidation accelerates. Distribution runs through agricultural retail networks in North America, direct manufacturer negotiations in Brazil, and integrated chemical complexes in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards backward integration into captive ammonia supply or downstream agronomy service platforms that bundle nutrient recommendations with bulk delivery contracts.
For Market Incumbents: Anchor supply security through membrane filtration upgrades extracting pharmaceutical-grade material from previously lower-value waste streams. Defend against urea substitution by embedding ammonium sulphate into subscription-based soil testing and prescription agronomy services that lock in farm-gate offtake. Prioritize crystallization line investments ahead of EU Fertilizing Products Regulation contaminant threshold enforcement. For New Entrants and Emerging Players: Municipal water utilities requiring rapid-dissolution powder grades represent an underpenetrated specification-tender channel with limited incumbent focus. Target Indian food-grade FSSAI certification as a margin expansion pathway beyond agricultural commodity pricing, leveraging dual certification timelines that deter established fertilizer-grade specialists. Lead with technical sales support for pH adjustment protocol documentation. For Investors and Strategic Acquirers: Distressed-cycle entries favor caprolactam-integrated chemical complexes with environmental compliance infrastructure in China's Shandong province. Long-term viability hinges on sulphur recovery economics diverging from ammonia price volatility through the forecast horizon. Watch MEE emission control enforcement intensity as consolidation inflection signal toward state-owned enterprise capture of displaced volume.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Supply | Captive natural gas feedstock insulates BASF and AdvanSix from price volatility compressing merchant-grade competitors. |
| Membrane Filtration Technology Deployment | Enables caprolactam producers to extract pharmaceutical-grade ammonium sulphate from previously lower-value waste streams. |
| Crystallization Line Retrofit Investment | Positions producers to capture EU Fertilizing Products Regulation premium demand as contaminant thresholds tighten. |
| Subscription Agronomy Service Launch | Bundles Nutrien's nutrient recommendations with bulk delivery contracts, compressing traditional distributor margins. |
| Dual Certification Track Pursuit | Opens FSSAI food-grade and BIS fertilizer-grade parallel pathways in India despite extended regulatory review cycles. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with caprolactam plant managers, fertilizer procurement leads at Brazilian commercial farming cooperatives, European agricultural distribution channel partners, and water utility specification engineers. Bottom-up volume modeling triangulated against top-down macroeconomic indicators derived from ACC and Cefic chemical industry reports, EPA discharge compliance databases, and REACH registration documentation.
Granularity-level modeling segmented the market by product grade tier, end-use application, packaging format, and regional production hub across the projection horizon. CAGRs were derived from historical trade flow analysis and forward-looking capacity expansion announcements. Forecast inputs incorporated sulphur recovery economics from petroleum refining and ammonia price volatility trajectories.
Revisions become necessary when MEE emission control enforcement accelerates plant closures, EU Fertilizing Products Regulation implementation timelines shift, or Brazilian digital buyer alliance consolidation concentrates procurement power beyond modeled thresholds. A small set of regulatory enforcement intensity and feedstock cost divergence triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Bio Based Platform Chemicals Market
Bulk Chemicals
Aerospace and Defense Chemical Distribution Market
Bulk Chemicals
South America Carbon Black Market
Bulk Chemicals
Ferric Sulfate Market
Bulk Chemicals
Global Ethylene Market
Bulk Chemicals
Magnesium Lactate Market
Bulk Chemicals
Isoprene Monomer Market
Bulk Chemicals
Muconic Acid Market
Bulk Chemicals
Monoethylene Glycol (MEG) Market
Bulk Chemicals
Aluminum Sulfide Market
Bulk Chemicals
Caproic Acid Market
Bulk Chemicals
Phosphorus and Derivatives Market
Bulk Chemicals
Chlorotoluenes Market
Bulk Chemicals
North America Starch Derivatives Market
Bulk Chemicals
Aluminum Sulfate Market
Bulk Chemicals
Calcium Carbonate Market