
 Ethylbenzene Market | 2026-2036
Ethylbenzene Market Size, Share, and Industry Trends Forecast 2026-2036
Ethylbenzene Market Intelligence
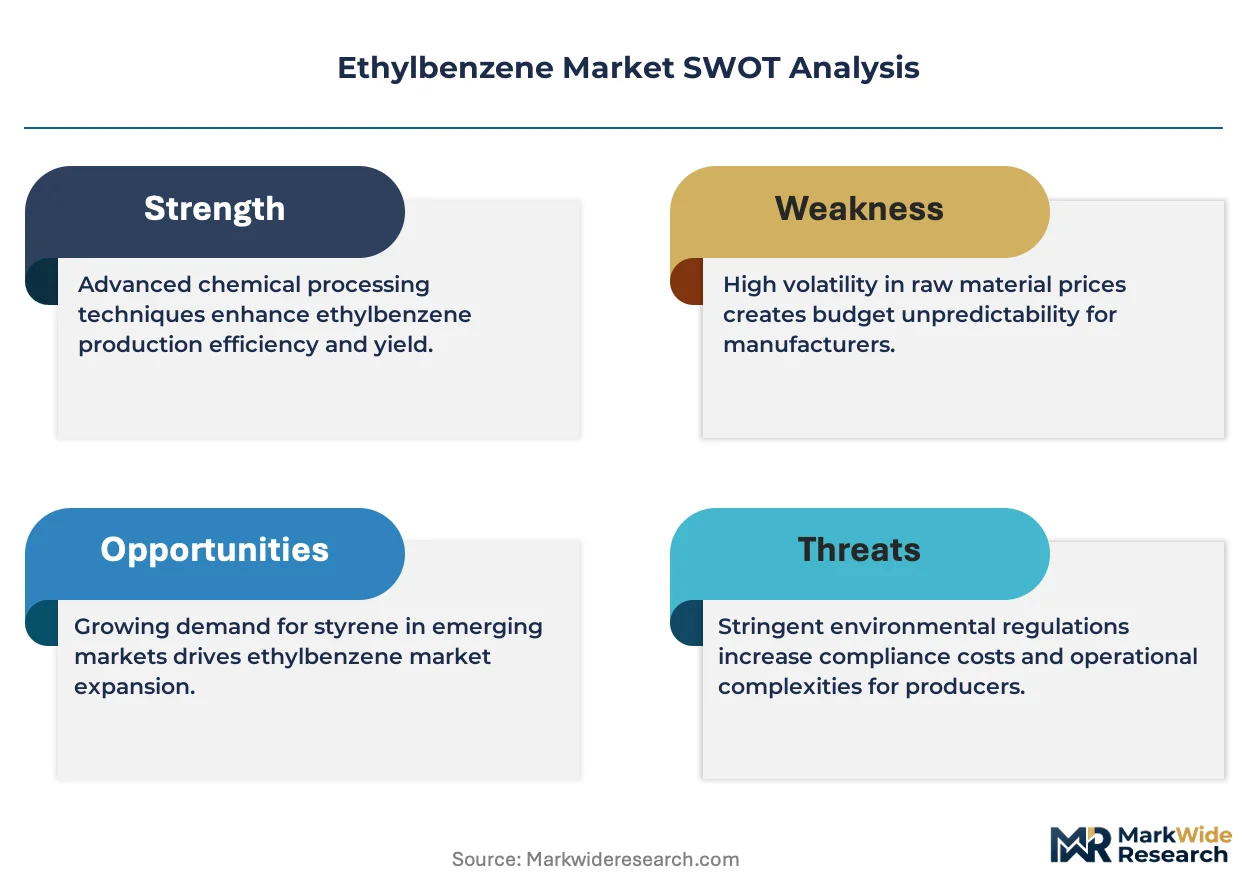
Alkylation catalyst innovation is reconfiguring how ethylbenzene producers optimize benzene-to-ethylene conversion efficiency and byproduct control. LyondellBasell Industries Holdings B.V. leverages its proprietary technology licensing to sustain margins across multiple geographies. Chevron Phillips Chemical Company LLC anchors its position through Gulf Coast feedstock integration. INEOS dominates European merchant supply with dedicated aromatics chain control.
Ethylbenzene is an aromatic hydrocarbon with formula C₈H₁₀, produced primarily via catalytic alkylation of benzene with ethylene using zeolite or aluminum chloride catalysts, serving almost exclusively as the precursor to styrene monomer. Styrene polymerization consumes over ninety-nine percent of global ethylbenzene output, with polystyrene and expandable polystyrene representing the dominant downstream value pools. Construction end-use applications command the largest share of styrene-derived demand, while electronics and consumer goods segments are expanding fastest in Asia-Pacific manufacturing hubs. Chemical intermediates applications outside styrene remain marginal but attract specialty margins in coatings and adhesives formulations.
US EPA benzene emission standards and OSHA workplace exposure limits constrain alkylation unit design and operating permits, while China's MEE enforces stricter volatile organic compound controls on petrochemical complexes. REACH registration requirements in Europe shape import competitiveness and substitution economics for non-integrated buyers. Stakeholders must monitor catalyst technology licensing costs against carbon border adjustment mechanisms that could restructure interregional trade flows.
Market Dynamics
Zeolite catalyst substitution for aluminum chloride systems is compressing alkylation unit operating costs while tightening benzene conversion efficiency standards across integrated petrochemical complexes.
Growth Catalysts
- Styrene polymerization for packaging:Food contact applications and e-commerce protective materials are pulling ethylbenzene through expandable polystyrene value chains.
- China's dual carbon goals:MEE emissions standards are accelerating refinery catalyst replacement cycles and favoring lower-carbon alkylation process designs.
- East China petrochemical clusters:Nanjing and Ningbo integrated styrene-ethylbenzene units are concentrating capacity additions and feedstock optimization investments.
Market Restraints
- Benzene feedstock volatility:Aromatics extraction economics tie ethylbenzene margins to refinery reformate output and naphtha cracking spreads.
- US Gulf Coast supply concentration:Chevron Phillips and LyondellBasell capacity dominance creates bottleneck risk for North American merchant buyers.
- REACH registration friction:ECHA compliance costs for non-integrated European importers compress arbitrage windows against Middle Eastern supply.
Strategic Opportunities
- India's petrochemical corridor expansion:Dahej and Mundra clusters lack integrated styrene capacity, creating merchant ethylbenzene entry points for Middle Eastern producers.
- Bio-based styrene R&D:Renewable feedstock pathways for styrene monomer could bifurcate ethylbenzene demand between fossil and circular value pools.
- Carbon border adjustment mechanisms:EU CBAM implementation favors low-carbon intensity alkylation processes in carbon-accounting trade flows.
Industry Challenges
- Catalyst licensing complexity:Proprietary zeolite formulations from UOP and ExxonMobil lock process economics into long-term royalty structures.
- Alkylation unit retrofit capex:Converting aluminum chloride systems to solid acid catalysts demands extended turnaround timelines and specialized reactor engineering.
- OSHA benzene exposure compliance:Workplace monitoring and abatement systems add operational overhead to legacy alkylation facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethylbenzene Market |
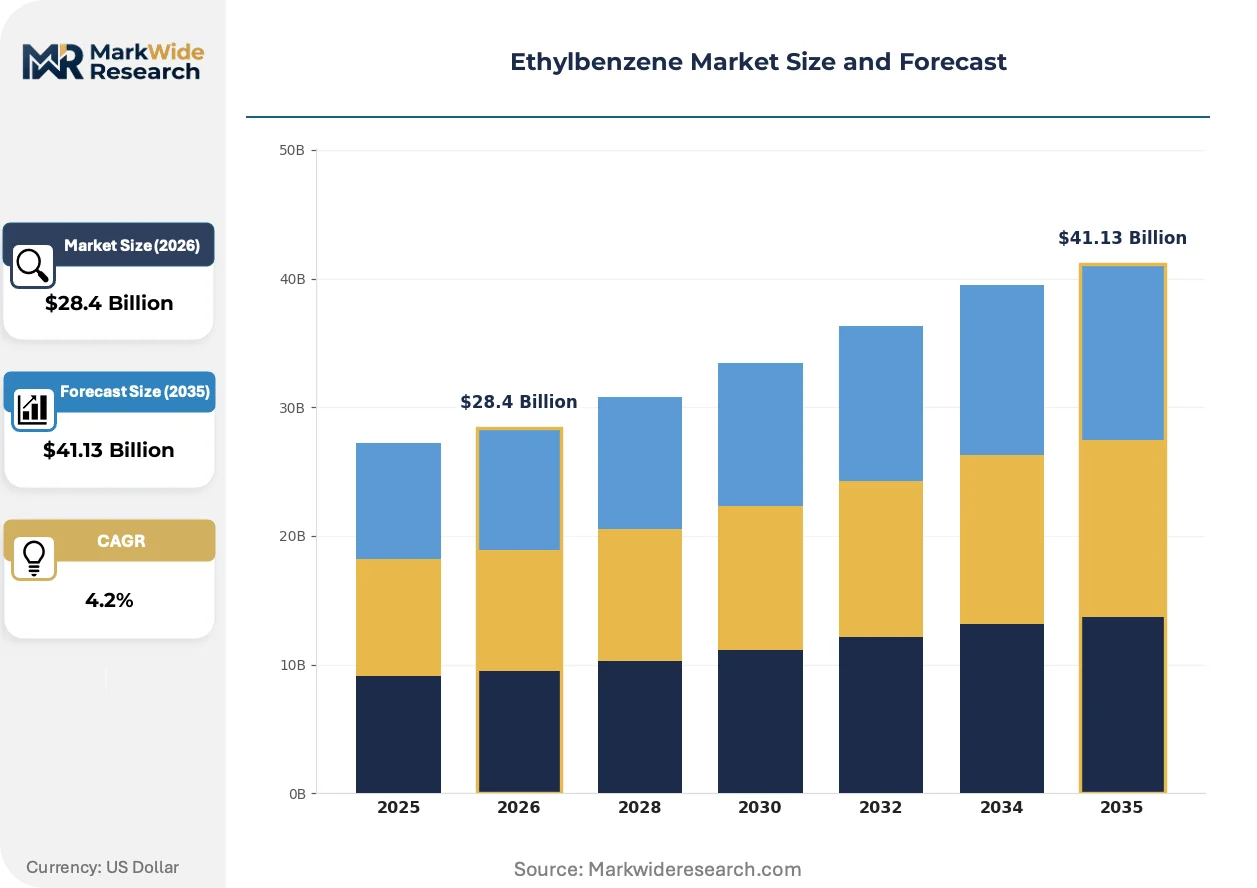
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $41.13 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Styrene, Coatings, Adhesives, Plastics End User: Construction, Automotive, Electronics, Consumer Goods Application: Manufacturing, Chemical Intermediates, Packaging, Insulation Distribution Channel: Direct Sales, Distributors, Retail, Online |
| Companies Covered | Royal Dutch Shell, Honeywell International Inc, LyondellBasell Industries Holdings B.V., Reliance Industries Limited, Dow, INEOS, China Petroleum & Chemical Corporation (Sinopec), Sasol Limited, Chevron Phillips Chemical Company LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethylbenzene Market Strategic Shifts & Innovations
Process intensification and regulatory carbon accounting are converging to reshape catalyst selection, unit design, and interregional trade economics for ethylbenzene producers.
Zeolite-based alkylation technology is hybridizing fixed-bed and fluidized-bed reactor architectures to maximize ethylene utilization rates while minimizing benzene recycle loops. Integrated styrene producers in China and the Middle East are adopting these hybrid configurations for greenfield units. This convergence is compressing the cost gap between merchant and captive ethylbenzene supply.
China's MEE volatile organic compound controls are tightening fugitive emission standards for benzene handling and alkylation unit vent streams. Refinery-petrochemical complexes must install continuous monitoring systems and vapor recovery units to maintain operating permits. East China facilities around Ningbo are retrofitting first, creating a compliance cost gradient versus newer Gulf Coast installations.
Spot purchasing concentration among large styrene polymerization units is compressing contract tenures and amplifying price volatility transmission. Merchants are responding with formula pricing tied to benzene and ethylene indices rather than fixed differentials. This shift is most pronounced in Asian trading hubs where integrated producers compete directly with Middle Eastern importers.
Ethylbenzene Market Segmentation
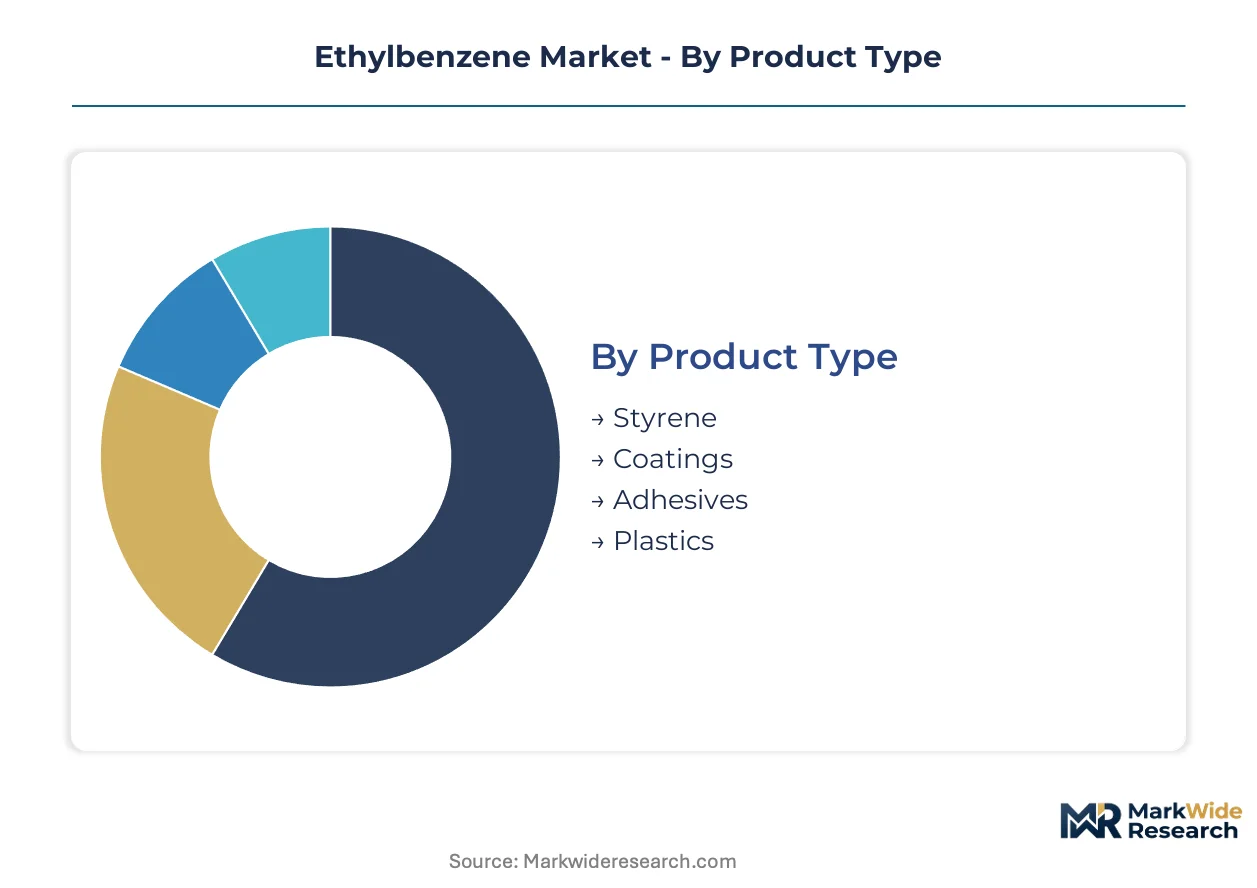
Ethylbenzene demand patterns diverge sharply across downstream chemistry pathways, end-use durability requirements, and supply chain configurations. Understanding these segment boundaries clarifies where integrated producers extract margin premiums versus where merchant suppliers compete on feedstock arbitrage.
Product Type:
Styrene monomer dominates the use-case spectrum, though specialty chemical applications generate disproportionate margin capture.
- Styrene:Catalytic dehydrogenation of ethylbenzene yields this aromatic monomer at purity grades exceeding 99.8%, with polymerization-grade specifications governing refinery-petrochemical integration economics. Construction and packaging applications in China, the US, and Germany absorb the preponderance of styrene-derived ethylbenzene, constrained by benzene-ethylene spread volatility and alkylation catalyst replacement cycles.
- Coatings:Solvent-grade ethylbenzene serves as a high-boiling-point diluent in industrial coatings formulations, particularly for marine and protective applications requiring controlled evaporation rates. Demand concentrates in European and Japanese automotive OEM supply chains, where REACH registration and VOC emission limits under Japan's Air Pollution Control Act shape formulation substitution economics.
- Adhesives:Pressure-sensitive and hot-melt adhesive systems utilize ethylbenzene as a tackifier solvent and viscosity modifier in specialty industrial bonding applications.
- Plastics:Minor direct incorporation into modified polystyrene grades and polymer blends occurs outside the dominant styrene monomer pathway.
Established volume favors styrene; emerging adoption favors coatings.
End User:
Construction durability requirements and automotive lightweighting specifications create divergent purity and volume demands across end-use categories.
- Construction:Expandable polystyrene insulation boards and concrete formwork systems anchor styrene consumption in residential and commercial building envelopes. China's urban renewal programs and US single-family housing starts in Texas and Florida drive regional demand clustering, with MEE emissions compliance adding cost layers to East China supply.
- Automotive:Acrylonitrile-butadiene-styrene resins for interior trim and structural components require tight monomer impurity controls. German and Japanese OEM specifications favor integrated ethylbenzene-styrene producers with continuous catalytic reformer feedstock access.
- Electronics:High-impact polystyrene for appliance housings and semiconductor packaging trays demands ultra-low metal content specifications.
- Consumer Goods:Food-contact polystyrene for disposable tableware and retail packaging operates under FDA, EFSA, and China's NMPA migration limit frameworks.
Construction commands absolute volume; electronics exhibits the steepest expansion trajectory.
Application:
Captive manufacturing integration versus merchant chemical intermediates trade defines margin architecture across application modes.
- Manufacturing:On-site ethylbenzene-to-styrene conversion within integrated petrochemical complexes eliminates logistics costs and inventory carrying charges. LyondellBasell's Channelview and INEOS's Cologne facilities exemplify this configuration, with benzene pipeline access from adjacent refinery aromatics extraction units.
- Chemical Intermediates:Merchant ethylbenzene sales to non-integrated styrene producers concentrate in European spot markets and Indian import corridors, with Dahej and Mundra clusters lacking captive alkylation capacity.
- Packaging:Expandable polystyrene for protective shipping materials and food service applications pulls ethylbenzene through e-commerce logistics expansion in Southeast Asian manufacturing hubs.
- Insulation:Rigid polystyrene foam board for building energy efficiency standards operates under divergent fire safety regulations across US ICC codes, EU CPR classifications, and China's GB standards.
Manufacturing integration maximizes margin retention; chemical intermediates trade amplifies price volatility exposure.
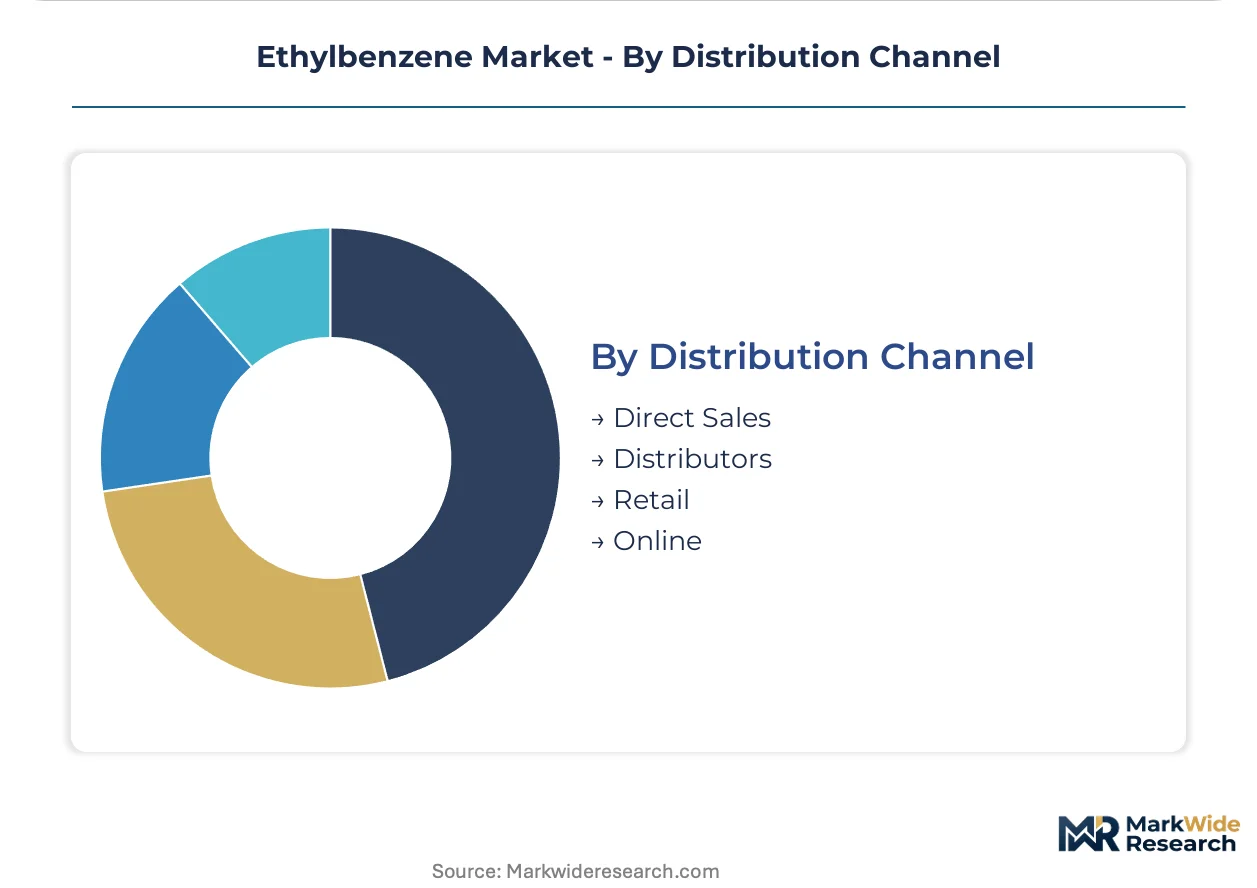
Distribution Channel:
Contract tenure compression and spot market liquidity reshape channel economics for ethylbenzene procurement.
- Direct Sales:Long-term offtake agreements between integrated producers and captive styrene units lock in benzene-ethylene formula pricing, with Chevron Phillips and SABIC favoring this structure for Gulf Coast and Middle Eastern supply.
- Distributors:Regional chemical merchants aggregate smaller styrene producer demand in Europe and India, warehousing inventory to buffer turnaround-related supply interruptions.
- Retail:Drum and tote packaging for laboratory and specialty coatings applications represents marginal volume with premium pricing.
- Online:Digital procurement platforms for spot benzene and ethylene index-linked contracts are gaining traction among Asian trading houses seeking real-time price discovery.
Direct sales preserve supply security; online channels accelerate price transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated styrene producers concentrate procurement power across four demand centers where alkylation capacity and downstream polymerization units co-locate. Merchant supply competes where refinery-petrochemical integration remains incomplete.
China
MEE volatile organic compound controls are tightening fugitive emission standards for benzene handling in East China petrochemical clusters. The country's dual carbon goals accelerate catalyst replacement cycles at integrated Nanjing and Ningbo facilities. East China facilities retrofit vapor recovery units first, creating compliance cost gradients versus newer installations elsewhere.
United States
OSHA benzene exposure limits and EPA emission standards constrain alkylation unit design along the Gulf Coast. Chevron Phillips and LyondellBasell capacity dominance concentrates merchant supply risk for non-integrated buyers. Texas and Louisiana facilities leverage pipeline-connected refinery aromatics extraction for captive feedstock security.
Germany
REACH registration requirements shape import competitiveness for non-integrated European styrene producers. INEOS maintains dedicated aromatics chain control through Cologne integrated operations. The country's automotive OEM specifications favor continuous catalytic reformer feedstock access for tight monomer impurity controls.
Saudi Arabia
SABIC's Gulf Coast-adjacent capacity anchors Middle Eastern merchant supply into Indian import corridors lacking integrated alkylation infrastructure. The kingdom's feedstock integration economics compress delivered costs versus European spot alternatives. Dahej and Mundra clusters represent entry points for Middle Eastern producers seeking non-captive demand.
India
Petrochemical corridor expansion at Dahej and Mundra lacks integrated styrene capacity, creating merchant ethylbenzene demand for Middle Eastern importers. The country's national pollution control standards tighten benzene handling protocols at port terminals and chemical processing zones. Maharashtra and Gujarat coastal clusters concentrate import logistics infrastructure for non-integrated downstream units.
Ethylbenzene Market Key Industry Players
Channel-controlling players compete with product-specialist players across a consolidated structure where integrated refinery-petrochemical complexes dominate volume. Three archetypes define positioning: Gulf Coast feedstock-integrated majors, European merchant specialists with aromatics chain control, and Middle Eastern export-oriented producers leveraging ethane cracking economics. Capacity expansion and catalyst technology licensing represent the dominant competitive moves, with retrofit alkylation unit conversions extending turnaround timelines for legacy facilities.
Within the integrated-major tier, Chevron Phillips Chemical Company LLC and LyondellBasell Industries Holdings B.V. exemplify Gulf Coast feedstock integration archetypes. INEOS occupies a position representing European merchant supply concentration with dedicated aromatics infrastructure. China Petroleum & Chemical Corporation (Sinopec) anchors the state-integrated producer category serving captive East China demand clusters.
| Leading Market Players |
|---|
| Royal Dutch Shell |
| Honeywell International Inc |
| LyondellBasell Industries Holdings B.V. |
| Reliance Industries Limited |
| Dow |
| INEOS |
| China Petroleum & Chemical Corporation (Sinopec) |
| Sasol Limited |
| Chevron Phillips Chemical Company LLC |
| Others |
Cost & Logistics Intelligence
Benzene-ethylene spread volatility determines both contract pricing tier spreads and supply chain configuration for ethylbenzene producers. This feedstock cost interdependency compresses margins for merchant suppliers while rewarding integrated refinery-petrochemical complexes with captive aromatics extraction.
Pricing Analysis
Cost-plus contracts with benzene and ethylene indexation dominate ethylbenzene procurement, with formula pricing tied to spot aromatics and olefins benchmarks rather than fixed differentials. Price differentiation rests on alkylation catalyst technology licensing tiers and volume scale commitments, with zeolite-based producers commanding premium terms over aluminum chloride legacy units. Pricing pressure stems from spot purchasing concentration among large styrene polymerization units compressing contract tenures. Merchant buyers in European spot markets exhibit highest price sensitivity, while integrated Gulf Coast producers with pipeline-connected refinery feedstock demonstrate lowest sensitivity due to captive supply economics.
Supply Chain Analysis
Contract manufacturing concentration sits with LyondellBasell Industries Holdings B.V., Chevron Phillips Chemical Company LLC, and INEOS holding dominant alkylation capacity positions across the United States, Saudi Arabia, and Germany. Raw material dependencies center on refinery reformate benzene, steam cracker ethylene, and proprietary zeolite catalyst formulations from UOP and ExxonMobil licensing. Supply chain risk manifests as single-source vulnerability for North American merchant buyers dependent on Gulf Coast production concentration. Distribution runs through pipeline networks for integrated captive supply, with seaborne bulk shipment serving European spot markets and Indian import corridors at Dahej and Mundra.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ethylbenzene demand tracks construction cyclicality through expandable polystyrene insulation consumption, with China's urban renewal programs and US housing starts serving as lead indicators for volume recovery.
For Market Incumbents: Insulate margin position by accelerating zeolite catalyst retrofits at legacy aluminum chloride facilities before MEE emissions deadlines tighten in East China. Deepen backward integration into refinery aromatics extraction where pipeline infrastructure permits, particularly along the US Gulf Coast where benzene feedstock security differentiates integrated producers from merchant competitors facing reformate output volatility.
For New Entrants and Emerging Players: India's Dahej and Mundra petrochemical corridors lacking integrated styrene capacity represent the most penetrable entry point for Middle Eastern producers with ethane cracking economics. Merchant ethylbenzene supply to non-integrated downstream units in Maharashtra and Gujarat coastal clusters offers volume traction without competing against established integrated majors. A go-to-market angle anchored to carbon intensity differentials under EU CBAM implementation protocols attracts European buyers seeking lower-carbon alkylation process credentials.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated refinery-petrochemical complexes with catalyst technology licensing control and captive aromatics chain access. Long-term viability over the next decade hinges on greenfield capacity economics in low-carbon jurisdictions and retrofit completion timelines for legacy alkylation units. The signal to watch is MEE enforcement intensity at East China facilities, where compliance cost gradients between retrofitted and non-compliant plants will determine regional competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Zeolite Catalyst Retrofit | Alkylation unit conversions to solid acid systems reduce MEE compliance costs at East China facilities. |
| Backward Integration | Pipeline-connected refinery aromatics extraction secures benzene feedstock against reformate output volatility. |
| Long-term Supply Agreement | Formula-priced offtake contracts with Indian styrene producers lock in Dahej corridor volume commitments. |
| Joint Venture | Technology licensing partnerships with Sinopec accelerate greenfield hybrid reactor adoption in Ningbo clusters. |
| Green Manufacturing Transition | Low-carbon intensity alkylation processes position supply for EU CBAM-advantaged trade flows. |
Research Approach
A spread of perspectives from plant managers at integrated petrochemical complexes, procurement leads at downstream styrene polymerization units, distribution channel partners in European spot markets, and technical R&D directors at catalyst technology licensors converged on the working assumptions. These primary insights were cross-referenced against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical producers, and MEE emissions disclosure records. Bottom-up capacity and utilization estimates were triangulated with top-down demand modeling across styrene, coatings, and adhesives end-use segments.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeling spanning product grade tiers, end-use industry concentrations, regional production hub configurations, and catalyst technology licensing categories. CAGRs were derived from trend extrapolation of historical volume movements adjusted for announced capacity additions and regulatory-driven retrofit timelines. Forecast inputs incorporated benzene-ethylene spread trajectories, construction sector polystyrene consumption patterns, and MEE enforcement intensity scenarios.
Stress conditions across benzene feedstock price spikes, ethylene supply disruptions, and MEE compliance deadline accelerations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding catalyst replacement cycle completion rates and regional construction sector demand elasticity. Quarterly review of East China facility emission compliance progress, US housing start data, and Indian petrochemical corridor import volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Ferric Sulphate and Polyferric Sulphate Market
Bulk Chemicals
Global Isobutanol Market
Bulk Chemicals
Caprylic Acid Market
Bulk Chemicals
Sodium Bromide Market
Bulk Chemicals
Aluminum Nitrate Nonahydrate Market
Bulk Chemicals
2-Methylfuran Market
Bulk Chemicals
Global Linear Alpha Olefins Market
Bulk Chemicals
4-Diisopropylbenzene Market
Bulk Chemicals
US Magnesium Stearate Market
Bulk Chemicals
North America Methyl Acrylate Market
Bulk Chemicals
Sodium Hydroxide Market
Bulk Chemicals
Aluminum Sulfide Market
Bulk Chemicals
North America Hydrochloric Acid Market
Bulk Chemicals
Global Potassium Metabisulfite Market
Bulk Chemicals
Global Sodium Percarbonate Market
Bulk Chemicals
Acetyl Tributyl Citrate Market