
 Asia-Pacific Caustic Soda Market | 2026-2036
Asia-Pacific Caustic Soda Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Caustic Soda Market Outlook
Project finance tied to chlor-alkali capacity expansions is reconfiguring competitive entry in the Asia-Pacific caustic soda sector. Tata Chemicals Ltd leverages captive brine access and coastal logistics to sustain cost leadership across Indian subcontinent markets. Grasim Industries Limited anchors its position through backward integration into power generation and salt sourcing, insulating margins from feedstock volatility. Shin-Etsu Chemical Co., Ltd. differentiates via high-purity grades serving semiconductor and electronics chemical channels where specification thresholds exceed commodity benchmarks.
Caustic soda—sodium hydroxide manufactured through electrolysis of sodium chloride brine—typically presents as a 50% aqueous solution with strong alkaline reactivity essential for pH adjustment, saponification, and alumina digestion. Membrane cell technology has displaced mercury and diaphragm methods across most Asia-Pacific installations, yielding higher purity and lower energy intensity per ton of chlorine co-product. Liquid caustic dominates volume flows due to handling economies in bulk chemical transfer, though flake and solid forms command premium positioning in remote construction and specialized cleaning applications where dilution control matters. Industrial grade absorbs the majority of tonnage, while pharmaceutical and food grades extract disproportionate margin pools from stringent impurity protocols.
China's MEE enforces emissions intensity caps on chlor-alkali clusters, accelerating membrane conversions and carbon accounting disclosures. India's BIS certification requirements for caustic used in food processing and water treatment create compliance thresholds that filter smaller traders from formal supply chains. Stakeholders must track how carbon border adjustments and green hydrogen pilot integrations reshape the cost structure of electrolytic production across the region's major manufacturing zones.
Market Dynamics
Membrane cell retrofits across China's chlor-alkali belt are compressing mercury-process capacity while tightening supply elasticity for industrial-grade caustic. This technology transition is redistributing production advantage toward coastal plants with renewable power purchase agreements and integrated brine sourcing.
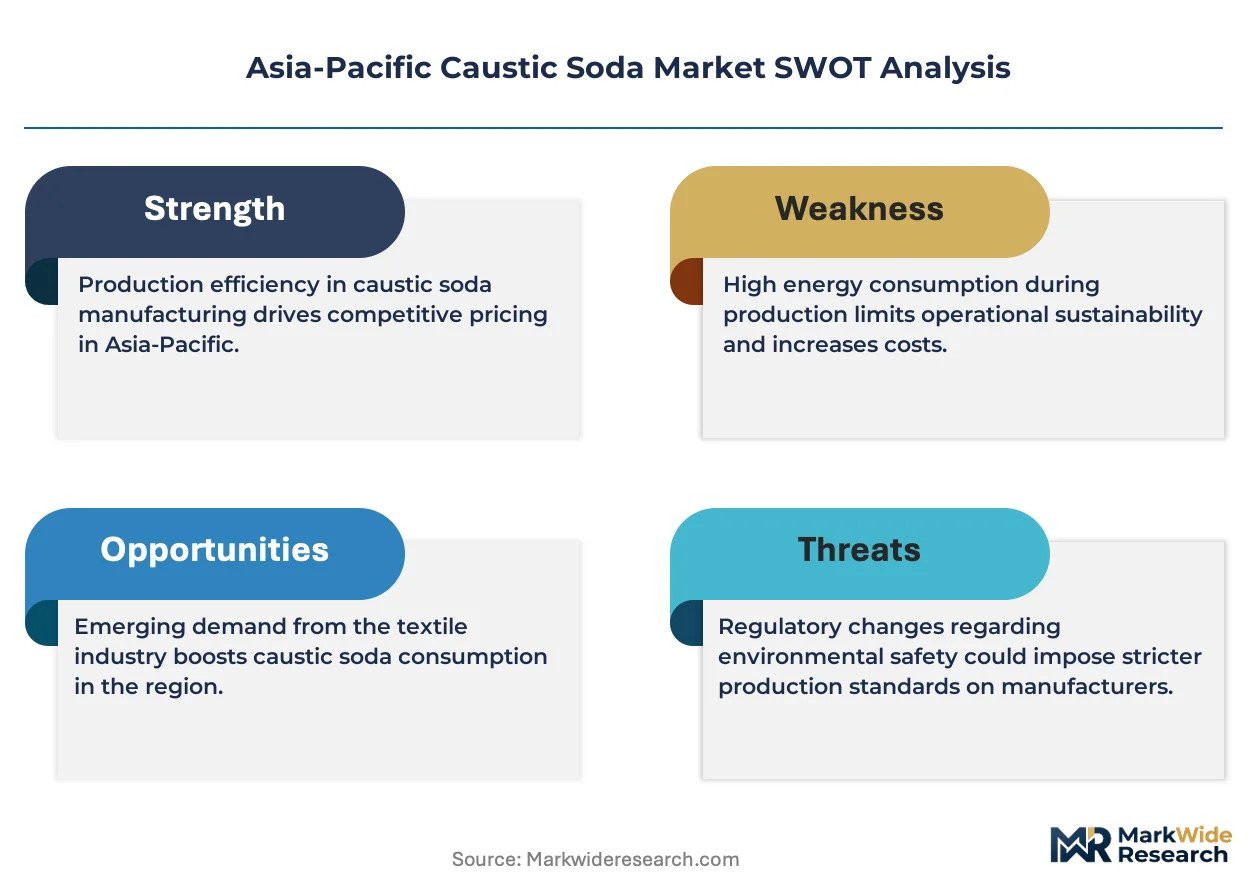
Growth Catalysts
- Alumina digestion demand:Bauxite refineries in Australia and Indonesia are lifting caustic offtake volumes as smelter-grade alumina capacity expands to serve regional aluminum fabrication.
- MEE emissions intensity caps:China's Ministry of Ecology and Environment mandates are accelerating membrane conversions that yield higher-purity output suitable for electronics-grade specifications.
- Integrated industrial park clustering:Eastern China's chemical manufacturing corridors concentrate buyers and suppliers within pipeline distance, reducing logistics friction and enabling just-in-time caustic delivery.
Market Restraints
- Salt and power input volatility:Electrolytic caustic production remains exposed to thermal coal price swings and solar curtailment rates that compress margin predictability for non-integrated producers.
- Supply concentration in coastal China:Shandong and Jiangsu provinces control disproportionate membrane cell capacity, creating geographic vulnerability to regional grid constraints or environmental shutdowns.
- Lime-based caustic substitution:Soda ash-lime processes in certain pulp bleaching applications are displacing merchant caustic volumes where pH adjustment tolerates lower alkalinity.
Strategic Opportunities
- Vietnam's emerging chemical corridor:Northern industrial zones around Haiphong offer underpenetrated demand from textile dyeing and paper processing seeking reliable liquid caustic supply.
- Green hydrogen pilot integration:Chlor-alkali producers with electrolyzer co-location can access renewable hydrogen offtake agreements that subsidize power costs through dual-product economics.
- Semiconductor-grade purity premium:Electronics chemical channels in South Korea and Taiwan specification thresholds exceed commodity benchmarks, extracting disproportionate margin pools from impurity-controlled production.
Industry Challenges
- Membrane cell engineering talent scarcity:Specialized technicians for ion-exchange membrane maintenance and cell room optimization command premium wages that inflate operating costs for retrofitting facilities.
- BIS certification timeline compression:India's Bureau of Indian Standards food-grade and water-treatment caustic approvals require extended laboratory validation that filters smaller traders from formal supply chains.
- Legacy mercury cell decommissioning complexity:Remediation of contaminated electrolyzer halls and brine circuits demands capital-intensive environmental liability management that strains balance sheets during technology transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Caustic Soda Market |
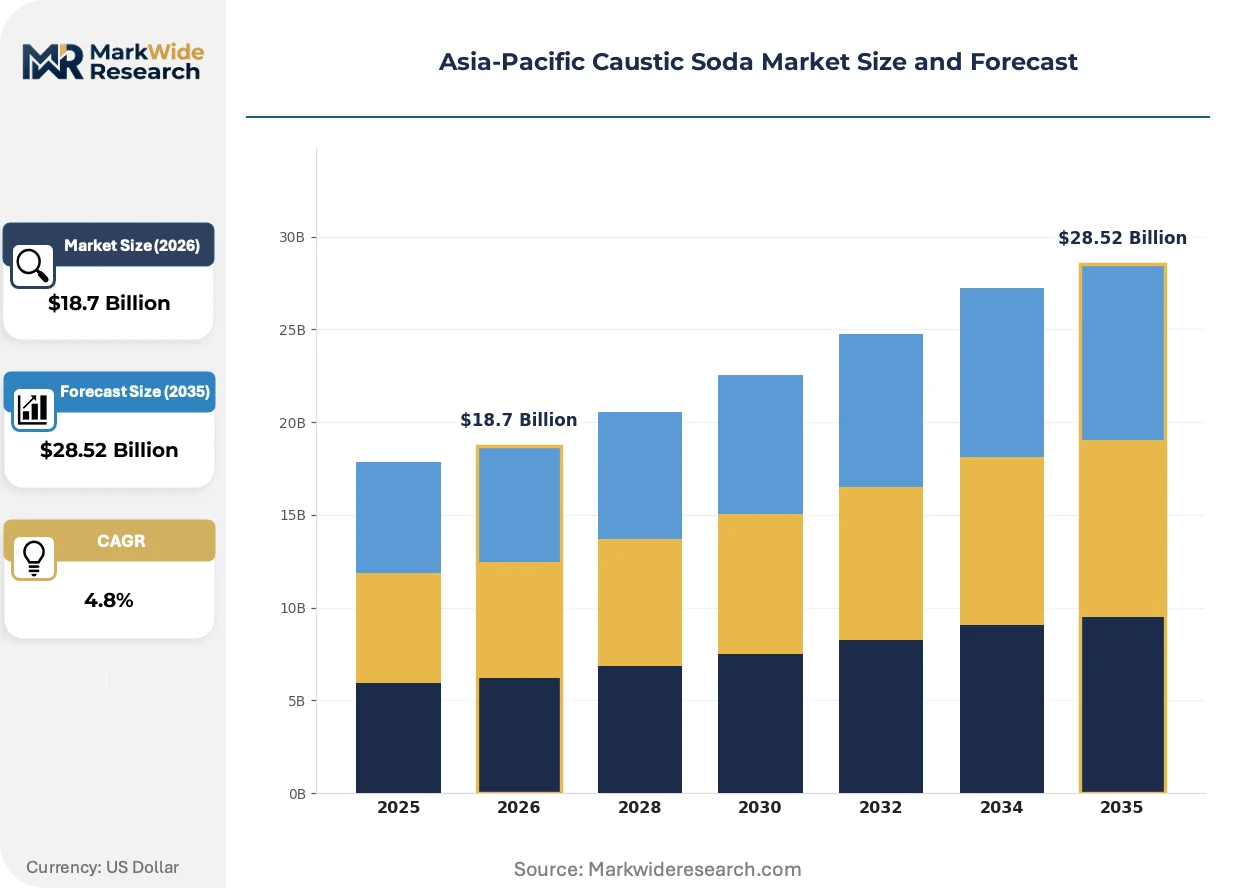
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Solid, Flake, Granule End User: Pulp & Paper, Textiles, Chemicals, Soaps & Detergents Application: Neutralization, Water Treatment, Cleaning Agents, Chemical Synthesis Grade: Standard, Industrial, Food, Pharmaceutical |
| Companies Covered | Tata Chemicals Ltd, Hanwha Solutions, Aditya Birla, Grasim Industries Limited, Shin-Etsu Chemical Co., Ltd., DCM Shriram, Tosoh Corporation, AGC Chemicals, Gujarat Alkalies and Chemicals Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Caustic Soda Market Strategic Shifts
Electrolyzer technology and power sourcing strategies are converging to redefine cost structures across Asia-Pacific chlor-alkali operations. Producers are repositioning around carbon intensity metrics that increasingly gate access to premium customer segments.
Membrane cell technology is migrating from mercury-process dominance in China's Shandong and Jiangsu provinces toward full regional standardization. Alumina refiners and pulp mills are adopting the higher-purity output at accelerating rates as specification thresholds tighten. This migration from legacy electrolysis is compressing residual mercury-cell margins while enabling electronics-grade caustic production that commands premium positioning in semiconductor chemical channels.
China's dual carbon goals under MEE supervision are enforcing renewable power sourcing mandates on chlor-alkali clusters above designated capacity thresholds. Industrial consequence includes accelerated power purchase agreement negotiations with provincial wind and solar farms. Coastal membrane cell operators in Jiangsu and Zhejiang are most affected, responding through integrated industrial park microgrids that stabilize electricity costs against grid volatility.
Specification-driven procurement is consolidating buyer preference around carbon-disclosed supply chains with membrane cell provenance. Chemical manufacturers and water treatment utilities are displacing spot-market spot purchases with long-term offtake contracts tied to emissions accounting. South Korean electronics chemical distributors and Australian alumina refineries exhibit this pattern most visibly, prioritizing suppliers with verified renewable power integration and ISO-certified impurity protocols.
Asia-Pacific Caustic Soda Market Segmentation
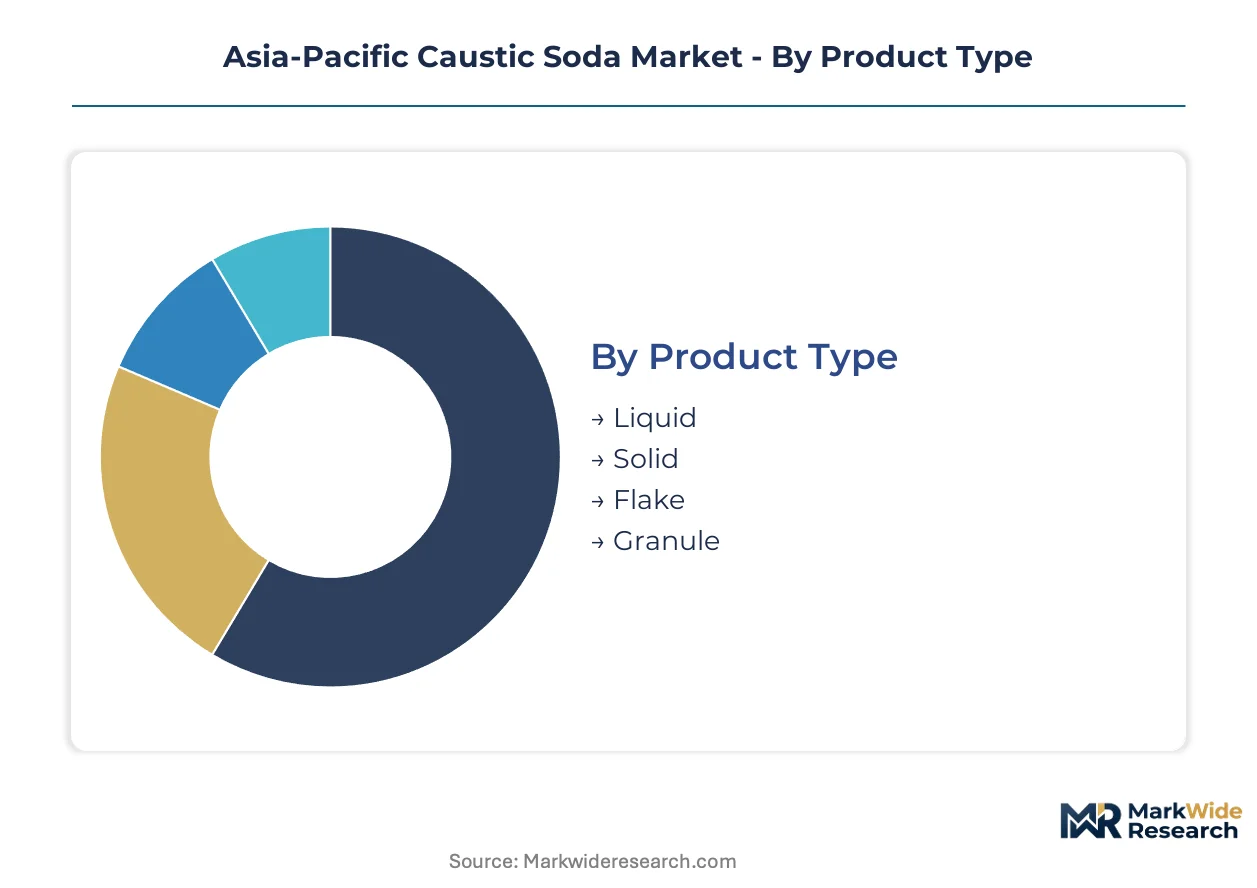
Caustic soda segmentation in Asia-Pacific tracks how physical form, purity thresholds, and end-use chemistry create divergent margin structures. Procurement cycles vary dramatically across these dimensions, from bulk liquid tenders tied to alumina refinery operations to pharmaceutical-grade validations requiring extended laboratory certification.
Product Type:
Liquid caustic turns inventory fastest through pipeline-connected industrial parks, while solid and specialty forms lock up working capital through longer conversion and distribution cycles.
- Liquid:A 50% aqueous solution delivered via tanker truck or dedicated pipeline, optimized for bulk chemical transfer economies. Alumina refineries in Australia's Gladstone corridor and Indonesia's Bintan Island absorb the largest volumes under long-term offtake contracts tied to bauxite processing schedules.
- Flake:Dehydrated caustic formed into thin sheets for controlled dissolution in remote construction and water treatment applications. Chemical distributors across Vietnam's northern industrial zones stock flake inventory where dilution precision matters and liquid bulk infrastructure remains underdeveloped.
- Solid:Cast blocks or briquettes with extended shelf stability for mining and metallurgical operations lacking on-site dilution equipment.
- Granule:Free-flowing particles sized for automated dosing systems in municipal water treatment and food processing facilities requiring rapid dissolution kinetics.
Liquid dominates installed base. Flake is where expansion concentrates.
End User:
Cost tier separation runs sharp across end-use segments, with commodity chemicals and pulp operations at the base and specialized detergents commanding formulation premiums.
- Chemicals:The largest consumption channel encompassing organic synthesis, petrochemical derivatives, and inorganic salt production. Eastern China's chemical manufacturing corridor from Shanghai to Ningbo clusters the densest demand, with membrane cell producers supplying pipeline-connected industrial parks under just-in-time logistics.
- Pulp & Paper:Kraft pulping and bleach sequences consume substantial caustic volumes for lignin removal and pH control. Indonesian mills in Sumatra and Kalimantan drive regional tonnage as plantation fiber capacity expands to serve packaging board export markets.
- Textiles:Mercerization and dyeing processes require controlled alkalinity for cotton fiber treatment and synthetic fiber finishing.
- Soaps & Detergents:Saponification reactions and pH adjustment in formulated cleaning products, with food-grade certification requirements filtering supply sources for consumer-facing brands.
Chemicals anchors volume throughput. Pulp & Paper is climbing the fastest.
Application:
Volume concentration aligns with process intensity, where neutralization and chemical synthesis absorb continuous flows versus intermittent treatment cycles.
- Neutralization:pH adjustment across wastewater streams, acid spill remediation, and process effluent treatment. Industrial parks in Jiangsu province deploy centralized neutralization facilities serving multiple tenants, consolidating caustic procurement under utility operators.
- Chemical Synthesis:Feedstock for sodium salts, plastics intermediates, and pharmaceutical precursors. South Korean petrochemical complexes at Yeosu and Ulsan specification thresholds exceed commodity benchmarks, extracting premium positioning from impurity-controlled membrane cell output.
- Water Treatment:Municipal and industrial purification systems for pH correction and heavy metal precipitation.
- Cleaning Agents:Equipment degreasing, tank cleaning, and surface preparation in food processing and transportation maintenance.
Neutralization dominates installed base. Chemical Synthesis is gaining share fastest.
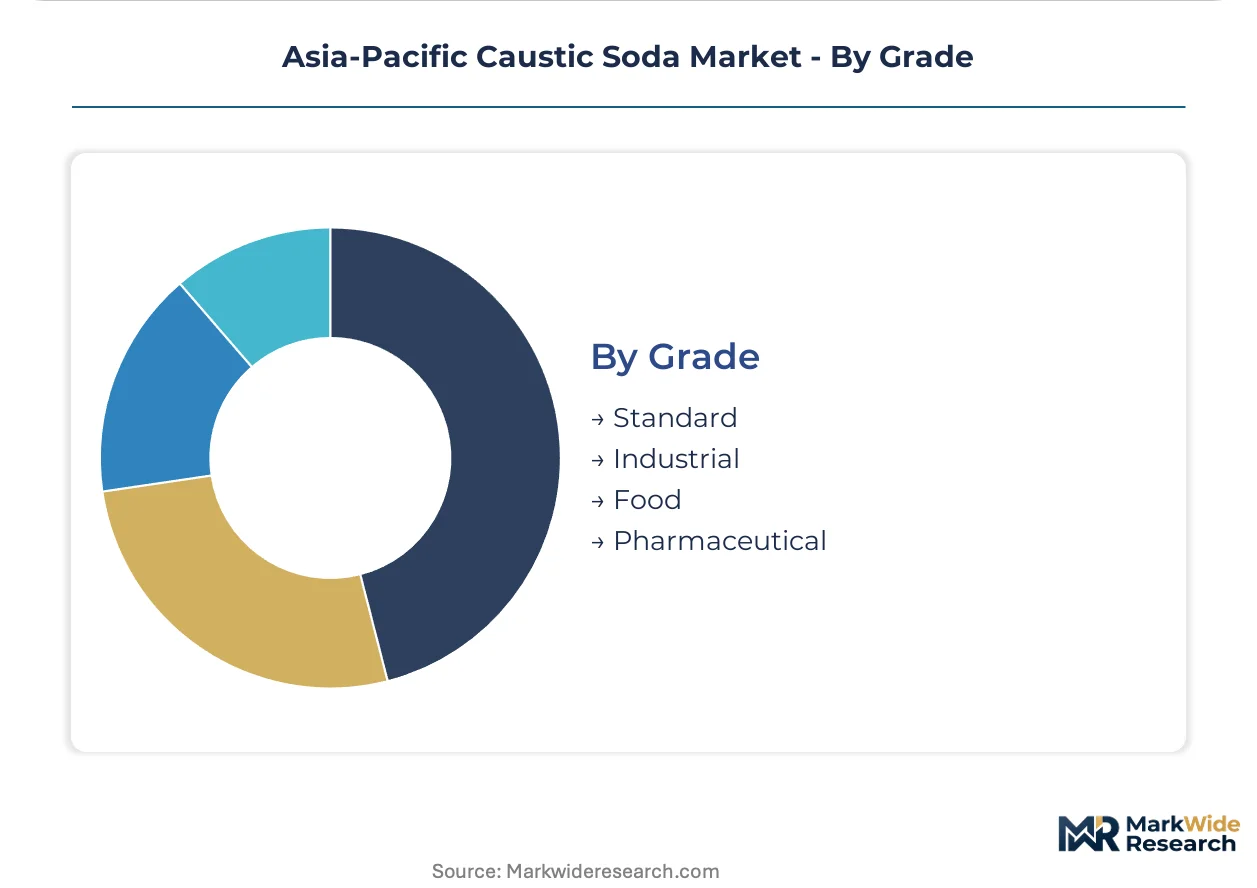
Grade:
Margin stratification separates certification tiers, with pharmaceutical and food grades extracting disproportionate returns against standard industrial specifications.
- Industrial:The baseline specification for alumina refining, pulp processing, and bulk chemical manufacturing, tolerating higher trace metal content. Membrane cell technology has elevated typical industrial grade purity beyond legacy mercury-process benchmarks, compressing differentiation against standard grades.
- Standard:Intermediate purity tier for general manufacturing applications not requiring food-contact or environmental discharge certifications. Chinese chlor-alkali producers in Shandong province concentrate standard grade output for domestic distribution through merchant chemical traders.
- Food:BIS certification in India and equivalent national standards elsewhere mandate impurity protocols for direct food contact applications. Extended laboratory validation timelines filter smaller traders from formal supply chains serving dairy processing and edible oil refining.
- Pharmaceutical:Stringent monograph compliance for active pharmaceutical ingredient synthesis and medical device sterilization, with South Korean and Taiwanese electronics chemical distributors prioritizing verified renewable power integration and ISO-certified protocols.
Industrial dominates installed base. Pharmaceutical is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia-Pacific caustic soda trade flows reveal a structural deficit in high-purity grades against surplus industrial volumes concentrated in eastern Chinese coastal provinces. Import dependency for electronics-grade material shapes procurement strategies across semiconductor corridors from Seoul to Taipei.
China
Shandong and Jiangsu provinces host the densest membrane cell capacity serving alumina refineries and chemical synthesis operations. MEE emissions intensity caps are accelerating mercury cell decommissioning while tightening supply elasticity for standard grades. The Yangtze River Delta industrial corridor clusters pipeline-connected buyers under just-in-time logistics arrangements.
India
Gujarat and Maharashtra absorb expanding volumes for textile mercerization and soap manufacturing as domestic chemical processing scales. BIS certification requirements for food-grade and water-treatment applications filter smaller traders from formal supply chains. Dahej and Mundra port zones concentrate captive brine sourcing with coastal logistics integration.
Australia
Gladstone and Kwinana alumina refineries drive caustic offtake tied to bauxite digestion for smelter-grade output serving Asian aluminum fabrication. TGA environmental discharge protocols govern neutralization applications in mining wastewater treatment. Queensland's bauxite belt expansion is lifting long-term contract volumes with regional chlor-alkali suppliers.
South Korea
Yeosu and Ulsan petrochemical complexes specification thresholds exceed commodity benchmarks for electronics-grade caustic serving semiconductor chemical channels. MFDS pharmaceutical-grade monograph compliance creates procurement filters for active ingredient synthesis operations. Seoul Capital Area distributors prioritize carbon-disclosed supply chains with verified renewable power integration.
Indonesia
Bintan Island and Sumatra pulp mills consume substantial volumes for kraft pulping and bleach sequences as plantation fiber capacity expands. The Ministry of Environment and Forestry enforces wastewater neutralization standards that consolidate caustic procurement under industrial park utility operators. Kalimantan chemical processing zones represent underpenetrated demand for reliable liquid caustic supply.
Asia-Pacific Caustic Soda Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with narrower scope but sharper purity positioning. The Asia-Pacific chlor-alkali sector exhibits tiered concentration where coastal membrane cell operators with captive power and brine sourcing sustain cost leadership against inland merchant producers. Three archetypes dominate: integrated chemical conglomerates with backward power generation, high-purity specialists serving electronics channels, and regional volume players anchored to alumina and pulp offtake contracts. Competitive moves center on membrane retrofit completion timelines and renewable power purchase agreement negotiations that gate access to carbon-disclosed customer segments.
Within the integrated conglomerate tier, Tata Chemicals Ltd and Grasim Industries Limited exemplify scale-driven positioning through captive resource control and coastal logistics infrastructure. Shin-Etsu Chemical Co., Ltd. occupies the high-purity specialist position where semiconductor-grade specification thresholds extract premium returns from impurity-controlled membrane cell output. These three anchors illustrate how technology vintage and power sourcing strategy are redistributing competitive advantage across the region's production base.
| Leading Market Players |
|---|
| Tata Chemicals Ltd |
| Hanwha Solutions |
| Aditya Birla |
| Grasim Industries Limited |
| Shin-Etsu Chemical Co., Ltd. |
| DCM Shriram |
| Tosoh Corporation |
| AGC Chemicals |
| Gujarat Alkalies and Chemicals Ltd |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Shandong and Jiangsu membrane cell clusters determines both pricing tier spreads and supply chain shape across Asia-Pacific caustic soda markets. MEE emissions enforcement and coastal grid constraints amplify volatility, compressing margins for non-integrated producers while rewarding renewable-powered coastal operators with pricing power in premium grades.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across alumina and pulp channels, with pharmaceutical and electronics-grade specifications commanding substantial premiums over industrial baselines. Price differentiation rests on membrane cell provenance and renewable power verification, with carbon-disclosed supply chains extracting margin advantages from specification-driven procurement in South Korea and Taiwan. Cost compression in standard grades intensifies as Chinese mercury cell decommissioning tightens merchant supply, while food-grade BIS certification timelines filter smaller traders and sustain premium positioning for validated producers. Alumina refineries exhibit lowest price sensitivity due to captive pipeline logistics, whereas textile dyeing houses in Vietnam's emerging zones negotiate aggressively on delivered liquid caustic terms.
Supply Chain Analysis
Rock salt and thermal power feedstock dependencies tether production economics to commodity volatility across China, India, and Australia's chlor-alkali corridors. Geographic supply concentrates in Shandong and Jiangsu provinces, with Gujarat's Dahej-Mundra belt and Queensland's Gladstone corridor serving secondary sourcing roles. Single-source vulnerability intensifies around ion-exchange membrane supply, where cell room engineering talent scarcity constrains retrofit timelines and maintenance capacity. Distribution runs through pipeline-connected industrial parks in eastern China's chemical manufacturing corridor, supplemented by coastal tanker logistics for Australian alumina refineries and Indonesian pulp mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized membrane cell engineering capability gaps are redistributing competitive advantage toward producers with captive technical talent and renewable power integration, locking out undercapitalized entrants from premium grade participation.
For Market Incumbents: Insulate margin structures through backward integration into captive brine sourcing and coastal logistics infrastructure, particularly across India's Gujarat corridor and China's Jiangsu belt. Accelerate renewable power purchase agreement negotiations to meet MEE emissions intensity thresholds and secure carbon-disclosed supply chain positioning for electronics-grade channels. Prioritize membrane cell engineering talent retention against poaching from green hydrogen pilot projects that compete for electrolyzer expertise. For New Entrants and Emerging Players: Vietnam's northern industrial zones around Haiphong represent the most penetrable entry point for liquid caustic supply, with textile dyeing and paper processing operations seeking alternatives to Chinese import dependency. Kalimantan chemical processing zones offer secondary white-space opportunity as Indonesian pulp capacity expands beyond Sumatra's saturated merchant supply. Establish go-to-market positioning through flake distribution partnerships where dilution precision matters and liquid bulk infrastructure remains underdeveloped. For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors membrane cell retrofit completion and renewable power integration over legacy mercury-process capacity. Long-term viability across the projection horizon rests on carbon intensity metrics that increasingly gate access to premium customer segments in semiconductor and pharmaceutical channels. Watch for MEE enforcement acceleration and carbon border adjustment proposals as inflection indicators that would compress residual mercury-cell valuations and elevate renewable-integrated coastal assets.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Cell Retrofit Completion | MEE emissions caps in Shandong and Jiangsu provinces are decommissioning mercury-process capacity and redistributing production advantage. |
| Renewable Power Purchase Agreement | Coastal operators with verified wind and solar integration access carbon-disclosed supply chains preferred by South Korean electronics distributors. |
| Captive Brine Sourcing Integration | Backward control over salt supply insulates margin predictability against thermal coal price swings affecting non-integrated producers. |
| Pharmaceutical-Grade Certification Investment | BIS and MFDS monograph compliance creates procurement filters that sustain premium positioning against standard-grade commodity competition. |
| Pipeline-Connected Industrial Park Expansion | Eastern China's Yangtze River Delta clustering enables just-in-time logistics that reduce working capital requirements for bulk liquid delivery. |
Study Parameters
Initial hypotheses were tested against primary input from chlor-alkali plant managers, downstream procurement leads at alumina refineries, membrane cell engineering specialists, and chemical distribution channel partners, then refined through secondary validation. Bottom-up and top-down triangulation combined customs and trade data from China's General Administration of Customs, ACC and Cefic industry reports, SEC 10-K filings from listed chemical conglomerates, and MEE emissions disclosure databases. Cross-referencing merchant caustic spot pricing against long-term offtake contract terms verified segmentation assumptions across grade tiers and end-use industries.
Demand-supply-balance modeling across the analysis window integrated alumina refinery capacity expansion schedules, Indonesian pulp mill commissioning timelines, and semiconductor fabrication capacity buildouts in South Korea and Taiwan. Segmentation dimensions tracked physical form, purity grade, end-use chemistry, and regional production hub clustering. CAGRs were derived from production capacity utilization rates, bauxite processing intensity coefficients, and specification-driven procurement shift patterns. Forecast inputs incorporated renewable power penetration trajectories in coastal Chinese provinces and membrane conversion completion timelines under MEE supervision.
Practitioners should monitor MEE enforcement acceleration, carbon border adjustment proposal progress, and green hydrogen pilot project scale-up for early signals of forecast revision. Cross-checking against IEA industrial power pricing data and Chinese provincial grid curtailment statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Acetate Salt Market
Bulk Chemicals
Global Acrylate Monomers Market
Bulk Chemicals
Calcium Chloride Market
Bulk Chemicals
Global Acrolein Market
Bulk Chemicals
Caprylic Acid Market
Bulk Chemicals
Copper Sulfate Market
Bulk Chemicals
Castor Oil Derivatives Market
Bulk Chemicals
Mancozeb Market
Bulk Chemicals
Calcined Petcoke Market
Bulk Chemicals
Cobalt Acetate Crystals Market
Bulk Chemicals
United States Calcium Carbonate Market
Bulk Chemicals
Carbonate Market
Bulk Chemicals
Global Persulfates Market
Bulk Chemicals
Iodine Market
Bulk Chemicals
Hydrochloric Acid Market
Bulk Chemicals
Ethyl Mercaptan Market