
 Monodose Packs Market | 2026-2036
Monodose Packs Market Size, Share, and Industry Trends Forecast 2026-2036
Monodose Packs Market Outlook
Consolidation among hospital group purchasing organizations is repositioning procurement leverage toward large health systems that demand unit-dose compliance and traceability. Gerresheimer AG leverages its specialized glass forming expertise to dominate high-barrier vial supply for injectable biologics. Berry Global sustains manufacturing scale across plastic blister and sachet formats for retail pharmacy chains. Amcor competes through integrated film-lamination capabilities that extend shelf stability for moisture-sensitive oral solids.
Monodose packs are single-unit primary packaging formats designed to contain, protect, and dispense one measured dose of a product, typically employing multi-layer barrier films, formed aluminum, or borosilicate glass with tamper-evident closures and child-resistant features; they serve to eliminate dosing errors, reduce contamination risk, and enable adherence tracking in regulated environments. Blister packs lead volume in oral pharmaceutical applications where moisture and oxygen ingress must stay below specified thresholds, while sachets capture growth in nutraceutical powders and liquid cosmetics driven by portability demand. Glass vials and ampoules concentrate margin pools in parenteral and vaccine segments where USP Type I borosilicate and break-ring ampoule standards govern market access.
The FDA enforces unit-dose labeling and child-resistant packaging requirements under 16 CFR 1700, while the EU MDR mandates unique device identification and traceability for pharmaceutical packaging materials classified as medical device accessories. REACH and ECHA substance restrictions further constrain plasticizer and adhesive chemistries in European supply chains. Stakeholders must monitor evolving pharmacopeial standards for extractables and leachables, as regulatory divergence between FDA and EMA testing protocols continues to shape regional sourcing strategies and qualification timelines.
Market Dynamics
Hospital group purchasing organization consolidation is compressing supplier margins and mandating unit-dose traceability as a non-negotiable procurement condition across North American and European health systems.
Growth Catalysts
- EU MDR traceability mandates:Unique device identification requirements for pharmaceutical packaging accessories force manufacturers to upgrade serialization infrastructure, creating pull for integrated monodose formats.
- Biologics cold-chain expansion:mRNA vaccines and temperature-sensitive injectables demand borosilicate glass vials with validated barrier performance, accelerating specialized monodose procurement.
- Germany's pharmaceutical cluster concentration:Gerresheimer AG and Schott AG anchor specialized glass forming capacity that supplies high-barrier vial demand across European biologics manufacturing.
Market Restraints
- Aluminum and specialty polymer cost volatility:Multi-layer barrier films and formed aluminum blister substrates face input price swings that compress converter margins and destabilize long-term supply agreements.
- European supply concentration:Specialized borosilicate glass forming capacity clusters in Germany and limited alternative qualified suppliers create vulnerability to regional production disruptions.
- REACH substance restrictions:ECHA constraints on plasticizers and adhesive chemistries force European manufacturers to reformulate multi-layer laminations, extending qualification timelines.
Strategic Opportunities
- Personalized medicine dose customization:Orphan drugs and patient-specific biologics require small-batch monodose formats that large-scale converters struggle to supply profitably.
- Home healthcare self-administration:Pre-filled syringes and auto-injector compatible monodose packs open channels outside institutional pharmacy procurement.
- EU F-Gas Regulation phase-down:Refrigeration-dependent biologics packaging gains preference for passive thermal protection in monodose formats that reduce cold-chain energy intensity.
Industry Challenges
- Extractables and leachables testing divergence:FDA and EMA pharmacopeial protocol differences force manufacturers to run parallel qualification studies, doubling timeline and cost burdens.
- Serialization equipment capex intensity:Unit-level traceability mandates require line-by-line hardware upgrades that strain mid-cap converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monodose Packs Market |
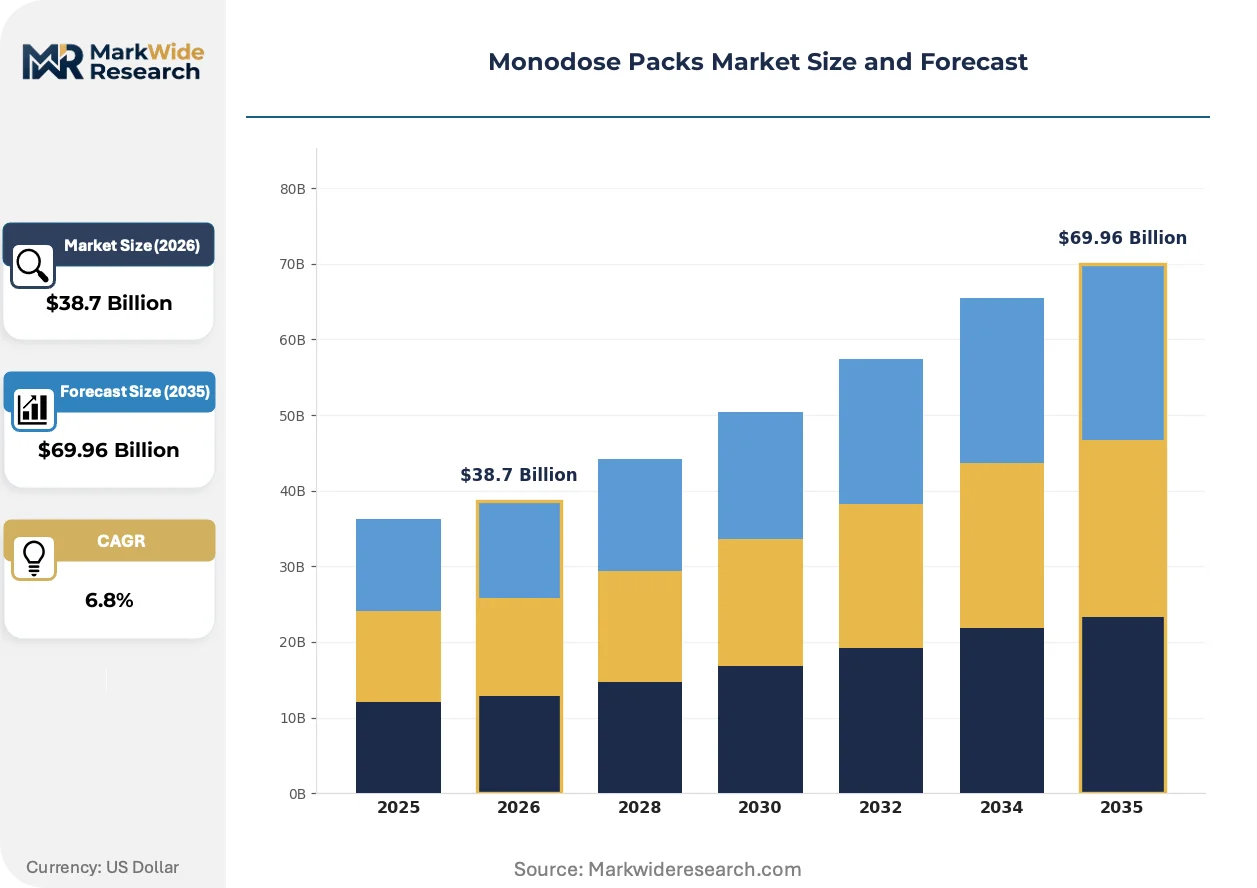
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Sachets, Vials, Ampoules Material: Plastic, Glass, Aluminum, Paperboard End User: Pharmacies, Hospitals, Clinics, Homecare Providers Application: Pharmaceuticals, Nutraceuticals, Cosmetics, Veterinary |
| Companies Covered | Gerresheimer AG, Berry Global Inc., Amcor plc, AptarGroup, Inc., Huhtamäki Oyj, Schott AG, Stevanato Group, Constantia Flexibles, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monodose Packs Market Strategic Shifts
Active barrier technologies and digital integration are compressing the functional gap between primary packaging and connected drug delivery systems.
Multi-layer co-extruded barrier films with embedded desiccant and oxygen-scavenging chemistries are rewriting shelf-life expectations for moisture-sensitive oral solids. Chronic disease pharmaceutical manufacturers are adopting these structures for tropical market distribution where conventional blister packs fail stability specifications. The technology is compressing regional formulation differences and enabling centralized manufacturing with extended distribution reach.
The EU F-Gas Regulation and its refrigerant phase-down timetable are forcing cold-chain-dependent biologics to adopt passive thermal protection in monodose formats. Vaccine distributors are qualifying insulated glass vial systems with phase-change materials that maintain temperature bands without active refrigeration. European logistics providers are restructuring hub networks to accommodate these packaging-intensive distribution models.
Hospital pharmacy buyers are consolidating vendor relationships and demanding outcome-validated packaging performance rather than component specifications. Large health systems in the United States are awarding sole-source contracts to converters who integrate serialization, child-resistance, and adherence tracking in single-platform monodose designs. This behavior is most visible in oncology and anticoagulant therapeutic categories where dosing errors carry severe liability exposure.
Monodose Packs Market Segmentation
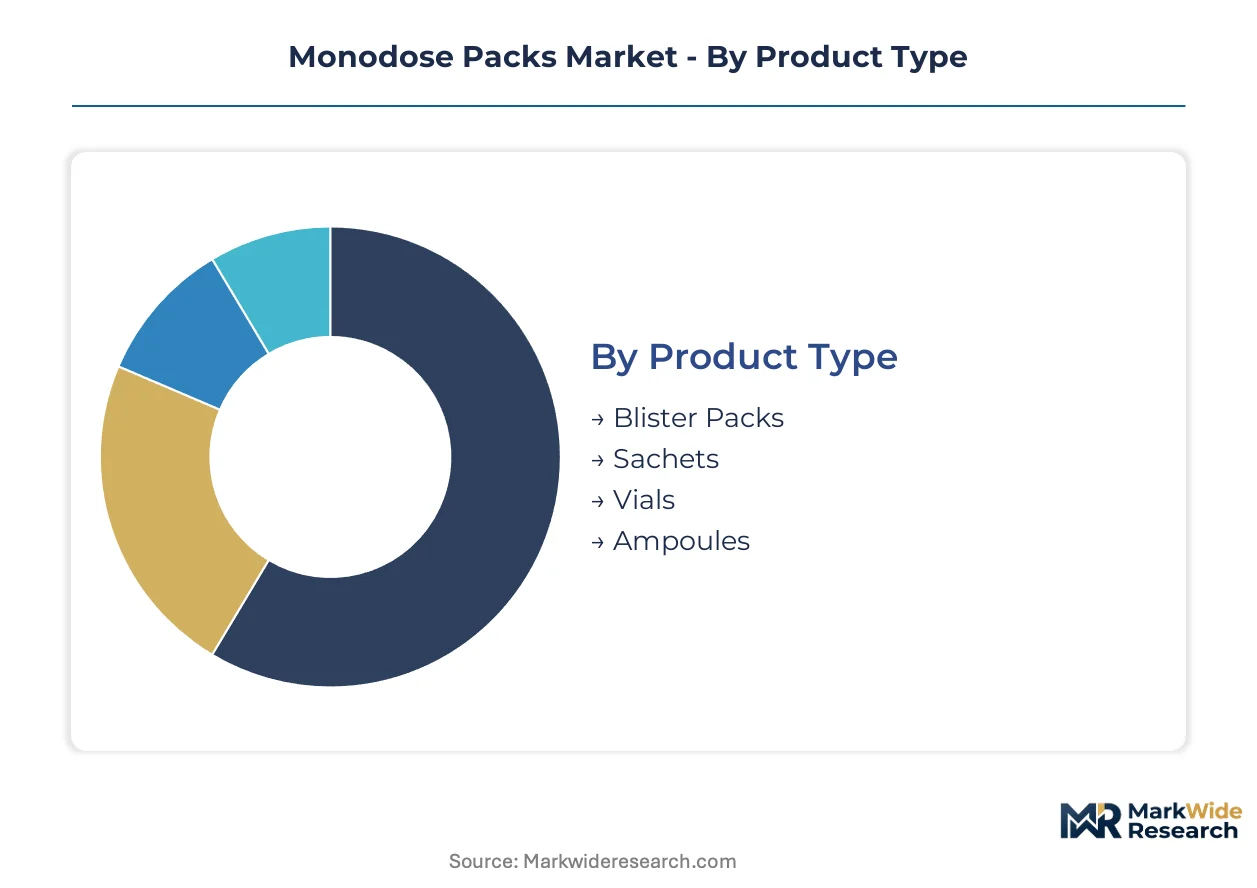
Monodose pack procurement decisions pivot on barrier performance specifications, regulatory compliance tier, and end-use handling requirements. Material selection and format geometry must align with product stability profiles and distribution channel constraints.
Product Type:
Hospital pharmacy buyers prioritize unit-dose traceability and child-resistance certification when selecting formats for high-risk therapeutic categories.
- Blister Packs:Multi-layer aluminum-PVC-PVDC laminations dominate oral solid dispensing where moisture ingress must stay below specified thresholds. North American health systems mandate these formats for anticoagulant and oncology protocols where dosing errors carry severe liability exposure.
- Vials:USP Type I borosilicate glass with validated barrier performance anchors parenteral and vaccine segments. Germany's pharmaceutical cluster concentrates specialized forming capacity that supplies temperature-sensitive biologics across European manufacturing networks.
- Sachets:Flexible film pouches capture nutraceutical powders and liquid cosmetics driven by portability demand and retail pharmacy chain procurement.
- Ampoules:Break-ring glass formats serve single-use injectable applications requiring absolute tamper evidence and minimal residual volume.
Volume sits with blister packs; growth tilts toward vials.
Material:
REACH substance restrictions and ECHA plasticizer constraints are forcing European converters to reformulate multi-layer laminations.
- Glass:Borosilicate and soda-lime compositions govern high-barrier parenteral applications. Schott AG and Gerresheimer AG anchor specialized forming capacity in Germany that supplies biologics manufacturers with validated extractables profiles.
- Plastic:Co-extruded barrier films with embedded desiccant chemistries extend shelf stability for moisture-sensitive oral solids distributed in tropical climates.
- Aluminum:Cold-formed foil substrates provide absolute moisture and oxygen barriers for hygroscopic pharmaceuticals in European supply chains.
- Paperboard:Sustainable fiber-based formats gain preference in cosmetic sampling and veterinary applications where barrier demands remain moderate.
Glass commands premium positioning; plastic sustains volume scale.
End User:
Procurement leverage is compressing supplier margins as hospital group purchasing organizations consolidate vendor relationships.
- Hospitals:Large health systems award sole-source contracts demanding integrated serialization, child-resistance, and adherence tracking in single-platform designs.
- Pharmacies:Retail chains prioritize manufacturing scale and format standardization across high-volume oral solid categories.
- Homecare Providers:Pre-filled syringe and auto-injector compatible formats open channels outside institutional procurement with distinct handling requirements.
- Clinics:Outpatient facilities favor cost-optimized blister and sachet formats for routine therapeutic administration.
Hospitals drive specification intensity; homecare channels expand most quickly.
Application:
Cold-chain expansion for temperature-sensitive biologics is reshaping format requirements across therapeutic categories.
- Pharmaceuticals:FDA unit-dose labeling and EU MDR traceability mandates force serialization infrastructure upgrades that favor integrated monodose procurement.
- Nutraceuticals:Powder and liquid formats in flexible sachets capture retail-driven portability demand with lower regulatory qualification burdens.
- Cosmetics:Single-use sampling formats prioritize aesthetic differentiation and sustainable material credentials for brand positioning.
- Veterinary:Dose-customized blister packs serve companion animal and livestock segments with modified child-resistance specifications.
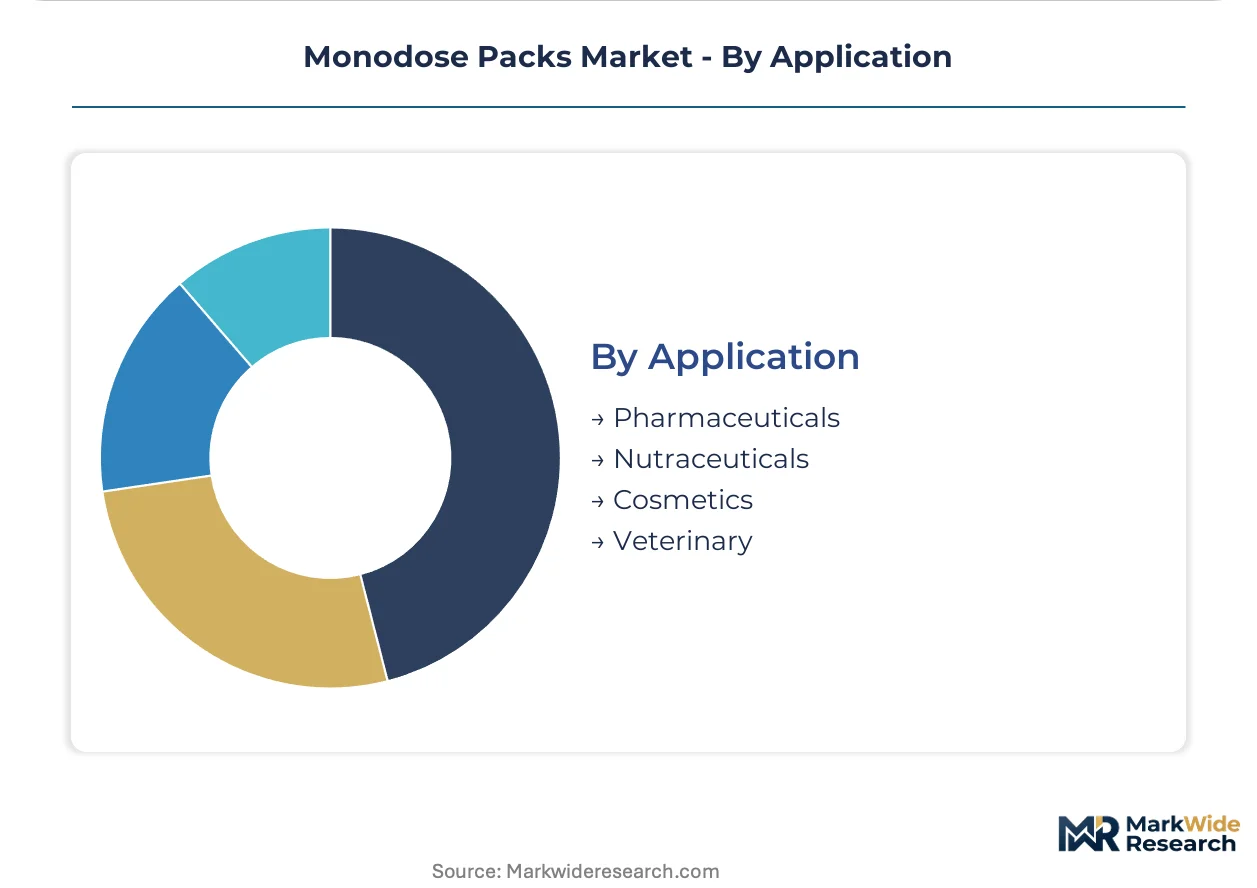
Pharmaceuticals anchor revenue concentration; nutraceuticals gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consolidation and biologics manufacturing expansion concentrate monodose pack demand in pharmaceutical clusters across Germany, the United States, and select Asian manufacturing hubs. Regulatory divergence between FDA and EMA traceability mandates shapes regional sourcing strategies. Cold-chain infrastructure investments accelerate specialized glass vial procurement in temperature-sensitive vaccine distribution networks.
Germany
Specialized borosilicate glass forming for parenteral biologics anchors demand in the Rhine-Main and Bavarian pharmaceutical corridors. The EU MDR and F-Gas Regulation force serialization upgrades and passive thermal protection adoption across supply chains. Gerresheimer AG and Schott AG concentrate high-barrier vial capacity in Mainz and Mitterteich, supplying European biologics manufacturers with validated extractables profiles.
United States
Hospital group purchasing organization consolidation mandates unit-dose traceability and child-resistant packaging for high-risk therapeutic categories. FDA enforcement of 16 CFR 1700 unit-dose labeling requirements shapes procurement specifications across health systems. The New Jersey and Massachusetts pharmaceutical clusters drive specialized procurement for oncology and anticoagulant protocols where dosing errors carry severe liability exposure.
China
Domestic biologics manufacturing expansion and NMPA serialization mandates accelerate monodose infrastructure investment. The country's national pharmaceutical regulator tightens extractables and leachables testing protocols for imported packaging materials. The Yangtze River Delta pharmaceutical corridor concentrates contract manufacturing demand for both domestic distribution and export qualification.
India
Contract research and manufacturing organization growth drives procurement of cost-optimized blister and sachet formats for export markets. CDSCO alignment with ICH traceability standards forces serialization equipment upgrades across domestic converters. The Gujarat and Maharashtra pharmaceutical clusters specialize in high-volume oral solid packaging for regulated European and North American export channels.
Switzerland
Specialized biologics and orphan drug manufacturing sustains premium-tier demand for small-batch monodose customization. Swissmedic pharmacopeial standards for parenteral packaging materials exceed baseline EU requirements, extending qualification timelines. The Basel biopharmaceutical corridor concentrates demand for high-barrier vial systems serving temperature-sensitive injectable portfolios.
Monodose Packs Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue active barrier technologies and digital integration adjacent spaces. The supplier base stratifies across three maturity tiers: integrated multinational converters with film-lamination and glass forming capabilities, mid-cap specialists in serialization-enabled formats, and regional fabricators serving cost-sensitive generic pharmaceutical markets. Two dominant competitive moves define current positioning: backward integration into specialized polymer and glass raw material supply, and strategic partnerships with cold-chain logistics providers to validate passive thermal protection performance.
Among Germany-based specialists, Gerresheimer AG and Schott AG exemplify the high-barrier glass archetype, anchoring European parenteral packaging supply through validated borosilicate forming expertise. Berry Global Inc. occupies a position within the scale-driven plastic converter tier, sustaining manufacturing breadth across blister and sachet formats. These three entities represent distinct competitive vectors: specialized material science, integrated film technology, and volume manufacturing scale.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Berry Global Inc. |
| Amcor plc |
| AptarGroup, Inc. |
| Huhtamäki Oyj |
| Schott AG |
| Stevanato Group |
| Constantia Flexibles |
| ProAmpac |
| Others |
Value Chain & Pricing Dynamics
Specialized borosilicate glass forming technicians in the Rhine-Main corridor command wage premiums that compress converter margins at the standard tier while sustaining premium pricing for USP Type I validated vial supply. Labor-cost differentials between German high-barrier specialists and Asian contract manufacturers drive three-tier spreads across blister, sachet, and parenteral formats.
Pricing Analysis
Volume concentrates in plastic blister and sachet formats where Berry Global and Amcor compete on manufacturing scale; margins pool in borosilicate glass vials where Gerresheimer and Schott extract premiums for validated extractables profiles. Price differentiation hinges on certification tier—EU MDR traceability compliance and USP Type I pharmacopeial standards—and geographic delivery cost to pharmaceutical clusters. Pricing pressure stems from aluminum and specialty polymer input volatility that destabilizes long-term supply agreements. Retail pharmacy chains exhibit highest price sensitivity; biologics manufacturers show lowest sensitivity due to qualification switching costs.
Supply Chain Analysis
Pharmacopeial qualification gating restricts qualified borosilicate glass forming to Germany, with secondary capacity in China and India serving cost-optimized oral solid segments. Supply chains draw from aluminum cold-forming substrates, multi-layer co-extruded barrier films, and borosilicate raw material feedstock. Single-source vulnerability concentrates in German high-barrier vial capacity where alternative qualified suppliers remain limited. Distribution runs through hospital group purchasing organizations in North America, pharmaceutical wholesalers in Europe, and contract manufacturing networks in Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained specialized glass forming capacity in Germany props pricing power for validated parenteral formats, creating durable margin pools for incumbents with pharmacopeial certification assets.
For Market Incumbents: Acquire serialization-enabled production lines to meet EU MDR traceability mandates and US FDA unit-dose labeling requirements. Backward integration into captive borosilicate raw material supply hedges against German capacity concentration risk. Certification investment in dual pharmacopeial qualification—FDA and EMA extractables protocols—defends against emerging Asian converters with lower labor costs. For New Entrants and Emerging Players: Launch via direct-to-biotech-manufacturer sales models targeting orphan drug and personalized medicine dose customization where large-scale converters struggle with small-batch profitability. White-space targets include pre-filled syringe compatible monodose formats for home healthcare self-administration and passive thermal protection systems for EU F-Gas Regulation compliance. The most penetrable segment sits in mid-tier plastic blister for generic oral solids where hospital GPO consolidation has not yet mandated sole-source contracts. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap serialization specialists given EU MDR infrastructure upgrade pull and hospital pharmacy digitization mandates. Long-term viability favors converters with integrated film-lamination and glass forming capabilities spanning both high-volume oral solids and premium parenteral biologics. The signal to watch is CDSCO alignment with ICH traceability standards in India, which would trigger qualification-driven M&A demand for serialization-capable assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Raw Material Supply | Captive feedstock secures German glass forming capacity against regional supply disruptions and ECHA substance restrictions. |
| Serialization Infrastructure Upgrade | Line-by-line hardware deployment satisfies EU MDR unique device identification mandates for pharmaceutical packaging accessories. |
| Dual Pharmacopeial Qualification Investment | Parallel FDA and EMA extractables testing protocols reduce timeline duplication for biologics manufacturers with transatlantic portfolios. |
| Passive Thermal Protection Development | Phase-change material integration addresses EU F-Gas Regulation refrigerant phase-down for cold-chain dependent vaccine distribution. |
| Small-Batch Dose Customization Capability | Flexible forming lines capture orphan drug and personalized medicine procurement outside large-scale converter minimum order quantities. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with pharmaceutical packaging procurement managers, regulatory affairs leads at converters, hospital GPO contract specialists, and biologics manufacturing supply chain directors combined with secondary validation from FDA 510(k) filings, EMA medical device accessory registrations, and EU customs trade databases. Bottom-up capacity modeling and top-down pharmaceutical production forecasts were triangulated to derive volume estimates.
Granularity-level modeling operated at product type, material composition, end-user channel, and application dimensions across the analysis window. Segmentation by therapeutic category—oncology, anticoagulant, vaccine, and orphan drug—captured differential barrier specification intensity. CAGRs were derived from regression analysis of historical pharmaceutical packaging procurement trends and projected biologics cold-chain expansion. Industry-specific forecast inputs included EU MDR implementation timelines and NMPA serialization mandate phase-in schedules.
Raw material cost volatility, regulatory protocol divergence between FDA and EMA, and hospital GPO consolidation pace are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in pharmacopeial extractables testing standards or EU F-Gas Regulation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
United States Retort Pouches Market
Pouch
Global Pouches Packaging Market
Pouch
Flexible Pouch Market
Pouch
North America Lithium-Ion Battery Pouch Film Market
Pouch
Foil Pouch Packaging Market
Pouch
North America Stand-Up Pouch Packaging Market
Pouch
Global Boil-In Bags Market
Pouch
Pre-Made Pouch Packaging Market
Pouch
Retort Pouch Packaging Market
Pouch
Aluminum-Free Food Pouch Market
Pouch
Foil Zipper Bags Market
Pouch
Liquid Pouch Packaging Market
Pouch
Slider Pouches Market
Pouch
2 Seal Pouches Market
Pouch
Ziplock Products Market
Pouch
MAP Flow Wrappers Market