
 Trinitrotoluene (TNT) Market | 2026-2036
Trinitrotoluene (TNT) Market Size, Share, and Industry Trends Forecast 2026-2036
Trinitrotoluene (TNT) Market Analytics
The gap between military-grade and industrial-grade specifications is realigning procurement strategies across the TNT value chain. Hanwha Group leverages its integrated defense-chemicals platform to sustain captive supply for South Korean military contracts. Orica Limited anchors its position through blasting-system bundling that extends beyond commodity explosives into drill-and-blast services.
Trinitrotoluene is a nitroaromatic explosive compound synthesized through sequential nitration of toluene, yielding a crystalline solid with a detonation velocity of approximately 6,900 meters per second and primary use as a booster explosive and shell filling in military and commercial blasting applications. Military Grade formulations dominate value pools given stringent purity and stability requirements, while Industrial Grade output competes on volume in mining and quarrying operations. Powder and solid forms occupy distinct logistics channels, with emulsion-based delivery systems gaining traction in controlled demolition applications where handling safety governs specification selection.
EPA oversight of precursor chemicals under the Safe Explosives Act, EU REACH registration requirements for nitroaromatic substances, and India's Explosives Act administered by the Petroleum and Explosives Safety Organisation collectively constrain capacity expansion and shape cross-border trade patterns. Stakeholders must monitor how fragmentation between national stockpiling directives and commercial mining demand reshapes contract structures and inventory obligations.
Market Dynamics
Defense procurement cycles are compressing as NATO member states accelerate ammunition stockpile replenishment, forcing TNT manufacturers to choose between military-grade purity investments and industrial-grade volume commitments.
Growth Catalysts
- Munitions stockpiling directives:NATO defense ministries are mandating minimum explosive reserves, pulling forward multi-year procurement schedules for shell-fill formulations.
- REACH registration completion:ECHA's streamlined nitroaromatic substance approvals are reducing compliance timelines for EU-based chemical processors seeking military contracts.
- India:Domestic ordnance factory modernization and Solar Industries' capacity expansions are redirecting regional supply chains away from import dependence.
Market Restraints
- Toluene price volatility:Petrochemical feedstock fluctuations compress blending margins for industrial-grade output destined for quarrying operations.
- Supply concentration:Three integrated defense-chemicals groups control the majority of military-grade purification capacity, creating bottleneck risk during surge demand.
- Substitution threat:RDX and HMX formulations are displacing TNT in next-generation shaped charge designs where higher brisance governs specification selection.
Strategic Opportunities
- Demolition robotics integration:Autonomous drilling and emulsion-charging systems are opening precision-controlled blasting contracts in urban infrastructure removal.
- US Safe Explosives Act modernization:Proposed ATF precursor tracking reforms could advantage domestic manufacturers with established compliance infrastructure.
- Emulsion-based delivery:Pumpable TNT-analog formulations are penetrating tunneling operations where manual cartridge handling faces safety restrictions.
Industry Challenges
- Nitration chemistry expertise:The specialized workforce capable of managing exothermic reaction control and waste acid recovery is aging without sufficient pipeline replacement.
- Military certification timelines:NATO STANAG and MIL-STD qualification protocols for new production batches extend 18-24 months, freezing formulation innovation.
- Legacy inventory integration:Cold-war era TNT stockpiles require reprocessing to meet current stability specifications, straining existing reclamation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trinitrotoluene (TNT) Market |
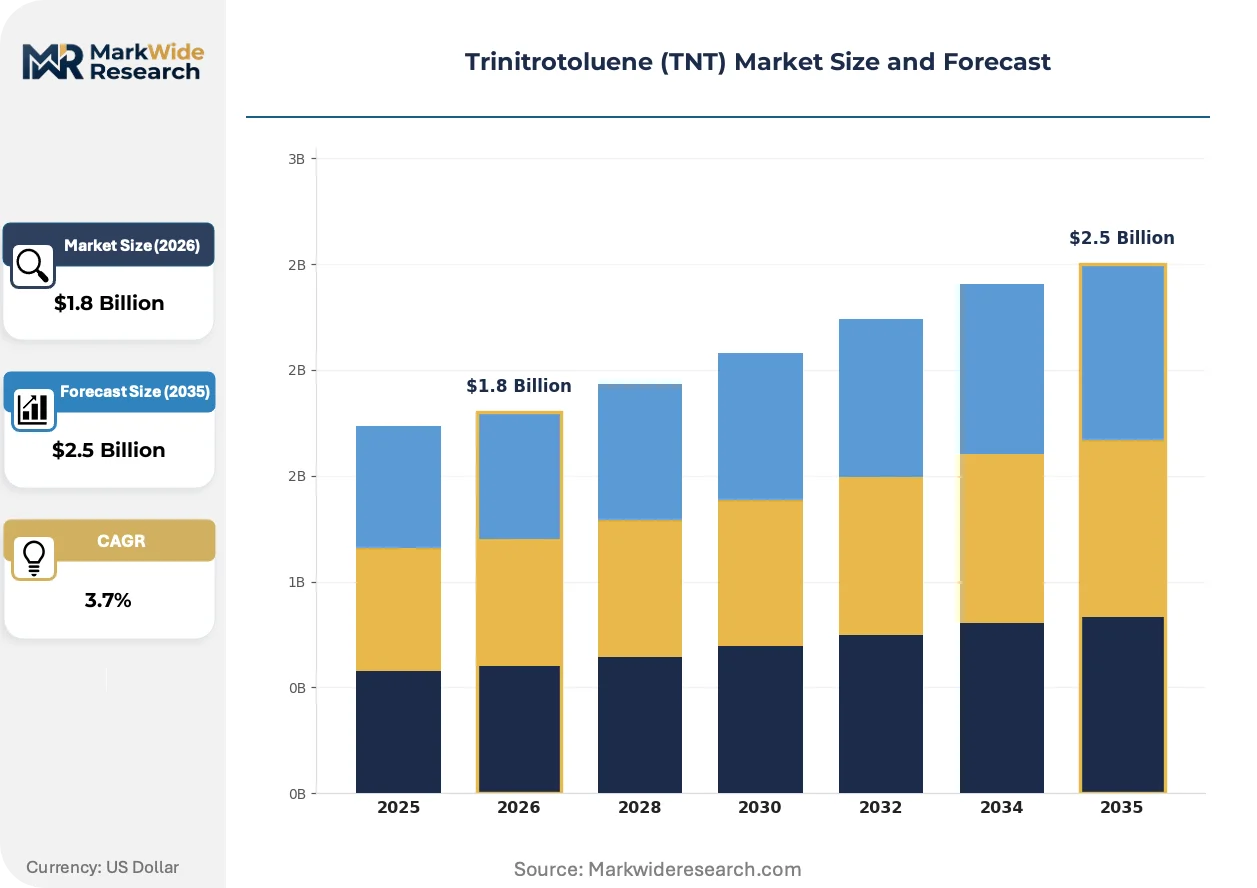
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Explosives, Military Grade, Industrial Grade, Commercial Grade Application: Construction, Mining, Demolition, Military Form: Solid, Solution, Emulsion, Powder End User: Defense Contractors, Construction Companies, Mining Firms, Demolition Experts |
| Companies Covered | Hanwha Group, NITRO-CHEM SA, Orica Limited, Enaex, China Gezhouba Group Corporation, Dyno Nobel, Austin Powder, Solar Industries India Limited, MAXAMCORP HOLDING SL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trinitrotoluene (TNT) Market Evolving Landscape
Sequential nitration process intensification and emulsion delivery system maturation are redrawing the boundary between military and commercial explosive applications.
Microreactor continuous-flow nitration technology is decentralizing production economics for TNT synthesis. South Korean and German chemical engineering firms are retrofitting pilot plants with modular reaction units that reduce hold-up volumes and thermal runaway risk. This architecture is enabling smaller-batch military-grade output without the capital intensity of traditional stirred-tank trains, compressing minimum efficient scale thresholds for national stockpile suppliers.
EU REACH authorization requirements for nitroaromatic substances are tightening substance dossier obligations across the value chain. ECHA's 2024 updated guidance on explosive precursor registration is forcing non-EU exporters to establish EU-based only representatives or forfeit military contract eligibility. German and French defense chemical processors are consolidating their regulatory submission functions to capture this compliance-driven supplier reduction.
Buyer consolidation among tier-one mining contractors is compressing explosives procurement into integrated drill-and-blast service agreements. Australian and Canadian iron ore operators are bundling emulsion supply with blast design and fragmentation analysis, marginalizing commodity-only TNT merchants. This unbundling reversal favors chemical producers with in-house blasting engineering capabilities over pure manufacturers.
Trinitrotoluene (TNT) Market Segmentation
TNT procurement divides sharply between military purity mandates and industrial volume economics. Each segmentation axis reveals distinct margin structures, certification barriers, and logistics requirements that reshape supplier positioning.
Product Type:
Supply concentration among integrated defense-chemicals groups creates divergent competitive dynamics across purity tiers.
- Military Grade:Formulations meeting NATO STANAG and MIL-STD specifications for thermal stability and impurity thresholds. Demand concentrates in NATO member state defense ministries replenishing shell-fill inventories under accelerated procurement directives. EPA and EU REACH precursor tracking requirements extend qualification timelines.
- Industrial Grade:Standardized crystalline output for quarrying and bulk earthmoving where detonation velocity tolerance is wider. Mining contractors in Australia and Canada bundle procurement into drill-and-blast service agreements, compressing standalone chemical margins.
- Explosives:Blended formulations incorporating TNT as a booster component within composite explosive systems. Demolition robotics integration is opening precision-controlled urban blasting contracts.
- Commercial Grade:Lower-specification output for non-critical civil engineering applications. Toluene feedstock volatility directly squeezes blending economics.
Today's leader: Military Grade. Tomorrow's challenger: Emulsion-based delivery systems.
Application:
End-use fragmentation between stockpiling mandates and cyclic mining investment governs contract duration and pricing power.
- Military:Shell filling, booster charges, and ammunition core loads requiring 18-24 month NATO certification cycles. Procurement compression under NATO explosive reserve directives is pulling forward multi-year schedules.
- Mining:Iron ore and copper extraction in Australian Pilbara and Canadian Shield operations. Tier-one contractors are unbundling commodity supply from blast engineering services.
- Demolition:Controlled structural removal in urban corridors where handling safety restrictions favor pumpable emulsion formulations.
- Construction:Tunneling and infrastructure earthworks facing stricter OSHA and national explosives handling protocols.
Military applications command price premiums through certification scarcity. Mining volumes scale fastest where commodity bundling reverses.
Form:
Physical state determines logistics infrastructure requirements and labor safety exposure across the value chain.
- Emulsion:Pumpable slurry formulations reducing manual cartridge handling in confined tunneling operations. South Korean and German chemical engineering firms are deploying microreactor continuous-flow production architecture.
- Solid:Cast or pressed blocks for military shell filling with established NATO supply chain protocols. Legacy cold-war inventories require reprocessing to meet current stability specifications.
- Powder:Granular output for industrial blasting where bulk density governs loading efficiency.
- Solution:Liquid-phase precursors and intermediate processing states managed within integrated chemical complexes.
Solid forms dominate military certification pathways. Emulsion delivery is climbing the fastest through demolition robotics integration.
End User:
Customer concentration among state buyers versus fragmented private contractors creates divergent contract structures and payment terms.
- Defense Contractors:Lockheed Martin, Rheinmetall, and Hanwha Aerospace managing NATO ammunition production. Multi-year framework agreements with cost-plus pricing and stringent traceability requirements.
- Mining Firms:BHP, Rio Tinto, and Vale integrating explosives procurement into operational efficiency contracts. Volume commitments fluctuate with commodity price cycles.
- Construction Companies:Skanska, Bechtel, and Vinci procurement teams balancing safety compliance with project schedule pressure.
- Demolition Experts:Specialized contractors in European and North American urban markets adopting autonomous drilling and emulsion-charging systems.
Defense contractors anchor value capture through certification barriers. Mining firms represent the steepest expansion trajectory where service bundling reverses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized nitration chemists and explosives safety engineers concentrate in defense-industrial clusters across five countries, anchoring global TNT production capacity and military certification expertise.
United States
Department of Defense ammunition stockpiling directives and Army Materiel Command procurement schedules drive demand from Radford Army Ammunition Plant and Holston Army Ammunition Plant in Tennessee and Virginia. EPA oversight under the Safe Explosives Act constrains precursor chemical handling and cross-state transport logistics. The Tennessee Valley corridor hosts the densest concentration of military-grade purification and blending operations.
Germany
Bundeswehr munitions replenishment programs and Rheinmetall ammunition production contracts sustain demand from state-owned and private defense chemical processors. EU REACH authorization requirements for nitroaromatic substances administered by ECHA extend registration timelines for military-grade formulations. The Chemiepark Bitterfeld-Wolfen complex in Saxony-Anhalt anchors nitroaromatic synthesis capacity serving NATO supply chains.
India
Ordnance Factory Board modernization and Solar Industries India Limited capacity expansions redirect regional supply chains away from import dependence. The Petroleum and Explosives Safety Organisation enforces India's Explosives Act compliance for domestic manufacturing licensing. Maharashtra and Telangana host the fastest-scaling production complexes, with Nagpur and Hyderabad emerging as ordnance manufacturing hubs.
South Korea
Hanwha Aerospace ammunition contracts and Defense Acquisition Program Administration procurement schedules sustain captive supply from integrated defense-chemicals platforms. The country's national explosives regulator coordinates military-grade certification with NATO STANAG alignment requirements. The Daejeon-Sejong corridor concentrates microreactor continuous-flow pilot plants for decentralized military-grade batch production.
Australia
BHP and Rio Tinto drill-and-blast service agreements bundle industrial-grade explosives procurement with operational efficiency contracts. WorkSafe Australia and state-level explosives handling regulations govern quarrying and mining applications. The Pilbara region in Western Australia anchors iron ore extraction demand, with Gladstone in Queensland serving coastal coal and metallurgical operations.
Trinitrotoluene (TNT) Market Competitive Landscape
Top-tier vendors anchor military-grade purification capacity, while mid-scale specialists compete on industrial-grade volume and emulsion delivery system integration. Three integrated defense-chemicals groups control the majority of NATO-certified production, creating bottleneck risk during surge demand cycles. Strategic archetypes include captive defense suppliers with in-house nitration trains, mining service bundlers with blast engineering capabilities, and regional ordnance specialists with government contract lock-in. Dominant competitive moves center on capacity expansion for national stockpile security and strategic partnerships for demolition robotics integration.
Among Asia-Pacific-based integrated conglomerates, Hanwha Group exemplifies the captive defense supplier archetype through its chemicals-to-aerospace platform. Solar Industries India Limited represents the regional ordnance specialist model with state-backed contract structures. Orica Limited anchors the mining service bundler position, extending beyond commodity explosives into integrated drill-and-blast operations.
| Leading Market Players |
|---|
| Hanwha Group |
| NITRO-CHEM SA |
| Orica Limited |
| Enaex |
| China Gezhouba Group Corporation |
| Dyno Nobel |
| Austin Powder |
| Solar Industries India Limited |
| MAXAMCORP HOLDING SL |
| Others |
Value Network & Pricing Analysis
Microreactor continuous-flow nitration technology is compressing minimum efficient scale thresholds while simultaneously fragmenting production economics and redrawing supplier concentration maps across military-grade and industrial-grade tiers. This dual shift feeds directly into how contract structures allocate pricing power between integrated defense-chemicals platforms and specialized batch processors.
Pricing Analysis
Bundled drill-and-blast service agreements versus unbundled commodity supply defines the dominant pricing split across TNT procurement. Three-tier pricing structure across premium, standard, and economy levels separates NATO-certified military formulations from industrial quarrying grades and lower-specification civil engineering output. Price differentiation rests on certification scarcity and volume scale, with military-grade purity commanding substantial premiums through 18-24 month STANAG qualification timelines. Cost compression in industrial-grade output is intensifying because mining contractors are consolidating procurement into operational efficiency contracts with embedded explosives supply. Construction and demolition segments exhibit the sharpest price sensitivity, while defense ministries remain least sensitive given national stockpile security mandates.
Supply Chain Analysis
Freight cost exposure for hazardous materials shapes facility siting decisions and regional supply radius economics across the TNT value chain. Production gravity centers on the United States, Germany, and India, with South Korea and Australia anchoring specialized capacity clusters. Toluene feedstock, concentrated sulfuric acid, and nitric acid constitute the critical input trio, with petrochemical volatility transmitting directly into blending margin pressure. Single-source vulnerability concentrates in military-grade purification capacity, where three integrated defense-chemicals groups control NATO-certified output. Distribution runs through defense ministry procurement frameworks for military applications and tier-one mining contractor logistics networks for industrial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
TNT procurement has shifted toward premium military-grade specifications as NATO ammunition stockpiling directives compress multi-year schedules, elevating late-cycle quality considerations above volume scale economics.
For Market Incumbents: To counter RDX and HMX substitution in next-generation shaped charge designs, Hanwha Group and Solar Industries should deepen captive nitration train investments in South Korea and Maharashtra respectively. Backward integration into toluene sourcing and waste acid recovery infrastructure protects blending margins against feedstock volatility while extending certification barrier durability. For New Entrants and Emerging Players: EU REACH authorization streamlining for nitroaromatic substances opens a window for specialized batch processors to capture compliance-driven supplier reduction benefits in German and French defense chemical markets. Emulsion-based delivery systems for tunneling and demolition robotics integration represent the most penetrable white-space target, with autonomous drilling partnerships offering the clearest go-to-market angle against established cartridge handlers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional ordnance specialists with state-backed contract lock-in and aging nitration chemistry workforces nearing replacement inflection. Long-term viability over the coming decade hinges on microreactor technology deployment and demolition robotics integration capabilities. Watch for NATO STANAG qualification timeline compression as the signal indicating accelerated procurement velocity and pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Microreactor Capacity Deployment | South Korean and German engineering firms reduce thermal runaway risk while enabling smaller-batch military output. |
| Backward Integration into Toluene Sourcing | Integrated defense-chemicals platforms hedge petrochemical feedstock volatility compressing industrial-grade margins. |
| Demolition Robotics Partnership | Emulsion-charging system integration opens precision-controlled urban blasting contracts beyond commodity explosives. |
| NATO STANAG Certification Investment | Extended qualification timelines create scarcity premiums for approved military-grade purification capacity. |
| Waste Acid Recovery Infrastructure | Specialized nitration chemistry expertise preservation depends on environmental compliance and cost structure control. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with defense procurement officers, explosives plant managers, mining contractor procurement leads, and nitration chemistry specialists with secondary validation. Customs and trade data, ACC and Cefic chemical industry reports, SEC 10-K filings from listed defense contractors, and national explosives safety regulator disclosures formed the core secondary source base. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic and defense spending frameworks.
Historical reference periods anchored volume and value projections across the modeling period, with segmentation dimensions including grade tier, end-use application, physical form, and regional production hub. CAGRs derived from fitted growth curves incorporating defense procurement cycle compression, mining investment cyclicality, and regulatory timeline evolution. Industry-specific forecast inputs encompassed NATO ammunition stockpiling directives, EU REACH authorization progress, and India ordnance factory modernization schedules.
Revisions become necessary when defense procurement acceleration stalls, REACH authorization timelines extend unexpectedly, or RDX substitution penetrates shaped charge applications faster than modeled. Forecasts reflect documented assumptions about regulatory compliance trajectories and national security spending continuity. Stakeholders should weight assumptions against their own operating context and contract exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Dipropylene Glycol (DPG) Market
Industrial Chemicals
Nitrous Oxide Market
Industrial Chemicals
Ferrocene Market
Industrial Chemicals
Caustic Calcined Magnesia Market
Industrial Chemicals
Global Biochemical Market
Industrial Chemicals
Enzymes for Laundry Detergent Market
Industrial Chemicals
Acetylene Market
Industrial Chemicals
Gypsum-Based Products Market
Industrial Chemicals
Global Chemical Mechanical Planarization Market
Industrial Chemicals
Honing Oil Market
Industrial Chemicals
Global Lignosulfonate Based Concrete Admixtures Market
Industrial Chemicals
Nonylphenol Ethoxylate Market
Industrial Chemicals
Heat Transfer Fluids Market
Industrial Chemicals
Lithium Hexafluorophosphate Market
Industrial Chemicals
Bio Derived Enzymes for Detergents Market
Industrial Chemicals
Modified Bitumen Market