
 Wire-To-Board Connector Market | 2026-2036
Wire-To-Board Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Wire-To-Board Connector Market Insights
Surface mount technology is tilting assembly economics toward higher-density board designs that demand precision mating interfaces. TE Connectivity leverages captive tooling capabilities across Asia and Europe to sustain delivery reliability for automotive tier-ones. Molex anchors its position through R&D intensity in micro-pitch formats that serve smartphone and wearable OEMs. Amphenol ICC competes on harsh-environment specifications that differentiate its product line in industrial automation deployments.
A wire-to-board connector establishes electrical continuity between discrete wire conductors and printed circuit board traces through soldered or press-fit termination interfaces, typically rated for current loads from milliamps to tens of amps depending on contact alloy and plating thickness. Its primary commercial purpose is to replace hand-soldered wire harnesses with standardized, repeatable interconnection systems that cut assembly labor and improve signal integrity. Pin header connectors occupy the mature volume tier where margin pools have compressed to single-digit percentages, while insulation displacement connectors represent the fastest-growing technology segment as appliance and HVAC manufacturers adopt tool-less termination for field serviceability. Socket connectors concentrate margin in medical and test equipment applications where mating cycle durability commands premium pricing.
The US FCC governs electromagnetic emissions from connector assemblies in telecommunications gear, forcing shielded designs for 5G infrastructure deployments. The EU RoHS directive and REACH framework restrict cadmium and lead content in contact platings, compelling migration to tin-bismuth and palladium-nickel finishes across export-bound production lines. China's GB standards and MIIT certification requirements shape domestic procurement specifications that foreign suppliers must meet for market access. Stakeholders must monitor evolving halogen-free material mandates and contactless test standards that will determine qualification timelines for next-generation interconnect portfolios.
Market Dynamics
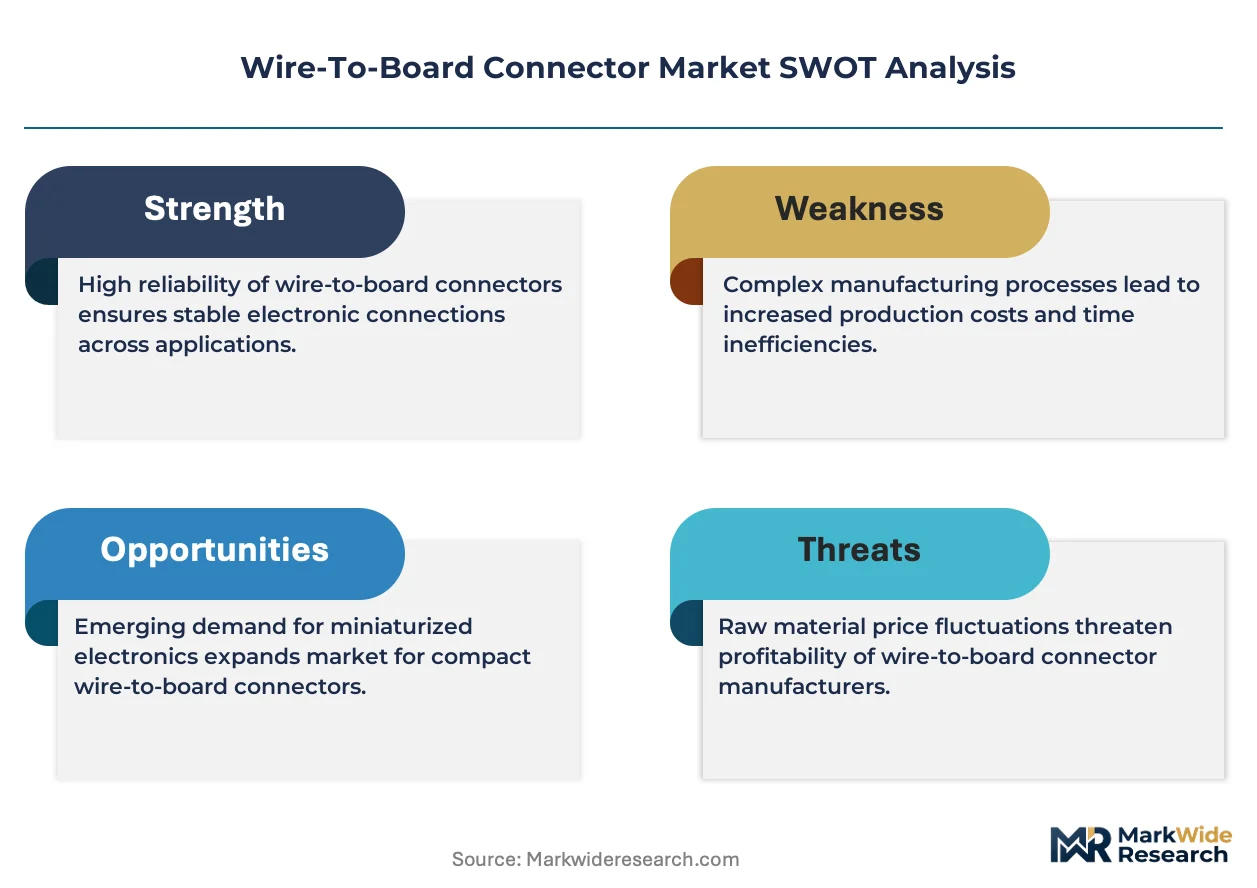
Automotive electrification is restructuring procurement priorities as OEMs migrate from 12V to 800V architectures, forcing connector suppliers to requalify product lines for high-voltage isolation and thermal cycling durability.
Growth Catalysts
- EU RoHS and REACH frameworks:Restrictions on cadmium and lead in contact platings are accelerating migration to palladium-nickel and tin-bismuth finishes, creating upgrade cycles across export-bound production lines.
- Insulation displacement termination:Appliance and HVAC manufacturers are adopting tool-less connection methods to reduce field service labor and improve technician safety during maintenance operations.
- China's MIIT certification requirements:Domestic procurement specifications for GB-standard compliance are compelling foreign suppliers to establish local testing partnerships for market access.
Market Restraints
- Copper and palladium price volatility:Contact material costs represent 35-45% of bill-of-materials for precision connectors, compressing margins when commodity markets spike.
- Asian tooling concentration:Captive mold-making capabilities cluster in Guangdong and Zhejiang provinces, creating single-source dependencies for complex housing geometries.
- High-voltage clearance limitations:Miniaturization trends in consumer electronics conflict with creepage distance requirements for automotive applications below 2.0mm pitch.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives for mobile phone and component assembly are attracting connector investments to Noida and Sri City industrial corridors.
- Medical device mating cycle specifications:Test equipment and diagnostic instrument OEMs demand 10,000+ insertion durability, commanding premium pricing for gold-plated contact systems.
- 5G infrastructure shielding mandates:FCC electromagnetic emission rules for telecommunications gear are forcing architectural redesigns that favor integrated connector-filter assemblies.
Industry Challenges
- High-voltage safety certification timelines:UL and IEC qualification protocols for 800V automotive applications extend development cycles by 18-24 months.
- Legacy harness integration friction:Industrial automation retrofits require mechanical adapters to bridge incompatible termination interfaces between old and new connector generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wire-To-Board Connector Market |
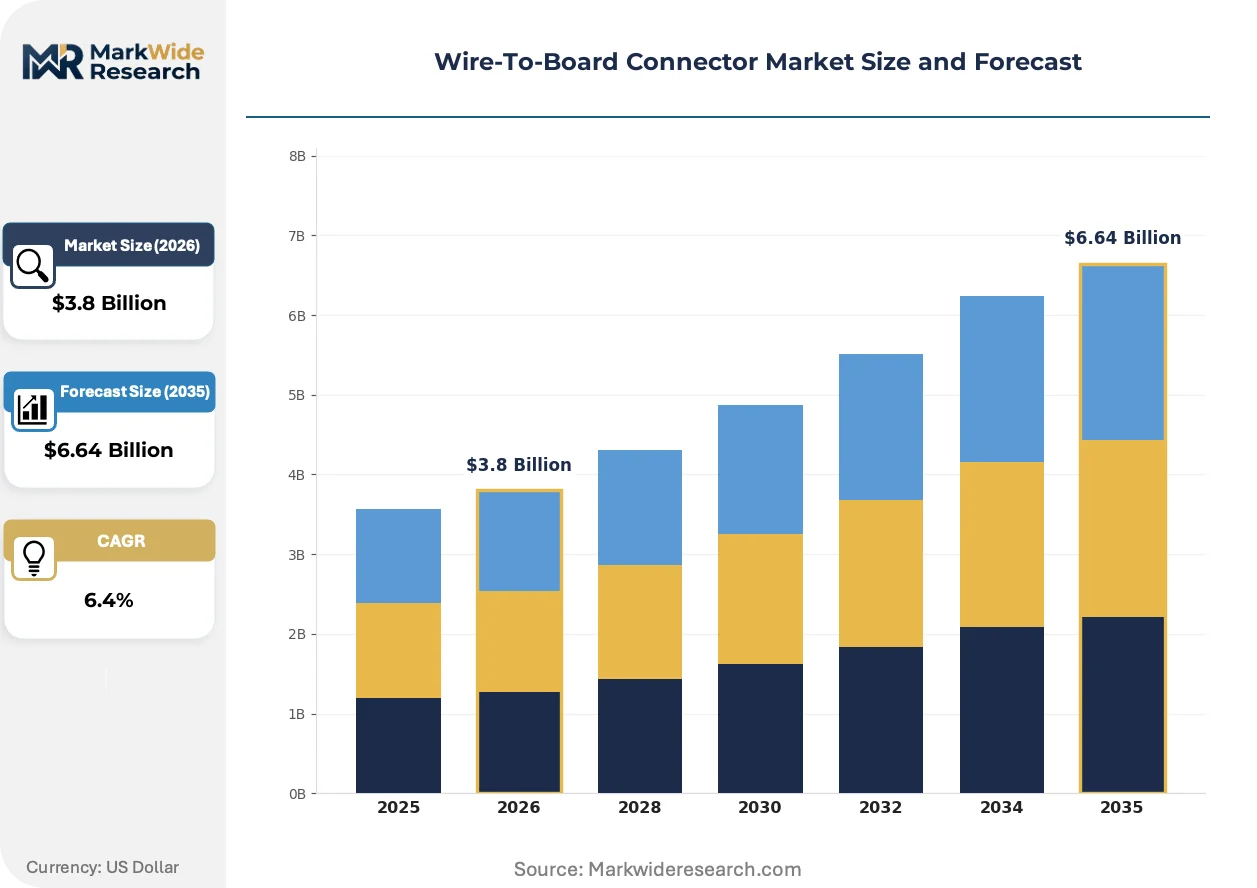
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulation Displacement Connectors, Pin Header Connectors, Socket Connectors, Male/Female Connectors Technology: Surface Mount Technology, Through Hole Technology, Hybrid Technology, Automated Connection Technology End User: Consumer Electronics, Industrial Automation, Automotive Components, Telecommunication Devices Application: Power Supply, Signal Transmission, Data Transfer, Control Systems |
| Companies Covered | TE Connectivity, Molex, Amphenol ICC, Hirose Electric, Samtec, J.S.T. Mfg. Co. Ltd, HARTING Technology Group, 3M, KYOCERA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wire-To-Board Connector Market Trends and Innovations
Surface mount termination methods are compressing assembly economics while regulatory mandates for material compliance are accelerating plating chemistry transitions across manufacturing footprints.
Press-fit compliant pin technology is rendering obsolete hand-soldered through-hole terminations in automotive power distribution modules. Tier-one suppliers in Germany and the United States are qualifying these interfaces for 100A+ current loads. The shift is rendering obsolete traditional wave soldering equipment investments and reducing thermal stress on multilayer PCBs.
China's GB standards and MIIT certification requirements are tightening domestic content rules for wire-to-board connectors used in telecommunications infrastructure. Foreign suppliers must establish in-country testing laboratories to maintain qualification status. Medical and industrial segments face the steepest compliance burdens as documentation requirements expand beyond electrical testing to material traceability.
Automotive OEMs are consolidating supplier relationships around vertically integrated partners capable of delivering connector-to-cable assembly systems. Tier-one procurement teams in Stuttgart and Detroit are reducing qualified vendor lists from twelve to four sources per vehicle platform. This consolidation is most visible in battery management system architectures where single-source accountability for signal integrity is becoming mandatory.
Wire-To-Board Connector Market Segmentation
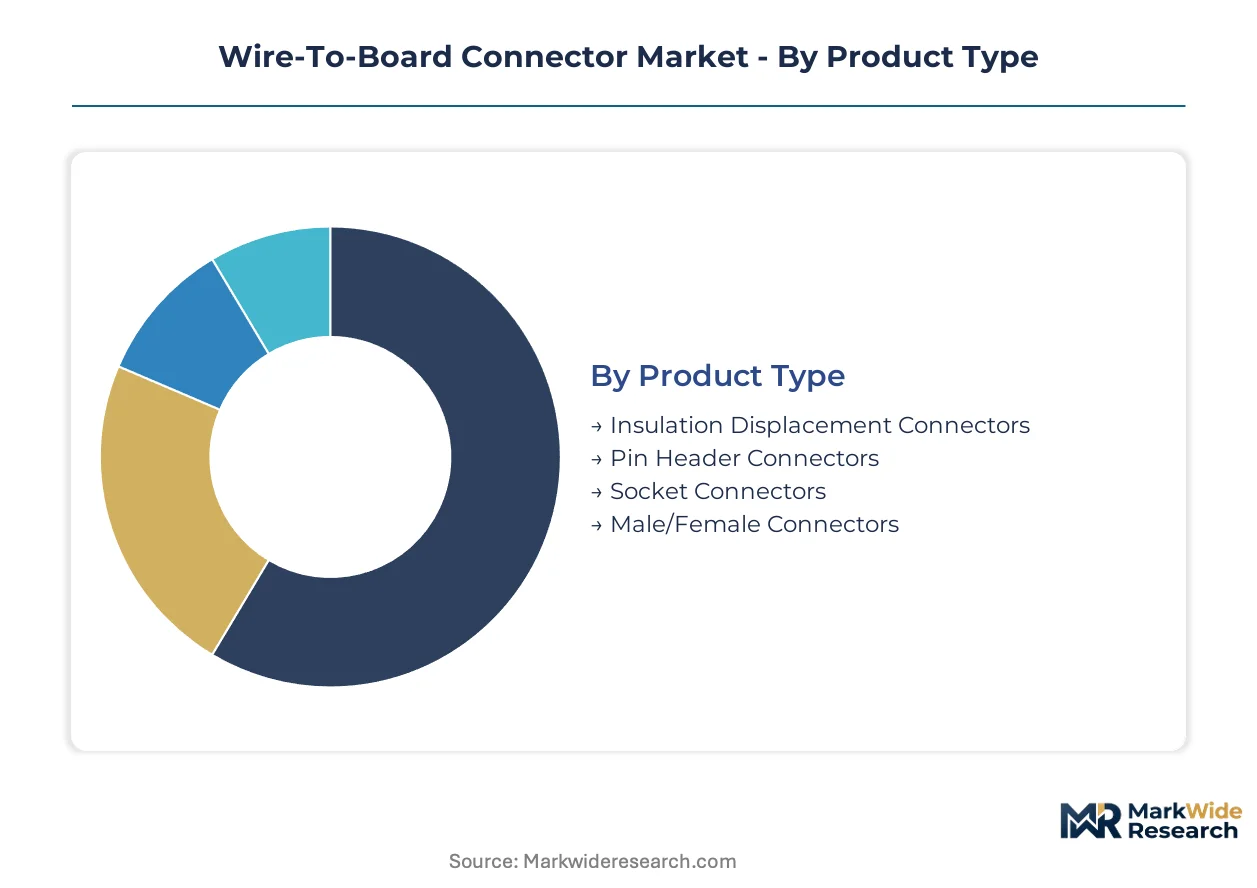
Wire-to-board connector procurement varies sharply across technical specifications and end-use environments. Product managers must align termination geometry, current rating, and mating cycle durability with specific application demands to avoid field failures and qualification delays.
Product Type:
Mature pin-and-socket formats dominate high-volume production while tool-less termination methods gain share in service-intensive applications.
- Pin Header Connectors:Rectangular arrays of male pins on 2.54mm or smaller pitch, soldered directly to PCB traces. Consumer electronics OEMs in Shenzhen and Dongguan source these in billions for motherboard peripheral expansion, though margin compression has pushed suppliers toward automated assembly integration.
- Insulation Displacement Connectors:Slotted contact beams slice through wire insulation to establish gas-tight electrical bonds without stripping tools. HVAC manufacturers in Germany and appliance makers in the United States are converting field-wiring harnesses to these interfaces to cut technician installation time and reduce callback rates.
- Socket Connectors:Female receptacles designed for high-cycle mating durability in test equipment and medical instrumentation. Gold-plated contact systems command premium positioning where 10,000+ insertion ratings are mandatory.
- Male/Female Connectors:Mated plug and receptacle pairs providing polarized mechanical keying for blind-mate applications. Industrial automation deployments favor these for hot-swappable I/O modules in harsh-environment enclosures.
Pin Header Connectors retain volume leadership; Insulation Displacement Connectors hold the steepest expansion curve.
Technology:
Assembly economics and thermal management requirements determine termination method selection across manufacturing footprints.
- Surface Mount Technology:Termination leads soldered directly to PCB pad surfaces without through-hole penetration. Smartphone OEMs in South Korea and Taiwan specify micro-pitch variants below 1.0mm to maximize board density in wearable form factors.
- Through Hole Technology:Leads inserted through drilled holes and wave-soldered for mechanical strain relief. Automotive power distribution modules in Stuttgart and Detroit retain these for 100A+ current loads where thermal cycling resistance outweighs density priorities.
- Hybrid Technology:Mixed surface-mount and through-hole terminations on single connectors. Telecom infrastructure suppliers combine SMT signal pins with press-fit power blades to balance density and current capacity in 5G base station designs.
- Automated Connection Technology:Machine-insertable interfaces with positive-lock housings for robotic assembly lines. Electric vehicle battery pack manufacturers deploy these to eliminate hand-termination variability in high-voltage interconnect systems.
Through Hole Technology anchors automotive and industrial procurement; Surface Mount Technology is climbing the fastest as consumer electronics pitch specifications tighten.
End User:
Procurement specifications diverge sharply between cost-optimized consumer volumes and reliability-critical transportation applications.
- Automotive Components:Connectors qualified for 800V architectures and thermal cycling from -40°C to 150°C. Battery management systems and inverter interfaces in Germany and the United States drive qualification investments for high-voltage isolation and vibration resistance.
- Consumer Electronics:Miniaturized interfaces for smartphones, laptops, and wearables where sub-millimeter pitch and EMI shielding determine competitive positioning. Assembly partners in Vietnam and India are absorbing volume migration from coastal China.
- Industrial Automation:IP-rated sealed connectors for factory floor environments with oil, moisture, and electromagnetic interference. German machinery OEMs specify M12-coded variants for deterministic Ethernet in motion control systems.
- Telecommunication Devices:Shielded backplane and mezzanine connectors for 5G infrastructure and data center switching. FCC emission mandates force integrated connector-filter architectures for baseband processing hardware.
Automotive Components command the highest qualification investment per SKU; Consumer Electronics generates the steepest unit volume expansion.
Application:
Current load and signal integrity requirements segment connector architectures across electrical function.
- Power Supply:High-current interfaces with beefy contact cross-sections and thermal management features. Electric vehicle onboard chargers and DC-DC converters specify these for 200A+ continuous operation with minimal temperature rise.
- Signal Transmission:Low-current precision contacts optimized for impedance control and crosstalk suppression. Medical imaging equipment and semiconductor test systems demand these for analog signal fidelity below 100mV noise floors.
- Data Transfer:Differential pair configurations supporting multi-gigabit serial protocols. Server and storage OEMs deploy these for PCIe and Ethernet backplane connectivity with bit-error-rate specifications below 10^-12.
- Control Systems:Mixed-signal connectors carrying both power and low-speed data in integrated industrial I/O. Programmable logic controller manufacturers favor these to reduce connector count in compact DIN-rail modules.
Power Supply applications absorb the highest material cost per connector; Data Transfer is expanding most quickly as serial data rates escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports wire-to-board connectors to automotive assembly plants in Germany and consumer electronics OEMs in South Korea, establishing the dominant trade-flow corridor in this industry. Manufacturing clusters in Guangdong and Zhejiang provinces feed tier-one procurement networks across three continents. Regulatory fragmentation across destination markets compels suppliers to maintain parallel certification portfolios.
China
Domestic EV production and telecommunications infrastructure deployment absorb the highest connector volumes globally. MIIT certification requirements and GB standards compel foreign suppliers to establish in-country testing partnerships for market access. Shenzhen and Dongguan industrial corridors concentrate precision stamping and plating capacity for micro-pitch formats serving smartphone OEMs.
Germany
Battery management systems and inverter interfaces for 800V automotive architectures drive qualification investments for high-voltage isolation. EU RoHS and REACH frameworks restrict cadmium and lead content in contact platings, accelerating migration to palladium-nickel finishes. Stuttgart procurement teams consolidate supplier relationships around vertically integrated partners capable of delivering connector-to-cable assembly systems.
United States
5G base station deployments and data center switching hardware generate demand for shielded backplane connectors with integrated filter assemblies. FCC electromagnetic emission rules force architectural redesigns for telecommunications gear. Detroit automotive tier-ones qualify press-fit compliant pin technology for 100A+ current loads in electric vehicle power distribution modules.
Japan
Miniaturization trends in wearable devices and medical instrumentation push pitch specifications below 1.0mm. METI industrial policy supports domestic precision manufacturing capabilities for high-reliability applications. Nagoya and Osaka clusters specialize in gold-plated contact systems for test equipment demanding 10,000+ insertion durability.
India
Mobile phone assembly expansion under the PLI scheme attracts connector investments to Noida and Sri City industrial corridors. BIS certification requirements shape domestic procurement specifications for telecommunications infrastructure. Karnataka and Tamil Nadu electronics manufacturing zones absorb volume migration from coastal China for consumer electronics applications.
Wire-To-Board Connector Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated specialists capable of delivering connector-to-cable assembly systems. Tier-one procurement teams reduce qualified vendor lists from twelve to four sources per vehicle platform. Three archetypes dominate: captive tooling specialists with in-house mold-making capabilities, R&D-intensive micro-pitch developers, and harsh-environment specification leaders. M&A activity and geographic expansion into India and Vietnam represent the dominant competitive moves.
Within the premium-tier vector, TE Connectivity exemplifies the vertically integrated archetype through captive tooling capabilities across Asia and Europe. Molex occupies a position representing R&D intensity in micro-pitch formats. Amphenol ICC anchors the harsh-environment specification tier. These three entities collectively illustrate how competitive positioning separates automotive electrification specialists from consumer electronics miniaturization leaders.
| Leading Market Players |
|---|
| TE Connectivity |
| Molex |
| Amphenol ICC |
| Hirose Electric |
| Samtec |
| J.S.T. Mfg. Co. Ltd |
| HARTING Technology Group |
| 3M |
| KYOCERA Corporation |
| Others |
Pricing and Supply Chain Analysis
Guangdong and Zhejiang tooling clusters concentrate captive mold-making for complex housing geometries, anchoring margin capture at the precision stamping tier while downstream assembly operations face persistent cost compression.
Pricing Analysis
Next-generation micro-pitch formats command substantial premiums over legacy 2.54mm pin headers and mature through-hole designs. Pricing stratifies across premium, standard, and economy tiers based on certification grade—UL and IEC automotive tiers extract highest value—and volume scale, with smartphone OEM procurement compressing unit economics at billion-piece scale. Cost compression in pin header segments is intensifying because automated assembly integration has eliminated labor differentiation. Consumer electronics OEMs exhibit extreme price sensitivity, while medical device manufacturers prioritize insertion durability over unit cost.
Supply Chain Analysis
Copper cathode and palladium sponge feedstock markets draw from Chilean mining operations and Russian refining capacity, creating raw material cost volatility that propagates through contact plating tiers. Manufacturing concentrates in China, Germany, and the United States, with precision stamping anchored in Shenzhen-Dongguan corridors and automotive qualification centered in Stuttgart and Detroit. Single-source vulnerability concentrates at the captive tooling tier where complex housing geometries require specialized mold-making expertise. Distribution runs through tier-one supplier networks that consolidate vendor lists from twelve to four sources per vehicle platform.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wire-to-board connector market is entering a cyclical recovery phase as automotive electrification drives replacement demand for high-voltage qualified product lines.
For Market Incumbents: Entrench position through backward integration into captive plating operations that secure palladium-nickel supply chains against commodity volatility. Deepen certification investments for 800V automotive architectures to defend against emerging Asian suppliers seeking tier-one qualification. Consolidate supplier relationships around connector-to-cable assembly capabilities that single-source accountability demands. For New Entrants and Emerging Players: Build out micro-pitch development capabilities targeting India's PLI scheme corridors in Noida and Sri City, where mobile phone assembly expansion has outrun local connector supply. Penetrate the insulation displacement segment serving HVAC and appliance field service markets, where tool-less termination adoption lags behind technical availability. Pursue co-development partnerships with domestic Indian OEMs seeking GB-standard alternatives to Chinese supply. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with in-house mold-making and automotive qualification portfolios that consolidation-resistant tier-one procurement demands. Long-term viability hinges on exposure to electrification-driven high-voltage segments rather than consumer electronics volume plays. Monitor UL and IEC qualification pipeline velocity as the inflection signal for supplier share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plating Operations | Captive palladium-nickel capacity insulates margins from contact material cost spikes. |
| Automotive High-Voltage Qualification Investment | UL and IEC certification for 800V architectures unlocks tier-one procurement consolidation. |
| Geographic Expansion into India PLI Corridors | Noida and Sri City manufacturing positions suppliers for mobile phone assembly migration. |
| Insulation Displacement Product Line Development | Tool-less termination formats capture HVAC and appliance field service upgrade cycles. |
| Connector-to-Cable Assembly System Integration | Single-source accountability for signal integrity meets Stuttgart and Detroit procurement mandates. |
Research Methodology
The analysis maps pin header, insulation displacement, socket, and male/female connector formats, each validated through procurement directors at automotive tier-ones, platform engineers at smartphone OEMs, and maintenance heads at industrial automation deployers. Primary fieldwork combined with secondary validation against SEC filings from TE Connectivity, Molex, and Amphenol, customs trade data for copper and palladium flows, and MIIT certification registries. Bottom-up SKU-level volume builds triangulated against top-down segment value allocations.
Fixed assumptions across the projection horizon include sustained automotive electrification capex, continued RoHS and REACH material compliance mandates, and stable China-Germany-US manufacturing concentration. Segmentation dimensions modeled span product type, termination technology, end-use vertical, and application function. CAGRs derived from regression against historical automotive production and consumer electronics shipment correlations, with specific inputs from electric vehicle platform rollout schedules and 5G base station deployment pipelines.
Sensitivities concentrate around copper and palladium price volatility, high-voltage safety certification timeline extensions, and geopolitical friction affecting China-based tooling access. Cross-checking against IHS Markit automotive production forecasts and MIIT telecommunications infrastructure disclosure databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Circular Waterproof Connector Market
Connectors
Connector Kits Market
Connectors
Asia-Pacific Connector Market
Connectors
Underwater Mate Connectors Market
Connectors
Global Fiber Optic Connectors Market
Connectors
Japan Connector Market
Connectors
Global Board to Board (BTB) Connectors Market
Connectors
Latin America Connector Market
Connectors
Power Connector Market
Connectors
Smart Crimper Market
Connectors
Connector Market
Connectors
Middle East and Africa Hazardous Location Connectors Market
Connectors
Heavy-Duty Connector Market
Connectors
Global Wired Interface Market
Connectors
LCP Connectors Market
Connectors
Magnetic Connector Market