
 Liquid Cooling Systems Market | 2026-2036
Liquid Cooling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Cooling Systems Market Outlook
Direct-to-chip distribution channels is tilting toward integrated solution providers as hyperscalers seek single-source accountability for thermal performance. Schneider Electric leverages its electrical-thermal bundled offering to control specification conversations at the data center design stage. Vertiv Group Corp. anchors its position through captive manufacturing of precision cooling hardware across three continents. Alfa Laval competes on heat exchanger engineering depth, sustaining R&D intensity that outpaces generalist HVAC suppliers.
Liquid cooling systems circulate engineered dielectric fluids or water-glycol mixtures through cold plates, manifolds, or immersion baths to extract heat from densely packed electronic components operating above 300W per chip. Direct liquid cooling dominates current data center deployments due to its retrofit compatibility with existing server architectures, while immersion cooling captures margin pools in blockchain and AI training clusters where rack densities exceed 50kW. Chilled liquid cooling maintains installed-base relevance in telecommunications shelters with moderate thermal loads, though its share of new-build specifications is compressing as direct-to-chip designs advance.
The EPA's ENERGY STAR server specifications and ASHRAE's expanding liquid cooling guidelines are tightening thermal design power compliance thresholds across US facilities, while China's MIIT dual carbon goals and GB standards are accelerating domestic immersion cooling adoption for state-backed computing centers. Stakeholders must monitor regulatory divergence between efficiency mandates and refrigerant phase-down timelines, as coolant chemistry choices carry decade-long lock-in consequences for infrastructure planners.
Market Dynamics
The thermal design power threshold crossing 300W per processor is forcing infrastructure planners to abandon air-cooled architectures entirely, triggering a wholesale specification rewrite across data center construction pipelines.
Growth Catalysts
- AI Training Cluster Density:Hyperscale facilities deploying GPU racks above 50kW per rack require direct liquid cooling as the only viable heat rejection pathway, pulling demand from traditional chilled water systems.
- EPA ENERGY STAR Server Specifications:The tightened efficiency thresholds for federal procurement are mandating liquid-cooled configurations for any server deployment above 450W thermal design power.
- Automotive Battery Gigafactories:Cell formation and aging chambers in Germany, China, and the United States require precision temperature control within ±1°C, driving adoption of closed-loop dielectric cooling circuits.
Market Restraints
- Fluorinated Coolant Supply Concentration:Engineered dielectric fluids rely on three chemical conglomerates based in Belgium, Japan, and the United States, creating vulnerability to export control adjustments.
- Retrofit Capex Burden:Converting existing raised-floor data centers requires structural reinforcement for coolant distribution manifolds, often doubling the mechanical budget of brownfield projects.
- ASHRAE Guideline Fragmentation:Competing thermal classification standards between the United States and European Committee for Standardization create compliance duplication for multinational operators.
Strategic Opportunities
- India Data Center Buildout:The country's national electronics policy incentives for semiconductor packaging and cloud regions are creating first-mover advantage for liquid cooling EPC contractors establishing local presence.
- Two-Phase Immersion Convergence:Integration of passive two-phase heat transfer with direct-to-chip cold plates enables 100kW+ rack densities without mechanical pumping at the chip level.
- China MIIT Dual Carbon Mandates:State-backed computing centers in Beijing and Shanghai must achieve PUE below 1.2, effectively mandating liquid cooling for all new hyperscale approvals.
Industry Challenges
- Fluid Chemistry Expertise Gap:Facility engineers trained on refrigerant-based HVAC lack competency in dielectric fluid compatibility testing with server board materials, slowing commissioning timelines.
- Leak Detection Certification Delays:UL and IEC safety certifications for sub-floor coolant distribution systems require 14-18 month validation cycles, misaligning with construction schedules.
- Legacy Air-Cooled Asset Stranding:Enterprises with depreciated CRAC infrastructure face write-down pressure when liquid cooling mandates hit procurement policies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Cooling Systems Market |
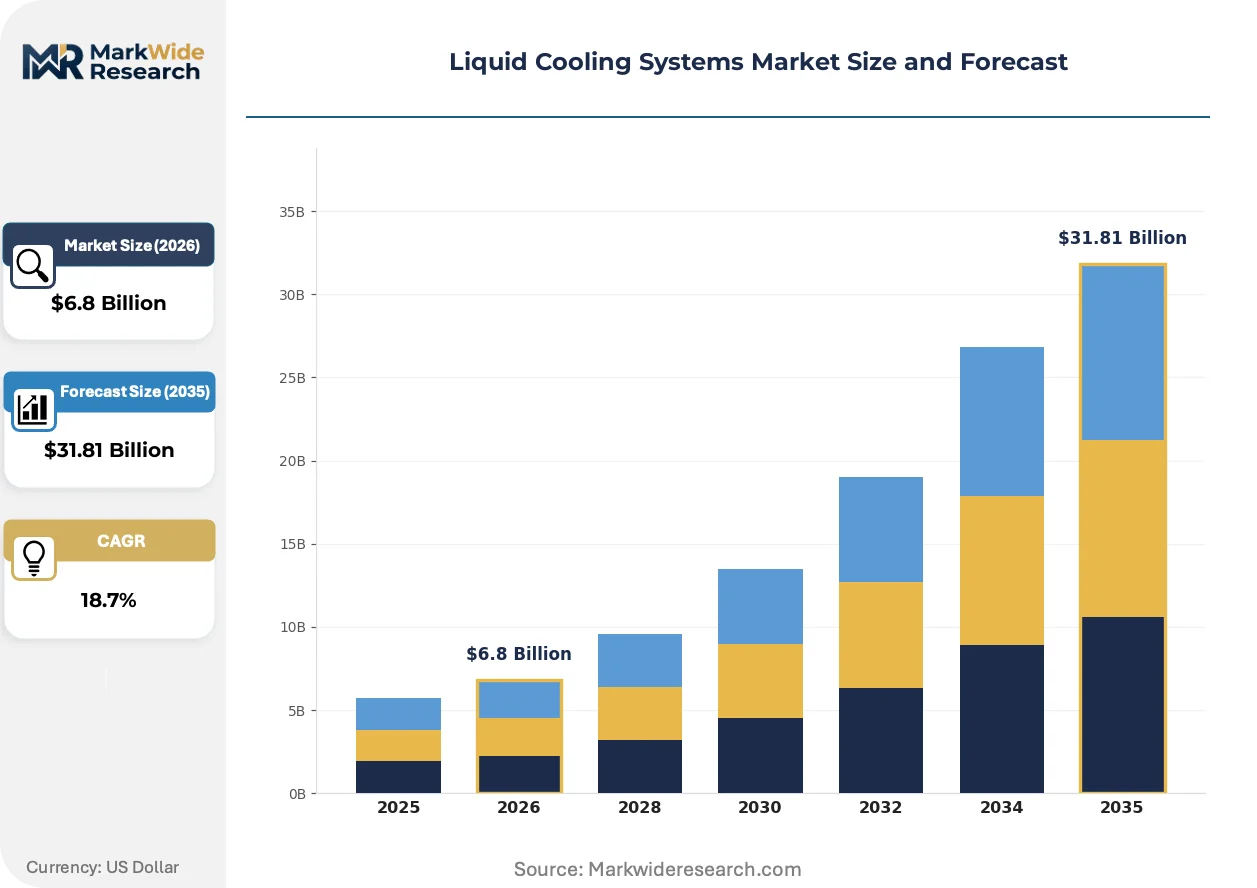
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.81 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Data Centers, High-Performance Computing, Telecommunications, Electric Vehicles System Type: Direct Liquid Cooling, Immersion Cooling, Chilled Liquid Cooling, Liquid-to-Air Systems End User: IT Industry, Automotive, Aerospace, Military Component: Pumps, Radiators, Coolant, Heat Exchangers |
| Companies Covered | Schneider Electric, Vertiv Group Corp., Alfa Laval, LiquidStack Holding B.V., Asetek Inc., Boyd Corporation, Rittal GmbH & Co. KG, CoolIT Systems, Green Revolution Cooling Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Cooling Systems Market Strategic Shifts
Coolant chemistry, system architecture, and procurement logic are diverging simultaneously as thermal loads outpace incremental improvements in conventional approaches.
Single-phase immersion baths using synthetic hydrocarbon formulations are rendering obsolete the raised-floor perimeter cooling designs that dominated enterprise data centers for three decades. Cryptocurrency mining operations in Texas and Kazakhstan adopted this architecture first due to rack density requirements exceeding 75kW, and now AI training facilities in Singapore and Ireland are specifying identical configurations for new builds.
REACH restrictions on per- and polyfluoroalkyl substances are accelerating reformulation of dielectric coolants toward hydrofluoroether blends with lower global warming potential. Chemical suppliers in Germany and the Netherlands are scaling production of these next-generation fluids, though their margin structures remain compressed against legacy fluorocarbon price benchmarks established over two decades.
Hyperscalers are consolidating thermal performance accountability under single-source engineering-procurement-construction contracts rather than fragmenting responsibility between electrical and mechanical contractors. This bundling is displacing the traditional bid-package separation in Northern Virginia, Frankfurt, and Amsterdam markets, where Microsoft, Amazon Web Services, and Google have each shifted procurement specifications in the past eighteen months.
Liquid Cooling Systems Market Segmentation
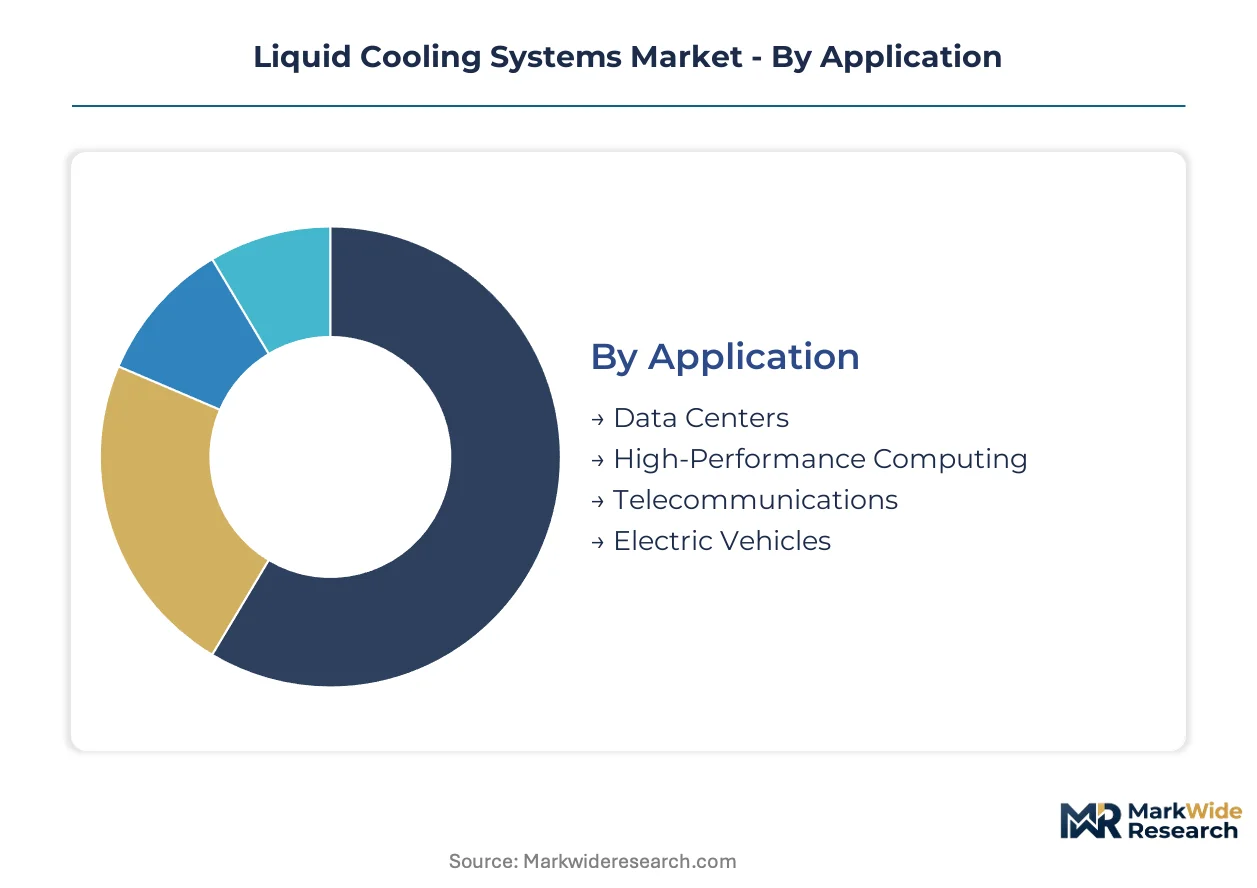
Liquid cooling systems fragment across thermal load intensity, infrastructure maturity, and coolant chemistry compatibility. Each segment carries distinct commissioning protocols and aftermarket service requirements that shape supplier economics.
Application:
After-sales service intensity varies dramatically across deployment environments, with mission-critical facilities demanding 24-hour response commitments that alter vendor profitability structures.
- Data Centers:Hyperscale facilities in Northern Virginia, Frankfurt, and Singapore specify direct-to-chip architectures for GPU racks exceeding 50kW. EPA ENERGY STAR procurement mandates and China's MIIT dual carbon goals are tightening thermal design power compliance thresholds, forcing liquid-cooled configurations for new federal and state-backed deployments.
- High-Performance Computing:Academic and government research clusters in the United States, Germany, and Japan require precision temperature control within ±0.5°C for molecular simulation workloads. These installations command premium service contracts due to extended validation cycles and specialized fluid chemistry expertise.
- Telecommunications:Edge computing shelters and 5G base stations in India and Brazil deploy chilled liquid cooling for moderate thermal loads below 15kW per rack.
- Electric Vehicles:Battery gigafactories in Germany, China, and the United States rely on closed-loop dielectric circuits for cell formation chambers requiring ±1°C stability.
By volume, Data Centers leads. By growth pace, Electric Vehicles is ahead.
System Type:
Cost tier stratification separates retrofit-compatible solutions from greenfield-optimized architectures, with price premiums correlating to rack density enablement.
- Direct Liquid Cooling:Cold plate configurations circulate water-glycol mixtures or engineered dielectric fluids across processor surfaces. Microsoft, Amazon Web Services, and Google have standardized this approach for AI training facilities, pulling specification authority away from traditional mechanical contractors.
- Immersion Cooling:Single-phase and two-phase baths submerge entire server assemblies in synthetic hydrocarbon or hydrofluoroether formulations. Cryptocurrency operations in Texas and Kazakhstan pioneered 75kW+ rack densities, with Singapore and Ireland AI clusters now adopting identical architectures.
- Chilled Liquid Cooling:Perimeter CRAH units with chilled water distribution maintain relevance in legacy enterprise facilities with moderate density requirements.
- Liquid-to-Air Systems:Hybrid architectures reject heat to ambient air through dry coolers, serving telecommunications shelters and edge locations without mechanical cooling infrastructure.
By installed base, Chilled Liquid Cooling dominates. By specification momentum, Immersion Cooling is climbing the fastest.
End User:
Customer type determines procurement centralization, with consolidated hyperscaler buyers extracting volume pricing that compresses margins for generalist suppliers.
- IT Industry:Cloud providers and colocation operators in the United States, Germany, and China consolidate thermal performance accountability under single-source EPC contracts, displacing traditional bid-package separation.
- Automotive:Cell manufacturers and EV platform integrators in Germany, China, and the United States specify precision cooling for battery pack thermal management and cell formation processes.
- Aerospace:Satellite and avionics applications require lightweight, vibration-resistant cooling loops with dielectric fluids meeting MIL-STD specifications.
- Military:Command center and field-deployable systems demand hardened packaging and rapid-deployment manifolds with classified coolant distribution protocols.
By contract value, IT Industry leads. By technical complexity, Aerospace is expanding most quickly.
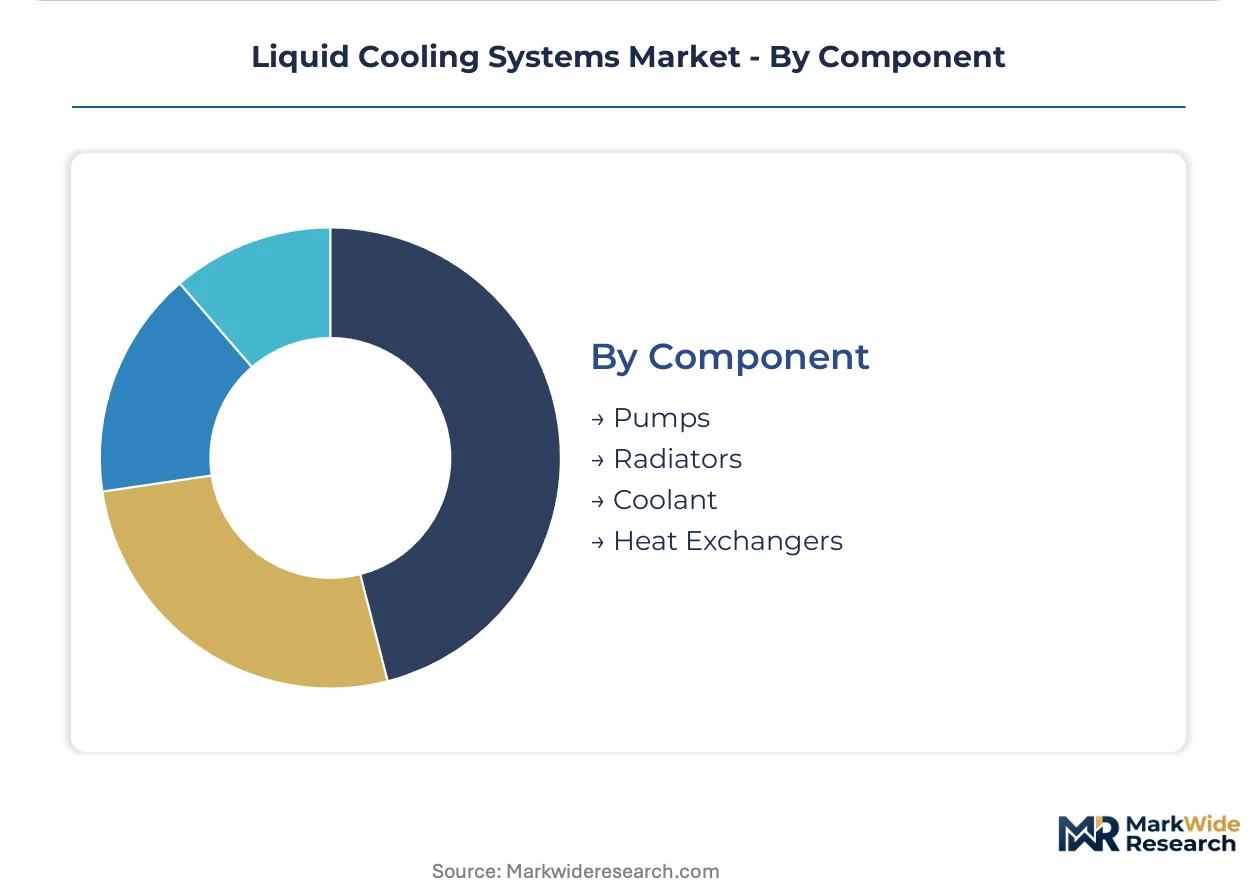
Component:
Supply concentration for precision-manufactured subsystems creates margin capture opportunities for captive producers versus outsourced assemblers.
- Pumps:Magnetic-drive and canned-motor configurations circulate dielectric fluids at flow rates exceeding 20 liters per minute. German and Japanese suppliers control high-reliability designs for data center applications.
- Radiators:Aluminum and copper-fin heat rejection surfaces dimensioned for dry cooler integration or facility water loops. Chinese manufacturers dominate volume production for cost-sensitive telecommunications deployments.
- Coolant:Engineered dielectric fluids from Belgian, Japanese, and United States chemical conglomerates face REACH-driven reformulation toward hydrofluoroether blends with reduced global warming potential.
- Heat Exchangers:Plate-and-frame and brazed-aluminum designs transfer thermal energy between primary and secondary loops, with Alfa Laval and specialized HVAC engineering houses sustaining R&D intensity above generalist competitors.
By revenue contribution, Coolant leads. By technical differentiation, Heat Exchangers is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Suppliers in Germany and the United States command 15-20% pricing premiums over Chinese manufacturers due to certification depth and captive coolant chemistry capabilities, while Indian and Southeast Asian markets absorb cost-optimized configurations for volume deployments.
United States
Hyperscale cloud construction in Northern Virginia and Dallas-Fort Worth drives direct-to-chip specification volumes. EPA ENERGY STAR server procurement mandates now require liquid-cooled configurations above 450W thermal design power for federal deployments. Microsoft and Amazon Web Services have consolidated thermal accountability under single-source EPC contracts, displacing traditional mechanical-electrical bid separation.
China
State-backed computing centers in Beijing and Shanghai face MIIT-mandated PUE ceilings below 1.2, effectively requiring liquid cooling for all new hyperscale approvals. The Yangtze River Delta hosts domestic immersion cooling manufacturing clusters serving both cloud providers and cryptocurrency mining operations. GB standards evolution is accelerating local certification pathways for dielectric fluid formulations.
Germany
Battery gigafactories in Lower Saxony and Baden-Württemberg deploy precision dielectric cooling for cell formation chambers requiring ±1°C stability. ECHA REACH restrictions on per- and polyfluoroalkyl substances are forcing coolant reformulation toward hydrofluoroether blends with reduced global warming potential. Frankfurt's data center corridor maintains Europe's densest concentration of direct liquid cooling deployments.
India
National electronics policy incentives for semiconductor packaging and cloud regions are creating first-mover advantage for liquid cooling EPC contractors establishing local presence. CEA efficiency guidelines for data centers are tightening toward PUE thresholds that favor liquid-cooled architectures. Maharashtra and Karnataka host emerging hyperscale construction pipelines where specification authority remains contested between global suppliers and domestic system integrators.
Singapore
AI training facilities are adopting single-phase immersion architectures pioneered by cryptocurrency operations in Texas and Kazakhstan, achieving rack densities exceeding 75kW. The tropical climate eliminates dry cooler viability, mandating facility water loop integration for heat rejection. Government land-use constraints are compressing data center footprints, intensifying thermal density requirements.
Liquid Cooling Systems Market Competitive Environment
Integrated solution providers and specialized thermal engineering houses split the market based on procurement centralization preferences among hyperscalers. The vendor base concentrates around three strategic archetypes: electrical-thermal bundlers controlling specification conversations at design stage, captive manufacturers of precision cooling hardware sustaining multi-continental production footprints, and heat transfer specialists competing on engineering depth rather than scale. Dominant competitive moves include geographic expansion into India and Southeast Asia data center construction pipelines, plus backward integration into coolant distribution and aftermarket service capabilities.
Within the integrated solution tier, Schneider Electric and Vertiv Group Corp. exemplify archetypes that bundle electrical infrastructure with thermal performance accountability. Alfa Laval occupies a position among heat transfer engineering specialists where R&D intensity outpaces generalist HVAC competitors. These three anchors span French, American, and Swedish geographic origins respectively, representing the geographic diversification of supply-side capability concentration.
| Leading Market Players |
|---|
| Schneider Electric |
| Vertiv Group Corp. |
| Alfa Laval |
| LiquidStack Holding B.V. |
| Asetek Inc. |
| Boyd Corporation |
| Rittal GmbH & Co. KG |
| CoolIT Systems |
| Green Revolution Cooling Inc. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese radiator manufacturing is compressing margins for commodity heat rejection hardware while simultaneously creating procurement leverage for hyperscale buyers negotiating long-term dielectric fluid supply agreements. This utilization asymmetry between precision-engineered coolants and volume-manufactured components is fragmenting supplier economics across the value chain.
Pricing Analysis
Configured-to-order pricing for direct-to-chip cold plate systems commands 40-60% premiums over standard chilled water CRAH units due to material compatibility testing and ASHRAE certification requirements. Three-tier pricing structure across premium, standard, and economy levels separates UL-certified immersion baths from CE-marked regional variants and unbranded Chinese assemblies. Pricing pressure stems from hyperscaler consolidation of EPC contracts, which extracts volume discounts that compress margins for generalist HVAC suppliers. Colocation operators exhibit highest price sensitivity due to pass-through lease structures, while automotive battery manufacturers prioritize precision over cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic planning for coolant distribution infrastructure and precision pump assemblies. Engineered dielectric fluids draw from Belgian, Japanese, and United States chemical conglomerates, while aluminum radiators and copper-fin heat exchangers source predominantly from Chinese and German manufacturers. Single-source vulnerability concentrates in hydrofluoroether formulations facing REACH-driven reformulation timelines. Distribution runs through integrated solution providers capturing specification authority at data center design stage, displacing traditional mechanical-electrical bid separation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as two-phase immersion architectures threaten to displace direct-to-chip systems in AI training clusters exceeding 75kW per rack.
For Market Incumbents: Insulate specification relationships by embedding thermal engineers within hyperscaler design teams during pre-construction phases, locking out challenger EPC bids. Captive manufacturing of precision pumps and cold plates in Germany and Japan defends margin position against Chinese cost-optimized entrants. Certification investment in UL and IEC safety standards for sub-floor coolant distribution creates 14-18 month switching barriers. For New Entrants and Emerging Players: Build out fluid chemistry expertise capabilities targeting the automotive battery gigafactory segment in Lower Saxony and Michigan, where precision temperature control requirements exceed incumbent service capacity. India's national electronics policy incentives for semiconductor packaging and cloud regions offer white-space entry with contested specification authority. Partner with domestic system integrators in Maharashtra and Karnataka to bypass entrenched EPC relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across immersion cooling manufacturing as two-phase system R&D and dielectric fluid reformulation absorb capital deployment. Long-term viability favors vertically integrated specialists with captive coolant chemistry and precision hardware production. The signal to watch is hyperscaler procurement consolidation velocity—accelerating EPC bundling indicates margin capture shifting to integrated providers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coolant Chemistry | Captive hydrofluoroether production defends margin against REACH-driven supply disruption. |
| Certification Acceleration Programs | Parallel UL and IEC validation compresses 14-18 month safety cycles to align with construction schedules. |
| Geographic Manufacturing Footprint Expansion | Local precision pump production in India captures national electronics policy incentives. |
| Two-Phase Immersion R&D Partnerships | Passive heat transfer integration enables 100kW+ rack densities without mechanical pumping. |
| Aftermarket Service Network Buildout | 24-hour response commitments in Northern Virginia and Frankfurt lock in mission-critical facility contracts. |
Study Parameters
Cross-validation between primary interviews with data center facility engineers, EPC procurement directors, automotive battery plant managers, and dielectric fluid R&D chemists anchors the qualitative findings. Secondary validation draws from EPA ENERGY STAR server specifications, ASHRAE liquid cooling guidelines, China MIIT dual carbon policy documents, and ECHA REACH substance restrictions. Bottom-up demand modeling triangulates against top-down hyperscaler capex disclosures and battery gigafactory construction pipelines.
Calibration against historical thermal design power trajectories and rack density specifications shapes the analytical framework across the analysis window. Segmentation dimensions include system architecture type, coolant chemistry compatibility, end-use application intensity, and regional regulatory cluster. CAGRs derive from fitted adoption curves for direct liquid cooling versus immersion architectures, incorporating AI training cluster deployment schedules and automotive cell formation capacity expansion.
Stress conditions across fluorinated coolant export control adjustments, ASHRAE-European Committee for Standardization guideline divergence, and hyperscaler EPC procurement consolidation velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about thermal design power thresholds and regulatory compliance timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
AC DC Power Adapter Market
Power Systems
Synchronous Condenser Market
Power Systems
Voltage Stabilizer System Market
Power Systems
Thermoelectric Generator (TEG) Market
Power Systems
Global Flexible Batteries Market
Power Systems
Battery Charge Controller Market
Power Systems
Solid State Power Controller Market
Power Systems
Insulated Gate Bipolar Transistor (IGBT) Market
Power Systems
Ultrafast Rectifiers Market
Power Systems
Low Voltage Drives Market
Power Systems
Asia-Pacific DC Distribution Networks Market
Power Systems
Global Data Center Transformer Market
Power Systems
Asia-Pacific Shunt Reactors Market
Power Systems
Global Synchronous Motor Market
Power Systems
High Voltage Ceramic Zinc Oxide Surge Arrester Market
Power Systems
Medium Voltage Drives Market