
 Liquid Chemical Tanker Shipping Market | 2026-2036
Liquid Chemical Tanker Shipping Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Chemical Tanker Shipping Market Insights
Spot charter revenue is narrowing toward voyage-contract margins as time-charter coverage thins across the chemical tanker orderbook. Stolt-Nielsen Limited leverages its integrated terminal-to-tanker logistics network to sustain contract renewal rates above spot indexes. Scorpio Tankers Inc. anchors its fleet positioning around refined-product flexibility, while Odfjell SE specializes in stainless-steel coated vessels for high-purity cargo segments.
Liquid chemical tanker shipping denotes the maritime transport of industrial chemicals in dedicated vessels built to International Maritime Organization classification standards, with cargo tanks constructed from stainless steel or epoxy-coated mild steel to resist corrosive substances and prevent cross-contamination between voyages. The fleet serves as the primary intermodal link between petrochemical production clusters and downstream formulation plants across oceanic trade lanes. IMO Type 2 chemical tankers occupy the core volume position due to their versatility across medium-hazard cargoes, while specialty chemicals demand drives premium pricing for IMO Type 1 vessels with the most stringent safety architecture. Petrochemicals dominate cargo volumes through ethylene, methanol, and benzene movements, though organic chemicals freight is accelerating fastest on Asia-to-Europe glycol and alcohol trade expansions.
The International Maritime Organization enforces MARPOL Annex II standards governing chemical cargo categorization and tank coating requirements, while the EU Green Deal's FuelEU Maritime initiative is tightening carbon intensity benchmarks for vessels calling at European ports. Classification societies including DNV and Lloyd's Register have begun embedding well-to-wake emission protocols into newbuild chemical tanker specifications. Stakeholders must monitor whether methanol dual-fuel propulsion investments align with charterer sustainability procurement thresholds before committing to yard slots.
Market Dynamics
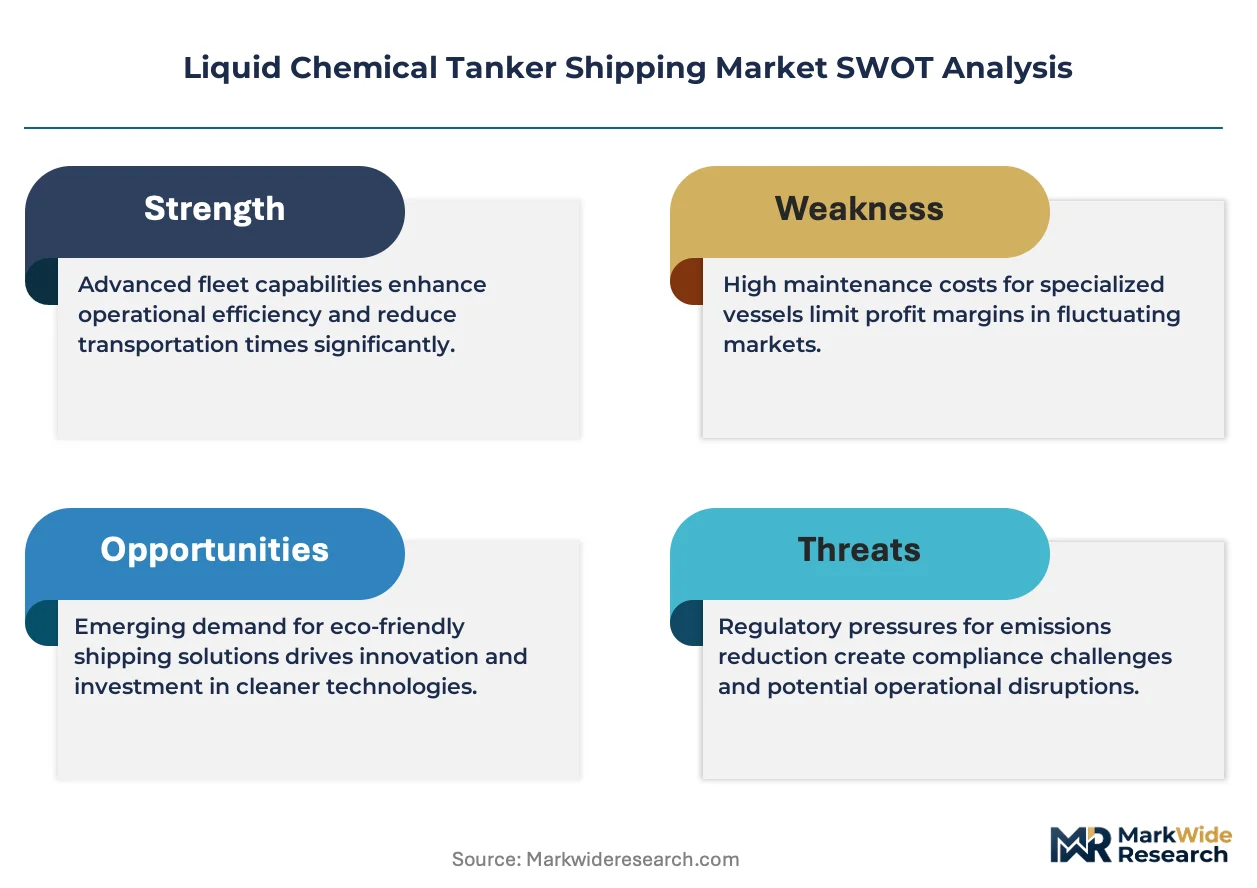
IMO MARPOL Annex II revisions are forcing accelerated stainless-steel tanker replacements as epoxy-coated mild steel vessels lose certification eligibility for high-grade chemical cargoes.
Growth Catalysts
- EU FuelEU Maritime:The EU Green Deal's carbon intensity benchmarks are pulling dual-fuel methanol newbuild orders from charterers with European port exposure.
- Specialty chemical formulators:Pharmaceutical manufacturers in Germany and agrochemical blenders in India are expanding import volumes for high-purity intermediates requiring IMO Type 1 architecture.
- US Gulf Coast ethylene terminal expansions:Petrochemical export capacity additions along the Texas-Louisiana corridor are absorbing coated-stainless chemical tanker tonnage at premium rates.
Market Restraints
- Stainless steel plate volatility:Nickel price swings from Indonesian supply disruptions inflate newbuild yard quotations unpredictably.
- Korean and Chinese yard concentration:Over 70 percent of chemical tanker construction concentrates in two East Asian shipbuilding clusters, creating delivery slot scarcity.
- Epoxy coating lifespan limits:Coated mild steel tanks face 15-year recertification cycles that compress asset residual values versus full stainless alternatives.
Strategic Opportunities
- India's agrochemical import corridor:Gujarat and Maharashtra formulation plants are underpenetrated by dedicated stainless-steel parcel tanker services.
- Carbon accounting integration:Well-to-wake emission protocols from DNV and Lloyd's Register enable charterer differentiation for EU CSRD-compliant shippers.
- Terminal-tanker logistics bundling:Integrated storage and vessel contracting models are displacing spot-market fragmentation in North Sea chemical trades.
Industry Challenges
- Marine chemist certification bottlenecks:The Institute of Marine Engineering, Science and Technology reports acute shortages of cargo surveyors qualified for MARPOL Annex II compliance verification.
- Dual-fuel retrofit capex burdens:Existing IMO Type 2 vessels require engine-room modifications exceeding 40 percent of book value to meet FuelEU Maritime thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Chemical Tanker Shipping Market |
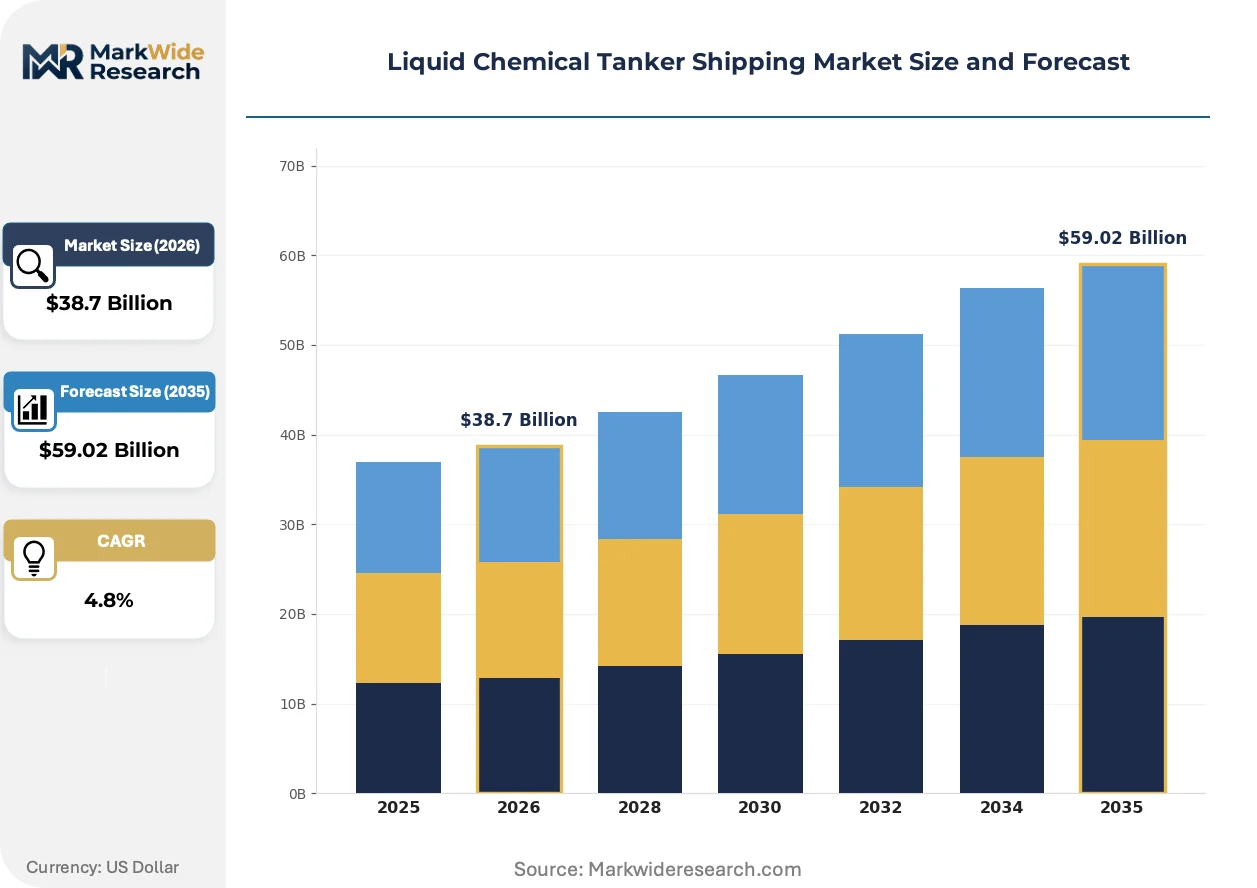
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: IMO Type 1, IMO Type 2, IMO Type 3, Chemical Tanker Cargo Type: Petrochemicals, Specialty Chemicals, Organic Chemicals, Inorganic Chemicals End User: Chemical Manufacturers, Oil Refiners, Pharmaceutical Companies, Food Processing Operation Mode: Time Charter, Voyage Charter, Bareboat Charter, Freight Forwarding |
| Companies Covered | Navig8 Group, Scorpio Tankers Inc., Stolt-Nielsen Limited, International Seaways Inc., Ardmore Shipping Corporation, Odfjell SE, Hafnia, BW Group, MOL Chemical Tankers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Chemical Tanker Shipping Market Trends and Innovations
Digital cargo matching platforms and emission tracking protocols are compressing chartering cycles while elevating vessel utilization transparency across chemical tanker trades.
Digital twin systems for tank coating degradation monitoring are virtualizing preventive maintenance schedules. Stolt-Nielsen and Odfjell are piloting sensor arrays that predict epoxy failure months before inspection deadlines. This capability is virtualizing the traditional drydock recertification calendar, compressing off-hire periods and extending trading windows for coated-steel fleets.
The EU Green Deal's FuelEU Maritime initiative is tightening carbon intensity benchmarks for vessels calling at Rotterdam, Antwerp, and Hamburg. Charterers with European supply chain exposure now embed well-to-wake emission clauses in three-to-five-year time charter agreements. IMO Type 1 stainless-steel vessels with methanol dual-fuel capability command rate premiums against conventional tonnage in this compliance environment.
Procurement patterns among German pharmaceutical manufacturers are consolidating contract volumes with integrated logistics providers offering terminal-to-tanker carbon accounting. Spot-market fragmentation is losing share to pre-allocated parcel schedules with verified emission footprints. This consolidation is most visible in glycol and alcohol trades from Singapore and Jubail to Rotterdam and Antwerp.
Liquid Chemical Tanker Shipping Market Segmentation
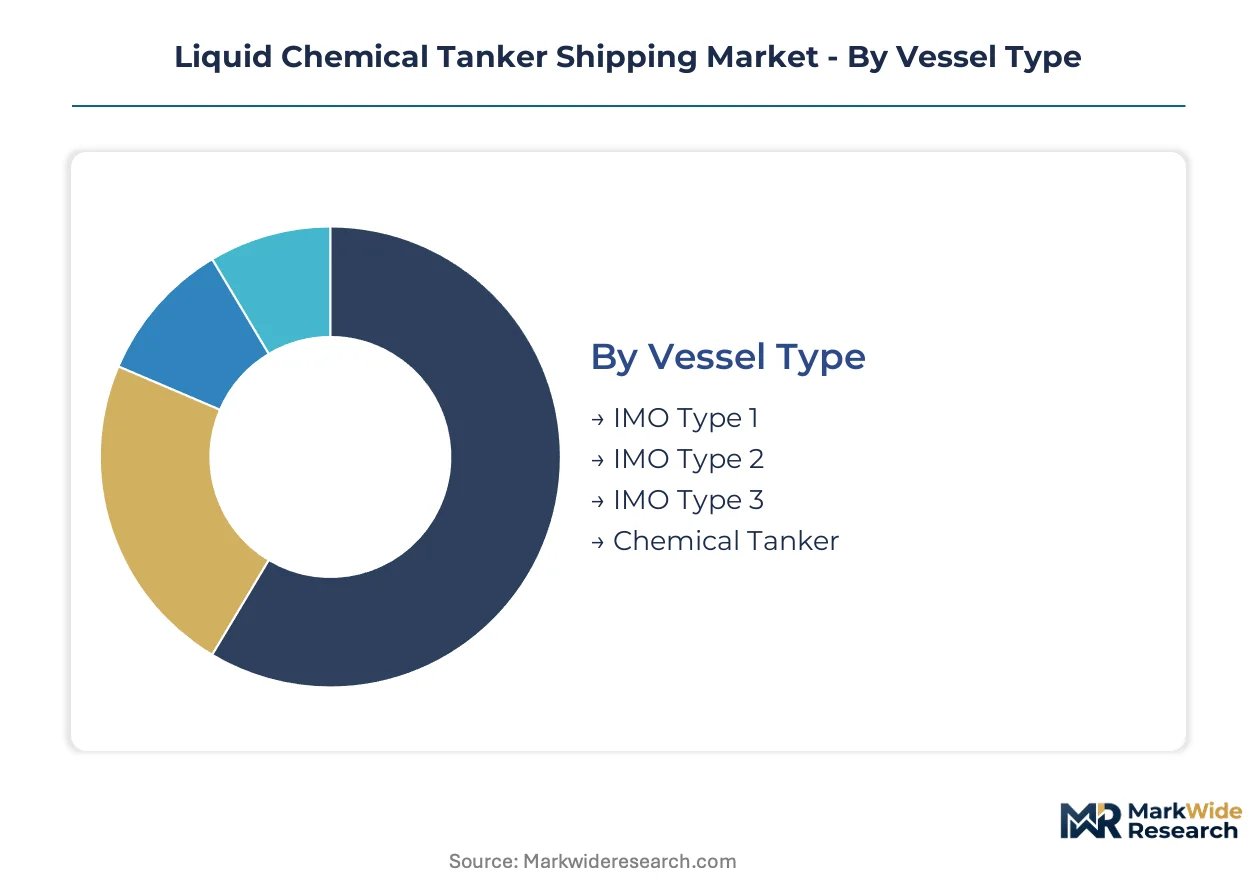
Chemical tanker segmentation determines asset allocation, charter rate structures, and compliance pathways across vessel specifications, cargo hazards, and contracting modes. Fleet managers match vessel certification tiers against cargo classification requirements while balancing time-charter coverage against spot market exposure.
Vessel Type:
Cycle times vary sharply across IMO certification tiers, with Type 1 vessels commanding longest charter durations and Type 3 seeing fastest spot turnover.
- IMO Type 1:Stainless-steel tank construction with double hull and most stringent safety architecture for high-hazard cargoes. German pharmaceutical manufacturers and Indian agrochemical formulators concentrate demand here for high-purity intermediates requiring zero contamination risk.
- IMO Type 2:Epoxy-coated or stainless tanks for medium-hazard chemicals with moderate cargo segregation requirements. The US Gulf Coast ethylene and methanol export corridor absorbs the largest share of this fleet segment at premium contract rates.
- IMO Type 3:Single-hull or double-hull mild steel construction for low-hazard bulk chemical transport with simplified tank cleaning protocols.
- Chemical Tanker:General-purpose vessels carrying IMO-certified chemical cargoes without specific hazard tier designation, often trading in regional coastal routes.
IMO Type 2 dominates installed base. IMO Type 1 is where expansion concentrates.
Cargo Type:
Margin profiles diverge by cargo chemistry, with petrochemicals delivering volume scale and specialty chemicals capturing rate premiums.
- Petrochemicals:Ethylene, methanol, and benzene movements form the volume backbone, with US Gulf Coast terminal expansions driving ton-mile demand.
- Specialty Chemicals:High-purity intermediates for pharmaceutical and agrochemical formulation. German manufacturers and Indian blenders are expanding import volumes fastest.
- Organic Chemicals:Glycol and alcohol trades from Singapore and Jubail to Rotterdam and Antwerp are climbing the fastest on Asia-Europe route expansion.
- Inorganic Chemicals:Sulfuric acid, caustic soda, and ammonia movements with standardized handling protocols and compressed rate spreads.
Petrochemicals anchor fleet deployment. Specialty chemicals command the steepest expansion trajectory.
End User:
Procurement sophistication varies by sector, with pharmaceutical buyers embedding carbon accounting and refiners optimizing for volume throughput.
- Chemical Manufacturers:Integrated petrochemical producers and specialty chemical formulators requiring dedicated parcel tanker services with cargo segregation capabilities.
- Oil Refiners:Downstream processors moving aromatic byproducts and intermediate feedstocks on flexible voyage-charter terms.
- Pharmaceutical Companies:German manufacturers consolidating contract volumes with logistics providers offering terminal-to-tanker emission verification under EU CSRD compliance frameworks.
- Food Processing:Edible oil and fatty acid transport with food-grade tank certification requirements and stringent cleaning protocols.
Chemical manufacturers represent the largest chartering base. Pharmaceutical companies are consolidating procurement fastest.
Operation Mode:
Contract duration structures segment risk allocation between vessel owners and cargo interests across freight market cycles.
- Time Charter:Multi-year vessel employment with owner retaining crew and technical management, preferred by Stolt-Nielsen for integrated logistics bundling.
- Voyage Charter:Single-trip freight contracts with spot rate exposure, compressing margins as digital platforms accelerate price discovery.
- Bareboat Charter:Long-term vessel lease with charterer assuming crew and operational responsibility, common in emerging market fleet expansion.
- Freight Forwarding:Non-vessel-operating intermediaries consolidating parcel shipments across multiple chemical tanker sailings.
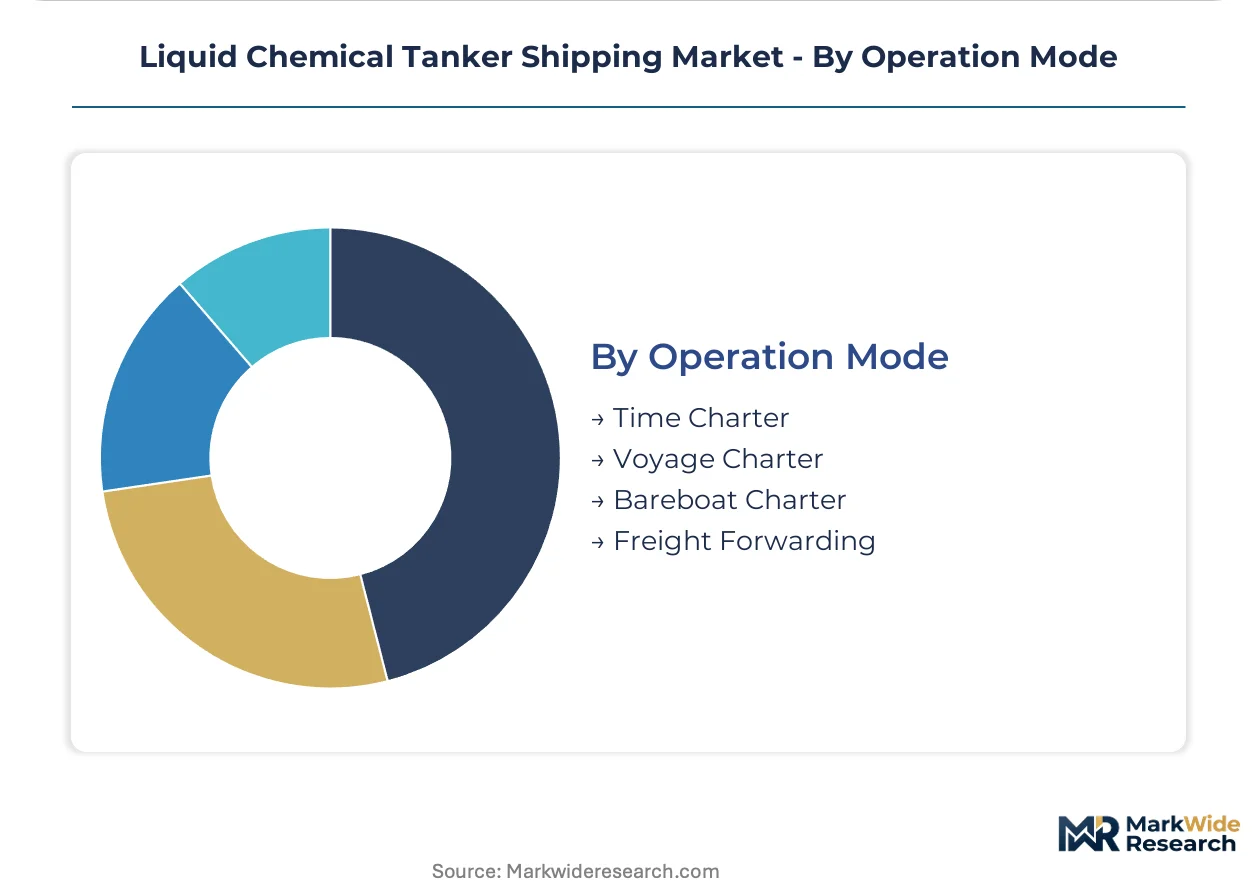
Voyage charter dominates spot market liquidity. Time charter is where contract coverage is concentrating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Charterers in Germany and the Netherlands demonstrate the lowest price elasticity, embedding emission verification clauses into multi-year contracts, while spot-market buyers along the US Gulf Coast exhibit acute sensitivity to freight rate swings.
United States
Ethylene and methanol export terminal expansions along the Texas-Louisiana corridor are absorbing coated-stainless chemical tanker capacity at premium rates. The Environmental Protection Agency enforces Clean Air Act standards that tighten vessel emission profiles in port zones. Houston-Galveston anchors the densest concentration of petrochemical export infrastructure, with new berth capacity coming online through 2026.
Germany
Pharmaceutical manufacturers in Ludwigshafen and Leverkusen are consolidating procurement with logistics providers offering terminal-to-tanker carbon accounting. The EU Green Deal's FuelEU Maritime initiative binds German ports to well-to-wake emission benchmarks. The Rhine-Ruhr chemical cluster demands IMO Type 1 stainless-steel architecture for high-purity intermediate transport.
India
Agrochemical formulators in Gujarat and Maharashtra are expanding import volumes for specialty chemical intermediates. The Directorate General of Shipping implements MARPOL Annex II compliance verification protocols for coastal chemical movements. Dahej and Mundra port complexes are underpenetrated by dedicated stainless-steel parcel tanker services, creating slot scarcity during peak formulation seasons.
Singapore
Glycol and alcohol transshipment volumes to Rotterdam and Antwerp are climbing fastest on Asia-Europe route expansion. The Maritime and Port Authority enforces emission reporting standards aligned with EU CSRD frameworks for vessels calling at Singapore terminals. Jurong Island's integrated petrochemical complex generates dense intra-Asian chemical tanker demand.
Saudi Arabia
Jubail Industrial City's methanol and benzene export capacity is pulling coated-stainless tonnage from Mediterranean and Asian fleets. The General Authority of Ports mandates International Maritime Organization certification compliance for chemical cargo handling. The Eastern Province's Ras Al-Khair complex is adding dedicated chemical jetty infrastructure to capture European and Indian charterer volumes.
Liquid Chemical Tanker Shipping Market Competitive Landscape
Capability concentration sits with integrated logistics providers; scale advantage sits with diversified tanker operators. The market structures around three tiers: full-service parcel carriers with terminal networks, stainless-steel specialists serving high-purity cargo segments, and refined-product flexible operators cross-trading into chemical lanes. Dominant competitive moves include fleet renewal toward dual-fuel methanol propulsion and terminal-tanker logistics bundling to displace spot-market fragmentation.
Among integrated logistics providers, Stolt-Nielsen Limited and Odfjell SE exemplify the terminal-to-tanker bundling archetype, while Scorpio Tankers Inc. occupies a position on the refined-product flexibility vector. These three entities represent distinct strategic postures: captive storage infrastructure, stainless-steel specialization, and asset class fungibility across clean petroleum and chemical trades.
| Leading Market Players |
|---|
| Navig8 Group |
| Scorpio Tankers Inc. |
| Stolt-Nielsen Limited |
| International Seaways Inc. |
| Ardmore Shipping Corporation |
| Odfjell SE |
| Hafnia |
| BW Group |
| MOL Chemical Tankers |
| Others |
Pricing and Supply Chain Analysis
The US Gulf Coast ethylene export corridor compresses freight margins through concentrated terminal ownership while generating rate premiums for stainless-steel vessels with MARPOL Annex II certification. Supply concentration among Korean and Chinese shipyards amplifies newbuild pricing power, forcing charterers into extended time-charter commitments to lock vessel slots.
Pricing Analysis
Extended service contracts and recertification bundling drive lifetime value differentiation across coated-steel and full stainless fleets. Three-tier pricing structure across premium, standard, and economy levels stratifies by IMO certification grade and cargo hazard tier, with Type 1 stainless vessels commanding spreads against epoxy-coated alternatives. Pricing pressure stems from digital cargo matching platforms accelerating spot-market transparency. Chemical manufacturers exhibit lowest price sensitivity, embedding multi-year emission verification clauses, while spot charterers along export corridors show acute elasticity.
Supply Chain Analysis
Export-control restrictions on advanced coating technologies and dual-fuel propulsion systems limit technology transfer to non-allied shipbuilding jurisdictions. Fleet renewal draws from South Korean, Chinese, and Japanese yard capacity, with nickel plate and marine-grade stainless steel feeding from Indonesian and Philippine smelter networks. Single-source vulnerability concentrates in East Asian construction clusters holding over seventy percent of orderbook slots. Distribution runs through integrated terminal operators bundling storage with vessel contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FuelEU Maritime carbon intensity benchmarks are disrupting charter procurement patterns, forcing fleet renewal decisions toward methanol dual-fuel architecture before compliance deadlines tighten.
For Market Incumbents: Entrench contract renewal advantages by deepening terminal-tanker logistics integration along the North Sea and US Gulf Coast corridors. Accelerate stainless-steel newbuild programs to preempt MARPOL Annex II certification eligibility losses for coated fleets. Lock Korean yard slots through 2028 delivery commitments before nickel price volatility inflates quotations further.
For New Entrants and Emerging Players: Establish a beachhead in India's Gujarat-Maharashtra agrochemical import corridor, where dedicated stainless-steel parcel tanker services remain underpenetrated. Target pharmaceutical formulators in Germany seeking terminal-to-tanker carbon accounting under EU CSRD frameworks. Lead with verified well-to-wake emission protocols to differentiate against spot-market incumbents.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified shipping conglomerates divesting non-core chemical tanker divisions to refocus on container or dry bulk segments. Long-term viability hinges on dual-fuel methanol exposure and European port call frequency. Watch for IMO Type 1 vessel orderbook acceleration as signal of charterer commitment to premium cargo segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Methanol Newbuild Program | FuelEU Maritime compliance secures Rotterdam and Antwerp access for EU-exposed charterers. |
| Terminal-Tanker Logistics Bundling | Integrated storage and vessel contracting displaces spot-market fragmentation in chemical trades. |
| Stainless-Steel Fleet Renewal | MARPOL Annex II revisions eliminate epoxy-coated vessel eligibility for high-grade chemical cargoes. |
| Digital Twin Coating Monitoring | Sensor arrays predicting epoxy failure compress off-hire periods for coated-steel fleets. |
| Carbon Accounting Integration | DNV and Lloyd's Register well-to-wake protocols enable EU CSRD-compliant shipper differentiation. |
Research Methodology
Initial hypotheses were tested against primary input from fleet managers, chartering executives, shipyard procurement leads, and marine chemist surveyors and refined through secondary validation across Lloyd's Register classification records, IMO MARPOL submission databases, EU CSRD disclosure filings, and customs trade data for chemical cargo movements. Bottom-up vessel deployment modeling triangulated against top-down trade flow analysis across petrochemical and specialty chemical corridors.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation modeling across IMO certification tier, cargo hazard classification, contracting mode, and regional port cluster. CAGRs derived from trade volume elasticities against petrochemical capacity expansion timelines, incorporating stainless-steel plate cost curves and FuelEU Maritime compliance pathway assumptions.
Macroeconomic conditions sit as an overlay; deviation in energy transition investment cycles or nickel supply disruptions would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation schedules and charterer sustainability procurement thresholds. Material shifts in IMO emission protocol timelines or dual-fuel engine technology cost curves would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
China less than-Truck-Load (LTL) Market
Logistics and Shipping
Jordan Freight and Logistics Market
Logistics and Shipping
Italy Cold Chain Logistics Market
Logistics and Shipping
Water Hauling Services Market
Logistics and Shipping
Mexico Freight Forwarding Market
Logistics and Shipping
Poland Cold Chain Logistics Market
Logistics and Shipping
Thailand E-Commerce Logistics Market
Logistics and Shipping
Germany Third-Party Logistics (3PL) Market
Logistics and Shipping
Germany Last Mile Delivery Market
Logistics and Shipping
North America Same Day Delivery Market
Logistics and Shipping
Intralogistics Containers Market
Logistics and Shipping
Spain Third-Party Logistics (3PL) Market
Logistics and Shipping
France Last Mile Delivery Market
Logistics and Shipping
Multi-Enterprise Logistics Contract and SLA Performance Management Platforms Market
Logistics and Shipping
Poland Freight and Logistics Market
Logistics and Shipping
Secure Logistics Market