
 Germany Last Mile Delivery Market | 2026-2036
Germany Last Mile Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Last Mile Delivery Market Foresight
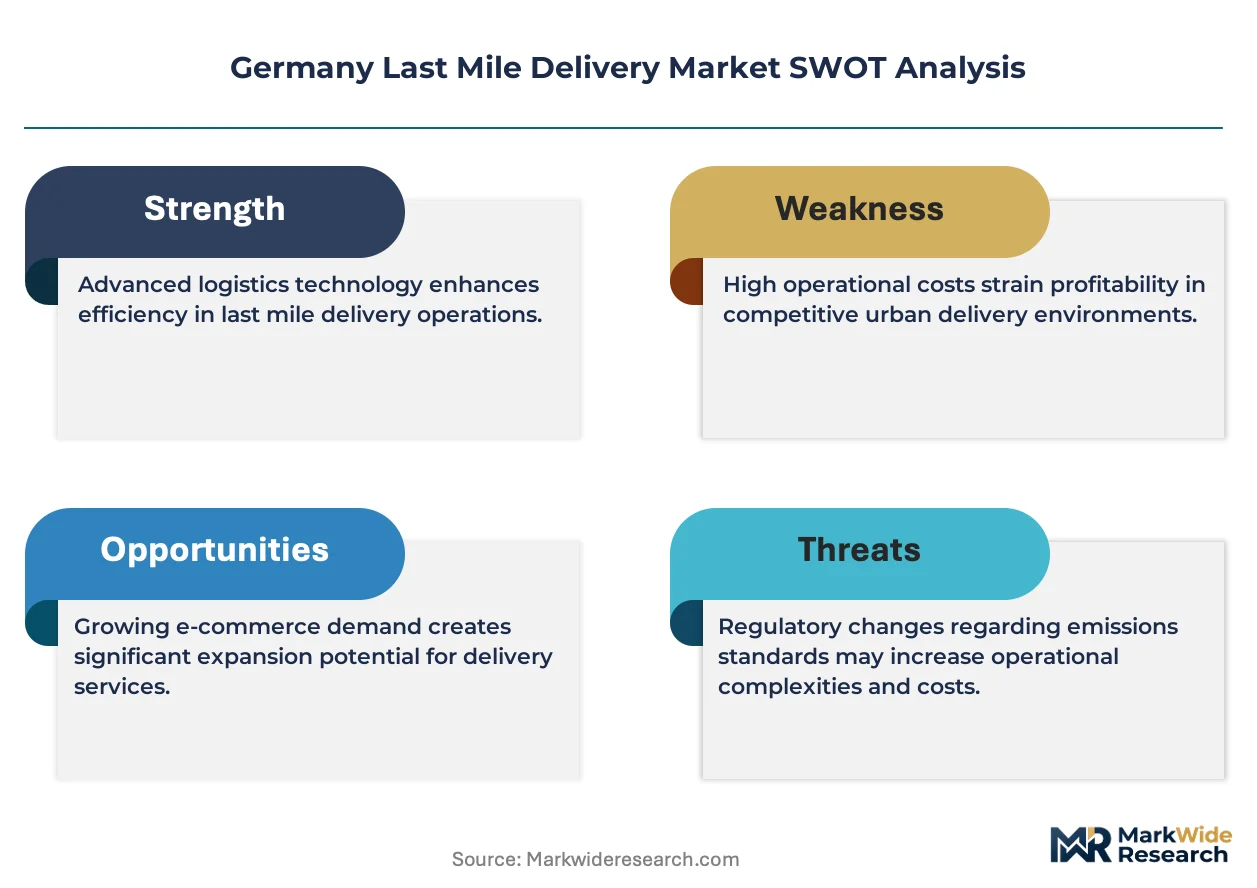
Modular bundling of click-and-collect with parcel locker access is repositioning how e-commerce retailers structure fulfillment contracts. Deutsche Post DHL Group leverages its Packstation network to anchor urban density coverage. Hermes competes through decentralized micro-depots in residential zones. DPD differentiates via proprietary routing software that optimizes multi-drop sequences.
Last mile delivery denotes the final transportation leg from distribution hub to end recipient, typically spanning under 50 kilometers and requiring real-time tracking integration, dynamic route optimization, and proof-of-delivery capture. Courier services dominate current volume flows while parcel lockers represent the fastest-growing delivery method due to lower per-drop labor costs and reduced redelivery incidence. E-commerce retailers command the largest customer segment spend, though small businesses are shifting scheduled delivery slots to off-peak windows.
The Kraftfahrt-Bundesamt enforces zero-emission vehicle mandates for commercial fleets in German city centers, while EU Green Deal targets accelerate electric van procurement timelines. REACH compliance and national packaging regulations from the Umweltbundesamt shape material standards for returnable containers and protective wrapping. Stakeholders must monitor regulatory tightening on urban access windows and vehicle emissions tiers to align fleet investment cycles with compliance deadlines.
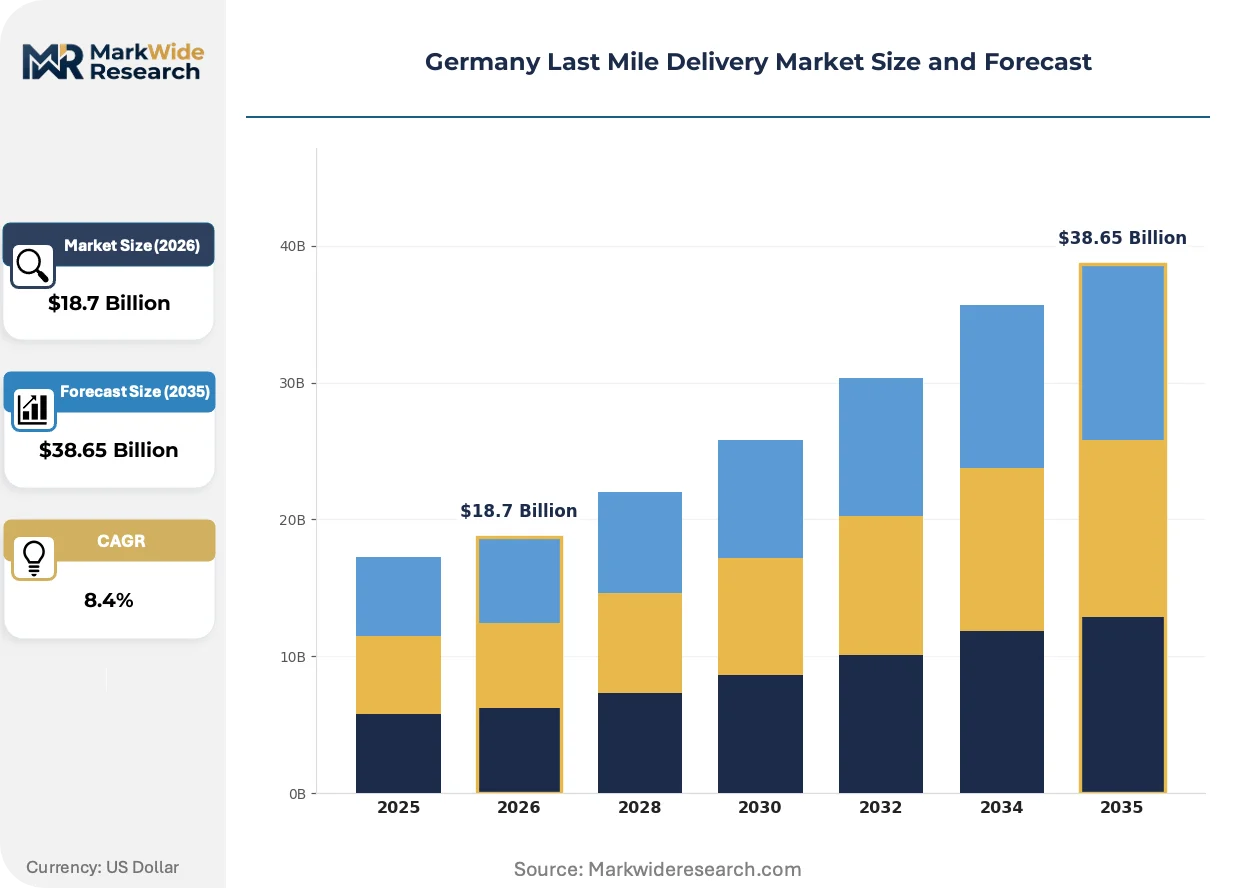
Market Dynamics
The EU Green Deal's zero-emission vehicle mandates are forcing fleet operators to accelerate electric van procurement while simultaneously reconfiguring depot locations around charging infrastructure availability.
Growth Catalysts
- Parcel locker network expansion:E-commerce retailers are deploying automated pickup points across Rhine-Ruhr metropolitan zones to eliminate failed delivery costs and reduce per-drop labor expenditure.
- Kraftfahrt-Bundesamt emission tiers:Commercial fleet regulations in German city centers are compressing diesel vehicle replacement timelines and redirecting capital toward electric powertrain procurement.
- Click-and-collect modular bundling:Retail fulfillment contracts now integrate locker access with in-store pickup, creating density economies in urban logistics networks.
Market Restraints
- Electric vehicle charging infrastructure gaps:Depot electrification requires grid capacity upgrades that lag vehicle procurement schedules in secondary German cities.
- Battery supply concentration:Lithium-ion cell production clusters in East Asian manufacturing hubs expose fleet operators to input cost volatility and supply chain disruption risks.
- Last-mile labor cost rigidity:Courier wage structures and union density in German urban logistics compress margin flexibility despite automation investments.
Strategic Opportunities
- Rhine-Ruhr micro-depot densification:Residential zone warehousing in Dortmund, Essen, and Düsseldorf enables sub-30-minute delivery radius coverage with reduced vehicle mileage.
- Dynamic route optimization software:Proprietary algorithm deployment for multi-drop sequencing creates service differentiation against competitors relying on static routing.
- Returnable packaging compliance:Umweltbundesamt material standards for protective wrapping and containers open circular economy service revenue streams.
Industry Challenges
- Electric vehicle technician scarcity:Fleet maintenance operations face skill gaps in high-voltage system diagnostics and battery management unit repair.
- Real-time tracking integration complexity:Legacy warehouse management systems require API reconfiguration to synchronize with customer-facing delivery notification platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Last Mile Delivery Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Method: Courier Services, Click & Collect, Parcel Lockers, Home Delivery Service Type: Same-Day Delivery, Next-Day Delivery, Scheduled Delivery, Standard Delivery Customer Segment: Consumers, E-commerce Retailers, Small Businesses, Enterprises Technology: Routing Software, Real-Time Tracking, Mobile Apps, Automated Warehousing |
| Companies Covered | DPD, FedEx Express, Deutsche Post DHL Group, Rhenus Logistics, DSV, Hermes, GLS, DB Schenker, UPS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Last Mile Delivery Market Shifts & Advancements
Route optimization algorithms are converging with parcel locker hardware to compress delivery density while regulatory pressure on urban emissions is accelerating powertrain technology substitution across German logistics networks.
Dynamic routing software is converging with automated locker systems to enable predictive drop sequencing based on real-time customer availability signals. Mid-sized logistics operators in Bavaria and Baden-Württemberg are piloting these integrated platforms ahead of national rollout. The technology is converging with existing fleet telematics to create closed-loop delivery networks that minimize redelivery incidence.
EU Green Deal national emissions targets are mandating zero-emission commercial vehicle fleets in urban logistics corridors by specified compliance deadlines. German operators must align procurement cycles with Kraftfahrt-Bundesamt enforcement timelines or face city center access restrictions. Battery-electric van segments are responding with accelerated leasing models that transfer residual value risk to OEM captive finance arms.
Scheduled delivery slot preferences are compressing toward off-peak windows as residential customers prioritize evening and weekend receipt over traditional business hours. E-commerce retailers are unbundling premium time-guarantee tiers from standard delivery offerings. This behavioral shift is most visible in Berlin and Hamburg apartment-dense districts where daytime absence rates exceed suburban and rural benchmarks.
Germany Last Mile Delivery Market Segmentation
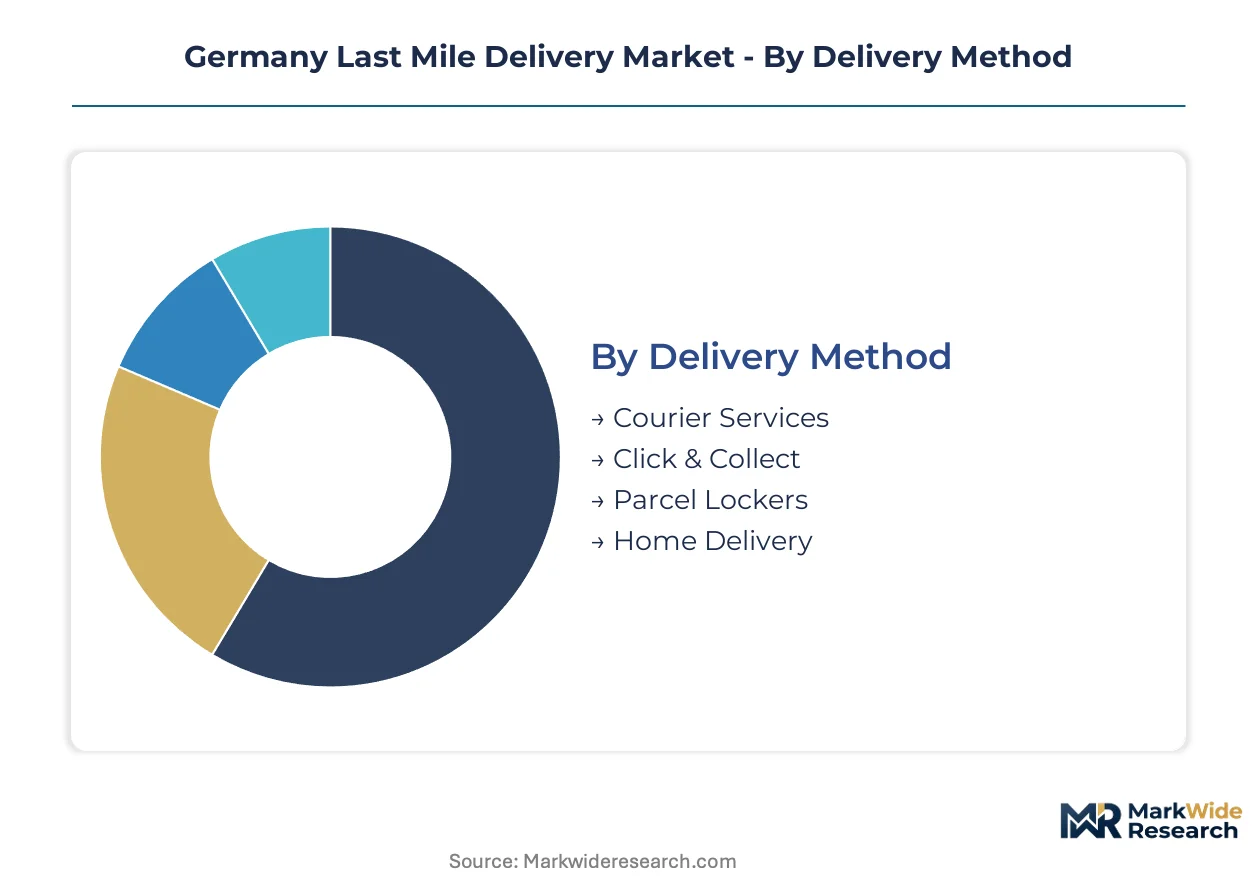
Segmentation in the Germany last mile delivery market reveals how service configuration, technology deployment, and customer contracting structures determine operational economics. Delivery method selection drives capital intensity and labor cost profiles. Service type tiering separates premium positioning from volume-driven standard offerings.
Delivery Method:
Technology integration and infrastructure density define competitive positioning across pickup and drop-off modalities.
- Courier Services:Human-operated vehicle fleets execute door-to-door handoff with signature capture and exception handling. Rhine-Ruhr metropolitan zones concentrate volume due to apartment density and commercial address clustering. Labor cost rigidity under German wage frameworks compresses margin flexibility despite route optimization software deployment.
- Parcel Lockers:Automated self-service terminals enable 24/7 retrieval with QR code or PIN authentication, eliminating redelivery costs and failed drop rates. Packstation networks anchor urban density coverage while micro-depot operators expand residential zone penetration. Capital expenditure for hardware and site leasing exceeds courier fleet models but per-drop labor costs fall substantially.
- Click & Collect:Retail-integrated pickup points combine online order fulfillment with physical store foot traffic capture. Modular bundling with parcel locker access creates density economies in urban logistics contracts.
- Home Delivery:Direct-to-doorstep service maintains premium positioning for bulky goods and time-guaranteed shipments. Evening and weekend slot preferences are compressing demand toward off-peak windows in Berlin and Hamburg apartment districts.
Mature deployment sits with courier services. Newer deployment is concentrated in parcel lockers.
Service Type:
Speed-to-delivery and scheduling precision separate pricing tiers and operational complexity levels.
- Same-Day Delivery:Order-to-doorstep fulfillment within hours requires micro-fulfillment center positioning and dynamic inventory allocation. Bavarian and Baden-Württemberg pilots test predictive drop sequencing ahead of national scaling.
- Next-Day Delivery:24-hour commitment windows balance customer expectation with consolidated sortation and line-haul efficiency. This tier captures the steepest expansion trajectory as e-commerce retailers unbundle premium guarantees from standard offerings.
- Scheduled Delivery:Customer-selected time slots prioritize convenience over speed, with off-peak evening and weekend windows gaining preference in residential zones. Small businesses are shifting scheduled slots to reduce failed delivery incidence.
- Standard Delivery:Unspecified 2-3 day windows optimize for network density and vehicle fill rates. Cost-sensitive volume flows through this tier with minimal customer communication overhead.
Volume concentration rests with standard delivery. Margin expansion concentrates in same-day and scheduled tiers.
Customer Segment:
Contract scale and delivery density requirements shape service level agreements and technology integration depth.
- E-commerce Retailers:High-volume shippers command dedicated capacity allocation and API-integrated order management systems. Fulfillment contract structures now modularize click-and-collect with parcel locker access.
- Consumers:Individual recipients drive scheduled slot preferences and real-time notification expectations. Residential daytime absence rates exceed suburban benchmarks, elevating locker and evening delivery demand.
- Small Businesses:Mid-tier shippers balance cost control with service reliability, increasingly selecting off-peak delivery windows to reduce per-shipment expenditure.
- Enterprises:Large corporate accounts require multi-location distribution and returns management integration with procurement systems.
Revenue concentration aligns with e-commerce retailers. Growth velocity favors small business segment expansion.
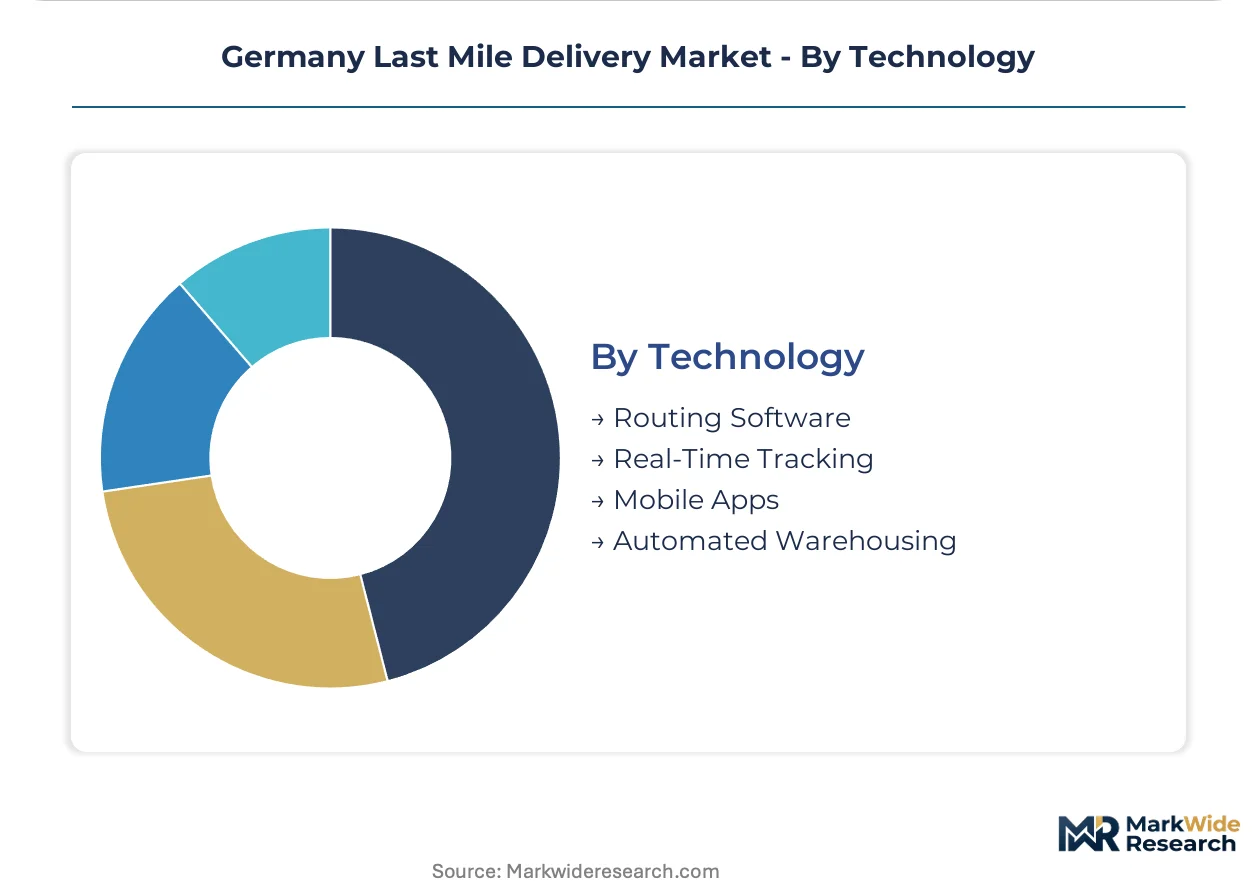
Technology:
Software and automation layers determine routing efficiency, customer experience, and warehouse throughput.
- Routing Software:Proprietary algorithms optimize multi-drop sequences against real-time traffic and customer availability signals. DPD and mid-sized Bavarian operators deploy differentiated platforms.
- Real-Time Tracking:GPS-telemetrics integration enables customer-facing delivery notifications and exception alerts. Legacy warehouse management systems require API reconfiguration for synchronization.
- Mobile Apps:Driver-facing interfaces capture proof-of-delivery, route deviations, and customer communication logs.
- Automated Warehousing:Robotic sortation and pick-to-light systems compress hub processing times for same-day and next-day service tiers.
Established deployment centers on routing software. Accelerated investment flows toward automated warehousing and real-time tracking integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German consumption outpaces domestic production capacity in last-mile infrastructure, creating import dependency on electric vehicle powertrains and battery systems from Asian manufacturing clusters.
North Rhine-Westphalia
The Rhine-Ruhr metropolitan corridor concentrates parcel volume flows through Dortmund, Essen, and Düsseldorf distribution nodes. Kraftfahrt-Bundesamt emission tier enforcement compresses diesel fleet replacement timelines in Cologne and Düsseldorf urban zones. Deutsche Post DHL Group anchors density coverage through Packstation networks across the Ruhr industrial belt.
Bavaria
Munich and Nuremberg logistics corridors drive same-day delivery pilot programs with predictive drop sequencing algorithms. Mid-sized operators test integrated routing-locker platforms ahead of national scaling. The Bavarian state government coordinates with federal regulators on zero-emission commercial vehicle procurement subsidies.
Baden-Württemberg
Stuttgart's automotive supplier density creates specialized B2B last-mile requirements for just-in-time component delivery. EU Green Deal national targets accelerate electric van leasing models through OEM captive finance arms. Karlsruhe and Mannheim micro-depots enable sub-30-minute delivery radius coverage for e-commerce fulfillment.
Berlin-Brandenburg
Apartment-dense districts in Berlin exhibit elevated daytime absence rates, elevating parcel locker and evening delivery demand. Umweltbundesamt packaging regulations shape returnable container service revenue streams for urban logistics operators. The capital region's off-peak delivery slot preferences compress toward weekend and evening windows.
Hamburg
Port-centric warehousing clusters in the Hamburg metropolitan area integrate maritime freight with last-mile distribution networks. Scheduled delivery preferences concentrate in residential zones along the Elbe corridor. Local operators deploy decentralized micro-depots to reduce vehicle mileage in the city-state's compact geography.
Germany Last Mile Delivery Market Competitive Landscape
The competitive structure tilts toward integrated postal-incumbent dominance with challenger specialization at the edges. Deutsche Post DHL Group commands density advantages through legacy infrastructure, while parcel locker specialists and courier platforms fragment residual share. Two strategic archetypes define positioning: network-scale incumbents leveraging fixed-asset density, and technology-differentiated challengers deploying proprietary routing algorithms. Dominant competitive moves include electrification-driven fleet renewal partnerships and micro-depot real estate acquisition in residential zones.
Among Germany-based logistics groups, Deutsche Post DHL Group, Hermes, and DPD occupy distinct competitive positions. Deutsche Post DHL Group exemplifies the infrastructure-anchored archetype through its Packstation network dominance. Hermes represents the decentralized challenger model with residential micro-depot penetration. DPD sits within the technology-differentiated tier, anchoring its position through proprietary multi-drop sequencing platforms.
| Leading Market Players |
|---|
| DPD |
| FedEx Express |
| Deutsche Post DHL Group |
| Rhenus Logistics |
| DSV |
| Hermes |
| GLS |
| DB Schenker |
| UPS |
| Others |
Supply & Pricing Matrix
E-commerce retailers' preference for off-peak delivery windows and automated pickup integration is compressing per-drop labor costs and forcing fleet operators to restructure service tiering around density economics rather than speed premiums.
Pricing Analysis
Margin tightening in standard delivery reflects diesel fleet phase-out timelines compressing under Kraftfahrt-Bundesamt emission tier enforcement. Pricing stratifies across premium time-guarantee, standard next-day, and economy locker-access tiers, with certification level for zero-emission vehicle compliance emerging as a key price differentiation driver. Cost-down pressure on scheduled delivery slots accelerates because residential customers prioritize evening and weekend receipt. Small businesses exhibit highest price sensitivity, while e-commerce retailers with volume commitments command lowest unit rates through dedicated capacity contracts.
Supply Chain Analysis
Workforce availability constraints in Chinese and South Korean lithium-ion cell manufacturing hubs are extending procurement lead times for German fleet electrification programs. Battery supply draws from concentrated East Asian production clusters, with lithium carbonate and nickel sulfate feedstocks subject to commodity price volatility. Single-source vulnerability in cathode material processing exposes operators to input cost spikes. Distribution runs through OEM captive finance arms offering residual value risk transfer on electric van leasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German last mile delivery is becoming a vertical-integration race, with players pursuing upstream control over charging infrastructure real estate to lock in depot positioning advantages.
For Market Incumbents: Deploy micro-depot densification in Rhine-Ruhr residential zones to anchor sub-30-minute delivery radius coverage against Hermes-style decentralized challengers. Deepen backward integration into parcel locker hardware manufacturing to reduce capital expenditure dependency on third-party terminal suppliers. Prioritize Packstation network expansion ahead of regulatory tightening on urban access windows. For New Entrants and Emerging Players: Capture white-space in Bavarian and Baden-Württemberg same-day delivery corridors where predictive routing-locker integration remains underdeveloped. Target small business scheduled delivery segment with off-peak window specialization and API-light integration. Lead with dynamic route optimization software as service differentiation against infrastructure-heavy incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with technology-differentiated mid-cap operators given EU Green Deal enforcement accelerating electric fleet procurement cycles. Long-term viability hinges on proprietary algorithm deployment and charging infrastructure access rights rather than vehicle asset ownership. Watch Kraftfahrt-Bundesamt emission tier advancement as signal for fleet replacement inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Depot Network Expansion | Residential zone warehousing in Dortmund and Düsseldorf enables sub-30-minute delivery radius with reduced vehicle mileage. |
| Electric Fleet Procurement Partnership | OEM captive finance leasing transfers residual value risk while aligning with Kraftfahrt-Bundesamt zero-emission mandates. |
| Proprietary Routing Software Deployment | Dynamic multi-drop sequencing algorithms differentiate service against competitors relying on static route planning. |
| Parcel Locker Hardware Integration | Automated terminal deployment eliminates redelivery costs and captures density economies in urban logistics contracts. |
| Returnable Packaging Compliance Service | Umweltbundesamt material standards open circular economy revenue streams through container and protective wrapping recovery. |
Research Methodology
Document review covered customs trade data, Kraftfahrt-Bundesamt fleet registration statistics, and EU Green Deal implementation directives, complemented by interviews with logistics operations directors, e-commerce fulfillment managers, electric vehicle procurement leads, and parcel locker network planners. Secondary validation drew from Deutsche Post DHL Group infrastructure disclosures, Hermes depot expansion announcements, and Umweltbundesamt packaging regulation filings. Bottom-up volume modeling triangulated against top-down market sizing from macroeconomic consumption indicators.
Cross-referencing historical fleet replacement cycles with panel input from logistics procurement executives shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include delivery method, service type tier, customer segment scale, and regional regulatory cluster. CAGRs derived from vehicle procurement pipeline analysis and parcel locker deployment trajectories. Forecast inputs incorporated charging infrastructure build-out schedules and emission tier enforcement timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery supply chain disruption and labor cost rigidity under German wage frameworks. Forecasts reflect documented assumptions on electrification subsidy continuity and urban access regulation trajectory. Material deviation in Kraftfahrt-Bundesamt enforcement pace or lithium-ion cell supply concentration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Russia Freight and Logistics Market
Logistics and Shipping
Kazakhstan Freight and Logistics Market
Logistics and Shipping
GCC Event Logistics Market
Logistics and Shipping
Outbound Logistics Market
Logistics and Shipping
Shipping Container Market
Logistics and Shipping
Colombia Freight and Logistics Market
Logistics and Shipping
Jordan Freight and Logistics Market
Logistics and Shipping
France Freight and Logistics Market
Logistics and Shipping
High-Tech Logistics Market
Logistics and Shipping
Freight Transport Management Market
Logistics and Shipping
Spain Freight and Logistics Market
Logistics and Shipping
North America Refrigerated Container Shipping Market
Logistics and Shipping
Global Automated Container Terminal Market
Logistics and Shipping
Global Courier Market
Logistics and Shipping
Third-Party Logistics (3PL) Market
Logistics and Shipping
Florida Freight and Logistics Market