
 France Last Mile Delivery Market | 2026-2036
France Last Mile Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
France Last Mile Delivery Market Foresight
Multi-source fleet contracting is repositioning how retailers secure last-mile capacity across French urban corridors. Colissimo anchors nationwide coverage through La Poste Group's postal infrastructure. Geopost dominates parcel consolidation via its European hub network. Chronopost competes on time-definite express lanes into Paris, Lyon, and Marseille.
France last mile delivery denotes the final transportation leg from distribution hub to end recipient, typically spanning 0-50 kilometers with delivery windows compressed to under four hours for express segments. Electric van deployment and route optimization algorithms reduce per-stop cost and emissions compliance burden in regulated zones. Same-day delivery commands premium positioning as consumer tolerance for wait times compresses. Contactless delivery sustained structural relevance post-pandemic, embedding signature-free handoff protocols across pharmaceutical and food service verticals. Automated dispatch systems now sit at the margin pool center, replacing manual fleet coordination in dense urban operations.
France's national environmental regulator enforces low-emission zone standards that restrict diesel van access in Paris, Lyon, and Grenoble city centers, directly shaping fleet composition decisions. ANSM oversees temperature-controlled pharmaceutical delivery protocols, mandating chain-of-custody documentation for last-mile vaccine and biologic distribution. CSRD disclosure requirements pressure logistics operators to report scope-three emissions from subcontracted courier networks. Stakeholders must monitor regulatory divergence between national decarbonization timelines and municipal enforcement intensity as electrification capex commitments lock in.
Market Dynamics
Fleet electrification mandates from France's national environmental regulator are compressing diesel vehicle replacement timelines while forcing capital reallocation toward charging infrastructure and battery leasing structures. Urban low-emission zones in Paris, Lyon, and Grenoble now block conventional van access during peak delivery windows.
Growth Catalysts
- CSRD disclosure requirements:Scope-three emissions reporting obligations push retailers to consolidate subcontractor networks into traceable, electrified fleets with verified carbon accounting.
- Pharmaceutical cold chain:ANSM temperature protocols for vaccine and biologic distribution mandate validated last-mile thermal packaging, creating specialized service tiers with premium positioning.
- Paris metropolitan density:Congestion pricing and restricted access zones concentrate same-day delivery demand into premium corridors where electric cargo bikes and micro-fulfillment nodes achieve cost parity.
Market Restraints
- Charging infrastructure gaps:Depot electrification requires grid connection upgrades that extend lead times 18-24 months in older Paris industrial zones.
- Battery supply concentration:European cell manufacturing capacity constraints force French operators into Asian supplier queues with volatile lithium carbonate pricing.
- Driver qualification thresholds:Heavy goods vehicle licensing requirements block flexible gig-economy recruitment for electric van fleets over 3.5 tonnes.
Strategic Opportunities
- Rural corridor electrification:Lyon-to-Marseille freight rail terminals offer intermodal handoff points for battery-swappable last-mile distribution into Provence-Alpes-Côte d'Azur.
- Automated dispatch convergence:Machine learning route optimization combined with real-time traffic APIs compresses per-stop labor minutes in dense urban cores.
- Contactless protocol permanence:Signature-free handoff standards institutionalized during pandemic response now extend to pharmaceutical and prepared food verticals with recurring subscription models.
Industry Challenges
- Telematics integration complexity:Legacy warehouse management systems require API middleware development to ingest real-time vehicle state-of-charge data for dynamic dispatch.
- Thermal packaging certification:ANSM validation cycles for insulated container designs extend 8-14 months, blocking seasonal service launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Last Mile Delivery Market |
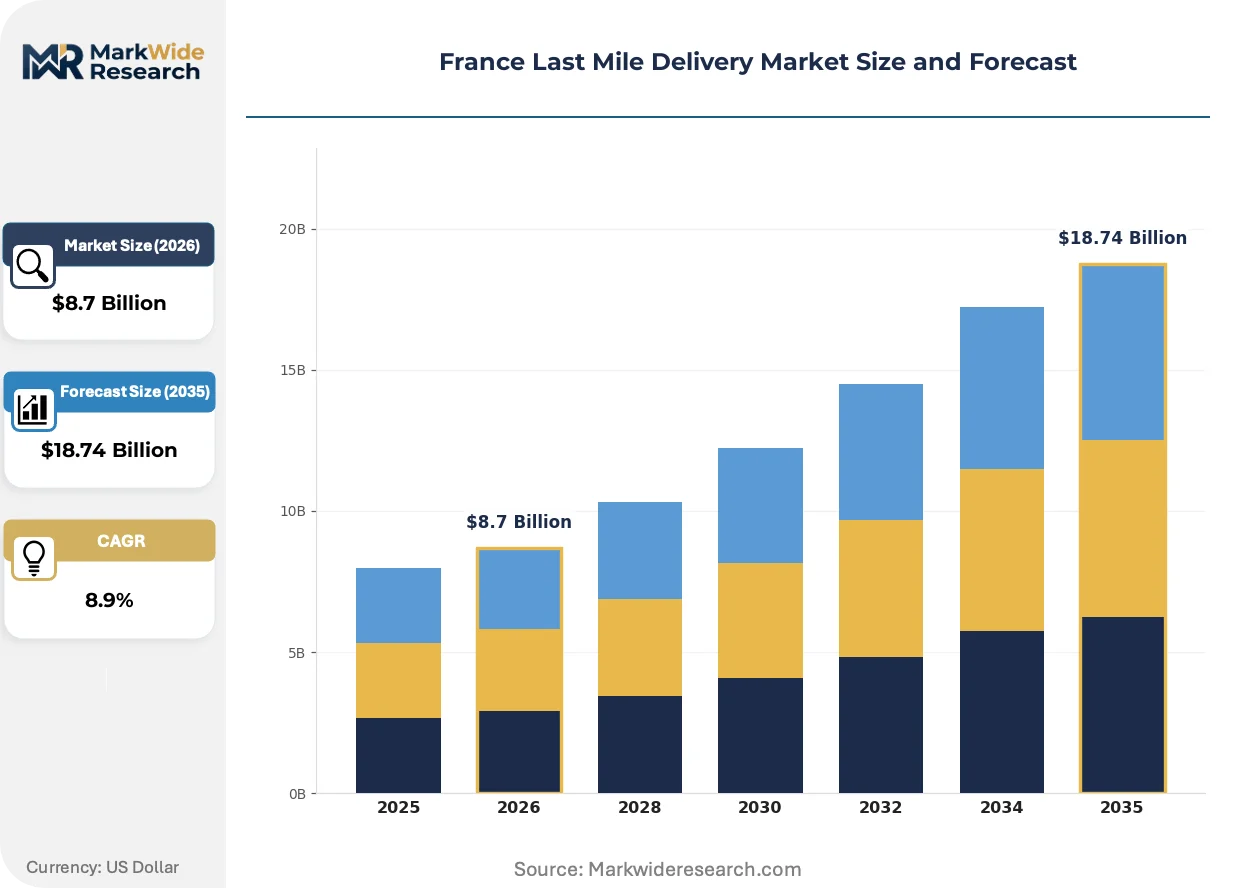
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $18.74 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Mode: Bike Courier, Electric Van, Drone Service, Walking Courier, Autonomous Vehicle Service Type: Same-Day Delivery, Next-Day Delivery, Scheduled Delivery, Contactless Delivery, Express Delivery End User: Retail Chains, E-Commerce Platforms, Food & Beverage Vendors, Pharmaceutical Providers, Electronics Suppliers Technology Integration: Route Optimization, Real-Time Tracking, Automated Dispatch, Customer Notification, Signature Capture |
| Companies Covered | Mondial Relay, UPS, Colissimo (La Poste Group), Geopost, FedEx, Chronopost, DHL Express, XPO Logistics, DPD France, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Last Mile Delivery Market Shifts & Advancements
Micro-fulfillment nodes and automated dispatch systems are compressing the physical and temporal distance between inventory positioning and customer handoff. Three interconnected developments are restructuring how capacity gets deployed and priced.
Dynamic route optimization software is decentralizing dispatch authority from centralized control towers to edge-computing devices mounted in electric vans. Major grocery and pharmaceutical distributors in the Paris basin are deploying these systems across 40% of fleet hours. The technology is decentralizing delivery network topology by enabling ad-hoc pickup consolidation without return-to-depot requirements.
France's national low-emission zone framework tightens diesel access restrictions annually through 2030, with municipal enforcement varying between Paris's total ban and Lyon's time-windowed tolls. Fleet operators must maintain dual-fuel capabilities during transition periods. Pharmaceutical and temperature-controlled food segments face the steepest compliance costs due to payload-sensitive vehicle selection constraints.
Subscription-based delivery memberships are displacing per-transaction pricing for urban consumers in Île-de-France and Auvergne-Rhône-Alpes. Retailers bundle unlimited same-day access with loyalty program tiers. Grocery and pet supply verticals show the fastest uptake, with membership penetration highest among households within 10 kilometers of micro-fulfillment centers.
France Last Mile Delivery Market Segmentation
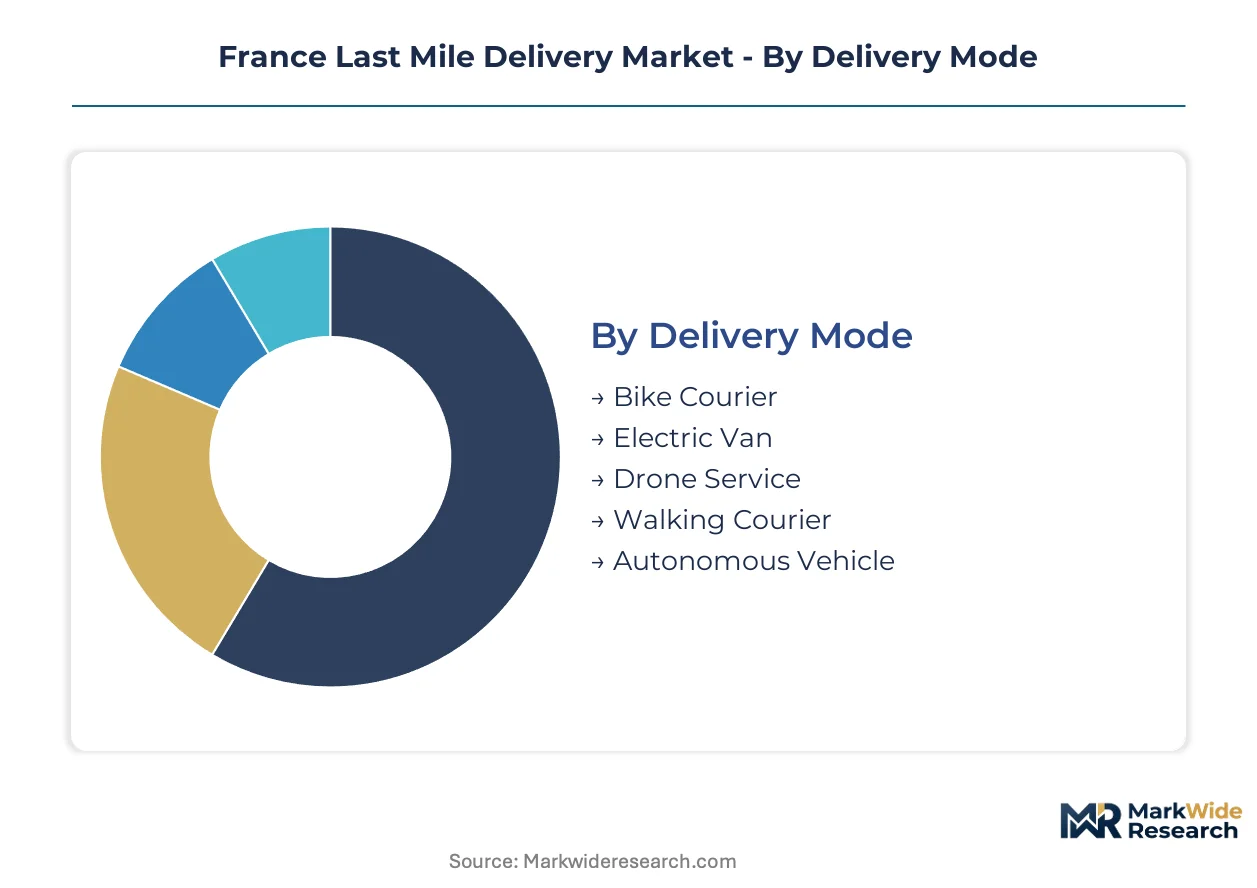
Segmentation in France's last mile delivery market reveals how capital allocation, regulatory compliance, and technology adoption diverge across operational models. Delivery mode selection directly determines electrification capex requirements, while service type stratification reflects urban density premiums and consumer tolerance compression.
Delivery Mode:
Capital intensity varies sharply across vehicle categories, with battery-electric platforms demanding depot infrastructure investment that cargo bike networks avoid entirely.
- Electric Van:Battery-powered commercial vehicles between 2.5 and 3.5 tonnes GVW carry the bulk of parcel volume in Paris and Lyon low-emission zones. Fleet operators face 18-24 month grid connection delays for depot charging, locking in diesel transition timelines. ANSM pharmaceutical mandates and CSRD scope-three reporting accelerate consolidation around traceable, electrified subcontractor networks.
- Bike Courier:Electric cargo bicycles with 150-300kg payload capacity achieve cost parity in Île-de-France congestion corridors under 5km radius. Micro-fulfillment node proximity determines viable catchment areas; subscription membership penetration concentrates within 10km of urban dark stores.
- Walking Courier:Pedestrian delivery operates in Paris arrondissements 1-4 with pedestrian-zone access privileges, serving prepared food and pharmaceutical verticals where handoff speed outweighs payload constraints.
- Drone Service:Beyond-visual-line-of-sight operations remain restricted by DGAC airspace regulations, limiting deployment to rural corridor trials between Lyon and Grenoble.
- Autonomous Vehicle:Street-legal robotic delivery units face municipal permitting fragmentation, with Paris testing restricted to designated innovation zones in the 15th arrondissement.
Electric van infrastructure absorbs the bulk of installed capacity; bike courier networks are expanding most quickly in dense urban cores.
Service Type:
Speed-based service tiers stratify pricing power and operational complexity, with same-day and express segments commanding premium positioning through time-definite guarantees.
- Same-Day Delivery:Four-hour fulfillment windows from order placement require micro-fulfillment inventory positioning and dynamic route optimization. Paris metropolitan density and congestion pricing create corridor-specific premiums where electric cargo bikes and van fleets achieve coverage overlap.
- Express Delivery:Two-hour time-definite lanes into Paris, Lyon, and Marseille rely on Chronopost and Geopost hub networks with dedicated sortation capacity. Pharmaceutical cold chain and electronics verticals drive demand for validated thermal packaging and chain-of-custody documentation.
- Next-Day Delivery:Colissimo postal infrastructure anchors nationwide coverage with economy positioning, leveraging La Poste Group's existing last-mile density for non-urgent parcel flows.
- Scheduled Delivery:Appointment-based windows concentrate in furniture and appliance verticals where recipient presence requirements conflict with gig-economy driver availability.
- Contactless Delivery:Signature-free handoff protocols institutionalized during pandemic response now extend to pharmaceutical and prepared food subscriptions with recurring delivery patterns.
Same-day and express delivery concentrate revenue per stop; contactless protocols are climbing fastest across subscription membership models.
End User:
Vertical-specific requirements reshape fleet composition, with pharmaceutical and food service segments imposing temperature control and documentation burdens that general parcel networks avoid.
- Pharmaceutical Providers:ANSM temperature-controlled protocols mandate validated thermal packaging and real-time chain-of-custody tracking for vaccine and biologic distribution. Insulated container certification cycles extend 8-14 months, blocking seasonal service launches and concentrating market share among pre-qualified operators.
- Food & Beverage Vendors:Prepared meal and grocery subscriptions drive electric cargo bike deployment in Paris and Lyon urban cores, where congestion pricing and parking scarcity favor two-wheeled payload capacity.
- E-Commerce Platforms:Multi-source fleet contracting splits volume between Geopost consolidation hubs, Colissimo postal coverage, and Chronopost express lanes based on delivery speed tier.
- Retail Chains:Click-and-collect integration with store inventory positions same-day fulfillment without dedicated warehousing, though ANSM restrictions block pharmacy retail from generalist courier networks.
- Electronics Suppliers:High-value parcel security requirements favor signature capture technology and real-time tracking integration, with express delivery premiums justified by replacement cost exposure.
Pharmaceutical and food service verticals absorb specialized fleet investment; e-commerce platforms are gaining share fastest through subscription membership bundling.
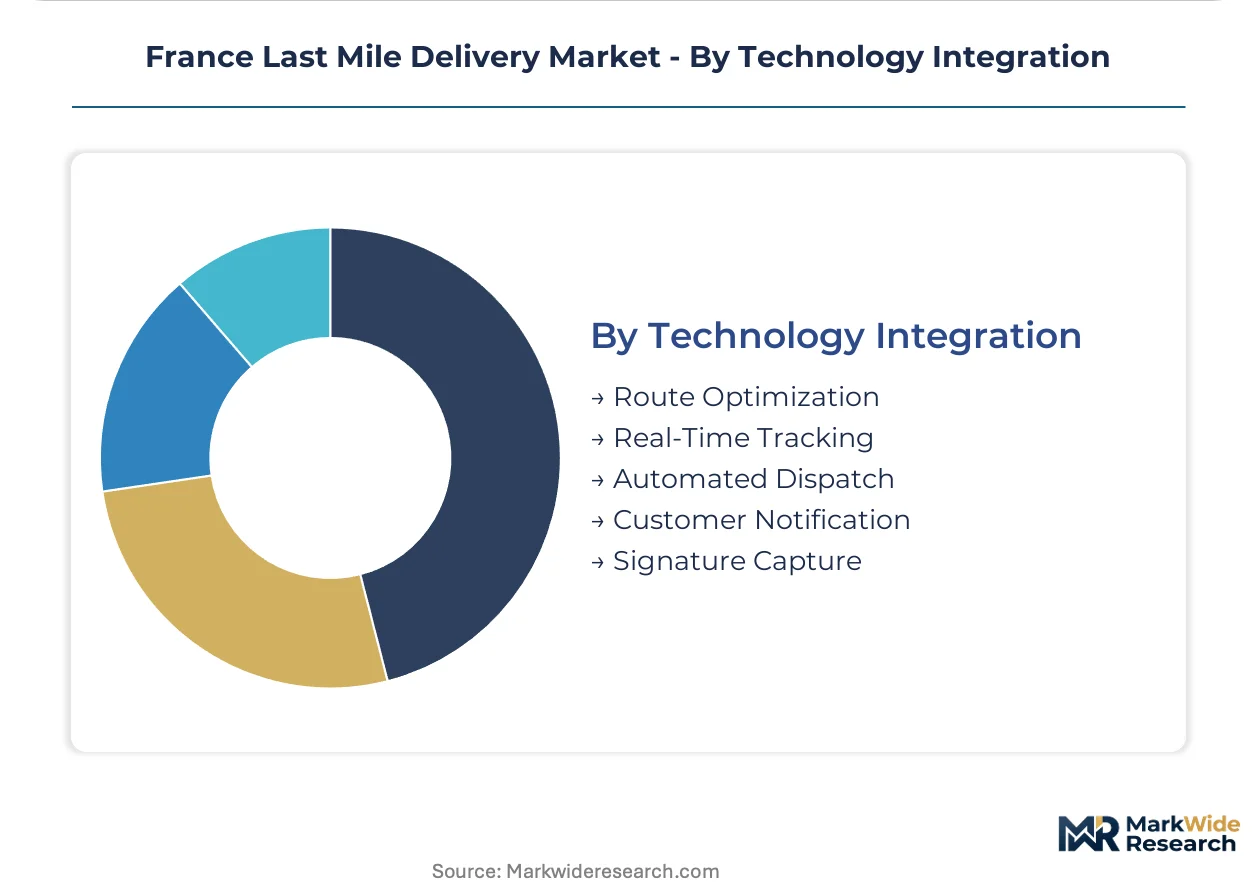
Technology Integration:
Software stack selection determines dispatch efficiency and regulatory compliance traceability, with automated systems displacing manual coordination in dense urban operations.
- Automated Dispatch:Machine learning route optimization combined with real-time traffic APIs compresses per-stop labor minutes, with Paris basin grocery and pharmaceutical distributors deploying across 40% of fleet hours.
- Route Optimization:Edge-computing devices mounted in electric vans decentralize dispatch authority from centralized control towers, enabling ad-hoc pickup consolidation without return-to-depot requirements.
- Real-Time Tracking:GPS telematics integration with warehouse management systems requires API middleware development to ingest vehicle state-of-charge data for dynamic dispatch decisions.
- Customer Notification:Predictive arrival windows reduce failed delivery rates in apartment-dense Paris arrondissements where concierge access varies by building.
- Signature Capture:Digital proof-of-delivery systems remain required for high-value electronics and pharmaceutical controlled substances, though contactless alternatives displace them in general parcel flows.
Automated dispatch and route optimization anchor operational investment; real-time tracking integration is expanding most quickly under CSRD emissions reporting pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France's logistics density anchors French last-mile infrastructure, with the Paris metropolitan area concentrating depot networks, micro-fulfillment nodes, and electric van charging clusters that shape national capacity allocation.
Île-de-France
Congestion pricing in Paris arrondissements 1-4 accelerates electric cargo bike deployment for prepared food and pharmaceutical subscriptions. ANSM temperature-control mandates concentrate specialized cold-chain operators in Saint-Denis logistics parks. La Poste Group's Colissimo hub at Roissy-Charles de Gaulle anchors nationwide parcel consolidation with dedicated express sortation for same-day corridors.
Auvergne-Rhône-Alpes
Lyon's time-windowed low-emission zone tolls force dual-fuel fleet transitions during peak delivery windows. Geopost's European hub network leverages Lyon-Saint-Exupéry freight terminals for intermodal handoffs into Alpine corridors. Battery-swappable van trials operate between Lyon Part-Dieu and Grenoble city centers under municipal innovation permits.
Provence-Alpes-Côte d'Azur
Marseille's port-centric logistics absorbs sea freight from North African manufacturing zones into regional distribution. Chronopost maintains dedicated express lanes from Lyon freight rail terminals into Aix-en-Provence micro-fulfillment nodes. DGAC airspace restrictions block drone deployment beyond rural corridor trials toward Grenoble.
Hauts-de-France
Lille's cross-border e-commerce volume from Belgian and Dutch platforms drives demand for bilingual delivery confirmation systems. DPD France operates depot electrification pilots near the Channel Tunnel freight terminal to capture UK-originated parcel flows. CSRD scope-three reporting pressures retailers to consolidate subcontractor networks into traceable fleets.
Nouvelle-Aquitaine
Bordeaux's wine export logistics infrastructure repurposes temperature-controlled warehousing for pharmaceutical cold-chain distribution. Rural delivery density gaps exceed 15 kilometers between micro-fulfillment nodes, preserving next-day postal economics over same-day premiums. Automated dispatch deployment lags Paris basin adoption by approximately 18 months.
France Last Mile Delivery Market Competitive Landscape
Global express networks compete with postal incumbents and regional specialists across speed-tier positioning and electrification compliance. Market structure tilts toward consolidated hub-and-spoke operators with dedicated sortation capacity, while fragmented bike-courier networks capture hyperlocal density premiums. Three archetypes dominate: legacy postal groups with nationwide coverage, global integrators with time-definite express lanes, and urban micro-fulfillment specialists. Competitive moves center on depot electrification partnerships and automated dispatch licensing.
Within the postal-incumbent tier, Colissimo and Chronopost exemplify state-affiliated infrastructure leverage against private capital. Global integrators DHL Express and FedEx occupy premium express positioning anchored by international hub connectivity. Among regional specialists, Mondial Relay and DPD France represent consolidation plays for suburban and cross-border parcel density. XPO Logistics sits within the contract logistics archetype, offering fleet outsourcing to retailers avoiding direct electrification capex.
| Leading Market Players |
|---|
| Mondial Relay |
| UPS |
| Colissimo (La Poste Group) |
| Geopost |
| FedEx |
| Chronopost |
| DHL Express |
| XPO Logistics |
| DPD France |
| Others |
Supply & Pricing Matrix
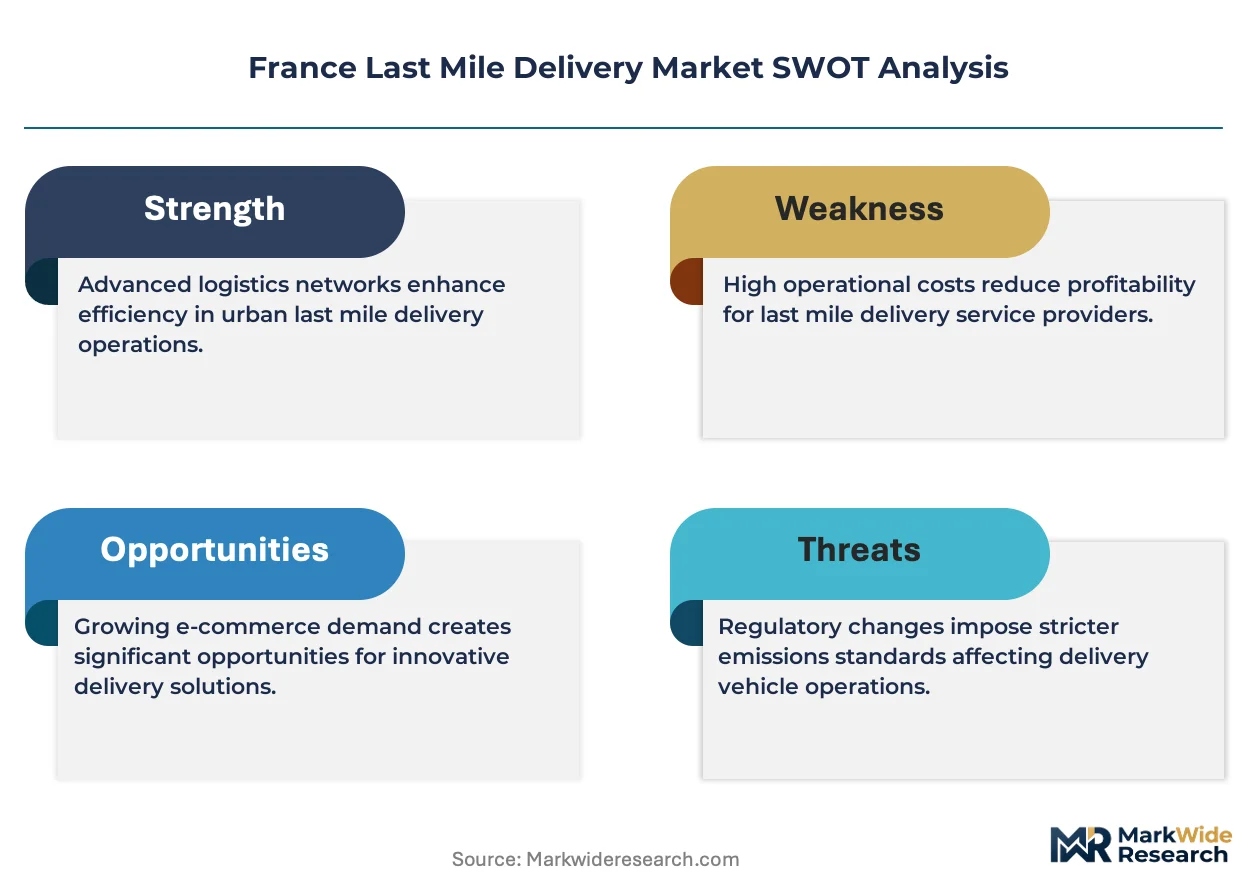
Postal-sovereign infrastructure operators anchor France's last-mile capacity, with La Poste Group's state-backed balance sheet enabling below-market electrification capex that private couriers cannot match. This ownership pattern concentrates pricing power in premium express corridors while forcing independent operators toward subscription bundling and micro-fulfillment partnerships to defend margin structures.
Pricing Analysis
Service bundling separates subscription memberships from per-transaction pricing across French urban corridors. Three-tier pricing structure across premium, standard, and economy levels stratifies around speed guarantees and ANSM certification status. Cost compression in express tiers is intensifying because Geopost and Chronopost hub investments create fixed-cost leverage. E-commerce platforms show highest price sensitivity, while pharmaceutical providers absorb premium positioning for validated cold-chain documentation.
Supply Chain Analysis
Domestic-content mandates under France's national decarbonization framework restrict diesel van procurement to EU-manufactured electric platforms, reshaping fleet sourcing toward Renault and Stellantis production. Battery cell supply draws from South Korea and China, with European cell manufacturing capacity constraints extending procurement queues. Single-source vulnerability concentrates in lithium carbonate processing. Distribution runs through depot-based hub networks with micro-fulfillment node satellite positioning in Paris and Lyon density corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's last-mile delivery sector sits in a fleet-electrification transition phase, with battery-electric vans displacing diesel platforms under low-emission zone mandates. Automated dispatch systems are replacing manual control-tower coordination as the dominant operational technology.
For Market Incumbents: Extend depot electrification partnerships with grid operators to secure 18-24 month connection timelines before competitors lock capacity. Consolidate subcontractor networks into traceable fleets to preempt CSRD scope-three reporting exposure. Vertical integration into battery leasing structures defends against Asian cell supply volatility.
For New Entrants and Emerging Players: The gap between premium express and economy postal pricing in Provence-Alpes-Côte d'Azur rural corridors offers white-space entry. Target Bordeaux pharmaceutical cold-chain distribution where ANSM certification barriers block generalist competitors. Deploy bike-courier networks with subscription membership bundling as the go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with pre-qualified ANSM thermal packaging in Auvergne-Rhône-Alpes. Five-to-ten year viability hinges on automated dispatch software licensing revenue streams. Watch DGAC drone regulation relaxation as the inflection signal for autonomous delivery capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Depot Electrification Partnership | Grid connection priority secures charging capacity ahead of 18-24 month lead times in Paris industrial zones. |
| Automated Dispatch Licensing | Machine learning route optimization generates recurring revenue from grocery and pharmaceutical distributors. |
| ANSM Thermal Packaging Certification | Validated cold-chain documentation blocks seasonal entrants and concentrates pharmaceutical market share. |
| Micro-Fulfillment Node Expansion | Dark store proximity within 10 kilometers enables subscription membership penetration in dense urban cores. |
| Battery Leasing Structure Development | Captive financing reduces exposure to volatile lithium carbonate pricing from Asian suppliers. |
Research Methodology
Multi-period observation of fleet electrification deployment rates, low-emission zone compliance timelines, and subscription membership penetration anchored the trend analysis, supplemented by interviews with logistics depot managers, pharmaceutical supply chain directors, e-commerce platform operations leads, and ANSM regulatory affairs specialists. Secondary validation drew from DGAC airspace filings, CSRD disclosure frameworks, La Poste Group infrastructure reports, and European battery supply chain databases. Bottom-up fleet deployment modeling triangulated against top-down e-commerce volume projections.
Input-output matrix mapping connected vehicle category adoption curves to service tier demand elasticity across delivery mode, speed guarantee, and end-user vertical dimensions. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic consumption indicators. Forecast inputs included municipal low-emission zone enforcement calendars and pharmaceutical cold-chain certification pipeline data across the projection horizon.
Inputs from DGAC regulatory filings and ANSM validation cycle records were available through the study window; gaps in real-time battery supply chain pricing introduce uncertainty bands around electrification capex assumptions. Forecasts reflect documented assumptions regarding municipal enforcement intensity and grid connection approval velocities. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Air Cargo Container Market
Logistics and Shipping
China Shipping Agency Services Market
Logistics and Shipping
United Kingdom Third Party Logistics (3PL) Market
Logistics and Shipping
Indonesia Cold Chain Logistics Market
Logistics and Shipping
Bangladesh Contract Logistics Market
Logistics and Shipping
Hazardous Goods Logistics Market
Logistics and Shipping
Vietnam Logistics Market
Logistics and Shipping
Europe Chemical Logistics Market
Logistics and Shipping
Latin America Fourth Party Logistics (4PL) Market
Logistics and Shipping
China Third-Party Logistics (3PL) Market
Logistics and Shipping
Multi-Enterprise Logistics Contract and SLA Performance Management Platforms Market
Logistics and Shipping
Germany Contract Logistics Market
Logistics and Shipping
Uruguay Freight and Logistics Market
Logistics and Shipping
LAOS Freight and Logistics Market
Logistics and Shipping
Contract Logistics Market
Logistics and Shipping
Canada Cold Chain Logistics Market