
 Ready Mix Joint Compound Market | 2026-2036
Ready Mix Joint Compound Market Size, Share, and Industry Trends Forecast 2026-2036
Ready Mix Joint Compound Market Outlook
Software-defined inventory management and digital ordering platforms is repositioning how ready mix joint compound reaches job sites. USG leverages its distribution network to sustain contractor loyalty across major metropolitan corridors. Knauf Gips KG anchors European supply through gypsum-adjacent manufacturing scale. Georgia Pacific competes on brand recognition and channel density in residential construction.
Ready mix joint compound is a pre-blended vinyl or acrylic-latex modified gypsum paste, typically supplied in pails at 60-75% solids content, designed for sealing drywall seams and embedding joint tape without on-site water addition. All-purpose compound dominates contractor workflows for its versatility across finishing and texturing applications, while lightweight compound captures margin pools through reduced freight costs and improved worker handling. Setting-type compound occupies a specialized niche where rapid cure cycles justify premium positioning in commercial repair schedules.
OSHA enforces permissible exposure limits on respirable crystalline silica during sanding operations, compelling manufacturers toward dust-controlled formulations. EPA VOC regulations under the National Volatile Organic Compound Emission Standards constrain solvent content in acrylic-modified products. ISO 9001 quality management systems and ASTM C475 joint treatment standards govern batch consistency and performance certification. Stakeholders must monitor evolving state-level low-VOC mandates and weigh reformulation investments against regional specification requirements.
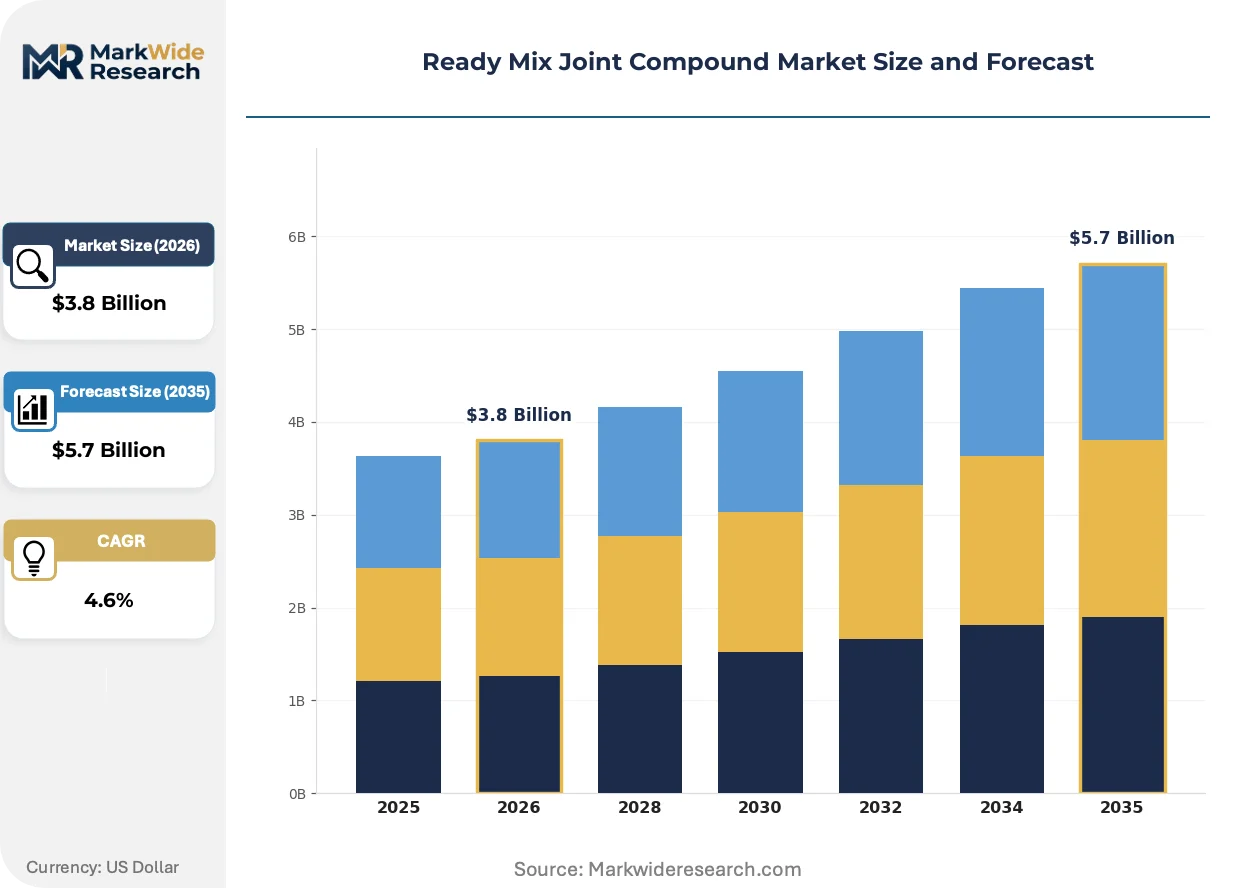
Market Dynamics
Lightweight ready mix joint compound is overtaking traditional heavyweight formulations as residential and commercial contractors prioritize freight economics and worker safety. This material transition, accelerated by silica exposure regulations, is compressing legacy product margins while redistributing volume toward reformulated alternatives.
Growth Catalysts
- OSHA Silica Limits:The agency's tightened permissible exposure limits on respirable crystalline silica during sanding operations are compelling contractors toward dust-controlled lightweight formulations that reduce airborne particulate generation.
- Commercial Repair Schedules:Rapid-cure setting-type compounds are capturing premium positioning in commercial maintenance workflows where compressed downtime windows justify higher material costs.
- Digital Ordering Platforms:Software-defined inventory management systems are repositioning procurement patterns, enabling just-in-time delivery to metropolitan job sites and reducing contractor working capital requirements.
Market Restraints
- Gypsum Input Volatility:Synthetic gypsum supply from flue-gas desulfurization depends on coal-fired power generation trends, creating raw material uncertainty for compound manufacturers concentrated in specific production corridors.
- Freight Cost Sensitivity:Water-weighted pail products face inherent distribution radius limitations, constraining market expansion for producers without regional manufacturing presence.
- Acrylic-Latex Substitution:Advanced tape systems and spray-applied alternatives are encroaching on traditional joint treatment workflows in high-volume commercial drywall installations.
Strategic Opportunities
- Underpenetrated Retrofit Segment:Aging commercial building stock in the United States presents untapped demand for repair-grade compounds formulated for adhesion to existing painted surfaces and plaster substrates.
- EPA VOC Tailwinds:State-level low-VOC mandates beyond federal National Volatile Organic Compound Emission Standards are creating specification advantages for early reformulators with compliant product portfolios.
- Prefabrication Convergence:Offsite construction modules and panelized wall systems require factory-applied joint treatment, opening channel partnerships with modular building manufacturers.
Industry Challenges
- ASTM C475 Certification Timelines:Batch consistency validation and performance certification under joint treatment standards create extended product development cycles that delay market entry for reformulated lines.
- Skilled Finisher Shortage:Experienced drywall contractors capable of achieving Level 5 finish specifications are becoming scarcer, pressuring manufacturers to develop more forgiving application properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready Mix Joint Compound Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-Purpose Compound, Topping Compound, Setting-Type Compound, Lightweight Compound Application: Drywall Finishing, Texturing, Repairing, Seaming End User: Construction Contractors, DIY Enthusiasts, Commercial Builders, Residential Builders Form: Ready-Mixed, Powdered, Spray, Cartridge |
| Companies Covered | Dow Inc., Knauf Gips KG, USG, ASG, DAP Products Inc., Compagnie de Saint-Gobain, Georgia Pacific, Everbuild, National Gypsum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready Mix Joint Compound Market Strategic Shifts
Material science advances and regulatory compliance requirements are converging to transform product formulation priorities. Manufacturers are investing in density reduction and dust suppression technologies while navigating evolving chemical content restrictions.
Lightweight microsphere technology is overtaking traditional perlite and expanded shale fillers as the dominant density-reduction approach in premium compound formulations. Residential builders in high-volume markets are specifying these products for multi-story projects where manual handling frequency amplifies worker fatigue costs. The structural consequence is margin compression for producers unable to source specialized filler supply chains or achieve comparable performance at equivalent weight reduction.
EPA enforcement of National Volatile Organic Compound Emission Standards is constraining solvent content in acrylic-modified ready mix products. Manufacturers serving California and Northeast corridor markets face overlapping state-level low-VOC mandates that exceed federal thresholds, forcing parallel inventory management. The segment most affected is all-purpose compound, where reformulation to maintain workability without elevated solvent levels requires binder system innovation.
Contractor buying patterns are consolidating around integrated material suppliers capable of bundling joint compound with drywall, fasteners, and finishing tools. Large metropolitan drywall contractors are reducing vendor counts to simplify procurement administration and leverage volume rebates. This concentration is most visible in Sun Belt metropolitan corridors where commercial construction activity sustains sufficient volume to support dedicated distribution infrastructure.
Ready Mix Joint Compound Market Segmentation
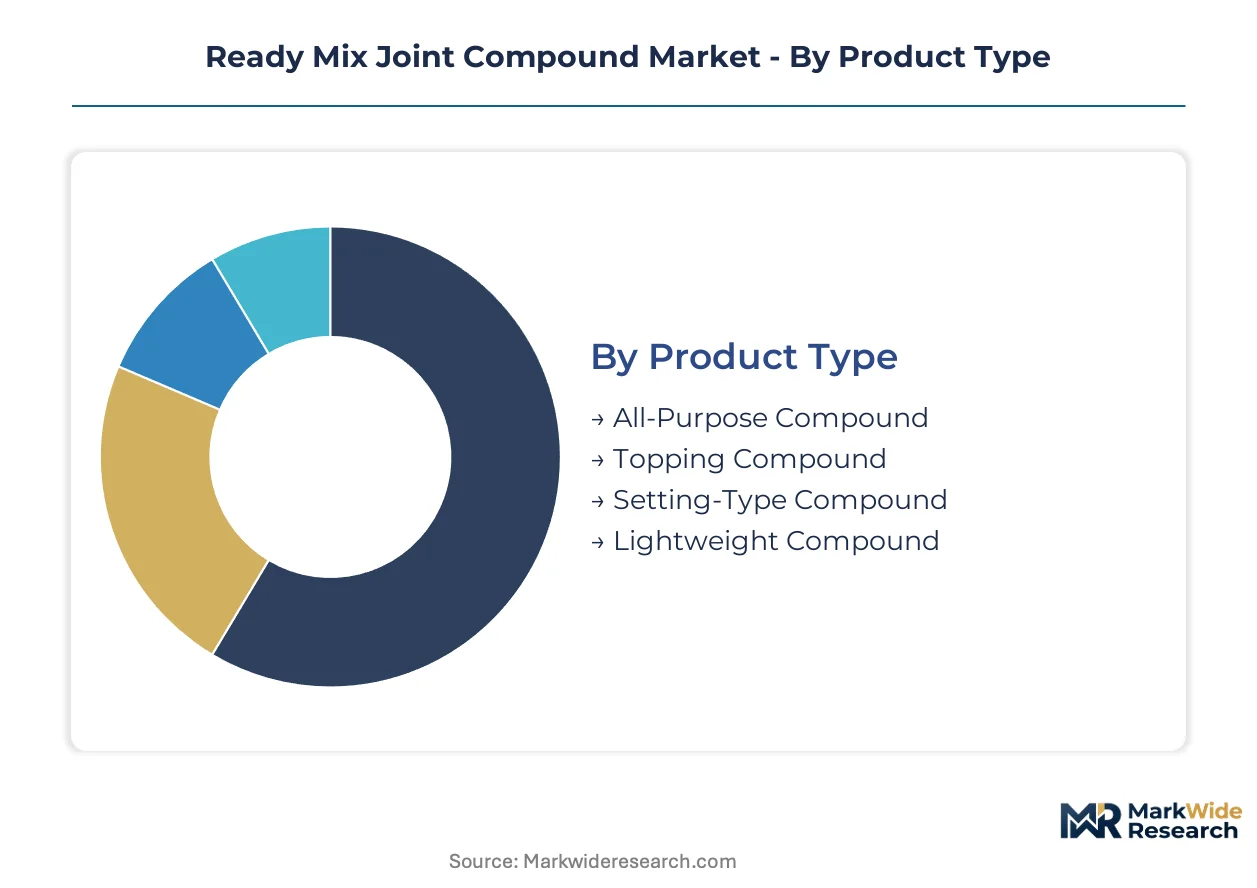
Segmentation in ready mix joint compound reveals how product specifications align with distinct workflow economics. Contractors select formulations based on cure speed, density, and finish requirements rather than brand preference alone.
Product Type:
Upgrade cycles from traditional heavyweight formulations toward specialized alternatives are shortening as silica regulations and freight costs reshape contractor specifications.
- All-Purpose Compound:A vinyl-modified gypsum paste formulated for embedding tape, finishing, and texturing without product switching. Residential builders in the United States specify this grade for single-family tract housing where crew productivity depends on material versatility across application stages. OSHA silica exposure limits are compressing margins for legacy heavyweight versions while rewarding dust-controlled reformulations.
- Lightweight Compound:Microsphere-filled formulations achieving 25-30% density reduction against traditional compounds through expanded perlite or glass bubble integration. Commercial contractors in high-rise metropolitan corridors prioritize this grade for reduced worker fatigue and lower per-unit freight costs on multi-story projects. EPA VOC constraints on acrylic modifiers add reformulation complexity for manufacturers serving California and Northeast markets.
- Topping Compound:Fine-aggregate finishing-grade material designed for final coat applications requiring minimal sanding.
- Setting-Type Compound:Chemical-cure formulations hardening through crystallization rather than evaporation, specified where rapid return-to-service justifies premium positioning.
Volume placements concentrate in all-purpose compound; the faster expansion belongs to lightweight formulations.
Application:
Cost tier differentiation separates specification-grade commercial work from production residential finishing.
- Drywall Finishing:The core application spanning embedding, taping, and surface preparation for painted wall systems. Construction contractors in Sun Belt metropolitan markets drive specification volume where commercial construction activity sustains dedicated distribution infrastructure. ASTM C475 certification requirements extend product development timelines for reformulated lines targeting this segment.
- Repairing:Adhesion-optimized compounds formulated for existing painted substrates and plaster wall systems in aging commercial building stock. Commercial builders in legacy urban centers specify repair-grade materials where substrate compatibility determines project success. Skilled finisher scarcity pressures manufacturers toward more forgiving application properties in this technically demanding segment.
- Texturing:Viscosity-adjusted formulations for spray or manual application of decorative wall surfaces.
- Seaming:High-adhesion compounds engineered specifically for joint tape embedding and seam concealment.
Contractor procurement concentrates in drywall finishing; repair applications are climbing the fastest as commercial retrofit activity accelerates.
End User:
Customer type determines packaging format, technical support requirements, and channel economics.
- Construction Contractors:Professional drywall crews purchasing in pallet quantities through integrated material suppliers bundling compound with board and fasteners. This segment consolidates vendor counts to simplify procurement administration and leverage volume rebates in high-activity metropolitan corridors.
- Commercial Builders:General contractors and construction managers specifying products for multi-trade projects where schedule compression and finish quality standards drive material selection.
- Residential Builders:Production homebuilders and custom residential contractors representing the largest volume placement channel.
- DIY Enthusiasts:Retail purchasers of small-format pails through home improvement centers, representing minimal volume but sustaining brand awareness.
Material volume concentrates with construction contractors; commercial builders are gaining share fastest as non-residential construction expands.
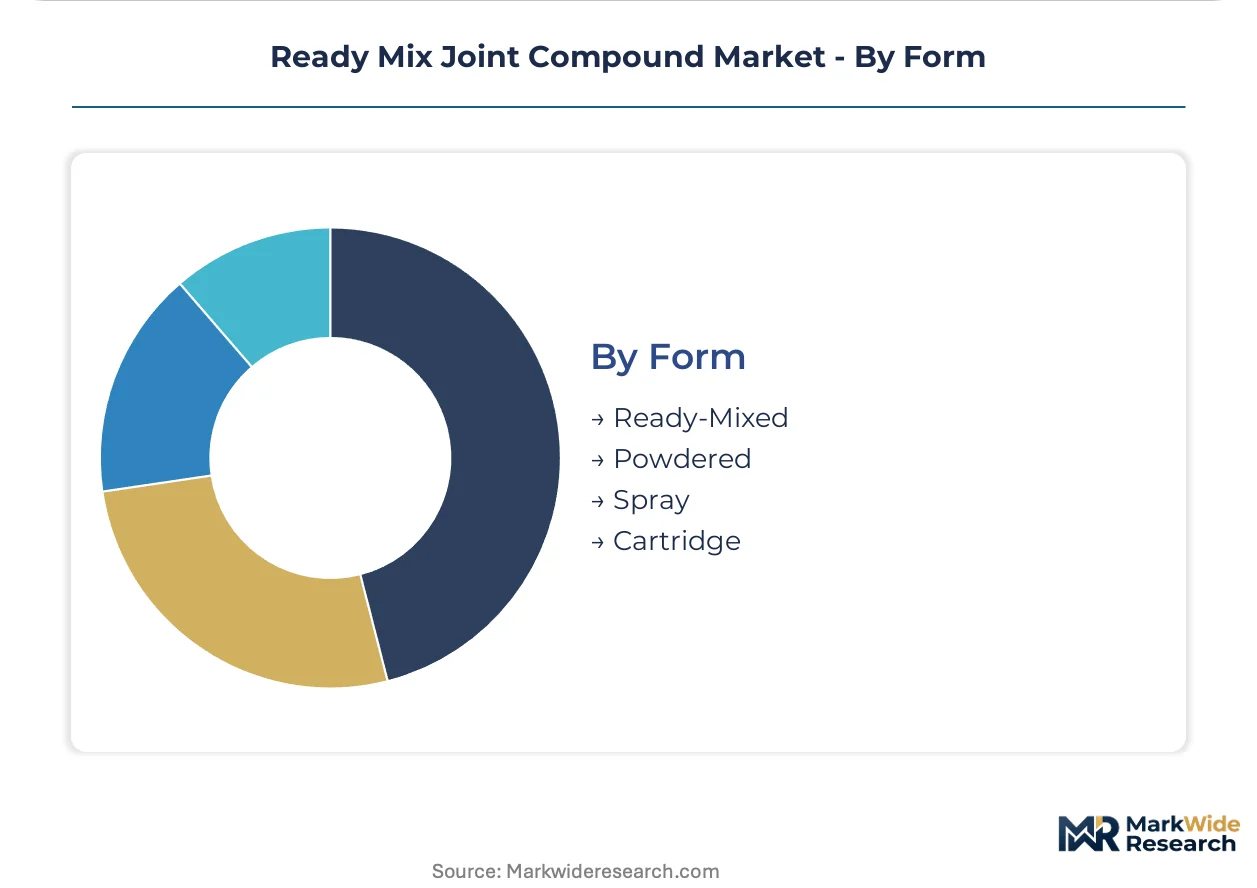
Form:
Supply concentration in water-weighted formats creates distribution radius constraints that powder and spray alternatives circumvent.
- Ready-Mixed:Pre-blended pail products at 60-75% solids content eliminating on-site water addition and batch inconsistency. This format dominates contractor workflows where crew productivity depends on immediate usability without mixing equipment.
- Powdered:Dry bagged formulations reducing freight cost per unit of finished compound and extending distribution reach beyond regional manufacturing footprints.
- Spray:Pump-applied formulations for high-volume commercial installations where mechanized application displaces manual finishing.
- Cartridge:Small-format caulking-gun dispensing for touch-up and repair applications requiring precision placement.
Ready-mixed pails capture the dominant volume share; spray formats are expanding most quickly in high-volume commercial drywall installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters near gypsum deposits and major construction corridors, while consumption concentrates in high-activity metropolitan markets. The United States generates the largest absolute demand volume. Germany and China anchor regional supply positions in Europe and Asia respectively.
United States
Commercial construction in Sun Belt metropolitan corridors sustains the highest per-capita consumption rates. OSHA silica exposure limits are tightening permissible levels for respirable crystalline during sanding operations. Atlanta, Dallas, and Phoenix distribution hubs are expanding lightweight compound throughput as residential builders specify reduced-density formulations.
Germany
Industrial refurbishment and energy-efficient building retrofits are accelerating repair-grade compound demand. REACH regulations govern chemical content in acrylic-modified formulations crossing into neighboring markets. The Rhine-Ruhr corridor hosts concentrated gypsum processing capacity serving Central European distribution networks.
China
Urban residential development and commercial interior fit-out projects are absorbing expanding domestic production. GB standards for building materials set performance benchmarks for joint treatment products in domestic construction codes. The Yangtze River Delta manufacturing cluster is scaling lightweight formulation output for both domestic use and regional export.
Canada
Multi-family residential construction in Toronto and Vancouver is sustaining import-dependent consumption volumes. Health Canada and PMRA oversee chemical safety assessments for construction material formulations. Prairie province distribution networks are extending reach into northern resource extraction camp construction where rapid-build drywall systems dominate.
United Kingdom
Commercial renovation of aging office stock and residential conversion projects are driving repair-segment growth. Building Regulations Part F ventilation standards indirectly affect compound selection through moisture-management specifications. The Midlands manufacturing belt supplies ready-mix pail production serving London and Southeast England construction corridors.
Ready Mix Joint Compound Market Competitive Environment
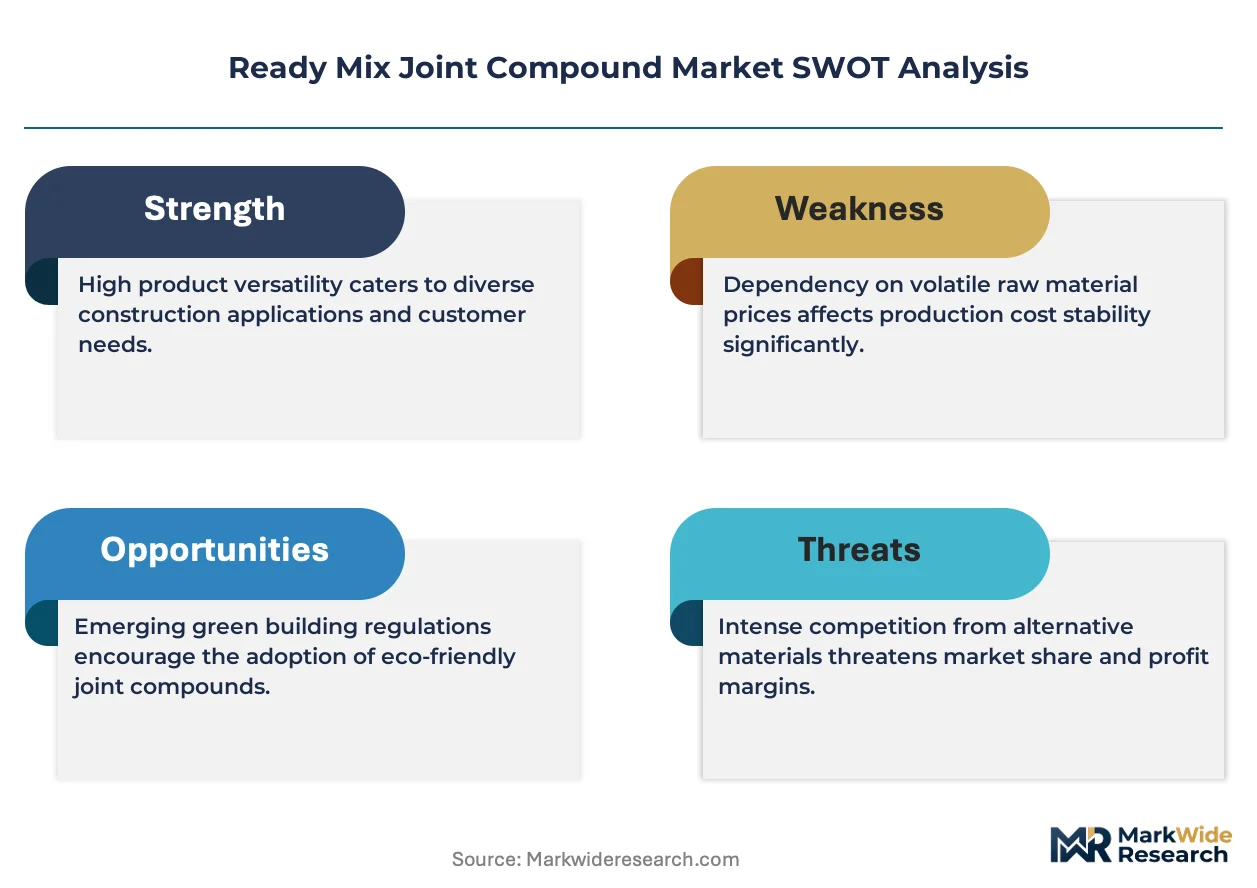
Top-tier vendors anchor specification-grade commercial work, while mid-scale regional producers compete on freight-radius coverage and contractor loyalty programs. The market structure reflects moderate consolidation around integrated gypsum-to-compound manufacturers. Two strategic archetypes dominate: vertically integrated mining-to-pail operators controlling raw material inputs, and specialized compounders competing through formulation agility and regional distribution density. Capacity expansion and dust-controlled product line extensions are the dominant competitive moves reshaping portfolio positioning.
Among North American building materials conglomerates, USG and Georgia Pacific occupy positions representing scale-driven distribution network leverage. Knauf Gips KG exemplifies the European integrated gypsum operator archetype with captive raw material supply chains. These three entities anchor tier-one competitive positioning through metropolitan corridor density and contractor procurement consolidation.
| Leading Market Players |
|---|
| Dow Inc. |
| Knauf Gips KG |
| USG |
| ASG |
| DAP Products Inc. |
| Compagnie de Saint-Gobain |
| Georgia Pacific |
| Everbuild |
| National Gypsum |
| Others |
Value Chain & Pricing Dynamics
Microsphere filler adoption in lightweight formulations is simultaneously compressing per-unit production costs and redistributing manufacturing advantage toward producers with captive supply of expanded perlite and glass bubble inputs. This density-reduction transition concentrates margin pools with integrated operators while forcing compounders without filler supply chain control into price-competitive defensive positions.
Pricing Analysis
Price erosion across standard-weight compounds traces to freight cost sensitivity and silica-driven demand migration toward dust-controlled alternatives. Three-tier pricing structure across premium lightweight, standard all-purpose, and economy heavyweight levels separates formulations by density grade and OSHA compliance tier. Cost-down pressure on legacy heavyweight lines accelerates because residential builders in Sun Belt metropolitan corridors specify reduced-density products for multi-story handling efficiency. Commercial contractors demonstrate lowest price sensitivity where rapid-cure setting-type compounds justify premium positioning against schedule compression value.
Supply Chain Analysis
Freight economics constrain distribution radius for water-weighted pail products to approximately 300-500 miles from manufacturing nodes, anchoring supply concentration in the United States, Germany, and China where gypsum processing clusters align with major construction corridors. Synthetic gypsum from flue-gas desulfurization and natural gypsum deposits feed compound production, with microsphere fillers increasingly sourced from specialized industrial minerals suppliers. Single-source vulnerability concentrates in lightweight filler supply chains where expanded perlite producers face capacity constraints. Distribution runs through integrated building material suppliers bundling compound with drywall board and fasteners to large metropolitan contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lightweight microsphere technology is displacing traditional heavyweight formulations as the dominant density-reduction approach, compressing timelines for incumbents to reformulate and reposition supply chains around filler-integrated manufacturing.
For Market Incumbents: Acquire microsphere filler production capacity or secure long-term offtake agreements with industrial minerals suppliers to defend margin position against supply-constrained competitors. Backward integration into synthetic gypsum sourcing from coal-fired power plant FGD systems reduces raw material volatility exposure. Prioritize ASTM C475 certification acceleration for dust-controlled reformulations before state-level OSHA silica enforcement tightens. For New Entrants and Emerging Players: Capture the underpenetrated commercial repair segment where adhesion-optimized compounds for aging painted substrates face limited specialized competition. Target legacy urban centers with aging building stock where substrate compatibility requirements deter generalist incumbents. Establish channel partnerships with modular building manufacturers for factory-applied joint treatment in offsite construction modules. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated gypsum-to-compound conglomerates seeking regional manufacturing footprint expansion. Long-term viability favors operators with captive filler supply and metropolitan distribution density within freight-economic radius of major construction corridors. Watch OSHA silica enforcement acceleration in additional states as the signal indicating reformulation investment urgency and consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Microsphere Filler Supply Integration | Captive expanded perlite sourcing locks in 25-30% density reduction capability against supply-constrained competitors. |
| Dust-Controlled Formulation Launch | OSHA-compliant product lines capture contractor specifications as silica exposure limits tighten enforcement. |
| Modular Building Channel Partnership | Factory-applied joint treatment partnerships open prefabrication convergence demand outside traditional job-site distribution. |
| Regional Manufacturing Footprint Expansion | Sun Belt metropolitan corridor plants reduce freight cost disadvantage against incumbent distribution networks. |
| Repair-Grade Product Line Extension | Adhesion-optimized formulations for painted substrates address aging commercial building stock retrofit demand. |
Study Parameters
Independent corroboration across building materials procurement managers, drywall contractor operations leads, and synthetic gypsum supply specialists underwrites the qualitative findings in this study. Primary fieldwork encompassed interviews with plant managers at compound manufacturing facilities, distribution channel partners in major metropolitan corridors, and technical R&D directors overseeing filler integration programs. Secondary validation drew from customs and trade data on gypsum and microsphere imports, SEC 10-K filings of publicly traded building materials conglomerates, and ASTM certification records. Bottom-up volume estimates from product-type and application segmentations were triangulated against top-down construction spending allocations.
Comparable-period anchoring linked projection models to historical reference periods spanning residential construction cycles and commercial retrofit waves. Segmentation dimensions modeled across the analysis window encompass product type, application workflow, end-user category, and supply format. CAGRs were derived from elasticity-adjusted demand curves incorporating gypsum input cost trajectories and regulatory compliance timelines. Forecast inputs included OSHA silica enforcement acceleration scenarios and state-level low-VOC mandate adoption patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to synthetic gypsum supply disruption from coal plant retireals and lightweight filler capacity expansion timing. Outputs reflect documented assumptions around regulatory enforcement pace and construction activity correlations. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Galactoarabinan Market
Specialty Compounds
Expandable Microspheres Market
Specialty Compounds
Mexico Masterbatch Market
Specialty Compounds
Global Antifreeze Proteins Market
Specialty Compounds
Global Color Masterbatch Market
Specialty Compounds
North America Lithium Compound Market
Specialty Compounds
Potassium Derivatives Market
Specialty Compounds
Polypropylene Compounds Market
Specialty Compounds
Chemical Hardener Compounds Market
Specialty Compounds
Carbon Black for Packaging Market
Specialty Compounds
Kokum Butter Market
Specialty Compounds
Conductive Plastic Compounds Market
Specialty Compounds
China Collagen Market
Specialty Compounds
Dextran Sulfate Sodium Market
Specialty Compounds
Oxygen Scavenger Masterbatch Market
Specialty Compounds
Dammar Gum Market