
 Asia-Pacific Programmable Logic Controller Market | 2026-2036
Asia-Pacific Programmable Logic Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Programmable Logic Controller Market Outlook
South Korea's semiconductor equipment manufacturing base is rewriting supply dynamics for advanced PLCs across the region. Mitsubishi Electric Corporation leverages its legacy in factory automation to sustain dominance in compact PLC architectures for Japanese automotive plants. Omron Corporation anchors its position through deep integration with pharmaceutical packaging lines in India and Southeast Asia. Siemens AG competes aggressively on modular platforms targeting smart factory retrofits in China's Yangtze River Delta.
A programmable logic controller is an industrial digital computer designed for electromechanical process automation, typically featuring ruggedized construction, real-time operating systems, and I/O modules ranging from 16 to thousands of points. The device executes ladder logic or structured text to control machinery on assembly lines, power plants, and material handling systems with microsecond response precision. Compact PLCs lead volume shipments across small and medium enterprises due to lower entry cost and simplified deployment, while modular PLCs capture the majority of margin pools in large-scale automotive and oil and gas installations. Rack-mount PLCs retain entrenched positions in legacy process industries where hot-swappable redundancy remains non-negotiable, and soft PLCs are gaining traction among system integrators seeking PC-based flexibility for Industry 4.0 retrofits.
China's MIIT enforces GB/T industrial control system security standards that mandate encrypted communication protocols and hardware certification for critical infrastructure deployments. Japan's METI promotes JIS-compliant open automation architectures that reduce vendor lock-in and accelerate interoperability testing across domestic suppliers. India's CEA electrical safety regulations and BIS equipment certification requirements shape procurement specifications for power sector PLC installations. Stakeholders must weigh the cost of multi-standard compliance against the volume opportunity created by divergent national industrial policies.
Market Dynamics
China's MIIT cybersecurity mandates for industrial control systems are forcing accelerated hardware replacement cycles across critical infrastructure sectors, compressing traditional seven-year upgrade timelines to three-year intervals.
Growth Catalysts
- MIIT GB/T Security Standards:China's mandatory encrypted communication protocols for critical infrastructure are creating immediate replacement demand across power generation and water treatment facilities.
- EV Assembly Automation:Southeast Asian automotive manufacturers are deploying compact PLCs for battery module integration and motor assembly lines.
- Pharmaceutical Corridor Concentration:India's Hyderabad-Ahmedabad manufacturing belt is driving modular PLC installations for FDA-compliant batch processing and serialization.
Market Restraints
- Semiconductor Supply Concentration:Advanced PLC processor fabrication depends heavily on South Korean and Taiwanese foundry capacity, creating single-source vulnerability.
- Multi-Standard Compliance Costs:Vendors must simultaneously satisfy China's GB/T encryption, Japan's JIS interoperability, and India's BIS certification requirements.
- Soft PLC Substitution Threat:Industrial PC-based control systems are capturing greenfield smart factory projects that previously specified dedicated hardware.
Strategic Opportunities
- Vietnam Manufacturing Expansion:Electronics contract manufacturers are relocating capacity from China, creating fresh demand for mid-range modular controllers in Bac Ninh and Hai Phong industrial zones.
- Digital Twin Convergence:Integration of PLC edge data with cloud-based simulation platforms is opening subscription-based service revenue streams for system integrators.
- India PLI Scheme Incentive:Production-linked incentives for advanced manufacturing are accelerating capital expenditure timelines for domestic pharmaceutical and automotive OEMs.
Industry Challenges
- Legacy Protocol Integration:Retrofitting decades-old fieldbus networks with modern Ethernet/IP infrastructure requires specialized bridging hardware and extended commissioning periods.
- Cybersecurity Skill Scarcity:Industrial facilities lack personnel trained in both operational technology hardware and IT security frameworks, slowing secure deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Programmable Logic Controller Market |
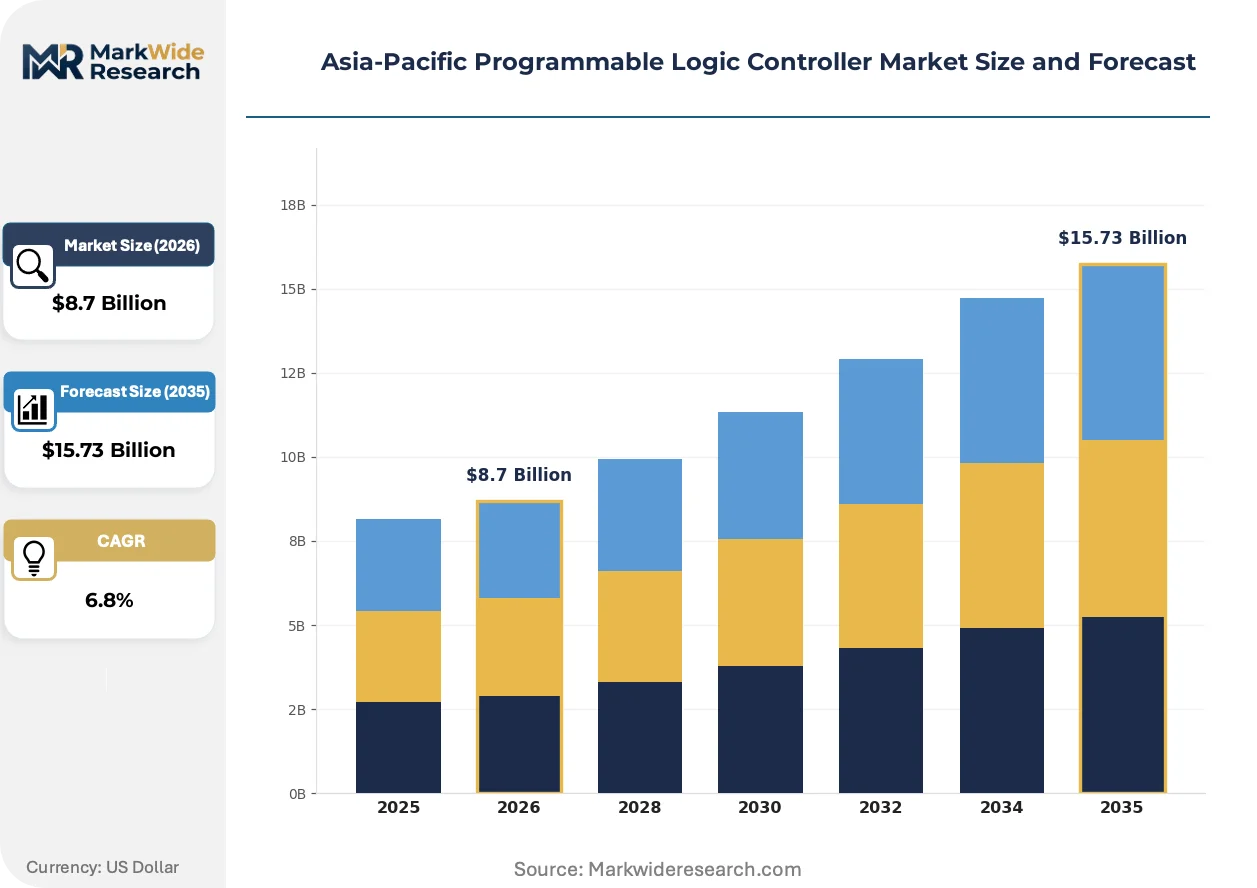
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact PLC, Modular PLC, Rack-Mount PLC, Soft PLC Industry Vertical: Manufacturing, Oil & Gas, Automotive, Pharmaceuticals End User: OEMs, System Integrators, End Users, Aftermarket Providers Connectivity: Wired, Wireless, Ethernet, Fieldbus |
| Companies Covered | Mitsubishi Electric Corporation, Omron Corporation, Schneider Electric SE, Rockwell Automation Inc., Siemens AG, ABB Ltd., Panasonic Corporation, Honeywell International Inc., Fuji Electric Co. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Programmable Logic Controller Market Strategic Shifts
Software-defined control architectures are dissolving traditional boundaries between hardware PLCs and industrial computing platforms, enabling runtime flexibility that fixed-function systems cannot match.
Soft PLC runtime environments executing on hardened industrial PCs are virtualizing the traditional controller hardware layer, allowing automotive OEMs in Japan and South Korea to consolidate multiple control functions onto single computing nodes while maintaining deterministic microsecond response times for safety-critical loops.
Japan's METI open automation framework is mandating interoperability testing across domestic PLC suppliers, reducing vendor lock-in and accelerating multi-brand system integration for smart factory retrofits in the Nagoya and Osaka industrial clusters.
System integrators across China's Yangtze River Delta are unbundling hardware supply from engineering services, selling controller hardware at thin margins while capturing value through application-specific software libraries and remote monitoring subscriptions.
Asia-Pacific Programmable Logic Controller Market Segmentation
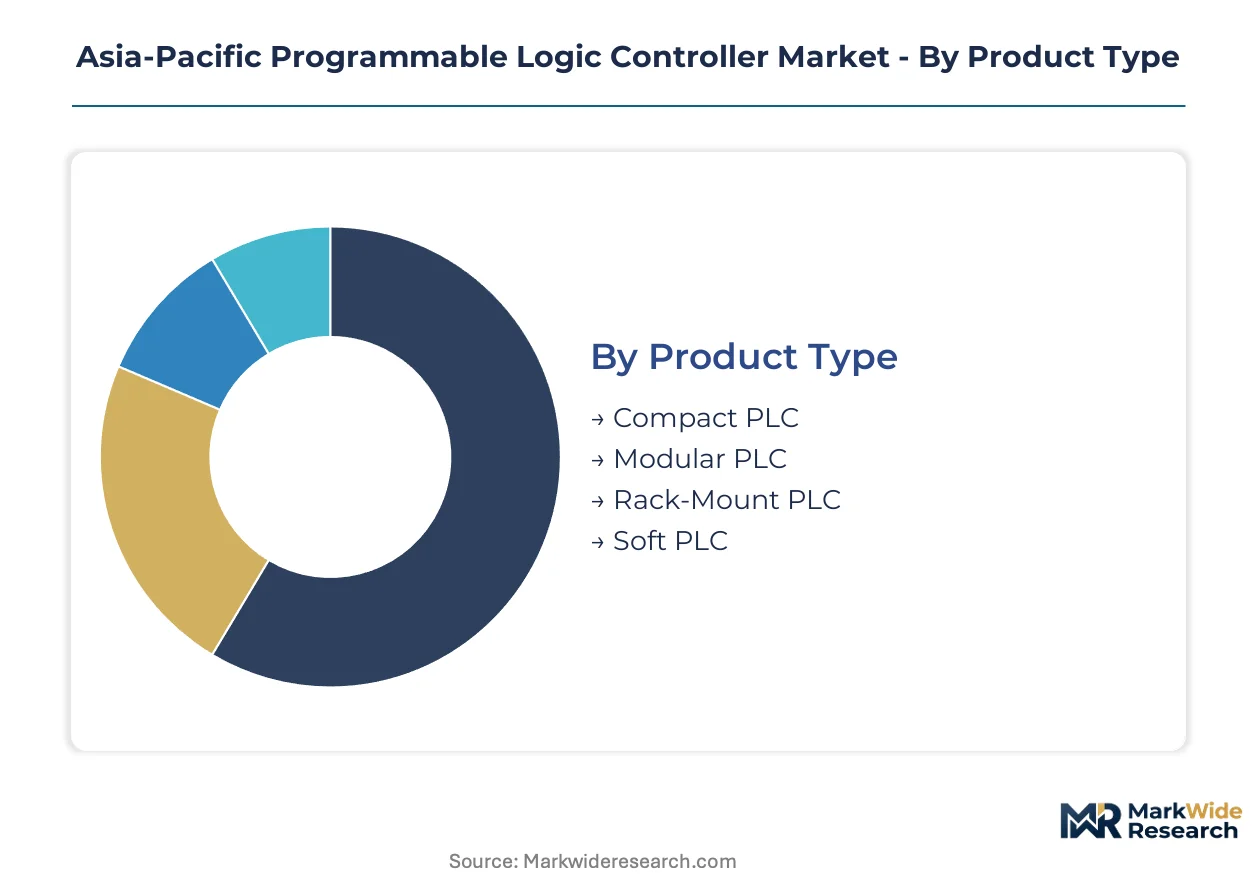
PLC procurement patterns across Asia-Pacific diverge sharply by operational scale and legacy infrastructure maturity. Understanding these splits reveals where hardware margins concentrate versus where volume shipments dominate.
Product Type:
Mature rack-mount architectures coexist with emerging software-defined alternatives, creating a bifurcated technology landscape.
- Compact PLC:Self-contained units integrate processor, power supply, and I/O in fixed configurations. Small and medium enterprises across Vietnam's Bac Ninh electronics zone favor these for rapid deployment on battery module assembly lines where capital constraints limit modular system investment.
- Modular PLC:Expandable chassis accommodate hot-swappable I/O cards and redundant processors. Large-scale automotive plants in Japan's Nagoya cluster deploy these for powertrain assembly where downtime costs exceed hardware premiums by an order of magnitude.
- Rack-Mount PLC:Legacy 19-inch chassis dominate process industries with decades-old control room infrastructure. India's power sector under CEA regulations maintains extensive installed bases requiring spare part continuity.
- Soft PLC:Runtime environments execute ladder logic on hardened industrial PCs. South Korean semiconductor equipment builders are adopting these for flexible reconfiguration between product generations.
Modular PLCs handle the majority of throughput; Soft PLCs are gaining share fastest as virtualization penetrates greenfield smart factory projects.
Industry Vertical:
Application requirements range from explosive atmosphere certification to pharmaceutical batch integrity validation.
- Manufacturing:Discrete automation spans packaging, material handling, and assembly operations. China's Yangtze River Delta contract manufacturers drive demand for controllers supporting rapid changeover between consumer electronics SKUs.
- Oil & Gas:Hazardous location ratings and SIL safety integrity levels dominate procurement specifications. Offshore platforms in Southeast Asia require explosion-proof enclosures and redundant communication paths.
- Automotive:Electric vehicle battery assembly demands precision torque control and traceability systems. Thailand's Eastern Economic Corridor expansion is accelerating compact PLC deployments for motor winding and pack integration stations.
- Pharmaceuticals:FDA 21 CFR Part 11 compliance and serialization mandates shape controller selection. Hyderabad's formulation corridors under India's PLI scheme are retrofitting batch reactors with modular systems supporting electronic batch records.
Manufacturing commands the largest installed base; Pharmaceuticals shows the steepest expansion trajectory as serialization regulations tighten across ASEAN markets.
End User:
Procurement authority varies by technical sophistication and in-house engineering depth.
- OEMs:Original equipment manufacturers embed controllers in purpose-built machinery. Japanese machine tool builders specify Mitsubishi and Omron platforms to ensure global service consistency.
- System Integrators:Third-party engineering firms design and commission complete automation solutions. China's SI community is unbundling hardware from software services, capturing recurring revenue through remote monitoring subscriptions.
- End Users:Industrial facility owners purchase directly for maintenance or expansion. India's pharmaceutical majors maintain captive engineering teams capable of self-executing PLC programming.
- Aftermarket Providers:Spare parts distributors and refurbishment specialists serve legacy installations. Taiwan's industrial electronics channel stocks obsolete processor modules for semiconductor fab equipment with multi-decade service lives.
System Integrators intermediate the majority of new project value; Aftermarket Providers are expanding fastest as China's MIIT cybersecurity mandates force accelerated replacement cycles.
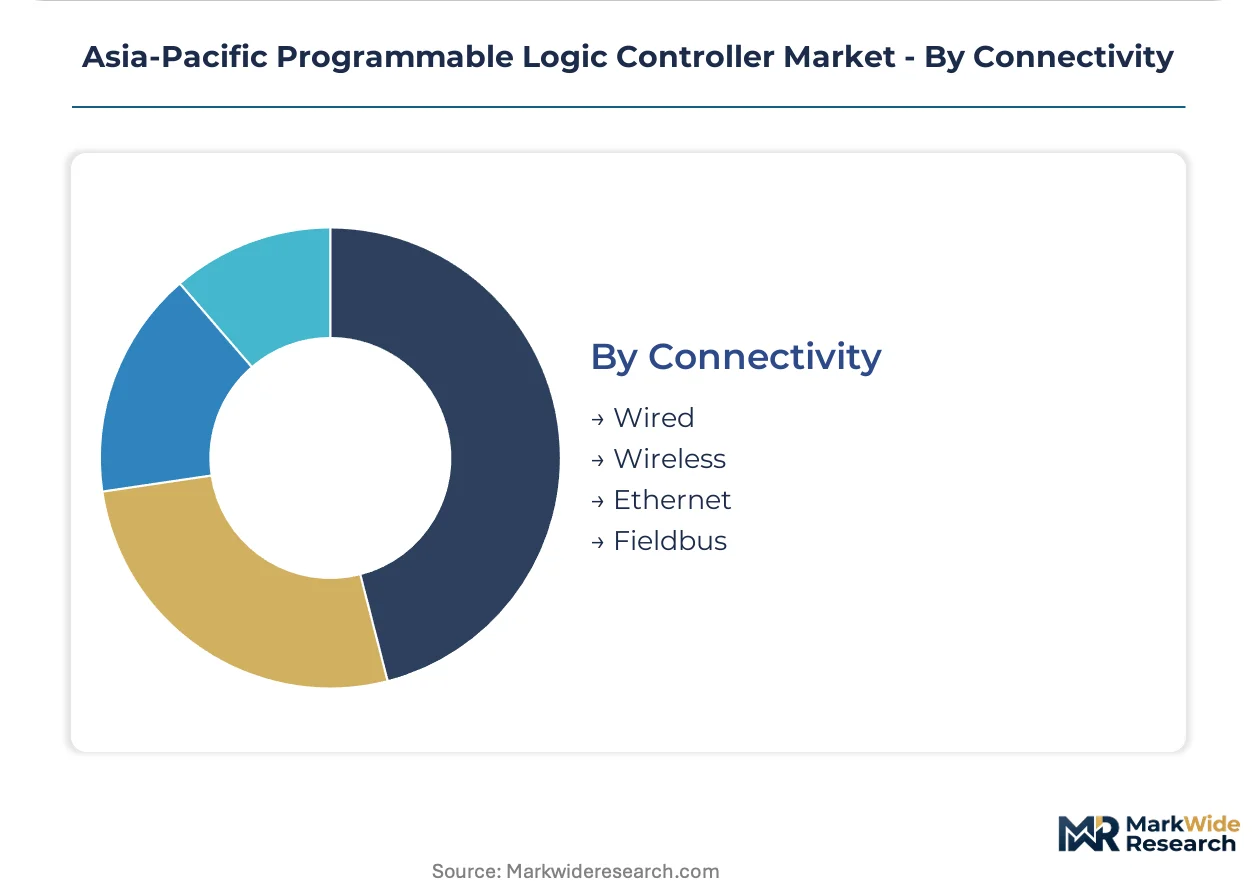
Connectivity:
Physical layer selection determines cybersecurity exposure and real-time determinism tradeoffs.
- Wired:Dedicated copper cabling remains standard for safety-critical loops. Hardwired I/O dominates Japanese automotive plants where microsecond jitter tolerance is non-negotiable.
- Wireless:Industrial Wi-Fi and proprietary radio protocols enable mobile operator interfaces. Southeast Asian port automation projects are deploying wireless pendant stations for crane control.
- Ethernet:IEEE 802.3-based networks with real-time extensions consolidate IT and OT traffic. China's GB/T encrypted Ethernet/IP implementations satisfy MIIT critical infrastructure mandates.
- Fieldbus:Legacy serial protocols including Profibus and DeviceNet persist in brownfield installations. India's process industries maintain extensive Foundation Fieldbus segments requiring specialized bridging hardware for Ethernet migration.
Ethernet carries the majority of new project data; Wireless is climbing fastest as battery-powered sensors proliferate in predictive maintenance applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT cybersecurity mandates are compressing hardware replacement cycles across critical infrastructure sectors. Japan's METI open automation framework is accelerating interoperability testing among domestic suppliers. India's PLI scheme is triggering capital expenditure acceleration in pharmaceutical and automotive corridors.
China
Power generation and water treatment facilities are replacing legacy controllers under GB/T encrypted communication mandates. The MIIT certification requirements for critical infrastructure hardware are forcing three-year upgrade intervals. The Yangtze River Delta contract manufacturers are deploying modular PLCs for rapid consumer electronics SKU changeover.
Japan
Automotive powertrain assembly plants demand microsecond-precision deterministic control for safety-critical loops. METI's JIS-compliant open automation architectures are reducing vendor lock-in across Nagoya and Osaka industrial clusters. Kansai-based system integrators are unbundling hardware supply from software engineering services.
India
Pharmaceutical serialization regulations are driving modular PLC installations for FDA-compliant batch processing. The CEA electrical safety standards and BIS equipment certification shape procurement specifications for power sector deployments. Hyderabad-Ahmedabad manufacturing corridors are retrofitting batch reactors under PLI scheme incentives.
South Korea
Semiconductor equipment manufacturers are adopting soft PLCs for flexible reconfiguration between product generations. The country's national industrial technology regulator promotes advanced manufacturing standards for domestic automation suppliers. Seoul Capital Area fabs are consolidating multiple control functions onto single computing nodes.
Vietnam
Electronics contract manufacturers relocating from China are creating demand for mid-range modular controllers. The country's investment promotion agencies are streamlining industrial zone permitting for Bac Ninh and Hai Phong facilities. Battery module assembly lines favor compact PLCs where capital constraints limit modular system investment.
Asia-Pacific Programmable Logic Controller Market Competitive Environment
Capability concentration sits with established factory automation specialists; scale advantage sits with diversified industrial conglomerates. The vendor landscape organizes into three functional tiers: integrated automation platforms, component specialists, and regional system integrators. Premium-tier players defend position through application-specific software libraries and remote monitoring subscriptions. Mid-tier competitors capture volume through standardized compact architectures for small and medium enterprises.
Among Japan-based automation specialists, Mitsubishi Electric Corporation and Omron Corporation exemplify divergent strategic positioning within the premium controller segment. Mitsubishi anchors the legacy factory automation tier through deep integration with domestic automotive production lines. Omron occupies a position emphasizing pharmaceutical packaging applications across India and Southeast Asia. Siemens AG represents the diversified European conglomerate archetype competing aggressively on modular platforms for smart factory retrofits. These three companies illustrate how geographic origin and historical vertical focus shape competitive differentiation in a market where hardware margins are compressing and software services are capturing expanding value pools.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| Omron Corporation |
| Schneider Electric SE |
| Rockwell Automation Inc. |
| Siemens AG |
| ABB Ltd. |
| Panasonic Corporation |
| Honeywell International Inc. |
| Fuji Electric Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Taiwanese and South Korean foundry capacity for advanced PLC processors compresses pricing tier spreads between premium modular systems and entry-level compact units while simultaneously forcing supply chain redundancy investments. MIIT certification requirements for critical infrastructure hardware in China add regulatory chokepoint costs that propagate through distributor markups across the Asia-Pacific region.
Pricing Analysis
Geographic price spreads between Japanese automotive-grade controllers and Southeast Asian compact units for battery assembly lines reflect divergent certification burdens and service bundling intensity. Pricing stratifies across premium, standard, and economy tiers based on SIL safety integrity levels and encrypted protocol compliance rather than raw hardware specifications. Cost compression in the compact PLC segment is intensifying because Vietnamese electronics manufacturers prioritize capital efficiency over feature depth. Small and medium enterprises in Bac Ninh industrial zones exhibit the highest price sensitivity, while Japanese automotive OEMs absorb premiums for microsecond-deterministic performance guarantees.
Supply Chain Analysis
Export control regimes restricting advanced semiconductor manufacturing equipment to Chinese fabs constrain processor supply flows and accelerate regional sourcing diversification. Component supply concentrates in Taiwan, South Korea, and Japan, with advanced logic fabrication drawing from TSMC and Samsung foundry capacity. Raw material dependencies span silicon wafers, rare earth magnets for servo integration, and copper for industrial Ethernet cabling. Single-source vulnerability around 7nm and below processor nodes threatens delivery continuity for safety-critical applications. Distribution runs through authorized distributor networks in Tokyo, Shanghai, and Singapore, with system integrators capturing margin through software service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Japanese automotive OEMs and Indian pharmaceutical majors with captive engineering capabilities, fragmenting procurement authority away from traditional system integrator intermediaries.
For Market Incumbents: Harden defensive positions by deepening software library investments for pharmaceutical serialization applications and securing MIIT pre-certification for processor modules ahead of competitor submissions. Soft PLC runtime environments from South Korean semiconductor equipment builders threaten dedicated hardware margins in greenfield projects. Channel control through exclusive distributor agreements in Vietnam's Bac Ninh corridor remains a critical lever. For New Entrants and Emerging Players: Pursue white-space opportunities in aftermarket refurbishment for India's CEA-regulated power sector legacy rack-mount installations and wireless-enabled compact controllers for Southeast Asian port automation. The most penetrable segment sits in mid-range modular systems for electronics contract manufacturers relocating to Hai Phong industrial zones. A direct system integrator partnership model bypassing established distributor networks offers the cleanest go-to-market angle. For Investors and Strategic Acquirers: The market sits at a regulatory-acceleration phase that favors acquisition targets with pre-certified hardware portfolios and established pharmaceutical vertical relationships. Long-term viability over the next decade hinges on software-defined control architectures that virtualize hardware dependencies. The signal to watch is MIIT enforcement consistency across provincial power generation facilities as an inflection indicator for replacement cycle durability.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Pre-Certification Investment | Accelerates hardware approval timelines for critical infrastructure deployments in China's power sector. |
| Software Library Development | Captures recurring revenue through pharmaceutical batch processing and serialization application modules. |
| Regional Distributor Consolidation | Strengthens channel control in Vietnam's Bac Ninh and Hai Phong electronics manufacturing corridors. |
| Soft PLC Runtime Acquisition | Positions for virtualization trends in South Korean semiconductor equipment and Japanese automotive lines. |
| Aftermarket Service Expansion | Addresses India's accelerated replacement cycles under CEA electrical safety regulations and BIS mandates. |
Study Parameters
Initial hypotheses were tested against primary input from plant engineers at Japanese automotive facilities, procurement leads at Indian pharmaceutical OEMs, system integrators in China's Yangtze River Delta, and aftermarket service heads across Taiwan's semiconductor equipment channel, then refined through secondary validation. Bottom-up triangulation incorporated customs and trade data for industrial controller shipments, MIIT certification registry filings, and SEC disclosures from listed automation suppliers. Top-down cross-checks applied macroeconomic indicators for manufacturing capital expenditure across the region.
Demand-supply balance modeling across the projection horizon segmented volume and value outputs by product architecture, industry vertical, end-user procurement authority, and physical connectivity protocol. CAGRs were derived from regression analysis of historical replacement cycles adjusted for regulatory compression effects and greenfield expansion trajectories. Industry-specific forecast inputs included MIIT enforcement intensity indices for critical infrastructure sectors and PLI scheme disbursement patterns for Indian pharmaceutical and automotive capital expenditure.
Sensitivities concentrate around semiconductor foundry capacity allocation shifts and MIIT certification timeline variability. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology substitution rates. Material shifts in export control regime stringency or encrypted protocol standard adoption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Asia Pacific Industrial Communication Market
Industrial Automation
Mini-Load Systems Market
Industrial Automation
Global Industrial Control and Factory Automation Market
Industrial Automation
North America Industrial Vending Machine Market
Industrial Automation
Global Operational Technology Market
Industrial Automation
Motion Positioning Stages Market
Industrial Automation
North America Automated Rotary Indexing Table Market
Industrial Automation
Computer-Aided Manufacturing (CAM) Market
Industrial Automation
Rotary Actuators Market
Industrial Automation
Intralogistics Market
Industrial Automation
Europe Factory Automation and Industrial Controls Market
Industrial Automation
Parcel Sortation Systems Market
Industrial Automation
Global Warehouse Automation Market
Industrial Automation
Latin America Factory Automation and Industrial Controls Market
Industrial Automation
Mining Automation Systems Market
Industrial Automation
United Kingdom Factory Automation and Industrial Control Systems Market