
 Asia-Pacific Automation Components Market | 2026-2036
Asia-Pacific Automation Components Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Automation Components Market Analytics
Aftermarket service revenue is narrowing the profitability gap against original equipment sales across the Asia-Pacific automation landscape. Siemens AG leverages its digital twin platforms to capture recurring software income from industrial clients. ABB Ltd. anchors its regional position through localized drive manufacturing in Shanghai and Bangalore. Mitsubishi Electric Corporation dominates precision servo markets in Japan and extends control system exports across ASEAN automotive plants.
Asia-Pacific automation components encompass electromechanical and electronic devices including controllers, sensors, actuators, and drives that execute, monitor, or regulate industrial processes with response times measured in milliseconds and communication protocols such as EtherCAT and PROFINET. These components translate digital commands into physical motion or measurement, enabling closed-loop control in manufacturing lines, logistics systems, and energy infrastructure. Controllers and drives currently occupy the largest value pools where firmware complexity creates vendor stickiness, while sensor integration with IoT architectures represents the fastest-expanding segment as edge analytics demand multi-parameter environmental and positional data. Application demand skews heavily toward manufacturing and logistics, with oil and gas automation exhibiting slower replacement cycles due to capital discipline among upstream operators.
Japan's METI enforces Top Runner standards that mandate progressive efficiency gains in industrial motors, directly stimulating premium actuator and drive upgrades across Japanese-owned facilities regionwide. China's SAMR administers GB standards for functional safety and electromagnetic compatibility that determine market access for imported controllers and robotic components. India's BIS certification requirements for electrical control gear are tightening, compelling foreign suppliers to establish local testing partnerships. Stakeholders must weigh compliance investment against the margin compression from localized supply mandates as each major economy hardens its technical barriers to automation imports.
Market Dynamics
Japan's METI Top Runner standards and China's dual carbon mandates are forcing simultaneous replacement cycles across precision motor and drive systems, compressing upgrade timelines from seven-year cycles to four-year refresh intervals.
Growth Catalysts
- Electrification mandates:China's GB standards for new energy vehicles require robotic welding and battery assembly lines, pulling servo actuator demand through automotive OEM supply chains.
- Thailand's Eastern Economic Corridor:Board of Investment incentives for smart factory certification are accelerating controller and sensor deployments in automotive and electronics plants.
- Edge analytics convergence:Multi-parameter environmental sensors with millisecond response times are displacing single-function devices in semiconductor cleanrooms across the Yangtze River Delta.
Market Restraints
- Rare earth magnet dependency:Neodymium price volatility and concentrated Chinese processing capacity create input cost instability for permanent-magnet servo motors.
- Legacy protocol fragmentation:EtherCAT, PROFINET, and CC-Link IE fieldbus incompatibility forces redundant gateway hardware and extends integration timelines.
- Capital discipline in upstream oil and gas:Seven-to-ten-year replacement cycles for offshore platform automation suppress actuator and valve controller demand.
Strategic Opportunities
- Vietnam's northern industrial zones:Underpenetrated precision agriculture and food processing automation present white space for sensor-integrated packaging lines.
- India's PLI scheme for textiles:Production-linked incentives for technical textiles are creating first-mover openings for automated loom controllers and tension sensors.
- Digital twin software layering:Firmware subscriptions atop hardware sales are capturing recurring revenue from predictive maintenance contracts in Japanese-owned regional facilities.
Industry Challenges
- Functional safety certification lag:GB/T 20438 SIL compliance timelines extend eighteen to twenty-four months for imported safety controllers, delaying market entry.
- Legacy system integration friction:Thirty-year-old relay logic in Japanese automotive stamping plants resists seamless migration to modern PLC architectures without full line shutdowns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Automation Components Market |
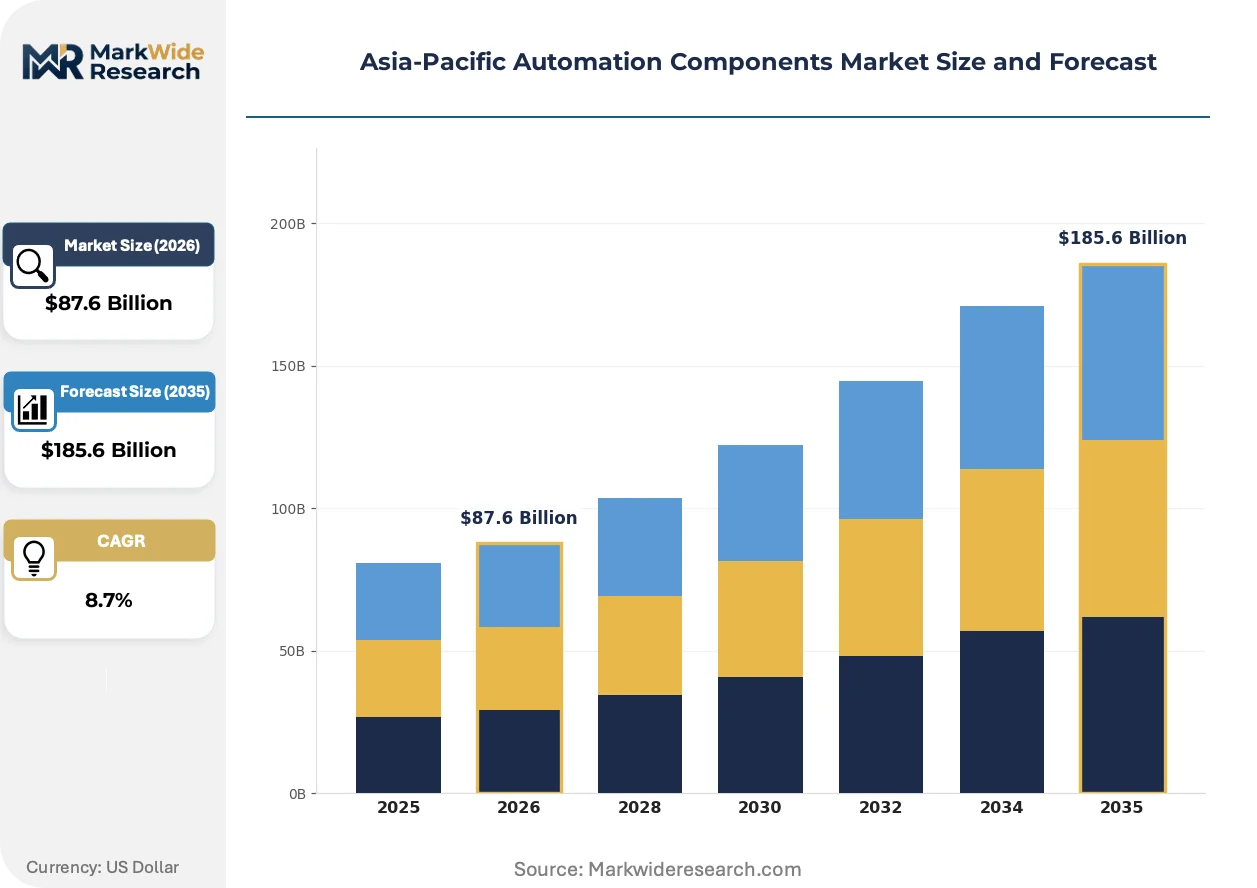
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $185.6 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Controllers, Sensors, Actuators, Drives Application: Manufacturing, Logistics, Oil & Gas, Aerospace End User: Manufacturers, Distributors, OEMs, Integrators Technology: Cloud Computing, IoT, Robotics, AI |
| Companies Covered | Rockwell Automation, Inc., Siemens AG, ABB Ltd., Schneider Electric SE, Mitsubishi Electric Corporation, Emerson Electric Co., Nidec Corporation, Omron Corporation, Bosch Rexroth AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Automation Components Market Evolving Landscape
Software-defined architectures are collapsing the traditional boundary between hardware controllers and cloud analytics, forcing component vendors to restructure R&D allocation toward firmware and edge computing stacks.
Digital twin platforms for industrial assets are virtualizing physical commissioning processes, allowing automotive manufacturers in China and Southeast Asia to simulate robotic cell performance before floor installation. Tier-one suppliers are adopting these tools at pilot scale now, with full deployment accelerating as 5G private networks reduce latency. This virtualization is compressing the traditional six-month integration window into eight-week digital validation cycles.
Japan's METI enforcement of 2024 efficiency benchmarks for industrial motors is mandating IE4-class premium efficiency actuators across domestic and overseas Japanese-owned facilities. The regulation tightens allowable losses in variable-frequency drive systems by fifteen percent versus prior Top Runner cycles. Precision servo manufacturers are responding with ferrite-assisted magnet designs that reduce rare earth content while maintaining torque density.
Aftermarket service unbundling from original equipment contracts is redistributing margin pools toward regional system integrators in South Korea and Taiwan. Buyers in semiconductor and flat-panel display sectors are separating hardware procurement from multi-year maintenance agreements, creating standalone software update revenue streams. This pattern is most visible in the Yangtze River Delta, where foundry operators now source controllers directly while contracting local firms for predictive analytics deployment.
Asia-Pacific Automation Components Market Segmentation
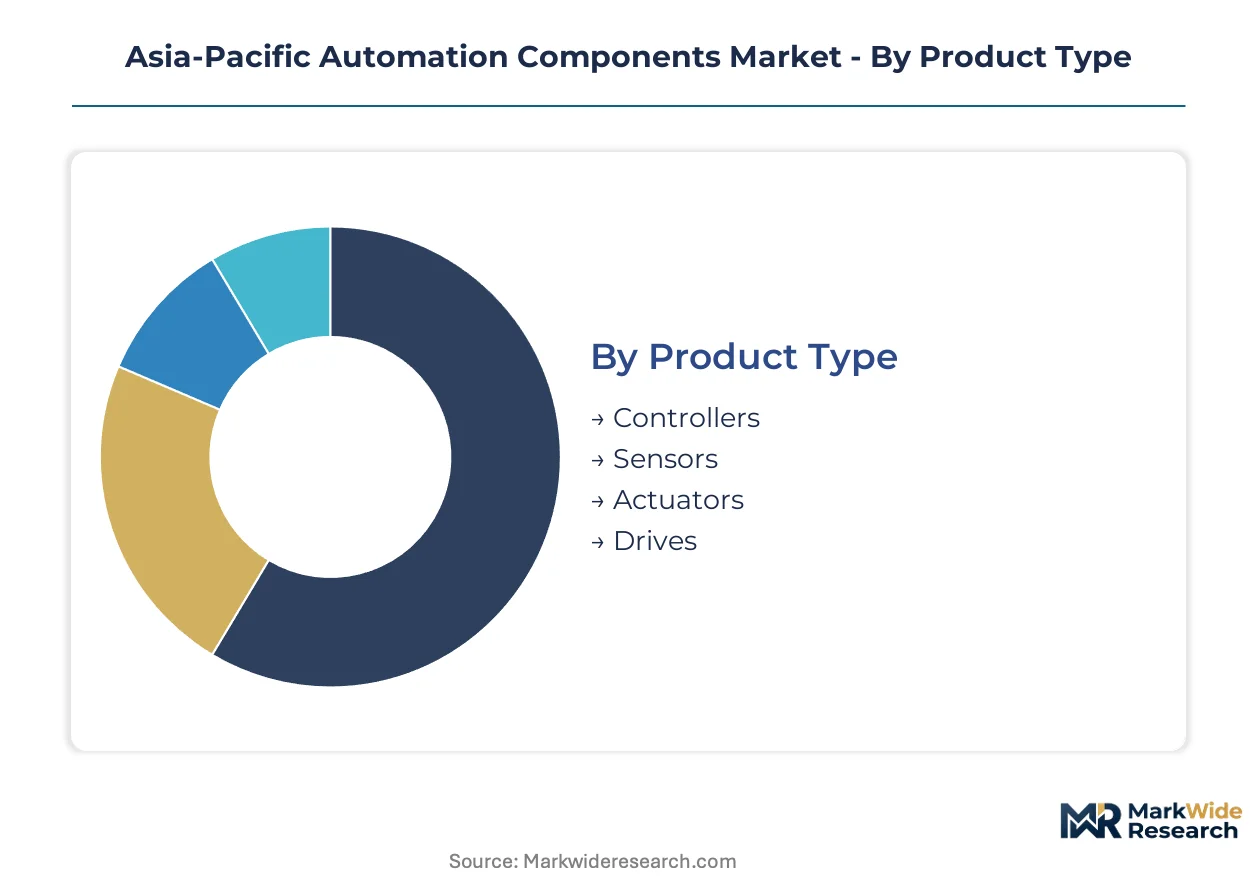
Component segmentation in Asia-Pacific automation reveals distinct service revenue profiles across hardware categories. Firmware complexity and replacement cycle variance create divergent aftermarket opportunities that reshape vendor strategies across the region.
Product Type:
After-sales-service intensity varies sharply across electromechanical categories, with firmware-dependent segments generating recurring revenue streams absent from purely mechanical alternatives.
- Controllers:Programmable logic controllers and industrial PCs execute closed-loop process commands with millisecond cycle times. Demand concentrates in China's Yangtze River Delta automotive battery plants where GB standards for new energy vehicles mandate frequent logic updates. Firmware subscriptions now match original hardware margins for tier-one suppliers.
- Sensors:Multi-parameter environmental and positional measurement devices integrate edge analytics capabilities for real-time process feedback. Semiconductor cleanrooms across South Korea and Taiwan are displacing single-function devices with combined temperature-humidity-pressure units to reduce wiring complexity.
- Actuators:Electromechanical motion converters translate digital commands into physical displacement.
- Drives:Variable-frequency motor controllers manage power delivery precision.
By volume, Drives leads. By growth pace, Sensors is expanding most quickly.
Application:
Capital deployment cycles and regulatory pressure intensity segment end-use markets into refresh-rate tiers that determine component procurement patterns.
- Manufacturing:Robotic welding and assembly lines in automotive and electronics sectors demand sub-millisecond response components. Thailand's Eastern Economic Corridor smart factory certifications are accelerating controller and sensor deployments across tier-one supplier facilities.
- Logistics:Automated storage and retrieval systems plus conveyor networks require synchronized multi-axis coordination. E-commerce fulfillment centers in Vietnam's northern industrial zones are creating first-mover demand for sensor-integrated packaging automation.
- Oil & Gas:Offshore platform automation exhibits extended replacement timelines due to upstream operator capital discipline.
- Aerospace:Precision machining and assembly applications maintain stringent certification requirements.
Manufacturing commands the largest installed base. Logistics is climbing the fastest as warehouse automation accelerates.
End User:
Procurement authority distribution shapes component specification power, with direct manufacturers exerting tighter technical control than intermediaries.
- Manufacturers:Automotive OEMs and electronics assemblers specify component performance requirements directly. Japanese-owned facilities across ASEAN are unbundling hardware procurement from maintenance contracts to capture standalone software update revenue.
- OEMs:Original equipment manufacturers integrate automation components into capital goods for resale.
- Distributors:Channel intermediaries aggregate demand across fragmented buyer bases.
- Integrators:Regional system integrators in South Korea and Taiwan are capturing predictive analytics deployment contracts separated from hardware sales.
Manufacturers dominate specification authority. Integrators are gaining share fastest as service unbundling accelerates.
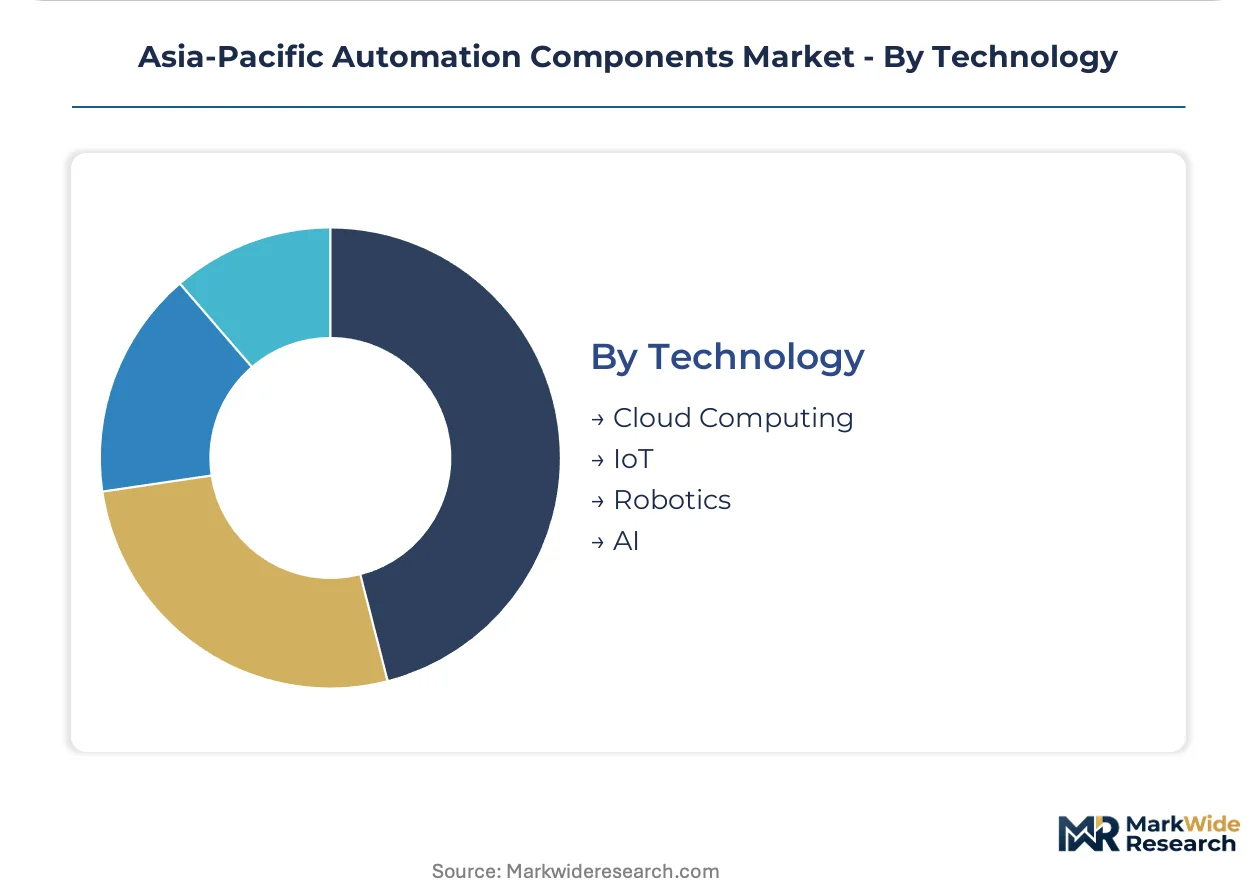
Technology:
Software-defined architectures are collapsing hardware-software boundaries and forcing vendor R&D reallocation toward firmware stacks.
- IoT:Networked sensor architectures with edge analytics capabilities enable predictive maintenance and real-time optimization. Multi-parameter environmental sensors with millisecond response times are displacing legacy single-function devices across semiconductor cleanrooms.
- Robotics:Articulated and collaborative robotic systems demand precision servo coordination.
- Cloud Computing:Centralized data processing and remote monitoring platforms extend visibility across distributed assets.
- AI:Machine learning inference at the edge enables adaptive process control without latency penalties.
IoT anchors current deployment value. AI is gaining the steepest expansion trajectory as inference capabilities migrate to edge devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the Asia-Pacific Automation Components Market diverge sharply by industrial maturity. Japanese facilities prioritize precision servo upgrades under efficiency mandates, while Chinese plants favor high-volume controller deployments for new energy vehicle lines. Southeast Asian markets show mixed adoption, with Thailand and Vietnam importing complete automation suites versus component-level procurement.
China
Automotive electrification drives controller and actuator demand through the Yangtze River Delta manufacturing corridor. SAMR-administered GB standards for functional safety and electromagnetic compatibility determine market access for imported robotic components. Battery assembly plants in Suzhou and Ningbo are expanding robotic welding capacity to meet domestic EV production targets.
Japan
Precision manufacturing maintains dominant specification authority for servo systems across domestic and overseas Japanese-owned facilities. METI enforces Top Runner standards mandating progressive efficiency gains in industrial motors, directly stimulating premium actuator upgrades. Nagoya's automotive stamping plants are unbundling hardware procurement from maintenance contracts to capture standalone software revenue.
India
Production-linked incentives for technical textiles are creating first-mover openings for automated loom controllers and tension sensors. BIS certification requirements for electrical control gear are tightening, compelling foreign suppliers to establish local testing partnerships. Gujarat's textile clusters are deploying sensor-integrated packaging lines under PLI scheme eligibility rules.
South Korea
Semiconductor cleanrooms across Gyeonggi Province are displacing single-function sensors with combined temperature-humidity-pressure units. Regional system integrators are capturing predictive analytics deployment contracts separated from hardware sales. Samsung and SK Hynix supplier parks near Seoul are driving multi-parameter environmental sensor demand.
Vietnam
Underpenetrated precision agriculture and food processing automation present white space for sensor-integrated packaging lines in northern industrial zones. E-commerce fulfillment centers in Hai Phong and Bac Ninh are creating first-mover demand for warehouse automation components. Foreign direct investment in smart factory certification is accelerating controller deployments in electronics assembly plants.
Asia-Pacific Automation Components Market Competitive Landscape
Capability concentration sits with precision servo specialists; scale advantage sits with diversified industrial conglomerates. The vendor base organizes around three tiers: integrated automation platforms with software layering revenue, component specialists with regional manufacturing footprints, and system integrators capturing unbundled service contracts. Consolidation pressure is intensifying as firmware complexity creates vendor stickiness in controller and drive segments. Dominant competitive moves include strategic partnerships for local certification compliance and portfolio diversification into edge analytics software.
Within the integrated platform tier, Siemens AG and ABB Ltd. exemplify vendors leveraging digital twin architectures to capture recurring software income. Mitsubishi Electric Corporation occupies a position representing precision servo dominance in Japanese markets with regional extension across ASEAN automotive facilities. Among Germany-based industrial conglomerates, Bosch Rexroth AG sits within the drive systems archetype. These three anchors illustrate how firmware subscriptions atop hardware sales are redistributing margin pools toward predictive maintenance contracts in Japanese-owned regional facilities.
| Leading Market Players |
|---|
| Rockwell Automation, Inc. |
| Siemens AG |
| ABB Ltd. |
| Schneider Electric SE |
| Mitsubishi Electric Corporation |
| Emerson Electric Co. |
| Nidec Corporation |
| Omron Corporation |
| Bosch Rexroth AG |
| Others |
Value Network & Pricing Analysis
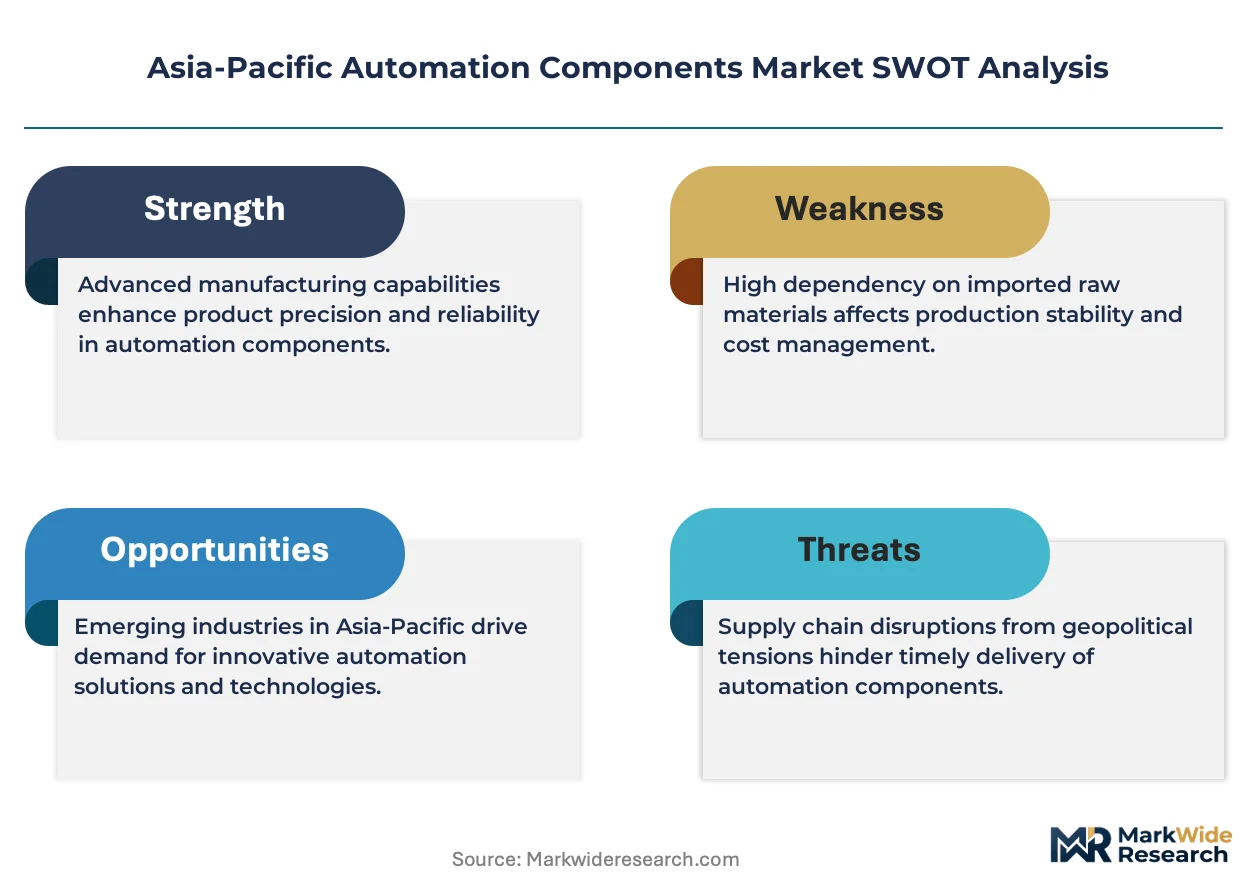
Rare earth processing concentration in China's Jiangxi and Inner Mongolia provinces funnels margin capture toward magnet-dependent servo motor tiers, forcing Japanese and European suppliers to absorb neodymium volatility through ferrite-assisted redesigns or pass-through contract structures.
Pricing Analysis
Long-term offtake contracts dominate controller and drive procurement from tier-one automotive OEMs, while spot-market spot-buying persists for standard sensors in fragmented logistics applications. Three-tier pricing structure across premium, standard, and economy levels separates IEC-certified safety controllers from uncertified alternatives and gray-market imports. Cost compression in standard-grade drives is intensifying because Chinese domestic suppliers are scaling localized IGBT production. Automotive OEMs in the Yangtze River Delta exhibit lowest price sensitivity due to electrification mandates, whereas Vietnamese packaging integrators face acute margin pressure.
Supply Chain Analysis
Export-control regimes limiting semiconductor lithography equipment flows into China are diverting advanced controller chip sourcing toward South Korean and Taiwanese foundries. Geographic supply concentration clusters in China for rare earth magnet processing, Japan for precision servo motors, and Germany for high-voltage drive systems. Raw material dependencies draw from neodymium-iron-boron magnets, silicon carbide substrates, and high-grade copper windings. Single-source vulnerability in Chinese rare earth separation capacity exposes servo motor manufacturers to input disruption. Distribution runs through authorized distributor networks in Japan and South Korea, direct OEM contracts in China, and system integrator channels in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware complexity in closed-loop control systems has created a talent scarcity for embedded software engineers capable of certifying functional safety under GB/T 20438, concentrating value capture with vendors who have already cleared eighteen-month compliance timelines.
For Market Incumbents: Harden software-defined architecture positions by acquiring edge analytics startups with proven semiconductor cleanroom deployments, insulating against unbundling pressure from South Korean integrators. Deepen backward integration into ferrite magnet supply to offset Chinese neodymium concentration risk. Prioritize GB/T 20438 pre-certification investments to compress future market entry delays for next-generation safety controllers. For New Entrants and Emerging Players: Build out Vietnam's northern industrial zones as a beachhead for sensor-integrated food packaging lines, where precision agriculture automation remains underpenetrated versus saturated automotive corridors. Target India's technical textile clusters under PLI scheme eligibility rules for automated loom controller pilots. Lead with subscription-based predictive maintenance pricing to bypass capital-intensive hardware margin competition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision servo specialists in Japan's Nagoya corridor holding METI-compliant IE4 actuator portfolios but lacking digital twin software layering. Five-to-ten-year viability hinges on recurring revenue ratios exceeding hardware replacement cycles. Watch for unbundling acceleration in South Korean semiconductor supplier parks as the signal for service-margin redistribution inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Subscription Layering | Siemens AG and ABB Ltd. capture recurring income from predictive maintenance contracts in Japanese-owned ASEAN facilities. |
| Localized Drive Manufacturing | ABB Ltd.'s Shanghai and Bangalore plants shorten delivery timelines for Yangtze River Delta battery assembly lines. |
| GB/T 20438 Pre-Certification | Early SIL compliance investments compress eighteen-month market entry delays for imported safety controllers. |
| Ferrite-Assisted Magnet Design | Mitsubishi Electric Corporation reduces rare earth content while maintaining torque density under METI efficiency mandates. |
| Edge Analytics Partnership | Regional integrators in South Korea capture predictive deployment contracts separated from hardware procurement. |
Research Methodology
A spread of perspectives from plant engineers at automotive battery facilities, procurement leads at Japanese-owned ASEAN electronics plants, aftermarket service heads at regional system integrators, and regulatory affairs specialists navigating SAMR GB standards converged on the working assumptions. Primary interview insights were cross-checked against secondary sources including SAMR functional safety filings, METI Top Runner efficiency benchmarks, BIS electrical control gear certifications, and ASEAN Board of Investment smart factory incentive disclosures. Bottom-up component demand modeling was triangulated with top-down industrial automation capex tracking.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type (controllers, sensors, actuators, drives), application (manufacturing, logistics, oil and gas, aerospace), end user (manufacturers, OEMs, distributors, integrators), and technology (IoT, robotics, cloud computing, AI). CAGRs were derived from installed base refresh rates under regulatory compression scenarios and greenfield capacity expansion in electrification corridors. Forecast inputs incorporated neodymium price volatility bands and 5G private network deployment trajectories for digital twin latency reduction.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic drive suppliers into premium servo tiers would shift outcomes. Material shifts in METI efficiency benchmark stringency or SAMR import certification timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Robot Gearboxes Market
Industrial Automation
Asia Pacific Sortation Systems Market
Industrial Automation
Motion Positioning Stages Market
Industrial Automation
Asia Pacific Manufacturing Execution Systems (MES) Market
Industrial Automation
Smart Warehouse Technologies Market
Industrial Automation
Parcel Sortation Systems Market
Industrial Automation
Robotic Paint Booth Market
Industrial Automation
Global Smart Warehousing Market
Industrial Automation
Multi-Axis Motion Controller Market
Industrial Automation
North America Human Machine Interface Market
Industrial Automation
Palletizing Systems Market
Industrial Automation
Predictive Maintenance for Manufacturing Market
Industrial Automation
Motion Control Market
Industrial Automation
Global Programmable Logical Controllers Automation Market
Industrial Automation
Global Smart Manufacturing Platform Market
Industrial Automation
Global Mining Automation Consumption Market