
 HMI Market | 2026-2036
HMI Market Size, Share, and Industry Trends Forecast 2026-2036
HMI Market Outlook
Software-defined licensing for HMI runtime environments is realigning vendor revenue models away from perpetual hardware sales. Rockwell Automation leverages its FactoryTalk platform to sustain recurring service attach rates across North American automotive plants. Siemens anchors European demand through its TIA Portal ecosystem, while Mitsubishi Electric competes aggressively in Asian machine tool applications.
Human-machine interface systems encompass hardware and software layers enabling operator interaction with industrial control systems, typically integrating resistive or capacitive touch panels with OPC-UA and MQTT protocol support for real-time data exchange. These systems serve as the primary visual and control bridge between human operators and automated production equipment. Touchscreen technology dominates current installations, though voice recognition segments are expanding fastest in hands-constrained environments such as pharmaceutical cleanrooms. Among end users, system integrators capture disproportionate margin pools by bundling custom SCADA visualization with HMI hardware deployment.
FDA 21 CFR Part 11 requirements in pharmaceutical manufacturing and IEC 62443 cybersecurity standards in critical infrastructure are tightening validation protocols for HMI software deployments. EUs Machinery Directive and CE marking obligations further constrain interface design for exported European equipment. Stakeholders must monitor how NIST cybersecurity framework updates in the United States and evolving MEE emissions standards in China reshape certification timelines for next-generation interface platforms.
Market Dynamics
Industrial automation deployments across automotive assembly lines are accelerating interface complexity requirements. IEC 62443 cybersecurity standards for operational technology are reshaping product certification pathways while software-defined licensing realigns vendor revenue models away from perpetual hardware sales.
Growth Catalysts
- Automotive Electrification:Battery assembly lines in Germany require multi-touch HMI panels with real-time torque monitoring. Siemens and Bosch smart factory investments are standardizing OPC-UA protocol integration across supplier tiers.
- IEC 62443 Mandates:Critical infrastructure operators in the United States must deploy security level 3 certified interfaces. NERC CIP alignment is forcing hardware refresh cycles in power generation facilities.
- Voice Recognition:Hands-constrained pharmaceutical cleanrooms in Switzerland are adopting speech-controlled HMIs. Swissmedic validation requirements for aseptic processing are accelerating this interface modality.
Market Restraints
- Semiconductor Supply Concentration:Display driver IC sourcing from Taiwan creates single-point vulnerability. Foundry capacity allocation favors consumer electronics over industrial panels.
- Legacy Protocol Proliferation:Proprietary fieldbus networks in installed machine bases resist OPC-UA migration. Brownfield integration costs often exceed greenfield deployment budgets.
- Skill Scarcity:Certified IEC 62443 security engineers command premium wages. System integrators report 8-14 month hiring timelines for qualified OT cybersecurity specialists.
Strategic Opportunities
- Indian Pharmaceutical Manufacturing:CDSCO's phased implementation of 21 CFR Part 11 equivalents is creating validation-ready HMI demand. PLI scheme incentives for active pharmaceutical ingredient production are accelerating cleanroom automation.
- Edge-AI Convergence:On-device inference for predictive maintenance alerts is reducing cloud dependency. NVIDIA Jetson and Intel Movidius modules are embedding directly into panel PCs.
- Subscription Licensing:Runtime environment SaaS models capture recurring revenue from automotive OEMs. Ford and Stellantis procurement teams are piloting per-seat HMI software licensing.
Industry Challenges
- Cybersecurity Certification Timelines:IEC 62443 SL3 validation requires 14-18 months of third-party assessment. Product launch windows slip when security audits uncover firmware vulnerabilities.
- Multi-Protocol Integration Complexity:Simultaneous support for EtherCAT, PROFINET, and EtherNet/IP strains embedded processor resources. Engineering teams must optimize stack performance without compromising real-time determinism.
- Intergenerational Workforce Training:Veteran operators resist touchscreen migration from physical pushbuttons. Change management programs in Japanese automotive plants require 6-12 month transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HMI Market |
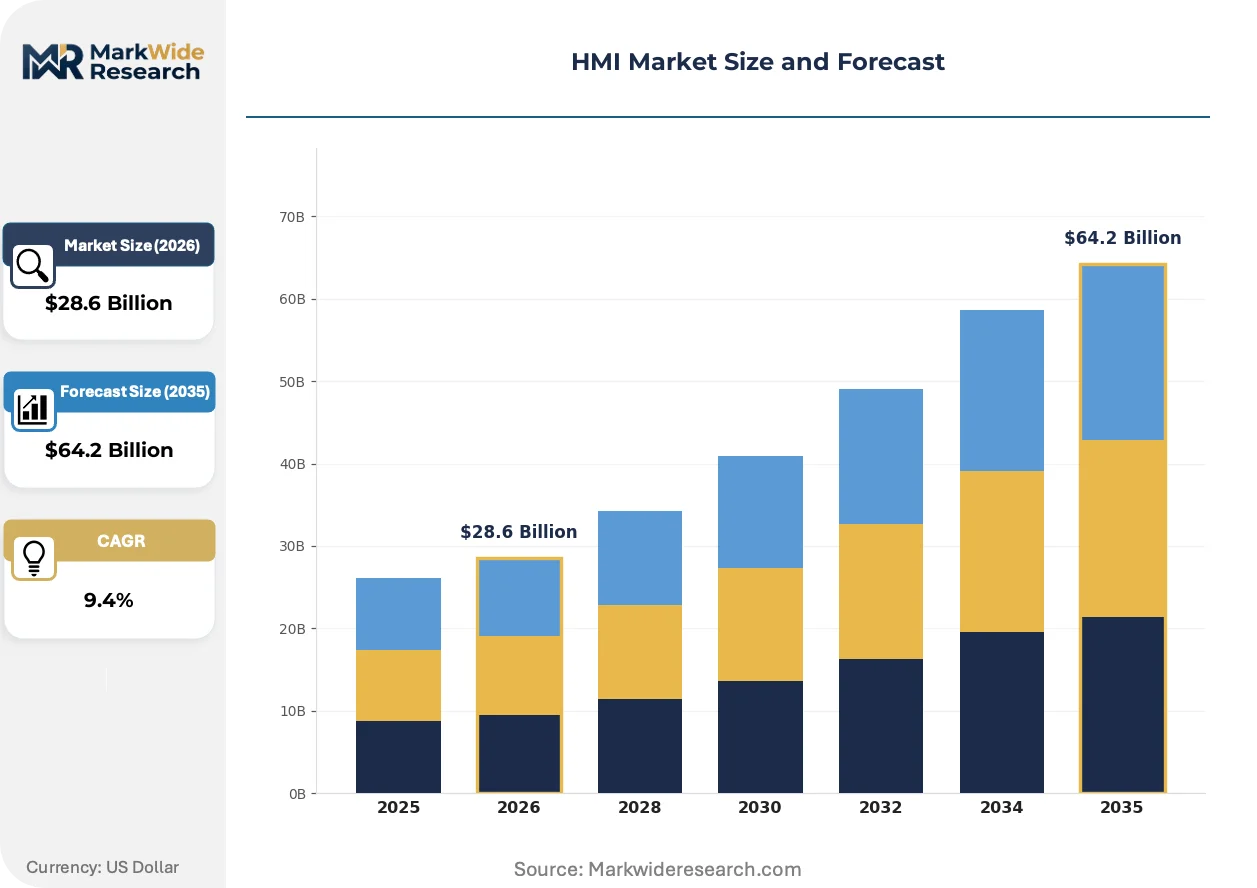
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Touchscreen, Voice Recognition, Gesture Control, Eye Tracking Application: Automotive, Industrial Automation, Consumer Electronics, Healthcare End User: OEMs, System Integrators, Manufacturers, Software Developers Product Type: Web-Based Interfaces, Mobile Applications, Software Platforms, Standalone Devices |
| Companies Covered | Rockwell Automation, Siemens, Schneider Electric, ABB, Honeywell International Inc., Mitsubishi Electric Corporation, Emerson Electric Co., Yokogawa Electric Corporation, Advantech Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HMI Market Strategic Shifts
Touchscreen technology dominates current installations, though voice recognition segments are expanding fastest in hands-constrained environments. Three developments are redefining how operators interact with automated production equipment.
Projected capacitive touch panels with glove-compatible sensitivity are overtaking resistive alternatives in food processing and pharmaceutical applications. Tyson Foods and Nestlé production facilities are standardizing on projected capacitive interfaces that maintain responsiveness through nitrile and latex barriers. This shift is compressing the addressable market for legacy resistive suppliers while elevating durability specifications for panel seal ratings.
EU Machinery Directive updates and CE marking obligations are constraining interface design for exported European equipment. The directive's revised ergonomic safety requirements mandate minimum font sizes and color contrast ratios for emergency stop visibility. Asian machine tool exporters to Germany are redesigning HMI shells to comply with EN ISO 13849-1 safety integrity levels, adding 8-12 weeks to product development cycles.
Automotive OEM procurement teams are unbundling hardware purchase from software licensing and service contracts. Tier-1 system integrators now face margin pressure as Ford, BMW, and Hyundai Motor Group negotiate direct runtime licenses with Rockwell Automation and Siemens. This disintermediation is most visible in North American electric vehicle battery gigafactories, where OEMs seek to reduce lifetime cost of ownership through subscription-based visualization platforms.
HMI Market Segmentation
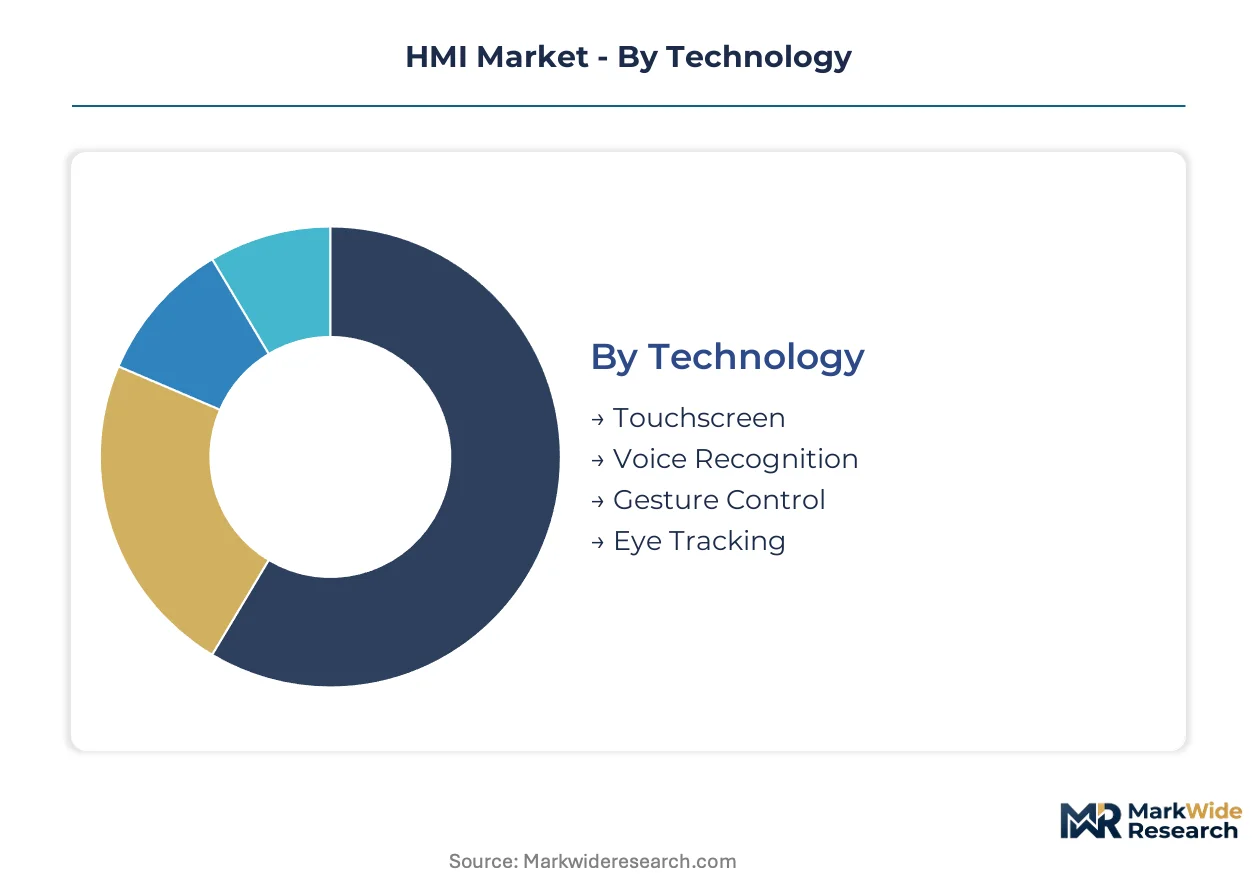
HMI market segmentation reveals how interface modalities, deployment contexts, and procurement models create distinct competitive arenas. Technology choices determine hardware margins, while application verticals dictate certification requirements and customer lifetime value.
Technology:
Interface modality selection hinges on environmental constraints, operator safety protocols, and the precision requirements of underlying control systems.
- Touchscreen:Projected capacitive panels with glove-compatible sensitivity dominate food processing and pharmaceutical cleanrooms. Tyson Foods and Nestlé facilities standardize on these interfaces for nitrile and latex barrier compatibility. This segment leads on scale; voice recognition leads on momentum.
- Voice Recognition:Speech-controlled HMIs are expanding most quickly in hands-constrained pharmaceutical cleanrooms in Switzerland. Swissmedic validation requirements for aseptic processing accelerate this modality's deployment where physical contact risks contamination.
- Gesture Control:Contactless operation suits hazardous chemical environments and sterile surgical suites. BMW assembly pilots evaluate mid-air gesture systems for paint shop applications where glove changes disrupt workflow.
- Eye Tracking:Gaze-directed interfaces serve mobility-impaired operators and high-cognitive-load monitoring stations. Aviation and power generation control rooms pilot this technology for hands-free alarm acknowledgment.
Touchscreen leads on scale; voice recognition leads on momentum.
Application:
End-use verticals impose divergent regulatory frameworks, cycle time demands, and operator skill profiles on interface design.
- Automotive:Battery gigafactories in Germany and the United States drive multi-touch panel demand with real-time torque monitoring requirements. Ford and Stellantis procurement teams pilot subscription licensing models to reduce lifetime ownership costs.
- Industrial Automation:IEC 62443 SL3 certification mandates in critical infrastructure force 14-18 month validation timelines. Power generation facilities align with NERC CIP requirements, accelerating hardware refresh cycles.
- Consumer Electronics:High-volume, low-margin production favors standardized interface modules. This segment concentrates manufacturing in Asian electronics clusters with rapid design iteration cycles.
- Healthcare:FDA 21 CFR Part 11 and EMA validation protocols constrain software deployment in pharmaceutical manufacturing. Cleanroom automation in Switzerland and Germany elevates voice and gesture modalities over touch.
Automotive commands revenue concentration; healthcare shows the steepest expansion trajectory from regulatory-driven upgrade cycles.
End User:
Procurement authority and technical integration depth vary sharply across customer types, reshaping vendor go-to-market economics.
- OEMs:Automotive and machinery builders increasingly unbundle hardware purchase from software licensing. Direct runtime license negotiations with Rockwell Automation and Siemens disintermediate traditional system integrator relationships.
- System Integrators:These players capture disproportionate margin pools by bundling custom SCADA visualization with HMI hardware deployment. Brownfield integration expertise commands premium pricing where legacy protocol proliferation resists OPC-UA migration.
- Manufacturers:End-user factories prioritize total cost of ownership and operator training minimization. Japanese automotive plants require 6-12 month change management programs for touchscreen migration from physical pushbuttons.
- Software Developers:Runtime environment specialists supply SaaS licensing models for visualization platforms. Subscription revenue streams from automotive OEMs realign vendor economics away from perpetual hardware sales.
System integrators lead on margin capture; OEMs lead on procurement influence.
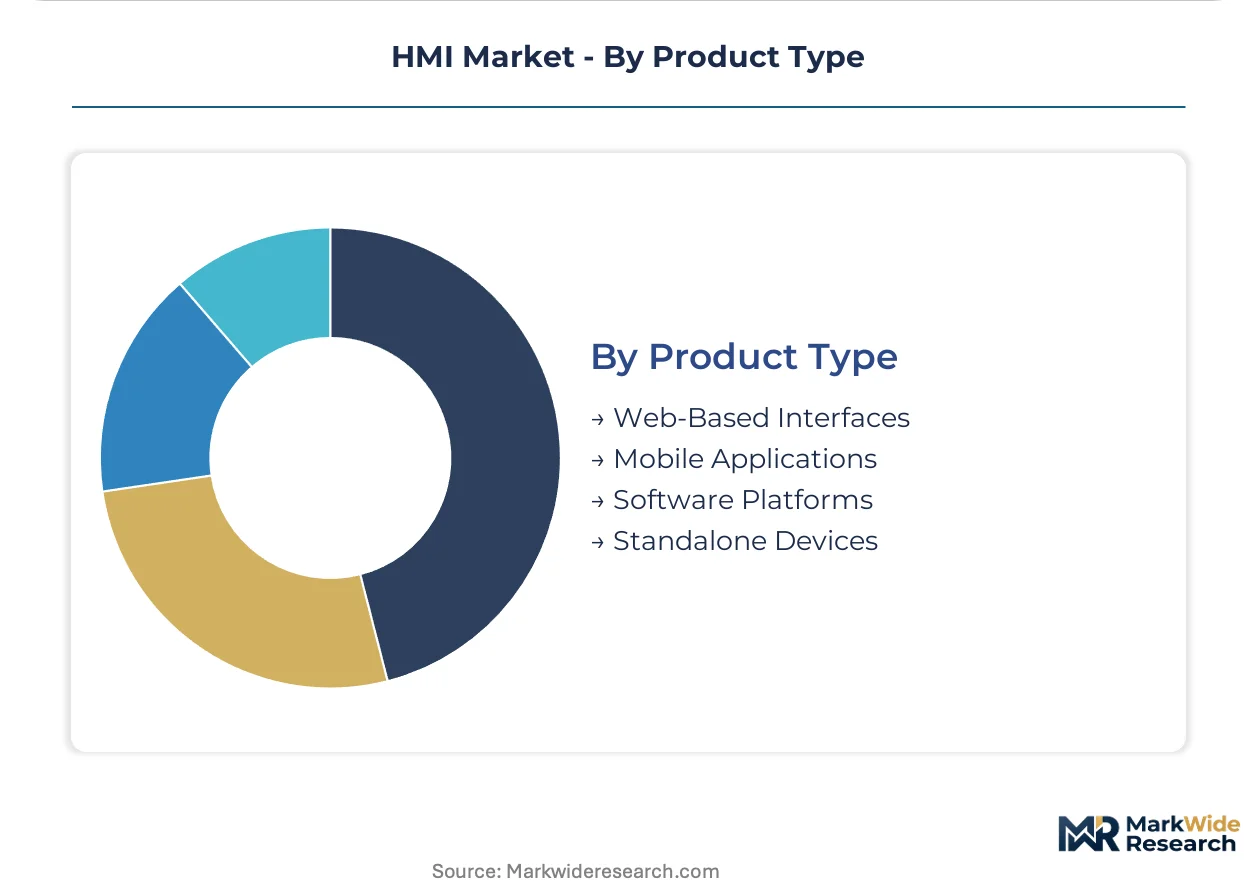
Product Type:
Delivery architecture determines deployment flexibility, update velocity, and cybersecurity attack surface exposure.
- Web-Based Interfaces:Browser-rendered HMIs enable centralized update distribution and reduce on-premise software maintenance. Cloud dependency concerns limit adoption in IEC 62443-mandated critical infrastructure environments.
- Mobile Applications:Tablet and smartphone-based operator interfaces support roaming maintenance staff. Ford and BMW production facilities evaluate bring-your-own-device policies against cybersecurity hardening requirements.
- Software Platforms:Siemens TIA Portal and Rockwell FactoryTalk anchor integrated development environments. These ecosystems lock in recurring service attach rates through protocol compatibility and certified hardware pairing.
- Standalone Devices:Embedded panel PCs with edge-AI modules reduce latency for predictive maintenance alerts. NVIDIA Jetson and Intel Movidius processors embed directly into hardened industrial enclosures.
Software platforms lead on ecosystem stickiness; web-based interfaces lead on deployment velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial automation density outpaces India's pharmaceutical cleanroom buildout, though both drive divergent HMI specification requirements across their respective manufacturing bases.
Germany
Battery gigafactories and automotive assembly lines demand multi-touch panels with real-time torque monitoring. IEC 62443 SL3 certification mandates reshape vendor qualification timelines. Bavaria and Baden-Württemberg concentrate Siemens and Bosch smart factory investments.
United States
Electric vehicle battery plants and power generation facilities accelerate hardware refresh cycles. NERC CIP alignment forces security-certified interface deployments. Michigan and Tennessee automotive clusters pilot subscription licensing models with Rockwell Automation.
China
Machine tool manufacturers and consumer electronics assembly drive standardized module demand. MEE emissions standards and GB certification protocols constrain interface design for domestic and export equipment. Yangtze River Delta electronics clusters favor rapid design iteration cycles.
Switzerland
Pharmaceutical cleanrooms in Basel and Geneva adopt voice-controlled HMIs for aseptic processing. Swissmedic validation requirements accelerate hands-free interface modalities. Nestlé production facilities standardize on projected capacitive touch panels.
India
Active pharmaceutical ingredient production under PLI scheme incentives creates validation-ready HMI demand. CDSCO's phased 21 CFR Part 11 equivalent implementation tightens software deployment protocols. Maharashtra and Gujarat pharmaceutical clusters drive cleanroom automation investments.
HMI Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated automation conglomerates commanding ecosystem stickiness while hardware fabricators compete on panel durability specifications. The vendor base concentrates around three strategic archetypes: full-stack automation platforms, display hardware specialists, and software runtime licensors. M&A activity targets cybersecurity certification capabilities, while capacity expansion focuses on glove-compatible projected capacitive panel production.
Among Germany-based industrial conglomerates, Siemens anchors European demand through integrated development environments. Rockwell Automation exemplifies the North American platform-centric archetype with recurring service attach models. Mitsubishi Electric occupies a position within Asian machine tool applications, competing on embedded processor optimization for multi-protocol environments.
| Leading Market Players |
|---|
| Rockwell Automation |
| Siemens |
| Schneider Electric |
| ABB |
| Honeywell International Inc. |
| Mitsubishi Electric Corporation |
| Emerson Electric Co. |
| Yokogawa Electric Corporation |
| Advantech Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Automotive OEM procurement teams in Germany and the United States are consolidating direct licensing negotiations with Rockwell Automation and Siemens, shifting vendor economics from perpetual hardware sales toward recurring SaaS revenue models. This buyer concentration intensifies price transparency and compresses margins for system integrators caught between unbundled software contracts and panel hardware commoditization.
Pricing Analysis
Capacity additions in China's Yangtze River Delta panel manufacturing clusters are reshaping price floors for standardized resistive touch modules. Three-tier pricing structure across premium certified, standard industrial, and economy commercial levels reflects IEC 62443 SL3 validation costs and glove-compatible projected capacitive sensitivity grades. Cost compression in economy tiers stems from foundry capacity allocation favoring consumer electronics over industrial displays. Automotive OEMs exhibit lowest price sensitivity due to total cost of ownership frameworks, while small machine tool builders in Asia face acute margin pressure.
Supply Chain Analysis
Display driver IC supply rests on Taiwanese foundry capacity and South Korean specialty semiconductor producers, with Japanese substrate material providers anchoring upstream tiers. Projected capacitive sensor glass, edge-AI inference modules from NVIDIA Jetson and Intel Movidius, and hardened enclosure aluminum extrusions constitute critical input dependencies. Single-source vulnerability concentrates in Taiwan's foundry allocation decisions for industrial-grade semiconductors. Distribution runs through authorized system integrator channels in Europe and direct OEM procurement desks in North American automotive clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
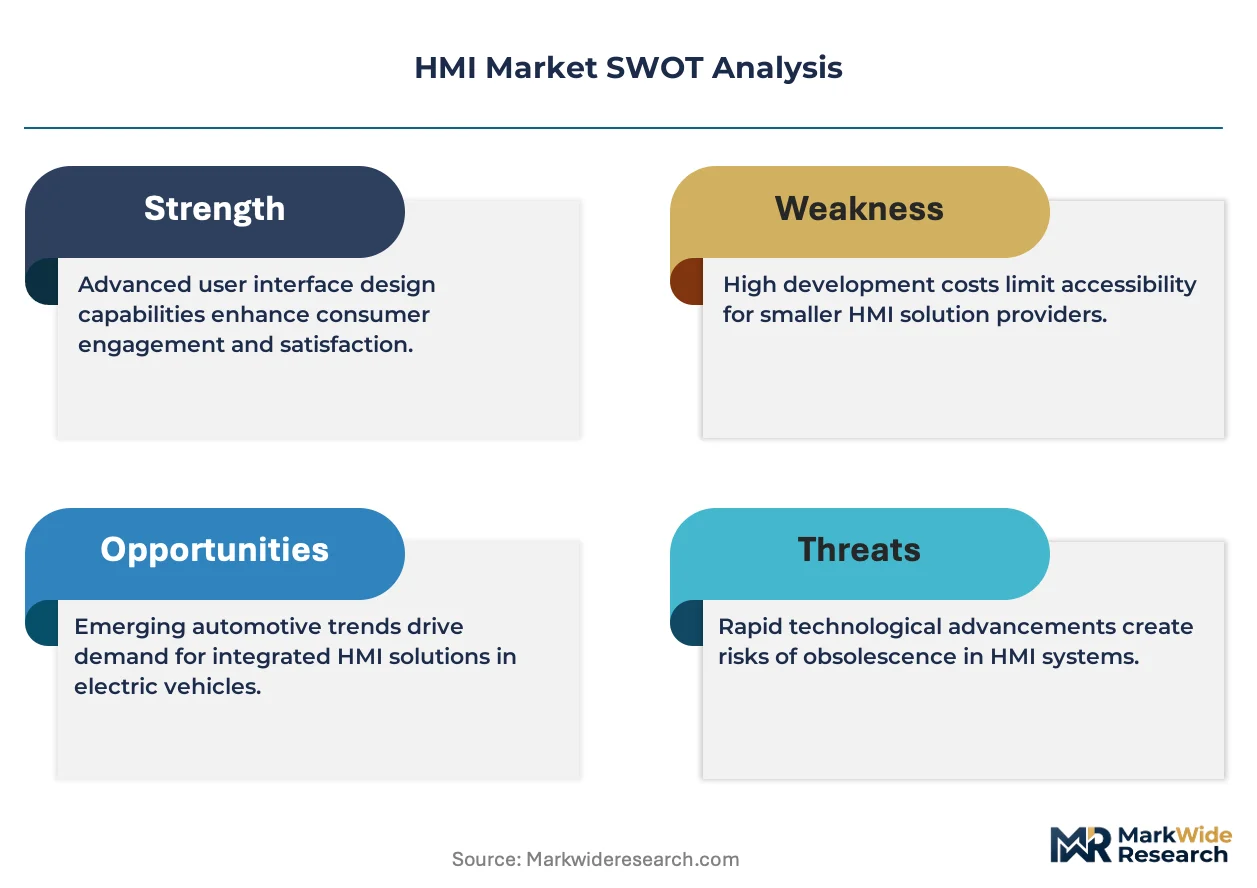
IEC 62443 SL3 certification mandates across critical infrastructure verticals compound demand for validated HMI platforms, creating structural pricing power for security-certified vendors. This regulatory compounding accelerates hardware refresh cycles and elevates cybersecurity engineering capabilities as a scarce, premium-priced input.
For Market Incumbents: Anchor ecosystem stickiness through TIA Portal and FactoryTalk runtime environment lock-in, while acquiring IEC 62443 certification boutiques to compress 14-18 month validation timelines. Defensive moves must address subscription licensing disintermediation by automotive OEMs and voice recognition modality displacement in pharmaceutical cleanrooms. Certification investment in Swissmedic-validated aseptic processing interfaces secures premium tier positioning.
For New Entrants and Emerging Players: The mid-market price-point gap between Siemens premium platforms and economy resistive panel suppliers opens white-space opportunity in Indian pharmaceutical manufacturing under CDSCO's phased 21 CFR Part 11 equivalent implementation. Target cleanroom automation buildouts in Maharashtra and Gujarat with validation-ready, subscription-priced web-based interfaces. Go-to-market leverage rests on bundling edge-AI predictive maintenance modules with hardware-light deployment models.
For Investors and Strategic Acquirers: Industrial automation conglomerates are the most active acquirer in this space, seeking cybersecurity certification capabilities and glove-compatible projected capacitive production capacity. Long-term viability favors vendors with recurring software revenue attach rates above 60 percent and validated positions in automotive battery gigafactory supply chains. Watch for IEC 62443 SL3 audit backlog duration as inflection indicator for certification-constrained supply.
| Strategic Initiative | Industry Significance |
|---|---|
| IEC 62443 SL3 Certification Investment | Accelerates vendor qualification timelines for NERC CIP-aligned power generation deployments. |
| Edge-AI Module Integration | NVIDIA Jetson embedding enables on-device predictive maintenance without cloud dependency. |
| Subscription Licensing Transition | Ford and Stellantis pilots demonstrate recurring revenue capture from automotive OEM procurement. |
| Projected Capacitive Capacity Expansion | Glove-compatible sensitivity production serves Tyson Foods and Nestlé food processing standardization. |
| Voice Recognition Validation Pathway | Swissmedic-compliant aseptic processing interfaces unlock pharmaceutical cleanroom premium pricing. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers, OEM procurement teams, system integrator technical leads, and aftermarket service heads with secondary validation against SEC filings, customs trade records, IEC certification registries, and automotive production databases. Bottom-up panel shipment aggregation and top-down automation spend allocation provided cross-check triangulation.
Comparable-period anchoring linked projection horizons to historical HMI deployment cycles in automotive electrification and pharmaceutical cleanroom buildouts. Segmentation dimensions spanned interface modality, application vertical, end-user procurement authority, and delivery architecture across the modeling period. CAGRs derived from installed base replacement rates, greenfield automation capex trajectories, and protocol migration timelines for OPC-UA adoption.
Caveats apply where semiconductor foundry capacity reallocation, IEC 62443 audit backlog extension, or automotive OEM insourcing of visualization software could materially shift the outlook. Forecasts embed assumptions regarding certification timeline stability and subscription licensing adoption velocity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Industrial Human-Machine Interface Market
Industrial Automation
India Industrial Automation Market
Industrial Automation
Global Automated Truck Loading System Market
Industrial Automation
Smart Sorting Line Market
Industrial Automation
Programmable Logic Controller Market
Industrial Automation
Warehouse Automation Equipment Market
Industrial Automation
China Factory Automation and Industrial Controls Market
Industrial Automation
Industrial Multiprotocol Gateways Market
Industrial Automation
Asia-Pacific Programmable Logic Controller Market
Industrial Automation
Modular High-Bay Solutions Market
Industrial Automation
Asia Pacific Warehouse Automation Market
Industrial Automation
Grippers Market
Industrial Automation
Warehouse Automation Solutions Market
Industrial Automation
Latin America Automated Storage and Retrieval System Market
Industrial Automation
Global Programmable Logical Controllers Automation Market
Industrial Automation
Smart Escalator Market