
 Global Plasma Derived Therapy Market | 2026-2036
Global Plasma Derived Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plasma Derived Therapy Market Foresight
United States fractionation capacity is reshaping supply dynamics for plasma-derived proteins. CSL Behring leverages vertical integration across plasma collection and finished-dose manufacturing to sustain competitive moats. Takeda Pharmaceutical Company Limited anchors its position through R&D intensity in immunoglobulin therapies. Grifols dominates the European collection network while extending manufacturing scale across Iberian facilities.
Plasma derived therapy comprises biologically active proteins extracted from human plasma through cold ethanol fractionation or chromatographic purification, yielding immunoglobulins, albumin, coagulation factors, and hyperimmune globulins with defined purity thresholds and viral safety profiles. These therapies replace deficient proteins, modulate immune responses, or confer passive immunity in clinical settings ranging from inherited disorders to acute trauma. Immunoglobulins occupy the largest margin pool given chronic administration in primary immunodeficiency and autoimmune neuropathies. Coagulation factors compete on recombinant substitution risk but retain entrenched demand in hemophilia with inhibitors. Subcutaneous delivery mode is gaining fastest as patients shift from hospital-based intravenous infusion toward self-administration protocols.
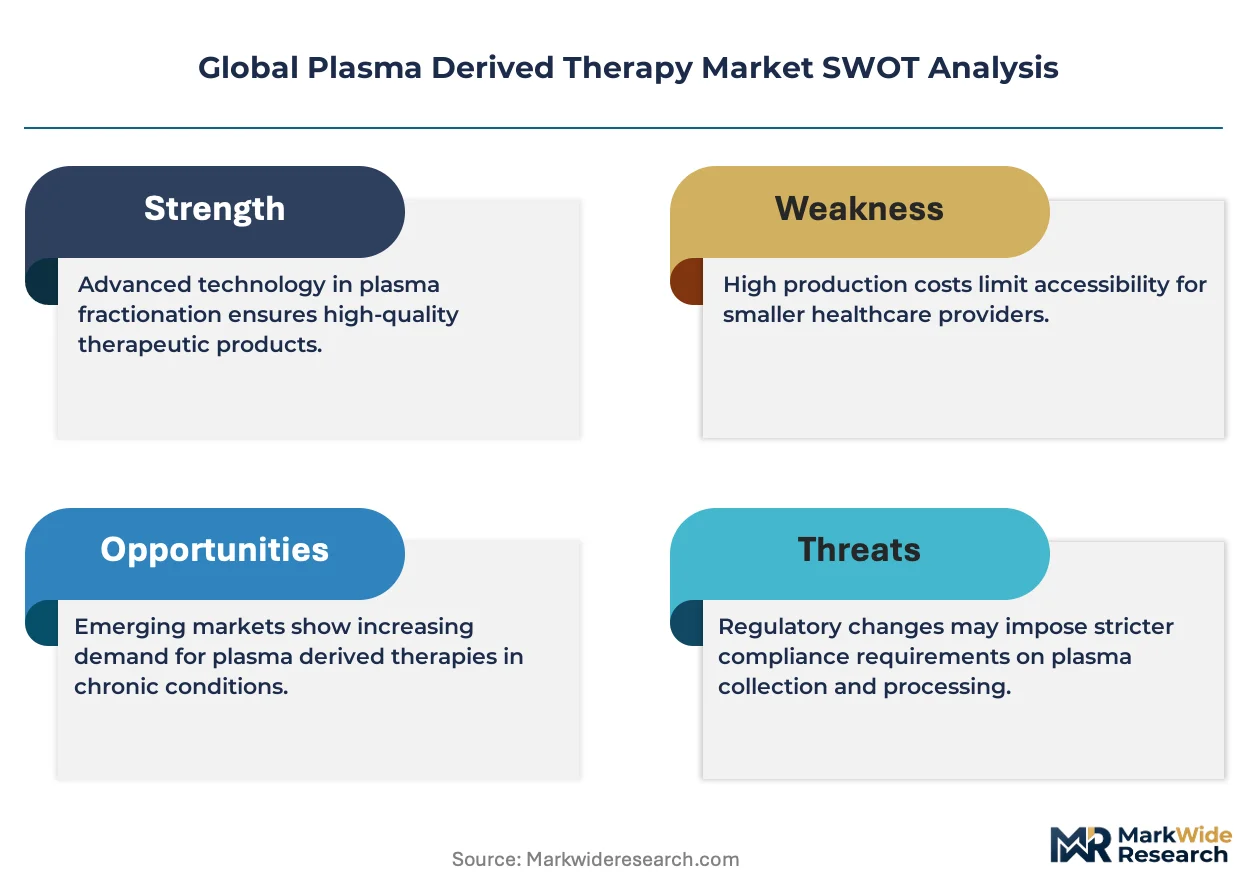
FDA plasma-sourcing guidelines, EU F-Gas Regulation, and WHO plasma quality standards collectively elevate barriers to market entry while mandating pathogen-reduction technologies across collection networks. EMA's MDR framework further tightens traceability requirements for plasma-derived medicinal products, redirecting procurement toward certified fractionators. Stakeholders must monitor regulatory divergence between FDA and EMA on emerging pathogen threats while calibrating capacity investments against collection economics.
Market Dynamics
Fractionation capacity concentration across the United States, Germany, and Japan is tightening plasma supply allocation while subcutaneous immunoglobulin protocols pull patient administration away from hospital infusion centers toward home-based care models.
Growth Catalysts
- FDA plasma-sourcing guidelines:These standards mandate pathogen-reduction technologies that elevate viral safety profiles and accelerate certified fractionator procurement by hospital pharmacies.
- Primary immunodeficiency patient pools:Chronic immunoglobulin administration requirements in autoimmune neuropathies sustain recurring demand with limited therapeutic substitution options.
- EU F-Gas Regulation:Cold chain infrastructure investments compliant with this framework enable plasma collection network expansion across Iberian and Central European collection sites.
Market Restraints
- Plasma donation economics:Donor compensation inflation and collection center operating costs compress margin structures for independent plasma collectors.
- Recombinant coagulation factor substitution:Hemophilia treatment centers increasingly prescribe recombinant alternatives for non-inhibitor patients, eroding plasma-derived factor VIII volume.
- EMA MDR traceability mandates:Certification timelines for plasma-derived medicinal products extend qualification periods and concentrate procurement among established fractionators.
Strategic Opportunities
- Japan domestic fractionation buildout:METI-supported capacity investments reduce import dependency and create captive supply arrangements for regional immunoglobulin demand.
- Chromatographic purification convergence:Integration of affinity chromatography with nanofiltration yields higher-purity immunoglobulin fractions with improved yield economics.
- Specialty infusion center networks:These channels bypass hospital pharmacy procurement bottlenecks and capture margin from self-administration protocol transitions.
Industry Challenges
- Fractionation specialist talent scarcity:Cold ethanol process engineering expertise concentrates among legacy Cohn fractionation facilities with limited training pipeline expansion.
- Viral safety validation timelines:FDA and EMA divergence on emerging pathogen threat assessment protocols complicates unified submission strategies for new plasma-derived products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plasma Derived Therapy Market |
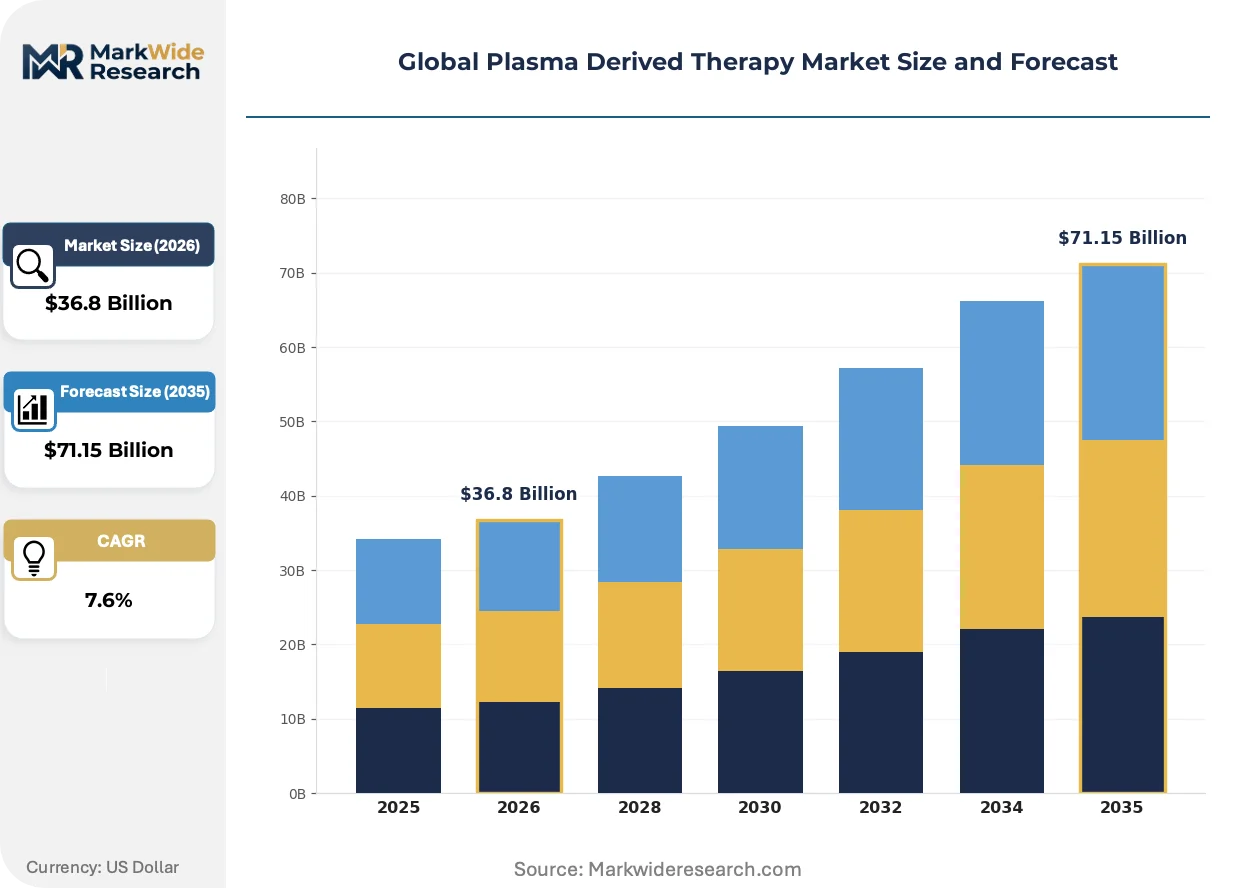
| Market Size in 2026 | $36.8 Billion |
| Market Size in 2035 | $71.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoglobulins, Albumin, Coagulation Factors, Hyperimmune Globulins, Others Application: Immunodeficiency, Hemophilia, Autoimmune Disorders, Infectious Diseases, Trauma Care End User: Blood Banks, Specialty Clinics, Research Institutes, Transfusion Centers Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral, Nasal |
| Companies Covered | CSL Behring, Takeda Pharmaceutical Company Limited, Grifols, Octapharma, Kedrion, ADMA Biologics, Biotest AG, Bio Products Laboratory, Kamada, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plasma Derived Therapy Market Shifts & Advancements
Plasma-derived therapy production is pivoting toward patient-centric delivery models while regulatory frameworks harden traceability requirements and purification technologies advance yield efficiency.
Chromatographic purification is hybridizing with traditional cold ethanol fractionation to produce higher-specific-activity immunoglobulin concentrates. Academic medical centers in Germany and Japan are piloting these hybrid processes for specialty hyperimmune globulin manufacturing. The technology is compressing batch cycle times while meeting EMA MDR purity thresholds that ethanol-only methods struggle to achieve.
EU F-Gas Regulation enforcement is redirecting cold chain infrastructure investments toward lower-global-warming-potential refrigerants across plasma collection networks. Fractionators operating Iberian and Central European collection centers face accelerated retrofit timelines. German facilities are responding with ammonia-based secondary refrigeration systems that maintain plasma integrity during extended transport legs.
Self-administration protocols are displacing hospital-based intravenous infusion for primary immunodeficiency maintenance therapy. Home healthcare distributors and specialty pharmacies are capturing patient volume previously routed through hospital outpatient departments. United States immunoglobulin prescribing patterns show the strongest shift, with subcutaneous 20% formulations enabling weekly patient-managed dosing without nursing supervision.
Global Plasma Derived Therapy Market Segmentation
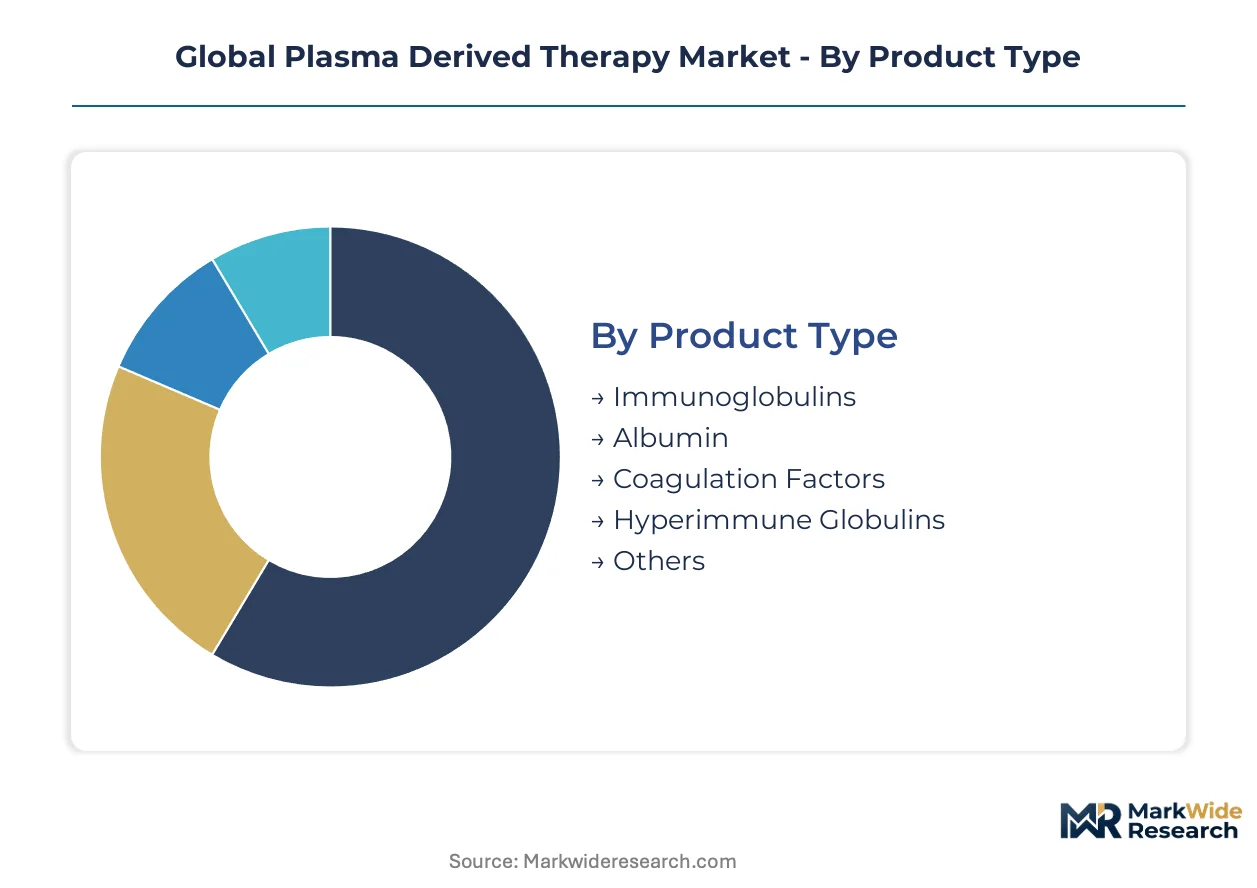
Plasma-derived therapy segmentation reflects divergent clinical workflows, reimbursement pathways, and manufacturing economics across immunoglobulin, albumin, and coagulation factor portfolios. Understanding these partitions clarifies where fractionators must align purification investments with patient administration preferences.
Product Type:
Use-case spectrum spans chronic replacement therapy, acute volume resuscitation, and targeted immune modulation across hospital and ambulatory settings.
- Immunoglobulins:Polyclonal antibody concentrates derived from pooled plasma fractionation, standardized to IgG subclasses with defined Fc functionality. Demand concentrates in United States specialty infusion centers and German hospital pharmacies as primary immunodeficiency diagnoses expand and subcutaneous self-administration protocols displace intravenous dependency.
- Albumin:Heat-stabilized plasma protein fraction with colloid osmotic pressure maintenance properties, supplied in iso-oncotic and hyper-oncotic concentrations. Japanese trauma centers and German hepatology units anchor procurement volume, though synthetic colloid substitution and albumin-sparing surgical techniques constrain expansion in elective procedures.
- Coagulation Factors:Plasma-derived factor VIII, factor IX, and prothrombin complex concentrates for hemophilia and acquired coagulopathy management.
- Hyperimmune Globulins:Pathogen-specific antibody concentrates from vaccinated donor plasma, including hepatitis B, rabies, and tetanus immunoglobulins.
- Others:Alpha-1 proteinase inhibitor, C1 esterase inhibitor, and fibrin sealant preparations for niche indications.
Established volume favors immunoglobulins; emerging adoption favors hyperimmune globulins as pandemic preparedness programs stockpile targeted antibody therapies.
Application:
Cost tier stratification separates chronic maintenance indications with predictable reimbursement from acute intervention categories vulnerable to protocol substitution.
- Immunodeficiency:Lifelong immunoglobulin replacement for primary antibody deficiencies including common variable immunodeficiency and X-linked agammaglobulinemia. United States and German prescribing patterns show strongest subcutaneous transition, pulling patient volume toward home healthcare channels and compressing hospital outpatient department margins.
- Hemophilia:Factor replacement for hemophilia A and B, with plasma-derived products retaining entrenched demand in inhibitor patients where recombinant bypass agents prove insufficient. Japanese hemophilia treatment centers maintain higher plasma-derived factor VIII share than United States or European counterparts due to historical supply arrangements and patient antibody profiles.
- Autoimmune Disorders:Intravenous immunoglobulin for chronic inflammatory demyelinating polyneuropathy, multifocal motor neuropathy, and dermatomyositis.
- Infectious Diseases:Hyperimmune globulin prophylaxis and convalescent plasma protocols for emerging viral threats.
- Trauma Care:Massive transfusion protocols incorporating plasma, albumin, and fibrinogen concentrates.
Reimbursement stability favors immunodeficiency; protocol innovation favors autoimmune disorders as neurology departments expand off-label immunoglobulin utilization.
End User:
Customer type fragmentation reflects divergent procurement authority, inventory holding capacity, and patient throughput economics across collection and clinical sites.
- Blood Banks:National and regional blood collection organizations with integrated plasma procurement and contracted fractionation arrangements. German Red Cross plasma operations and United States community blood centers supply raw material to CSL Behring, Takeda, and Grifols under long-term supply agreements with defined volume commitments and quality specifications.
- Specialty Clinics:Dedicated immunology, hematology, and infusion centers with direct patient relationships and formulary influence. United States specialty infusion networks bypass hospital pharmacy procurement committees, capturing margin from subcutaneous immunoglobulin transitions and home nursing coordination.
- Research Institutes:Academic medical centers and contract research organizations conducting clinical trials for novel plasma-derived indications.
- Transfusion Centers:Hospital-based blood banks and surgical suites managing perioperative plasma component utilization.
Procurement scale favors blood banks; patient access innovation favors specialty clinics as site-of-care migration accelerates.
Delivery Mode:
Supply concentration in intravenous infrastructure confronts patient preference shifts and nursing cost pressures driving alternative administration development.
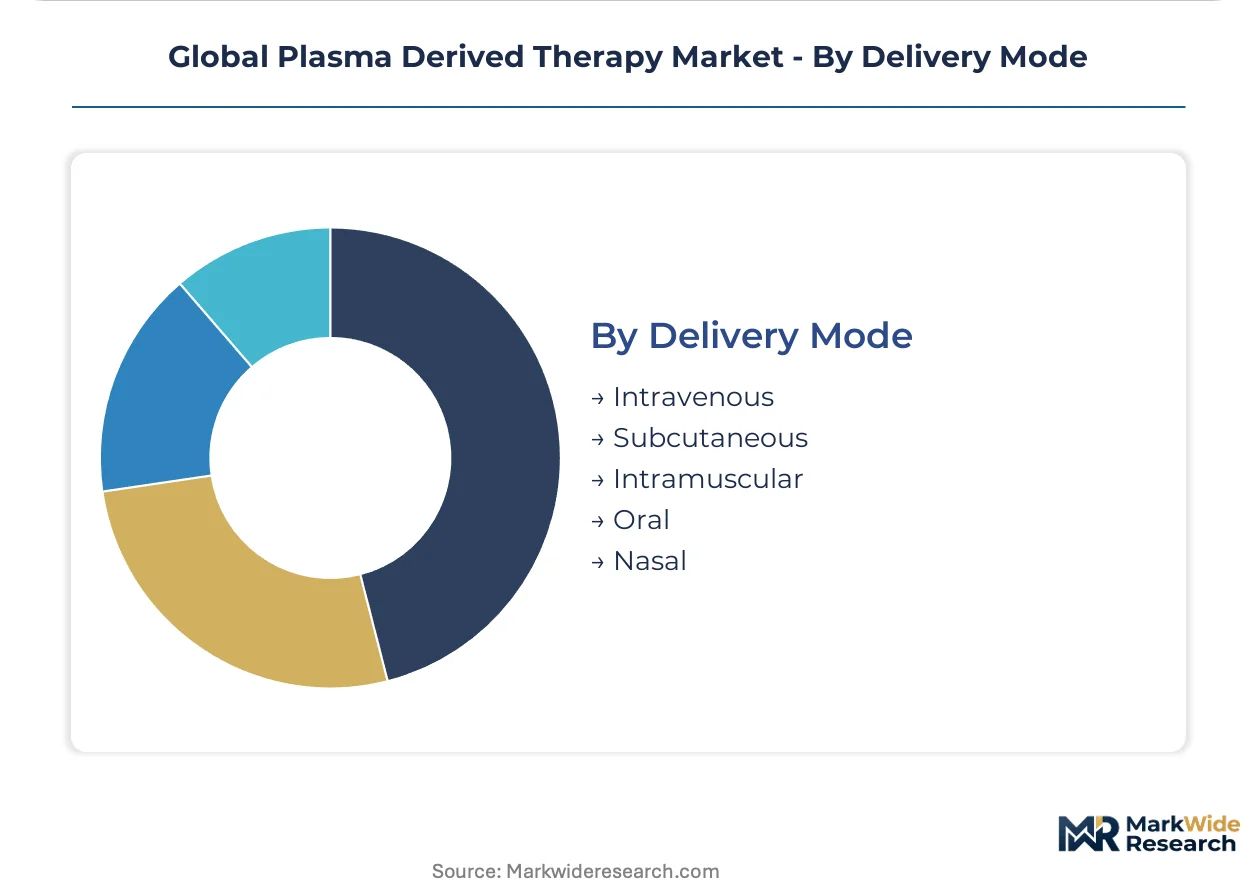
- Intravenous:Hospital and infusion center-based administration requiring nursing supervision, vascular access maintenance, and extended monitoring protocols. German and Japanese hospital systems retain higher intravenous immunoglobulin share than United States counterparts due to reimbursement structures favoring facility-based administration.
- Subcutaneous:Patient-managed administration using 20% immunoglobulin formulations with portable infusion pumps, enabling weekly dosing without nursing presence. United States adoption leads globally, with specialty pharmacies capturing dispensing margin and patient training responsibilities previously held by hospital outpatient departments.
- Intramuscular:Hyperimmune globulin and specific antibody preparations for rapid localized immune protection.
- Oral:Limited applicability for plasma-derived proteins given gastrointestinal degradation; experimental formulations for localized mucosal immunity.
- Nasal:Investigational delivery for hyperimmune globulin respiratory prophylaxis, with stability and dosing precision challenges unresolved.
Clinical infrastructure favors intravenous; patient autonomy and cost containment favor subcutaneous as home healthcare channels expand technical support capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasma fractionation capacity clusters in the United States, Germany, and Japan, with each jurisdiction deploying distinct regulatory frameworks to secure domestic supply chains for immunoglobulin and albumin therapies.
United States
Hospital pharmacies and specialty infusion centers drive immunoglobulin procurement volume as primary immunodeficiency diagnoses expand. FDA plasma-sourcing guidelines mandate pathogen-reduction technologies that elevate collection standards across community blood center networks. The Research Triangle Park corridor in North Carolina anchors fractionation R&D concentration, with process engineering talent clustering near legacy Cohn fractionation facilities.
Germany
German Red Cross plasma operations supply raw material to contracted fractionators under long-term volume commitments with defined quality specifications. EMA's MDR framework tightens traceability requirements for plasma-derived medicinal products, redirecting procurement toward certified facilities. The Hesse region hosts concentrated fractionation infrastructure, with Frankfurt-area logistics hubs managing cold chain distribution across Central European collection sites.
Japan
Domestic immunoglobulin demand outstrips local fractionation output, sustaining import dependency for specialty plasma proteins. METI-supported capacity investments target reduced reliance on foreign supply arrangements for critical blood products. The Kansai industrial corridor around Osaka anchors domestic plasma processing infrastructure, with Nagoya-area bioclusters developing chromatographic purification capabilities for higher-specific-activity concentrates.
Switzerland
Swissmedic certification requirements for plasma-derived medicinal products extend qualification timelines, concentrating procurement among established fractionators with demonstrated viral safety validation. Basel-area pharmaceutical clusters leverage proximity to German fractionation networks while maintaining independent quality oversight. The country's central European location positions it as a logistics intermediary for plasma protein distribution across Alpine and Mediterranean markets.
Australia
TGA oversight of plasma collection and fractionation aligns with WHO plasma quality standards, elevating barriers to market entry for non-certified suppliers. The Melbourne-Sydney corridor concentrates specialty infusion center networks that bypass hospital pharmacy procurement for subcutaneous immunoglobulin administration. Domestic collection economics face pressure from donor compensation inflation, compressing margin structures for independent plasma collectors operating outside national blood service arrangements.
Global Plasma Derived Therapy Market Competitive Landscape
Vertically integrated multinationals and regional collection specialists split the market between global scale economies and localized supply security. The vendor base concentrates around fractionators with captive plasma collection networks and established viral safety validation histories. Three archetypes dominate: integrated plasma-to-finished-dose operators, regional collection-to-fractionation specialists, and contract manufacturing organizations serving niche hyperimmune globulin indications. Capacity expansion and chromatographic purification technology licensing represent the dominant competitive moves as yield economics and purity thresholds tighten.
Within the integrated operator tier, CSL Behring and Takeda Pharmaceutical Company Limited exemplify archetypes combining plasma collection infrastructure with finished-dose manufacturing scale. Grifols occupies a position representing European collection network concentration with Iberian manufacturing footprint. These three anchors demonstrate how backward integration into plasma sourcing and captive supply of fractionation capacity sustain competitive positioning against recombinant substitution threats and regulatory barrier escalation.
| Leading Market Players |
|---|
| CSL Behring |
| Takeda Pharmaceutical Company Limited |
| Grifols |
| Octapharma |
| Kedrion |
| ADMA Biologics |
| Biotest AG |
| Bio Products Laboratory |
| Kamada |
| Others |
Supply & Pricing Matrix
Single-source dependency on United States plasma collection networks determines both pricing tier spreads and supply chain shape across the global plasma derived therapy market. FDA plasma-sourcing guidelines and EU F-Gas Regulation compliance costs feed directly into fractionation economics, compressing margins for non-integrated collectors while concentrating procurement authority among certified manufacturers with captive supply arrangements.
Pricing Analysis
EMA MDR traceability mandates dictate the pricing tier structure across the plasma derived therapy market. Three-tier pricing structure across premium, standard, and economy levels separates certified fractionators with full viral validation from regional processors with limited regulatory dossiers and commodity plasma brokers. Price differentiation hinges on certification grade and volume scale, with hospital pharmacies paying premiums for EMA-compliant immunoglobulin concentrates. Cost compression in the economy tier is intensifying because donor compensation inflation erodes independent collector margins. Specialty infusion centers show least price sensitivity given direct patient relationships, while blood banks operate under strict procurement budgets that favor long-term offtake contracts.
Supply Chain Analysis
Contract fractionation capacity concentrates among CSL Behring, Takeda, and Grifols facilities across the United States, Germany, and Japan. Raw material flows draw from paid donor plasma collected at Iberian and Central European sites, with German Red Cross operations and United States community blood centers feeding contracted processing arrangements. Single-source vulnerability persists in chromatographic purification resin supply anchored to German chemical manufacturers. Distribution runs through cold chain logistics hubs in the Frankfurt area for Central European coverage and Research Triangle Park for North American reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plasma derived therapy market sits in an early-cycle expansion phase driven by subcutaneous self-administration protocol penetration. Home healthcare channel development and patient-managed dosing adoption create durable tailwinds for fractionators with specialty pharmacy partnerships.
For Market Incumbents: Build captive plasma collection moats through backward integration into United States and Iberian donor networks. Add chromatographic purification capacity in the Kansai corridor to capture Japanese domestic fractionation incentives. Defend against recombinant coagulation factor substitution by locking hemophilia treatment center contracts for inhibitor patient segments. For New Entrants and Emerging Players: Pursue white-space opportunities in hyperimmune globulin manufacturing for pandemic preparedness stockpiles. Target Australian and Swiss markets where TGA and Swissmedic certification barriers have limited established competitor presence. Lead with niche C1 esterase inhibitor or alpha-1 proteinase inhibitor indications that escape attention from major fractionators. For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors integrated operators with validated viral safety dossiers. Long-term viability rests on collection network density and regulatory certification depth rather than single-product positioning. Watch FDA-EMA divergence on emerging pathogen threat assessment protocols as the signal for submission strategy disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Chromatographic Purification Licensing | Affinity chromatography integration with nanofiltration compresses batch cycle times for EMA MDR compliance. |
| Specialty Infusion Center Partnership | Direct relationships with United States home healthcare distributors capture subcutaneous immunoglobulin dispensing margin. |
| Cold Chain Infrastructure Retrofit | Ammonia-based secondary refrigeration systems in German facilities maintain plasma integrity under EU F-Gas Regulation timelines. |
| Domestic Fractionation Buildout | METI-supported capacity investments in Japan reduce import dependency for critical immunoglobulin therapies. |
| Pathogen-Reduction Technology Deployment | FDA-mandated viral safety protocols accelerate certified fractionator procurement by hospital pharmacy networks. |
Research Methodology
Operator-level perspectives from plasma collection center managers, hospital pharmacy directors, specialty infusion center operators, and regulatory affairs leads anchored the qualitative base. These primary insights combined with secondary validation from FDA 510(k) filings, EMA marketing authorization dossiers, WHO plasma quality standards documentation, and German Red Cross supply agreement disclosures. Bottom-up patient population modeling and top-down fractionation capacity assessment provided cross-check triangulation.
Scenario-bracketing framed volume and value outputs across the projection horizon. Segmentation dimensions included product type, application, end user, and delivery mode with regional regulatory cluster differentiation. CAGRs derived from patient diagnosis expansion rates, protocol substitution curves, and fractionation yield improvement trajectories. Immunoglobulin dosing frequency assumptions and subcutaneous penetration curves served as plasma-specific forecast inputs.
Sensitivities concentrate around regulatory divergence on emerging pathogen threats and donor compensation inflation trajectories. Forecasts reflect documented assumptions on collection economics and purification technology adoption. Quarterly review of FDA guidance publication cadence and EMA MDR certification timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Omeprazole Market
Pharmaceuticals
North America Adenomyosis Drugs Market
Pharmaceuticals
Global Dengue Vaccine Market
Pharmaceuticals
Paracetamol IV Market
Pharmaceuticals
Advanced Therapy Medicinal Products CDMO Market
Pharmaceuticals
Global Ebola Virus Vaccine Market
Pharmaceuticals
Global Polio Vaccines Market
Pharmaceuticals
Herbal Drugs Market
Pharmaceuticals
Global General Anesthesia Drugs Market
Pharmaceuticals
Global Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Exocrine Pancreatic Insufficiency Therapeutics Market
Pharmaceuticals
Global Anti-Fungal Drugs Market
Pharmaceuticals
China Plasma Protein Therapeutics Market
Pharmaceuticals
Mail Order Pharmacy Market
Pharmaceuticals
Latin America FMD Vaccine Market
Pharmaceuticals
Cortisone Market