
 Beta Blockers Market | 2026-2036
Beta Blockers Market Size, Share, and Industry Trends Forecast 2026-2036
Beta Blockers Market Outlook
Market Context
India is rewriting the cost structure of generic beta blocker supply through API and formulation capacity expansion. Teva Pharmaceutical Industries Ltd. leverages its vertically integrated manufacturing footprint to sustain cost leadership in commoditized oral tablets. AstraZeneca differentiates through sustained-release formulation expertise and cardiology channel depth. Pfizer, Inc. anchors hospital and institutional contracts with injectable product lines.
Technical Definition and Segment Structure
Beta blockers constitute a class of competitive antagonists that bind β-adrenergic receptors to reduce heart rate, myocardial contractility, and renin release, with selectivity profiles ranging from non-selective (propranolol) to β1-cardioselective (bisoprolol, metoprolol, atenolol). These compounds serve as first-line pharmacotherapy for hypertension, chronic heart failure, angina pectoris, and arrhythmia management across inpatient and outpatient settings. Metoprolol and bisoprolol dominate volume due to established cardioselectivity and tolerability profiles, while propranolol retains specialized positioning in migraine prophylaxis and essential tremor. The hospital end-user segment captures the highest value per dose through IV infusion and perioperative protocols, whereas homecare oral tablet demand expands on chronic prescription refill density.
Regulatory Frame and Outlook
FDA bioequivalence standards under 21 CFR 320 govern abbreviated new drug application pathways for generic beta blockers, while EMA guidance through the Committee for Medicinal Products for Human Use shapes European market access requirements. India's CDSCO and BIS frameworks regulate domestic manufacturing quality and export certification for API producers. Stakeholders must monitor evolving pharmacovigilance mandates and tightening impurity specification thresholds as regulators align on nitrosamine risk controls.
Market Dynamics
Hospital procurement of oral beta blocker therapies is tightening cardiovascular disease protocols and compressing formulary slots, forcing manufacturers to defend position through bioequivalence documentation and sustained-release formulation differentiation rather than commodity volume alone.
Growth Catalysts
- Hypertension protocol expansion:India's CDSCO is accelerating chronic disease management program rollouts that mandate first-line beta blocker therapy in public health facilities.
- EMA bioequivalence alignment:The Committee for Medicinal Products for Human Use is harmonizing generic approval standards across member states, reducing regulatory duplication for multi-market filings.
- Perioperative IV demand:Cardiac surgery volume concentration in United States tertiary centers is pulling injectable metoprolol through hospital group purchasing organizations.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production clusters in specific Indian states create geographic vulnerability to environmental compliance disruptions.
- Nitrosamine impurity thresholds:FDA 21 CFR 320 enforcement actions on N-nitrosamine controls are forcing batch recalls and reformulation costs for legacy manufacturers.
- ACE inhibitor substitution:Renin-angiotensin system antagonists are capturing initial hypertension prescriptions in younger patient cohorts per updated clinical guidelines.
Strategic Opportunities
- German ambulatory care integration:Disease management program contracts in Bavaria and North Rhine-Westphalia are opening long-acting formulation tenders outside hospital channels.
- Combination therapy convergence:Fixed-dose combinations pairing cardioselective beta blockers with diuretics are gaining protocol inclusion in Indian state procurement lists.
- Homecare infusion transition:Subcutaneous beta blocker delivery systems are enabling post-acute cardiac rehabilitation outside institutional settings in United States Medicare Advantage networks.
Industry Challenges
- Bioanalytical talent scarcity:Pharmacokinetic study directors with ANDA submission experience command premium compensation, constraining mid-tier generic timelines.
- Legacy manufacturing retrofit costs:Continuous processing equipment upgrades for impurity control require capital deployment that compresses near-term margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beta Blockers Market |
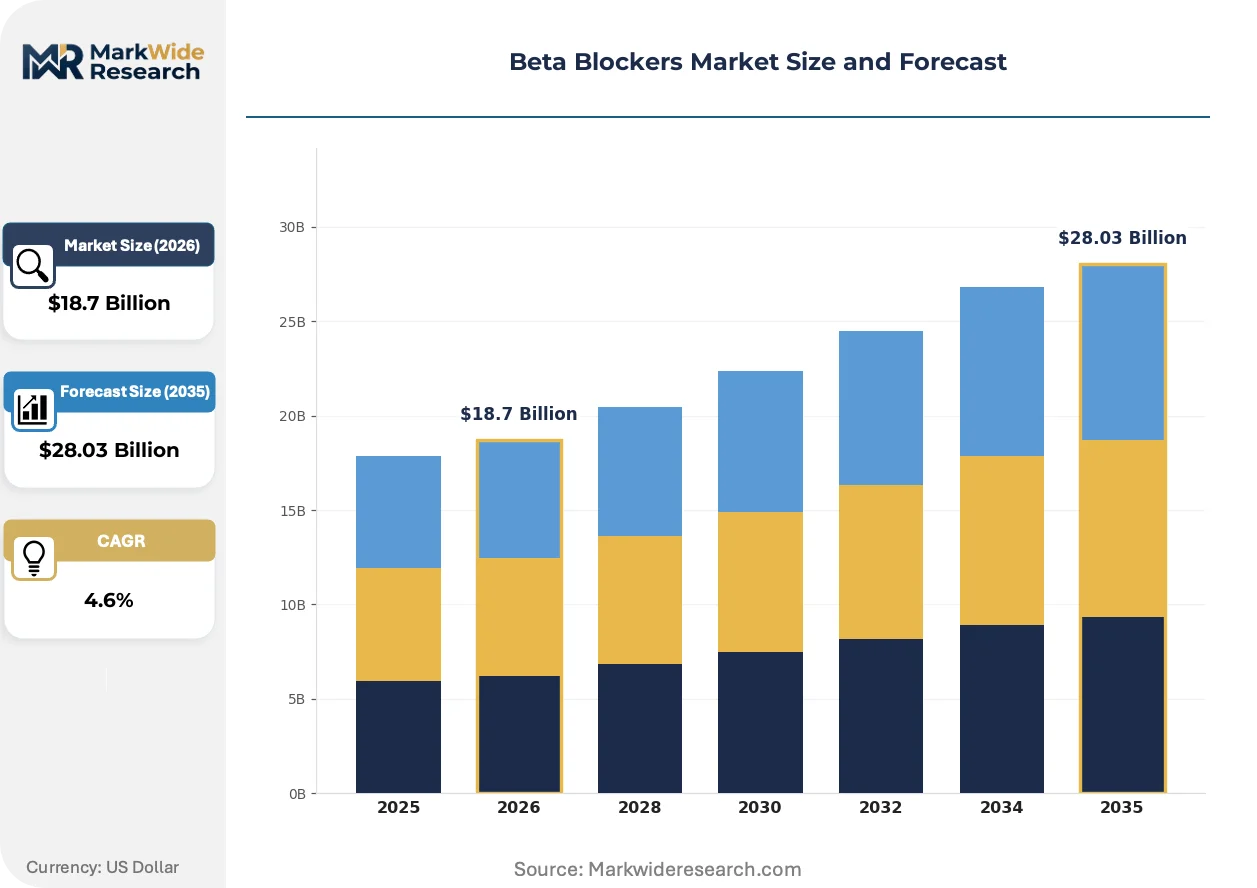
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Atenolol, Metoprolol, Propranolol, Bisoprolol Therapy Area: Hypertension, Heart Failure, Angina, Arrhythmia End User: Hospitals, Clinics, Homecare, Ambulatory Care Delivery Mode: Oral Tablets, Injectable, IV Infusions, Topical |
| Companies Covered | Novartis AG, Teva Pharmaceutical Industries Ltd., GSK plc, Sun Pharmaceutical Industries Ltd., Pfizer, Inc., AstraZeneca, ANI Pharmaceuticals, Inc., Lupin, Amneal Pharmaceuticals LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beta Blockers Market Strategic Shifts
Formulation science and regulatory science are converging to redefine competitive advantage, with sustained-release architectures and nitrosamine risk management protocols separating viable suppliers from commodity players.
Polymorphic control technologies that ensure consistent crystal form across manufacturing scales are rendering obsolete batch-to-batch variability in generic bioequivalence studies. Contract research organizations serving ANDA filers are adopting real-time process analytical technology to compress stability timeline risk. The structural consequence is a bifurcation between manufacturers with in-house polymorphism expertise and those dependent on external analytical support.
REACH authorization requirements for nitrosamine precursor chemicals are forcing European API suppliers to requalify solvent and reagent sourcing. ECHA's updated guidance on secondary amine contamination pathways is extending quality agreement audits upstream to chemical intermediates. German formulation houses are responding by consolidating supplier panels and demanding certificates of analysis with nitrosamine-specific testing.
Hospital pharmacy and therapeutics committees are unbundling beta blocker selection from broader cardiovascular bundle contracts, enabling therapeutic substitution at the drug level rather than class level. United States health system procurement is rotating toward 90-day oral tablet dispensing for post-discharge cardiac patients, compressing the institutional-to-retail transition window. This pattern is most visible in Medicare ACOs where medication adherence metrics directly impact shared savings calculations.
Beta Blockers Market Segmentation
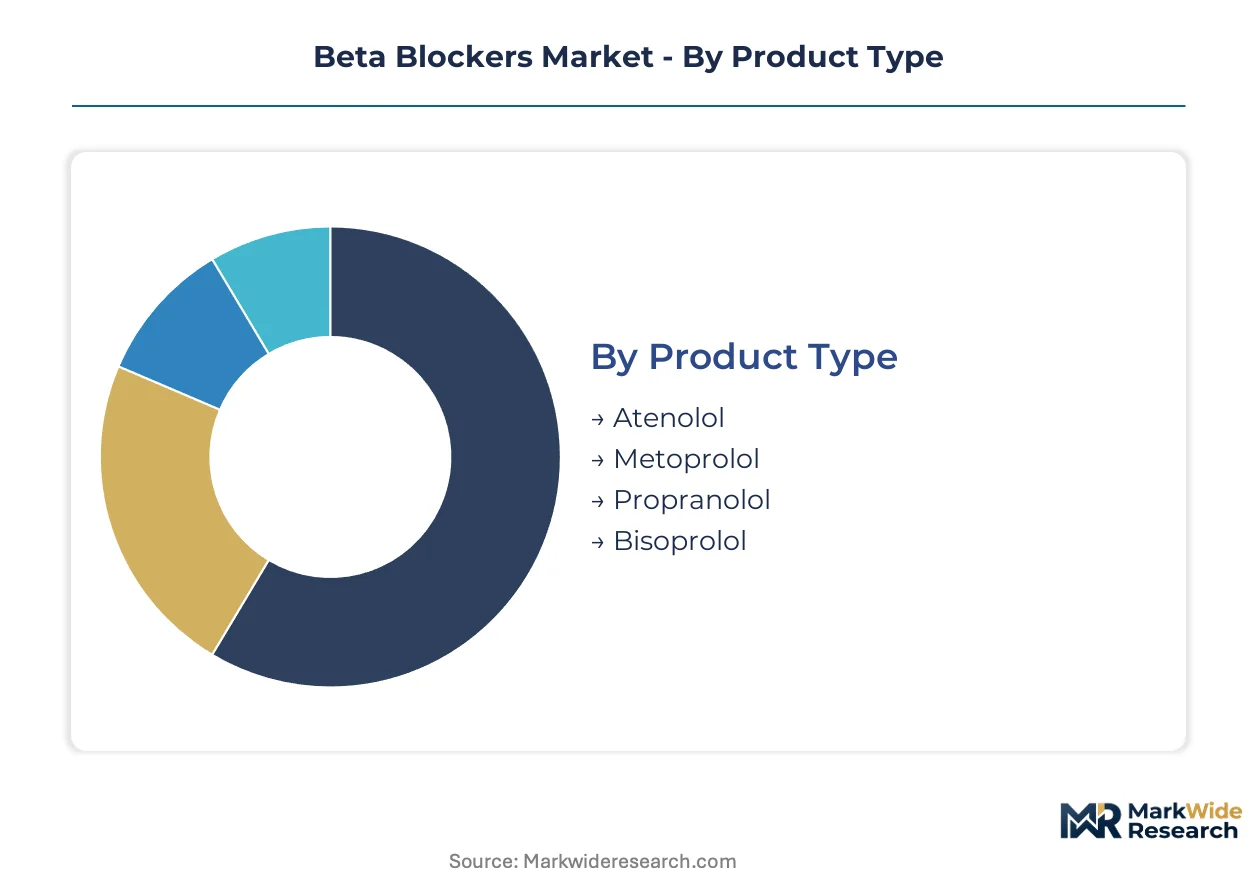
Beta blocker segmentation reveals how formulation selectivity, care setting economics, and delivery technology intersect to determine procurement patterns. Manufacturers must align R&D and commercial resources against the segments where reimbursement and protocol inclusion create sustainable margin structures.
Product Type:
Cardioselectivity profiles and tolerability data define prescribing hierarchies across acute and chronic care pathways.
- Metoprolol:β1-selective antagonist with established perioperative safety data. Demand concentrates in United States tertiary cardiac centers where IV-to-oral step-down protocols drive formulary standardization. FDA bioequivalence documentation requirements favor manufacturers with in-house polymorphism expertise.
- Bisoprolol:Highly cardioselective agent with once-daily dosing advantages. German ambulatory care networks and Indian state procurement lists are expanding chronic heart failure prescriptions based on mortality outcome studies.
- Atenolol:First-generation β1-blocker with extensive generic competition. Cost-sensitive hospital systems in India retain formulary inclusion for hypertension first-line therapy despite emerging guideline preferences.
- Propranolol:Non-selective beta blocker retaining specialized positioning in migraine prophylaxis and essential tremor management. United States neurology practices and movement disorder clinics sustain niche demand outside cardiovascular protocols.
The dominant share belongs to Metoprolol, while Bisoprolol is gaining share fastest on heart failure protocol expansion.
Therapy Area:
Clinical guideline hierarchies and reimbursement bundling determine which indications support premium pricing versus commodity competition.
- Hypertension:Largest addressable population with intense generic substitution pressure. United States Medicare Advantage plans and Indian public health facilities prioritize cost-minimization over brand loyalty in first-line therapy selection.
- Heart Failure:Mortality endpoint trials create protocol stickiness that protects selected beta blockers from therapeutic substitution. German disease management programs and United States hospital readmission penalty structures reinforce evidence-based prescribing.
- Angina:Symptom control focus with combination therapy prevalence. European cardiology practices increasingly pair beta blockers with calcium channel antagonists in stable coronary disease management.
- Arrhythmia:Rate control applications in atrial fibrillation management. United States electrophysiology practices balance beta blocker selection against catheter ablation candidacy assessments.
Hypertension generates the highest prescription volumes, though Heart Failure commands superior reimbursement per treated patient.
End User:
Procurement authority and payment mechanism fragmentation create distinct competitive dynamics across care settings.
- Hospitals:Highest value per dose through IV infusion protocols and perioperative cardiac protection. United States group purchasing organizations and German hospital federations consolidate formulary decisions across multi-facility networks.
- Homecare:Oral tablet refill density with adherence metric implications. Medicare ACO shared savings calculations in the United States are extending 90-day dispensing authorizations for post-discharge cardiac patients.
- Clinics:Outpatient cardiology and internal medicine practices with protocol-driven prescribing. Indian urban clinic chains are integrating with state chronic disease management programs for hypertension screening and treatment initiation.
- Ambulatory Care:Same-day surgical and diagnostic centers with limited therapeutic scope. German outpatient cardiac rehabilitation facilities represent emerging demand for long-acting oral formulations.
Hospitals retain the dominant procurement value, while Homecare is expanding most quickly on post-acute care decentralization.
Delivery Mode:
Formulation technology and administration setting requirements segment manufacturing capabilities and regulatory pathways.
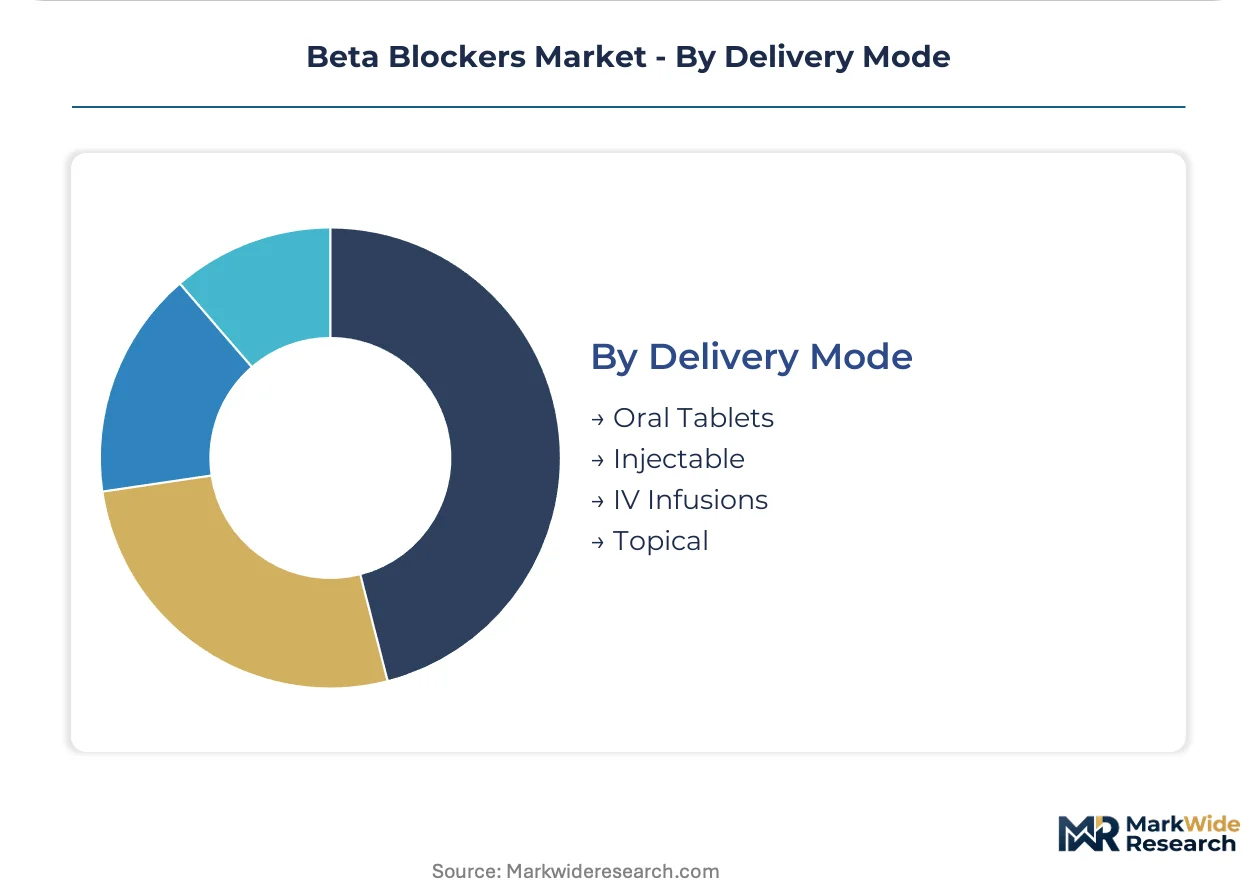
- Oral Tablets:Core chronic therapy format with bioequivalence documentation as primary competitive barrier. Indian API producers and formulation houses dominate supply through cost-optimized immediate-release and sustained-release architectures.
- Injectable:Perioperative and emergency applications requiring sterile manufacturing certification. United States hospital procurement contracts favor suppliers with demonstrated supply continuity and cold chain reliability.
- IV Infusions:Critical care and surgical settings with exacting stability and compatibility requirements. Tertiary cardiac centers in the United States specify metoprolol tartrate for controlled hypotension protocols.
- Topical:Limited applications including ophthalmic beta blockers for glaucoma. Specialized formulation expertise separates viable suppliers from commodity oral tablet competitors.
Oral Tablets command the dominant prescription volume, though Injectable formats sustain premium positioning in institutional procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets. The United States concentrates beta blocker use in perioperative IV protocols and tertiary cardiac centers, while India and Germany emphasize oral chronic disease management through public health procurement and ambulatory care networks respectively.
United States
Hospital group purchasing organizations consolidate metoprolol procurement across multi-facility cardiac surgery networks. FDA 21 CFR 320 bioequivalence enforcement shapes generic substitution patterns in Medicare Advantage formularies. Tertiary centers in Cleveland and Houston drive IV-to-oral step-down protocol standardization.
Germany
Disease management program contracts in Bavaria and North Rhine-Westphalia expand bisoprolol prescribing for chronic heart failure. EMA Committee for Medicinal Products for Human Use harmonization reduces regulatory duplication for multi-state filings. Berlin-based hospital federations unbundle beta blocker selection from broader cardiovascular bundle contracts.
India
CDSCO-mandated chronic disease management programs in public health facilities accelerate first-line beta blocker therapy initiation. BIS quality certification requirements govern API export eligibility for domestic manufacturers. Andhra Pradesh and Telangana API production clusters face tightening environmental compliance disruption risks.
United Kingdom
NHS England hypertension pathway updates influence primary care prescribing hierarchies between beta blockers and renin-angiotensin alternatives. MHRA pharmacovigilance mandates align with EMA nitrosamine risk control standards. London and Southeast England hospital trusts concentrate perioperative cardiac protection protocol adoption.
Japan
PMDA post-market surveillance requirements extend to beta blocker impurity specification thresholds. METI pharmaceutical industry policy supports domestic formulation capacity for sustained-release architectures. Osaka and Tokyo metropolitan medical centers concentrate electrophysiology practice arrhythmia rate control applications.
Beta Blockers Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. The market structures around vertically integrated API producers commanding cost positions in commoditized oral tablets, while formulation specialists defend margin through sustained-release expertise and hospital channel depth. Three archetypes dominate: generic volume manufacturers with captive API supply, branded portfolio holders with cardiology specialist relationships, and mid-tier ANDA filers dependent on contract research organizations for bioequivalence documentation. Competitive moves center on polymorphism control technology acquisition and nitrosamine risk management protocol certification.
Among Israel-based pharmaceutical manufacturers, Teva Pharmaceutical Industries Ltd. exemplifies scale-driven API and formulation integration. AstraZeneca and Pfizer, Inc. occupy positions on the branded-specialist tier, anchoring hospital and institutional contract channels through differentiated delivery formats and perioperative protocol relationships.
| Leading Market Players |
|---|
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| GSK plc |
| Sun Pharmaceutical Industries Ltd. |
| Pfizer, Inc. |
| AstraZeneca |
| ANI Pharmaceuticals, Inc. |
| Lupin |
| Amneal Pharmaceuticals LLC |
| Others |
Value Chain & Pricing Dynamics
Andhra Pradesh and Telangana API production clusters dictate downstream pricing power through captive supply of metoprolol and bisoprolol active pharmaceutical ingredients. Indian manufacturers with backward integration into these hubs command margin resilience against commodity tablet pricing pressure from European and North American hospital procurement.
Pricing Analysis
Long-term offtake contracts between Indian API producers and European formulation houses anchor pricing stability for sustained-release bisoprolol, while spot market transactions for immediate-release metoprolol expose smaller ANDA filers to raw material volatility. Price differentiation hinges on FDA bioequivalence documentation completeness and nitrosamine certification status. Pricing pressure stems from Medicare Advantage formulary tightening in the United States, where 90-day dispensing authorizations compress per-prescription revenue. Hospital procurement managers exhibit highest price sensitivity; cardiology specialists prescribing heart failure protocols show lowest sensitivity due to mortality outcome data stickiness.
Supply Chain Analysis
Tariff exposure between India and the European Union dominates supply chain risk planning for German formulation houses dependent on Andhra Pradesh API imports. Active pharmaceutical ingredient production concentrates in India, China, and the United States, with formulation finishing distributed across Western Europe and North America. Raw material dependencies include 4-methoxyphenethylamine precursors, tartaric acid for salt formation, and nitrosamine-controlled solvents. Single-source vulnerability characterizes specialized sustained-release polymer supply. Distribution runs through hospital group purchasing organizations in the United States, state procurement depots in India, and pharmacy benefit managers in ambulatory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through FDA bioequivalence documentation and EMA nitrosamine compliance creates durable incumbent advantages against commodity challengers.
For Market Incumbents: Entrench formulary position by acquiring polymorphism control technology to compress ANDA competitor timelines, while extending nitrosamine risk management certification upstream to chemical intermediate suppliers. ACE inhibitor substitution in younger hypertension cohorts threatens volume; defend through heart failure protocol expansion in German disease management programs and Indian state procurement lists.
For New Entrants and Emerging Players: German ambulatory cardiac rehabilitation facilities offer underpenetrated demand for long-acting oral formulations outside hospital bundle contracts. Fixed-dose beta blocker-diuretic combinations in Indian state tenders represent a second white-space target. Pursue contract research organization partnerships with real-time process analytical technology capabilities to accelerate bioequivalence documentation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulation specialists with sustained-release expertise and hospital channel depth over pure-play API commoditizers. Long-term viability rests on regulatory science capabilities rather than manufacturing scale alone. Watch FDA enforcement actions on nitrosamine impurity thresholds as the inflection signal for margin compression or consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Polymorphism Control Technology Acquisition | FDA bioequivalence documentation speed separates viable ANDA filers from stranded competitors. |
| Nitrosamine Risk Management Certification | ECHA REACH authorization requirements force upstream quality agreement consolidation. |
| Sustained-Release Formulation R&D Investment | German disease management program tenders favor once-daily dosing adherence advantages. |
| Hospital GPO Contract Consolidation | United States tertiary cardiac center networks standardize IV-to-oral step-down protocols. |
| Fixed-Dose Combination Development | Indian state procurement lists increasingly include beta blocker-diuretic pairings for hypertension. |
Study Parameters
Operator-level perspectives from hospital pharmacy and therapeutics committee members, CDSCO regulatory affairs leads, generic drug development executives, and group purchasing organization contract managers anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 21 CFR 320 filings, EMA Committee for Medicinal Products for Human Use guidance documents, ClinicalTrials.gov outcome data, and Indian BIS quality certification records. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing triangulated across the analysis window.
Scenario-bracketing around bioequivalence approval timeline variability and nitrosamine regulatory enforcement intensity shaped the forecast framework. Segmentation dimensions included cardioselectivity profile, therapy area indication, end-user care setting, and delivery mode format across the projection horizon. CAGRs derived from prescription refill density trajectories, hospital procurement contract renewal patterns, and chronic disease management program rollout schedules in target geographies.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Indian API-to-formulation players or sudden EMA nitrosamine threshold tightening would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Veterinary Active Pharmaceutical Ingredients Manufacturing Market
Pharmaceuticals
Osteoarthritis Drugs Market
Pharmaceuticals
Antidiarrhoeal Market
Pharmaceuticals
Anti-Platelet Agents Market
Pharmaceuticals
Compound Potassium Hydrogen Phosphate Injection Market
Pharmaceuticals
Adenosine Market
Pharmaceuticals
Global Prophylactic HIV Drugs Market
Pharmaceuticals
Global Tetanus Toxoid Vaccine Market
Pharmaceuticals
Latin America Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Organ Transplant Rejection Medications Market
Pharmaceuticals
Constipation Laxative Market
Pharmaceuticals
Global Pharmacy Benefit Management (PBM) Market
Pharmaceuticals
Tuberculosis Vaccine Treatment Market
Pharmaceuticals
US Pharmaceutical Warehousing Market
Pharmaceuticals
Microparticle Injectables Market
Pharmaceuticals
Thrombosis Drugs Market