
 Global Cold and Flu Drugs Market | 2026-2036
Global Cold and Flu Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cold and Flu Drugs Market Foresight
The EU Green Deal's pharmaceutical sustainability criteria is pivoting formulation priorities toward biodegradable excipients and reduced packaging waste. Johnson & Johnson leverages its consumer health division to sustain leadership in acetaminophen-based combination therapies across North American retail channels. GSK plc anchors its competitive position through dominance in respiratory antiviral research and established pharmacy distribution networks in Europe and Asia-Pacific. Bayer AG differentiates via its specialized focus on herbal and plant-derived cough suppressants targeting environmentally conscious consumers.
Cold and flu drugs comprise over-the-counter and prescription pharmaceutical formulations containing active ingredients such as pseudoephedrine, dextromethorphan, guaifenesin, and loratadine, typically administered in tablet, capsule, liquid, or nasal spray forms to alleviate respiratory symptoms. These products function primarily through vasoconstriction, antihistamine action, cough reflex suppression, or mucus thinning to restore patient functionality during acute viral infection. Combination medications command the largest revenue share due to consumer preference for multi-symptom relief in single-dose formats, while online pharmacies represent the fastest-growing distribution channel as digital prescription verification and direct-to-patient logistics mature. Decongestants maintain stable demand in seasonal peak periods, though antihistamines increasingly capture year-round use as allergic rhinitis diagnoses expand.
The FDA's OTC monograph reform streamlines market entry for established ingredients while tightening manufacturing documentation requirements. EMA's revised guidelines on excipient safety and REACH compliance for chemical additives elevate formulation costs for European manufacturers. China's NMPA accelerates domestic approvals for cold and flu therapies under its pharmacopoeia modernization program. Stakeholders must monitor regulatory divergence between major markets to optimize portfolio allocation and avoid reformulation penalties.
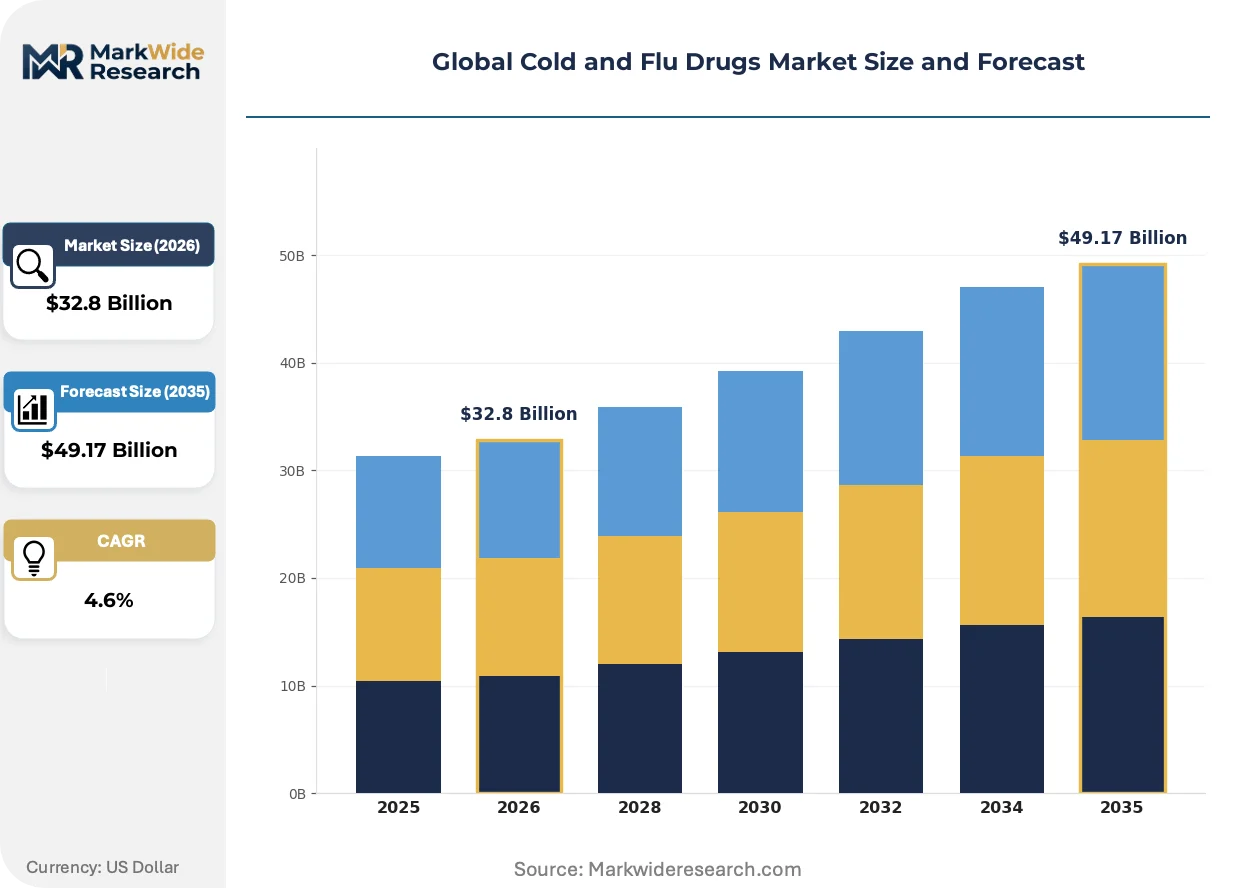
Market Dynamics
Retail pharmacy consolidation and the FDA's OTC monograph reform are compressing formulation diversity while accelerating prescription-to-non-prescription switches, forcing manufacturers to consolidate SKUs around proven active ingredients with documented safety profiles.
Growth Catalysts
- OTC Monograph Reform:The FDA's streamlined approval pathway reduces time-to-market for established ingredients, enabling faster commercialization of decongestant and antihistamine formulations without new drug application requirements.
- Self-Medication Patterns:Post-pandemic consumer behavior favors pharmacy aisle solutions over physician visits for symptomatic relief, expanding addressable demand for multi-symptom combination tablets.
- Domestic Manufacturing Scale-Up:India's PLI scheme for pharmaceuticals incentivizes local production of active pharmaceutical ingredients, reducing import dependency for paracetamol and pseudoephedrine precursors.
Market Restraints
- API Supply Concentration:China controls approximately 40% of global acetaminophen precursor output, creating geographic single-point-of-failure risk for North American and European formulators.
- REACH Compliance Costs:ECHA's expanded excipient safety documentation requirements elevate formulation expenses for European manufacturers seeking biodegradable alternatives to synthetic binders.
- Herbal Substitution Threat:Plant-derived cough suppressants and traditional Chinese medicine formulations capture preference share among environmentally conscious consumers in Germany and Scandinavia.
Strategic Opportunities
- Digital Pharmacy Expansion:Direct-to-patient logistics platforms in Brazil and Mexico bypass traditional wholesale distribution, capturing margin previously allocated to pharmacy chains.
- Biodegradable Excipient Innovation:EU Green Deal sustainability criteria create first-mover advantage for manufacturers developing starch-based tablet coatings and reduced-plastic blister packaging.
- Year-Round Antihistamine Positioning:Expanding allergic rhinitis diagnoses in Japan and South Korea enable seasonal brand extension beyond traditional cold and flu peak periods.
Industry Challenges
- Analytical Method Transfer:NMPA's pharmacopoeia modernization requires reformulation of legacy products to meet updated dissolution and impurity profile standards, compressing R&D timelines.
- Cold Chain Reconfiguration:Liquid nasal spray formulations require temperature-controlled distribution infrastructure that many emerging market distributors lack, limiting product format expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cold and Flu Drugs Market |
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $49.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Decongestants, Antihistamines, Cough Suppressants, Expectorants, Combination Medications Therapy Area: Common Cold, Influenza, Allergic Rhinitis, Sinusitis, Bronchitis End User: Pharmacies, Clinics, Home Care, Geriatric Care, Pediatric Care Distribution Channel: Retail Pharmacies, Online Pharmacies, Hospitals, Drug Stores, Wholesalers |
| Companies Covered | Reckitt Benckiser Group plc, Perrigo Company plc, Johnson & Johnson, GSK plc, Sun Pharmaceutical Industries Ltd., Bayer AG, Viatris Inc., Haleon Group plc, Sanofi S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cold and Flu Drugs Market Shifts & Advancements
Formulation science and distribution infrastructure are converging to reshape how symptomatic therapies reach patients, with sustainability mandates and digital verification creating new technical requirements across the value chain.
Continuous manufacturing technology is rewriting production economics for solid-dose cold and flu medications. GSK plc and mid-tier contract manufacturers are adopting powder-to-tablet direct compression systems that reduce batch cycle times from days to hours. This compression of production timelines enables just-in-season inventory positioning, reducing working capital requirements for retailers managing volatile demand patterns.
EMA's revised guidelines on excipient safety and REACH compliance for chemical additives are elevating documentation burdens across European manufacturing networks. Formulators must now submit extended safety data for synthetic colorants and preservatives previously grandfathered under older directives. Pediatric liquid formulations face the steepest compliance costs, driving portfolio rationalization toward adult tablet formats with simpler excipient profiles.
Subscription-based replenishment models are displacing episodic pharmacy purchases among chronic allergy sufferers in the United States. Amazon Pharmacy and CVS Caremark now offer automated 90-day supply programs for antihistamine therapies, capturing patient loyalty through convenience lock-in. This channel shift concentrates volume with platforms possessing sophisticated demand forecasting capabilities, marginalizing smaller retail chains lacking predictive analytics infrastructure.
Global Cold and Flu Drugs Market Segmentation
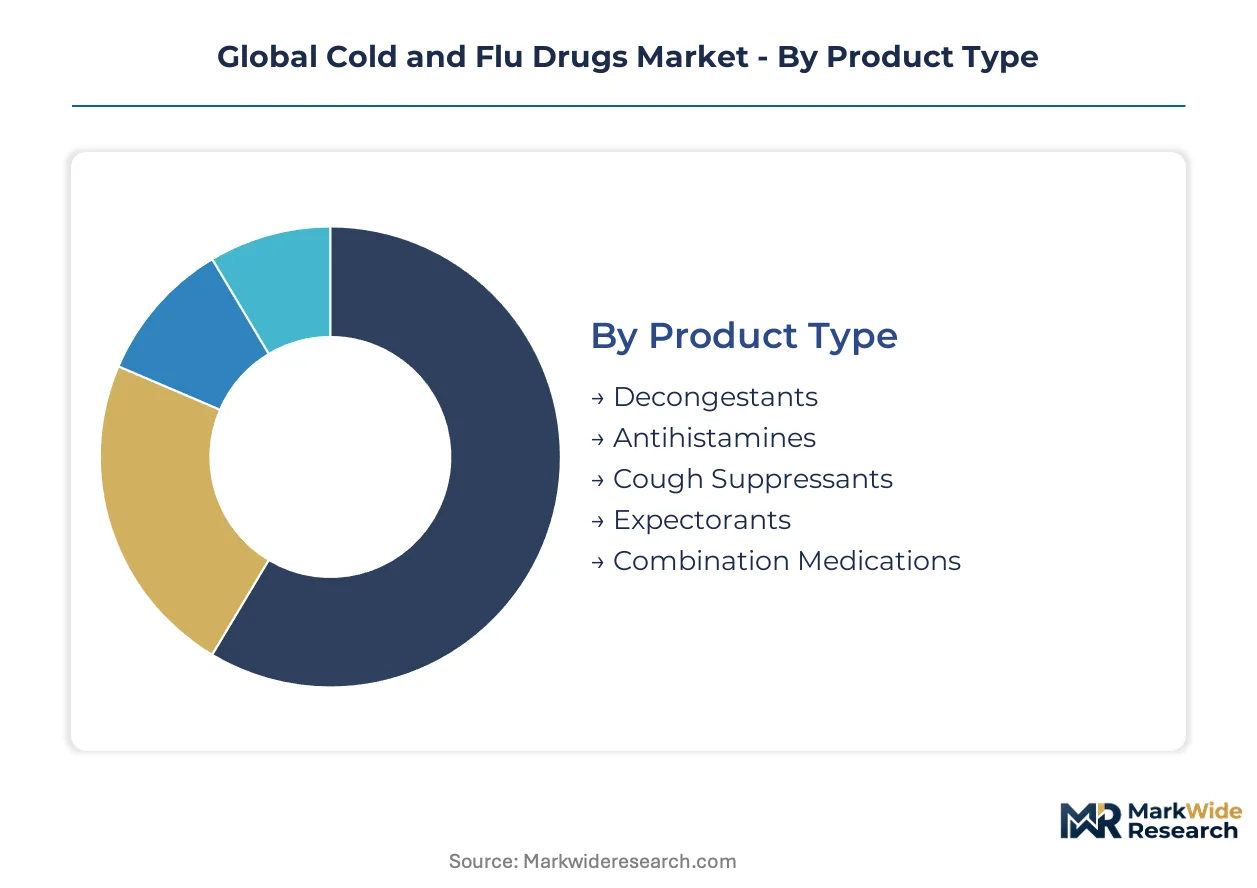
Cold and flu drugs fragment across formulation chemistry, clinical indication, patient setting, and procurement pathway. Each axis carries distinct margin profiles and regulatory exposure that shape portfolio prioritization for manufacturers.
Product Type:
Active ingredient selection determines efficacy profile, scheduling status, and manufacturing complexity across symptomatic therapies.
- Combination Medications:Multi-symptom tablets layer acetaminophen, dextromethorphan, and pseudoephedrine in fixed-dose formats. United States pharmacy chains favor these SKUs for basket-size expansion during winter peaks.
- Decongestants:Pseudoephedrine and phenylephrine formulations trigger vasoconstriction in nasal mucosa. China's NMPA maintains tighter precursor controls than FDA, fragmenting formulation strategies between markets.
- Antihistamines:Second-generation loratadine and cetirizine variants dominate year-round allergic rhinitis management with reduced sedation profiles.
- Cough Suppressants:Dextromethorphan centrally inhibits cough reflex; codeine-containing alternatives face prescription-only restrictions across European markets.
- Expectorants:Guaifenesin thins bronchial secretions through enhanced mucus hydration, preferred in pediatric liquid formats.
Mature deployment sits with decongestants. Newer deployment is concentrated in combination medications.
Therapy Area:
Clinical indication segmentation aligns R&D investment with epidemiological burden and reimbursement eligibility.
- Allergic Rhinitis:Chronic IgE-mediated inflammation drives sustained antihistamine consumption beyond seasonal cold patterns. Japanese and South Korean diagnosis rates climb fastest among developed markets.
- Common Cold:Acute rhinovirus infection generates episodic demand concentrated in retail pharmacy channels. India's domestic manufacturing scale-up targets this high-volume, low-margin segment.
- Influenza:Viral severity warrants prescription antiviral co-administration in hospitalized cases.
- Sinusitis:Bacterial superinfection complications require antibiotic adjuncts, complicating pure symptomatic therapy positioning.
- Bronchitis:Lower respiratory inflammation in smokers and COPD patients demands mucolytic-heavy formulations.
Volume concentration rests with common cold. Margin expansion concentrates in allergic rhinitis.
End User:
Patient setting determines dosing format, compliance packaging, and clinical support requirements.
- Pharmacies:Self-selection environments favor blister-packed tablets with prominent symptom icons. Brazil's independent pharmacy network captures Latin America's highest per-capita cold medication spend.
- Home Care:Family stockpiling of multi-symptom kits accelerated post-pandemic, particularly in United States suburban markets.
- Clinics:Physician-supervised administration captures severe cases requiring prescription-strength decongestants.
- Pediatric Care:Liquid suspension formats with calibrated dosing devices face EMA's tightened excipient safety documentation.
- Geriatric Care:Polypharmacy interactions necessitate acetaminophen-forward formulations avoiding NSAID complications.
Transaction volume clusters in pharmacies. Growth velocity peaks in home care.
Distribution Channel:
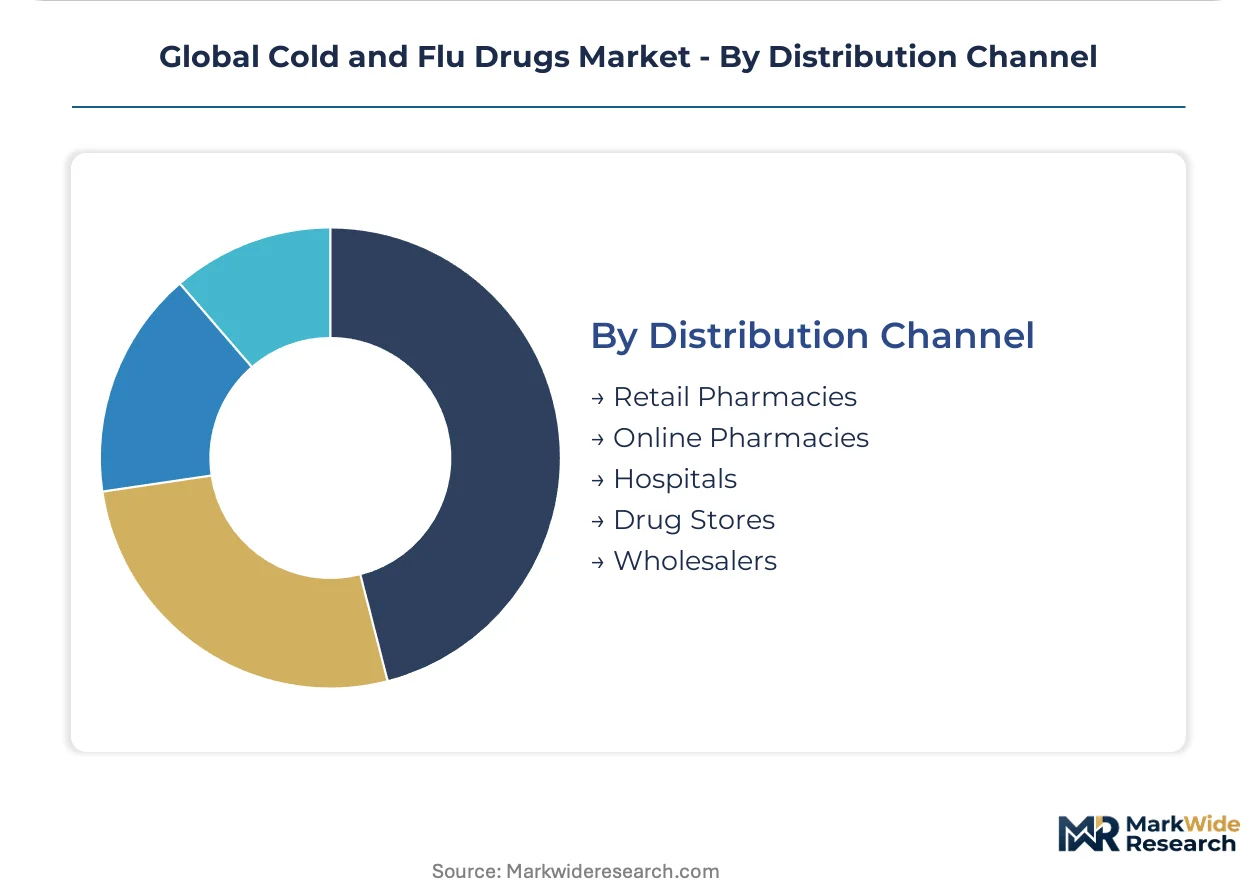
Route-to-patient economics diverge sharply between physical and digital fulfillment models.
- Online Pharmacies:Direct-to-patient platforms bypass wholesale markups through automated prescription verification. Amazon Pharmacy and CVS Caremark subscription models lock in chronic antihistamine users.
- Retail Pharmacies:Chain consolidation in United States and Germany compresses SKU diversity while expanding private-label shelf space.
- Hospitals:Inpatient formulary decisions favor single-ingredient injectables over combination oral products.
- Drug Stores:Convenience-oriented urban formats in Japan and South Korea emphasize grab-and-go blister packs.
- Wholesalers:McKesson and AmerisourceBergen maintain inventory financing relationships with independent pharmacies.
Established infrastructure sits with retail pharmacies. Channel expansion concentrates in online pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Jersey's pharmaceutical corridor anchors North American formulation capacity for acetaminophen-based therapies. The United States, China, India, Germany, and Japan concentrate distinct competitive advantages across manufacturing scale, API synthesis, and distribution infrastructure.
United States
Retail pharmacy consolidation and subscription-based replenishment models reshape demand capture. FDA's OTC monograph reform accelerates prescription-to-non-prescription switches for established decongestant ingredients. New Jersey and Pennsylvania host the densest cluster of formulation facilities serving North American distribution networks.
China
Domestic manufacturing scale-up targets paracetamol and pseudoephedrine precursor output under NMPA pharmacopoeia modernization. The regulator tightens precursor controls compared to Western counterparts, fragmenting multinational formulation strategies. Zhejiang and Jiangsu provinces concentrate API synthesis capacity for export markets.
India
PLI scheme incentives reduce import dependency for cold and flu active pharmaceutical ingredients. CDSCO accelerates domestic approvals for high-volume symptomatic therapies. Hyderabad and Ahmedabad emerge as formulation export hubs targeting African and Southeast Asian markets.
Germany
EMA's REACH compliance requirements elevate excipient safety documentation burdens for European manufacturers. Herbal and plant-derived cough suppressants capture preference share among environmentally conscious consumers in Bavaria and Baden-Württemberg. Munich anchors regional distribution infrastructure for Central European pharmacy chains.
Japan
Expanding allergic rhinitis diagnoses extend antihistamine consumption beyond traditional seasonal peaks. PMDA maintains stringent stability testing requirements for liquid pediatric formulations. Osaka and Tokyo metropolitan areas concentrate pharmacy chain headquarters deploying predictive demand analytics.
Global Cold and Flu Drugs Market Competitive Landscape
The competitive structure tilts toward diversified healthcare conglomerates with consumer health divisions. Market concentration remains moderate, with established pharmaceutical multinationals competing against regional generic specialists and emerging private-label suppliers. Three archetypes dominate: vertically integrated API-to-formulation operators, consumer health spin-offs with retail channel leverage, and contract manufacturing organizations serving pharmacy private-label programs. Capacity expansion and portfolio diversification represent the primary competitive vectors, with players consolidating around proven active ingredients with documented safety profiles.
Among diversified healthcare conglomerates, Johnson & Johnson and GSK plc occupy positions reflecting consumer health division scale, while Bayer AG exemplifies specialization in plant-derived therapeutic categories. Reckitt Benckiser Group plc and Haleon Group plc represent consumer health spin-off archetypes with pharmacy channel concentration. Sun Pharmaceutical Industries Ltd. anchors the generic specialist tier with India-based manufacturing scale.
| Leading Market Players |
|---|
| Reckitt Benckiser Group plc |
| Perrigo Company plc |
| Johnson & Johnson |
| GSK plc |
| Sun Pharmaceutical Industries Ltd. |
| Bayer AG |
| Viatris Inc. |
| Haleon Group plc |
| Sanofi S.A. |
| Others |
Supply & Pricing Matrix
Acetaminophen precursor spot indices cascade through formulation tiers, compressing margins for generic tablet manufacturers while enabling branded combination therapies to command stability premiums through pharmacy chain exclusivity arrangements.
Pricing Analysis
Symptom-resolution speed anchors value-based pricing for multi-symptom combination therapies in United States retail channels. Pricing stratifies across premium branded, standard private-label, and economy generic tiers based on excipient quality documentation and FDA monograph compliance status. Cost compression in the economy tier intensifies because India's PLI scheme expands paracetamol API output. Price-sensitive independent pharmacies in Brazil and Mexico gravitate toward economy generics, while least-sensitive hospital systems in Japan prioritize premium formulations with pediatric safety certifications.
Supply Chain Analysis
Regional distribution centers in New Jersey, Rotterdam, and Singapore orchestrate hub-and-spoke patterns for temperature-sensitive liquid formulations. API synthesis concentrates in China, India, and the United States, with Zhejiang province and Hyderabad anchoring precursor output for global formulators. Manufacturing draws from acetaminophen precursors, pseudoephedrine feedstocks, and biodegradable starch-based excipients. Single-source vulnerability persists in China's dominance of dextromethorphan intermediate production. Distribution runs through consolidated retail pharmacy chains in North America and fragmented independent networks in Latin America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API supply concentration in East Asian manufacturing clusters props pricing power for vertically integrated formulators, constraining margin expansion for pure-play distributors.
For Market Incumbents: Deepen backward integration into acetaminophen precursor production through captive facilities in India or long-term offtake agreements with Zhejiang-based suppliers. Consolidate SKU portfolios around FDA monograph-compliant formulations to deflect REACH-driven reformulation costs in European markets. For New Entrants and Emerging Players: Launch via direct-to-patient subscription platforms targeting chronic antihistamine users in Japan and South Korea, bypassing wholesale markups that compress retail pharmacy margins. White-space concentration sits in biodegradable excipient formulations for EU Green Deal-compliant markets. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier contract manufacturers with CDSCO-approved facilities in Hyderabad and Ahmedabad, positioned to capture formulation export demand into African and Southeast Asian markets. The inflection signal to monitor is NMPA pharmacopoeia modernization accelerating domestic approval timelines for imported therapies.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Excipient Transition | EU Green Deal compliance creates first-mover positioning for starch-based tablet coatings in German pharmacy chains. |
| Direct-to-Patient Platform Launch | Amazon Pharmacy and CVS Caremark subscription models lock in chronic antihistamine volume with predictive replenishment. |
| API Manufacturing Scale-Up | India's PLI scheme incentives reduce import dependency for paracetamol and pseudoephedrine precursors. |
| Regulatory Approval Pathway Optimization | FDA OTC monograph reform accelerates prescription-to-non-prescription switches for established decongestant ingredients. |
| Distribution Channel Expansion | Brazil and Mexico digital pharmacy platforms bypass traditional wholesale markups through automated prescription verification. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. FDA filings, EMA submissions, NMPA pharmacopoeia updates, and ClinicalTrials.gov databases provided validation anchors. Bottom-up volume modeling triangulated against top-down expenditure estimates across formulation chemistry and distribution channel dimensions.
Granularity-level modeling deployed treatment line, dosage form, patient population, and regional regulatory cluster dimensions at the SKU level. CAGRs derived from multivariate regression across epidemiological burden projections, reimbursement policy trajectories, and manufacturing capacity expansion schedules. Forecast inputs incorporated API precursor price indices and pharmacy channel consolidation rates.
Regulatory divergence between FDA, EMA, and NMPA frameworks, API supply disruption events, and excipient safety guideline revisions are the dominant revision risks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Antipyretic Drugs for Children Market
Pharmaceuticals
Peptide Therapeutics Market
Pharmaceuticals
PDE Inhibitors Market
Pharmaceuticals
South Korea Diabetes Drugs Market
Pharmaceuticals
Japan Diabetes Drugs Market
Pharmaceuticals
India Nicotine Replacement Therapy Market
Pharmaceuticals
Human Papillomavirus (HPV) Vaccine Market
Pharmaceuticals
Global BHK Rabies Vaccine Market
Pharmaceuticals
Unfractionated Heparin Market
Pharmaceuticals
Global Opioid Induced Constipation Market
Pharmaceuticals
Hypertriglyceridemia Therapeutics Market
Pharmaceuticals
United States Over the Counter (OTC) Drugs Market
Pharmaceuticals
Esomeprazole Market
Pharmaceuticals
Sweden Pharmaceutical Market
Pharmaceuticals
Complement-Targeted Therapeutics Market
Pharmaceuticals
Urban Pharma Micro-Depot and Delivery Network Market