
 Global Phosphoric Acid Market | 2026-2036
Global Phosphoric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Phosphoric Acid Market Foresight
Specialized chemical engineering talent is reorganizing around wet-process phosphoric acid purification and thermal acid conversion, tightening labor availability for new plant commissioning. OCP Group leverages captive phosphate rock reserves in Morocco to sustain vertical integration from mine to merchant acid. The Mosaic Company anchors North American supply through its Florida phosphate operations and downstream fertilizer integration. PJSC PhosAgro competes on sulfuric acid self-sufficiency and Arctic logistics access to European buyers.
Phosphoric acid (H₃PO₄) is a mineral acid produced primarily via the wet process reaction of phosphate rock with sulfuric acid, yielding acid concentrations of 75-85% P₂O₅ equivalent for industrial grades, or through thermal reduction of elemental phosphorus for higher-purity electronic and food applications. Its dominant commercial purpose lies in phosphate fertilizer manufacturing, where it serves as the intermediate for ammonium phosphates and triple superphosphate. Technical grade acid dominates volume flows into fertilizer and metal treatment applications where purity tolerance allows lower processing cost. Food grade commands concentrated margin pools from phosphate additive demand in processed meat and dairy stabilization, though volume remains fractionally small against agricultural offtake.
EPA effluent guidelines in the US, REACH chemical registration in Europe, and China's MEE emission standards for phosphate fertilizer production are elevating capital requirements for sulfur recovery and fluorine containment at acid plants. The EU F-Gas Regulation further constrains process cooling chemistries in thermal acid facilities, redirecting investment toward membrane purification retrofits. Stakeholders must monitor phosphate rock export quota shifts in Morocco and China alongside sulfur pricing volatility, as these dual feedstock dynamics determine margin compression or expansion for merchant acid producers without captive mining assets.
Market Dynamics
Phosphoric acid producers face intensifying pressure from Morocco's OCP Group consolidating captive phosphate rock access, forcing merchant acid competitors to absorb sulfur cost volatility without upstream mining control.
Growth Catalysts
- India fertilizer procurement:State-sponsored nutrient subsidy programs are expanding phosphate-based fertilizer offtake from domestic blenders and importers.
- Wet-process membrane purification:Advanced solvent extraction and membrane filtration technologies are enabling food-grade acid production from lower-quality phosphate feedstock.
- REACH chemical registration:European compliance requirements for industrial chemical purity are accelerating replacement of aging thermal acid capacity with upgraded wet-process plants.
Market Restraints
- Phosphate rock supply concentration:Morocco and China control over 70% of exportable phosphate rock reserves, exposing merchant acid producers to quota manipulation and price spikes.
- Sulfur input cost volatility:Refinery-derived sulfur prices fluctuate with crude oil and natural gas processing economics, compressing margins for sulfuric acid-dependent wet-process operations.
- Fluorine containment requirements:EPA effluent guidelines and China's MEE emission standards mandate capital-intensive scrubbing systems for hydrofluorosilicic acid recovery at acid plants.
Strategic Opportunities
- Brazil agricultural expansion:Cerrado region soybean and corn cultivation is driving phosphate fertilizer consumption beyond domestic acid production capacity.
- EU F-Gas Regulation retrofit demand:Thermal acid facilities face process cooling chemistry constraints, creating equipment upgrade contracts for membrane purification system vendors.
- Electronic-grade acid qualification:Semiconductor wet-etching applications require sub-ppb metal impurity specifications, opening premium pricing tiers for thermal acid producers with purification expertise.
Industry Challenges
- Wet-process purification engineering scarcity:Specialized chemical engineering talent for solvent extraction and crystallization unit commissioning commands premium compensation and extended lead times.
- Multi-jurisdiction certification timelines:Food-grade acid producers must secure simultaneous FDA, EFSA, and FSSAI approvals, stretching product launch schedules across 18-24 month windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Phosphoric Acid Market |
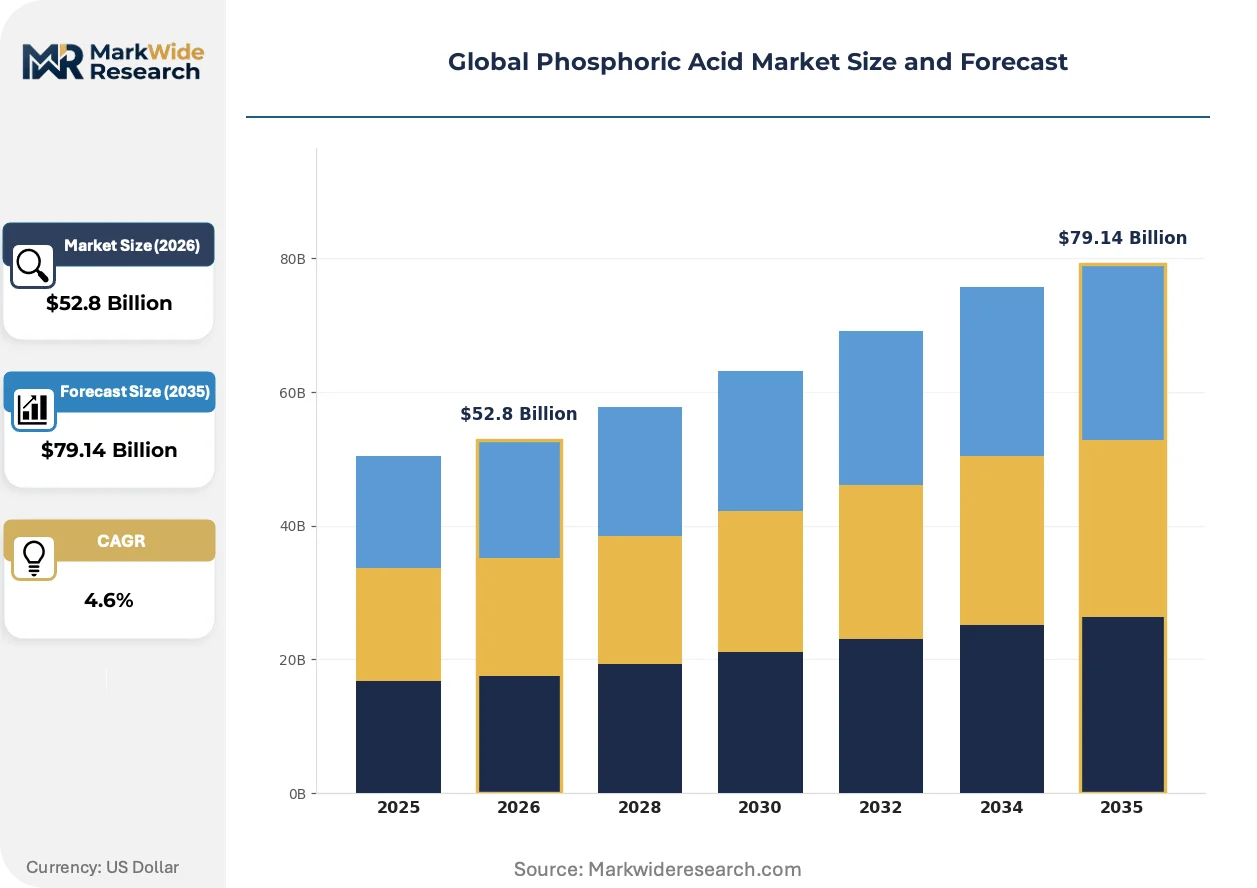
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $79.14 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Technical Grade, Pharmaceutical Grade, Industrial Grade Application: Fertilizers, Detergents, Metal Treatment, Food Additives, Water Treatment, Flame Retardants End User Industry: Agriculture, Chemical Manufacturing, Food Processing, Water Utilities, Metal Fabrication, Fire Safety Packaging Type: Drums, Bulk Bags, IBC Containers, Tankers, Bottles |
| Companies Covered | OCP Group, The Mosaic Company, PJSC PhosAgro, ICL Group Ltd, Nutrien Ltd, EuroChem Group AG, Ma’aden, IFFCO, Prayon Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Phosphoric Acid Market Shifts & Advancements
Process intensification and regulatory chemistry constraints are reconfiguring how phosphoric acid purity grades are produced and certified across fertilizer, food, and electronic end-uses.
Membrane-based solvent extraction systems for wet-process acid purification are displacing traditional thermal reduction routes to electronic-grade material. Semiconductor chemical suppliers in South Korea and Taiwan are adopting these systems to bypass elemental phosphorus production and its associated energy intensity. This shift is compressing the historical cost gap between wet-process and thermal acid for high-purity applications.
China's GB standards on industrial chemical purity and fluorine emission limits are tightening process design requirements for new acid plant construction. The MEE emission standards now mandate closed-loop fluorine recovery systems that add 15-20% to capital expenditure budgets. Domestic producers are responding by consolidating smaller facilities into larger integrated complexes with shared environmental control infrastructure.
Long-term offtake contracting is displacing spot market procurement for phosphate fertilizer manufacturers. Brazilian and Indian blenders are locking in 3-5 year acid supply agreements with Moroccan and US Gulf Coast producers to hedge sulfur and freight volatility. This pattern is most visible in agricultural input purchasing departments managing working capital exposure to commodity price swings.
Global Phosphoric Acid Market Segmentation
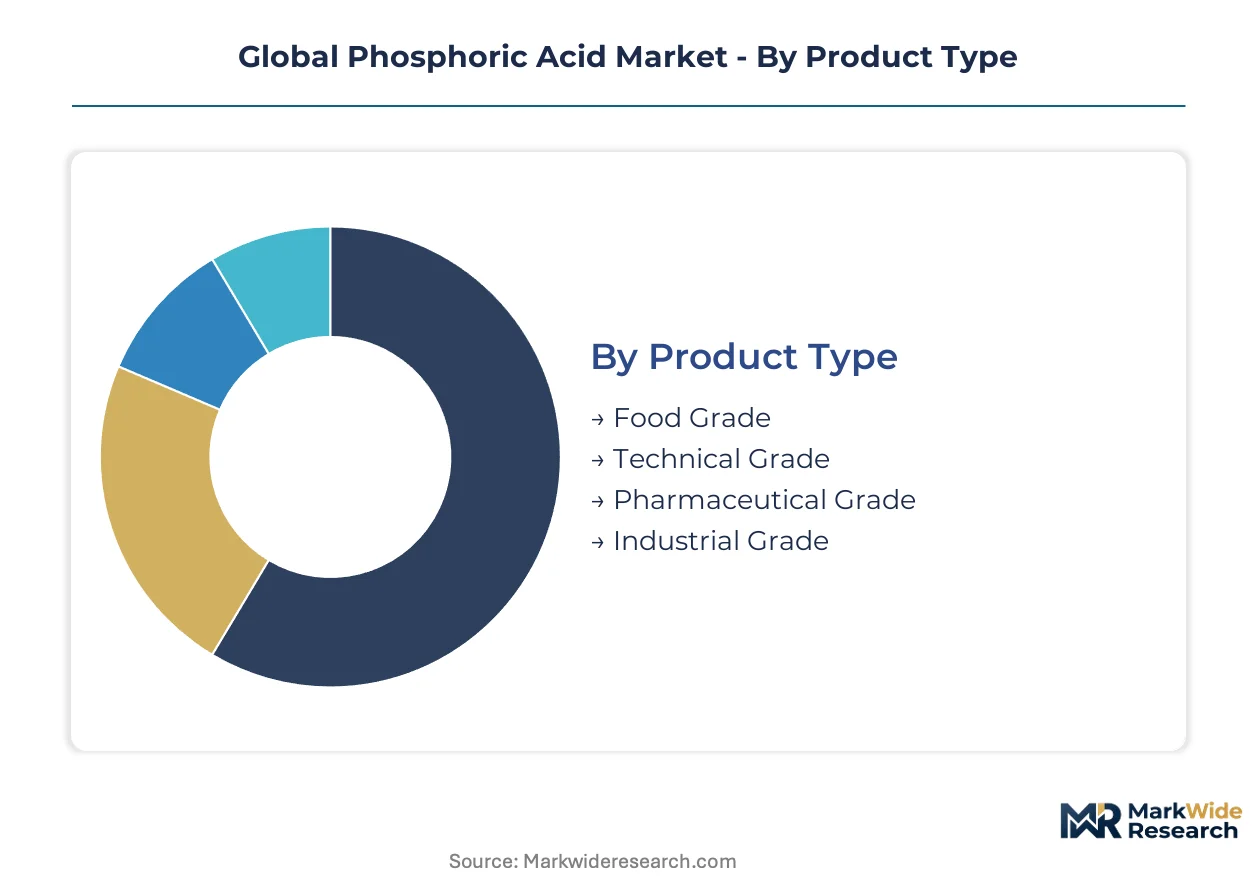
Phosphoric acid purity grades command radically different margin structures and regulatory burdens. Fertilizer manufacturers absorb technical grades at commodity scale while food and pharmaceutical certifications extract premiums through multi-jurisdiction compliance overhead.
Product Type:
Substitution pressure intensifies at the purity-grade boundary where membrane purification now enables wet-process acid to displace thermal routes in semiconductor applications.
- Technical Grade:Wet-process acid at 75-85% P₂O₅ equivalent serves phosphate fertilizer manufacturing and metal surface treatment where impurity tolerance permits lower processing cost. Demand concentrates in Morocco's OCP Group corridor and the US Gulf Coast petrochemical cluster as sulfuric acid integration determines delivered cost competitiveness.
- Food Grade:Solvent-extracted or crystallized acid meeting FDA, EFSA, and FSSAI specifications for phosphate additives in processed meat, dairy stabilization, and baking applications. Brazilian and Indian food processors are expanding procurement as domestic meat and dairy processing capacity scales.
- Industrial Grade:Intermediate purity material for water treatment chemicals and industrial cleaning formulations where food certification is unnecessary but metal contamination must stay below technical grade thresholds.
- Pharmaceutical Grade:Highest purity tier for intravenous solutions and active pharmaceutical ingredient synthesis, requiring sub-ppm metal specifications and batch-level documentation.
Technical grade anchors the volume base while food grade gains share at the steepest rate as emerging market food processing infrastructure expands.
Application:
Cost tier differentiation separates commodity-scale fertilizer absorption from specialty chemical premiums where purity certification commands pricing power.
- Fertilizers:Dominant application converting phosphoric acid into ammonium phosphates and triple superphosphate for Brazilian Cerrado soybean cultivation and Indian state-subsidized nutrient programs. OCP Group and The Mosaic Company anchor supply through captive phosphate rock integration.
- Food Additives:Phosphate salts for moisture retention, pH buffering, and emulsification in processed proteins and dairy. South Korean and Taiwanese semiconductor chemical suppliers are repurposing food-grade purification expertise toward electronic applications.
- Metal Treatment:Pickling and rust removal formulations for steel fabrication, competing with hydrochloric and sulfuric acid alternatives on cost and waste disposal economics.
- Detergents:Phosphate builders for industrial cleaning compounds, constrained by EU and US eutrophication regulations limiting discharge into watersheds.
- Water Treatment:Corrosion inhibition and pH adjustment for municipal and industrial water systems, competing with polyphosphate and non-phosphate alternatives.
- Flame Retardants:Ammonium polyphosphate formulations for textile and construction applications, facing halogen-free substitution pressure from phosphorus-nitrogen intumescent systems.
Fertilizer applications absorb the largest volume flows while food additive demand climbs fastest as processed food consumption expands in India and Southeast Asia.
End User Industry:
Customer type fragmentation separates price-tolerant agricultural procurement from specification-intensive pharmaceutical and food processing contracts.
- Agriculture:Fertilizer blenders and cooperatives in Brazil, India, and the US Midwest purchasing technical grade acid on long-term offtake contracts to hedge sulfur and freight volatility. State subsidy programs in India determine annual procurement timing and volume.
- Food Processing:Meat, dairy, and bakery manufacturers requiring multi-jurisdiction certification for phosphate additive inclusion, stretching supplier qualification timelines across 18-24 month windows.
- Chemical Manufacturing:Intermediate producers of phosphate salts, phosphates for detergents, and industrial specialty chemicals.
- Water Utilities:Municipal treatment facilities and industrial water management operations purchasing technical or industrial grades for corrosion control.
- Metal Fabrication:Steel mills and finishing operations using acid for surface preparation and scale removal.
- Fire Safety:Intumescent coating and textile manufacturers formulating ammonium polyphosphate flame retardants.
Agricultural procurement dominates absolute consumption while food processing contracts deliver the highest margin realization per ton.
Packaging Type:
Supply concentration in bulk logistics favors integrated producers with dedicated terminal infrastructure while specialty packaging serves fragmented downstream formulation.
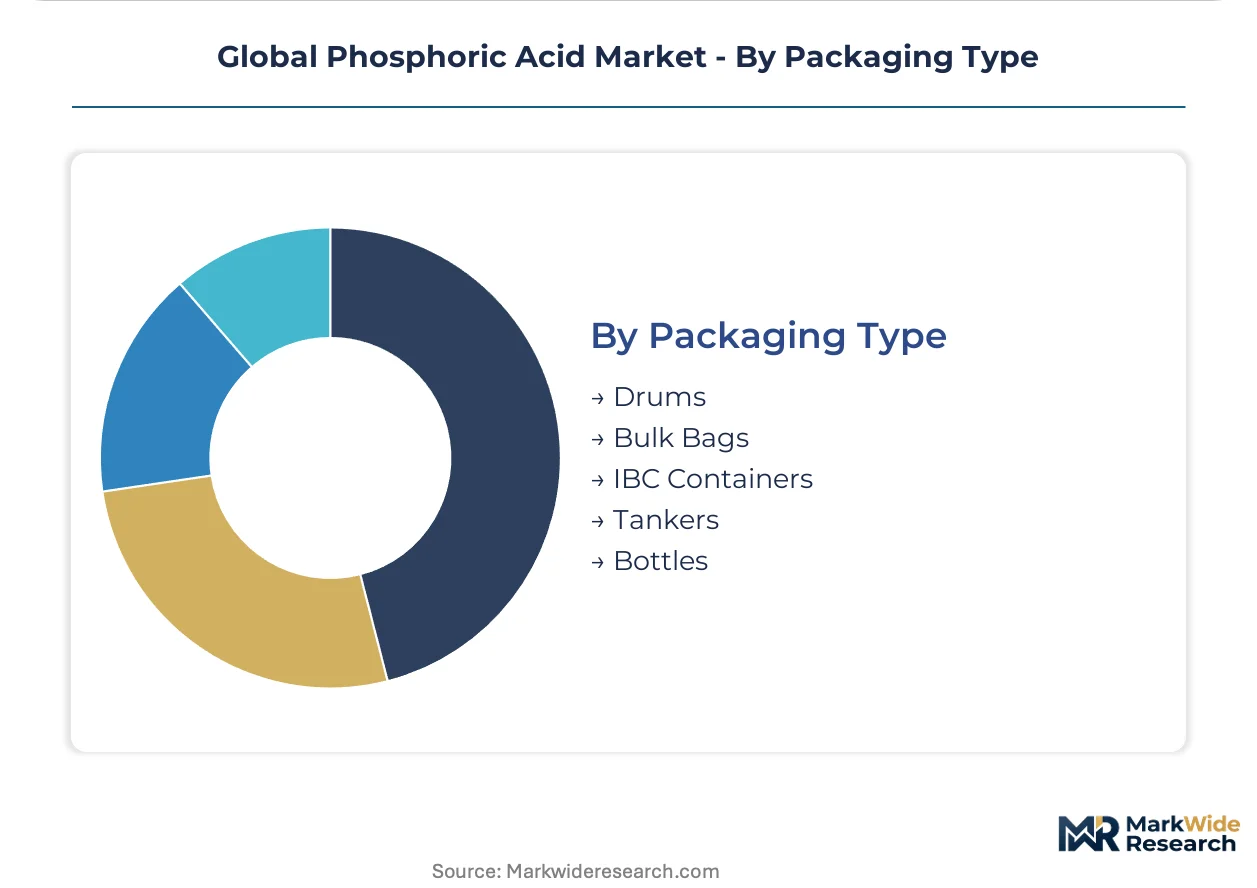
- Tankers:Rail and marine bulk delivery for fertilizer manufacturers and large chemical processors with dedicated unloading infrastructure, capturing lowest per-unit freight economics.
- IBC Containers:Intermediate bulk packaging for food processors and water treatment facilities requiring certified cleanliness without full tanker commitment.
- Bulk Bags:Solid phosphate salt shipment for downstream blending operations.
- Drums:Standard 200-liter steel or plastic containers for metal treatment and industrial cleaning compound manufacturers.
- Bottles:Laboratory and small-batch pharmaceutical and food processing applications requiring sealed contamination control.
Tanker delivery handles the greatest tonnage while IBC containers expand most quickly as mid-scale food processors upgrade from drum logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil and India absorb phosphoric acid primarily for fertilizer manufacturing, while China and the United States split demand between agricultural offtake and higher-purity industrial applications. Morocco converts captive phosphate reserves into merchant acid exports. Europe concentrates on food-grade and electronic-grade specifications with stringent purity requirements.
China
Fertilizer manufacturers in Shandong and Guizhou provinces consume wet-process acid for domestic ammonium phosphate production. MEE emission standards mandate closed-loop fluorine recovery systems that add capital intensity to new acid plant construction. The Yangtze River Delta hosts integrated phosphate complexes consolidating smaller facilities into shared environmental control infrastructure.
United States
The Mosaic Company anchors phosphate fertilizer production through Florida mining operations and downstream integration. EPA effluent guidelines enforce sulfur recovery and fluorine containment standards at acid plants. The US Gulf Coast petrochemical cluster concentrates merchant acid supply with dedicated terminal infrastructure for bulk tanker logistics.
Brazil
Cerrado region soybean and corn cultivation drives phosphate fertilizer consumption beyond domestic acid production capacity. State-sponsored agricultural credit programs determine annual procurement timing for fertilizer blenders. The São Paulo industrial corridor houses food processors expanding phosphate additive demand for meat and dairy stabilization.
India
State-sponsored nutrient subsidy programs expand phosphate-based fertilizer offtake from domestic blenders and importers. FSSAI certification requirements stretch food-grade acid supplier qualification timelines across 18-24 month windows. Gujarat and Maharashtra host fertilizer manufacturing clusters dependent on imported phosphoric acid for ammonium phosphate production.
Morocco
OCP Group leverages captive phosphate rock reserves to sustain vertical integration from mine to merchant acid. Export quota policies determine global phosphate rock availability for merchant acid producers without upstream mining control. The Khouribga mining corridor anchors integrated acid production with dedicated port infrastructure at Jorf Lasfar.
Global Phosphoric Acid Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in phosphoric acid supply. Captive phosphate rock access separates upstream-integrated producers from merchant acid competitors exposed to sulfur cost volatility. Three archetypes dominate: mining-integrated fertilizer suppliers, sulfuric acid self-sufficient processors, and specialty purification operators serving food and electronic grades. Competitive moves center on long-term offtake contracting and membrane purification technology licensing.
Within the integrated mining tier, OCP Group and The Mosaic Company exemplify upstream control over phosphate rock reserves. PJSC PhosAgro occupies a position emphasizing sulfuric acid self-sufficiency and Arctic logistics access to European buyers. These three anchors represent distinct geographic and supply-chain configurations: Moroccan captive mining, US Gulf Coast petrochemical integration, and Russian sulfur self-sufficiency with northern export routes.
| Leading Market Players |
|---|
| OCP Group |
| The Mosaic Company |
| PJSC PhosAgro |
| ICL Group Ltd |
| Nutrien Ltd |
| EuroChem Group AG |
| Ma'aden |
| IFFCO |
| Prayon Group |
| Others |
Supply & Pricing Matrix
REACH chemical registration and FDA food-grade certification regimes gate both supplier qualification timelines and price differentiation across purity tiers, forcing merchant acid producers to absorb compliance overhead while integrated miners capture margin through captive phosphate rock control.
Pricing Analysis
Long-term offtake contracts dominate procurement for Brazilian and Indian fertilizer blenders seeking sulfur and freight volatility hedges, while spot markets serve smaller metal treatment compounders with lower volume predictability. Three-tier pricing structure across food-grade, industrial-grade, and technical-grade levels reflects certification burden and impurity tolerance rather than manufacturing cost alone. Cost compression in technical-grade volumes is intensifying because OCP Group's Moroccan captive mining anchors global phosphate rock pricing. Agricultural blenders exhibit highest price sensitivity, while semiconductor chemical suppliers accept premium thermal acid pricing for sub-ppb metal specifications.
Supply Chain Analysis
Morocco and China anchor global phosphate rock extraction, with OCP Group's Khouribga corridor and Chinese Guizhou-Shandong mining clusters feeding downstream acid production. Wet-process operations draw from sulfuric acid integration, thermal reduction routes rest on elemental phosphorus energy intensity, and membrane purification systems hinge on solvent extraction chemical inputs. Single-source vulnerability concentrates in Moroccan export quota policies that determine rock availability for merchant acid producers without upstream mining assets. Distribution runs through dedicated marine terminals at Jorf Lasfar and US Gulf Coast petrochemical clusters for bulk tanker delivery to fertilizer manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wet-process membrane purification is reshaping competitive positioning by enabling food-grade and electronic-grade production from lower-quality phosphate feedstock, collapsing the historical cost advantage of thermal reduction routes.
For Market Incumbents: Compound captive mining advantages through long-term offtake contracting with Brazilian and Indian fertilizer blenders before merchant competitors secure sulfuric acid integration. Invest in solvent extraction and crystallization unit commissioning capabilities to defend against membrane purification technology licensors displacing thermal acid in semiconductor applications. Priority levers include backward integration into sulfur recovery systems and fluorine containment retrofit expertise. For New Entrants and Emerging Players: Lead with electronic-grade acid qualification for South Korean and Taiwanese semiconductor wet-etching chemical suppliers, where sub-ppb metal impurity specifications command premium pricing tiers absent from commodity fertilizer markets. Target food-grade certification in Brazil's São Paulo industrial corridor, where meat and dairy processing expansion outpaces domestic phosphate additive supply. Go-to-market angle: membrane-based purification system licensing to bypass elemental phosphorus production capital intensity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across wet-process acid purification as China's MEE emission standards mandate closed-loop fluorine recovery systems adding substantial capital expenditure overhead. Long-term viability favors integrated producers with captive phosphate rock and sulfuric acid self-sufficiency over pure-play merchant acid operators exposed to dual feedstock volatility. Acquisition target archetype: mid-scale thermal acid facilities with existing purification expertise and EU F-Gas Regulation retrofit contract pipelines. Signal to watch: membrane technology licensing deal flow from semiconductor chemical suppliers bypassing traditional thermal routes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock Mining | OCP Group's captive Khouribga reserves demonstrate margin protection against sulfur cost volatility. |
| Membrane Purification Technology Licensing | South Korean semiconductor chemical suppliers adopt solvent extraction to bypass thermal reduction energy intensity. |
| Long-term Supply Agreement with Brazilian Blenders | Cerrado agricultural credit programs lock in 3-5 year acid procurement hedging freight exposure. |
| Fluorine Recovery System Retrofit | EPA effluent guidelines and China's MEE standards mandate capital-intensive scrubbing infrastructure. |
| Food-Grade Certification Investment | FDA, EFSA, and FSSAI approvals stretch supplier qualification timelines across 18-24 month windows. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC 10-K filings, and industry association reports from ACC and Cefic. Primary interviews engaged acid plant managers, procurement leads at Brazilian and Indian fertilizer blenders, distribution channel partners in the US Gulf Coast petrochemical cluster, and technical R&D directors specializing in solvent extraction purification. Bottom-up volume modeling triangulates against top-down value projections across purity grades and end-use applications.
Segmentation dimensions modeled include purity grade tier, end-use industry, packaging format, and regional production hub across the analysis window. CAGRs derive from regression analysis against phosphate rock export flows, sulfur pricing volatility indices, and fertilizer subsidy program disbursements. Industry-specific forecast inputs incorporate fluorine containment capital expenditure cycles and semiconductor wet-etching chemical demand trajectories.
Forecasts assume regulatory continuity in REACH chemical registration, EPA effluent guidelines, and China's MEE emission standards; material policy shifts in Moroccan export quotas or EU F-Gas Regulation cooling chemistry constraints would require re-modeling. Specific risks include sulfur price spikes from refinery processing economics and membrane purification technology adoption curves in electronic-grade applications. Recalibration cycles align with material shifts in phosphate rock reserve depletion rates and semiconductor fabrication capacity announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Persulfates Market
Bulk Chemicals
North America Paraffin Wax and Emulsions Market
Bulk Chemicals
Global Butyric Acid Market
Bulk Chemicals
Global Ground and Precipitated Calcium Carbonate Market
Bulk Chemicals
Glyceryl Triacetate (Triacetin) Market
Bulk Chemicals
Nitric Acid Market
Bulk Chemicals
Potassium Cryolite Market
Bulk Chemicals
Sodium Hydroxide Market
Bulk Chemicals
Granular Urea Market
Bulk Chemicals
Caprolactam Market
Bulk Chemicals
Methanesulfonic Acid Market
Bulk Chemicals
Asia-Pacific Starch Derivatives Market
Bulk Chemicals
3-Mercapto-2-Pentanone Market
Bulk Chemicals
Global Hexane Market
Bulk Chemicals
Calcium Chloride Market
Bulk Chemicals
Furandicarboxylic Acid Market