
 United States Construction Materials Market | 2026-2036
United States Construction Materials Market Size, Share, and Industry Trends Forecast 2026-2036
United States Construction Materials Market Insights
Performance-based service contracts for concrete durability monitoring and predictive maintenance is realigning how suppliers capture lifetime value from infrastructure clients. Vulcan Materials Company leverages its quarry network density across the Southeast to control regional aggregate supply chains. Martin Marietta Materials anchors its position through backward integration into cementitious products and downstream ready-mix operations. Holcim US differentiates through carbon-reduced concrete formulations that meet emerging procurement standards for federal projects.
Construction materials encompass engineered mineral and metallic inputs—Portland cement clinker with specified C3S content, graded crushed stone meeting ASTM C33, and structural steel conforming to AISC 360—that provide compressive strength, dimensional stability, and load-bearing capacity in built environments. Aggregates occupy the largest volume share due to per-mile highway consumption rates, while cement commands disproportionate margin pools tied to energy-intensive production and regional shipping radius constraints. Residential Buildings application growth links to single-family housing starts volatility, whereas Infrastructure spending exhibits lower cyclical sensitivity due to multi-year appropriation timelines.
EPA National Ambient Air Quality Standards and OSHA silica exposure limits constrain quarry operating permits and batch plant siting decisions across metropolitan statistical areas. ASTM International performance specifications and ACI 318 building code provisions determine product qualification thresholds for structural concrete in seismic zones. Stakeholders must monitor evolving Buy America domestic content thresholds as these rules reshape supplier qualification criteria for federally funded transportation projects.
Market Dynamics
Federal infrastructure appropriations under the Infrastructure Investment and Jobs Act are compressing project timelines and forcing aggregate suppliers to expand rail-served quarry capacity ahead of traditional demand signals.
Growth Catalysts
- Bridge rehabilitation mandates:Federal highway funding prioritizes structurally deficient bridge replacement, concentrating demand for high-performance concrete and corrosion-resistant rebar in the Midwest and Southeast corridors.
- Mass timber code adoption:The International Building Code's expanded provisions for cross-laminated timber construction up to 18 stories are accelerating engineered wood demand in multi-story residential projects across Oregon, Washington, and Maine.
- Buy America thresholds:Domestic content requirements for federally funded transportation projects are reshaping supplier qualification criteria and anchoring procurement decisions toward US-sourced cement and steel.
Market Restraints
- Diesel and electricity input volatility:Quarry operations and cement kilns face margin compression from energy price swings, with diesel representing 15-20% of delivered aggregate costs in remote markets.
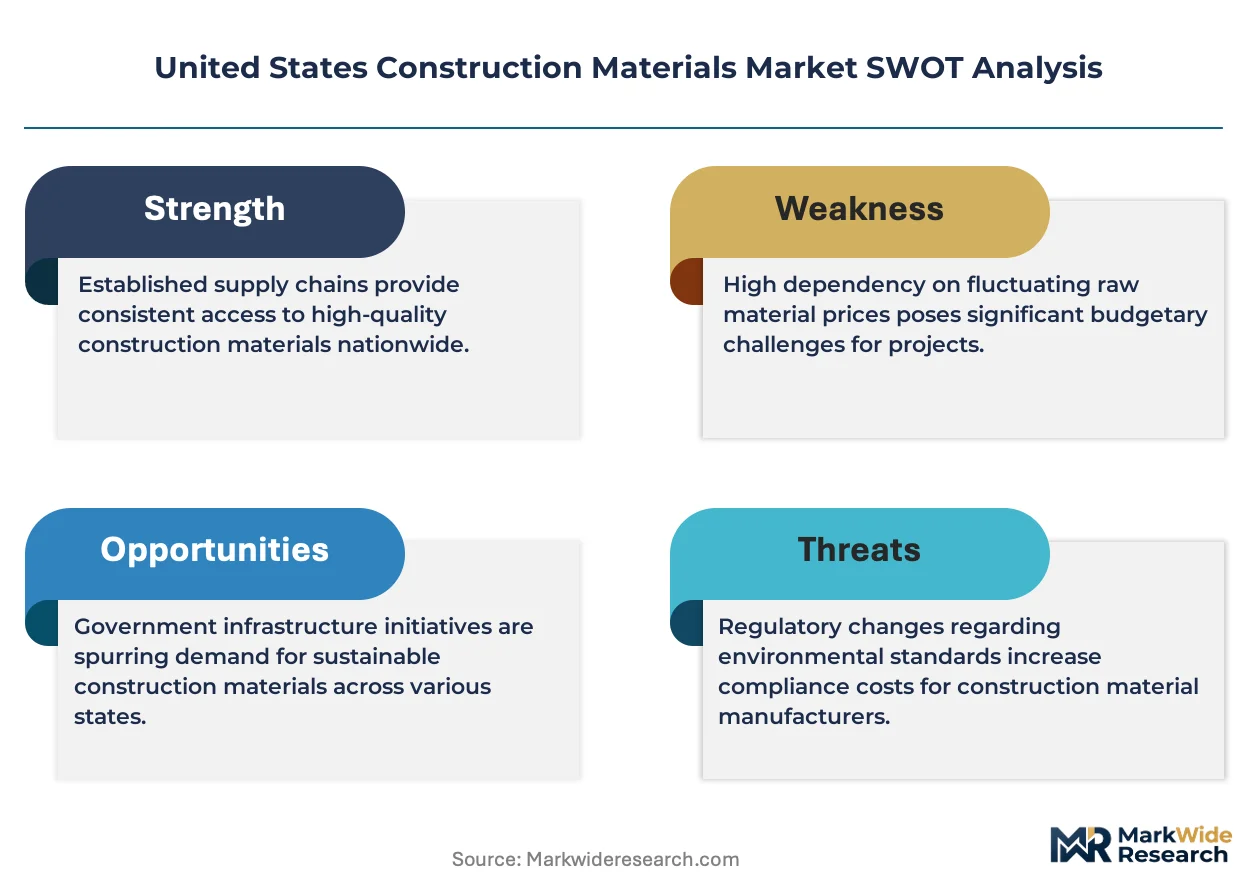
- Southeast aggregate supply concentration:Vulcan Materials and Martin Marietta control majority positions in Georgia, Alabama, and Tennessee, creating bottleneck risk for infrastructure contractors without long-term offtake agreements.
- EPA NAAQS permitting delays:New quarry siting in metropolitan statistical areas faces 18-36 month approval timelines due to particulate matter attainment designations, constraining capacity expansion in high-demand Texas and Florida markets.
Strategic Opportunities
- Carbon-reduced concrete procurement standards:Federal agencies and state DOTs are embedding embodied carbon limits into project specifications, creating first-mover advantage for suppliers with verified Environmental Product Declarations.
- Performance-based durability contracts:Infrastructure owners are piloting service agreements where suppliers guarantee concrete lifespan, shifting revenue models from volume to outcome and extending customer lifetime value.
- Texas population migration corridors:Dallas-Fort Worth and Austin metropolitan expansion is outpacing national construction activity, creating unmet demand for ready-mix concrete and structural steel in residential and commercial verticals.
Industry Challenges
- Ready-mix driver shortage:The specialized commercial driver's license requirement and seasonal demand volatility are constraining fleet utilization and extending delivery lead times in fast-growth markets.
- ASTM C33 certification bottlenecks:Independent laboratory capacity for aggregate gradation and durability testing is insufficient in the Mountain West, delaying project approvals and increasing working capital requirements for contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Construction Materials Market |
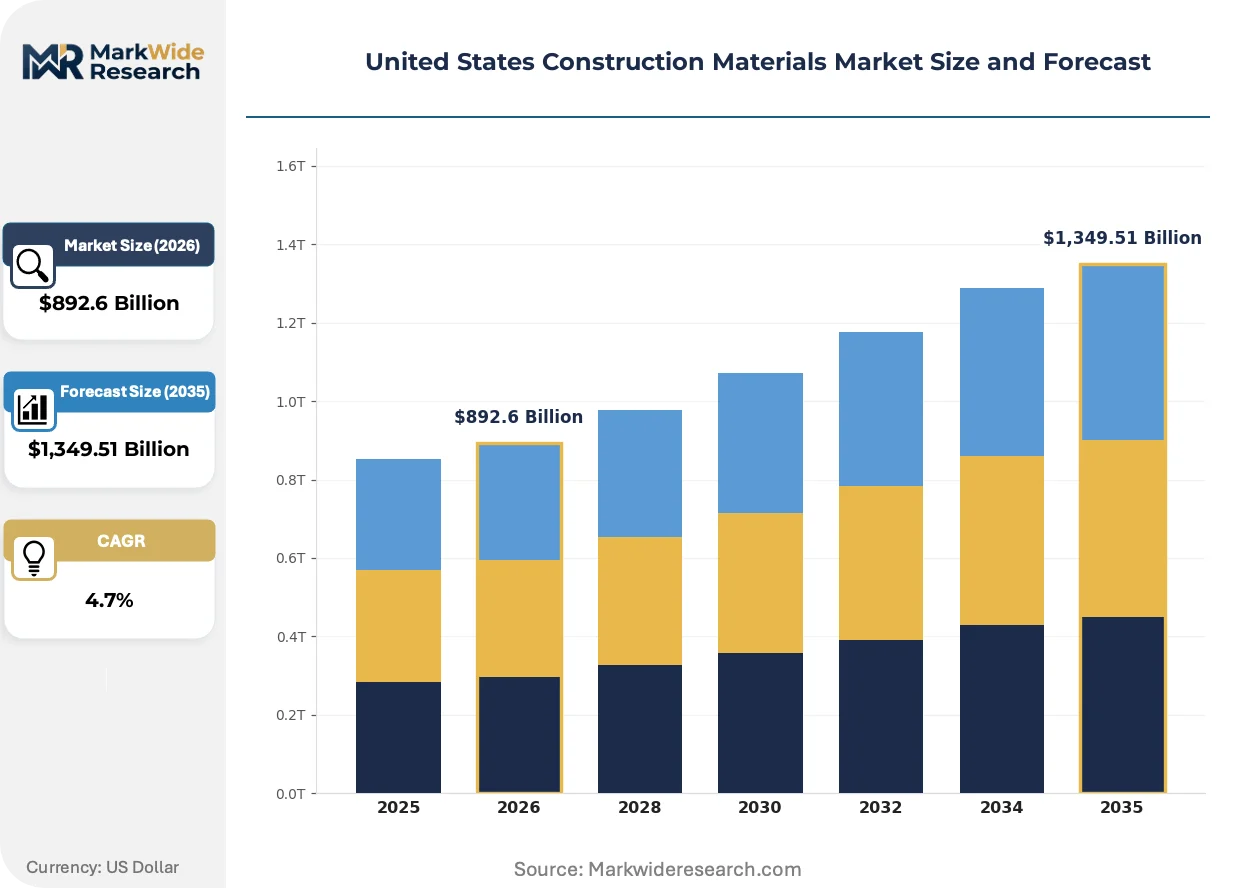
| Market Size in 2026 | $892.6 Billion |
| Market Size in 2035 | $1,349.51 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cement, Aggregates, Bricks, Steel Application: Residential Buildings, Commercial Structures, Infrastructure, Industrial Facilities End User: Contractors, Builders, Architects, Developers Distribution Channel: Direct Sales, Retail Outlets, Distributors, Online Platforms |
| Companies Covered | Vulcan Materials Company, Martin Marietta Materials, Builders FirstSource, Eagle Materials Inc., Ash Grove Cement Company, RPM International Inc., Carlisle Companies, Holcim US, CRH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Construction Materials Market Trends and Innovations
Digital fabrication and low-carbon formulation technologies are compressing traditional material procurement cycles and redefining supplier-customer relationships across residential, commercial, and infrastructure verticals.
Autonomous haulage systems are automating aggregate extraction and quarry-to-plant logistics, with major operators deploying driverless truck fleets in Arizona and Nevada surface mining operations. Cement producers and ready-mix suppliers are integrating these systems to reduce labor exposure in hazardous environments and compress cycle times for high-volume infrastructure deliveries. The technology is automating dispatch coordination between quarries, batch plants, and project sites, reducing empty-mile fuel consumption and enabling tighter just-in-time delivery windows for metropolitan construction.
OSHA's crystalline silica permissible exposure limit enforcement is tightening respirable dust controls at concrete cutting, drilling, and crushing operations nationwide. The standard is forcing capital expenditure on enclosed operator cabs, local exhaust ventilation, and real-time dust monitoring systems across the contractor base. Small and mid-sized concrete subcontractors in California, New York, and Illinois are consolidating or exiting the market due to compliance costs, concentrating volume toward integrated suppliers with in-house industrial hygiene capabilities.
Design-build and integrated project delivery contracts are displacing traditional design-bid-award sequences for complex infrastructure and commercial developments. General contractors are assuming earlier involvement in material specification, creating direct relationships with cement, steel, and engineered wood suppliers that bypass distributor intermediaries. The shift is most visible in federal highway projects and healthcare facility construction across the Southeast, where contractors are pre-qualifying suppliers based on Environmental Product Declaration availability and carbon accounting transparency rather than spot price competition.
United States Construction Materials Market Segmentation
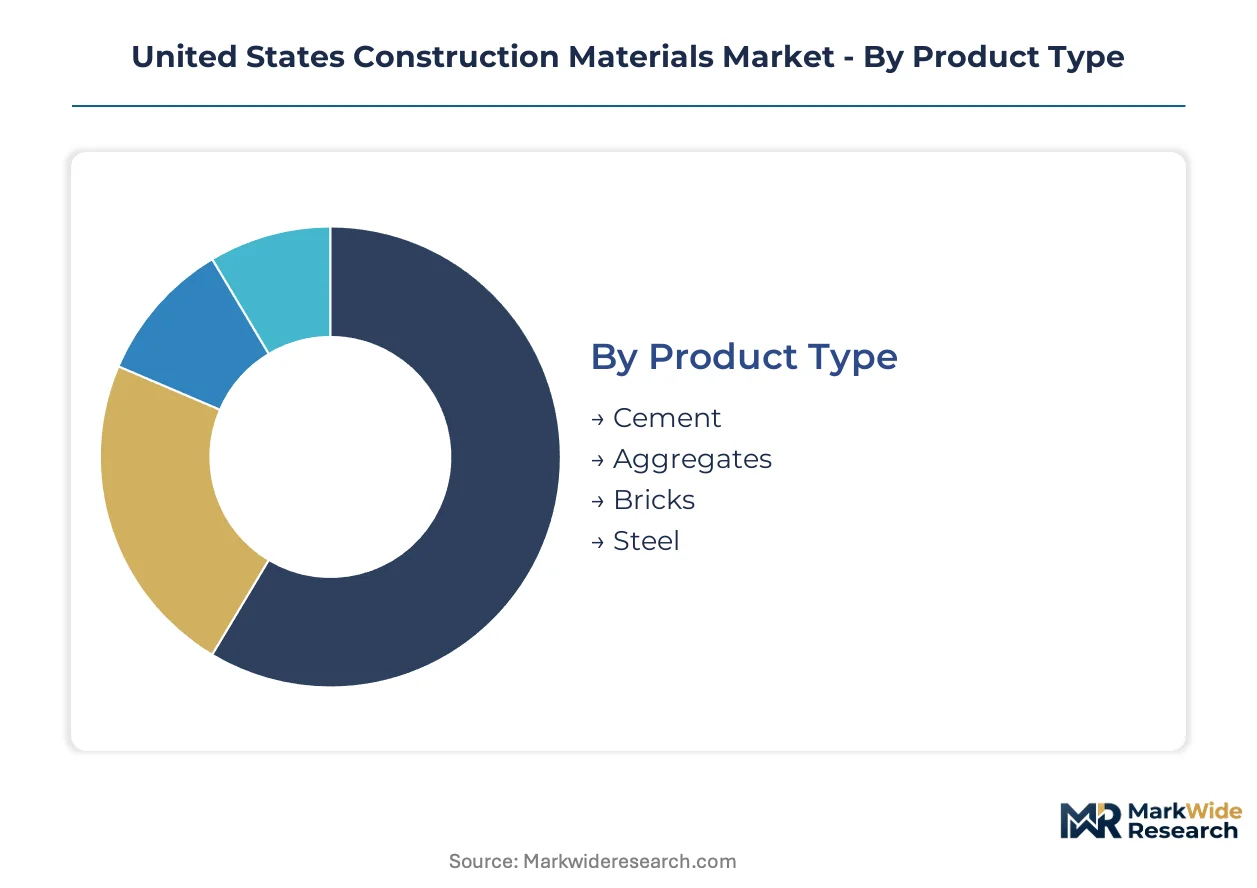
Segmentation in construction materials reveals how procurement decisions split across project scale, regulatory exposure, and supply chain reliability. Understanding these divides exposes where margin pools concentrate and which buyer categories drive specification changes.
Product Type:
Cost tier determines supplier relationships, with high-energy-intensity products commanding premium positioning and regional supply constraints.
- Cement:Portland cement clinker with specified C3S content provides compressive strength in structural concrete. EPA NAAQS permitting delays in Texas and Florida constrain kiln capacity expansion, tightening regional supply and extending order backlogs for infrastructure contractors.
- Aggregates:Graded crushed stone meeting ASTM C33 specifications delivers dimensional stability in base courses and concrete mixes. Highway expansion projects under the Infrastructure Investment and Jobs Act concentrate demand in the Southeast, where Vulcan Materials and Martin Marietta control majority quarry positions.
- Bricks:Fired clay masonry units serve residential cladding and commercial facade applications. Regional kiln operations in the Carolinas and Pennsylvania supply metropolitan construction clusters.
- Steel:Structural steel conforming to AISC 360 provides load-bearing capacity in commercial and industrial verticals. Buy America domestic content requirements anchor procurement toward domestic mill production for federally funded transportation projects.
Volume sits with Aggregates; growth tilts toward Cement as carbon-reduced formulations gain specification priority.
Application:
Project duration and funding stability separate cyclical residential exposure from multi-year infrastructure commitments.
- Infrastructure:Bridge rehabilitation and highway expansion projects under federal appropriation timelines exhibit lower cyclical sensitivity. Structurally deficient bridge replacement in the Midwest and Southeast corridors concentrates demand for high-performance concrete and corrosion-resistant rebar.
- Residential Buildings:Single-family housing starts volatility links directly to mortgage rate sensitivity and migration-driven demand in Texas, Florida, and California. Mass timber code adoption up to 18 stories is accelerating engineered wood demand in Oregon, Washington, and Maine multi-story projects.
- Commercial Structures:Office and retail construction responds to employment density shifts and capital availability. Design-build contracts are displacing traditional bid sequences, creating direct supplier-contractor relationships.
- Industrial Facilities:Manufacturing and logistics construction tracks reshoring announcements and e-commerce distribution network expansion. Heavy foundation requirements drive aggregate and ready-mix consumption at scale.
Revenue stability clusters with Infrastructure; specification innovation is expanding most quickly in Residential Buildings.
End User:
Technical sophistication and liability exposure determine whether buyers prioritize price, performance certification, or supply assurance.
- Contractors:General and specialty contractors assume material specification responsibility under design-build contracts. OSHA silica compliance costs are consolidating volume toward integrated suppliers with in-house industrial hygiene capabilities.
- Builders:Production homebuilders negotiate volume agreements for ready-mix concrete and structural components. Driver shortages and fleet utilization constraints are extending delivery lead times in fast-growth Dallas-Fort Worth and Austin markets.
- Architects:Design professionals embed embodied carbon limits and Environmental Product Declaration requirements into project specifications. Federal agency procurement standards are accelerating this specification shift.
- Developers:Project sponsors balance capital efficiency with green building certification targets. Carbon-reduced concrete procurement creates first-mover advantage for suppliers with verified EPDs.
Procurement volume flows through Contractors; specification authority is concentrating fastest with Architects.
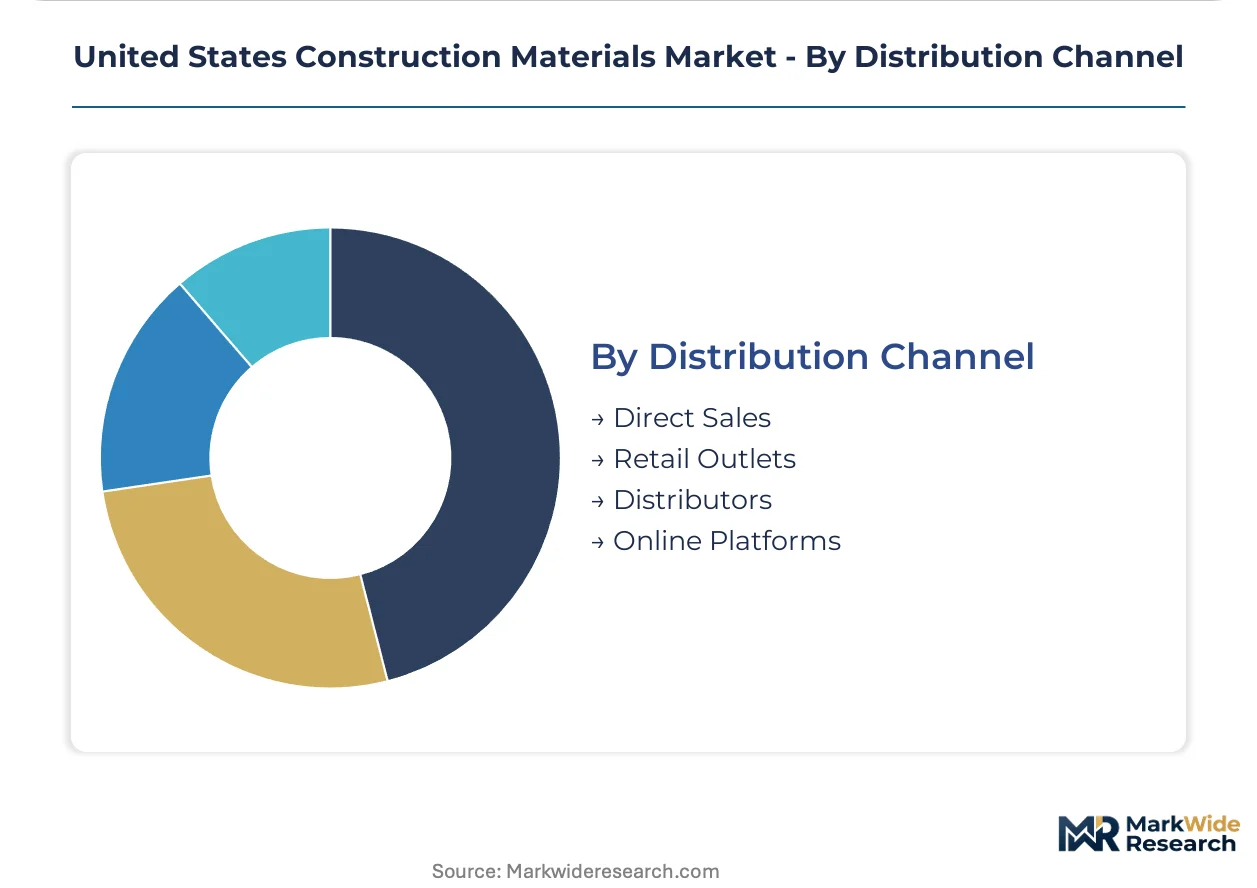
Distribution Channel:
Order size and just-in-time requirements determine whether buyers accept distributor markup or demand direct mill relationships.
- Direct Sales:Large infrastructure contractors secure long-term offtake agreements with cement producers and aggregate quarries. Rail-served quarry capacity expansion is compressing traditional demand signals under federal funding timelines.
- Distributors:Regional material yards serve mid-sized contractors with fragmented project portfolios. Inventory carrying costs and credit terms differentiate competitive positioning.
- Retail Outlets:Home improvement chains and local lumberyards supply renovation and small-scale residential construction. Last-mile delivery capabilities constrain effective service radius.
- Online Platforms:Digital procurement channels are emerging for standardized commodity products with defined specifications. Adoption remains limited by weight-to-value ratios and freight economics.
Transaction value concentrates with Direct Sales; channel experimentation is climbing fastest in Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States exhibits pronounced regional imbalances between coastal consumption centers and interior production zones. Texas and Florida absorb disproportionate material volumes while quarry capacity concentrates in the Southeast and Mountain West.
Texas
Dallas-Fort Worth and Austin metropolitan expansion drives ready-mix concrete and structural steel demand beyond regional supply capacity. EPA National Ambient Air Quality Standards constrain new quarry permitting in the Dallas metro, extending aggregate delivery radii and elevating freight costs for infrastructure contractors.
Florida
Population migration and hurricane-resistant building codes concentrate demand for concrete masonry and impact-rated structural components. State building code amendments following Hurricane Ian accelerate adoption of reinforced concrete construction in coastal counties from Miami-Dade through the Panhandle.
California
Seismic retrofit mandates and transit-oriented development sustain cement consumption despite housing start volatility. Caltrans specifications for low-carbon concrete procurement reshape supplier qualification criteria for state-funded transportation projects in Los Angeles and Bay Area corridors.
Southeast
Georgia, Alabama, and Tennessee anchor national aggregate production with rail-served quarry networks feeding Atlantic and Gulf Coast markets. Infrastructure Investment and Jobs Act bridge rehabilitation funding concentrates demand for high-performance concrete in the Midwest-Southeast corridor.
Pacific Northwest
Mass timber code adoption in Oregon and Washington accelerates cross-laminated timber demand for multi-story residential construction. Seattle and Portland building departments enforce stringent embodied carbon disclosure requirements that favor suppliers with verified Environmental Product Declarations.
United States Construction Materials Market Competitive Landscape
Capital-heavy producers compete with asset-light distributors across tiered market positions. The Southeast and Texas markets exhibit supply-side concentration, with vertically integrated quarry-to-concrete operators controlling regional aggregate flows. Three archetypes dominate: integrated materials conglomerates with cement-to-concrete pipelines; specialized aggregate miners with rail logistics advantages; and diversified building products distributors with last-mile delivery networks. Competitive dynamics center on rail-served capacity expansion and carbon-reduced formulation certification.
Among integrated materials operators, Vulcan Materials Company and Martin Marietta Materials exemplify the quarry-network archetype with southeastern density positions. Holcim US represents the multinational cement-to-concrete pipeline model with carbon-reduced formulation capabilities. These three occupy positions across the infrastructure procurement chain, from raw aggregate extraction through ready-mix delivery.
| Leading Market Players |
|---|
| Vulcan Materials Company |
| Martin Marietta Materials |
| Builders FirstSource |
| Eagle Materials Inc. |
| Ash Grove Cement Company |
| RPM International Inc. |
| Carlisle Companies |
| Holcim US |
| CRH |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap quarry operators across the Southeast and Texas anchor regional aggregate supply, their concentrated ownership patterns enabling disciplined capacity management and resisting spot-market volatility that fragments pricing power elsewhere. This ownership structure ties directly to freight economics: rail-served quarry density determines delivered cost premiums, while EPA permitting bottlenecks in Dallas-Fort Worth and Florida metros extend delivery radii and elevate landed prices for infrastructure contractors.
Pricing Analysis
Margin tightening in standard-grade aggregates reflects diesel input volatility and extended haul distances from permitted quarries. Contract-based long-term offtake agreements dominate infrastructure procurement, with price differentiation driven by ASTM C33 certification tier and rail-served delivery capability. Cost compression accelerates in remote markets as 15-20% diesel exposure erodes contractor margins. Production homebuilders exhibit highest price sensitivity due to volume volatility, while federal infrastructure contractors prioritize supply assurance over spot savings.
Supply Chain Analysis
ASTM C33 certification and EPA NAAQS permitting gate new quarry entry, concentrating supply in Georgia, Alabama, and Tennessee where Vulcan Materials and Martin Marietta control rail-served extraction. The chain draws from limestone deposits, diesel fuel, and specialized haul fleets, with single-source vulnerability in Southeast aggregate markets creating bottleneck risk for bridge rehabilitation timelines. Distribution runs through direct mill relationships for large contractors and regional material yards for fragmented project portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Construction Materials Market represents a consolidation play as OSHA silica compliance costs and EPA permitting delays force smaller concrete subcontractors toward exit or acquisition.
For Market Incumbents: Cement rail-served capacity positions in Texas and Florida ahead of traditional demand signals, capturing Infrastructure Investment and Jobs Act project flows. Backward integration into low-carbon cement formulations defends margin position against emerging federal procurement standards requiring Environmental Product Declarations. Prioritize quarry network density in migration corridors where population growth outpaces permitting velocity. For New Entrants and Emerging Players: Autonomous haulage systems offer a technology-first wedge into Arizona and Nevada surface mining operations where labor exposure and cycle time compression create adoption urgency. Target carbon-reduced concrete procurement in Pacific Northwest markets where Seattle and Portland building departments enforce stringent embodied carbon disclosure. Lead with verified EPD availability and predictive maintenance service contracts rather than volume-based spot competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized aggregate miners with rail logistics advantages in Southeast corridors where supply concentration creates pricing power. Long-term viability hinges on 5-10 year federal appropriation continuity and mass timber code expansion in multi-story residential verticals. Watch Buy America threshold enforcement as the inflection signal for domestic content premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Rail-Served Quarry Expansion | Compresses delivery lead times for Infrastructure Investment and Jobs Act bridge projects in the Midwest-Southeast corridor. |
| Carbon-Reduced Concrete Certification | Secures qualification for Caltrans and federal low-carbon procurement standards reshaping supplier selection criteria. |
| Autonomous Haulage Deployment | Reduces labor exposure and fuel consumption in Arizona and Nevada surface mining operations. |
| Performance-Based Durability Contracts | Shifts revenue models from volume to outcome, extending customer lifetime value with infrastructure owners. |
| Mass Timber Supply Chain Integration | Captures cross-laminated timber demand in Oregon and Washington multi-story residential construction. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across quarry operations managers, ready-mix procurement leads, state DOT specification engineers, and federal infrastructure contractors. National Stone, Sand and Gravel Association shipment reports, EPA enforcement and compliance databases, USGS mineral commodity summaries, and SEC 10-K filings from publicly traded materials producers supplied quantitative foundations. Bottom-up project pipeline tracking and top-down construction spending forecasts were triangulated against regional permit approval timelines.
Reconciliation of production capacity data, federal appropriation schedules, and migration-driven demand indicators shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application vertical, end-user technical sophistication, and distribution channel structure. CAGRs were derived from supply-demand imbalance analysis in high-growth corridors and carbon-reduced formulation adoption curves. Forecast inputs incorporated EPA NAAQS attainment designations and International Building Code mass timber provision expansion.
Several conditions sit outside the modeled scope, including abrupt shifts in federal infrastructure appropriation levels, hurricane frequency affecting Florida building code amendments, and breakthroughs in alternative cement chemistries. Forecasts reflect assumptions around permitting timeline continuity and diesel price regime stability. A model refresh is warranted upon material change in Buy America enforcement intensity or OSHA silica permissible exposure limit revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Germany Aluminum Door and Window Market
Building Materials
US Commercial Paving Slabs Market
Building Materials
Gravity Retaining Wall Market
Building Materials
Global Lightweight Aggregate Concrete Market
Building Materials
Ireland Cement Market
Building Materials
Global Pozzolan Market
Building Materials
Basalt Rock Market
Building Materials
Indonesia Dry Mix Mortar Market
Building Materials
HDG Steel Pipe Market
Building Materials
Cladding Market
Building Materials
Concrete Blocks and Bricks Market
Building Materials
Long Steel Market
Building Materials
North America Building and Construction Sheets Market
Building Materials
Solar Control Window Film Market
Building Materials
Saudi Arabia GRC Cladding Market
Building Materials
Cement Market