
 Light Interference Pigments Market | 2026-2036
Light Interference Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Light Interference Pigments Market Intelligence
The development of high-chroma, multi-angle color travel effects is reorganizing the value chain toward premium applications in automotive and cosmetics. BASF SE leverages its extensive chemical synthesis capabilities to produce pigments for the demanding automotive OEM sector. Merck KGaA differentiates with its portfolio of pearlescent and effect pigments for high-end cosmetics and industrial coatings. DIC Corporation sustains a dominant position by controlling a significant portion of the supply chain for organic and synthetic pigments across Asia.
Light interference pigments are complex, multi-layered structures composed of a transparent substrate like synthetic mica or silica coated with thin, precisely controlled layers of metal oxides. These pigments, including titanium dioxide and iron oxide, generate vivid color by reflecting and refracting specific wavelengths of light, creating angle-dependent color flop effects. The pearlescent product type commands a significant share, finding extensive use in cosmetics and plastics manufacturing. Automotive coatings represent the fastest-growing application, driven by consumer preference for dynamic, customized vehicle finishes.
Regulatory frameworks including the European Union’s REACH and the US EPA's Toxic Substances Control Act (TSCA) govern the chemical composition and safety profiles of pigments. Compliance with these substance registration standards, along with China's GB standards for coatings, is a prerequisite for market access and dictates raw material selection. Pigment suppliers must now decide whether to allocate R&D toward bio-based substrates or to focus on scaling production of established synthetic mica-based technologies.
Market Dynamics
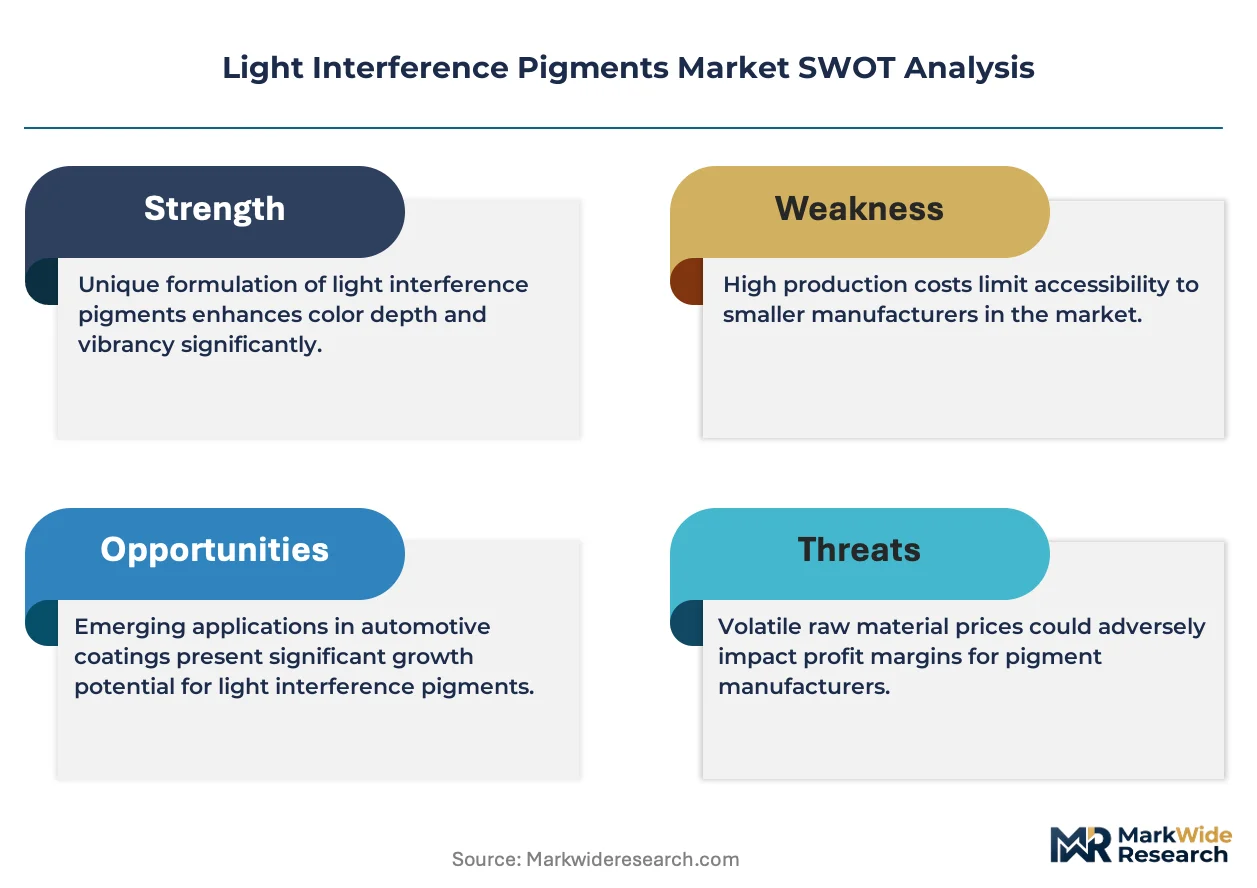
The primary dynamic shaping the market is the technical challenge of reconciling stringent environmental regulations with performance expectations. Mandates like the European Union's REACH framework are pushing formulators toward water-based systems, while automotive OEMs demand ever-higher chroma and color travel effects.
Growth Catalysts
- Automotive Customization:The demand for unique vehicle finishes and multi-angle color travel effects in the premium automotive segment is a significant driver, accelerating pigment adoption for OEM and aftermarket coatings.
- Consumer Electronics in China:China's vast consumer electronics manufacturing base requires advanced colorant solutions for device casings and components, creating a concentrated source of demand for high-performance interference pigments.
- Premium Cosmetics Formulations:The use of pearlescent and effect pigments in high-end cosmetics, including eyeshadows and nail polishes, expands as consumers seek products with unique visual textures and color-shifting properties.
Market Restraints
- Complex Manufacturing Processes:The production of light interference pigments involves precise, multi-layer deposition of metal oxides on substrates, leading to high capital expenditure, complex quality control, and elevated production costs.
- Stringent Chemical Regulations:Compliance with chemical inventories and safety standards like the EU's REACH and the US EPA's TSCA adds significant testing costs and limits the palette of available raw materials for new pigment development.
- Water-Based Formulation Challenges:Achieving stability and optimal color performance in water-based coating systems, which are increasingly mandated by environmental regulations, presents ongoing technical hurdles for pigment manufacturers.
Strategic Opportunities
- Bio-Based Substrates:Developing pigments based on biodegradable or bio-derived substrates like cellulose nanocrystals offers a path to meet sustainability goals and differentiate products in environmentally conscious markets like cosmetics.
- Anti-Counterfeiting Features:Incorporating angle-dependent color flop effects into security inks and brand protection labels for pharmaceuticals and luxury goods creates a high-value application in anti-counterfeiting solutions.
- Smart Coatings Integration:Combining interference pigments with thermochromic or photochromic technologies can create dynamic surfaces for architectural facades or interactive displays, opening new functional and aesthetic possibilities.
Industry Challenges
- Synthetic Mica Supply Scalability:Ensuring a stable, high-purity supply of synthetic mica, the preferred substrate for high-performance pigments, requires significant capital investment and long lead times to scale production capacity.
- Global Compliance Harmonization:Navigating disparate and evolving chemical registration requirements, such as China's GB standards alongside REACH and TSCA, complicates global product launches and increases administrative overhead for suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Interference Pigments Market |
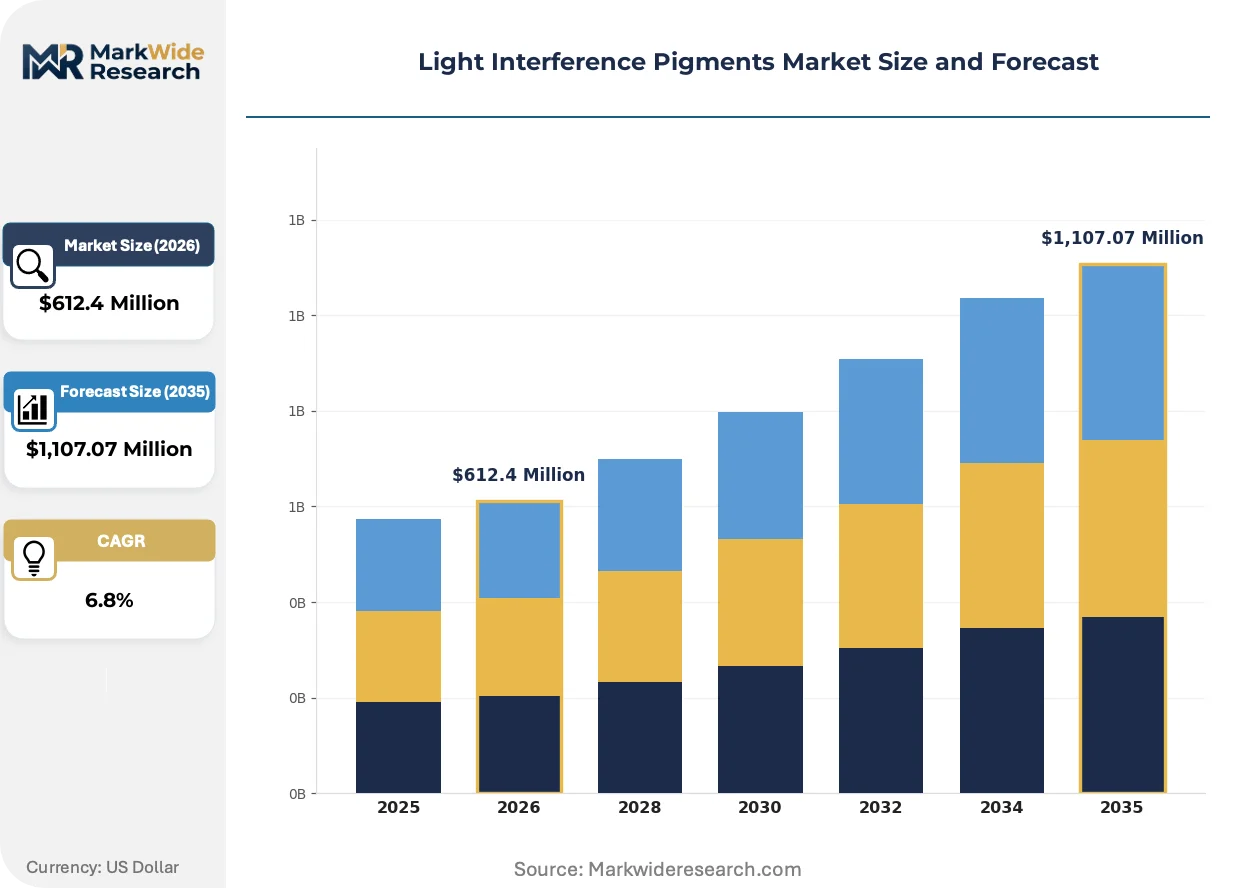
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colored, White, Metallic, Pearlescent Application: Cosmetics, Automotive Coatings, Industrial Coatings, Plastics End User: Consumer Goods, Automotive Manufacturers, Paint Suppliers, Plastic Manufacturers Formulation: Water-Based, Solvent-Based, Powdered, Liquid |
| Companies Covered | BASF SE, Viavi Solutions Inc., Merck KGaA, H. Costenoble GmbH & Co. KG, Sun Chemical, DIC Corporation, Kremer Pigments GmbH & Co. KG, Axalta Coating Systems, Clariant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Interference Pigments Market Strategic Shifts & Innovations
Product innovation is focused on achieving more vivid, multi-angle color effects while simultaneously adapting to a stricter global regulatory environment. This dual pressure forces manufacturers to advance both material science and formulation chemistry to remain competitive.
High-chroma pigments, engineered with ultra-smooth substrates and uniform nanoparticle coatings, deliver unprecedented color purity and travel. Automotive OEMs and high-end cosmetics brands are rapidly adopting these premium-grade materials to create signature colors. This advancement is decomposing the traditional value distinction between pearlescent and metallic effects, creating a new tier of hyper-chromatic finishes.
The European Union's REACH regulation continues to tighten restrictions on certain chemicals and requires extensive safety data for market access. This directly influences raw material selection, pushing pigment suppliers to phase out substances of very high concern and invest in safer alternatives. The coatings sector is most affected, accelerating its transition from solvent-based to water-based systems to ensure compliance across the European market.
End-users, particularly in automotive design, are shifting from purchasing standalone pigments to demanding co-developed, custom color solutions. This model disrupts the traditional transactional supplier relationship, requiring pigment manufacturers to provide extensive formulation support and trend forecasting services. This collaborative development approach is most prominent among European automotive brands and is gaining traction in the North American consumer electronics market.
Light Interference Pigments Market Segmentation
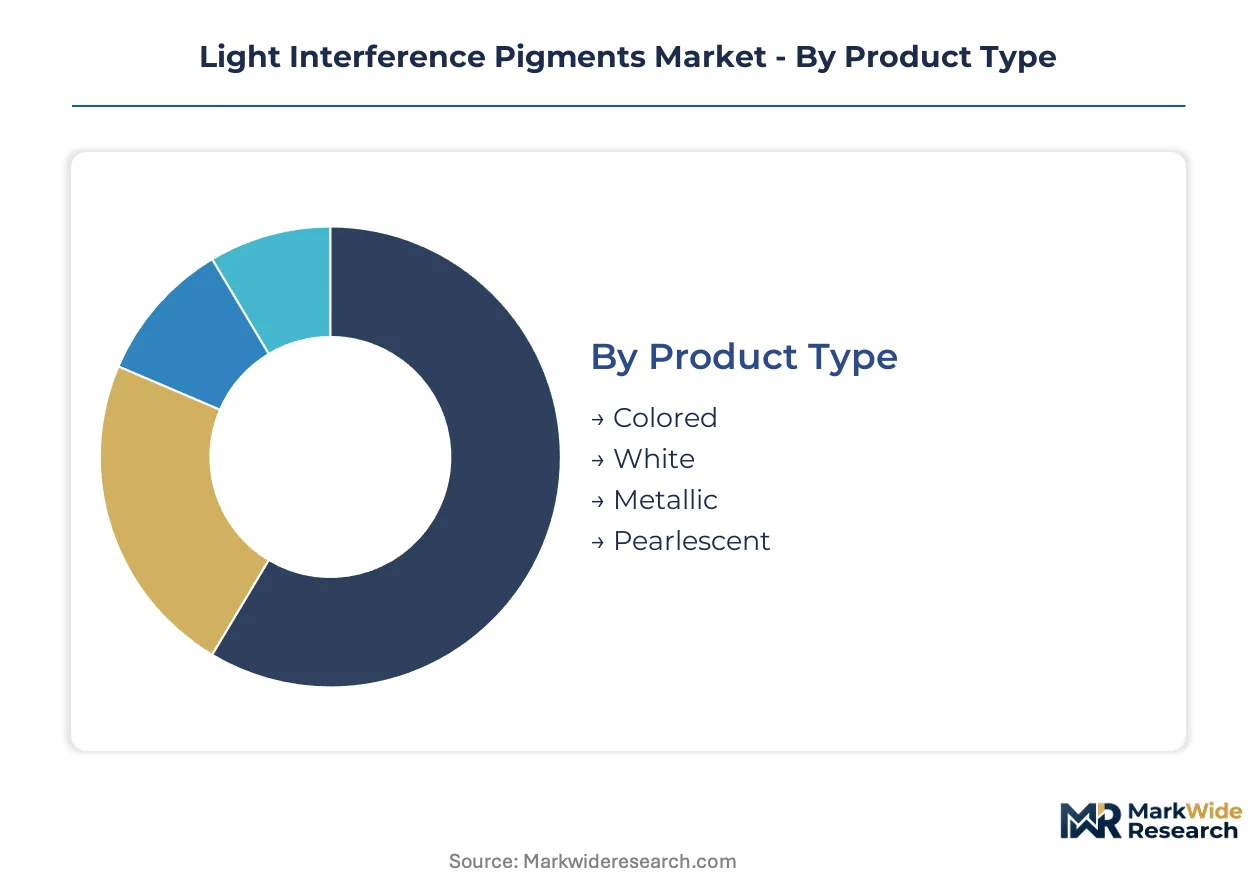
Segmentation of the light interference pigments market illuminates the diverse functional requirements and aesthetic demands across industries. Understanding these distinct segments helps manufacturers tailor product development and target specific application needs, from automotive to cosmetics.
Product Type:
Product type segmentation reveals how certain pigment effects dominate local markets while others are designed for global export.
- Pearlescent:Pearlescent pigments consist of transparent substrates coated with thin layers of metal oxides, creating a soft, lustrous sheen. This product type commands significant share, finding extensive use in cosmetics and plastics manufacturing due to its unique visual texture.
- Metallic:Metallic pigments incorporate fine metal flakes, typically aluminum or brass, to produce a reflective, opaque shimmer. Automotive coatings frequently utilize metallic pigments for deep, rich finishes, especially in premium vehicle models across Europe.
- Colored:Colored interference pigments provide vibrant, angle-dependent color shifts, enhancing visual appeal in various consumer products.
- White:White interference pigments offer a bright, iridescent effect, commonly used in decorative coatings and specialized plastics.
Pearlescent pigments command the established base. The steepest expansion runs through metallic effects for high-end applications.
Application:
Application segmentation highlights the varying cost structures and performance expectations for interference pigments across different industries.
- Automotive Coatings:These applications utilize multi-layered interference pigments to create dynamic, angle-dependent color travel effects on vehicle bodies. Automotive coatings represent the fastest-growing application, driven by consumer preference for customized, premium vehicle finishes.
- Cosmetics:Cosmetics incorporate interference pigments to impart shimmer, pearlescence, and color-shifting properties to makeup and personal care products. Premium cosmetics formulations, including eyeshadows and nail polishes, expand as consumers seek unique visual textures.
- Industrial Coatings:Industrial coatings employ interference pigments for durable, aesthetic finishes on architectural elements and specialized equipment.
- Plastics:Plastics integrate interference pigments to achieve decorative effects and unique visual depth in consumer goods and packaging.
Automotive coatings demonstrate a significant growth differential over traditional applications. Cosmetics continue to drive consistent volume.
End User:
End-user segmentation illustrates the distinct procurement patterns and volume requirements for light interference pigments across diverse industries.
- Automotive Manufacturers:These entities procure specialized interference pigments for direct integration into their OEM paint lines, demanding precise color matching and durability. Automotive OEMs require co-developed, custom color solutions, necessitating extensive formulation support from pigment suppliers.
- Consumer Goods:Consumer goods companies utilize interference pigments for aesthetic enhancement in product casings, packaging, and decorative items. China's vast consumer electronics manufacturing base creates a concentrated source of demand for advanced colorant solutions for device casings.
- Paint Suppliers:Paint suppliers purchase interference pigments for inclusion in their coating formulations, serving various industrial and decorative markets.
- Plastic Manufacturers:Plastic manufacturers integrate interference pigments into polymer matrices to produce visually striking components and finished products.
Automotive manufacturers represent a mature but evolving segment, while consumer goods end-users exhibit dynamic growth.
Formulation:
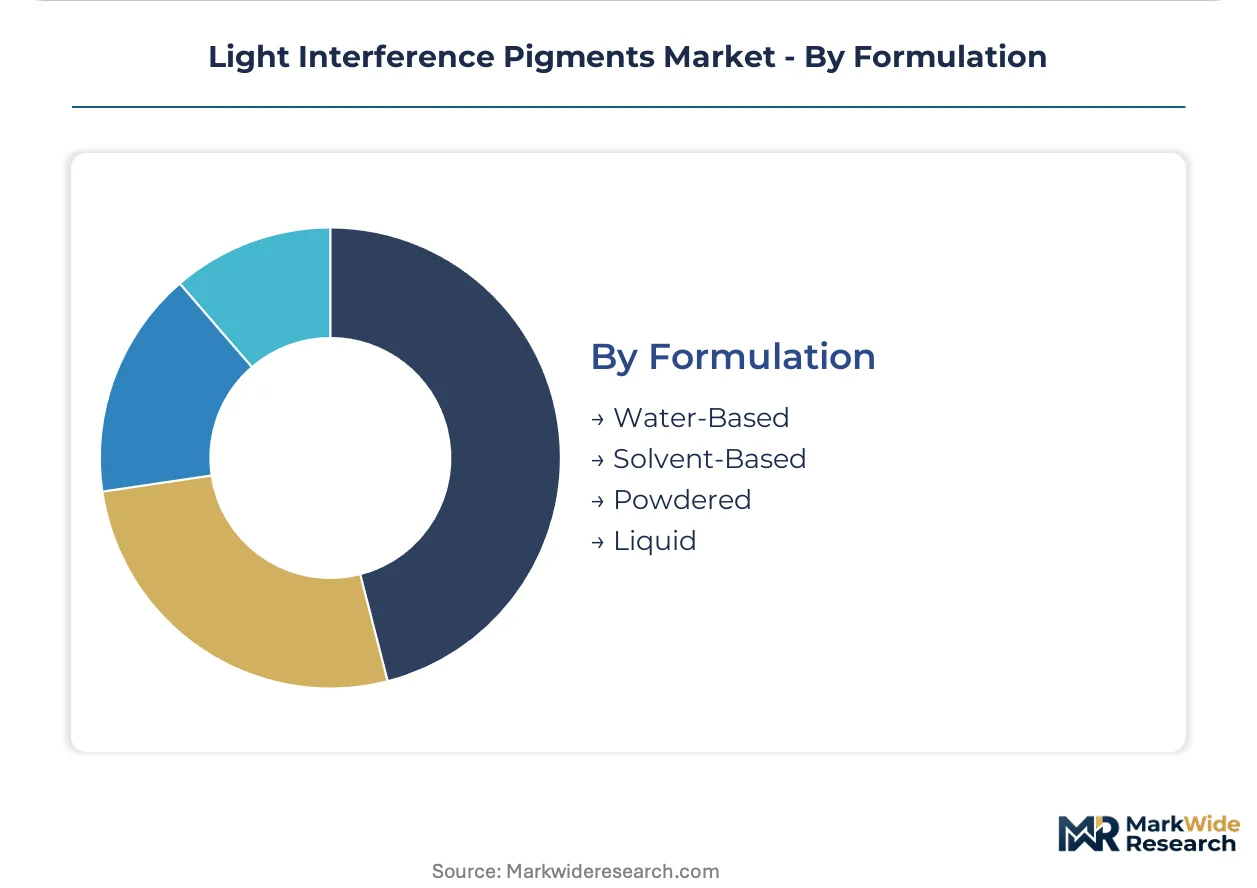
Formulation segmentation highlights the direct impact of environmental regulations and technical challenges on pigment product development.
- Water-Based:These formulations suspend interference pigments in aqueous systems, requiring specialized surface treatments for stability and optimal color performance. Mandates like the European Union's REACH framework are pushing formulators toward water-based systems to reduce VOC emissions.
- Solvent-Based:Solvent-based formulations utilize organic solvents to disperse interference pigments, offering robust performance in traditional coating applications. The coatings sector is accelerating its transition from solvent-based systems to ensure compliance across the European market.
- Powdered:Powdered formulations provide dry pigment concentrates for various applications, offering flexibility in dispersion and storage.
- Liquid:Liquid formulations present pre-dispersed interference pigments, simplifying integration into specific coating or ink systems.
Water-based formulations are a primary innovation focus, while solvent-based systems face increasing regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The light interference pigments market exhibits a complex export-import balance, with raw material sourcing often geographically distinct from final product manufacturing and application. Demand for advanced colorant solutions is concentrating in key industrial hubs globally. This dynamic shapes regional investment and supply chain strategies for pigment producers.
China
China's vast consumer electronics manufacturing base drives substantial demand for advanced colorant solutions. Compliance with China's GB standards for coatings dictates material selection and market access. The Yangtze River Delta region, a major electronics hub, sees concentrated procurement of high-performance interference pigments.
Germany
Germany's premium automotive sector demands high-chroma, multi-angle color travel effects for luxury vehicle finishes. The European Union's REACH framework heavily influences pigment formulation and raw material approval processes. Automotive OEMs in the Stuttgart region actively co-develop custom color solutions with pigment suppliers.
United States
United States automotive aftermarket and premium cosmetics formulations require diverse interference pigment solutions. The US EPA's Toxic Substances Control Act (TSCA) governs chemical safety and market entry for new pigment chemistries. California's consumer electronics design firms increasingly seek advanced colorants for innovative product casings.
Japan
Japanese manufacturers drive demand for light interference pigments in high-performance industrial coatings and specialized plastics. Japan's METI regulations and JIS standards influence product specifications and quality control. The Tokyo metropolitan area hosts significant R&D centers focused on advanced material science for pigment innovation.
India
India's expanding automotive OEM sector and consumer goods market are increasing demand for interference pigments. Compliance with India's BIS standards is essential for local market penetration and product acceptance. The Chennai automotive manufacturing cluster integrates these pigments into vehicle finishes for domestic and export models.
Light Interference Pigments Market Key Industry Players
Listed leaders compete with private specialists across material science innovation and application-specific formulation expertise for light interference pigments. The market structure is moderately consolidated, with a few global chemical giants holding significant shares, while numerous smaller players focus on niche segments. Strategic archetypes include diversified chemical conglomerates, niche effect pigment manufacturers, and specialized coating formulators. Companies primarily engage in portfolio diversification and strategic partnerships to expand their market reach and adapt to evolving regulatory landscapes.
Within the diversified chemical conglomerates, BASF SE exemplifies a broad portfolio approach, leveraging extensive chemical synthesis capabilities to serve demanding automotive and industrial sectors. Merck KGaA occupies a strong position in high-end cosmetics and specialized industrial coatings, differentiating its offerings through a comprehensive range of pearlescent and effect pigments. DIC Corporation anchors a significant portion of the supply chain for organic and synthetic pigments, sustaining a dominant position across various application segments, particularly within Asian markets.
| Leading Market Players |
|---|
| BASF SE |
| Viavi Solutions Inc. |
| Merck KGaA |
| H. Costenoble GmbH & Co. KG |
| Sun Chemical |
| DIC Corporation |
| Kremer Pigments GmbH & Co. KG |
| Axalta Coating Systems |
| Clariant |
| Others |
Cost & Logistics Intelligence
Bio-based substrate development, replacing traditional synthetic mica, reshapes pigment supply chains and pricing structures. This shift alters raw material sourcing geographies and introduces new cost considerations for pigment manufacturers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for light interference pigments. Price differentiation stems from the customization level required for unique vehicle finishes and the rigorous certification level demanded by regulations like REACH. Pricing pressure stems from the need to balance premium multi-angle effects with cost-effective water-based formulation development. Cosmetics brands exhibit lower price sensitivity for unique visual textures, while industrial coatings procurement remains more cost-conscious.
Supply Chain Analysis
China anchors synthetic mica production and concentrated consumer electronics demand for light interference pigments. The supply chain draws heavily from raw materials like synthetic mica, titanium dioxide, and iron oxide. Single-source vulnerability for high-purity synthetic mica presents a structural risk for pigment manufacturers. Distribution runs through specialized chemical distributors and direct sales channels serving large automotive OEMs globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The light interference pigments market faces a critical capability gap in developing stable, high-performance water-based formulations. This technical scarcity demands focused investment across the value chain.
For Market Incumbents:
Consolidate market position by investing heavily in bio-based substrate research and development to mitigate regulatory risks. Acquire specialized formulation expertise to master stable water-based systems, countering the threat from stringent REACH mandates. Capacity addition in high-purity synthetic mica production ensures supply stability. Certification investment for new pigment chemistries provides market access.
For New Entrants and Emerging Players:
Anchor in niche applications like premium cosmetics formulations or anti-counterfeiting features for luxury goods. The most penetrable segment for new players remains specialized plastics, where performance demands are high but volumes lower. Focus on sustainability credentials, leveraging bio-based substrates, as a key go-to-market angle. Offer unique visual effects not achievable with conventional pigments.
For Investors and Strategic Acquirers:
The market sits at a growth phase that favors specialized material science firms. Long-term viability is strong, driven by persistent demand for customization and advanced aesthetic effects in automotive and cosmetics. Target acquisition profiles should include companies with proprietary bio-based pigment technology or advanced water-based formulation expertise. Successful commercialization of water-based, high-chroma bio-pigments is the signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expanding synthetic mica production capacity ensures stable raw material supply for pigment manufacturers. |
| Bio-based Pigment Development | Developing pigments from bio-derived substrates meets sustainability goals for cosmetic and automotive brands. |
| Water-Based Formulation Expertise | Mastering water-based systems ensures compliance with EU REACH regulations for coatings manufacturers. |
| Strategic Partnerships | Collaborating with automotive OEMs provides co-developed custom color solutions for premium vehicle finishes. |
| Anti-Counterfeiting Integration | Incorporating pigments into security inks creates high-value brand protection solutions for luxury goods. |
Research Approach
Operator-level perspectives from pigment R&D directors, automotive OEM paint specialists, and cosmetic formulators anchored the qualitative base. Primary interviews combined with secondary validation from EU REACH filings, US EPA TSCA documents, and China GB standards informed the analysis. This approach integrated industry association reports and trade data. Bottom-up and top-down triangulation ensured data integrity.
Sensitivity analysis informed the quantitative modeling framework across the projection horizon. Segmentation dimensions included product type, application, end-user, formulation, and regional production hubs. Compound annual growth rates were derived from historical trends and projected market dynamics. R&D investment in bio-based materials and regulatory enforcement timelines served as key industry-specific forecast inputs.
Material uncertainties — unforeseen regulatory shifts or rapid technological disruption in substrate materials — sit outside the modeled envelope. Forecasts reflect assumptions regarding market evolution and competitive responses. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Cadmium Pigments Market
Dyes and Pigments
Bio Based Pigments and Dyes Market
Dyes and Pigments
Polymer Colorant Market
Dyes and Pigments
Synthetic Dyes Market
Dyes and Pigments
Colorants Market
Dyes and Pigments
Organic Pigment Dispersions Market
Dyes and Pigments
Global Aluminum Anodizing Dyes Market
Dyes and Pigments
High Performance Organic Pigments Market
Dyes and Pigments
Global Paint Pigments Market
Dyes and Pigments
Resin Pigments Market
Dyes and Pigments
Zinc Oxide Pigments Market
Dyes and Pigments
Algal Pigments Market
Dyes and Pigments
Pharmaceutical Dyes Market
Dyes and Pigments
Global Organic Pigments Market
Dyes and Pigments
Acrylic Colors Market
Dyes and Pigments
Ponceau 4R Colors Market