
 Colorants Market | 2026-2036
Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
Colorants Market Analysis
Food-grade and cosmetic-grade specifications is bifurcating the colorants market into premium-compliant and commodity streams. BASF SE leverages its integrated pigment and dye platform to serve pharmaceutical and food packaging accounts with certified low-migration products. Clariant anchors its position through specialty masterbatch formulations that meet EU 10/2011 food-contact standards. Sun Chemical Corporation competes in the narrow web and flexible packaging ink segments where color consistency and regulatory compliance carry premium pricing.
Colorants are substances that impart color to other materials through selective absorption and reflection of light, typically comprising chromophore-bearing organic molecules or transition-metal-based inorganic compounds manufactured via diazotization, coupling, calcination, or fermentation processes. Their primary purpose spans product identification, aesthetic enhancement, UV protection, and functional signaling across industrial and consumer goods. Natural colorants from botanical and microbial sources are gaining share in food and beverage applications where clean-label positioning commands shelf space, while synthetic organic pigments still dominate automotive and industrial coatings where lightfastness and thermal stability set performance floors. Inorganic pigments based on titanium dioxide and iron oxide sustain mature volume pools in construction and plastics despite margin compression from environmental scrutiny.
FDA color additive regulations, REACH Annex XVII restrictions on heavy metals, and EFSA re-evaluations of lake pigments are collectively elevating testing burdens and reformulation costs for suppliers seeking multi-jurisdictional market access. The EU Green Deal and state-level extended producer responsibility frameworks in Germany and France are pushing pigment houses to document carbon intensity and recyclability across their colorant portfolios. Stakeholders must monitor regulatory divergence between jurisdictions while building flexible formulation platforms that can pivot between natural and synthetic bases without full manufacturing line reinvestment.
Market Dynamics
Clean-label mandates from FSSAI in India and EFSA lake pigment re-evaluations are compressing synthetic colorant shelf life while accelerating fermentation-derived alternatives. Suppliers face simultaneous pressure to certify low-migration products for EU 10/2011 food-contact compliance and scale botanical extraction for beverage accounts.
Growth Catalysts
- EU 10/2011 Migration Limits:Food packaging converters in Germany and France now specify certified low-migration pigments, creating premium tier demand that rewards compliant suppliers with multi-year supply agreements.
- India Textile Export Surge:Tirupur and Surat processing clusters are expanding reactive dye offtake as Bangladesh and Vietnam garment orders shift to Indian mills with integrated finishing capacity.
- Fermentation Platform Scale-Up:Microbial-derived carotenoids from sugar feedstocks are achieving cost parity with synthetic alternatives in beverage applications where heat stability requirements are moderate.
Market Restraints
- Petroleum-Derived Intermediate Volatility:Naphthalene and aniline price swings compress margin predictability for azo dye manufacturers serving automotive coatings.
- Titanium Dioxide Feedstock Concentration:Ilmenite processing capacity clusters in China and Australia expose pigment houses to export duty fluctuations and shipping bottlenecks.
- Natural Colorant Lightfastness Ceiling:Anthocyanin and curcumin formulations degrade under UV exposure, restricting their deployment in outdoor signage and automotive exterior applications.
Strategic Opportunities
- Indonesia Processed Food Expansion:Instant noodle and confectionery manufacturers are localizing colorant sourcing to reduce import duty exposure on finished formulations.
- EU Green Deal Carbon Accounting:Pigment suppliers documenting Scope 3 emissions through CSRD-aligned reporting gain preferred supplier status with Unilever and Nestlé procurement teams.
- Digital Printing Ink Convergence:UV-curable inkjet formulations are merging narrow-web label and flexible packaging segments, opening single-pass production lines to mid-volume converters.
Industry Challenges
- Cross-Contamination Protocol Complexity:Facilities producing both food-grade and industrial pigments must maintain segregated production lines, doubling cleanroom capex and extending commissioning timelines.
- Dual Certification Lag:Simultaneous FDA color additive petitions and EFSA safety evaluations for novel natural extracts stretch regulatory approval cycles to 24-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colorants Market |
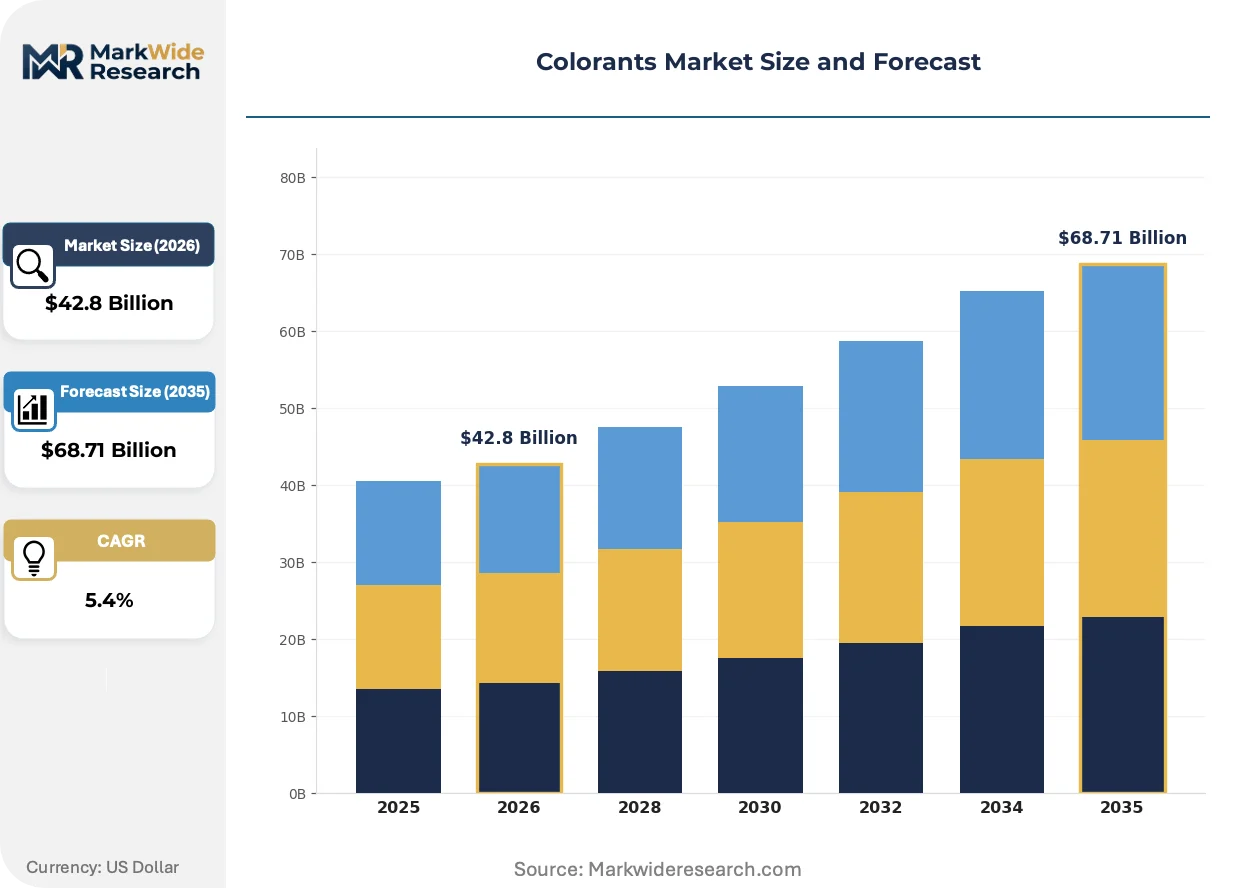
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $68.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Colorants, Synthetic Colorants, Organic Pigments, Inorganic Pigments Application: Food & Beverage, Oil & Gas, Textiles, Cosmetics End User: Manufacturers, Retailers, Distributors, Wholesalers Grade: Food Grade, Cosmetic Grade, Industrial Grade, Technical Grade |
| Companies Covered | BASF SE, Clariant, DIC Corporation, LANXESS, DuPont, Huntsman Corporation, Cabot Corporation, Sun Chemical Corporation, ADM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colorants Market Emerging Trajectories
Bioprocess engineering and regulatory disclosure requirements are compressing the innovation cycle for colorant suppliers. Three developments are restructuring competitive advantage.
Encapsulation technology using modified starch and gum arabic matrices is miniaturizing pigment particle distribution for enhanced stability in acidic beverage matrices. Soft drink formulators in Mexico and Brazil are adopting these systems to extend natural colorant viability through pasteurization. The technology is compressing reformulation cycles from 18 months to 6 months for seasonal product launches.
REACH Annex XVII heavy metal thresholds are tightening cadmium and lead limits in plastics and coatings applications. German toy manufacturers and Italian ceramic tableware exporters are accelerating substitution to rare-earth and organic alternatives. The restriction most affects inorganic pigment houses with legacy calcination assets in southern Spain and northern Italy.
Direct procurement platforms are disintermediating regional distributors for standard pigment grades. Large plastics compounders in Ohio and Bavaria now contract directly with Clariant and DIC for masterbatch volumes above 500 metric tons annually. This channel compression is visible most acutely in automotive interior specifications where color matching tolerances are tightest.
Colorants Market Segmentation
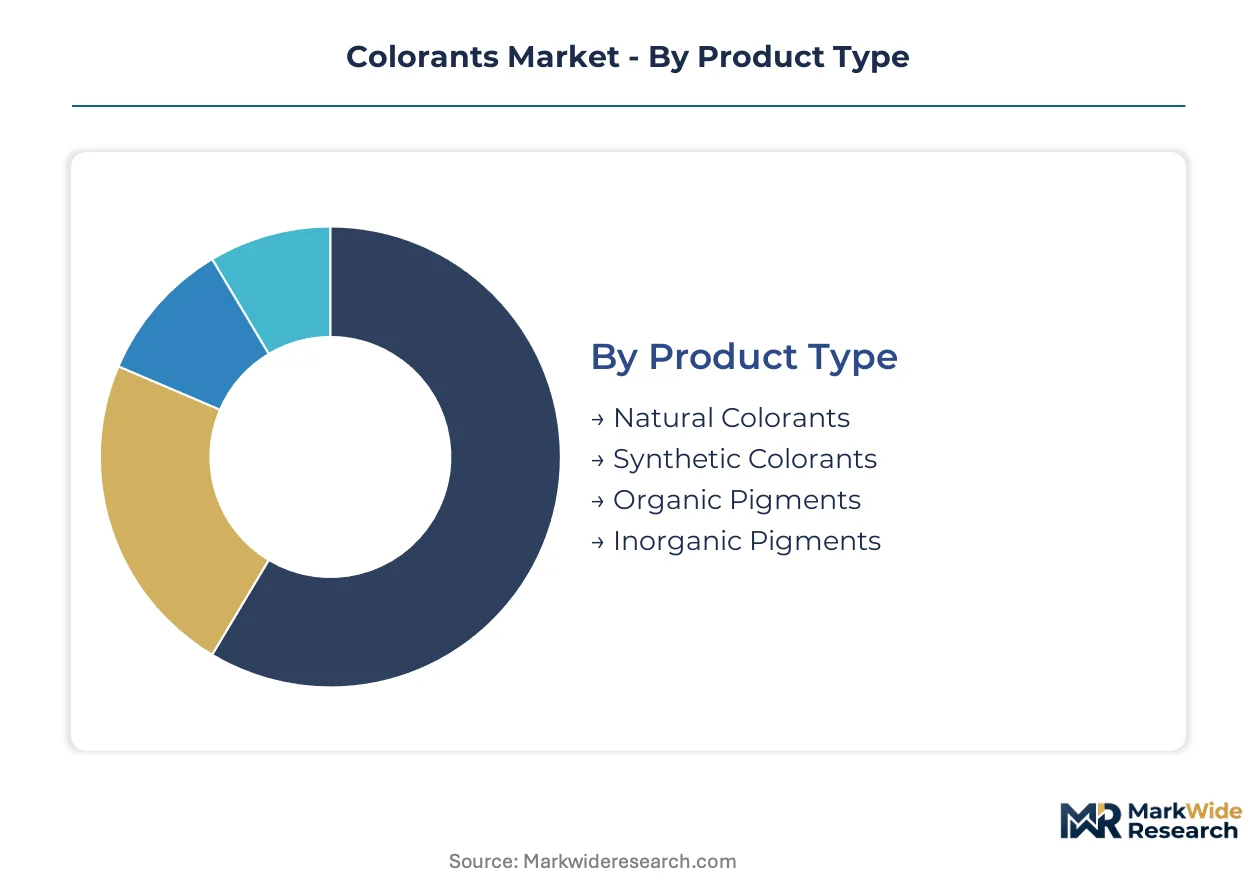
Colorant suppliers configure production assets and certification protocols around segment-specific purity thresholds. Channel economics diverge sharply between bulk industrial pigments and certified food-grade formulations requiring segregated handling.
Product Type:
Channel mix varies by molecular source: synthetic organics flow through distributor networks to coatings manufacturers, while natural extracts increasingly bypass intermediaries for direct beverage procurement.
- Natural Colorants:Anthocyanin, carotenoid, and curcumin extracts from botanical and microbial fermentation sources. Demand concentrates in European beverage clean-label launches where EFSA lake pigment restrictions are compressing synthetic alternatives. Suppliers face heat stability ceilings that restrict hot-fill applications.
- Synthetic Colorants:Azo dyes, triphenylmethane derivatives, and quinacridone pigments manufactured via diazotization and coupling reactions. Automotive coatings in Germany and Japan specify these for exterior lightfastness where natural alternatives fail. REACH Annex XVII cadmium limits are accelerating reformulation cycles.
- Organic Pigments:High-performance phthalocyanine and perylene structures for plastics and printing inks.
- Inorganic Pigments:Titanium dioxide, iron oxide, and chromium oxide from calcination processes serving construction and ceramics.
By volume, Synthetic Colorants leads. By growth pace, Natural Colorants is expanding most quickly.
Application:
Cost tier separation is pronounced: food and cosmetic applications command 3-5x pigment pricing versus industrial coatings due to certification and segregation requirements.
- Food & Beverage:Encapsulated natural colorants for acidic beverages and confectionery. FSSAI clean-label mandates in India are accelerating procurement shifts from synthetic lakes to botanical extracts. Heat stability requirements in UHT milk applications favor carmine and caramel alternatives.
- Textiles:Reactive, disperse, and vat dyes for cotton and polyester fiber processing. Tirupur and Surat clusters in India are expanding reactive dye offtake as garment finishing capacity consolidates. Bangladesh order shifts are drawing supplier investment toward integrated Indian mills.
- Cosmetics:FDA-certified lakes and iron oxides for color cosmetics and personal care.
- Oil & Gas:Leak detection dyes and pipeline identification pigments for downstream operations.
Food & Beverage generates premium margins per kilogram. Textiles dominates absolute volume throughput.
End User:
Customer type determines contract structure: manufacturers negotiate multi-year supply agreements with volume commitments, while distributors absorb working capital for smaller compounders.
- Manufacturers:Plastics compounders, coatings formulators, and food processors with in-house color matching laboratories. German automotive tier suppliers specify masterbatch volumes above 500 metric tons annually, contracting directly with pigment houses and compressing distributor margins.
- Distributors:Regional pigment traders serving mid-volume converters in Ohio, Bavaria, and São Paulo with technical service and inventory financing.
- Retailers:Direct procurement of natural colorant formulations for private-label food and cosmetic brands.
- Wholesalers:Bulk handlers of standard pigment grades for construction and industrial coatings.
Manufacturers capture lowest unit costs through scale. Retailers are gaining share fastest in natural colorant segments.
Grade:
Supply concentration intensifies at certification tiers: fewer than twenty facilities worldwide produce both food-grade and industrial-grade pigments under segregated protocols.
- Food Grade:FDA-certified color additives and EU 10/2011 compliant pigments with documented low-migration properties. Packaging converters in France and Germany now require certified supply chains for direct food contact, extending approval cycles to 24-36 months for novel extracts.
- Cosmetic Grade:Heavy metal-tested lakes and iron oxides meeting FDA and Health Canada specifications for eye and lip applications. Formulators in California and New Jersey are accelerating substitution away from talc-containing pigments.
- Industrial Grade:Standard pigments for coatings, plastics, and construction without migration or toxicity certification.
- Technical Grade:Signal and identification colorants for oilfield, agricultural, and safety applications.
Industrial Grade leads by volume. Food Grade shows the steepest expansion trajectory as clean-label mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Colorant trade flows reveal a widening deficit in Western markets against surging export capacity in South and East Asia. Import dependency for food-grade and textile-grade formulations is reshaping procurement geography as regional regulatory divergence accelerates.
United States
FDA color additive petitions for novel natural extracts now average 24-month review cycles, compressing launch timelines for beverage formulators. The EPA monitors titanium dioxide processing emissions under TSCA Section 5. Ohio plastics compounders contract directly with pigment houses for automotive interior masterbatches above 500 metric tons annually.
Germany
EU 10/2011 migration limits for food-contact materials now mandate certified low-migration pigments from converters in Bavaria and North Rhine-Westphalia. The CSRD requires Scope 3 carbon disclosure from pigment suppliers serving Unilever and Nestlé procurement teams. BASF SE leverages its integrated Ludwigshafen complex to serve pharmaceutical packaging accounts with certified formulations.
India
FSSAI clean-label mandates are accelerating synthetic-to-natural procurement shifts in Maharashtra and Gujarat beverage plants. Tirupur and Surat textile clusters expand reactive dye offtake as Bangladesh garment orders shift to Indian mills with integrated finishing capacity. The PLI scheme for specialty chemicals draws fermentation-platform investment toward microbial-derived carotenoids.
China
GB standards for food-contact pigments are tightening heavy metal thresholds in parallel with REACH alignment efforts. Ilmenite processing capacity clusters in Shandong and Jiangsu expose pigment houses to export duty fluctuations. Domestic automotive coatings demand sustains azo dye and phthalocyanine pigment volumes despite margin compression.
Brazil
ANVISA regulations for color additives in processed foods are converging with FDA specifications, easing multi-jurisdictional formulation for multinational CPG accounts. São Paulo beverage formulators adopt encapsulated natural colorants for acidic soft drink matrices. Local procurement is displacing finished formulation imports from Argentine suppliers.
Colorants Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers and geographic coverage. The market structure bifurcates between integrated chemical conglomerates with fermentation platforms and focused pigment houses serving narrow compliance segments. Three archetypes dominate: diversified chemical majors with food-grade certification assets, specialty masterbatch formulators with EU 10/2011 compliance capabilities, and regional distributors absorbing working capital for mid-volume compounders. Competitive moves concentrate on backward integration into fermentation feedstocks and direct procurement platform development to bypass distributor margins.
Within the diversified chemical tier, BASF SE anchors integrated pigment and dye production serving multi-jurisdictional pharmaceutical and food packaging accounts. Clariant occupies a position in specialty masterbatch formulations with documented EU food-contact compliance. Sun Chemical Corporation exemplifies narrow-segment concentration in flexible packaging inks where color consistency commands premium positioning. These three represent the certification-heavy end of competitive positioning where regulatory documentation substitutes for price competition.
| Leading Market Players |
|---|
| BASF SE |
| Clariant |
| DIC Corporation |
| LANXESS |
| DuPont |
| Huntsman Corporation |
| Cabot Corporation |
| Sun Chemical Corporation |
| ADM |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between German automotive tier suppliers and pigment houses lock in multi-year price visibility while securing dedicated masterbatch capacity above 500 metric tons annually. These arrangements concentrate pricing power with integrated producers possessing EU 10/2011 certification assets, leaving spot-market buyers exposed to naphthalene and aniline feedstock volatility.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification grade and volume scale drive price differentiation, with FDA-certified food-grade pigments commanding 3-5x premiums over industrial-grade alternatives. Cost compression in azo dye tiers is intensifying because petroleum-derived intermediate volatility compresses margin predictability. Mid-volume plastics compounders in Ohio and Bavaria exhibit highest price sensitivity, while pharmaceutical packaging accounts demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Ilmenite processing capacity clusters in Shandong and Jiangsu provinces expose pigment houses to export duty fluctuations and shipping bottlenecks. Titanium dioxide feedstock draws from Chinese and Australian mineral processing operations, while aniline and naphthalene intermediates rest on petrochemical complexes in Germany and the United States. Single-source vulnerability concentrates in microbial fermentation platforms for carotenoid production. Distribution runs through direct procurement platforms that disintermediate regional distributors for standard pigment grades above volume thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label mandates from FSSAI and EFSA lake pigment restrictions are accelerating early-cycle penetration of fermentation-derived alternatives, creating expansion headroom before saturation dynamics emerge.
For Market Incumbents: Shield certified low-migration product portfolios by extending EU 10/2011 compliance documentation to novel natural extracts, countering dual certification lag that stretches approval cycles to 24-36 months. Deepen backward integration into sugar feedstock fermentation platforms to secure cost parity with synthetic alternatives in beverage applications. For New Entrants and Emerging Players: FDA color additive petition fast-tracks for encapsulated natural colorants open procurement channels with São Paulo beverage formulators seeking acidic matrix stability. White-space concentrates in Indonesian processed food localization, where instant noodle manufacturers seek reduced import duty exposure. Lead with technical service partnerships that compress reformulation cycles from 18 months to 6 months for seasonal launches. For Investors and Strategic Acquirers: Capital is best deployed toward specialty masterbatch formulators possessing documented EU food-contact compliance and segregated production protocols. Long-term viability hinges on regulatory disclosure capabilities aligned with CSRD Scope 3 carbon accounting requirements. Monitor EFSA re-evaluation timelines for lake pigments as inflection indicators for synthetic-to-natural substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstocks | Captures margin compression from sugar-derived carotenoid cost parity achievements in beverage segments. |
| EU 10/2011 Certification Investment | Locks in multi-year supply agreements with Unilever and Nestlé procurement teams requiring documented low-migration properties. |
| Direct Procurement Platform Development | Bypasses distributor margins for automotive interior masterbatch volumes above 500 metric tons annually in Ohio and Bavaria. |
| Encapsulation Technology Scale-Up | Extends natural colorant viability through pasteurization for Mexican and Brazilian soft drink formulators. |
| Segregated Production Line Expansion | Doubles cleanroom capex but captures premium tier demand from facilities producing both food-grade and industrial pigments. |
Methodological Framework
Initial hypotheses were tested against primary input from pigment plant managers, procurement leads at downstream food and beverage processors, distribution channel partners, and technical R&D directors, then refined through secondary validation. Customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical conglomerates, and FDA color additive petition databases provided triangulation anchors. Bottom-up volume builds across grade tiers and end-use industries were cross-checked against top-down market sizing from production capacity assessments.
Variance decomposition across the projection horizon isolates drivers by product type, application, certification grade, and regional production hub. CAGRs were derived from segment-level growth trajectories weighted by volume contribution. Forecast inputs incorporated fermentation platform scale-up curves, REACH Annex XVII heavy metal threshold tightening schedules, and textile cluster capacity expansion timelines in Tirupur and Surat.
Decision-makers should treat outputs as directional under assumptions of sustained clean-label regulatory momentum and stable petrochemical feedstock availability; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as EFSA lake pigment re-evaluation outcomes and India PLI scheme disbursement patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Metallic Pigments Market
Dyes and Pigments
Ultramarine Pigments Market
Dyes and Pigments
Global Paper Dyes Market
Dyes and Pigments
Photoluminescent Paints Market
Dyes and Pigments
High Performance Pigments Market
Dyes and Pigments
Europe Hair Colorants Market
Dyes and Pigments
North America Hair Colorants Market
Dyes and Pigments
Bismuth Vanadate Pigment Market
Dyes and Pigments
Plastic Color Concentrates Market
Dyes and Pigments
Phthalocyanine Pigments Market
Dyes and Pigments
Reactive Dyes Market
Dyes and Pigments
Pearlescent Pigments Market
Dyes and Pigments
Oil-Dispersible Colors Market
Dyes and Pigments
Lithol Rubine BK Market
Dyes and Pigments
Phthalocyanine Blue Market
Dyes and Pigments
Organic Pigment Dispersions Market