
 Acrylic Colors Market | 2026-2036
Acrylic Colors Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylic Colors Market Outlook
Specialized polymer chemists and color formulation technicians is rotating toward Asia-Pacific production hubs, creating localized talent shortages in traditional European manufacturing centers. Golden Artist Colors leverages its vertically integrated New York facility to sustain premium pigment milling capabilities. Liquitex anchors North American distribution through controlled specialty retail partnerships. Winsor & Newton competes on heritage brand positioning across European atelier supply channels.
Acrylic colors are water-dispersible pigment suspensions in acrylic polymer emulsion, typically formulated with 30-50% solids content and engineered for flexibility, lightfastness, and adhesion across porous and non-porous substrates. Heavy body acrylics dominate professional studio consumption due to their high pigment load and impasto retention, while fluid acrylics occupy the fastest-expanding segment among pour-art practitioners and mural specialists. Educational institutions represent a mature, price-sensitive channel where batch-size procurement and safety certification drive supplier selection.
EPA oversight governs VOC emissions in U.S.-manufactured acrylic coatings, while REACH mandates full substance disclosure across EU supply chains, elevating compliance costs for imported formulations. ISO 787 standards for pigment testing provide baseline quality benchmarks that professional-grade suppliers must satisfy for institutional and commercial contracts. Stakeholders should monitor evolving chemical registration requirements in target export markets before committing to capacity expansion or reformulation investments.
Market Dynamics
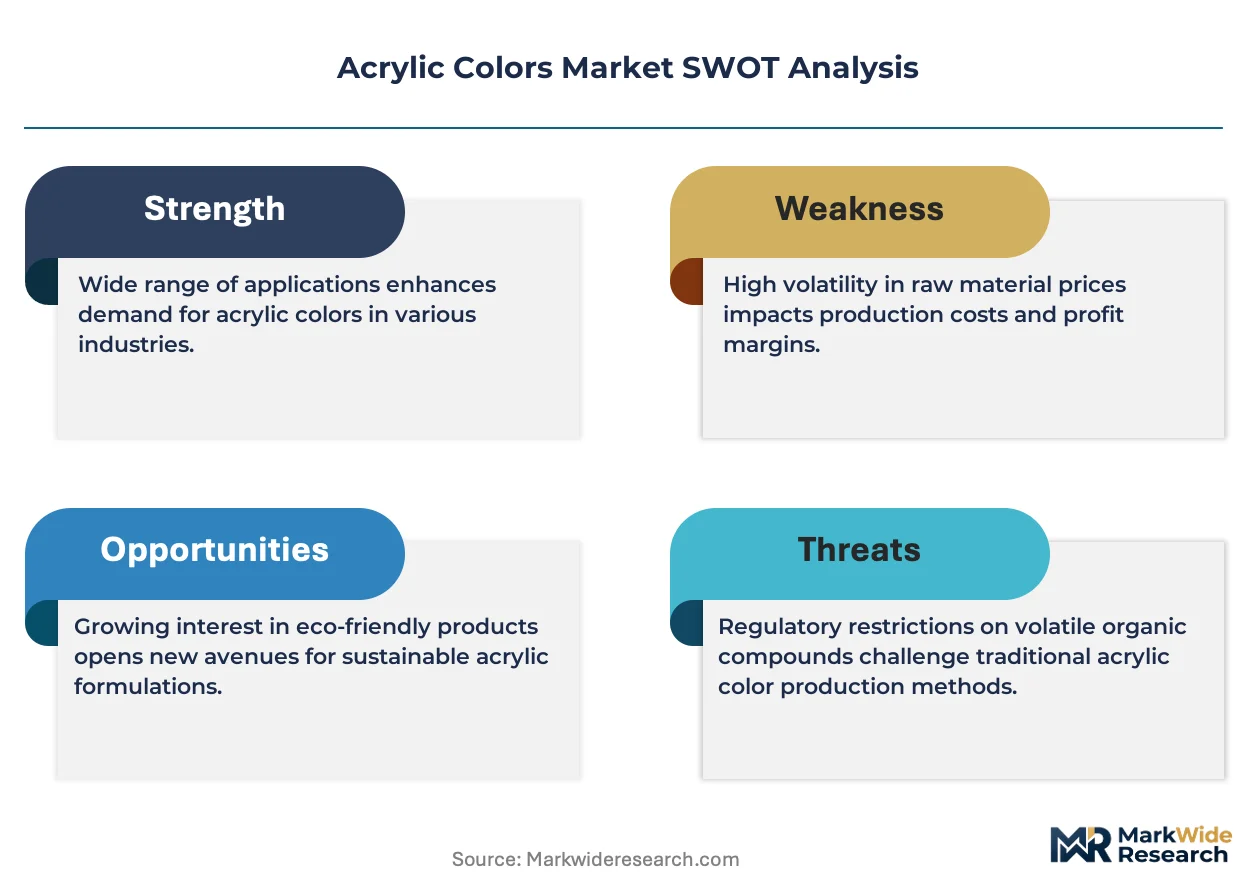
REACH substance disclosure mandates and EPA VOC thresholds are forcing simultaneous reformulation across European and North American production facilities, compressing margin structures while elevating technical barriers to import competition.
Growth Catalysts
- Archival-grade pigment systems:Museums and conservation studios in Germany and Italy are mandating ASTM D4303 lightfastness ratings for permanent collections, pulling premium heavy-body formulations into institutional procurement pipelines.
- Pour-art technique proliferation:Fluid acrylic viscosity grades are capturing mural specialists and decorative finishers seeking seamless color-field applications without brushmark retention.
- REACH Article 33 supply chain transparency:Full pigment provenance documentation is becoming a contractual requirement for EU educational tenders, advantaging compliant domestic mills over import-dependent distributors.
Market Restraints
- Titanium dioxide feedstock volatility:Rutile ore processing concentration in China creates input cost instability for opacity-critical white bases and tinting systems.
- Propylene polymer emulsion supply concentration:Acrylic binder manufacturing clusters in the US Gulf Coast and Rotterdam-Antwerp corridor expose formulated color producers to regional logistics disruptions.
- Waterborne alkyd substitution:Improved hybrid alkyd dispersions are capturing trim and furniture refinishing applications previously dominated by fast-drying acrylic enamels.
Strategic Opportunities
- India institutional art education expansion:State-funded fine arts academies under the Ministry of Culture are modernizing studio infrastructure, creating import substitution openings for localized milling operations.
- Digital color-matching kiosk networks:Hardware-software integration at specialty retail is collapsing the specification cycle between artist preference and SKU fulfillment.
- EU Green Deal bio-based binder incentives:R&D tax credits for polymer feedstock substitution are accelerating pilot-scale production of plant-derived acrylic alternatives.
Industry Challenges
- Specialized milling technician scarcity:Pigment dispersion expertise is migrating to Asia-Pacific production hubs, depleting European training pipelines for sub-micron particle size control.
- Multi-jurisdiction certification parallelism:Simultaneous EPA, REACH, and ISO 787 compliance testing extends product launch timelines by 8-14 months for cross-border formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylic Colors Market |
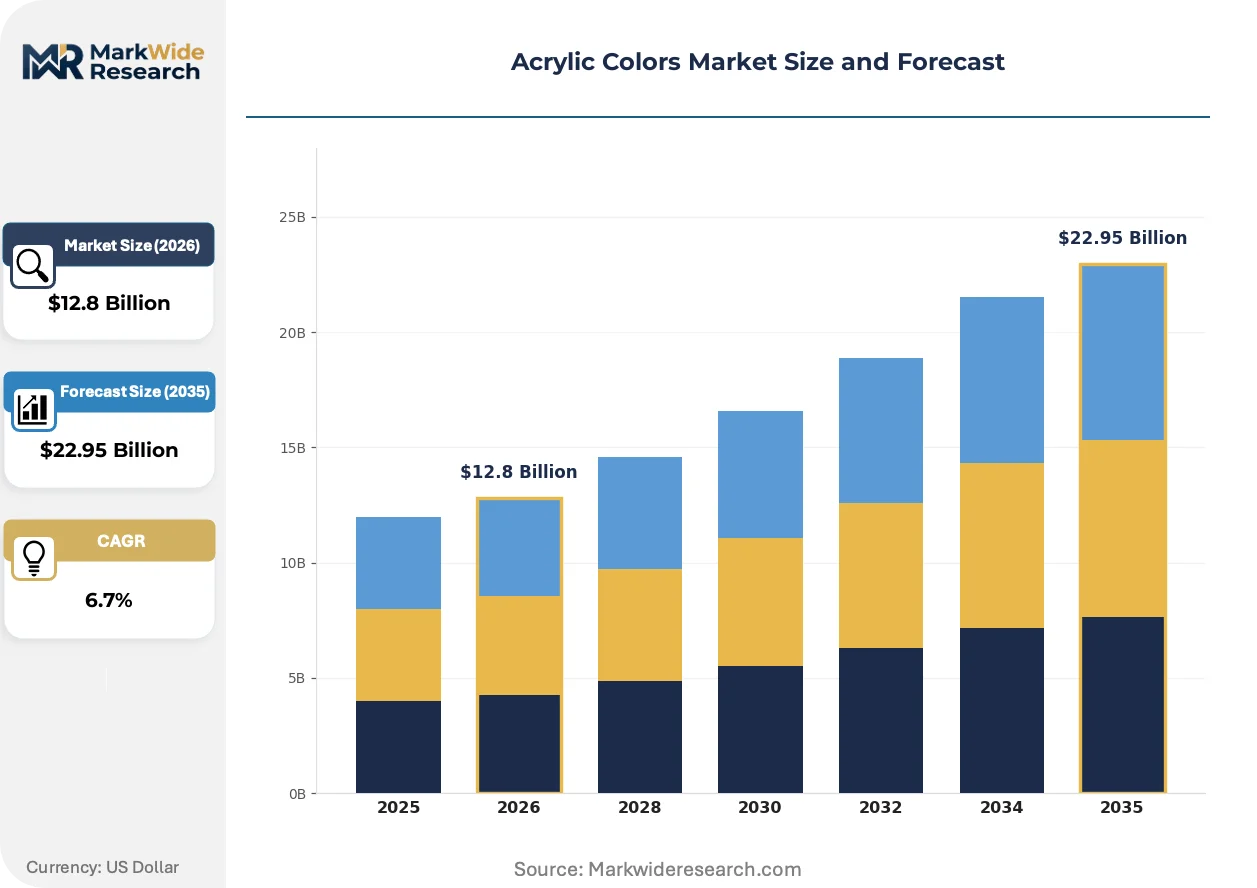
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artist Acrylics, Heavy Body Acrylics, Fluid Acrylics, Acrylic Gouache End User: Professional Artists, Hobbyists, Educational Institutions, Commercial Use Application: Painting, Crafting, Home Decor, Mural Art Batch Size: Small Packs, Medium Packs, Large Packs, Bulk Orders |
| Companies Covered | Golden Artist Colors, Liquitex, Winsor & Newton, Daler-Rowney, Royal Talens, Sennelier, Pebeo, Colart Group, AkzoNobel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylic Colors Market Strategic Shifts
Formulation science and color specification infrastructure are diverging along performance-versus-accessibility axes, with professional archival demands accelerating on one trajectory and hobbyist convenience requirements on another.
Interference and iridescent pigment technologies incorporating mica substrates and metal oxide layers are bifurcating the specialty effects segment. Automotive custom finishers and theatrical scenic designers are specifying these materials at 15-20% price premiums over conventional metallics. The technology is bifurcating supplier R&D budgets between commodity color matching and proprietary effect particle engineering.
EPA Method 24 VOC testing protocols are tightening enforcement granularity for architectural coatings sold through retail channels. Manufacturers must now submit batch-specific analytical data rather than formulation-range certifications. Small-batch artisan producers in California and New York face disproportionate compliance costs relative to high-volume competitors with captive testing laboratories.
Studio artists are consolidating pigment purchases through direct-to-manufacturer subscription programs, bypassing traditional distributor markups on consumables. This channel compression is most pronounced among professional painters in the US Pacific Northwest and UK metropolitan areas with established maker-space networks. Specialty retailers are responding with private-label fluid acrylic lines and exclusive heavy-body color ranges to defend foot traffic.
Acrylic Colors Market Segmentation
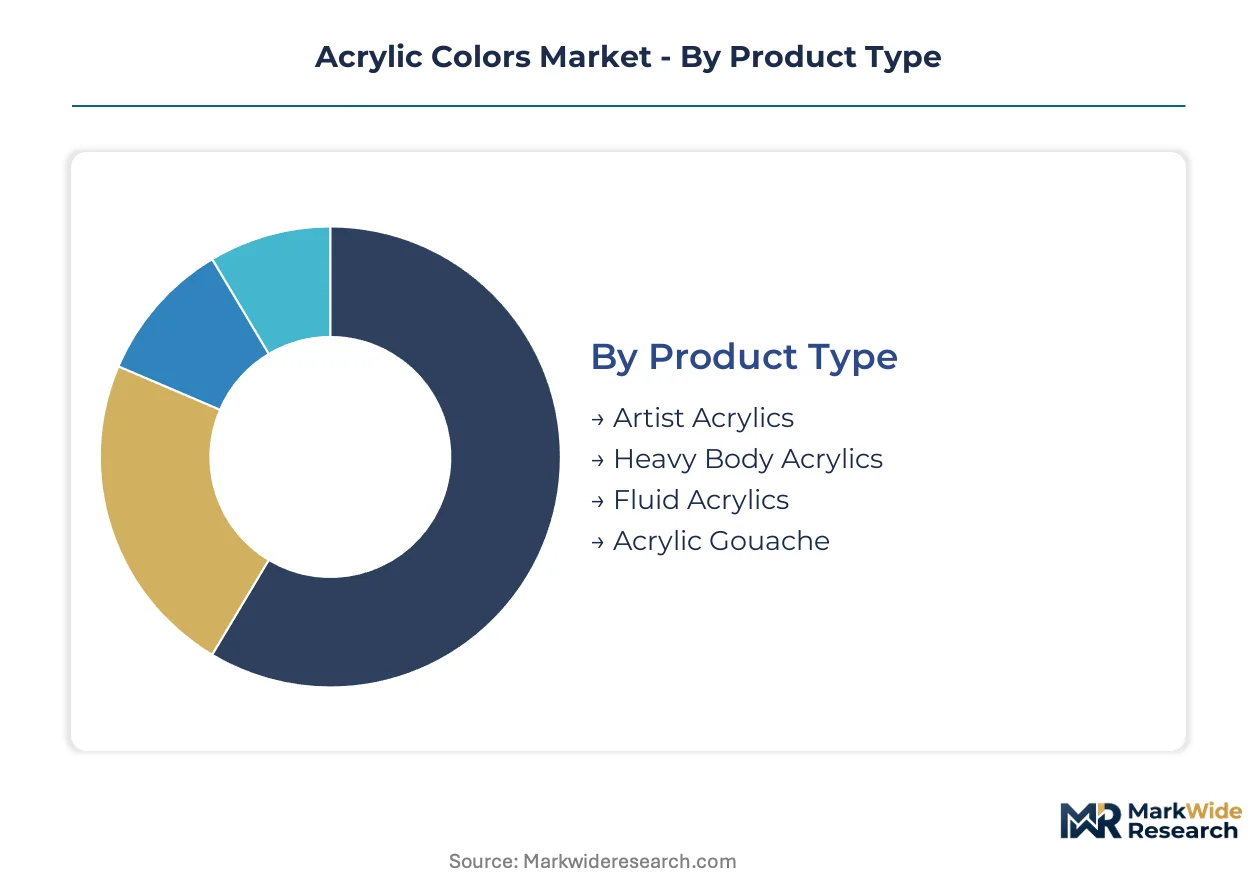
Acrylic colors flow through distinct procurement channels shaped by volume thresholds, certification requirements, and end-user sophistication. Each segment category carries specific margin implications and technical specifications that determine supplier positioning and channel strategy.
Product Type:
Specialty retailers stock heavy-body and fluid grades most densely, while educational distributors prioritize economy artist lines and bulk acrylic gouache for classroom budgets.
- Heavy Body Acrylics:These formulations carry 30-50% pigment load with rheology modifiers engineered for impasto retention and minimal color shift during drying. Demand concentrates in German atelier supply chains and Italian conservation studios where ASTM D4303 lightfastness ratings determine institutional procurement eligibility.
- Fluid Acrylics:Low-viscosity suspensions with 20-30% solids content enable pour-art techniques and seamless color-field applications without brushmark retention. Mural specialists in US Pacific Northwest metropolitan areas and UK maker-space networks are driving the steepest expansion trajectory for this grade.
- Artist Acrylics:General-purpose formulations balancing pigment concentration with workability for mixed-technique studio practice.
- Acrylic Gouache:Matte-finish, opaque variants formulated with added calcium carbonate for flat, velvety surfaces in illustration and design applications.
By volume, artist acrylics lead through educational procurement. By growth pace, fluid acrylics are ahead.
End User:
Margin structures diverge sharply across these tiers, with professional segments tolerating 40-60% price premiums for archival certification and hobbyist channels demanding private-label alternatives.
- Professional Artists:Studio practitioners specifying ASTM D4236 safety-labeled, ASTM D4303 lightfastness-rated formulations with full pigment disclosure documentation. Germany's museum conservation departments and Italy's fine art restoration workshops mandate these specifications for permanent collection work.
- Educational Institutions:K-12 and university art programs purchasing batch-size quantities under REACH Article 33 transparency requirements for EU tenders or EPA VOC compliance for US institutional contracts.
- Hobbyists:Price-sensitive consumers purchasing through mass-market craft retailers and direct-to-manufacturer subscription programs bypassing traditional distributor markups.
- Commercial Use:Theatrical scenic designers, automotive custom finishers, and decorative finishers sourcing interference pigments and metallic effects at 15-20% price premiums over conventional color ranges.
Educational institutions generate the highest absolute volume. Professional artists deliver the strongest margin contribution.
Application:
Substrate compatibility requirements and durability specifications determine whether formulations sell through specialty art supply, home improvement, or industrial coatings channels.
- Mural Art:Exterior-grade fluid acrylics with enhanced UV resistance and substrate adhesion for architectural surface applications. Germany's industrial coatings corridor and Rotterdam-Antwerp manufacturing clusters supply these formulations with ISO 787 pigment testing compliance.
- Painting:Canvas and panel-oriented heavy-body and artist grades dominating professional studio consumption and gallery-oriented retail.
- Crafting:Multi-surface compatible formulations for paper, fabric, and mixed-media applications through mass-market hobby channels.
- Home Decor:Decorative finish-grade products for furniture refinishing, facing substitution pressure from improved waterborne alkyd hybrid dispersions.
Painting applications retain the largest revenue base. Mural art is climbing the fastest as architectural color-field commissions expand.
Batch Size:
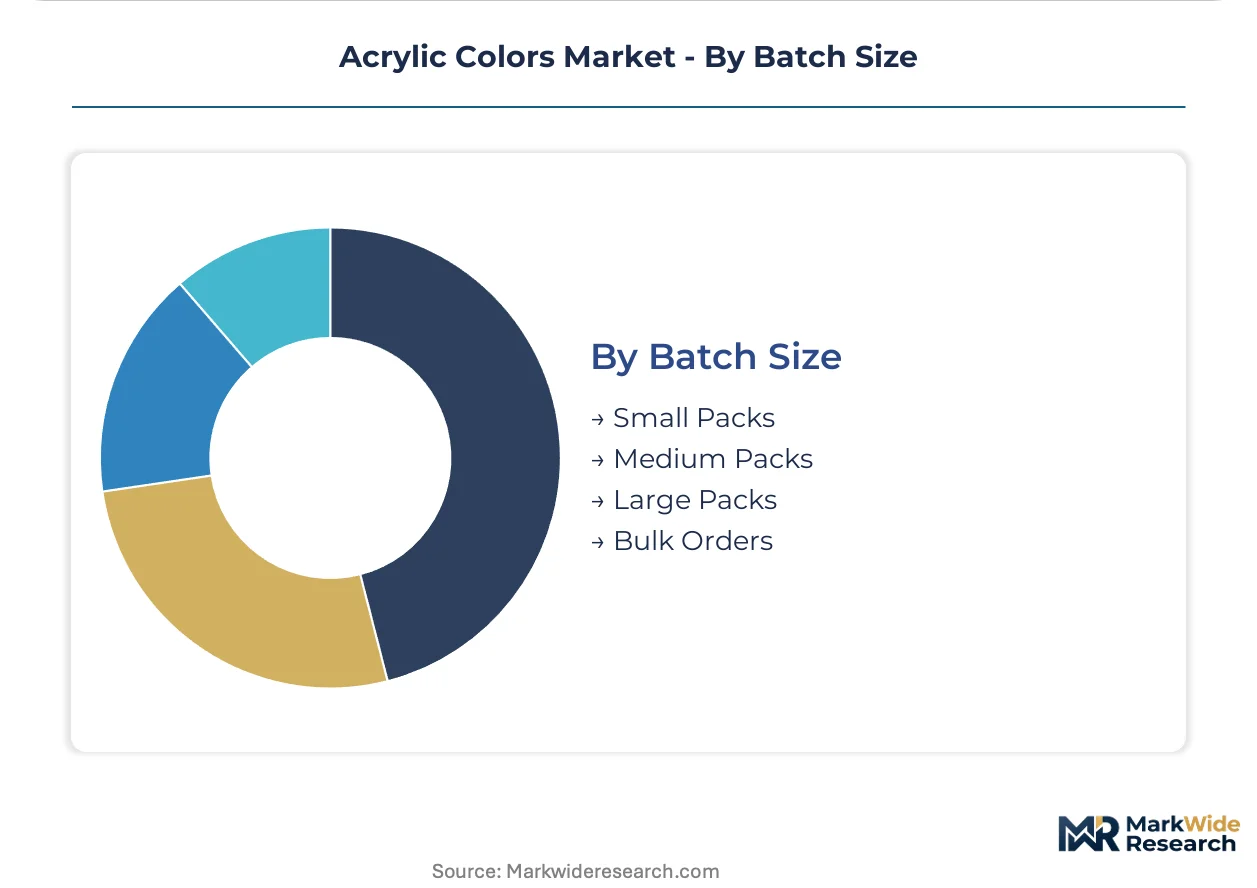
Packaging economics and inventory velocity separate artisan small-batch producers from high-volume manufacturers with captive testing laboratories for EPA Method 24 compliance.
- Bulk Orders:Institutional and commercial procurement of 20-liter containers and larger, requiring batch-specific analytical data under tightened EPA enforcement granularity for architectural coatings.
- Large Packs:500ml to 2-liter formats for professional studio consumption and educational bulk purchasing.
- Medium Packs:75ml to 200ml tubes and jars for individual professional and serious hobbyist purchase.
- Small Packs:20ml to 60ml introductory and travel formats, disproportionately burdening California and New York artisan producers with per-SKU compliance costs relative to high-volume competitors.
Medium packs dominate unit velocity. Bulk orders are gaining share fastest as institutional procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional artists in Germany and Italy specify archival-grade acrylic systems for conservation work, while hobbyist demand in the United States concentrates on fluid acrylics for pour-art techniques. This consumption-mix differential shapes supplier investment priorities across developed markets.
United States
Pour-art practitioners and mural specialists in the Pacific Northwest are driving fluid acrylic demand through maker-space networks and direct-to-manufacturer subscription programs. EPA Method 24 VOC testing protocols now require batch-specific analytical data for architectural coatings, elevating compliance costs for small-batch artisan producers in California and New York relative to high-volume competitors with captive laboratories. Golden Artist Colors maintains vertically integrated pigment milling capabilities at its New York facility to sustain premium production.
Germany
Museum conservation departments and industrial coatings formulators represent dual demand pillars, with ASTM D4303 lightfastness ratings mandatory for permanent collection procurement. REACH substance disclosure mandates under Article 33 require full pigment provenance documentation for educational tenders, advantaging compliant domestic mills. The industrial coatings corridor spanning Cologne-Düsseldorf supplies exterior-grade mural formulations with ISO 787 pigment testing compliance.
Italy
Fine art restoration workshops and atelier supply channels anchor professional-grade consumption, with heritage brand positioning determining competitive standing in conservation-studio procurement. EU Green Deal bio-based binder incentives are accelerating pilot-scale production of plant-derived acrylic alternatives in Emilia-Romagna manufacturing clusters. REACH compliance costs are compressing margin structures for import-dependent distributors serving the educational sector.
United Kingdom
Metropolitan maker-space networks and specialty retail partnerships are consolidating professional artist purchasing through digital color-matching kiosk infrastructure. REACH-aligned pigment disclosure requirements govern cross-border supply from EU manufacturing hubs, extending product launch timelines for reformulated lines. London-based conservation studios specify ASTM D4236 safety-labeled formulations for institutional contracts.
India
State-funded fine arts academies under the Ministry of Culture are modernizing studio infrastructure, creating import substitution openings for localized milling operations. BIS standards for pigment quality provide baseline benchmarks that domestic suppliers must satisfy to displace established import brands. Maharashtra and Gujarat industrial zones are attracting polymer emulsion manufacturing investment to serve regional educational procurement.
Acrylic Colors Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with vertical integration into pigment milling and captive binder production distinguishing the upper tier from formulation-dependent competitors. The middle tier comprises heritage-brand European houses and North American specialty manufacturers competing on archival certification and atelier channel relationships. Strategic archetypes include integrated pigment millers, heritage-brand conservation specialists, and fluid acrylic innovation-focused suppliers. Capacity expansion in Asia-Pacific production hubs and backward integration into titanium dioxide feedstock sourcing represent dominant competitive moves.
Among North American integrated manufacturers, Golden Artist Colors exemplifies the captive-milling archetype through its New York-based vertical production structure. Liquitex occupies a position within the fluid acrylic specialization tier, anchoring North American distribution through controlled specialty retail partnerships. Winsor & Newton represents the heritage-brand conservation specialist archetype, with its positioning across European atelier supply channels reflecting long-established institutional relationships. These three companies illustrate the competitive spectrum from manufacturing integration to brand heritage differentiation.
| Leading Market Players |
|---|
| Golden Artist Colors |
| Liquitex |
| Winsor & Newton |
| Daler-Rowney |
| Royal Talens |
| Sennelier |
| Pebeo |
| Colart Group |
| AkzoNobel |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty days of titanium dioxide inventory held by European mills determines margin resilience against Chinese rutile ore price swings, concentrating pricing power with integrated pigment producers while forcing formulation-dependent competitors toward spot-market exposure.
Pricing Analysis
Long-term offtake contracts dominate institutional procurement in Germany and Italy, where museum conservation departments mandate ASTM D4303 certification and full pigment disclosure under REACH Article 33. Three-tier pricing structure across premium archival, standard professional, and economy educational levels separates certified conservation-grade formulations from classroom bulk lines. Cost compression in the economy tier is intensifying because REACH compliance testing extends product launch timelines, elevating per-SKU burdens for small-batch producers. Educational institutions exhibit highest price sensitivity, while conservation studios tolerate substantial premiums for provenance documentation.
Supply Chain Analysis
China controls titanium dioxide feedstock processing, while the US Gulf Coast and Rotterdam-Antwerp corridor anchor acrylic binder manufacturing, creating geographic interdependence between opacity-critical inputs and emulsion production. Formulated color producers draw from concentrated rutile ore supply, propylene polymer feedstock, and specialty rheology modifier sources. Single-source vulnerability in Chinese titanium dioxide creates input cost instability during logistics disruptions. Distribution runs through specialty art supply retailers for professional grades and educational distributors for institutional bulk procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through REACH and EPA compliance creates substantial barriers against import competition and new entrant displacement.
For Market Incumbents: Secure captive titanium dioxide sourcing through backward integration or long-term offtake agreements with rutile processors, insulating margin structures against Chinese feedstock volatility. Deepen certification investment in ASTM D4303 and ISO 787 testing infrastructure to defend institutional procurement relationships against emerging Asia-Pacific millers. For New Entrants and Emerging Players: Differentiate on bio-based binder innovation under EU Green Deal incentives, targeting Italy's Emilia-Romagna manufacturing clusters where pilot-scale plant-derived alternatives command R&D tax credits. Pursue direct-to-manufacturer subscription channels in US Pacific Northwest maker-space networks, bypassing traditional distributor markups that compress pricing flexibility. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specialized milling technician scarcity and multi-jurisdiction certification parallelism favor scaled integrated producers over fragmented formulation houses. Target pigment dispersion specialists with captive sub-micron particle control capabilities. Watch for REACH enforcement granularity tightening as the inflection signal accelerating compliance cost divergence between integrated and import-dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Dioxide | Secures opacity-critical feedstock against Chinese rutile ore price volatility for European mills. |
| Bio-Based Binder Pilot Production | Captures EU Green Deal R&D tax credits in Italy's Emilia-Romagna manufacturing corridor. |
| Digital Color-Matching Kiosk Deployment | Collapses specification cycles between artist preference and SKU fulfillment at UK specialty retail. |
| Localized Milling Capacity in India | Displaces established import brands serving Maharashtra and Gujarat educational procurement expansion. |
| REACH Article 33 Compliance Infrastructure | Advantages domestic EU mills over import-dependent distributors in educational tender competition. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from coatings sector participants, and European Chemicals Agency registration databases. Interviews with polymer chemists, color formulation technicians, museum conservation procurement officers, and specialty art supply distributors informed demand-side dynamics. Bottom-up volume modeling triangulated against top-down value estimates derived from production capacity disclosures across Germany's industrial coatings corridor and New York State manufacturing facilities.
Segmentation dimensions modeled include product viscosity grade, end-user sophistication tier, application substrate compatibility, and batch-size procurement channel across the projection horizon. CAGRs were derived from trend extrapolation of institutional procurement volumes, hobbyist channel velocity, and commercial effects pigment adoption. Forecast inputs incorporated REACH enforcement trajectory, EPA Method 24 testing protocol evolution, and titanium dioxide feedstock concentration dynamics.
Material uncertainties — regulatory enforcement granularity shifts, propylene emulsion supply disruptions, and bio-based binder scale-up viability — sit outside the modeled envelope. Forecasts reflect assumptions regarding certification timeline stability and pigment provenance documentation standardization. Recalibration cycles align with material shifts in EU chemical registration requirements and US architectural coatings enforcement protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Asia-Pacific Pigments Market
Dyes and Pigments
Global Organic Pigments Market
Dyes and Pigments
France Aluminium Pigments Market
Dyes and Pigments
Global Cosmetic Pigments Market
Dyes and Pigments
Mulch Colorants Market
Dyes and Pigments
Classic Organic Pigments Market
Dyes and Pigments
Global Paper Dyes Market
Dyes and Pigments
Plastic Pigments Market
Dyes and Pigments
Brilliant Black BN Colors Market
Dyes and Pigments
Special Effect Pigments Market
Dyes and Pigments
Azo Pigments Market
Dyes and Pigments
Synthetic Dyes Market
Dyes and Pigments
Material Color Matching Booth Market
Dyes and Pigments
Photoluminescent Paints Market
Dyes and Pigments
Micronized Color Powder Market
Dyes and Pigments
Organic Lake Pigments Market