
 Global Organic Pigments Market | 2026-2036
Global Organic Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Global Organic Pigments Market Outlook
Specialty chemical distribution is tilting toward consolidated technical-service providers who bundle formulation support with pigment supply. BASF SE leverages its integrated colorant R&D hubs in Germany and Asia to sustain premium positioning across coatings and plastics accounts. Sudarshan Chemical Industries Limited anchors its competitive stance through backward integration into intermediates at its Indian manufacturing complexes. DIC Corporation competes via deep technical relationships with Japanese ink and display material customers.
Organic pigments are synthetic colorants derived from carbon-based chromophores, typically manufactured through diazotization, coupling, or phthalocyanine ring-closure reactions, with particle sizes engineered between 0.05 and 0.5 micrometers for optimal dispersion and tinctorial strength. These compounds deliver high color intensity, transparency, and lightfastness for surface coloring across industrial and consumer applications. Powder pigments dominate volume shipments due to their compatibility with diverse resin systems and lower logistics costs, while liquid pigments and concentrates are gaining share in automated dosing systems where dust-free handling and batch consistency command margin premiums. The coatings application segment leads value generation, though inks and plastics are expanding faster as packaging sustainability requirements and automotive interior specifications intensify.
REACH registration requirements and the EU Green Deal framework restrict certain azo pigment precursors and mandate hazard communication, compelling reformulation investments across European supply chains. The EPA and OSHA in the United States enforce parallel workplace exposure limits and toxic substance reporting that shape product development priorities for multinational suppliers. China SAMR administers national standards for pigment purity and labeling that influence export eligibility and domestic market access. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and maintain formulation agility across regional specifications.
Market Dynamics
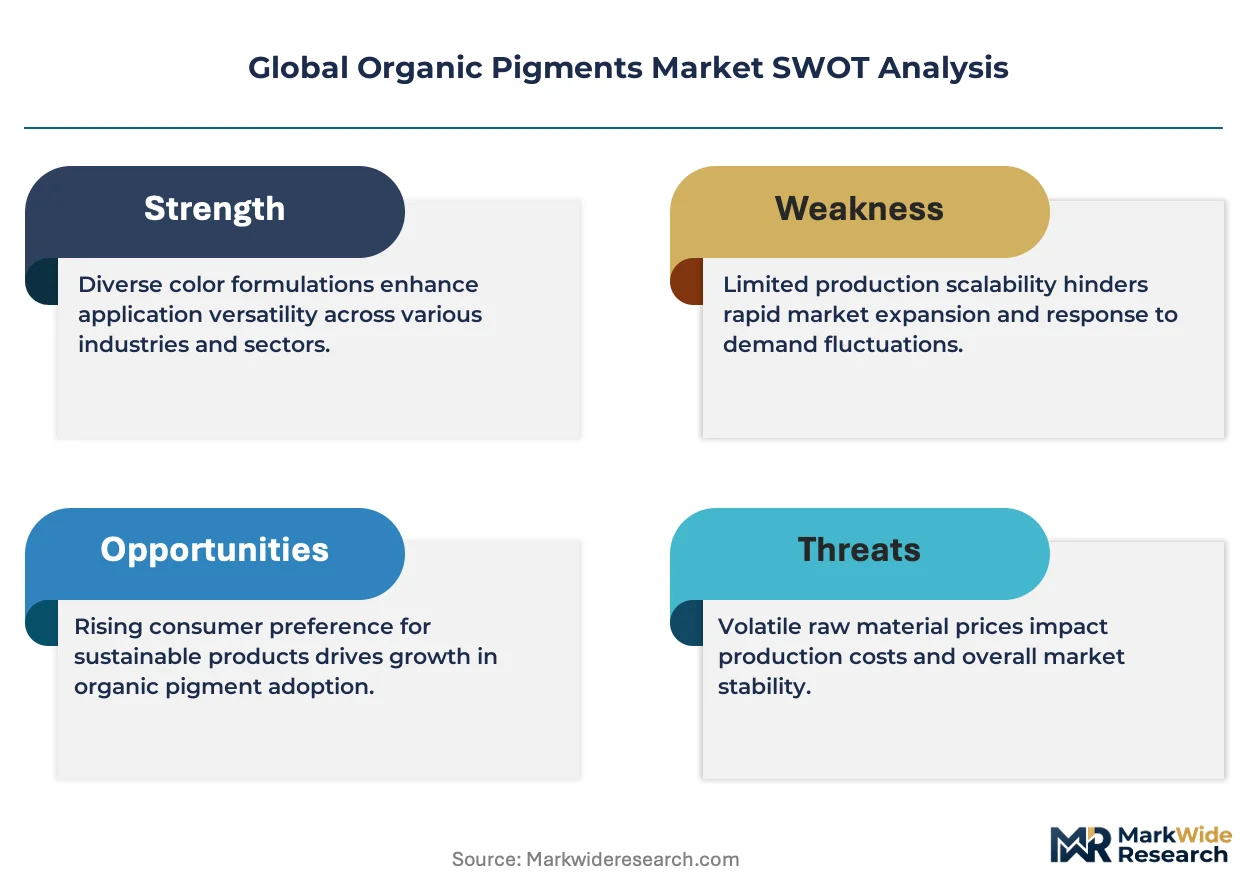
Automotive coatings manufacturers are systematically replacing heavy metal-based colorants with high-performance organic pigments as REACH and EPA restrictions tighten, while Chinese production capacity for azo and phthalocyanine compounds reshapes global supply availability.
Growth Catalysts
- REACH Phase-In Restrictions:ECHA's ongoing substance evaluations are accelerating reformulation across European coatings supply chains, pulling demand toward compliant organic alternatives.
- Automotive Interior Specifications:Cabin air quality standards and touch-surface regulations are mandating low-VOC, heavy-metal-free colorants in dashboard and trim applications.
- Chinese Domestic Capacity Expansion:Jiangsu and Zhejiang province manufacturing clusters are scaling phthalocyanine blue and green output, compressing import dependency for Asian processors.
Market Restraints
- Crude Oil Derivative Volatility:Naphtha and benzene feedstock costs for diazotization intermediates fluctuate with petrochemical pricing, squeezing margin predictability for pigment manufacturers.
- Intermediate Supply Concentration:Chinese producers control roughly two-thirds of global 3,3'-dichlorobenzidine and other key coupling component output, creating single-source vulnerability.
- Inorganic Pigment Substitution in High-Temperature Applications:Ceramic and complex inorganic colorants retain performance advantages in powder coatings above 280°C, capping organic penetration in industrial bake finishes.
Strategic Opportunities
- Brazilian Packaging Ink Growth:ANVISA's evolving food-contact material standards are opening specification windows for high-purity azo pigments in flexible packaging gravure applications.
- Digital Printing Convergence:UV-curable inkjet formulations combining organic pigments with oligomer carriers are displacing solvent systems in narrow-web label production.
- EU Green Deal Public Procurement:CSRD-aligned sustainability criteria in government and institutional purchasing are creating preferential channels for bio-based and recycled-content colorant suppliers.
Industry Challenges
- Colorimetric Calibration Talent Scarcity:Formulation chemists capable of matching legacy lead chromate and cadmium shades in high-chroma organic alternatives command premium compensation and extended recruitment timelines.
- Multi-Jurisdiction Registration Burden:Maintaining active dossiers under REACH, EPA TSCA, and China MEE new chemical notification requirements demands dedicated regulatory affairs capacity that mid-size pigment houses struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Organic Pigments Market |
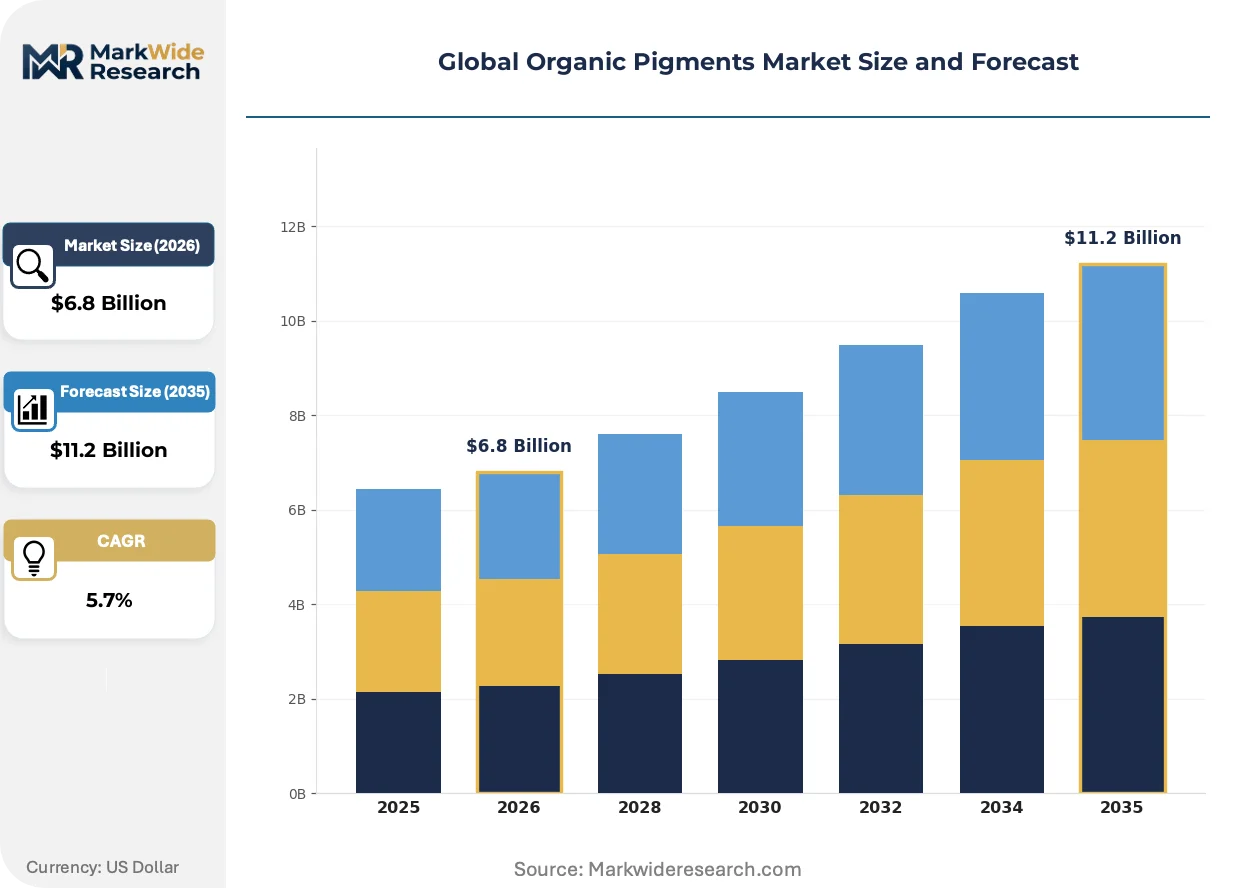
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder Pigments, Liquid Pigments, Concentrates, Pastes Application: Coatings, Plastics, Inks, Textiles End User: Automotive, Construction, Consumer Goods, Art Supplies Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | DIC Corporation, Sudarshan Chemical Industries Limited, BASF SE, Heubach GmbH, Clariant AG, Dainichiseika Color & Chemicals Mfg. Co., Ltd., Artience Co., Ltd., Atul Ltd., Anshan Hifichem Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Organic Pigments Market Strategic Shifts
Computational chemistry and particle engineering are compressing development cycles for novel chromophores, while regulatory data-sharing initiatives and digital color-matching platforms redistribute competitive advantage across the value chain.
Encapsulated pigment technologies employing silica and polymer shell architectures are virtualizing surface modification workflows that previously required dedicated milling and dispersion equipment. Tier-one automotive coatings suppliers in Germany and Japan are adopting these pre-dispersed concentrates to compress batch-to-batch variability. The technology is virtualizing capital investment patterns, enabling smaller regional compounders to specification-match multinational pigment houses without captive grinding infrastructure.
EPA's expanded reporting requirements under TSCA Section 8(a) for per- and polyfluoroalkyl substances are capturing certain fluorinated pigment dispersants and processing aids within compliance scope. Coatings formulators must now document unintentional PFAS content in organic pigment supply chains or certify absence through analytical testing. Waterborne industrial coatings segments in the United States are responding by accelerating qualification of fluorine-free wetting agents and grinding resin alternatives.
Specification-driven procurement is consolidating buyer power among multinational coatings and plastics compounders, compressing approved vendor lists and extending qualification timelines. Technical service capabilities and color-matching responsiveness are displacing price as the primary selection criterion in North American and European accounts. This concentration is most visible in automotive OEM tier supply chains, where single-source pigment approvals now span five-to-seven-year contract horizons.
Global Organic Pigments Market Segmentation
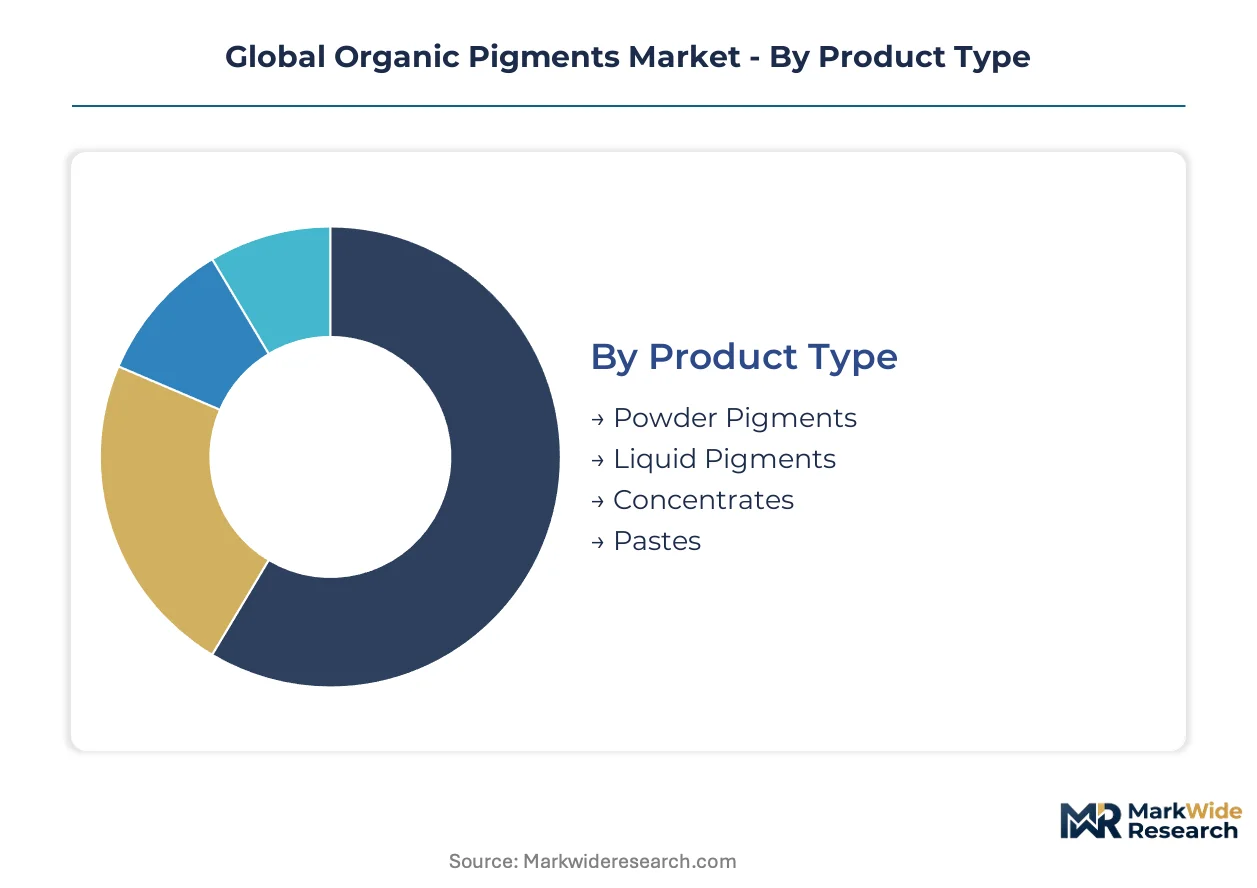
Organic pigment segmentation reflects divergent technical requirements across formulation workflows. Powder formats dominate established coatings and plastics processing, while liquid and concentrate formats gain traction in automated production environments. Distribution channel selection increasingly correlates with technical service intensity rather than commodity logistics alone.
Product Type:
Mature powder formats coexist with emerging liquid and concentrate systems engineered for dust-free handling and dosing precision.
- Powder Pigments:Dry particulate colorants with particle sizes engineered between 0.05 and 0.5 micrometers for optimal dispersion in solventborne and powder coatings. Automotive OEM coatings in Germany and Japan specify powder grades for batch consistency in metallic and solid-color basecoats. REACH registration requirements for powder handling are accelerating investment in containment systems at European compounding facilities.
- Liquid Pigments:Pre-dispersed colorants in carrier solvents or water, eliminating dust exposure and enabling pump-fed dosing in automated production lines. Flexible packaging ink manufacturers in Brazil are adopting liquid azo pigments to meet ANVISA food-contact migration limits through controlled particle stabilization. EPA workplace exposure regulations for respirable dust are pulling North American converters toward liquid alternatives.
- Concentrates:High-strength pigment preparations with polymer-specific carriers for direct let-down in thermoplastic processing. Injection molders in China's Guangdong province specify phthalocyanine blue concentrates for polypropylene automotive interior components.
- Pastes:Semi-liquid dispersions with thickened rheology for manual or low-shear incorporation in art materials and small-batch industrial applications. European art supply manufacturers source paste formats for heavy-body acrylic and oil paint formulations.
Powder pigments retain volume leadership; liquid pigments hold the steepest expansion curve.
Application:
Application segmentation tracks divergent performance specifications across surface coloring industries, with coatings commanding value premiums and packaging inks accelerating fastest.
- Coatings:Surface protection and decorative systems spanning automotive OEM, refinish, industrial, and architectural end-uses. Japanese automotive coatings suppliers specify high-performance organic pigments for clearcoat-compatible metallic finishes. ECHA substance evaluations under REACH are systematically disqualifying lead chromate and cadmium alternatives, pulling reformulation toward compliant organic chemistries.
- Plastics:Mass coloration of thermoplastic and thermoset resins for consumer goods, automotive interiors, and construction products. Dashboard and trim manufacturers in the United States face cabin air quality standards mandating low-VOC, heavy-metal-free colorants from EPA-registered suppliers.
- Inks:Printing systems spanning publication gravure, flexographic packaging, and digital inkjet technologies. Narrow-web label converters are adopting UV-curable inkjet formulations combining organic pigments with oligomer carriers.
- Textiles:Fiber and fabric coloration through printing, exhaust, and continuous dyeing processes. Technical textile producers in India specify vat and disperse organic pigments for automotive seating and industrial filter applications.
Coatings command value concentration; inks are climbing the fastest on packaging sustainability specifications.
End User:
End user segmentation reveals divergent procurement patterns, with automotive and construction buyers consolidating vendor lists while consumer goods and art supply channels fragment across specialty distributors.
- Automotive:OEM and refinish coatings, interior plastics, and textile applications subject to stringent color matching and durability specifications. German tier-one suppliers maintain single-source pigment approvals spanning five-to-seven-year contract horizons.
- Construction:Architectural coatings, concrete colorants, and building material applications requiring weatherfastness and alkali resistance. Chinese infrastructure projects specify phthalocyanine blue and green for exterior durability in coastal environments.
- Consumer Goods:Packaging, appliances, and durable products where color consistency supports brand recognition. Brazilian flexible packaging gravure applications are opening specification windows for high-purity azo pigments under evolving ANVISA standards.
- Art Supplies:Fine art, craft, and educational materials prioritizing lightfastness and color intensity over cost optimization. European manufacturers source from REACH-registered suppliers to maintain export eligibility.
Automotive retains procurement concentration; consumer goods channels are gaining share fastest on packaging specification evolution.
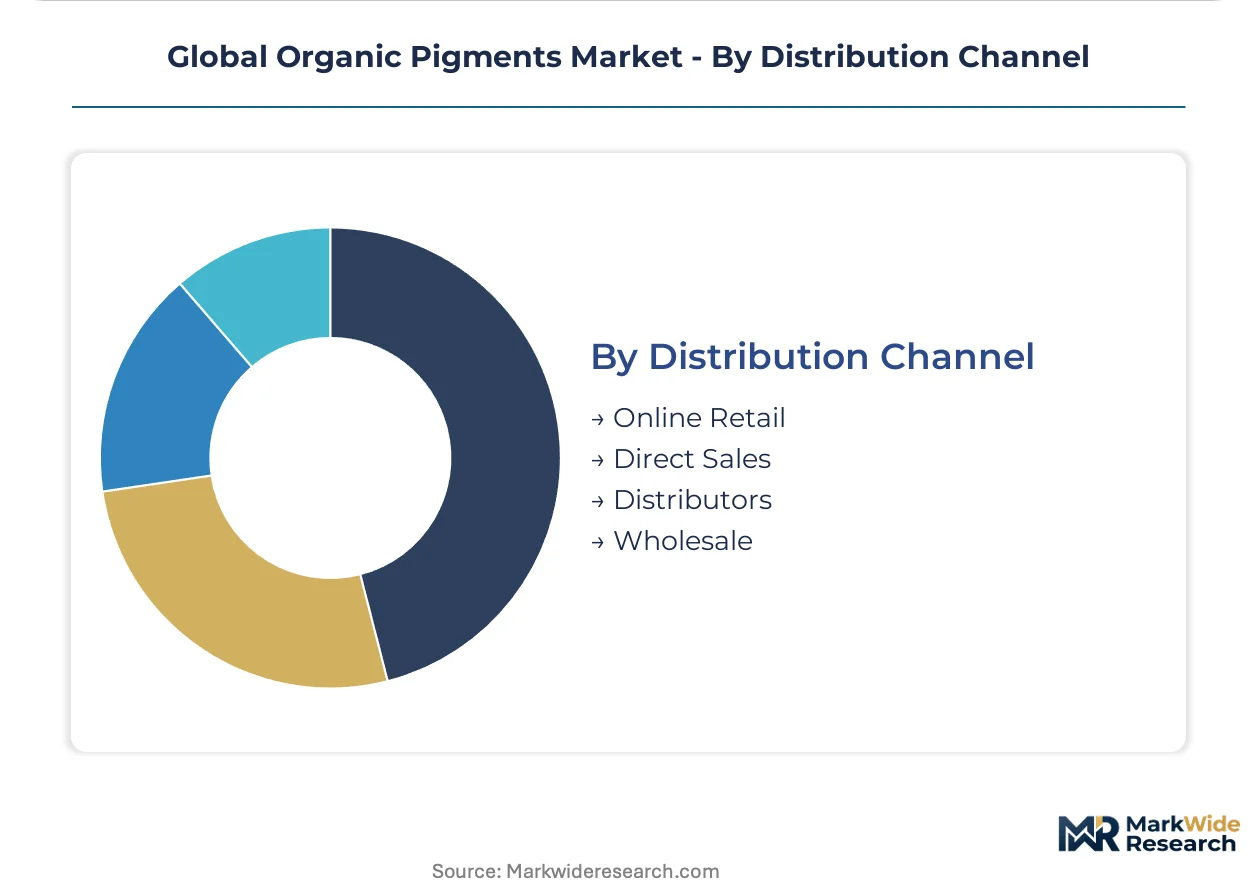
Distribution Channel:
Channel segmentation tracks the unbundling of commodity logistics from technical service, with direct and distributor relationships consolidating around formulation support capabilities.
- Direct Sales:Manufacturer-to-processor relationships for high-volume accounts requiring colorimetric calibration and regulatory documentation. Multinational coatings compounders in North America and Europe are compressing approved vendor lists and extending qualification timelines.
- Distributors:Technical-service providers bundling formulation support with pigment supply and inventory management. Specialty chemical distribution is tilting toward consolidated providers with captive application laboratories.
- Online Retail:E-commerce platforms for small-volume orders, standard grades, and rapid sampling. Art supply and small-batch industrial buyers in the United States source standard powder pigments through digital channels.
- Wholesale:Volume aggregation for commodity grades serving regional compounders and toll processors. Chinese domestic production capacity for azo and phthalocyanine pigments flows through wholesale networks to Asian processors.
Direct sales retain margin leadership; distributor relationships are expanding fastest on technical service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward German coatings compounders while Chinese phthalocyanine producers compress margins across Asian supply chains. This asymmetry reshapes procurement geography as REACH compliance costs and feedstock volatility diverge.
China
Jiangsu and Zhejiang province clusters scale phthalocyanine blue and green output for domestic processors and export markets. SAMR national standards for pigment purity and labeling influence eligibility for both domestic sales and overseas shipments. The Yangtze River Delta manufacturing corridor concentrates diazotization capacity and coupling component production.
Germany
Automotive OEM coatings suppliers in Stuttgart and Munich specify high-performance organic pigments for clearcoat-compatible metallic finishes. ECHA substance evaluations under REACH systematically disqualify legacy heavy-metal colorants, pulling reformulation toward compliant alternatives. BASF SE leverages integrated R&D hubs in Ludwigshafen to sustain premium positioning across European accounts.
United States
Dashboard and trim manufacturers face cabin air quality standards mandating low-VOC, heavy-metal-free colorants from EPA-registered suppliers. EPA TSCA Section 8(a) reporting requirements capture fluorinated pigment dispersants, forcing qualification of fluorine-free wetting agents. The Midwest industrial corridor hosts concentrated plastics compounding capacity serving automotive tier-one suppliers.
India
Technical textile producers in Gujarat and Maharashtra specify vat and disperse organic pigments for automotive seating and industrial filter applications. BIS standards for pigment quality influence domestic procurement and export competitiveness. Sudarshan Chemical Industries Limited anchors backward integration into intermediates at its manufacturing complexes in the west.
Brazil
Flexible packaging gravure manufacturers in São Paulo adopt high-purity azo pigments to meet ANVISA's evolving food-contact material standards. Brazilian packaging ink growth opens specification windows as migration limits tighten. The Southeast industrial belt concentrates converters serving multinational consumer goods brands.
Global Organic Pigments Market Competitive Environment
Integrated multinational chemical conglomerates and specialized regional pigment houses split the market into distinct capability tiers. Consolidation pressures intensify as specification-driven procurement compresses approved vendor lists among coatings and plastics compounders. Three archetypes dominate: backward-integrated intermediates producers, formulation-technical-service bundlers, and regional wholesale distributors. Capacity expansion in Chinese manufacturing clusters and M&A activity among European specialty chemical distributors represent the dominant competitive moves reshaping supply architecture.
Among Asia-Pacific-based manufacturers, DIC Corporation and Dainichiseika Color & Chemicals Mfg. Co., Ltd. occupy positions within the technical-relationship tier serving ink and display material customers. BASF SE and Clariant AG exemplify the integrated-multinational archetype with captive R&D and global registration dossiers. Sudarshan Chemical Industries Limited anchors the backward-integrated specialist tier through in-house production of diazotization intermediates. These three groupings reflect divergent strategic postures toward regulatory compliance burden, technical service intensity, and geographic market coverage.
| Leading Market Players |
|---|
| DIC Corporation |
| Sudarshan Chemical Industries Limited |
| BASF SE |
| Heubach GmbH |
| Clariant AG |
| Dainichiseika Color & Chemicals Mfg. Co., Ltd. |
| Artience Co., Ltd. |
| Atul Ltd. |
| Anshan Hifichem Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Chinese control over 3,3'-dichlorobenzidine and other diazotization intermediates concentrates upstream margin capture in Jiangsu and Zhejiang province manufacturing clusters, while downstream pricing power accrues to German automotive coatings compounders with REACH-locked formulation approvals.
Pricing Analysis
Configured-to-order pigment preparations command 15-40% premiums over standard powder grades depending on carrier system specificity and colorimetric tolerance bands. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by REACH registration completeness and automotive OEM qualification status. Cost compression in Chinese phthalocyanine output is intensifying because domestic capacity expansion outpaces derivative demand growth. Mid-size plastics compounders exhibit highest price sensitivity due to limited formulation chemistry resources, while automotive tier-one suppliers prioritize batch consistency over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for multinational coatings accounts, with supply-chain finance facilities increasingly bundled by technical-service distributors. Manufacturing concentration spans China, India, and Germany for distinct pigment chemistries—azo coupling in Asian clusters, high-performance phthalocyanines in European hubs. Feedstock dependencies center on naphtha-derived benzene, aniline, and phthalic anhydride from petrochemical value chains. Single-source vulnerability in Chinese intermediate supply creates structural risk for Western formulators. Distribution runs through consolidated technical-service providers with captive application laboratories rather than commodity logistics brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat—REACH registration dossiers and automotive OEM approvals create switching costs that compound over multi-year qualification cycles.
For Market Incumbents: Build regulatory moats by accelerating ECHA substance evaluation pre-submissions ahead of competitor reformulation cycles. Secure backward integration into 3,3'-dichlorobenzidine and other coupling intermediates to deflect Chinese supply disruption threats. Expand technical-service laboratory capacity in Stuttgart and Detroit automotive corridors to tighten specification-lock with tier-one coatings suppliers. For New Entrants and Emerging Players: Build out encapsulated pigment concentrate capabilities targeting mid-size European plastics compounders lacking captive grinding infrastructure. Brazilian flexible packaging gravure applications under ANVISA migration limit evolution represent the most penetrable specification window. Pursue distributor partnerships with technical-service bundlers rather than direct sales to compressed automotive vendor lists. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across liquid pigment and concentrate manufacturing as pre-dispersion technologies virtualize milling infrastructure requirements. Acquisition targets should prioritize REACH-registered specialists with active automotive OEM approvals and in-house intermediate production. Watch for ECHA substance evaluation disqualification announcements as inflection indicators for reformulation-driven demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Intermediates | Captive supply of 3,3'-dichlorobenzidine insulates margin from Chinese concentration risk. |
| Encapsulated Concentrate Capacity Expansion | Pre-dispersed formats enable regional compounders to bypass captive grinding investments. |
| REACH Dossier Acceleration | Early ECHA submission secures formulation lock-in ahead of competitor requalification. |
| Technical-Service Laboratory Buildout | Colorimetric calibration capabilities displace price as primary selection criterion. |
| Fluorine-Free Dispersant Qualification | EPA TSCA Section 8(a) compliance opens waterborne industrial coatings specification windows. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, encompassing coatings formulators at German automotive OEM suppliers, procurement leads at Chinese plastics compounders, technical R&D directors at Indian pigment houses, and distribution channel partners in Brazilian packaging markets. Secondary validation drew from ECHA substance evaluation databases, EPA TSCA Section 8(a) filings, SAMR national standard notifications, and ACC/Cefic trade flow reports. Bottom-up volume modeling triangulated against top-down value estimates derived from customs data and SEC 10-K pigment segment disclosures.
Calibration across the analysis window employed multi-segment growth rate derivation with explicit modeling of product type splits, application tier evolution, and regional production hub competitiveness. Segmentation dimensions spanned powder/liquid/concentrate formats, coatings/inks/plastics/textiles end-uses, and automotive/construction/consumer goods procurement archetypes. CAGRs were computed from annualized shipment trajectories adjusted for feedstock cost pass-through elasticity and regulatory-driven substitution effects.
Stress conditions across naphtha price volatility bands, REACH evaluation acceleration scenarios, and Chinese intermediate export restriction probabilities were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on reformulation timelines and automotive qualification cycle durations. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Global Cosmetic Pigments Market
Dyes and Pigments
Complex Inorganic Color Pigments Market
Dyes and Pigments
Lithol Rubine BK Market
Dyes and Pigments
Europe Pigments Market
Dyes and Pigments
Pharmaceutical Dyes Market
Dyes and Pigments
Erythrosine Market
Dyes and Pigments
Riboflavin Pigment Market
Dyes and Pigments
Global Pigments Market
Dyes and Pigments
Phosphorescent Pigments Market
Dyes and Pigments
Bio Based Pigments and Dyes Market
Dyes and Pigments
Titanium Dioxide Pigment Market
Dyes and Pigments
Algal Pigments Market
Dyes and Pigments
Global Thermochromic Materials Market
Dyes and Pigments
Brilliant Blue FCF Colors Market
Dyes and Pigments
Cacao Husk Pigment Market
Dyes and Pigments
Carmoisine Market