
 Resin Pigments Market | 2026-2036
Resin Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Resin Pigments Market Analytics
Modular formulation kits is shifting how mid-sized coating buyers configure their resin pigment procurement, unbundling traditional all-in-one supply contracts into component-based purchasing. BASF SE leverages its integrated pigment and dispersant technology to anchor premium positions in automotive refinish segments. DIC Corporation competes through specialized ink-grade resin pigments that dominate narrow web and flexible packaging applications. Sun Chemical Corporation extends its color science capabilities into UV-curable systems for electronics coatings.
Resin pigments comprise colorants dispersed within thermoset or thermoplastic resin matrices, typically incorporating organic or inorganic chromophores at particle sizes below five microns to ensure optical clarity and weather resistance. These materials serve primarily to deliver controlled coloration, opacity, and functional properties such as UV absorption or thermal stability in cured polymer systems. Acrylic resin pigments occupy mature volume positions in architectural coatings where cost efficiency outweighs performance premiums. Water-based formulations represent the fastest-expanding formulation category as environmental compliance tightens across industrialized economies. Powder coating pigments concentrate margin pools in appliance and automotive OEM channels where transfer efficiency and regulatory alignment command price premiums.
EPA regulations in the United States restrict volatile organic compound emissions from coating operations, directly constraining solvent-based resin pigment demand and redirecting investment toward compliant alternatives. REACH registration requirements and the EU Green Deal framework in Europe mandate chemical safety documentation and carbon intensity disclosures that reshape supplier qualification protocols. China's MEE enforces national emission standards for industrial coating facilities, accelerating domestic production of low-VOC resin pigment systems. Stakeholders must monitor how divergent regional compliance timelines reshape competitive access and determine where to concentrate reformulation partnerships.
Market Dynamics
Water-based and UV-curable formulation mandates are compressing solvent-compatible pigment demand while redirecting R&D budgets toward dispersant-pigment integration and low-VOC compatibility testing.
Growth Catalysts
- REACH and EU Green Deal phase-outs:European coating OEMs face binding solvent reduction timelines, forcing accelerated reformulation partnerships with pigment suppliers capable of water-based system validation.
- Automotive refinish channel recovery:Collision repair volume normalization in Germany, China, and the United States is pulling premium-grade resin pigments through certified refinish networks.
- UV-curable electronics coatings:Semiconductor packaging and display manufacturing in South Korea and Taiwan are adopting cationic UV systems that demand specialized photoinitiator-compatible colorants.
Market Restraints
- Titanium dioxide feedstock volatility:Sulfate-process TiO2 producers in China face sulfuric acid cost swings that transmit directly into white pigment pricing and margin compression for mid-tier formulators.
- Specialty dispersant supply concentration:Polymeric dispersant manufacturing for sub-micron pigment stabilization clusters among German and Japanese chemical producers, creating qualification bottlenecks for new market entrants.
- High-performance organic pigment substitution:Inorganic complex colorants in automotive OEM basecoat applications are displacing certain high-cost quinacridone and phthalocyanine chemistries on durability-per-cost metrics.
Strategic Opportunities
- India industrial coating formalization:Bureau of Indian Standards certification requirements for architectural and protective coatings are creating first-mover advantage for pigment suppliers with pre-validated water-based portfolios.
- Photovoltaic backsheet coloration:Fluoropolymer and PET-based solar module backsheets require weatherable pigment systems that resist hydrolysis at 85°C/85%RH testing protocols.
- Modular formulation kit expansion:Mid-sized coating buyers in North America are unbundling all-in-one supply contracts into component-based pigment-dispersant-resin purchasing, opening direct supplier relationships previously blocked by integrated distributors.
Industry Challenges
- Colorimetric formulation talent scarcity:Spectrophotometric matching and opacity modeling for multi-pigment systems requires specialized technicians that coating manufacturers struggle to recruit outside established industrial clusters.
- Dual certification timeline compression:Automotive OEM qualification cycles for new pigment grades now overlap with REACH SVHC screening and IMDS material data submission, extending time-to-revenue by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resin Pigments Market |
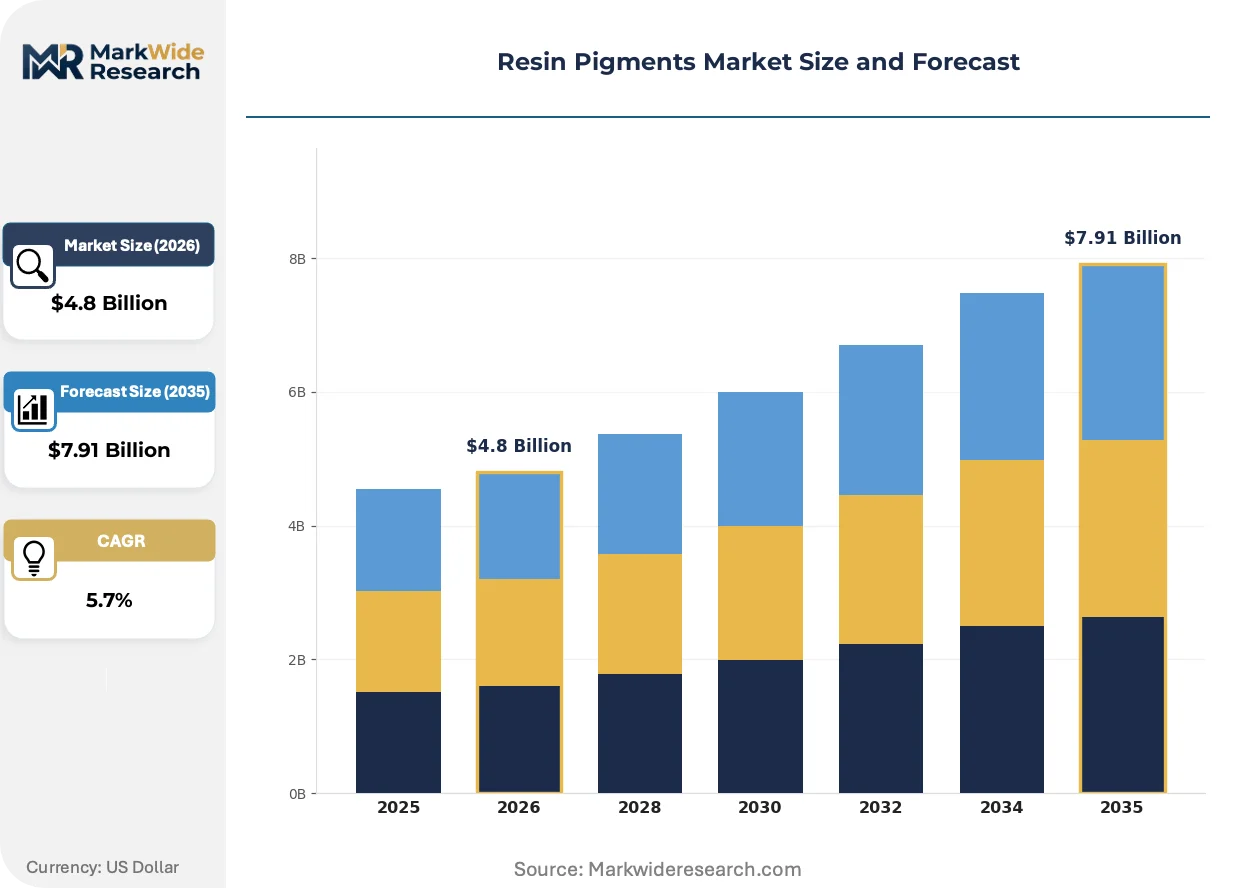
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Polyurethane, Polyester Formulation: Water-Based, Solvent-Based, Powder Coating, UV-Curable Application: Coatings, Inks, Plastics, Composites End User: Construction, Automotive, Electronics, Consumer Goods |
| Companies Covered | BASF SE, DIC Corporation, Dow Inc., Clariant International Limited, Arkema S.A., Sudarshan Chemical Industries, Lanxess AG, Sun Chemical Corporation, Toyocolor Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resin Pigments Market Evolving Landscape
Nano-dispersion technology and digital color matching platforms are compressing formulation development cycles while raising performance thresholds for weatherability and optical consistency.
Surface-functionalized nanoparticle pigments with silane and phosphate coupling agents are achieving sub-100 nanometer primary particle sizes without re-agglomeration. Automotive OEM clearcoat-over-basecoat systems in Germany and Japan are adopting these grades for enhanced flop and transparency. This capability is converging with self-healing clearcoat chemistry to enable deeper color saturation without sacrificing scratch recovery.
EPA New Source Performance Standards for coating operations are tightening VOC emission thresholds for facilities constructed or modified after 2023. Industrial coating applicators in the United States are retrofitting spray booths and converting to powder or water-borne systems to maintain operating permits. High-solids and powder coating pigment segments are capturing displaced solvent-borne volume in metal furniture and appliance manufacturing.
Buyers are consolidating supplier relationships around technical service capability rather than catalog breadth. Mid-sized coating formulators in China and India are reducing qualified pigment vendors from 8-12 to 3-4 per color space, prioritizing those with local application laboratories and just-in-time inventory positioning. This concentration is most visible in automotive refinish and industrial maintenance segments where color matching speed determines contract renewal rates.
Resin Pigments Market Segmentation
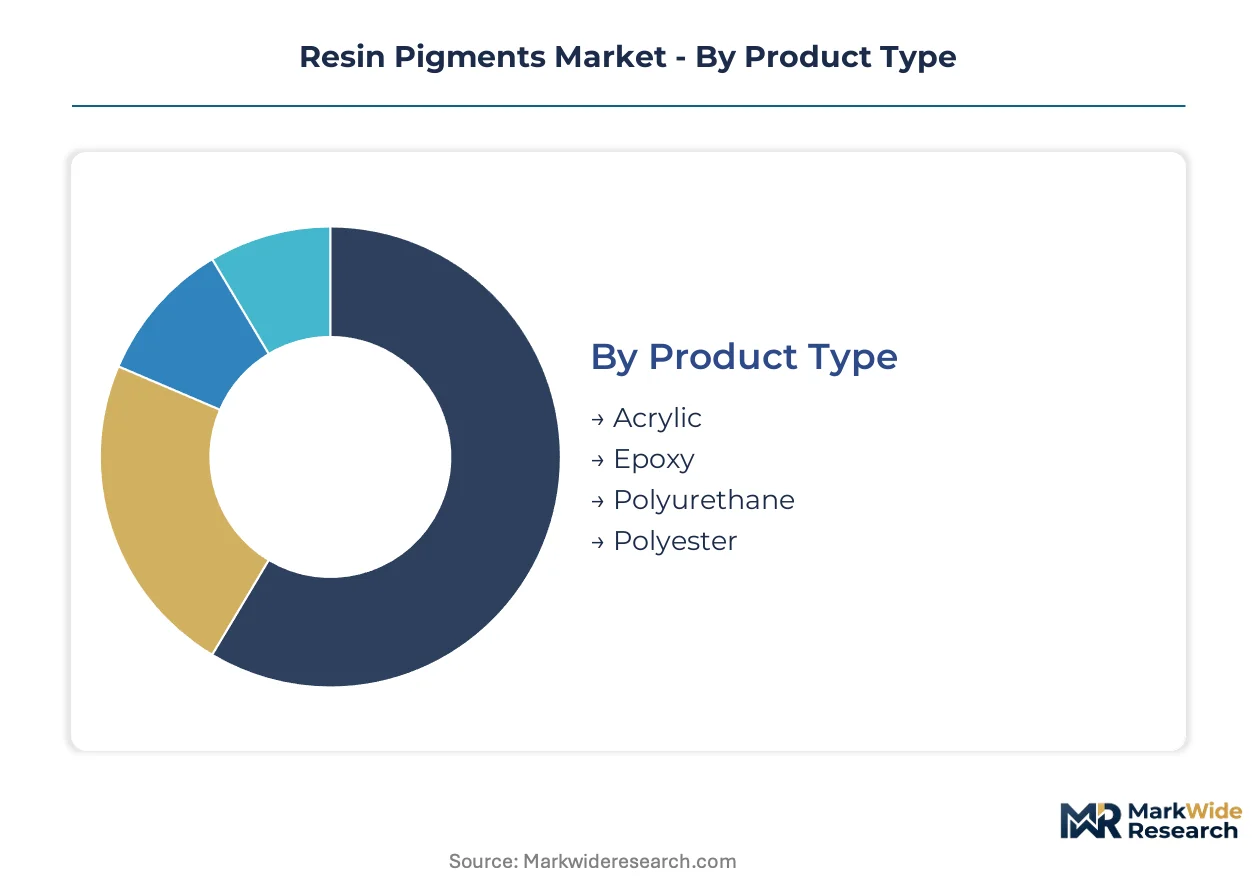
Resin pigment procurement patterns diverge sharply between high-volume commodity buyers seeking formulation standardization and specialized OEMs demanding custom colorimetric matching. Understanding these segment boundaries reveals where margin pools concentrate and which technical capabilities command pricing power across coating, ink, and plastics value chains.
Product Type:
Customization intensity varies from standardized architectural grades to highly specified automotive refinish systems where particle size distribution and weatherability metrics determine supplier qualification.
- Acrylic:Thermoplastic resin pigments dominate architectural coatings where cost efficiency and UV resistance outweigh performance premiums. Demand concentrates in China and India where construction activity pulls high volumes through domestic distribution networks constrained by MEE emission enforcement.
- Epoxy:Cross-linked resin matrices deliver chemical resistance and adhesion strength for protective coatings and industrial flooring. German and Japanese automotive OEMs specify these grades for underbody applications where stone chip resistance and salt spray performance are non-negotiable.
- Polyurethane:Aliphatic isocyanate-cured systems provide exceptional gloss retention and flexibility for premium automotive refinish and aerospace coatings.
- Polyester:Saturated and unsaturated variants serve powder coating and gelcoat applications in appliance manufacturing and marine composites.
Leading the category by volume: Acrylic. Growing fastest: Epoxy.
Formulation:
Regulatory pressure across multiple geographies is compressing solvent-compatible segments while expanding water-based and UV-curable alternatives.
- Water-Based:Dispersed pigment systems with polymeric stabilizers serve compliant architectural and industrial coatings. EPA New Source Performance Standards and REACH phase-out timelines in the United States and Europe are redirecting R&D investment toward dispersant-pigment integration for sub-micron stability.
- UV-Curable:Cationic and free-radical photoinitiator-compatible colorants enable instant cure for electronics coatings and narrow-web printing. South Korean and Taiwanese semiconductor packaging facilities specify these grades for display manufacturing where thermal sensitivity prohibits conventional oven curing.
- Solvent-Based:Traditional alkyd and acrylic resin solutions retain share in industrial maintenance where substrate compatibility and outdoor durability resist reformulation.
- Powder Coating:Dry-blend pigments with controlled particle morphology serve appliance and automotive OEM channels where transfer efficiency and zero-VOC profiles command price premiums.
Volume leadership: Water-Based. Steepest expansion trajectory: UV-Curable.
Application:
Performance specifications escalate from bulk coloration in plastics to multi-layer optical systems in automotive coatings where flop and transparency metrics determine competitive positioning.
- Coatings:Architectural, automotive, and industrial protective applications represent the dominant value pool. German automotive refinish networks and Chinese construction coating formulators drive differentiated demand patterns—premium color matching speed versus bulk cost efficiency.
- Inks:Offset, gravure, and flexographic printing systems require specialized dispersant technology for narrow web and flexible packaging. Japanese ink manufacturers concentrate procurement among pre-qualified pigment suppliers with validated food-contact compliance.
- Plastics:Masterbatch and compound applications for consumer goods and packaging prioritize heat stability and migration resistance.
- Composites:Gelcoat and resin infusion coloration for marine, wind energy, and transportation applications demands hydrolysis resistance and fiber wet-out compatibility.
Revenue concentration: Coatings. Gaining share fastest: Inks.
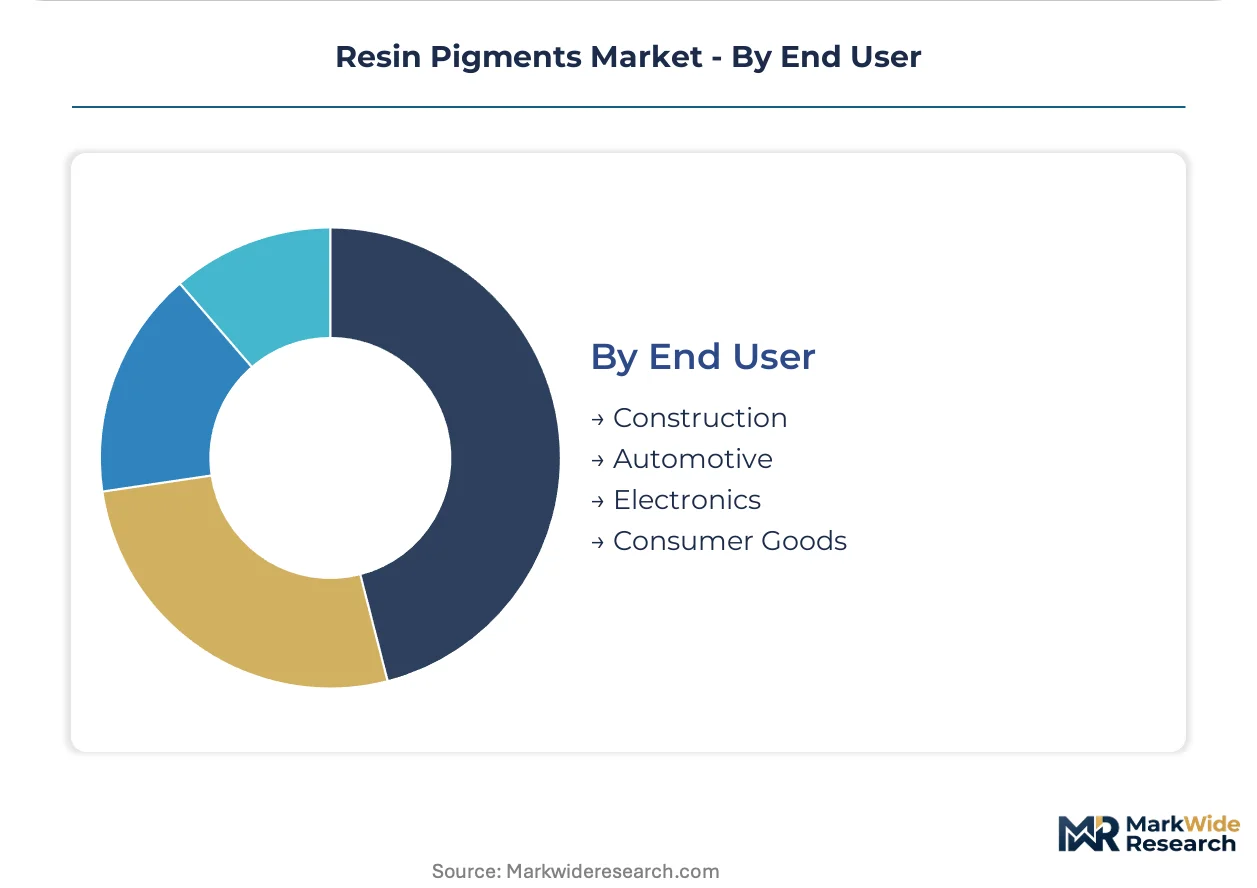
End User:
Customer technical sophistication ranges from specification-driven automotive OEMs with 18-24 month qualification cycles to price-sensitive construction contractors with minimal formulation expertise.
- Automotive:OEM basecoat and refinish applications impose the most stringent durability and colorimetric requirements. Collision repair volume normalization in Germany, China, and the United States pulls premium-grade pigments through certified distribution networks where IMDS material data submission and REACH SVHC screening extend supplier onboarding.
- Construction:Architectural coatings for residential and commercial buildings prioritize cost efficiency and weatherability over optical precision. Indian Bureau of Standards certification requirements are creating first-mover advantage for suppliers with pre-validated water-based portfolios.
- Electronics:Semiconductor packaging, display, and PCB coatings demand specialized UV-curable and high-purity grades.
- Consumer Goods:Packaging, appliances, and furniture applications balance aesthetic requirements with regulatory compliance for food contact and toy safety.
Margin leadership: Automotive. Expanding most quickly: Electronics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of resin pigment feedstock capacity while Germany and the United States absorb premium formulations for automotive and industrial coatings. This production-consumption divide shapes trade flows, regulatory arbitrage, and supplier qualification protocols across major economies.
China
Construction coating demand and export-oriented manufacturing pull acrylic and epoxy resin pigments through domestic distribution networks. MEE emission standards for industrial coating facilities accelerate domestic production of low-VOC systems. The Yangtze River Delta concentrates sulfate-process TiO2 manufacturing and pigment dispersion operations serving both local formulators and export markets.
Germany
Automotive OEM basecoat development and refinish network certification drive premium-grade consumption through qualified supply chains. REACH registration requirements and EU Green Deal carbon intensity disclosures reshape supplier onboarding protocols. The Cologne-Düsseldorf corridor hosts specialized dispersant manufacturing and colorimetric formulation laboratories serving automotive and industrial coating customers.
United States
Automotive refinish channel recovery and industrial maintenance coatings sustain demand for high-performance grades. EPA New Source Performance Standards tighten VOC emission thresholds for facilities modified after 2023, redirecting investment toward water-based and powder coating alternatives. The Southeast manufacturing belt, particularly Georgia and Tennessee, concentrates appliance and metal furniture coating operations adopting compliant pigment systems.
India
Bureau of Indian Standards certification requirements for architectural and protective coatings formalize procurement standards previously dominated by unorganized suppliers. Central Pollution Control Board emission norms for coating facilities in Maharashtra and Gujarat accelerate water-based system adoption. The Mumbai-Pune industrial corridor attracts first-mover pigment suppliers establishing local application laboratories and inventory positioning.
South Korea
Semiconductor packaging and display manufacturing generate specialized demand for UV-curable and high-purity resin pigments. MFDS chemical safety documentation requirements align with REACH-equivalent standards for electronics-grade materials. The Gyeonggi-do cluster around Seoul concentrates cationic UV system adoption for thermal-sensitive coating applications in flat-panel and chip packaging operations.
Resin Pigments Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive dispersant technology and pigment synthesis capabilities. Three to four diversified multinationals anchor premium positions in automotive and electronics segments, while mid-tier specialists concentrate on regional formulation services and commodity architectural grades. Two strategic archetypes dominate: technology-integrated suppliers bundling pigment-dispersant-resin systems, and regional formulators leveraging local regulatory knowledge and just-in-time logistics. Capacity expansion in China and India, alongside qualification partnerships for water-based system validation, constitute the dominant competitive moves.
Among diversified chemical conglomerates, BASF SE and DIC Corporation exemplify the technology-integrated archetype, occupying positions where integrated pigment and dispersant development anchors premium segment access. Sun Chemical Corporation represents the specialized color science vector, sitting within portfolios extending toward UV-curable and electronics-grade applications. These three entities illustrate how scale and technical service capability concentrate procurement relationships among mid-sized coating formulators reducing vendor counts per color space.
| Leading Market Players |
|---|
| BASF SE |
| DIC Corporation |
| Dow Inc. |
| Clariant International Limited |
| Arkema S.A. |
| Sudarshan Chemical Industries |
| Lanxess AG |
| Sun Chemical Corporation |
| Toyocolor Co. Ltd. |
| Others |
Value Network & Pricing Analysis
EU Green Deal carbon intensity disclosures and REACH SVHC screening protocols gate qualified supply access for automotive and electronics-grade resin pigments, concentrating premium-tier pricing power among integrated suppliers with pre-validated water-based and UV-curable portfolios. Buyers without IMDS material data submission capabilities face extended supplier onboarding timelines that compress their negotiating leverage.
Pricing Analysis
Margin tightening in mid-tier architectural grades reflects titanium dioxide feedstock volatility from Chinese sulfate-process producers and sulfuric acid cost swings. Three-tier pricing structure across premium, standard, and economy levels separates automotive OEM basecoat specifications with 18-24 month qualification cycles from bulk construction coatings. Price differentiation rests on REACH registration status and dispersant-pigment integration depth. Small formulators in India and Southeast Asia exhibit highest price sensitivity as Bureau of Indian Standards certification requirements force reformulation investments.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive and electronics buyer demand through qualified distribution networks in Germany, Japan, and the United States. Raw material dependencies center on Chinese sulfate-process TiO2, German and Japanese polymeric dispersant manufacturing, and South Korean photoinitiator supply for UV-curable systems. Single-source vulnerability concentrates in specialty dispersant production clustered among German and Japanese chemical producers. Distribution runs through integrated pigment-dispersant-resin bundlers serving refinish networks and component-based purchasing for mid-sized North American formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Resin pigment supply consolidation accelerates as REACH phase-out timelines and dual certification requirements force weaker regional formulators out of automotive and electronics qualification pipelines. Surviving players will capture displaced volume through technical service capabilities and pre-validated water-based portfolios.
For Market Incumbents: Cement premium positioning in automotive refinish by deepening captive dispersant technology and expanding application laboratory footprints in the Mumbai-Pune corridor and Southeast US manufacturing belt. Prioritize backward integration into polymeric dispersant manufacturing to reduce qualification bottlenecks from German and Japanese suppliers. Defend against modular formulation kit unbundling by embedding colorimetric formulation talent within customer technical service teams.
For New Entrants and Emerging Players: Regional distributors with certified refinish network access offer the fastest path to revenue for water-based system specialists lacking direct OEM relationships. Target India's Bureau of Indian Standards pre-validation gap for architectural coatings where organized suppliers remain underrepresented. Photovoltaic backsheet coloration for fluoropolymer solar module applications presents specialty-grade entry point with less entrenched incumbent control.
For Investors and Strategic Acquirers: Automotive OEM qualification cycle compression overlapping with REACH SVHC screening is the leading indicator that technical service-capable mid-caps will command scarcity premiums. Long-term viability favors targets with integrated pigment-dispersant development and regional application laboratory networks. Monitor collision repair volume normalization in Germany, China, and the United States as demand inflection signal for premium-grade consumption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dispersant Manufacturing | Captive polymeric stabilizer production reduces German and Japanese supplier dependency for sub-micron pigment grades. |
| Application Laboratory Expansion | Local colorimetric formulation capability in India and Southeast Asia accelerates Bureau of Indian Standards certification capture. |
| Water-Based System Pre-Validation | REACH and EPA New Source Performance Standards compliance positions suppliers for solvent-borne displacement volume. |
| UV-Curable Electronics Grade Development | Cationic photoinitiator-compatible colorants access South Korean and Taiwanese semiconductor packaging demand. |
| Modular Formulation Kit Partnerships | Component-based pigment-dispersant-resin supply relationships penetrate mid-sized North American coating buyer consolidation. |
Research Methodology
Independent corroboration across plant managers at Chinese sulfate-process TiO2 facilities, procurement leads at German automotive OEM coating operations, and technical R&D directors at Japanese ink manufacturers underwrites the qualitative findings. Secondary validation draws from customs and trade data, ACC and Cefic chemical industry reports, EPA New Source Performance Standards filings, and SEC 10-K disclosures from diversified chemical conglomerates. Bottom-up volume modeling across formulation categories triangulates with top-down consumption estimates from regional coating production databases.
Comparable-period anchoring to historical automotive refinish collision repair volumes, construction coating output indices, and electronics manufacturing capex cycles establishes the forecast baseline. Segmentation dimensions span resin chemistry type, formulation technology, end-use application, and regional regulatory compliance tier. CAGR derivation applies growth rate convergence analysis across the projection horizon, with industry-specific inputs including MEE emission enforcement intensity in China, EU Green Deal implementation pace, and photovoltaic installation forecasts for backsheet demand.
Caveats apply where titanium dioxide feedstock cost volatility, dispersant supply concentration bottlenecks, or divergent regional compliance timeline shifts could materially shift the outlook. Forecasts reflect assumptions regarding REACH phase-out adherence and automotive qualification cycle stability. Periodic stress-testing of base assumptions against EPA regulatory amendments and Bureau of Indian Standards certification rollout pace is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Quinacridone Pigments Market
Dyes and Pigments
Classic Organic Pigments Market
Dyes and Pigments
Inorganic Color Pigments Market
Dyes and Pigments
North America Hair Colorants Market
Dyes and Pigments
Reactive Dyes Market
Dyes and Pigments
Chlorophyll Color Market
Dyes and Pigments
Carmoisine Market
Dyes and Pigments
Global Aluminum Anodizing Dyes Market
Dyes and Pigments
Global Architectural Paint Oxide Market
Dyes and Pigments
Copper Chromite Black Pigment Market
Dyes and Pigments
Organic Pigment Dispersions Market
Dyes and Pigments
Global Thermochromic Materials Market
Dyes and Pigments
Bio Based Pigments and Dyes Market
Dyes and Pigments
Azo Pigments Market
Dyes and Pigments
Inorganic Pigments Market
Dyes and Pigments
Middle East and Africa Hair Colorants Market