
 Global Paint Pigments Market | 2026-2036
Global Paint Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Global Paint Pigments Market Foresight
The gap between premium and commodity paint pigment tiers is broadening as automotive OEMs and marine coaters demand higher color consistency and weatherability, while construction firms prioritize cost-per-unit coverage. BASF SE leverages its integrated pigment precursor operations to sustain margin advantages across specialty grades. Clariant AG anchors its position through controlled supply of high-performance organic pigments for automotive refinishing. Heubach GmbH competes on customized color matching services for industrial finishers in Europe.
Paint pigments encompass finely dispersed colorants—organic azo compounds, inorganic metal oxides, and interference mica platelets typically ground to 0.1–5.0 micron particle size—that impart opacity, tinting strength, and durability to protective and decorative coatings. Water-based technology leads volume growth as manufacturers reformulate to meet VOC restrictions, while solvent-based systems retain share in marine and protective coatings where substrate adhesion demands persist. Organic pigments capture premium pricing in automotive refurbishing due to chromatic intensity requirements, whereas inorganic titanium dioxide dominates architectural coatings on raw material scale.
EPA regulations in the United States restrict hazardous air pollutant emissions from coating operations, compelling pigment suppliers to certify low-HAP content. REACH and the EU Green Deal in Europe mandate substance registration and carbon footprint disclosure across chemical supply chains. China's MEE enforces discharge standards on titanium dioxide sulfate process waste. Stakeholders must monitor regulatory divergence across these jurisdictions to align product portfolios with diverging compliance thresholds.
Market Dynamics
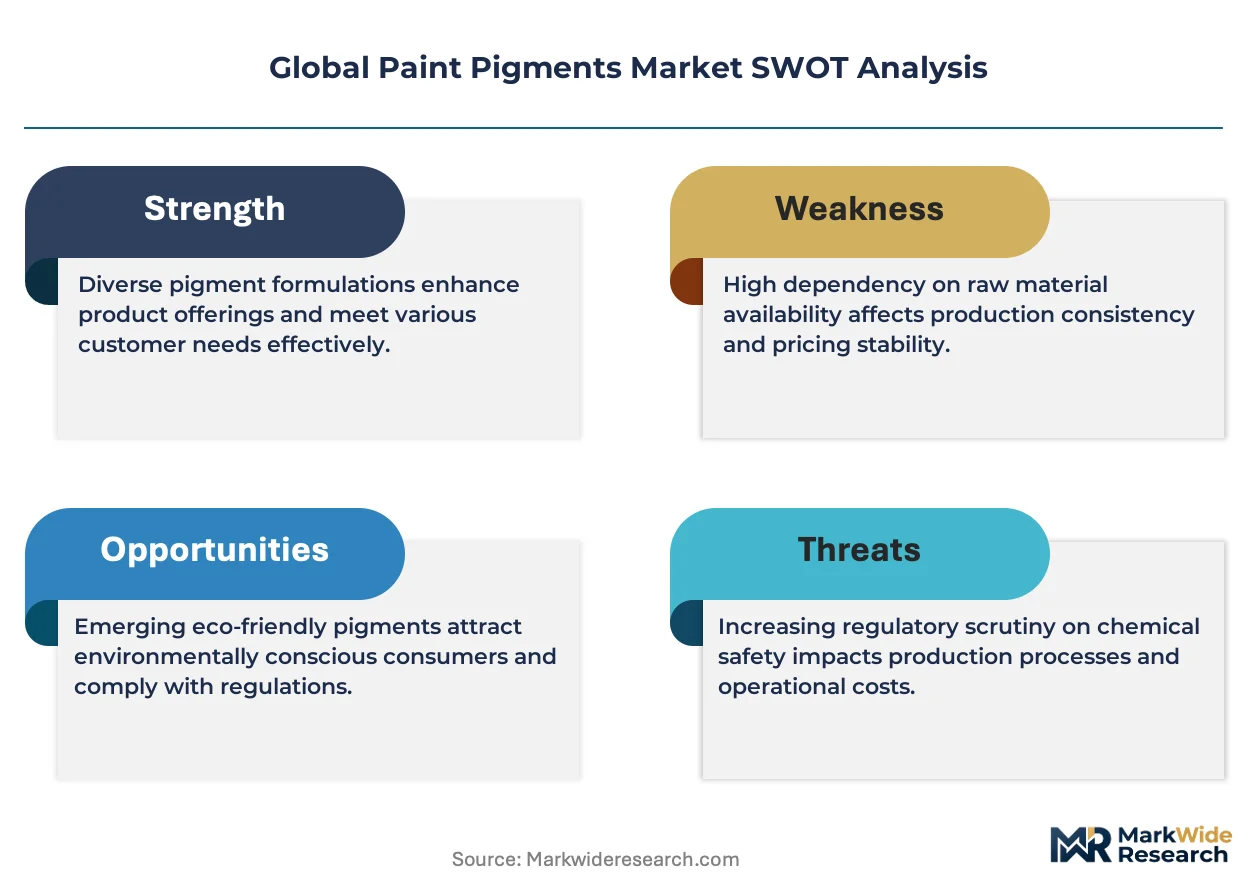
Water-based pigment reformulation is compressing solvent-based share as automotive OEMs and architectural coaters face tightening VOC mandates across North America, Europe, and East Asia.
Growth Catalysts
- REACH substance registration:European chemical compliance is forcing coating manufacturers to source pre-certified pigment grades, consolidating supplier relationships around compliant producers.
- Automotive waterborne coatings:OEM assembly plants are converting spray booths to handle water-based basecoats, pulling demand for compatible organic pigment dispersions.
- China titanium dioxide sulfate process scale:Domestic chloride-route capacity expansion is reducing import dependency for architectural coating producers in Shandong and Jiangsu provinces.
Market Restraints
- Titanium feedstock concentration:Ilmenite and rutile supply concentrates among Australian and South African mining operations, exposing pigment producers to bulk shipping rate volatility.
- High-performance organic pigment synthesis:Multi-step diazotization and coupling reactions require dedicated reactor infrastructure that smaller compounders cannot justify.
- Marine coating solvent retention:IMO antifouling standards and substrate adhesion requirements preserve solvent-based epoxy demand in shipyard applications, limiting waterborne conversion rates.
Strategic Opportunities
- India architectural coating penetration:Urban housing stock expansion and decorative paint consumption growth in Maharashtra and Gujarat states outpace domestic pigment supply.
- Photovoltaic backsheet pigmentation:Fluoropolymer and PET-based solar module backsheets require weatherable inorganic colorants, opening a non-coating application channel.
- EU Green Deal carbon border adjustments:Embedded emissions disclosure requirements favor European pigment producers with renewable energy sourcing over import competitors.
Industry Challenges
- Colorimetric formulation expertise:Spectrophotometric matching and dispersion rheology skills concentrate among aging technician cohorts in European and Japanese coating centers.
- Legacy solvent-based inventory amortization:Coatings manufacturers face write-down pressure on existing solvent pigment stocks during waterborne transition timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Paint Pigments Market |
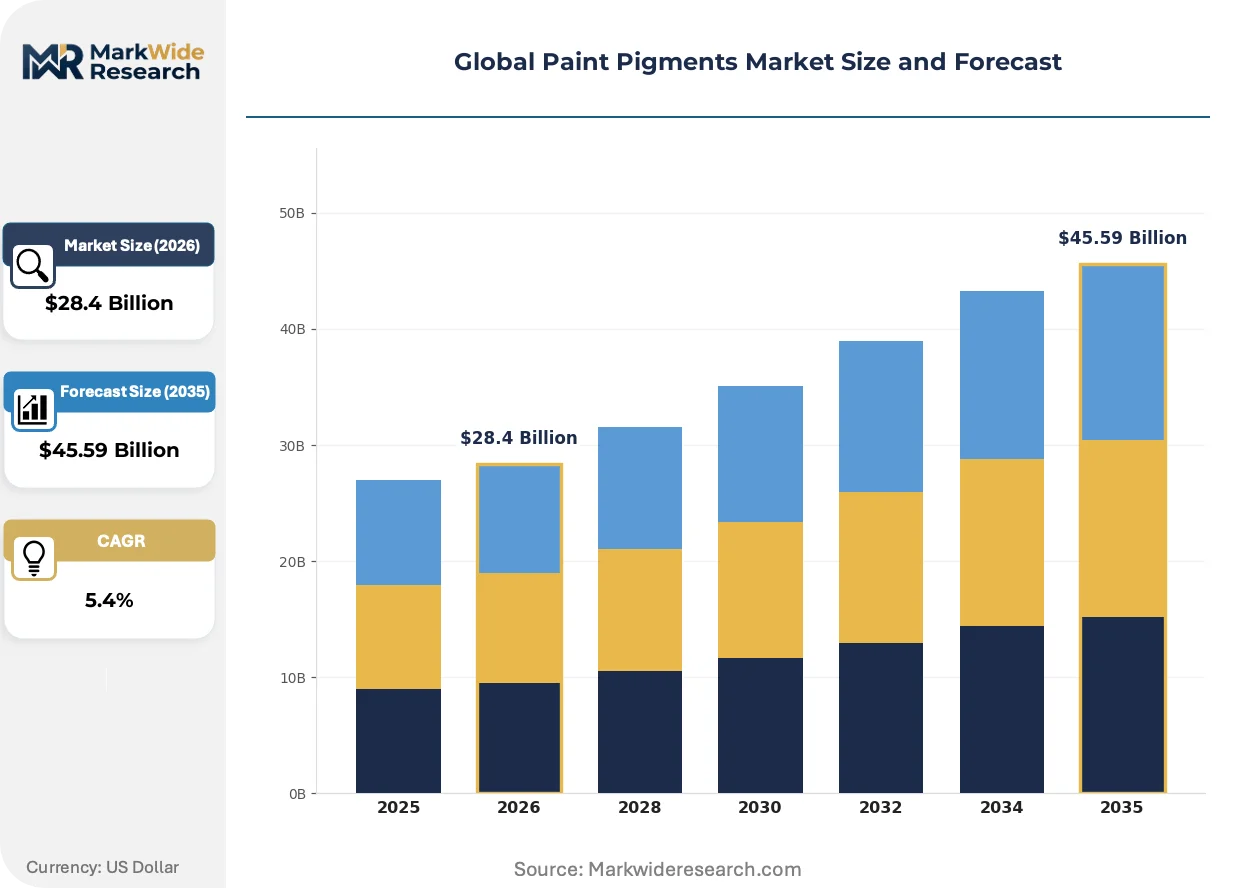
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $45.59 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Inorganic, Metallic, Pearlescent, Fluorescent Technology: Solvent-Based, Water-Based, Powder Coating, UV Curable, Epoxy Application: Architectural Coatings, Industrial Finishes, Automotive Refurbishing, Marine Coatings, Protective Coatings End User: OEM Manufacturers, Aftermarket Suppliers, Shipbuilders, Construction Firms, Furniture Producers |
| Companies Covered | Lanxess AG, Evonik Industries, BASF SE, Cabot Corporation, DuPont, Clariant AG, Huntsman Corporation, Heubach GmbH, DIC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Paint Pigments Market Shifts & Advancements
Dispersion automation and inline color control systems are compressing batch-to-batch variation while regulatory disclosure mandates reshape supplier documentation burdens.
Closed-loop spectrophotometric dosing is automating tinting operations in high-volume architectural coating plants. Retail paint manufacturers in North America are retrofitting automated dispensing equipment to reduce manual color matching labor. This technology is automating quality control steps that previously required dedicated laboratory verification.
EU Green Deal carbon footprint disclosure rules now extend to imported chemical intermediates. Pigment suppliers must document Scope 3 emissions from precursor synthesis through finished goods distribution. Automotive OEMs in Germany and France are prioritizing suppliers with verified lifecycle data for new model program awards.
Specification-driven procurement now dominates large coating contracts. Facility maintenance managers and automotive fleet operators are consolidating pigment purchases around certified performance tiers rather than spot-buying commodity grades. This pattern is most pronounced in North American industrial maintenance coating programs where warranty terms mandate documented raw material traceability.
Global Paint Pigments Market Segmentation
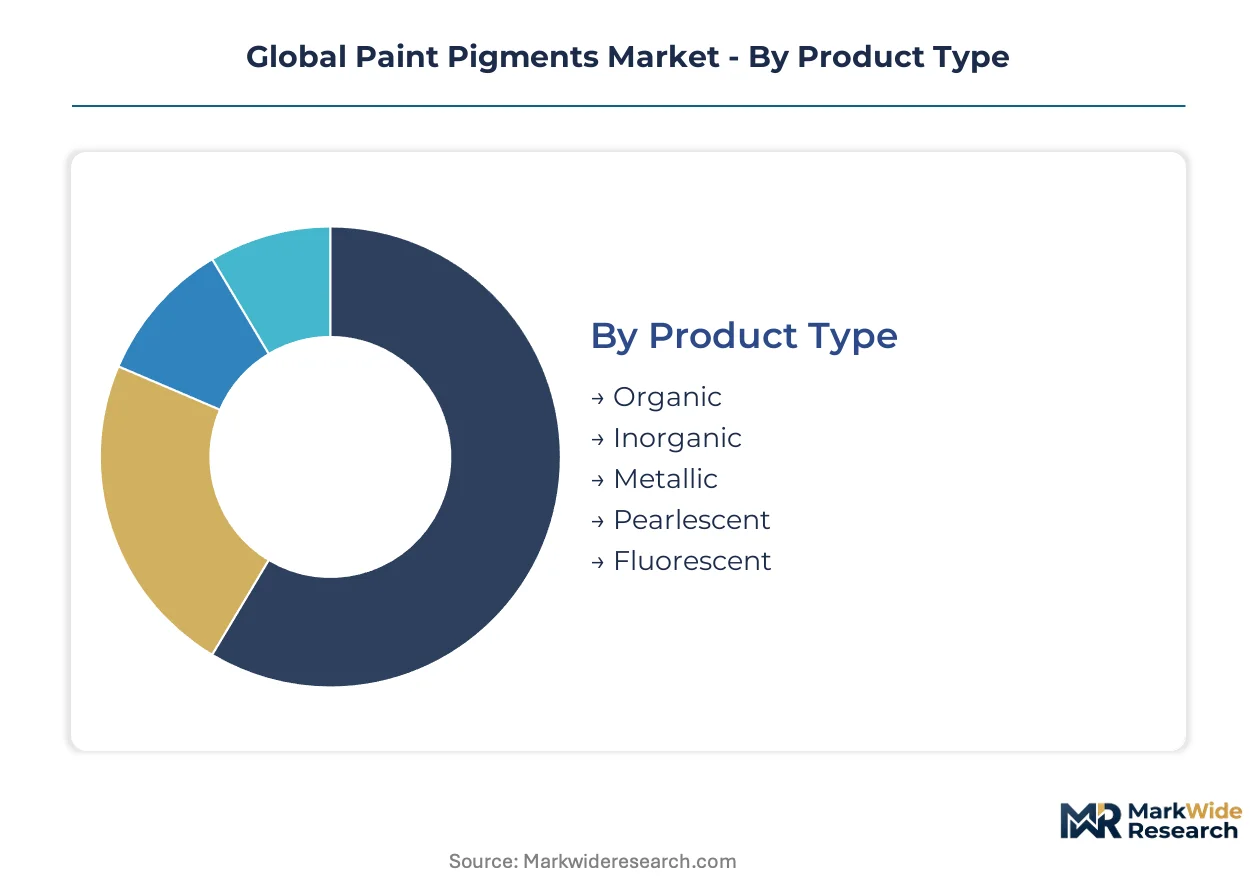
Paint pigment procurement decisions diverge sharply across end-use applications. Regulatory certification burdens, performance specifications, and cost-per-unit coverage requirements create distinct segment boundaries that suppliers must navigate.
Product Type:
REACH substance registration and EPA hazardous air pollutant certifications apply unevenly across pigment chemistries, with organic azo compounds facing the heaviest documentation load.
- Organic:Azo and phthalocyanine compounds deliver chromatic intensity for automotive refinishing. German automotive OEMs demand certified low-HAP organic grades for waterborne basecoat programs.
- Inorganic:Titanium dioxide and iron oxide pigments dominate architectural volume. Chinese sulfate-process producers in Shandong province supply cost-competitive TiO2 for domestic construction coating manufacturers.
- Metallic:Aluminum flake and bronze powder pigments provide reflective finishes for industrial machinery coatings.
- Pearlescent:Mica-based interference pigments create color-shift effects in premium automotive and cosmetic packaging applications.
- Fluorescent:Daylight-fluorescent pigments serve safety marking and traffic signage with high-visibility requirements.
Leading the category by volume: Inorganic. Expanding most quickly: Organic.
Technology:
Cost tier separation between water-based reformulation investments and legacy solvent infrastructure drives procurement patterns among coating manufacturers.
- Water-Based:Acrylic and polyurethane dispersions carry pigment loads for low-VOC architectural and automotive OEM coatings. Michigan automotive assembly plants mandate waterborne basecoat compatibility for new supplier qualifications.
- Solvent-Based:Alkyd and nitrocellulose systems retain marine and protective coating share. Korean shipyards specify solvent epoxy formulations for IMO antifouling compliance.
- Powder Coating:Thermoset powder systems encapsulate pigments without liquid carriers for appliance and furniture finishing.
- UV Curable:Photoinitiator-activated systems enable rapid-cure industrial coating lines with minimal solvent content.
- Epoxy:Two-component epoxy technologies serve chemical-resistant industrial maintenance applications.
Water-Based leads technology volume. UV Curable shows steepest expansion trajectory.
Application:
Customer type concentration varies from specification-driven automotive procurement to price-sensitive construction spot-buying.
- Architectural Coatings:Decorative and protective exterior paints consume titanium dioxide at scale. Indian housing stock expansion in Maharashtra and Gujarat outpaces domestic pigment supply.
- Industrial Finishes:Machinery and equipment coatings demand color consistency across batch production. Japanese coating centers concentrate spectrophotometric formulation expertise for this segment.
- Automotive Refurbishing:Body shop repair coatings require color-matched organic pigment dispersions.
- Marine Coatings:Shipyard applications preserve solvent-based epoxy demand for substrate adhesion.
- Protective Coatings:Infrastructure and pipeline coatings specify weatherable inorganic grades with documented traceability.
Architectural Coatings dominates application volume. Automotive Refurbishing climbs fastest.
End User:
Supply chain maturity separates consolidated OEM procurement from fragmented construction distribution channels.
- OEM Manufacturers:Automotive and appliance producers mandate certified pigment grades with full lifecycle documentation. French automotive OEMs prioritize suppliers with verified Scope 3 emissions data.
- Aftermarket Suppliers:Refinish coating distributors stock color-matched pigment dispersions for collision repair networks.
- Shipbuilders:Korean and Chinese shipyards procure marine-grade pigments for IMO-compliant antifouling systems.
- Construction Firms:Project-based coating consumption prioritizes cost-per-unit coverage over premium performance tiers.
- Furniture Producers:Powder coating and UV-curable systems serve mass-production finishing lines.
OEM Manufacturers lead end user volume. Construction Firms gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province in eastern China hosts the densest concentration of titanium dioxide sulfate-process capacity, supplying architectural coating manufacturers across East Asia with cost-competitive inorganic pigments.
China
Domestic chloride-route TiO2 expansion in Jiangsu and Shandong provinces is reducing import dependency for construction coating producers. The MEE enforces discharge standards on sulfate process waste streams. Qingdao and Jinan industrial clusters are scaling water-based pigment dispersions for automotive OEM supply chains.
Germany
Automotive OEMs in Stuttgart and Munich mandate certified low-HAP organic grades for waterborne basecoat programs. REACH substance registration forces coating manufacturers to source pre-certified pigment grades. The Leverkusen and Ludwigshafen chemical corridor anchors integrated pigment precursor operations serving specialty automotive refinishing demand.
United States
EPA hazardous air pollutant restrictions compel pigment suppliers to certify low-HAP content for coating operations. Michigan automotive assembly plants require waterborne basecoat compatibility for new supplier qualifications. The Gulf Coast petrochemical corridor supplies intermediate feedstocks for organic pigment synthesis.
India
Urban housing stock expansion in Maharashtra and Gujarat outpaces domestic pigment supply for architectural coatings. BIS standards govern pigment quality specifications for construction applications. The Mumbai-Pune industrial belt is attracting import substitution investments from Chinese TiO2 producers.
South Korea
Korean shipyards specify solvent epoxy formulations for IMO antifouling compliance, preserving marine coating pigment demand. The Busan-Ulsan industrial complex concentrates protective coating production for export markets. Domestic automotive OEMs in Gyeonggi province are converting spray booths to water-based systems.
Global Paint Pigments Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the pigment value chain. Integrated chemical conglomerates with captive titanium feedstock and precursor synthesis capabilities hold structural margin advantages over compounders sourcing intermediates. The vendor base separates into three archetypes: diversified multinationals with full vertical coverage, regional specialists in high-performance organic synthesis, and commodity-scale inorganic producers. Competitive moves center on backward integration into ilmenite processing and strategic partnerships with automotive OEMs for certified waterborne grade supply.
Among Germany-based chemical conglomerates, BASF SE and Lanxess AG exemplify the integrated archetype with upstream control over pigment precursor operations. Heubach GmbH occupies a position within the European specialist tier, anchoring customized color matching services for industrial finishers. These three entities represent the competitive spectrum from commodity-scale inorganic production through specialty organic synthesis.
| Leading Market Players |
|---|
| Lanxess AG |
| Evonik Industries |
| BASF SE |
| Cabot Corporation |
| DuPont |
| Clariant AG |
| Huntsman Corporation |
| Heubach GmbH |
| DIC Corporation |
| Others |
Supply & Pricing Matrix
Captive ilmenite-to-pigment operations in Australia and South Africa anchor supply positions and pricing power for integrated titanium dioxide producers serving architectural coating markets. This backward integration shields sulfate-process operators from bulk shipping rate volatility while compressing margin room for compounders sourcing intermediate feedstocks.
Pricing Analysis
Certified low-HAP content for EPA-compliant waterborne automotive basecoats commands value-based premiums tied to OEM warranty performance. Pricing stratifies across REACH-registered specialty grades, standard industrial tiers, and economy construction pigments with variable tinting strength. Cost compression in commodity titanium dioxide intensifies as Chinese sulfate-process capacity scales in Shandong province. Construction firms exhibit highest price sensitivity; automotive OEM procurement teams prioritize certification traceability over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Stuttgart and Munich automotive assembly plants requiring certified organic pigment dispersions. Raw material flows concentrate on Australian ilmenite, South African rutile, and Chinese sulfate-process titanium dioxide feedstock. The supply chain rests on titanium feedstock concentration among mining operations exposed to bulk shipping chokepoints. Specialty organic pigment synthesis depends on Indian and Chinese intermediate chemical production. Distribution runs through certified distributor networks for automotive refinishing and bulk construction chemical suppliers for architectural coatings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race defines competitive positioning as players pursue captive titanium feedstock security and certified waterborne grade supply chains. The upstream lever centers on ilmenite processing control; downstream leverage accumulates through automotive OEM qualification programs.
For Market Incumbents: Extend backward integration into Australian and South African ilmenite processing to defend margin structure against Chinese sulfate-process imports. Secure REACH pre-certification for organic azo compounds to consolidate supplier relationships as European coating manufacturers face substance registration deadlines. Capacity addition in Jiangsu province chloride-route TiO2 serves Chinese domestic automotive OEM demand growth. For New Entrants and Emerging Players: E-commerce pigment distribution platforms open white-space access to fragmented Indian construction coating distributors in Maharashtra and Gujarat states. Photovoltaic backsheet pigmentation offers penetrable non-coating application demand from fluoropolymer solar module manufacturers. Target certified small-batch color matching services for European industrial finishers as Heubach GmbH's traditional stronghold. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty organic pigment synthesis assets with automotive OEM qualification credentials and documented Scope 3 emissions data. Long-term viability favors producers with integrated precursor operations and renewable energy sourcing for EU Green Deal carbon border adjustment compliance. Monitor chloride-route TiO2 capacity expansion announcements in China as inflection signal for sulfate-process margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ilmenite Processing | Captive Australian and South African feedstock secures margin structure against shipping volatility. |
| REACH Pre-Certification Investment | European coating manufacturers consolidate supplier relationships around compliant organic pigment grades. |
| Waterborne Basecoat Qualification Programs | Michigan and Stuttgart automotive OEMs mandate certified low-HAP compatibility for new awards. |
| Photovoltaic Backsheet Pigmentation Development | Fluoropolymer solar module manufacturers create non-coating demand channel for weatherable inorganic colorants. |
| Chloride-Route TiO2 Capacity Expansion | Jiangsu and Shandong province builds reduce Chinese architectural coating import dependency. |
Research Methodology
Trade publications, chemical industry association reports, and customs shipment records formed the secondary backbone for supply-side capacity and trade flow assessment. Primary interviews with pigment plant managers, automotive OEM procurement leads, coating R&D directors, and construction chemical distributors combined with secondary validation across the analysis window. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Historical trendline analysis of titanium dioxide capacity utilization and organic pigment trade flows informed projection frameworks across the modeling period. Segmentation dimensions included pigment chemistry tier, coating technology type, end-use application intensity, and regional production hub concentration. CAGRs derived from trend extrapolation adjusted for regulatory phase-in schedules and automotive OEM platform conversion timelines. Forecast inputs incorporated REACH substance registration compliance costs and Chinese MEE discharge standard enforcement patterns.
The model holds under stable regulatory phase-in schedules and continued automotive waterborne conversion; deviation in EU carbon border adjustment implementation timing or Chinese environmental enforcement intensity would shift trajectory assumptions. Periodic stress-testing of base assumptions against ilmenite price volatility and shipping rate movements is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Titanium Dioxide Color Market
Dyes and Pigments
Global Thermochromic Paint Market
Dyes and Pigments
Riboflavin Pigment Market
Dyes and Pigments
White Pigment Market
Dyes and Pigments
Chemochromic Material Market
Dyes and Pigments
Methylene Blue Market
Dyes and Pigments
Fluorescent Brightening Agents Market
Dyes and Pigments
Acid Violet 43 Market
Dyes and Pigments
Light Interference Pigments Market
Dyes and Pigments
France Aluminium Pigments Market
Dyes and Pigments
Zinc Oxide Pigments Market
Dyes and Pigments
Color Retention Agents Market
Dyes and Pigments
Acid Dyes Market
Dyes and Pigments
Asia-Pacific Feed Pigments Market
Dyes and Pigments
Thermochromic Labels Market
Dyes and Pigments
Europe Hair Colorants Market