
 Asia-Pacific EVA Adhesives Market | 2026-2036
Asia-Pacific EVA Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific EVA Adhesives Market Outlook
China's GB standards for construction adhesives is recalibrating the cost-of-entry calculus for EVA adhesive suppliers seeking building-materials certification. Dow leverages its integrated ethylene-vinyl acetate supply chain to sustain cost leadership across hot melt formulations. Henkel AG & Co KGaA anchors its position through specialized automotive bonding solutions that navigate stringent OEM specifications. NANPAO RESINS CHEMICAL GROUP dominates Taiwan's domestic market and extends its reach into Southeast Asian electronics assembly.
Ethylene-vinyl acetate adhesives are thermoplastic polymer systems typically containing 18-40% vinyl acetate content, manufactured through high-pressure bulk polymerization and subsequently compounded with tackifiers and waxes for melt processing. These adhesives bond porous and non-porous substrates through mechanical interlocking and van der Waals forces, serving primary roles in packaging line sealing, automotive interior lamination, and solar panel encapsulation. Hot melt formulations command the largest volume share due to their solvent-free curing and rapid set times on high-speed production lines, while pressure sensitive adhesives are capturing faster growth from electronics and medical tape applications in South Korea and Japan. Reactive EVA systems carry premium positioning in automotive structural bonding where cure-on-demand properties justify higher formulation costs.
Japan's METI enforces JIS standards that restrict formaldehyde emissions from furniture and construction adhesives, directly shaping product formulation requirements for suppliers serving Japanese OEMs. India's BIS certification mandates for imported industrial chemicals create compliance barriers that favor domestic compounders with established testing relationships. The EU Green Deal's extraterritorial influence through supply chain auditing is pressing exporters in Thailand and Malaysia to document carbon intensity across EVA resin sourcing. Stakeholders must monitor divergence between national standards regimes as fragmentation in certification requirements threatens to segment the Asia-Pacific market into incompatible technical jurisdictions.
Market Dynamics
China's GB standards for construction material emissions are forcing wholesale reformulation across EVA adhesive portfolios, compressing margins for suppliers lacking captive resin production or low-VOC formulation expertise.
Growth Catalysts
- Solar encapsulation demand:Photovoltaic manufacturers in India are scaling high-performance EVA formulations for module lamination, pulling volume from conventional packaging applications.
- GB standards compliance:China's tightening VOC thresholds for construction adhesives are accelerating substitution of solvent-based systems with hot melt grades in building materials certification.
- Footwear production relocation:Vietnam's northern industrial provinces are concentrating demand as OEMs shift assembly from southern China, expanding regional consumption of assembly-grade EVA hot melts.
Market Restraints
- Ethylene feedstock volatility:Crude-linked naphtha pricing swings compress formulation margins for non-integrated compounders lacking backward integration into ethylene supply.
- Resin supply concentration:Asian EVA copolymer production clusters in South Korea and Thailand, creating geographic chokepoints that amplify disruption risk from plant outages or export restrictions.
- Hot melt temperature limitations:EVA-based systems face performance ceilings above 80°C in automotive underhood applications, blocking penetration into structural bonding segments dominated by reactive chemistries.
Strategic Opportunities
- Indonesian electronics assembly:Underpenetrated smartphone and tablet manufacturing clusters in Batam and Jakarta offer white space for pressure-sensitive EVA tape formulations serving component mounting.
- EU Green Deal auditing:Supply chain carbon documentation requirements are creating first-mover advantage for Thai and Malaysian exporters with verified low-intensity resin sourcing.
- Medical tape convergence:Hygiene-grade EVA adhesives combining breathability with skin-contact compliance are capturing share from acrylic systems in Japan's aging-care product segments.
Industry Challenges
- BIS certification timelines:India's mandatory testing protocols for imported industrial chemicals extend product registration cycles, stranding inventory and freezing supplier switching for compounders without established laboratory relationships.
- Legacy equipment retrofit costs:Hot melt application systems in Southeast Asian packaging lines require temperature control upgrades to process next-generation low-odor formulations, raising capital barriers for mid-scale converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific EVA Adhesives Market |
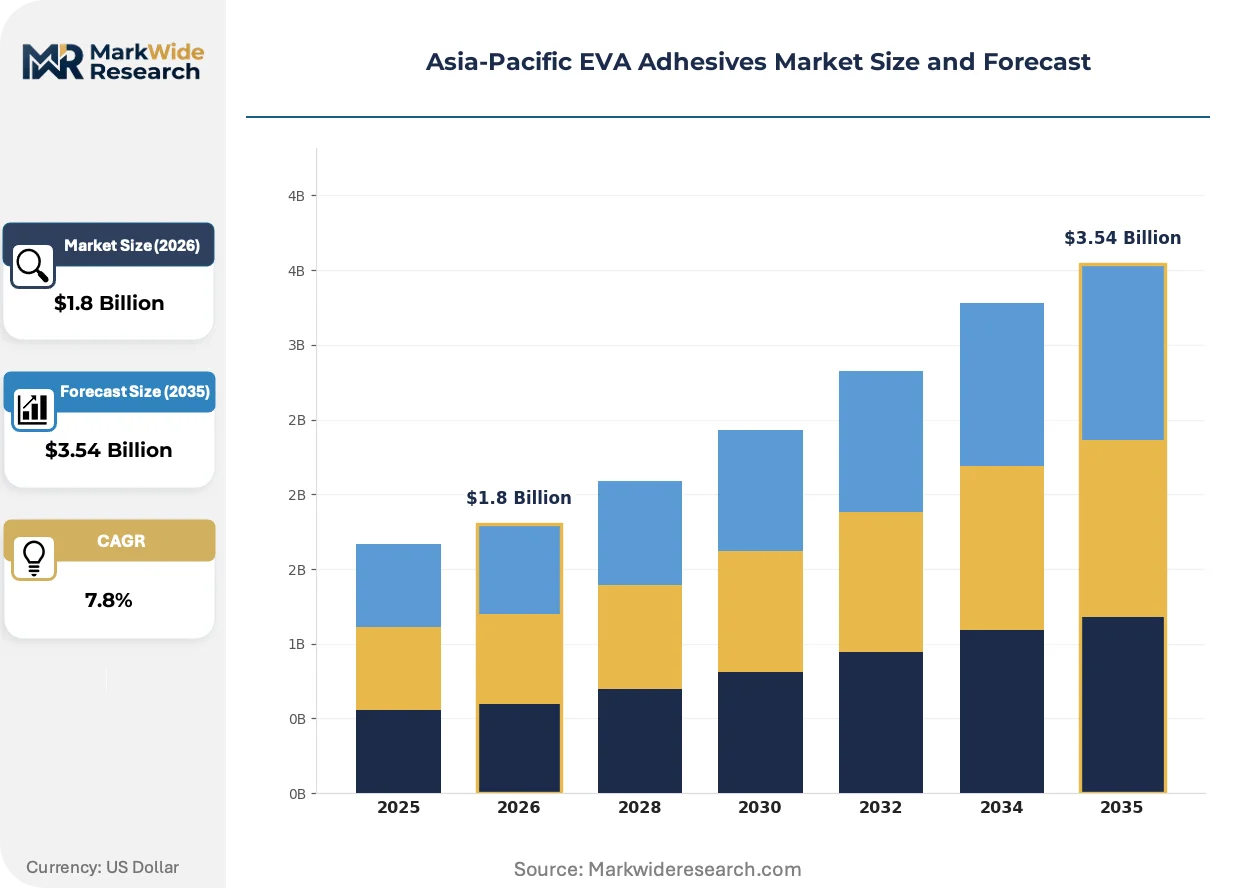
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Melt, Pressure Sensitive, Reactive, Soft Touch Application: Packaging, Automotive, Construction, Footwear End Use Industry: Consumer Goods, Electronics, Healthcare, Furniture Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | Aica Kogyo Co Ltd, Arkema Group, Dow, Henkel AG & Co KGaA, NANPAO RESINS CHEMICAL GROUP, CEMEDINE Co Ltd, H B Fuller Company, OKONG Corp, Selic Corp Public Company Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific EVA Adhesives Market Strategic Shifts
Formulation chemistry and compliance architecture are converging to redefine competitive advantage, with sustainability verification and processing efficiency emerging as the primary axes of supplier differentiation across the region.
Metallocene-catalyzed EVA copolymers are overtaking conventional Ziegler-Natta grades in high-speed packaging lines. Japanese converters operating 24-hour tissue and diaper lines are adopting these materials for their narrower molecular weight distribution and reduced char formation. The technology is compressing maintenance intervals and enabling thinner adhesive films without bond strength degradation.
Japan's METI enforcement of JIS standards restricting formaldehyde emissions from furniture adhesives is recalibrating formulation requirements for suppliers serving Japanese OEM manufacturing bases in Thailand and Vietnam. Woodworking operations exporting to Japan are reformulating with modified EVA systems to maintain market access, pushing regional compounders to establish JIS-certified production lines.
Direct mill relationships are displacing distributor networks for volume footwear and solar customers in Vietnam and India. Large OEMs are consolidating adhesive procurement through nominated supplier programs with technical service obligations, compressing the role of traditional trading houses. This pattern is most visible in Vietnam's northern provinces where Korean and Taiwanese footwear manufacturers have established captive sourcing offices.
Asia-Pacific EVA Adhesives Market Segmentation
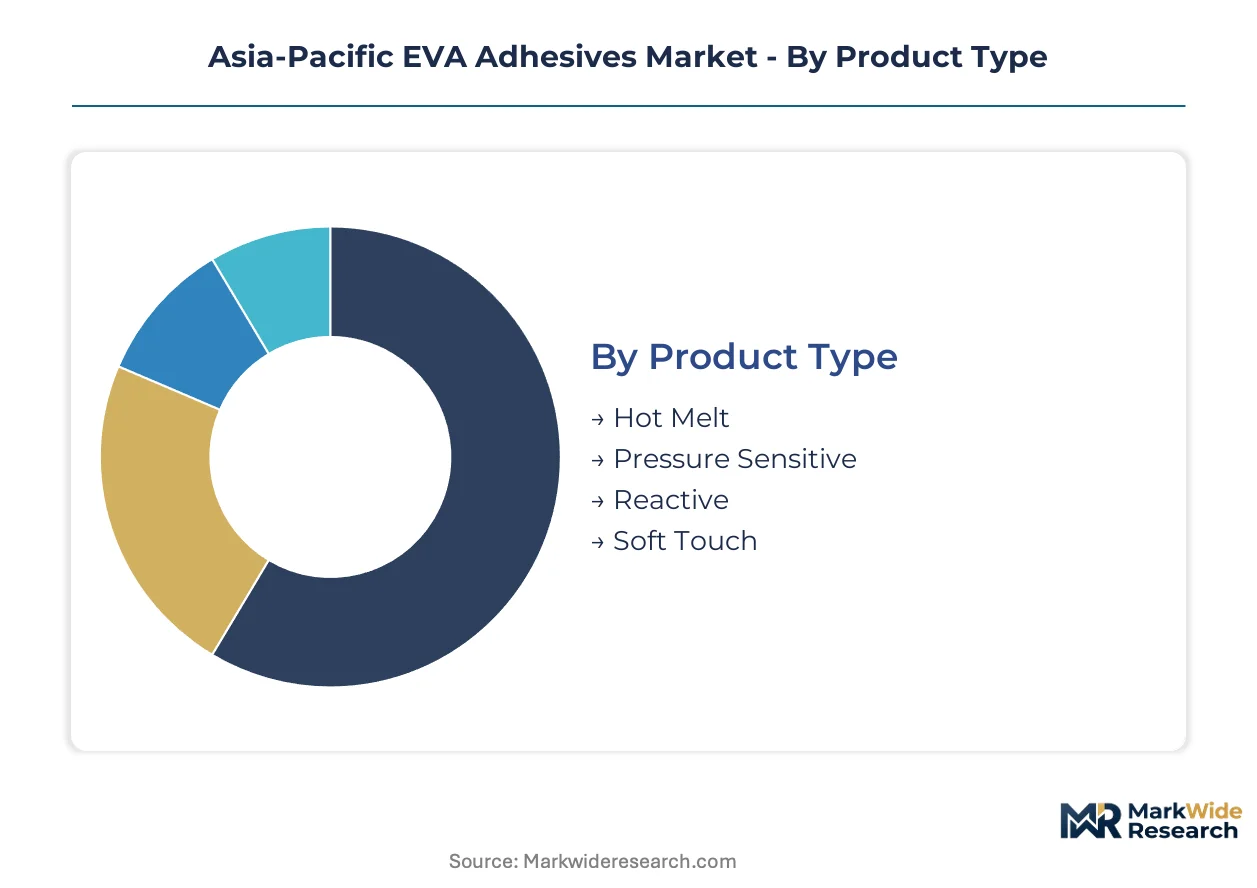
EVA adhesive formulations vary sharply in vinyl acetate content, tackifier loading, and melt viscosity specifications. These technical differences create distinct commercial lanes where suppliers specialize by curing chemistry and end-use performance requirements rather than competing across all categories.
Product Type:
Standardization dominates commodity grades while reactive and specialty systems command formulation customization and technical service bundling.
- Hot Melt:Solvent-free thermoplastic systems with 18-40% vinyl acetate content cure through rapid cooling on high-speed packaging lines. Vietnam's northern industrial provinces concentrate demand as Korean and Taiwanese footwear OEMs relocate assembly operations from southern China, pulling volume for bonding shoe uppers and insoles.
- Pressure Sensitive:Permanently tacky formulations with balanced peel and shear adhesion bond on contact without activation. South Korean and Japanese electronics manufacturers drive consumption for smartphone component mounting and display lamination where repositionability matters.
- Reactive:Moisture-cure or UV-triggered systems deliver structural strength for load-bearing applications.
- Soft Touch:Low-modulus grades with enhanced flexibility serve skin-contact and cushioning applications.
Most installed capacity flows through Hot Melt. Expansion is steepest in Pressure Sensitive.
Application:
Volume scales inversely with performance certification requirements across these four end-use clusters.
- Packaging:Case sealing and carton closing operations consume the largest tonnage of commodity hot melt grades. India's e-commerce fulfillment centers and corrugated box plants in Maharashtra and Gujarat are scaling automated lines that demand consistent melt viscosity and clean machining characteristics.
- Automotive:Interior trim lamination and headliner bonding require low-VOC formulations meeting Japanese OEM specifications. Thailand's export-oriented vehicle assembly plants enforce JIS-compliant adhesive sourcing that filters down through tiered supplier networks.
- Construction:China's GB standards for building material emissions are forcing reformulation toward low-odor hot melt grades in flooring and panel applications.
- Footwear:Assembly-grade EVA hot melts bond synthetic uppers to rubber soles in Vietnam's concentrated manufacturing belt.
Packaging absorbs the highest absolute volume. Construction is climbing the fastest as regulatory substitution accelerates.
End Use Industry:
Customer technical sophistication and specification control intensity segment these four verticals.
- Consumer Goods:Diaper and tissue packaging lines in Japan operate 24-hour schedules demanding metallocene-catalyzed grades with reduced char formation. These converters prioritize adhesive reliability over unit cost given downtime penalties.
- Electronics:Smartphone and tablet manufacturers in Batam and Jakarta source pressure-sensitive tapes for component mounting and temporary fixation during assembly.
- Healthcare:Japan's aging-care product segments are capturing hygiene-grade EVA adhesives combining breathability with skin-contact compliance.
- Furniture:Woodworking operations exporting to Japan reformulate with modified EVA systems to meet METI-enforced JIS formaldehyde emission limits.
Consumer Goods channels the most mature volume base. Healthcare is gaining share fastest on demographic tailwinds.
Distribution Channel:
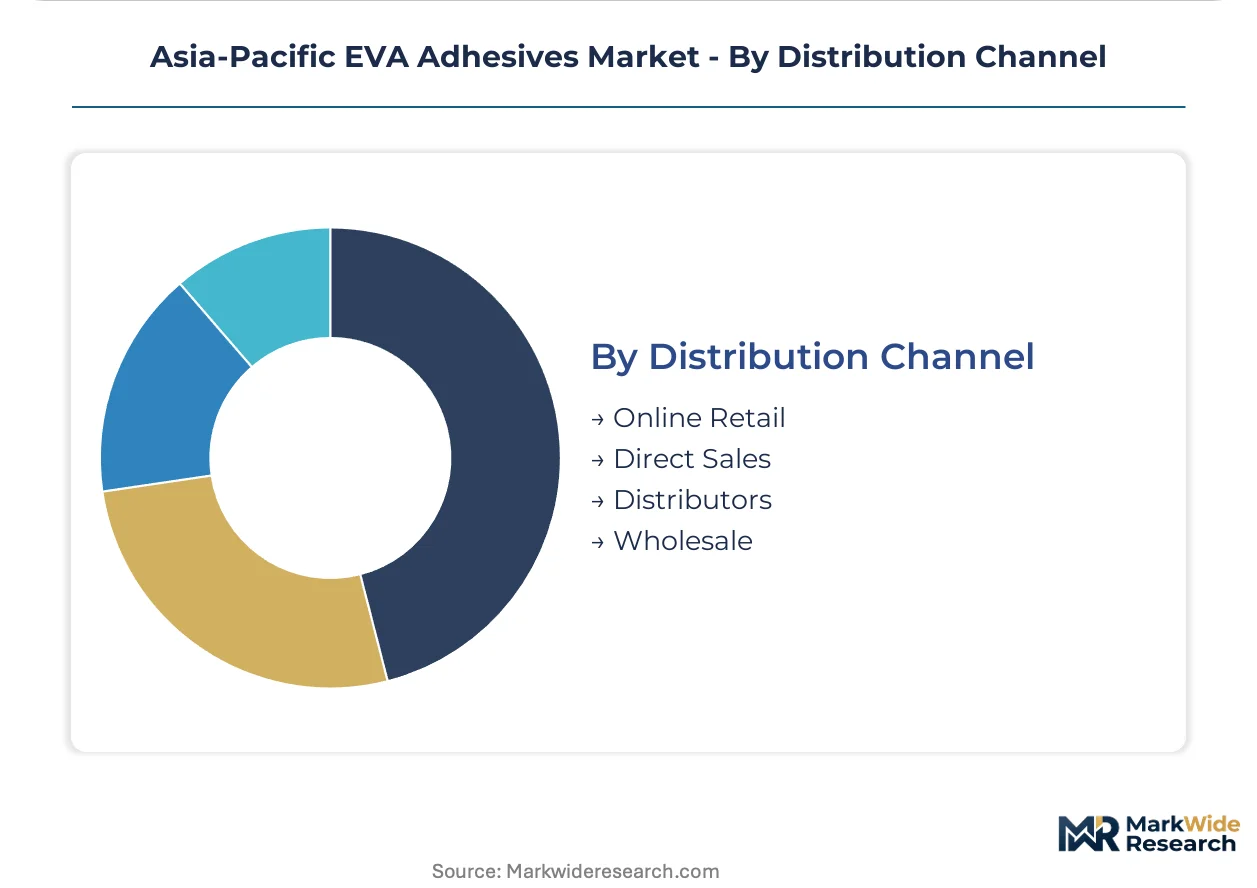
Direct relationships displace intermediaries as transaction sizes grow and technical service requirements intensify.
- Direct Sales:Large solar panel manufacturers in India and footwear OEMs in Vietnam consolidate procurement through nominated supplier programs with embedded technical service obligations. These arrangements compress traditional trading house margins.
- Distributors:Regional compounders with established BIS laboratory relationships in India navigate mandatory testing protocols for imported industrial chemicals.
- Online Retail:Small-batch specialty grades and maintenance supplies reach mid-scale converters through digital channels.
- Wholesale:Commodity hot melt pellets move through bulk handlers serving fragmented packaging converters.
Direct Sales commands the highest value concentration. Online Retail is expanding most quickly on small-lot convenience demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EVA adhesive manufacturing first scaled in Japan during the 1970s automotive boom, then migrated to South Korean petrochemical complexes in the 1990s. China's construction surge and India's solar expansion now anchor regional consumption patterns.
China
Construction material demand and photovoltaic module assembly dominate EVA adhesive consumption. GB standards issued by SAMR enforce tightening VOC thresholds for building adhesives certification. Manufacturing clusters in Guangdong and Jiangsu provinces are reformulating hot melt grades to meet low-odor specifications for flooring and panel applications.
India
Solar panel encapsulation and corrugated packaging automation drive formulation demand. BIS certification mandates for imported industrial chemicals extend registration timelines for foreign compounders. Production facilities in Maharashtra and Gujarat are scaling high-performance EVA grades for domestic photovoltaic manufacturers.
Japan
24-hour consumer goods packaging and automotive interior bonding sustain premium-grade consumption. METI enforces JIS standards restricting formaldehyde emissions from furniture and construction adhesives. Woodworking operations in Aichi and Shizuoka prefectures reformulate with modified EVA systems to maintain export market access.
Vietnam
Footwear assembly relocation from southern China concentrates demand for bonding applications. The country's national industrial chemical regulator maintains import testing protocols that favor established compounders. Northern industrial provinces around Hanoi and Hai Phong host Korean and Taiwanese OEMs operating nominated supplier programs.
South Korea
Electronics pressure-sensitive tapes and display lamination applications drive specialty grade consumption. MFDS oversees chemical substance registration for adhesives used in medical and skin-contact products. Manufacturing complexes in Gyeonggi-do and Chungcheong provinces supply metallocene-catalyzed copolymers for high-speed packaging lines.
Asia-Pacific EVA Adhesives Market Competitive Environment
The competitive structure tilts toward integrated petrochemical groups with captive ethylene-vinyl acetate resin supply. Mid-scale compounders lacking backward integration face margin compression from feedstock volatility and reformulation costs. Three archetypes dominate: Korean petrochemical majors with resin-to-adhesive integration, European multinationals bundling technical service with specialty formulations, and regional Asian compounders leveraging distributor relationships for compliance navigation. Capacity expansion and direct mill procurement programs represent the primary competitive moves reshaping channel relationships.
Among integrated material suppliers, Dow exemplifies the resin-backed cost leadership archetype through its ethylene-vinyl acetate supply chain control. Henkel AG & Co KGaA occupies a position within the specialty formulation tier, bundling automotive bonding expertise with OEM specification navigation. NANPAO RESINS CHEMICAL GROUP anchors the regional compounder segment, extending from Taiwan's domestic electronics assembly base into Southeast Asian markets through established distributor networks and compliance relationships.
| Leading Market Players |
|---|
| Aica Kogyo Co Ltd |
| Arkema Group |
| Dow |
| Henkel AG & Co KGaA |
| NANPAO RESINS CHEMICAL GROUP |
| CEMEDINE Co Ltd |
| H B Fuller Company |
| OKONG Corp |
| Selic Corp Public Company Limited |
| Others |
Value Chain & Pricing Dynamics
China's GB standards for construction material emissions gate qualified supply and premium-tier pricing access, forcing compounders to absorb reformulation costs or surrender certification-eligible segments to integrated resin producers. Buyers without JIS-compliant sourcing face automatic disqualification from Japanese OEM nominated supplier programs, compressing their addressable market to commodity grades where price competition intensifies.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified formulations for Japanese automotive OEMs from GB-compliant construction grades and uncertified commodity hot melts. Price differentiation rests on certification tier and volume scale, with solar encapsulation contracts commanding premium positioning due to technical service bundling. Cost compression in standard-grade packaging adhesives is intensifying because ethylene feedstock volatility squeezes non-integrated compounders. Small-scale Vietnamese footwear converters exhibit highest price sensitivity, while Indian photovoltaic manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with South Korean and Thai petrochemical complexes that anchor Asian EVA copolymer production. Raw material dependencies center on ethylene derived from naphtha cracking, tackifier resins from rosin and hydrocarbon feedstocks, and metallocene catalyst systems for specialty grades. Supply chain risk concentrates in geographic chokepoint exposure from plant outages or export restrictions at these production clusters. Distribution runs through direct mill relationships for large solar and footwear OEMs, with regional compounders leveraging established BIS laboratory partnerships to navigate India's import testing protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where China's GB standards milestone is accelerating substitution demand and reshaping supplier viability thresholds.
For Market Incumbents: Deepen backward integration into ethylene supply to defend margin position against naphtha price volatility, while establishing JIS-certified production lines in Thailand and Vietnam to capture Japanese OEM sourcing consolidation. Dow and Korean petrochemical majors threaten non-integrated compounders with cost leadership in reformulated low-VOC grades. For New Entrants and Emerging Players: Distributor partnerships with established BIS testing relationships offer the fastest path through India's mandatory import protocols, unlocking stranded volume for compounders lacking laboratory networks. Indonesian electronics assembly clusters in Batam and Jakarta represent the most penetrable white space, with pressure-sensitive tape formulations for smartphone component mounting offering technical differentiation without resin-scale capital requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Southeast Asian compounders with compliant distribution networks but lacking captive resin supply, as feedstock volatility discounts their earnings stability. Long-term viability over the projection horizon favors targets with dual JIS and GB certification capabilities. The signal to watch is nominated supplier program consolidation among Vietnamese footwear OEMs, which will compress trading house margins and force distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Supply | Captive naphtha cracking capacity insulates margin from crude-linked feedstock volatility affecting Korean and Thai competitors. |
| JIS-Certified Production Line Establishment | Thailand and Vietnam facilities secure access to Japanese OEM automotive interior bonding specifications enforced by METI. |
| Long-term Supply Agreement with Photovoltaic Manufacturers | Indian solar encapsulation contracts anchor volume through BIS-compliant domestic compounding relationships in Maharashtra. |
| Joint Venture with Regional Distributor Networks | BIS laboratory partnerships in India accelerate product registration timelines that strand inventory for foreign compounders. |
| Green Manufacturing Transition | EU Green Deal carbon documentation creates first-mover advantage for Thai and Malaysian exporters with verified low-intensity resin sourcing. |
Study Parameters
Multiple input streams — primary interviews with adhesive R&D directors, procurement leads at Indian solar manufacturers, and Vietnamese footwear OEM sourcing managers; secondary validation through customs trade data, SAMR GB standards documentation, and BIS certification registries; plus SEC filings from integrated petrochemical groups — were reconciled through bottom-up and top-down triangulation. Technical specifications from JIS and METI enforcement notices supplemented formulation requirement modeling.
Data-stream reconciliation across product type, vinyl acetate content tier, end-use industry, and regional regulatory cluster dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from segment-level elasticity modeling against ethylene feedstock price scenarios and solar installation forecasts. Industry-specific inputs included metallocene catalyst adoption rates in Japanese packaging lines and footwear production relocation patterns from southern China to Vietnam's northern provinces.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ethylene-naphtha spread volatility, GB standards enforcement intensity, and Japanese OEM supplier consolidation timing. Forecasts reflect documented assumptions about regulatory divergence and feedstock market structure. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Anaerobic Adhesives and Sealants Market
Adhesives & Sealants
Low VOC Adhesive Market
Adhesives & Sealants
South America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
South America Waterborne Adhesives Market
Adhesives & Sealants
Middle-East and Africa Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Germany Sealants Market
Adhesives & Sealants
Epoxy Glue Market
Adhesives & Sealants
Electric Vehicle Adhesives and Sealants Market
Adhesives & Sealants
Middle East and Africa Epoxy Curing Agents Market
Adhesives & Sealants
Global Ceramic Adhesives Market
Adhesives & Sealants
North America Bone Glue Market
Adhesives & Sealants
Global Tissue Sealants Market
Adhesives & Sealants
Global Cyanoacrylate Adhesives Market
Adhesives & Sealants
Curing Adhesives Market
Adhesives & Sealants
Specialty Adhesives Market
Adhesives & Sealants
United States Sealants Market