
 Middle-East and Africa Cyanoacrylate Adhesives Market | 2026-2036
Middle-East and Africa Cyanoacrylate Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Cyanoacrylate Adhesives Market Foresight
Skilled polymer chemist availability is unwinding across the Middle-East and Africa, forcing manufacturers to restructure technical service networks. Henkel AG & Co. KGaA anchors its regional position through localized compounding facilities in the UAE. 3M competes by leveraging global formulation libraries adapted for high-temperature Gulf-state assembly conditions. Sika AG extends its construction-adhesive expertise into industrial cyanoacrylate lines for infrastructure maintenance contracts.
Cyanoacrylate adhesives are single-component, fast-curing thermoplastic resins that polymerize on contact with trace moisture, achieving handling strengths within seconds and full cure in 24 hours at ambient temperatures. These adhesives bond dissimilar substrates including metals, plastics, rubber, and ceramics without primers, serving critical joining functions in automated manufacturing and field repair operations. Instant Adhesives dominate volume shipments due to their ubiquity in electronics assembly and consumer repair applications, while Medical Devices represents the fastest-expanding end-user category as Gulf-state health infrastructure localizes disposable instrument production. Gap-Filling Adhesives command premium positioning in automotive panel bonding where substrate alignment tolerances exceed standard cyanoacrylate gap specifications.
Saudi Food and Drug Authority and South African Health Products Regulatory Authority frameworks govern medical-grade adhesive biocompatibility testing, while Gulf Standardization Organization technical regulations enforce industrial chemical labeling and workplace exposure limits across GCC member states. These overlapping compliance requirements create differentiated product tiers that separate export-qualified formulations from domestic-general grades. Stakeholders must monitor harmonization progress between national standards bodies and the African Union's developing continental quality infrastructure framework to anticipate certification cost trajectories.
Market Dynamics
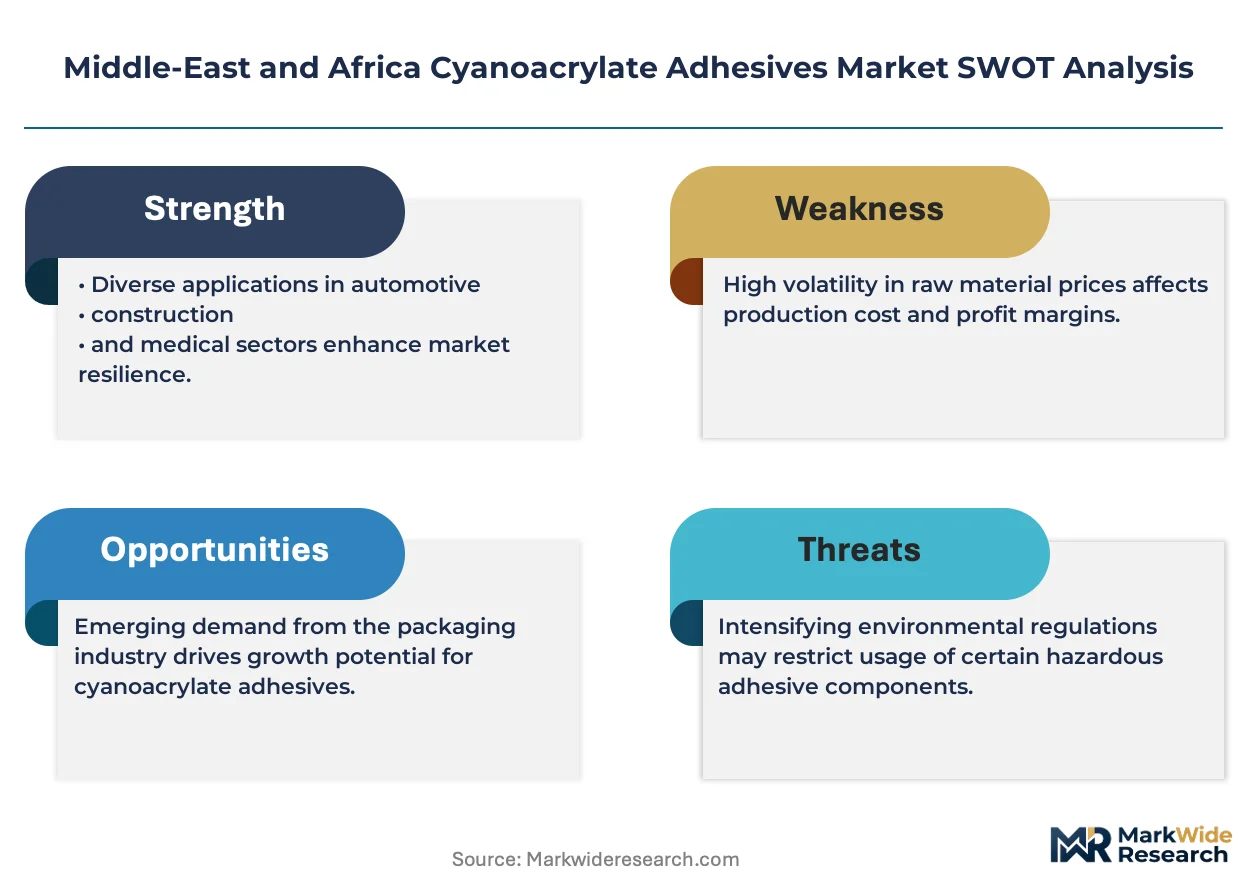
OEM localization across Moroccan and Egyptian automotive corridors is compressing adhesive supply chains, forcing formulation houses to establish compounding capacity within North African free-trade zones rather than serving via European distribution hubs.
Growth Catalysts
- SFDA Medical-Grade Certification:Saudi Food and Drug Authority biocompatibility frameworks are accelerating Gulf-state localization of disposable surgical instrument assembly, creating dedicated demand for ISO 10993-tested adhesive grades.
- Electronics Subcontracting Clusters:South Africa's precision manufacturing hubs in Gauteng and Western Cape are absorbing specialized cyanoacrylate formulations for medical device and consumer electronics component bonding.
- High-Temperature Formulation Adaptation:Gulf-state assembly conditions exceeding 45°C ambient temperatures are driving adoption of thermally stabilized cyanoacrylate variants for outdoor infrastructure maintenance contracts.
Market Restraints
- Ethyl Cyanoacrylate Feedstock Volatility:Regional dependence on Asian bulk monomer imports exposes formulators to freight cost swings and currency mismatch against dirham and rand-denominated contracts.
- REACH Alignment Costs:North African export corridors serving European automotive OEMs must maintain dual formulation inventories to satisfy ECHA registration requirements versus domestic-grade specifications.
- UV-Curable Acrylic Substitution:Electronics assemblers in South Africa are trialing light-curing alternatives for transparent substrate bonding where cyanoacrylate blooming risks optical clarity.
Strategic Opportunities
- Ethiopian Light Manufacturing Zones:Industrial park development around Addis Ababa and Hawassa offers first-mover positioning for adhesive technical service networks serving textile and leather goods exporters.
- Gulf Standardization Organization Harmonization:Pending technical regulation convergence across GCC member states would collapse six national certification regimes into unified product registration, reducing compliance overhead.
- Automated Dispensing Convergence:Integration of precision metering equipment with robotic assembly lines in Moroccan automotive plants enables adhesive consumption tracking and predictive replenishment contracts.
Industry Challenges
- Polymer Chemist Talent Scarcity:Skilled formulation specialists are unwinding across the Middle-East and Africa, forcing manufacturers to restructure technical service networks around remote European support models.
- African Union Quality Infrastructure Delays:Uncertain timelines for continental harmonization of adhesive testing standards complicate multi-country distribution strategies and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Cyanoacrylate Adhesives Market |
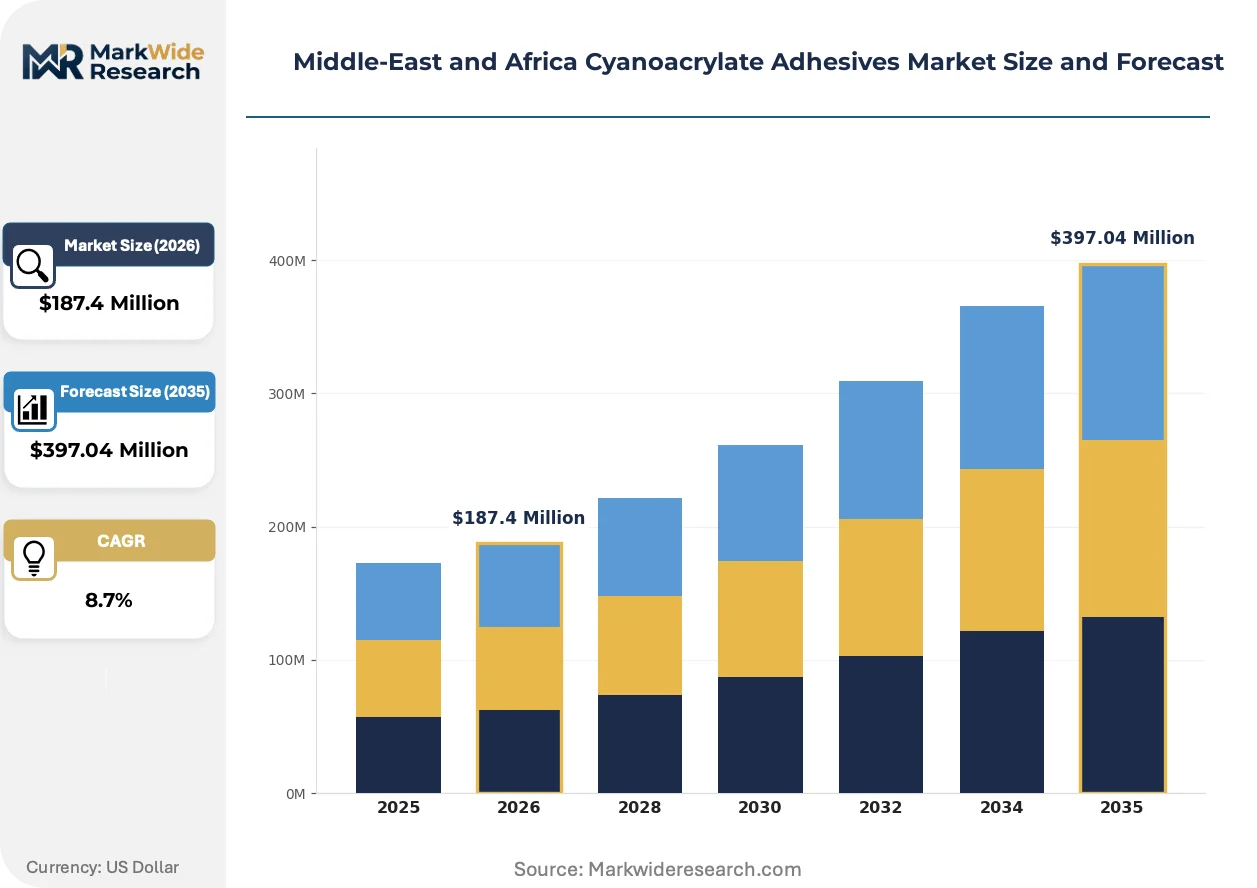
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Adhesives, Gap-Filling Adhesives, Specialty Adhesives, Low-Odor Adhesives End User: Automotive, Electronics, Woodworking, Medical Devices Packaging Type: Squeeze Bottles, Capsules, Syringes, Pumps Technology: UV-Cured, Anaerobic, Water-Soluble, Heat-Activated |
| Companies Covered | Henkel AG & Co. KGaA, 3M, Sika AG, Arkema Group, H.B. Fuller Company, Pidilite Industries Limited, Illinois Tool Works Inc., Toagosei Co., Ltd, Soudal Holding N.V., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Cyanoacrylate Adhesives Market Shifts & Advancements
Moisture-triggered curing chemistry is fragmenting into application-specific variants as end-users reject universal-grade formulations, while regulatory pressure on workplace exposure limits and biocompatibility testing is tightening product differentiation requirements.
Thermally stabilized cyanoacrylate formulations incorporating rubber-toughening modifiers are fragmenting the traditional instant-adhesive category. Automotive panel bonders in Egypt and Morocco are adopting these gap-tolerant variants for metal-to-plastic joints where thermal cycling exceeds standard-grade tolerances. The technology is fragmenting procurement patterns as buyers abandon single-grade contracts in favor of application-matched SKU portfolios.
Gulf Standardization Organization technical regulations on industrial chemical labeling and workplace exposure limits are tightening enforcement across Saudi Arabia, UAE, Kuwait, and Qatar. Formulators must now maintain separate documentation packages for GCC-export versus domestic-general grades, increasing product management overhead. Medical device assemblers in Dubai and Jeddah are responding by consolidating purchasing around suppliers with established SFDA and GSO dual-registration capabilities.
Consolidated procurement by multinational automotive OEMs is compressing supplier rosters across North African assembly corridors. Tier-1 component manufacturers in Tangier and Alexandria are shifting from spot purchasing to multi-year adhesive supply agreements with embedded technical service commitments. This concentration is most visible in Morocco's Renault-Nissan supplier park, where adhesive specification authority has centralized at platform-engineering level.
Middle-East and Africa Cyanoacrylate Adhesives Market Segmentation
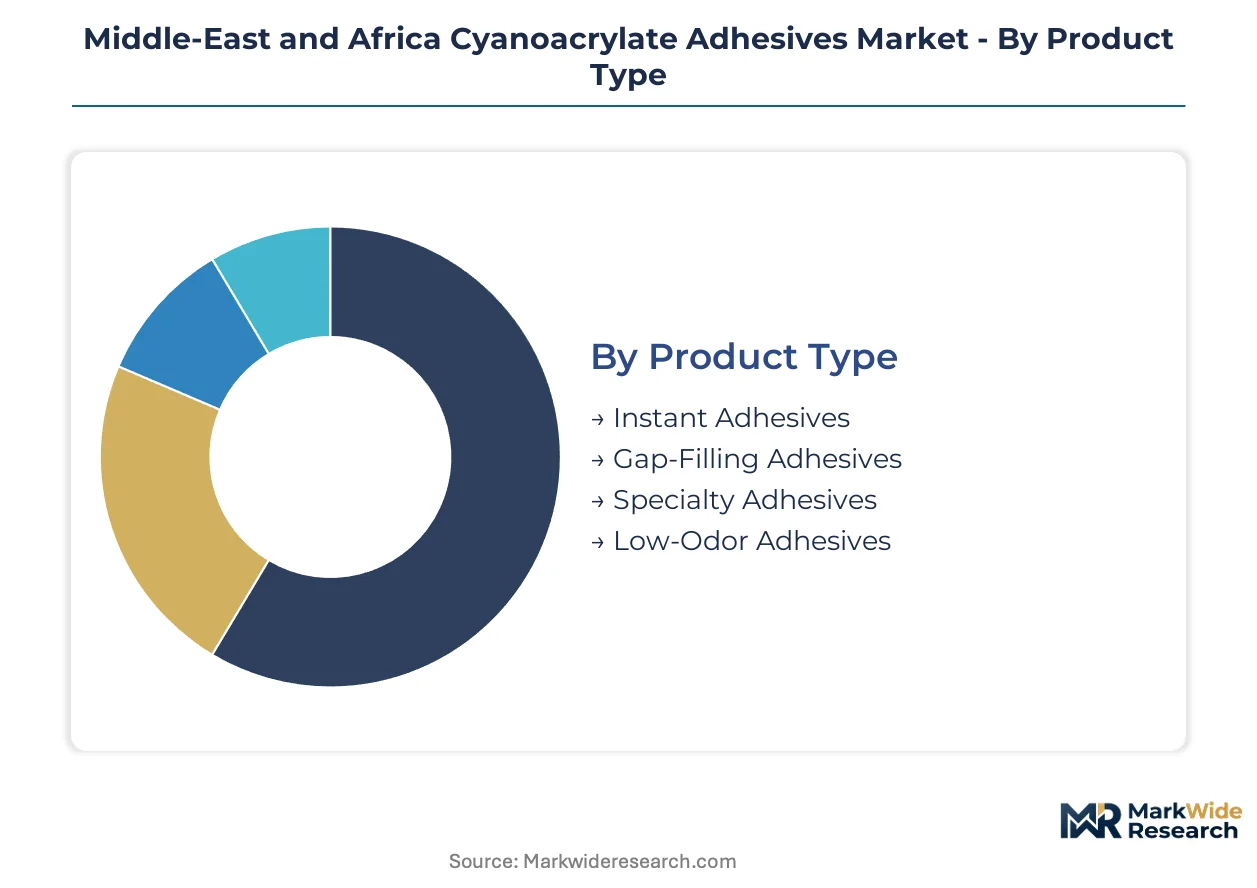
Channel strategy for cyanoacrylate adhesives in the Middle-East and Africa diverges sharply by segment. Technical grades flow through direct technical service networks, while commodity instant adhesives distribute through industrial chemical wholesalers serving fragmented repair and assembly operations.
Product Type:
Distribution intensity varies by formulation complexity, with high-performance grades requiring embedded application engineering support that commodity variants do not justify.
- Instant Adhesives:Ethyl and methyl cyanoacrylate formulations cure within seconds on trace moisture exposure, delivering handling strength for high-speed assembly lines. Electronics subcontractors in South Africa's Gauteng corridor absorb the largest volumes for consumer device component bonding, though UV-curable acrylic substitution is eroding share in transparent substrate applications.
- Gap-Filling Adhesives:Rubber-toughened variants tolerate substrate alignment tolerances up to 0.5mm, incorporating elastomeric modifiers to absorb thermal cycling stress. Automotive panel bonders in Morocco's Renault-Nissan supplier park and Egypt's Alexandria assembly corridor have adopted these formulations for metal-to-plastic joints where standard grades would craze or fracture.
- Specialty Adhesives:Custom-engineered formulations for extreme service conditions including cryogenic exposure or chemical immersion, serving oilfield maintenance contractors in Saudi Arabia and UAE.
- Low-Odor Adhesives:Butyl and octyl cyanoacrylate variants with reduced vapor pressure for confined-space assembly, penetrating medical device cleanrooms and electronics facilities with strict workplace exposure protocols.
Instant Adhesives dominates installed base. Gap-Filling Adhesives is where expansion concentrates as automotive localization accelerates across North African free-trade zones.
End User:
Customer concentration patterns split between multinational OEMs with centralized procurement authority and fragmented domestic assemblers purchasing through distribution.
- Automotive:Tier-1 component manufacturers in Tangier and Alexandria have shifted from spot purchasing to multi-year supply agreements with embedded technical service commitments. OEM localization across Moroccan and Egyptian corridors is compressing adhesive supply chains, forcing formulation houses to establish compounding capacity within North African free-trade zones rather than serving via European distribution hubs.
- Electronics:Precision manufacturing hubs in South Africa's Western Cape and Gauteng provinces absorb specialized formulations for medical device and consumer electronics component bonding, though UV-curable alternatives are gaining traction for optical clarity applications.
- Woodworking:Furniture and joinery operations across the Levant and East Africa, purchasing through regional chemical distributors with limited technical support requirements.
- Medical Devices:Disposable surgical instrument assemblers in Dubai and Jeddah are consolidating purchasing around suppliers with established SFDA and GSO dual-registration capabilities, climbing the fastest as Gulf-state health infrastructure localizes production.
Automotive commands the deepest technical engagement. Medical Devices is where regulatory certification creates the steepest supplier consolidation.
Packaging Type:
Packaging economics align with application scale and precision requirements, from high-volume squeeze bottles to single-use capsules for controlled dispensing environments.
- Squeeze Bottles:Standard 20-50g polyethylene containers for high-volume industrial assembly and field repair operations, dominating volume shipments through wholesale chemical distribution.
- Capsules:Single-dose aluminum-poly laminate pods for contamination-sensitive medical device assembly and aerospace maintenance applications.
- Syringes:Luer-lock compatible barrels for precision micro-dispensing in electronics and medical device cleanrooms, requiring calibrated needle gauge selection for controlled flow rates.
- Pumps:Metered-dose actuators for repetitive assembly station applications, integrating with automated dispensing equipment in Moroccan automotive plants.
Squeeze Bottles dominates unit volume. Syringes is where value-per-gram concentrates for precision manufacturing applications.
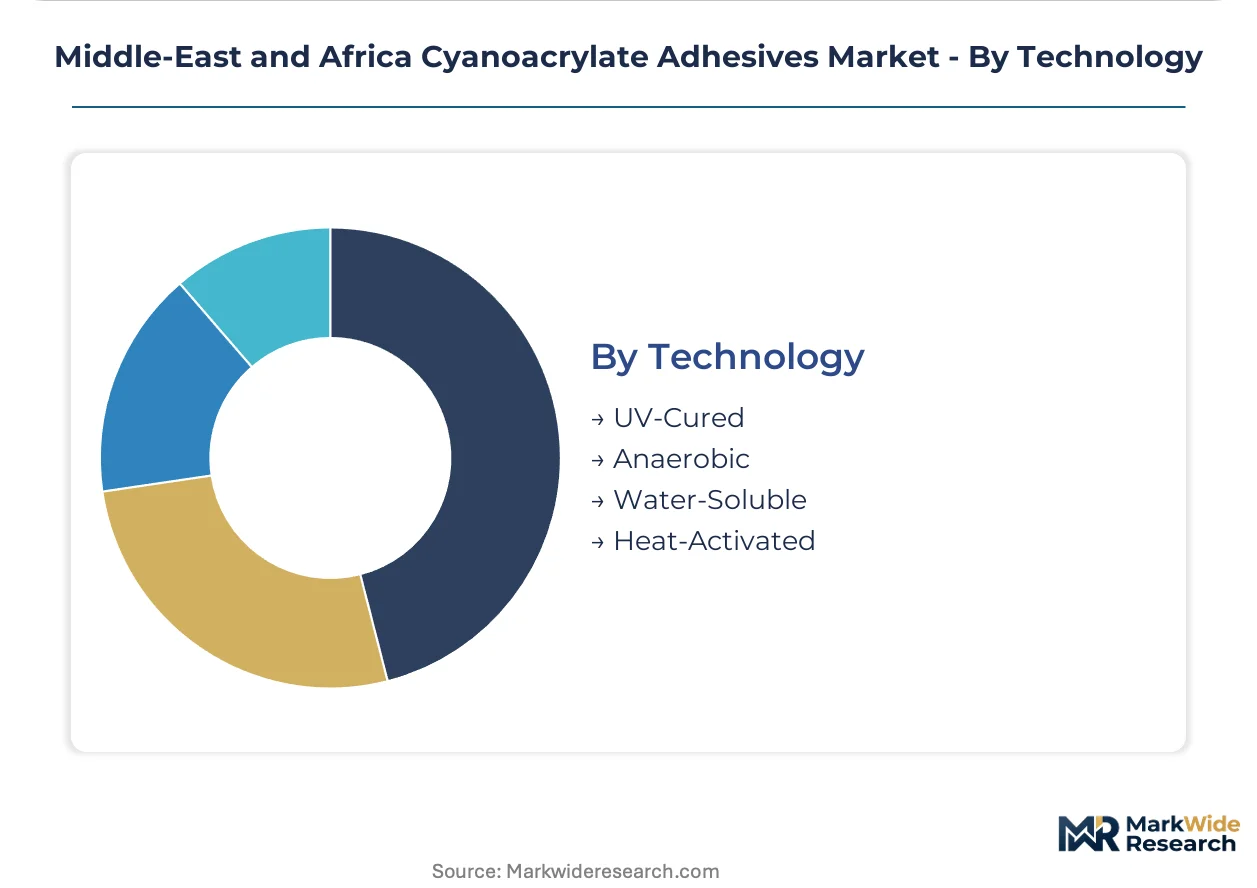
Technology:
Technology selection trades curing mechanism flexibility against substrate compatibility and production line integration requirements.
- UV-Cured:Photoinitiator-accelerated formulations polymerizing on 365nm exposure, enabling on-demand cure control for electronics assemblers trialing alternatives to moisture-cured systems where blooming risks optical clarity.
- Anaerobic:Metal-ion activated systems curing in oxygen-excluded joints, serving threaded fastener locking and cylindrical component retention in automotive and machinery maintenance.
- Water-Soluble:Removable formulations for temporary fixturing and textile bonding, penetrating Ethiopian light manufacturing zones around Addis Ababa and Hawassa.
- Heat-Activated:Latent catalyst systems requiring elevated temperature trigger, deployed in Gulf-state outdoor infrastructure maintenance where ambient conditions exceed 45°C and standard moisture-cured systems would skin over prematurely.
Moisture-cured cyanoacrylate chemistry dominates installed base. Heat-Activated variants are where thermal stabilization R&D concentrates for extreme climate deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA biocompatibility frameworks and GSO technical regulations anchor the Gulf states as the regulatory core of the Middle-East and Africa Cyanoacrylate Adhesives Market. Saudi Arabia and the UAE enforce the strictest chemical safety and medical-grade certification standards. These requirements cascade into formulation differentiation across North African export corridors and South African precision manufacturing hubs.
Saudi Arabia
Disposable surgical instrument assembly and outdoor infrastructure maintenance drive formulation demand. SFDA medical-grade certification mandates ISO 10993 testing for adhesives entering healthcare supply chains. Riyadh and Jeddah host medical device assemblers consolidating procurement around suppliers with dual SFDA-GSO registration capabilities.
United Arab Emirates
Localized compounding facilities and high-temperature assembly applications concentrate demand. GSO technical regulations on industrial chemical labeling and workplace exposure limits tighten enforcement across Dubai and Abu Dhabi. The UAE's free-trade zones attract formulation houses serving GCC re-export markets.
Morocco
Automotive panel bonding and metal-to-plastic joint applications absorb rubber-toughened cyanoacrylate variants. REACH alignment requirements for European automotive OEM exports force dual formulation inventories. Tangier's Renault-Nissan supplier park centralizes adhesive specification authority at platform-engineering level.
South Africa
Precision manufacturing for medical devices and consumer electronics consumes specialized formulations. The country's national pharmaceutical regulator enforces biocompatibility testing parallel to SFDA frameworks. Gauteng and Western Cape provinces absorb volumes for electronics subcontracting clusters.
Egypt
Automotive assembly line expansion and tier-1 component manufacturing drive adhesive consumption. Egyptian industrial chemical regulations are converging with GCC standards to facilitate export corridor access. Alexandria's assembly corridor has shifted from spot purchasing to multi-year supply agreements with embedded technical service.
Middle-East and Africa Cyanoacrylate Adhesives Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational chemical conglomerates controlling formulation libraries and regional distribution infrastructure. The market structure concentrates around three strategic archetypes: vertically integrated adhesive formulators with captive monomer supply, technical service specialists embedding application engineering at customer sites, and construction-adhesive houses extending into industrial lines. Competitive moves center on establishing compounding capacity within North African free-trade zones and consolidating technical service networks around remote European support models.
Within the integrated multinational tier, Henkel AG & Co. KGaA anchors regional positioning through localized compounding facilities in the UAE, while 3M occupies a position leveraging global formulation libraries adapted for extreme climate conditions. Sika AG represents the construction-to-industrial extension archetype, with its expertise in infrastructure maintenance contracts informing cyanoacrylate line development. These three companies exemplify the divergent geographic and segment strategies shaping competitive dynamics across the Middle-East and Africa.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M |
| Sika AG |
| Arkema Group |
| H.B. Fuller Company |
| Pidilite Industries Limited |
| Illinois Tool Works Inc. |
| Toagosei Co., Ltd |
| Soudal Holding N.V. |
| Others |
Supply & Pricing Matrix
Capacity utilization at Asian ethyl cyanoacrylate monomer plants shapes regional price floors across Middle-East and Africa formulation houses, compressing margins for distributors serving rand and dirham-denominated contracts while rewarding localized compounding investments in UAE free-trade zones.
Pricing Analysis
Price spreads between European REACH-compliant grades and domestic-general formulations widen across North African automotive corridors. Three-tier pricing structure across medical-grade, industrial-performance, and commodity-repair levels reflects SFDA certification costs and volume scale. Pricing pressure stems from Asian monomer freight volatility and currency mismatch exposure. Tier-1 automotive OEMs in Tangier and Alexandria exhibit lowest price sensitivity due to embedded technical service requirements, while fragmented woodworking assemblers in the Levant drive commodity-tier competition.
Supply Chain Analysis
Inventory lead times for ethyl cyanoacrylate monomer stretch across 60-90 day maritime corridors from Chinese and South Korean bulk producers. Regional formulation capacity concentrates in UAE, Saudi Arabia, and Morocco's free-trade zones. Raw material dependencies rest on Asian monomer imports, European rubber-toughening modifiers, and pharmaceutical-grade stabilizers. Single-source vulnerability from concentrated Asian monomer supply creates exposure to freight cost swings and port congestion. Distribution runs through direct technical service networks for high-performance grades and industrial chemical wholesalers for commodity instant adhesives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are fragmenting procurement authority across this market as multinational automotive OEMs centralize adhesive specification at platform-engineering level, collapsing supplier rosters and privileging formulators with embedded application engineering and GCC-wide registration capabilities.
For Market Incumbents: Consolidate technical service networks around remote European polymer chemist support models while establishing captive compounding capacity within Moroccan and Egyptian free-trade zones. Defend against UV-curable acrylic substitution in South African electronics assembly by accelerating thermally stabilized formulation R&D for Gulf-state infrastructure contracts.
For New Entrants and Emerging Players: Differentiate on Ethiopian light manufacturing zone penetration before technical service networks solidify around Addis Ababa and Hawassa textile clusters. Target medical device assemblers in Dubai and Jeddah seeking SFDA-GSO dual-registration suppliers. Pursue water-soluble formulation positioning for temporary fixturing applications in leather goods export operations.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among adhesive formulators with multi-year automotive supply agreements embedding predictive replenishment contracts and robotic dispensing integration. Long-term viability favors specialists with backward integration into monomer supply or captive rubber-toughening modifier production. Monitor African Union quality infrastructure harmonization timelines as signal for certification cost compression and multi-country distribution scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Localized Compounding Capacity | UAE free-trade zone facilities bypass Asian monomer freight exposure and compress lead times for GCC re-export markets. |
| SFDA-GSO Dual Registration | Consolidated certification packages reduce product management overhead for medical device assemblers in Riyadh and Jeddah. |
| Rubber-Toughened Formulation R&D | Thermal cycling tolerance captures automotive panel bonding contracts across Morocco's Renault-Nissan supplier park. |
| Automated Dispensing Integration | Precision metering equipment convergence enables predictive replenishment contracts with Moroccan Tier-1 manufacturers. |
| Ethiopian Technical Service Network | First-mover positioning in Hawassa and Addis Ababa industrial parks serves textile and leather goods exporters. |
Research Methodology
Initial hypotheses were tested against primary input from adhesive formulation chemists, automotive Tier-1 procurement directors, medical device quality assurance leads, and industrial chemical distribution channel managers, then refined against customs trade data, GCC standardization body filings, SEC 10-K disclosures from multinational chemical conglomerates, and automotive production databases. Bottom-up volume estimates from segment-level consumption patterns were triangulated against top-down market sizing derived from monomer import flows and formulation capacity utilization.
Variance decomposition across product type, end-use industry, packaging format, and regional production hub dimensions informed the analytical framework over the projection horizon. CAGRs were derived from segment-specific growth trajectories weighted by installed base and expansion pipeline visibility. Forecast inputs incorporated SFDA certification timeline acceleration, GSO harmonization progress, and UV-curable acrylic substitution rates in South African electronics assembly.
The analysis sits within stated boundaries; outcomes outside sustained Gulf-state infrastructure investment, African Union quality infrastructure convergence, or stable Asian monomer supply conditions would require recalibration. Forecasts reflect documented assumptions about regulatory enforcement intensity and OEM localization momentum. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Europe Hot-Melt Adhesives Market
Adhesives & Sealants
Aqueous Acrylic Binders Market
Adhesives & Sealants
Mexico Sealants Market
Adhesives & Sealants
Middle East and Africa Flock Adhesives Market
Adhesives & Sealants
Windscreen Adhesive Market
Adhesives & Sealants
North America Construction Adhesives and Sealants Market
Adhesives & Sealants
South Africa Adhesives Market
Adhesives & Sealants
North America Waterborne Adhesives Market
Adhesives & Sealants
Electric Vehicle Adhesives Market
Adhesives & Sealants
Glass Adhesive Market
Adhesives & Sealants
United Kingdom Sealants Market
Adhesives & Sealants
Acrylates Copolymer Market
Adhesives & Sealants
American Epoxy Adhesives Market
Adhesives & Sealants
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Removable Adhesive Market
Adhesives & Sealants
Russia Sealants Market