
 Compound Diclofenac Sodium and Chlorphenamine Maleate Tablets Market | 2026-2036
Compound Diclofenac Sodium and Chlorphenamine Maleate Tablets Market Size, Share, and Industry Trends Forecast 2026-2036
Compound Diclofenac Sodium and Chlorphenamine Maleate Tablets Market Insights
Multi-source API procurement is hardening as domestic manufacturers reduce reliance on imported diclofenac sodium intermediates. Beijing Shuguang Pharm leverages captive fermentation capacity for chlorphenamine precursors. Chengdu Tiantai Mount Pharmaceutical anchors western China supply through its Sichuan manufacturing base. Guangzhou Baiyunshan Mingxing Pharmaceutical dominates hospital tender channels in the Pearl River Delta.
Compound Diclofenac Sodium and Chlorphenamine Maleate Tablets combine a non-steroidal anti-inflammatory drug with a first-generation antihistamine, typically formulated as 25mg/2mg or 25mg/4mg immediate-release tablets for symptomatic relief of pain with allergic rhinitis. Sustained-release formulations command premium positioning due to modified-release polymer matrices that extend plasma concentration profiles. Immediate-release generics still occupy volume leadership in hospital formularies, though combination therapy segments gain traction in retail pharmacy channels where patient convenience drives substitution.
NMPA bioequivalence standards and China's GB pharmaceutical manufacturing norms shape product registration timelines and facility inspection intensity. The country's national pharmaceutical regulator enforces dissolution-profile matching for compound generic approvals, raising technical barriers for new entrants. Stakeholders must monitor evolving pharmacovigilance reporting requirements and anticipate how centralized procurement reforms reshape pricing power across hospital and retail segments.
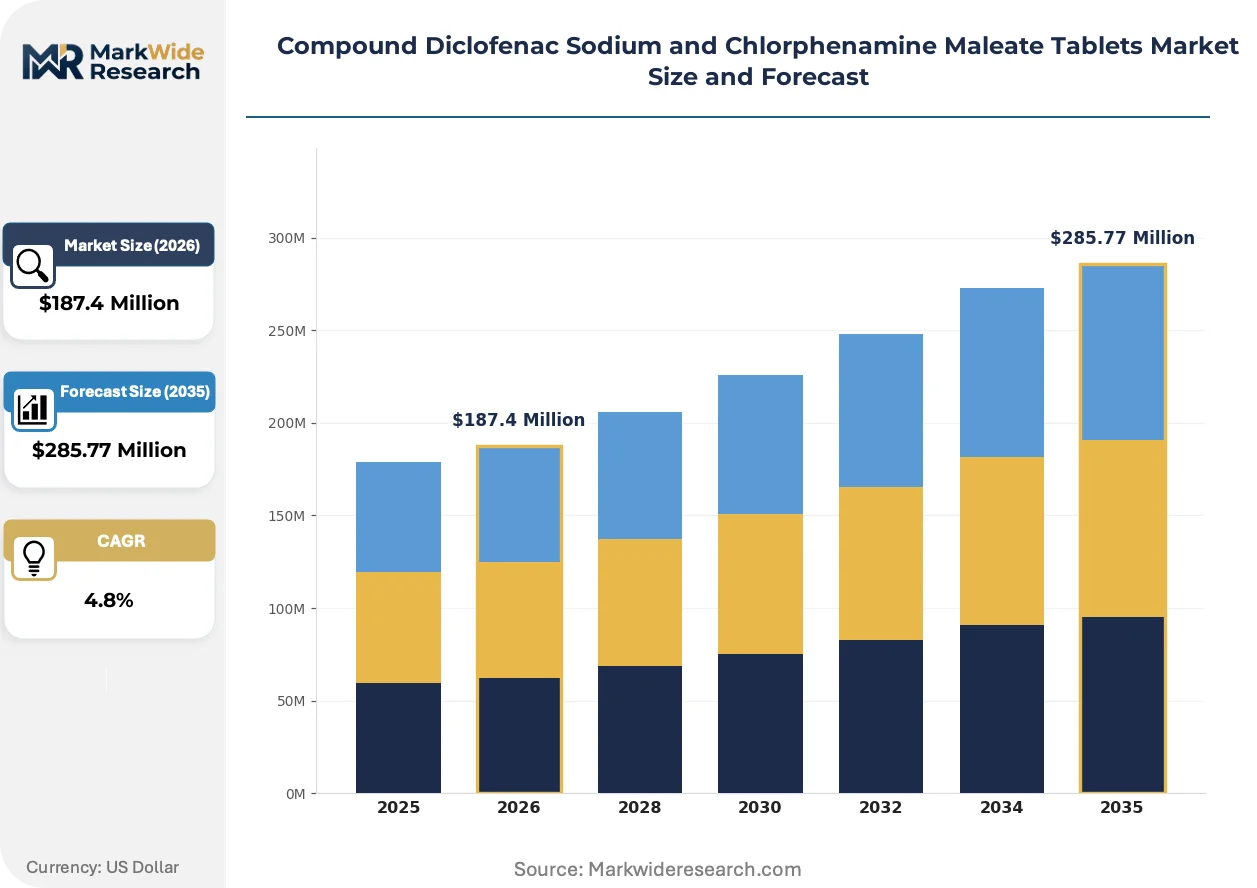
Market Dynamics
NMPA bioequivalence tightening for compound generics is compressing formulation timelines while pushing manufacturers toward sustained-release polymer matrix investments that extend plasma concentration profiles.
Growth Catalysts
- Emergency department protocols:Hospital outpatient settings are expanding combination analgesic-antihistamine stocking for rapid symptomatic relief. Procurement volumes through centralized tenders are rising.
- GB pharmaceutical manufacturing norms:Facility inspection standardization is consolidating quality-compliant production capacity. Registration timelines now favor manufacturers with pre-certified polymer modification capabilities.
- Pearl River Delta hospital clusters:Dense urban healthcare networks in Guangdong province are driving formulary adoption of immediate-release combination tablets through volume-based procurement channels.
Market Restraints
- API import dependency:Domestic diclofenac sodium intermediate supply remains concentrated among fermentation-based producers with captive precursor capacity.
- Dissolution-profile matching requirements:NMPA compound generic approvals demand exacting pharmacokinetic equivalence, raising technical barriers for new entrants without sustained-release expertise.
- First-generation antihistamine substitution:Second-generation H1 antagonists with reduced sedation profiles are displacing chlorphenamine in retail self-medication segments.
Strategic Opportunities
- Sichuan manufacturing base expansion:Western China pharmaceutical production capacity remains underdeveloped relative to eastern coastal demand density.
- Retail pharmacy channel migration:Patient convenience preferences are pulling combination therapy substitution from hospital outpatient to community pharmacy dispensing.
- Dual carbon goals alignment:MEE environmental compliance incentives favor fermentation-based chlorphenamine precursor production with lower carbon intensity profiles.
Industry Challenges
- Polymer matrix formulation expertise:Modified-release tablet development requires specialized talent in hydrophilic gel-forming excipient selection and dissolution kinetics modeling.
- Pharmacovigilance reporting infrastructure:Evolving adverse event documentation requirements demand upgraded IT systems for real-time signal detection across distributed manufacturing networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compound Diclofenac Sodium and Chlorphenamine Maleate Tablets Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immediate Release, Sustained Release, Combination Therapy, Generic Formulation: Tablet, Capsule, Oral Solution, Liquid End User: Hospitals, Clinics, Pharmacies, Home Care Therapy Area: Pain Management, Allergy Relief, Inflammatory Disorders, Respiratory Conditions |
| Companies Covered | Beijing Shuguang Pharm, Beijing Shuangji Pharmaceutical, Chengdu Tiantai Mount Pharmaceutical, Sichuan Yike Pharmaceutical, Zhongxing Pharmaceuticals, Guangzhou Baiyunshan Mingxing Pharmaceutical, Youhua Pharmaceutical, Jilin Wantong Pharmaceutical, Guangdong Huanan Pharmaceutical Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compound Diclofenac Sodium and Chlorphenamine Maleate Tablets Market Trends and Innovations
Formulation science advances and procurement centralization are reshaping how combination NSAID-antihistamine products reach hospital and retail channels.
Hydrophilic polymer matrix technology is absorbing manufacturing investment as the primary mechanism for diclofenac sodium sustained-release modification. Hospital formularies in eastern coastal provinces are adopting these formulations for reduced dosing frequency. The technology is absorbing premium positioning from immediate-release generics despite higher unit costs.
Centralized procurement reforms are compressing pricing power across hospital tender channels. Volume-based purchasing agreements now dominate public hospital procurement in China's eastern provinces. Generic manufacturers are responding with cost-engineered immediate-release formulations that sacrifice polymer complexity for tender compliance.
Patient-driven channel migration is fragmenting traditional hospital-centric distribution. Self-paying consumers in urban retail pharmacies are substituting combination tablets for separate NSAID and antihistamine purchases. This pattern concentrates in Guangdong and Jiangsu provinces where pharmacy chain density supports convenient access.
Compound Diclofenac Sodium and Chlorphenamine Maleate Tablets Market Segmentation
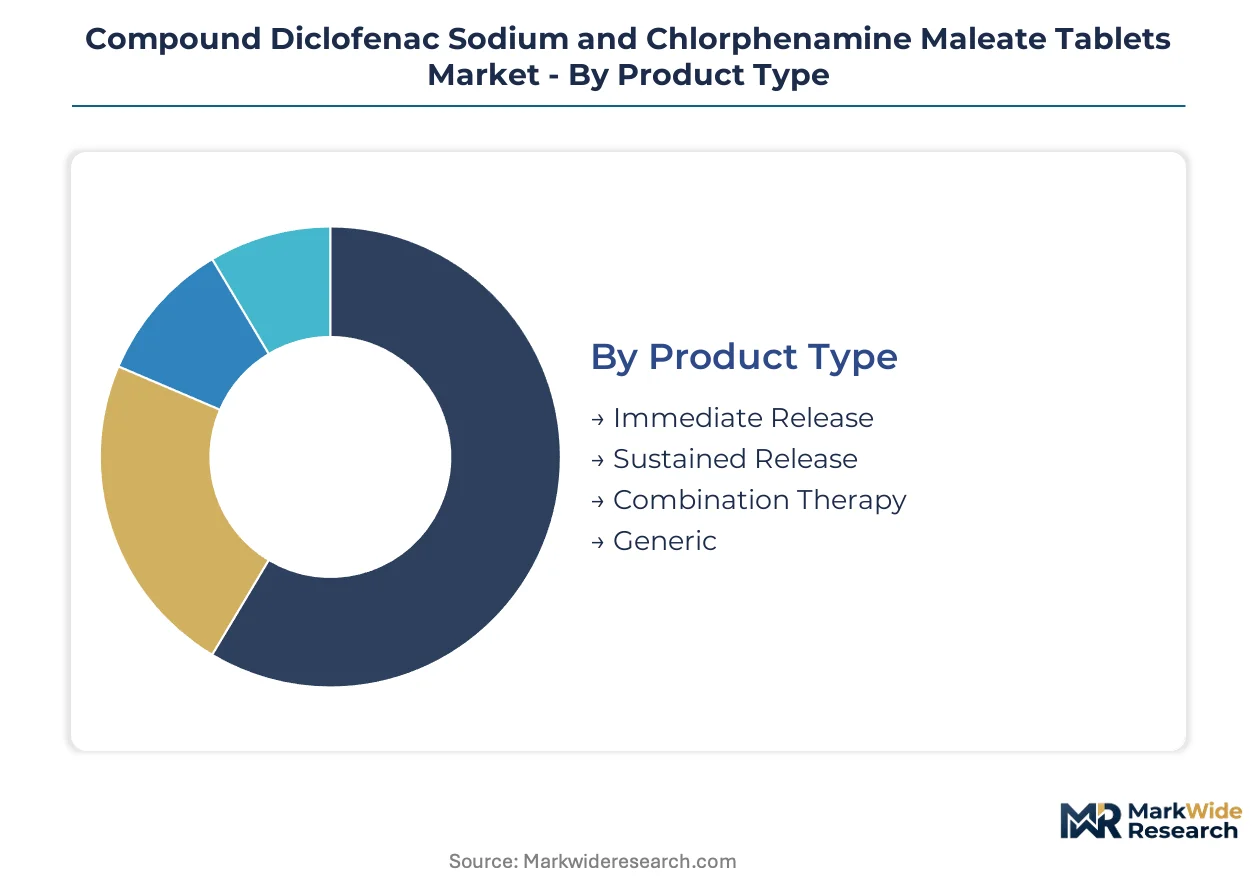
Product differentiation in this market hinges on release kinetics and procurement channel access. Buyers prioritize dosing convenience against reimbursement constraints.
Product Type:
Hospital procurement officers weight bioequivalence documentation against tender price floors when selecting release profiles.
- Sustained Release:Modified-release polymer matrices extend diclofenac plasma concentration over 8-12 hours, reducing dosing frequency. Eastern coastal hospital clusters in Jiangsu and Zhejiang provinces favor these formulations for outpatient pain protocols despite premium positioning.
- Immediate Release:Standard 25mg/2mg or 25mg/4mg tablets dissolve rapidly for acute symptomatic relief. Volume leadership concentrates in centralized procurement channels where Guangdong province tenders drive generic substitution.
- Combination Therapy:Fixed-dose NSAID-antihistamine pairings address concurrent pain and allergic rhinitis presentations.
- Generic:Unbranded equivalents compete on dissolution-profile matching under NMPA bioequivalence standards.
Immediate Release leads on scale; Sustained Release leads on momentum.
Formulation:
Manufacturing complexity separates oral solid dosage forms from liquid alternatives in facility certification requirements.
- Tablet:Direct compression and wet granulation methods dominate commercial production. GB pharmaceutical manufacturing norms govern hardness and friability specifications across domestic facilities.
- Capsule:Gelatin or HPMC shells accommodate taste-masked granules for pediatric-sensitive populations.
- Oral Solution:Liquid formulations serve dysphagia patients in geriatric home care settings.
- Liquid:Suspension-based delivery requires preservative systems meeting MEE environmental compliance for effluent discharge.
Tablet commands manufacturing volume; oral solution gains share in aging-population regions.
End User:
Channel economics determine whether products flow through centralized hospital tenders or retail pharmacy margins.
- Hospitals:Public institution procurement dominates volume through volume-based purchasing agreements. Sichuan and Shandong provincial health commissions set tender price ceilings that filter supplier pools.
- Clinics:Community health centers in urban districts stock immediate-release tablets for rapid turnaround.
- Pharmacies:Chain retailers in Guangzhou and Shenzhen exploit patient convenience preferences for combination therapy substitution.
- Home Care:Self-medication segments favor blister-packaged generics with clear dosing instructions.
Hospitals anchor procurement volume; pharmacies expand most quickly.
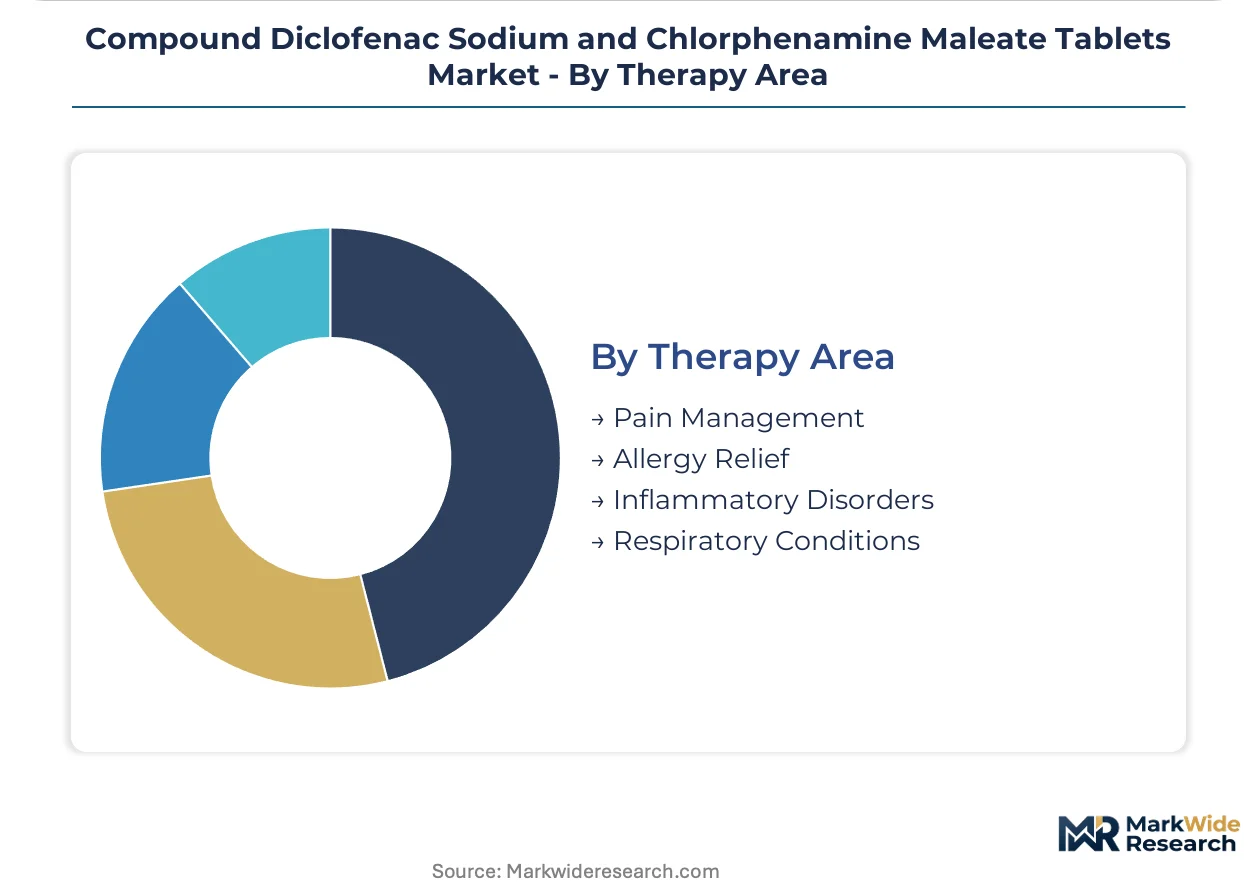
Therapy Area:
Clinical indication drives formulary placement against competing therapeutic classes.
- Pain Management:Post-operative and trauma-related analgesia protocols in emergency departments favor rapid-onset immediate-release formulations. NMPA pharmacovigilance requirements track NSAID gastrointestinal adverse events in this high-volume segment.
- Allergy Relief:First-generation antihistamine effects compete against second-generation H1 antagonists in retail self-selection. Chlorphenamine sedation profiles limit workplace-use adoption.
- Inflammatory Disorders:Rheumatoid arthritis maintenance therapy explores sustained-release dosing for overnight symptom control.
- Respiratory Conditions:Upper respiratory infection symptom complexes drive seasonal demand spikes in northern provinces.
Pain Management leads on scale; Allergy Relief faces steepest substitution pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pearl River Delta hospital clusters anchor procurement volume for combination analgesic-antihistamine therapies. NMPA bioequivalence standards and centralized procurement reforms reshape pricing power across provincial health systems. Manufacturing gravity concentrates in eastern coastal provinces where pharmaceutical distribution networks reach dense urban hospital clusters.
China
Volume-based procurement agreements dominate public hospital procurement in Guangdong and Jiangsu provinces. NMPA tightened dissolution-profile matching requirements for compound generic approvals, raising technical barriers for new entrants. Beijing-Tianjin-Hebei and Yangtze River Delta manufacturing bases supply immediate-release formulations to eastern coastal tender channels.
United States
FDA bioequivalence standards govern abbreviated new drug application pathways for diclofenac-containing combination products. Hospital outpatient settings stock immediate-release NSAID-antihistamine pairings for emergency department pain protocols. New Jersey and Pennsylvania pharmaceutical corridors host formulation development capacity for modified-release polymer matrices.
India
CDSCO manufacturing license requirements and state-level drug controller inspections shape facility certification timelines. Domestic API producers reduce reliance on imported diclofenac sodium intermediates through fermentation-based captive capacity. Gujarat and Maharashtra pharmaceutical clusters supply combination tablets to hospital procurement pools across western and southern states.
Germany
EMA centralized marketing authorization procedures govern combination fixed-dose products containing NSAID and antihistamine components. Hospital formularies in Bavaria and North Rhine-Westphalia favor sustained-release formulations for reduced dosing frequency. Baden-Württemberg manufacturing bases specialize in hydrophilic gel-forming excipient selection for modified-release tablets.
Japan
PMDA quality management system inspections enforce dissolution-profile standards for generic combination products. Kanto and Kansai region hospital networks procure immediate-release tablets for acute pain management protocols. Osaka-based pharmaceutical manufacturers develop polymer matrix expertise for extended plasma concentration profiles.
Compound Diclofenac Sodium and Chlorphenamine Maleate Tablets Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sustained-release polymer matrix specialization. The vendor base separates between fermentation-based API controllers and formulation-dependent tablet manufacturers. Three archetypes dominate: captive precursor producers with backward integration into chlorphenamine supply, tender-optimized immediate-release specialists, and polymer modification capability builders targeting premium hospital segments. Competitive moves concentrate on M&A for API security and strategic partnerships for sustained-release technology licensing.
Among Beijing-based pharmaceutical enterprises, Beijing Shuguang Pharm exemplifies captive fermentation capacity for antihistamine precursors. Chengdu Tiantai Mount Pharmaceutical occupies a position representing western China supply anchoring through Sichuan manufacturing infrastructure. Guangzhou Baiyunshan Mingxing Pharmaceutical sits within the tender-optimized tier, reflecting Pearl River Delta hospital channel dominance.
| Leading Market Players |
|---|
| Beijing Shuguang Pharm |
| Beijing Shuangji Pharmaceutical |
| Chengdu Tiantai Mount Pharmaceutical |
| Sichuan Yike Pharmaceutical |
| Zhongxing Pharmaceuticals |
| Guangzhou Baiyunshan Mingxing Pharmaceutical |
| Youhua Pharmaceutical |
| Jilin Wantong Pharmaceutical |
| Guangdong Huanan Pharmaceutical Group |
| Others |
Pricing and Supply Chain Analysis
MEE environmental compliance mandates govern effluent discharge standards for fermentation-based chlorphenamine precursor production, filtering qualified suppliers and gating access to premium-tier hospital procurement channels where sustained-release formulations command favorable positioning.
Pricing Analysis
Input-cost pass-through from diclofenac sodium intermediate supply determines margin structure across formulation tiers. Three-tier pricing structure across premium, standard, and economy levels separates sustained-release polymer matrix products from immediate-release generics and unbranded tenders. Cost compression in the immediate-release segment is intensifying because centralized procurement reforms in Guangdong and Jiangsu provinces enforce volume-based price ceilings. Retail pharmacy chains exhibit highest price sensitivity; hospital formulary committees with bioequivalence documentation requirements show lowest sensitivity.
Supply Chain Analysis
Chlorphenamine maleate precursor supply rests on domestic fermentation capacity concentrated in Sichuan and Hebei provinces, with diclofenac sodium API sourcing anchored in Shandong and Zhejiang manufacturing clusters. Key inputs span pharmaceutical-grade gelatin for capsule shells, hydroxypropyl methylcellulose for polymer matrices, and purified water systems meeting GB pharmaceutical manufacturing norms. Single-source vulnerability in fermentation-based antihistamine intermediate production creates concentration risk. Distribution runs through provincial pharmaceutical procurement platforms to hospital tender channels, with secondary flows reaching retail pharmacy chains via regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
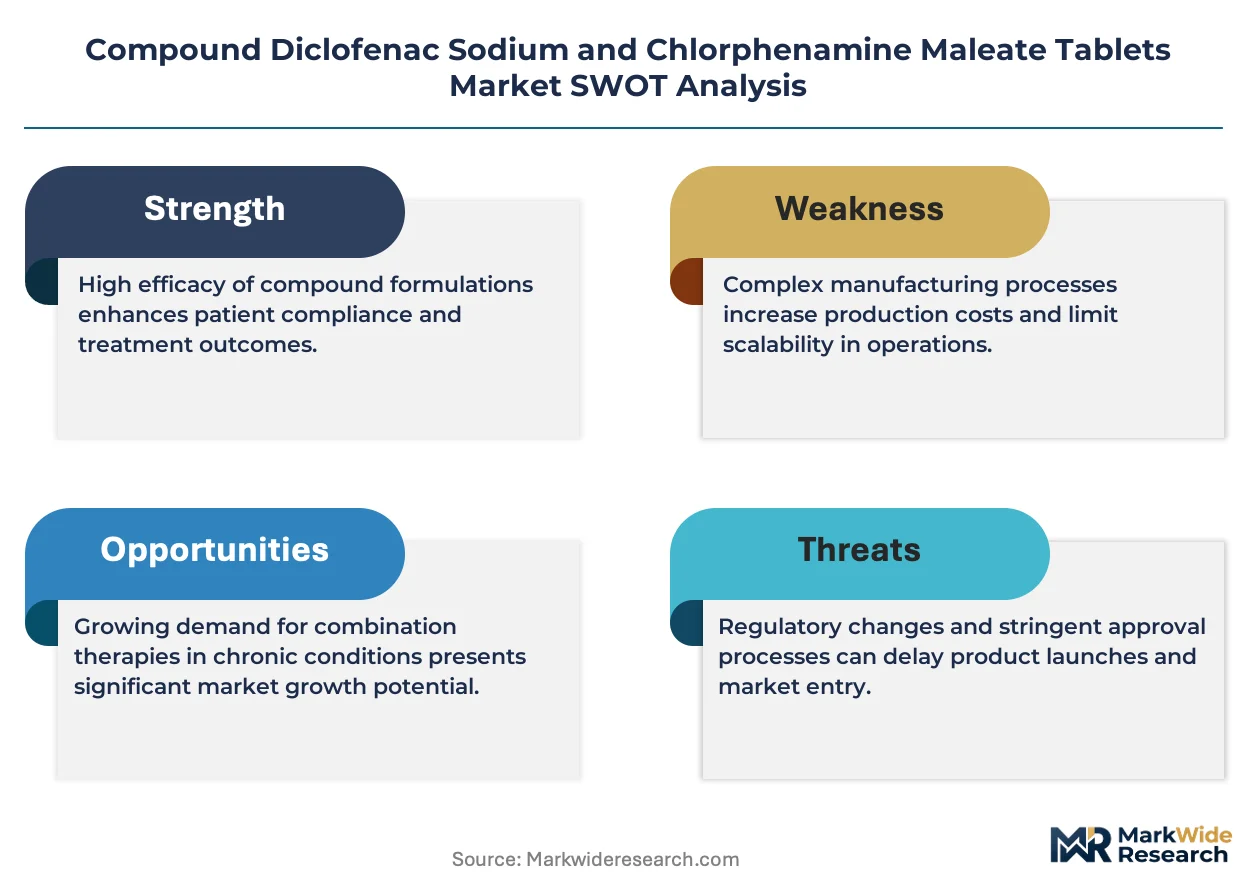
Margin expansion in this market hinges on polymer matrix formulation expertise that commands premium hospital positioning while fermentation-based API control insulates against input-cost volatility.
For Market Incumbents: Deepen captive precursor capacity for chlorphenamine maleate to reduce exposure to fermentation supply bottlenecks. Expand sustained-release polymer modification capabilities in Sichuan manufacturing bases to capture western China hospital tender growth. Second-generation H1 antagonist substitution in retail segments threatens immediate-release volume; defend through formulary lock-in with bioequivalence documentation. For New Entrants and Emerging Players: Retail pharmacy chains represent the most penetrable channel for combination therapy substitution away from hospital outpatient settings. Target community health centers in underdeveloped western provinces where tender competition remains less intense. Pursue white-label manufacturing partnerships with established Sichuan-based producers to bypass NMPA facility certification timelines. For Investors and Strategic Acquirers: Roll-up economics work for fermentation-based API specialists because regulatory barriers to new chlorphenamine precursor capacity create durable moats around existing producers. Long-term viability centers on polymer matrix formulation talent scarcity and hospital formulary stickiness. Watch NMPA bioequivalence standard tightening as the signal for sustained-release capability premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Matrix R&D Investment | Modified-release expertise unlocks premium hospital formulary placement in Jiangsu and Zhejiang provinces. |
| Fermentation Capacity Expansion | Captive chlorphenamine precursor production reduces import dependency and MEE compliance exposure. |
| Western China Manufacturing Footprint | Sichuan-based facilities anchor supply for underserved hospital clusters beyond Pearl River Delta density. |
| Retail Pharmacy Channel Partnership | Chain collaborations in Guangzhou and Shenzhen capture patient-driven combination therapy substitution. |
| NMPA Bioequivalence Pre-Certification | Early dissolution-profile matching investment accelerates compound generic approval timelines. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors combined with secondary validation against NMPA filings, provincial tender databases, GB pharmaceutical manufacturing standards, and customs trade records. Triangulation between demand-side volume signals and supply-side capacity announcements ensures consistency across estimation layers.
Input-output matrix framing connects diclofenac sodium intermediate availability to finished tablet production across immediate-release and sustained-release dosage forms. Segmentation dimensions span release kinetics, formulation type, procurement channel, and regional regulatory cluster. CAGRs derive from weighted average of historical tender volume trajectories and projected polymer matrix adoption curves across the analysis window. Forecast inputs incorporate NMPA bioequivalence approval timelines and MEE environmental compliance cost assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to centralized procurement pricing reforms and second-generation antihistamine substitution rates. Assumptions reflect current NMPA regulatory posture and MEE enforcement intensity. A small set of named triggers warrants ongoing watch: NMPA dissolution-profile standard revisions, MEE effluent discharge rule tightening, and Pearl River Delta hospital network consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Lignocaine/ Lidocaine Market
Pharmaceuticals
Global Prophylactic HIV Drugs Market
Pharmaceuticals
Global Acyclovir Market
Pharmaceuticals
Tunisia Pharmaceutical Market
Pharmaceuticals
Proton Pump Inhibitors Market
Pharmaceuticals
Antimalarial Drugs Market
Pharmaceuticals
Unfractionated Heparin Market
Pharmaceuticals
Global Non-Alcoholic Fatty Liver Disease (NAFLD) Drug Market
Pharmaceuticals
Pembrolizumab Market
Pharmaceuticals
Trisenox Market
Pharmaceuticals
Pharmaceuticals Lipids Market
Pharmaceuticals
Asia-Pacific Contraceptives Market
Pharmaceuticals
High Potency API Contract Manufacturing Market
Pharmaceuticals
OTC Topical Drugs Market
Pharmaceuticals
North America Pharmaceutical Warehousing Market
Pharmaceuticals
Global Psoriasis Drugs Market