
 India Over-The-Counter Drugs (OTC) Market | 2026-2036
India Over-The-Counter Drugs (OTC) Market Size, Share, and Industry Trends Forecast 2026-2036
India Over-The-Counter Drugs (OTC) Market Foresight
Subscription-based wellness programs bundled with chronic-condition monitoring is realigning how OTC portfolios get structured in India. Sun Pharmaceutical Industries Ltd. leverages its dermatology heritage to dominate skin-care OTC extensions. Dr. Reddy's Laboratories Ltd. anchors gastrointestinal and pain-management categories through pharmacy-first distribution. Cipla Ltd. competes in respiratory OTC through inhaler-to-capsule format transitions.
Over-the-counter drugs are pharmaceutical formulations approved for direct consumer purchase without prescription, typically containing active ingredients at standardized dosages such as ibuprofen, paracetamol, or ranitidine, manufactured through wet granulation or direct compression methods for oral delivery. Their primary commercial purpose is enabling self-treatment of common, self-limiting conditions while reducing healthcare system burden. Pain relievers occupy the largest revenue pool given habitual repurchase patterns across urban and semi-urban pharmacies. Cough and cold medications generate seasonal spikes that strain cold-chain logistics during monsoon quarters. Allopathic formulations sustain margin leadership against herbal alternatives due to faster perceived efficacy and stronger physician endorsement carryover.
CDSCO governs OTC switches and manufacturing standards under the Drugs and Cosmetics Act, while FSSAI asserts jurisdiction over nutraceutical-borderline products, creating compliance complexity for combination formats. BIS certification requirements for packaging materials add cost layers that disproportionately affect regional entrants against national brands. Stakeholders must monitor how regulator coordination between CDSCO and FSSAI resolves category-boundary disputes for vitamin-mineral combinations.
Market Dynamics
The CDSCO's streamlined OTC classification framework is compressing approval timelines and reshaping how manufacturers restructure prescription-to-OTC switch portfolios. This regulatory momentum is accelerating competitive entry into pain management and dermatology extensions.
Growth Catalysts
- CDSCO Switch Framework:The regulator's clarified OTC pathways reduce documentation burdens for prescription drugs seeking non-prescription status. Domestic manufacturers leverage this to expand analgesic and antacid portfolios.
- Rural Pharmacy Networks:Maharashtra and Gujarat hinterlands exhibit expanding self-medication adoption through kirana-to-pharmacy channel upgrades. Distributors report rising SKU velocity for cough-cold combinations in these corridors.
- Active Pharmaceutical Ingredient Localization:India's PLI scheme for bulk drugs is reducing import dependence on Chinese paracetamol and ibuprofen intermediates. Formulators secure cost advantages for standard-dosage tablets.
Market Restraints
- API Input Volatility:Paracetamol and ibuprofen intermediate prices fluctuate with Chinese environmental enforcement cycles. Margin compression hits regional generic manufacturers without backward integration into API synthesis.
- Regulatory Jurisdiction Overlap:CDSCO and FSSAI assert competing authority over vitamin-mineral combinations and nutraceutical-borderline formats. Compliance costs escalate for combination products facing dual scrutiny.
- Herbal Substitution Threat:Ayurvedic practitioners and Dabur-backed traditional formulations capture price-sensitive segments in Kerala and Tamil Nadu. Allopathic brands face physician endorsement erosion in these strongholds.
Strategic Opportunities
- Chronic Condition Monitoring Bundles:Subscription wellness programs integrating glucose tracking with metformin-adjacent OTC supplements open recurring revenue streams. Mumbai and Bengaluru insurers pilot these hybrid offerings.
- Inhaler-to-Capsule Format Convergence:Respiratory OTC players transition pressurized metered-dose inhalers toward dry-powder and soft-gel alternatives. This technology shift reduces cold-chain dependency and expands tier-3 distribution feasibility.
- BIS Packaging Certification Gap:National brands with certified blister-foil and bottle suppliers command retail shelf preference. Regional entrants face 8-12 month BIS approval delays that create temporary supply windows.
Industry Challenges
- Pharmacovigilance Talent Scarcity:CDSCO mandates adverse-event reporting for all OTC switches, yet qualified safety-data specialists concentrate in Hyderabad and Mumbai. Tier-2 manufacturers struggle to build compliant surveillance units.
- Legacy ERP Integration:Family-owned pharmacy distributors in Gujarat and Rajasthan operate on decade-old inventory systems. Real-time stock visibility for seasonal cough-cold surges remains operationally fractured.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Over-The-Counter Drugs (OTC) Market |
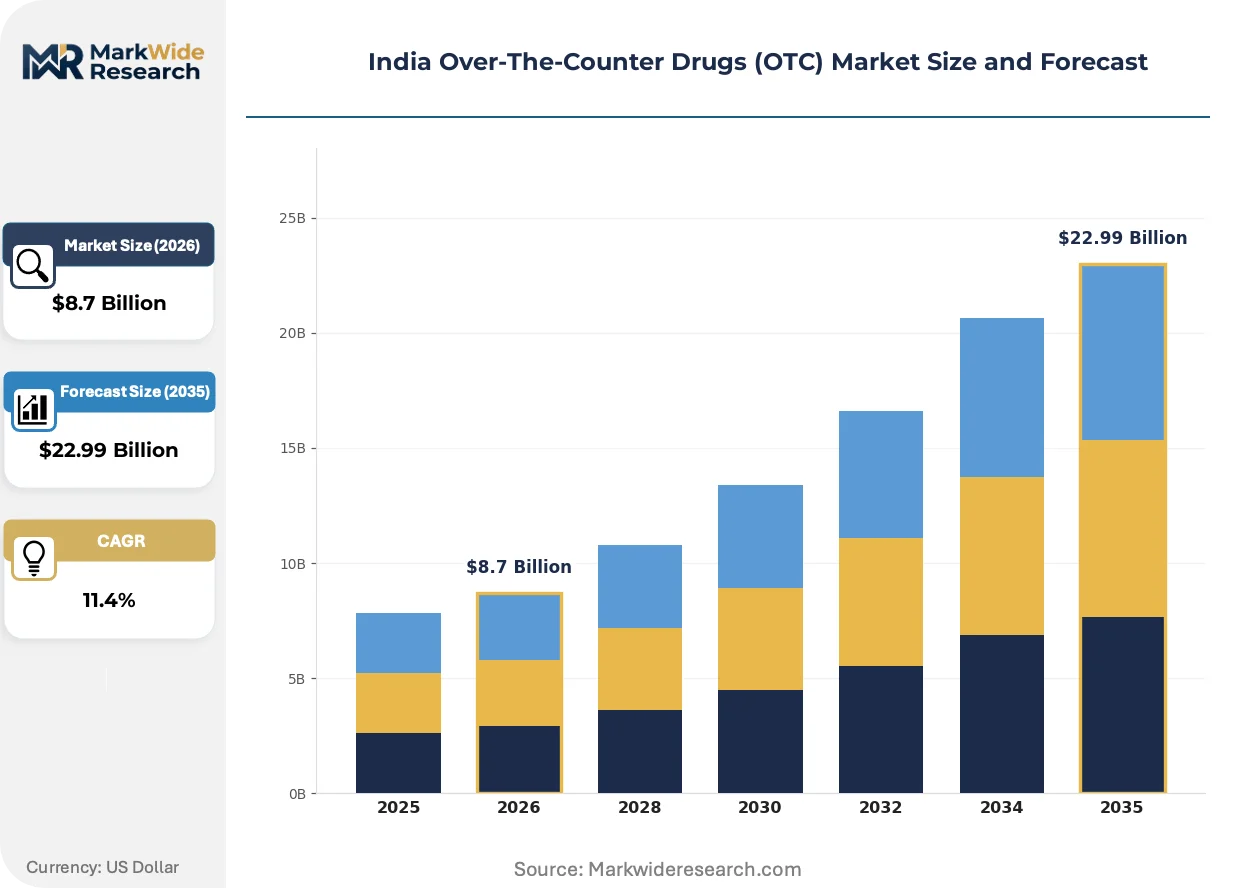
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pain Relievers, Cough & Cold Medications, Antacids, Allergy Medications Customer Type: Retail Consumers, Healthcare Professionals, Pharmacies, E-commerce Platforms Category: Herbal, Allopathic, Homeopathic, Nutraceuticals Distribution Channel: Supermarkets, Drugstores, Online Retail, Medical Stores |
| Companies Covered | Lupin Ltd., Alkem Laboratories Ltd., Sun Pharmaceutical Industries Ltd., GlaxoSmithKline Consumer Healthcare, Abbott India Ltd., Cipla Ltd., Zydus Lifesciences Ltd., Reckitt Benckiser (India) Ltd., Dr. Reddy's Laboratories Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Over-The-Counter Drugs (OTC) Market Shifts & Advancements
Digital health integration and format innovation are restructuring how OTC products reach Indian consumers. Manufacturers now compete on adherence-tracking features and channel convenience rather than formulation alone.
Direct-to-consumer telehealth platforms are consolidating prescription validation workflows with OTC fulfillment. PharmEasy and Apollo 24/7 embed algorithmic symptom checkers that route users toward appropriate self-medication SKUs. This channel compression bypasses traditional pharmacist consultation, concentrating volume with platform-integrated brands.
FSSAI's 2022 nutraceutical labeling amendments are forcing reformulation of combination products containing vitamins above RDA thresholds. Manufacturers must either strip dosages or register as drugs under CDSCO. The pain-cold segment faces the steepest compliance burden, with Mumbai-based formulators leading the dual-track registration strategy.
Self-medication behavior among Maharashtra's rural working-age population is rotating demand toward single-ingredient analgesics over fixed-dose combinations. Pharmacy chains in Nagpur and Nashik report paracetamol monotherapy outpacing traditional paracetamol-caffeine blends. This preference shift rewards transparent labeling and dosage clarity over legacy brand equity.
India Over-The-Counter Drugs (OTC) Market Segmentation
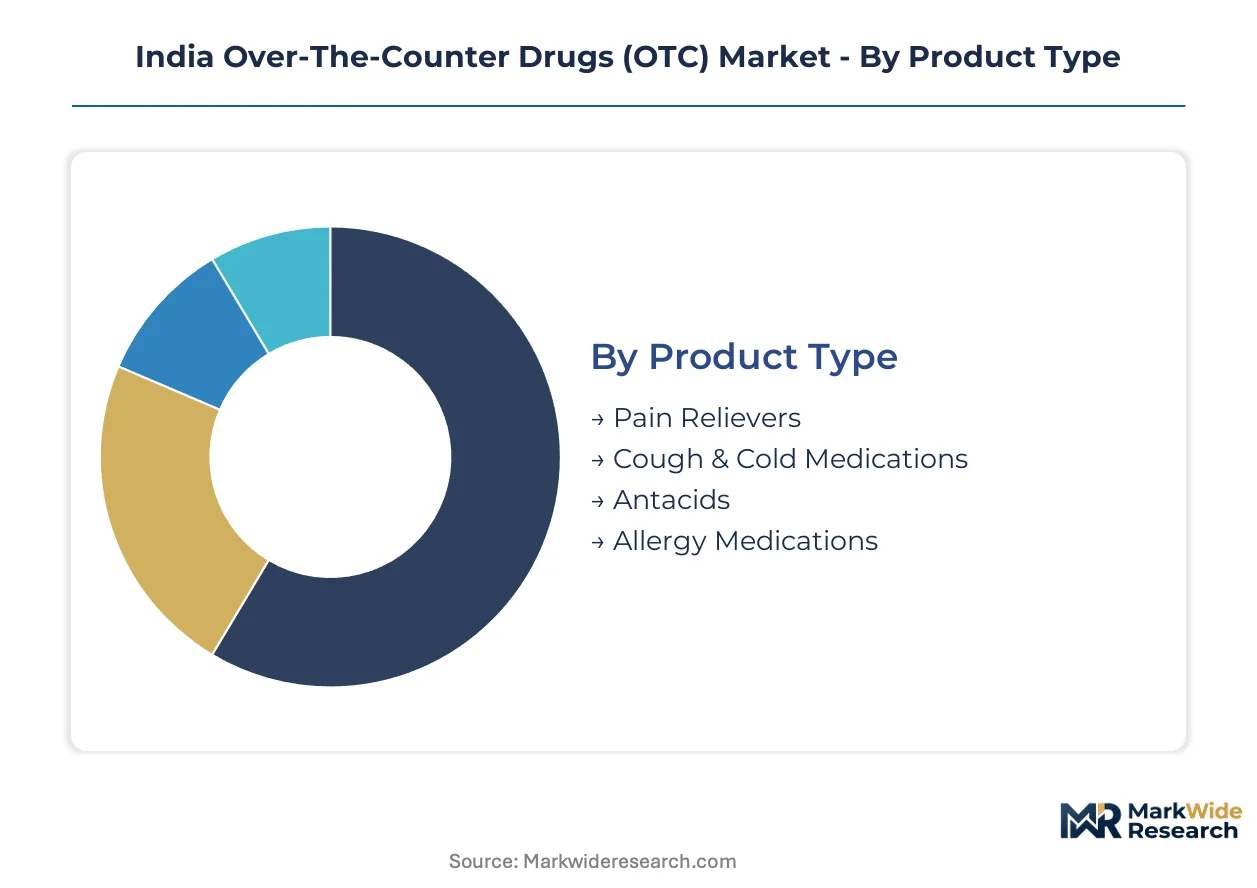
OTC portfolio strategy in India hinges on matching formulation formats to distinct procurement behaviors across pharmacy, institutional, and digital channels. Manufacturers must calibrate packaging, dosage, and margin structures separately for each segment cluster.
Product Type:
Manufacturing capacity concentrates around high-velocity formats with established API supply chains and predictable seasonal demand patterns.
- Pain Relievers:Ibuprofen and paracetamol formulations dominate tablet and capsule production, with standardized dosages enabling mass-scale direct compression. Maharashtra and Gujarat pharmacy networks report habitual repurchase cycles for single-ingredient analgesics as self-medication practices spread beyond metropolitan centers.
- Cough & Cold Medications:Seasonal surges strain cold-chain logistics during monsoon quarters, with fixed-dose combinations of antihistamines and decongestants requiring precise humidity-controlled packaging. Tier-2 distributors in Nagpur and Nashik face inventory fragmentation due to demand spikes concentrated in four-month windows.
- Antacids:Ranitidine-alternative formulations using calcium carbonate and magnesium hydroxide address post-meal acidity patterns in urban working populations.
- Allergy Medications:Second-generation antihistamines in non-drowsy formulations target metropolitan consumers with pollution-triggered respiratory sensitivities.
Pain Relievers absorb the bulk of installed capacity; Cough & Cold Medications are expanding most quickly.
Customer Type:
Procurement authority fragments across stakeholders with divergent price sensitivity and compliance requirements, forcing parallel go-to-market architectures.
- Retail Consumers:Direct purchasers prioritize convenience and brand recognition, with Mumbai and Bengaluru households driving demand for subscription-based wellness bundles integrating chronic-condition monitoring.
- Healthcare Professionals:Physician endorsement carries significant weight in tier-2 cities, where allopathic recommendations override herbal alternatives despite price premiums.
- Pharmacies:Stocking decisions hinge on distributor credit terms and BIS-certified packaging availability, with national brands commanding shelf preference over regional entrants facing 8-12 month certification delays.
- E-commerce Platforms:PharmEasy and Apollo 24|7 consolidate prescription validation with OTC fulfillment, concentrating volume with algorithm-integrated brands that bypass traditional pharmacist consultation.
Retail Consumers generate the highest transaction frequency; E-commerce Platforms are climbing the fastest as telehealth integration accelerates.
Category:
Regulatory jurisdiction boundaries between CDSCO and FSSAI create compliance complexity that shapes competitive positioning across formulation philosophies.
- Allopathic:Synthetic active ingredients at standardized dosages manufactured through wet granulation or direct compression methods sustain margin leadership due to faster perceived efficacy and stronger physician endorsement carryover in urban corridors.
- Herbal:Ayurvedic practitioners and Dabur-backed traditional formulations capture price-sensitive segments in Kerala and Tamil Nadu, where allopathic brands face physician endorsement erosion.
- Homeopathic:Dilution-based preparations serve niche consumer segments with preference for non-conventional treatment paradigms.
- Nutraceuticals:Vitamin-mineral combinations above RDA thresholds face FSSAI labeling amendments forcing reformulation or dual-track CDSCO registration, with Mumbai-based formulators leading compliance strategies.
Allopathic formulations command the dominant revenue share; Nutraceuticals face the steepest regulatory-driven restructuring.
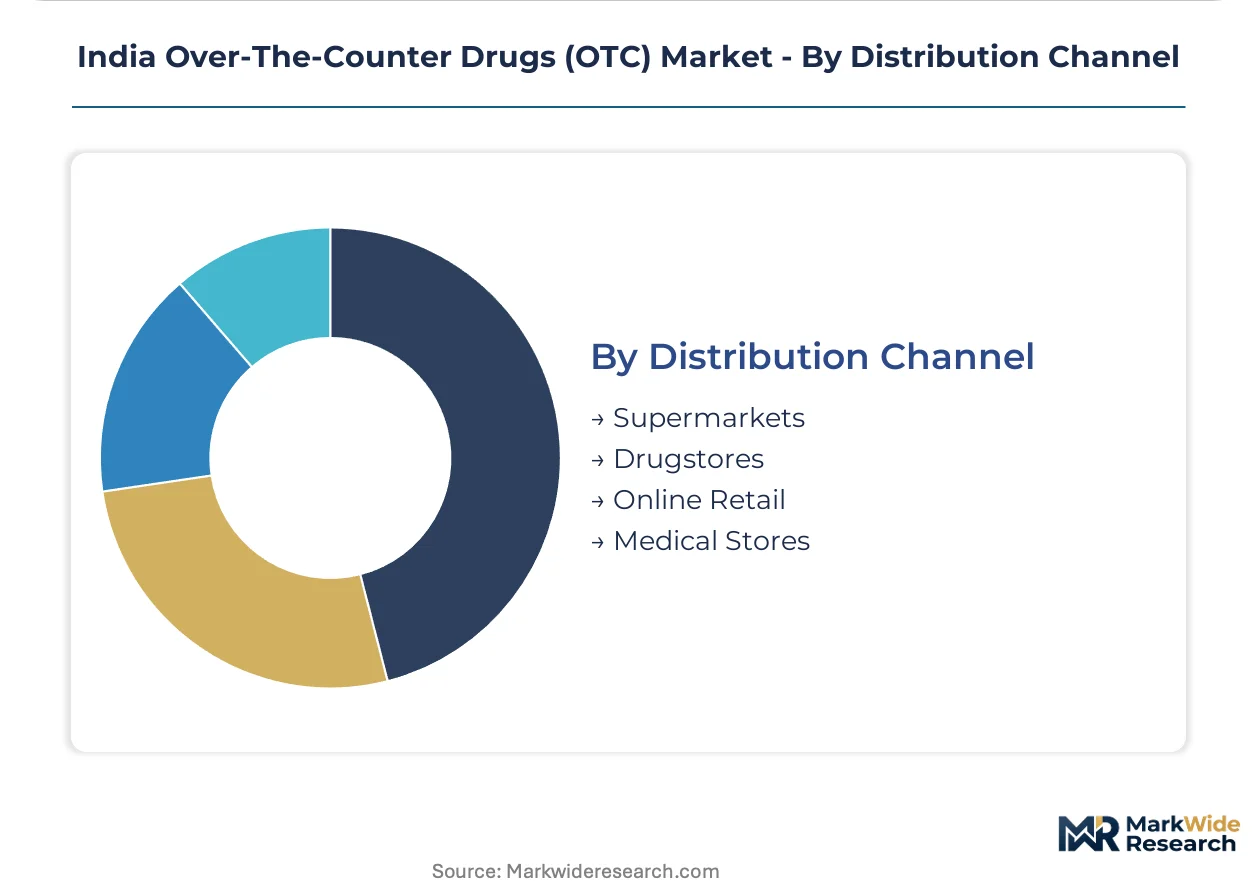
Distribution Channel:
Physical retail density in semi-urban corridors competes with digital platform consolidation for consumer access and loyalty.
- Drugstores:Dedicated pharmacy networks in tier-2 cities maintain pharmacist consultation as a differentiation layer, with Gujarat and Rajasthan family-owned distributors upgrading from kirana shops to licensed outlets.
- Medical Stores:Hospital-adjacent retail captures discharge-driven purchase behavior for post-treatment maintenance regimens.
- Supermarkets:Modern trade formats in metropolitan centers stock limited SKUs focused on high-recognition brands with impulse-purchase packaging.
- Online Retail:Direct-to-consumer platforms embed symptom-checker algorithms that route users toward appropriate self-medication SKUs, compressing traditional channel margins.
Drugstores retain the deepest geographic penetration; Online Retail is gaining share fastest as platform integration consolidates consumer journeys.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's OTC production capacity clusters around western pharmaceutical corridors, while consumption spreads through tier-2 pharmacy networks and emerging rural markets. Maharashtra and Gujarat anchor formulation output, with demand diffusion accelerating across semi-urban hinterlands.
Maharashtra
Mumbai and Pune house concentrated formulation facilities serving domestic pain-relief and antacid demand. CDSCO's streamlined switch framework accelerates prescription-to-OTC transitions for manufacturers headquartered in this corridor. Nashik and Nagpur pharmacy chains report surging single-ingredient analgesic velocity as self-medication practices penetrate rural working-age populations.
Gujarat
Ahmedabad and Vadodara host bulk drug and formulation operations feeding western India distribution networks. State-level pharmacy licensing upgrades transform kirana shops into licensed outlets across Saurashtra and North Gujarat. Family-owned distributors in these sub-regions face ERP integration gaps that fragment real-time inventory visibility during seasonal demand spikes.
Karnataka
Bengaluru's digital health ecosystem pilots subscription-based wellness bundles integrating chronic-condition monitoring with OTC supplements. FSSAI jurisdiction over nutraceutical-borderline products creates compliance complexity for vitamin-mineral combinations marketed through platform channels. The city's telehealth platforms compress prescription validation with OTC fulfillment, concentrating volume with algorithm-integrated brands.
Tamil Nadu
Chennai and Coimbatore manufacturing bases supply respiratory and dermatology OTC formats across southern markets. Ayurvedic practitioner networks in Kerala-adjacent districts capture price-sensitive segments, eroding allopathic physician endorsement in these strongholds. Regional distributors report herbal substitution pressure on standard-dosage tablet categories.
Telangana
Hyderabad anchors pharmacovigilance talent concentration for adverse-event reporting mandates under CDSCO switch regulations. The city's clinical research infrastructure supports safety-data specialist pipelines that tier-2 manufacturers struggle to replicate. API localization initiatives under the PLI scheme reduce import dependence for paracetamol and ibuprofen intermediates processed through regional formulators.
India Over-The-Counter Drugs (OTC) Market Competitive Landscape
Top-tier vendors anchor national distribution through pharmacy-first networks, while regional specialists compete on BIS-certified packaging speed and localized credit terms. The market exhibits tiered concentration with dermatology and gastrointestinal extension players commanding shelf preference. Three archetypes dominate: diversified pharmaceutical conglomerates leveraging prescription heritage, consumer health multinationals with platform-integrated logistics, and mid-scale regional formulators with API backward integration. Competitive moves center on inhaler-to-capsule format transitions and chronic-condition monitoring bundle partnerships.
Among domestic pharmaceutical conglomerates, Sun Pharmaceutical Industries Ltd., Dr. Reddy's Laboratories Ltd., and Cipla Ltd. occupy positions reflecting distinct therapeutic anchoring strategies. Sun Pharmaceutical exemplifies dermatology-to-OTC extension archetypes through heritage brand leverage. Dr. Reddy's Laboratories represents pharmacy-first distribution models concentrated in gastrointestinal and pain-management categories. Cipla anchors respiratory OTC transitions through format innovation from pressurized inhalers toward dry-powder alternatives. These three entities collectively illustrate how prescription-era positioning translates into self-medication market structure.
| Leading Market Players |
|---|
| Lupin Ltd. |
| Alkem Laboratories Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| GlaxoSmithKline Consumer Healthcare |
| Abbott India Ltd. |
| Cipla Ltd. |
| Zydus Lifesciences Ltd. |
| Reckitt Benckiser (India) Ltd. |
| Dr. Reddy's Laboratories Ltd. |
| Others |
Supply & Pricing Matrix
CDSCO-certified national brands versus BIS-pending regional entrants creates a two-tier divergence that manifests in both pricing power and supply chain configurations across Maharashtra and Gujarat corridors. Premium shelf positioning commands distributor credit advantages while certification delays force regional players into spot-market API procurement.
Pricing Analysis
Margin tightening in regional generic tiers reflects paracetamol and ibuprofen intermediate volatility tied to Chinese environmental enforcement cycles. Three-tier pricing structure across premium, standard, and economy levels stratifies by BIS certification status and backward integration depth. Cost-down pressure on economy-tier manufacturers accelerates because API import dependence strips pricing flexibility. Price-sensitive rural pharmacy networks in Saurashtra and North Gujarat prioritize single-ingredient analgesics over fixed-dose combinations.
Supply Chain Analysis
Cold-chain logistics costs for cough-cold seasonality strain distributor margins during monsoon quarters across tier-2 corridors. API supply concentrates in China and India with intermediate processing clustered around Ahmedabad and Hyderabad bulk drug parks. Raw material dependencies span paracetamol intermediates, ibuprofen APIs, and BIS-certified blister foils. Single-source vulnerability from Chinese environmental shutdowns threatens margin stability. Distribution runs through family-owned pharmacy networks upgrading from kirana shops to licensed outlets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API localization bottlenecks under India's PLI scheme prop pricing power for backward-integrated formulators while stranding import-dependent competitors.
For Market Incumbents: Hedge against herbal substitution in Kerala and Tamil Nadu through physician endorsement programs targeting allopathic efficacy claims. Secure captive API supply for paracetamol and ibuprofen intermediates via PLI-linked capacity additions in Telangana bulk drug corridors. Channel control through BIS-certified packaging partnerships reinforces shelf preference against regional entrants facing 8-12 month approval delays. For New Entrants and Emerging Players: Algorithm-integrated symptom checker technology opens white-space access through PharmEasy and Apollo 24|7 platform partnerships. Chronic-condition monitoring bundles represent the most penetrable segment given Mumbai and Bengaluru insurer pilot momentum. Direct-to-consumer telehealth integration offers a defensible go-to-market angle bypassing traditional pharmacist consultation layers. For Investors and Strategic Acquirers: Re-rating potential sits with respiratory format innovators given inhaler-to-capsule convergence catalysts reducing cold-chain dependency. Five-to-ten year viability favors manufacturers with dry-powder and soft-gel technology pipelines over legacy pressurized metered-dose platforms. Watch CDSCO-FSSAI jurisdiction resolution over vitamin-mineral combinations as the inflection signal for nutraceutical-borderline portfolio restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Switch Portfolio Expansion | Streamlined OTC classification reduces approval timelines for prescription-to-OTC candidates. |
| API Backward Integration | PLI scheme localization cuts import dependence on Chinese paracetamol intermediates. |
| Digital Platform Integration | Telehealth embedding consolidates prescription validation with OTC fulfillment volume. |
| Inhaler-to-Capsule Format Transition | Dry-powder alternatives reduce cold-chain logistics burden for tier-3 distribution. |
| Chronic-Condition Bundle Partnerships | Subscription wellness programs with glucose tracking create recurring revenue streams. |
Research Methodology
CDSCO regulatory filings, FSSAI nutraceutical amendments, and PLI scheme disbursement records formed the secondary backbone for this analysis. Primary interviews with pharmaceutical regulatory affairs leads, pharmacy chain procurement managers, and bulk drug plant operators in Maharashtra and Gujarat validated demand patterns. Bottom-up and top-down triangulation reconciled formulation capacity data with distributor SKU velocity reports across tier-2 city networks.
Bottom-up modeling anchored volume projections to API localization trajectories and switch candidate pipelines under CDSCO's streamlined framework. Segmentation dimensions spanned product type, customer archetype, regulatory category, and distribution channel density across western pharmaceutical corridors. CAGRs derived from installed capacity expansion rates and rural pharmacy network penetration curves. Forecast inputs incorporated BIS certification timelines and seasonal cough-cold demand elasticity.
Several conditions sit outside the modeled scope, including abrupt Chinese environmental enforcement shutdowns, CDSCO-FSSAI jurisdictional disputes, and Ayurvedic practitioner network expansion rates. Forecasts reflect assumptions about PLI scheme execution and switch framework stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Non-Alcoholic Steatohepatitis Drugs Pipeline Market
Pharmaceuticals
Oral Anticoagulant Market
Pharmaceuticals
Japan Pharmaceutical Market
Pharmaceuticals
Mouth Ulcers Treatment Market
Pharmaceuticals
Filgrastim Market
Pharmaceuticals
Canada Pharmaceutical Market
Pharmaceuticals
Canada Specialty Pharmacy Market
Pharmaceuticals
Large Molecule Contract Development and Manufacturing Organization Market
Pharmaceuticals
Omeprazole and Antihistamine Market
Pharmaceuticals
Global Bispecific Antibody Therapeutics Market
Pharmaceuticals
Global Equine Pharmaceuticals and Supplements Market
Pharmaceuticals
Global HPMC Capsules Market
Pharmaceuticals
Global Genitourinary Drugs Market
Pharmaceuticals
Adamantane Antiviral Drugs Market
Pharmaceuticals
Adrenocorticotropic Hormone [ACTH] Market
Pharmaceuticals
Human Growth Hormone Treatment and Drugs Market