
 South Korea Oil and Gas Market | 2026-2036
South Korea Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Oil and Gas Market Analytics
Digital twin deployment across downstream operations is reconfiguring how refineries optimize throughput and predictive maintenance. SK Energy leverages real-time simulation platforms to enhance yield optimization at its Ulsan complex. GS Caltex Corp anchors its competitive stance through integrated refining and petrochemical operations that sustain margin capture across the value chain. Korea National Oil Corporation (KNOC) controls strategic petroleum reserve infrastructure that positions the state entity as a buffer against supply volatility.
South Korea oil and gas encompasses the exploration, production, refining, and distribution of hydrocarbon resources including crude oil with API gravities typically ranging from 32 to 38 degrees, natural gas with methane content exceeding 85 percent, and derivative refined products meeting sulfur specifications below 10 parts per million. The sector serves industrial feedstock requirements, residential heating demand, transportation fuel consumption, and baseload power generation across the Korean peninsula. Refined products and petrochemicals command the dominant share of product type revenue, reflecting the country's massive downstream conversion capacity. LNG carriers and pipeline networks represent the most structurally significant delivery modes, given South Korea's near-total dependence on maritime imports and limited indigenous production.
MFDS oversight of industrial chemical safety, METI-coordinated hydrogen economy roadmaps, and KOGAS-mandated LNG infrastructure standards collectively shape operational compliance and capital allocation across the sector. These frameworks elevate entry barriers for new market participants while accelerating incumbent investment in carbon-reduction pathways. Stakeholders must weigh the pace of hydrogen blending requirements against the residual economic life of existing refining assets.
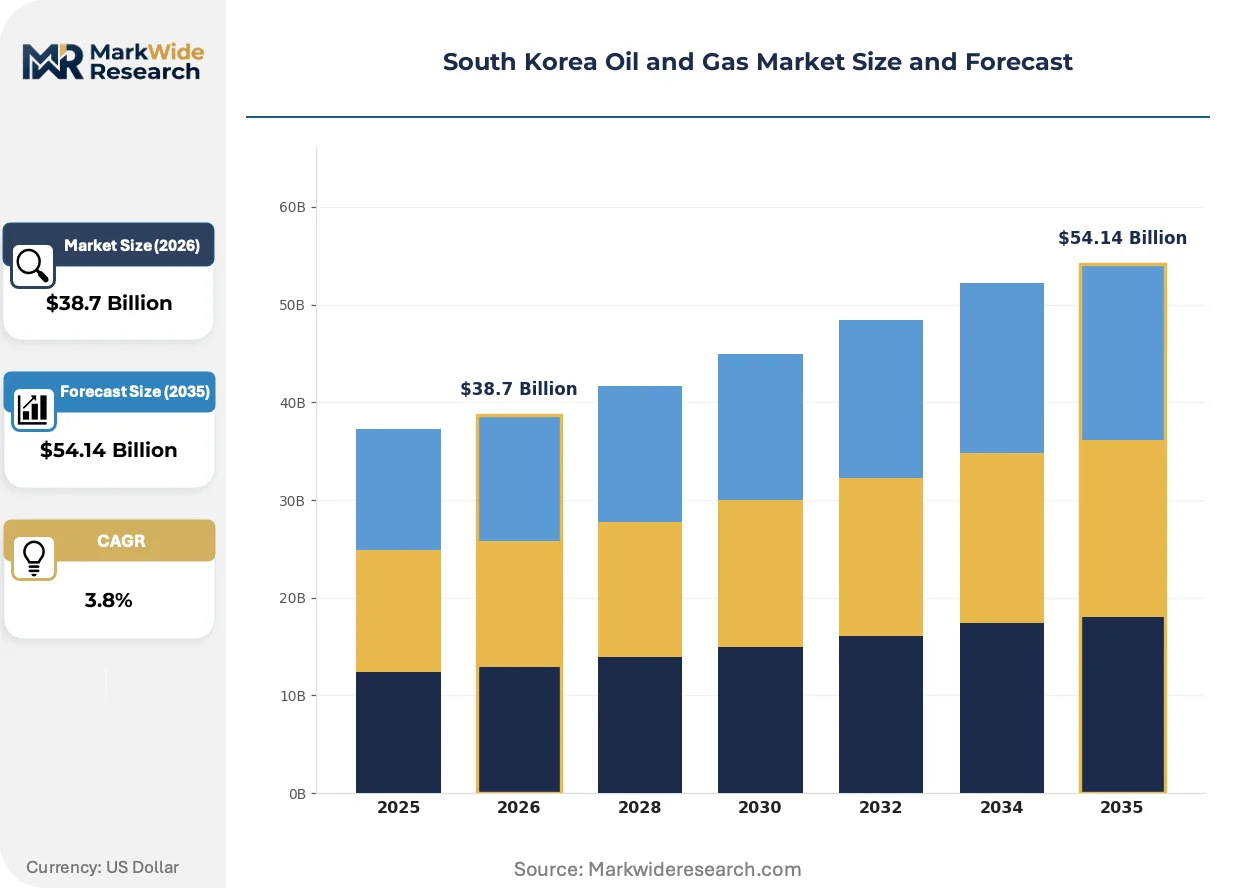
Market Dynamics
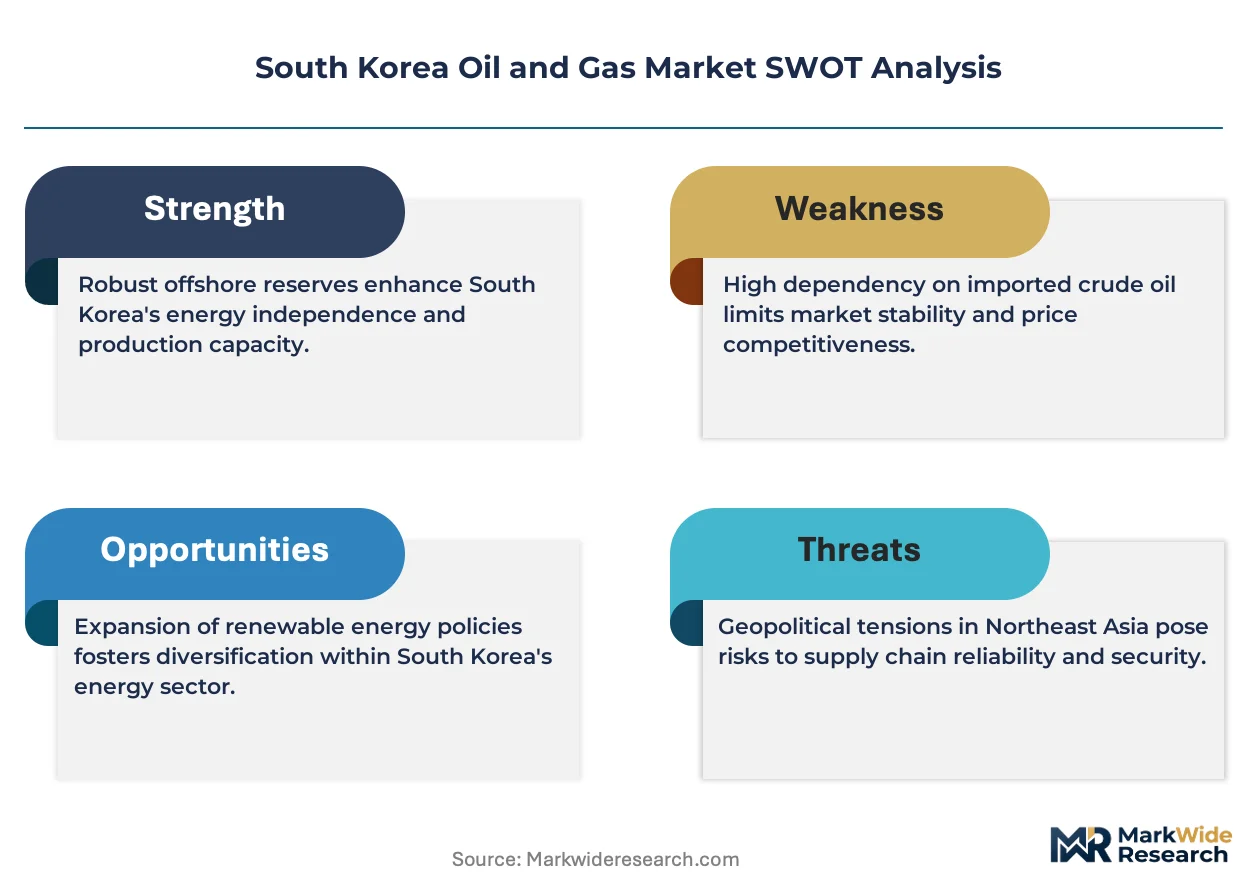
Hydrogen blending mandates from the Ministry of Trade, Industry and Energy are forcing refiners to reconfigure processing units ahead of residual asset lifecycles. This regulatory compression is accelerating capital redeployment toward dual-fuel infrastructure while stranding conventional hydrocracking investments.
Growth Catalysts
- Ulsan-Busan refining corridor concentration:Integrated petrochemical complexes capture margin across cracking, aromatics, and polymer chains. Downstream buyers secure feedstock proximity.
- KNOC strategic reserve infrastructure:State-controlled storage capacity buffers import volatility. Energy security policy sustains inventory financing mechanisms.
- MFDS industrial chemical safety frameworks:Compliance standardization elevates operational barriers. Incumbents with certified process safety management systems gain tender preference.
Market Restraints
- Crude import dependency:Near-zero domestic production locks pricing to Middle Eastern benchmark differentials and freight volatility.
- Residual refining asset life:Hydrogen retrofit requirements clash with hydrocracker depreciation schedules. Write-down risk concentrates in 150,000+ bpd units.
- LNG terminal congestion:KOGAS-mandated infrastructure standards extend permitting timelines. New regasification capacity faces 48-60 month approval cycles.
Strategic Opportunities
- Carbon capture integration at Yeosu cluster:Petrochemical steam crackers offer concentrated CO2 streams for sequestration. Offtake agreements with industrial gas processors are emerging.
- Blue ammonia export positioning:Incheon LNG receiving terminals enable hydrogen carrier conversion. Japanese power utilities represent anchor demand.
- Digital twin predictive maintenance:Real-time simulation platforms reduce unplanned outage frequency. Refinery operators target 15-20% maintenance cost compression.
Industry Challenges
- Process safety engineering scarcity:MFDS-certified hazard analysis practitioners command 40% wage premiums. Training pipeline lags retrofit project demand.
- Dual-fuel burner integration complexity:Hydrogen-natural gas co-firing requires flame stability recalibration. OEM warranty terms remain unresolved.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Oil and Gas Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $54.14 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Oil, Natural Gas, Refined Products, Petrochemicals End User: Industrial, Residential, Transportation, Power Generation Delivery Mode: Pipelines, Tankers, LNG Carriers, Rail Service Type: Exploration, Production, Refining, Distribution |
| Companies Covered | SK Energy, GS Caltex Corp, Korea National Oil Corporation (KNOC), POSCO International, SK Innovation, Korea Gas Corporation (KOGAS), Hyundai Oilbank Co., Ltd, SK Gas, S-Oil Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Oil and Gas Market Evolving Landscape
Downstream operators are virtualizing physical assets to compress optimization cycles. Three distinct vectors are restructuring competitive capability: simulation technology, hydrogen economy policy, and procurement model evolution.
Digital twin platforms are virtualizing refinery operations across distillation, reforming, and cracking units. SK Energy and GS Caltex deploy real-time thermodynamic models to simulate yield outcomes before physical parameter changes. This virtualization is compressing the experimentation cycle from weeks to hours, enabling daily optimization rather than monthly turnaround planning.
METI-coordinated hydrogen economy roadmaps are mandating ammonia co-firing trials in power generation and maritime bunkering. South Korean utilities must source 20% hydrogen-blended fuel by 2030 per draft enforcement rules. Heavy industry clusters in Ulsan and Yeosu face the steepest compliance curves, accelerating electrolyzer partnerships with domestic shipbuilders.
Long-term offtake contracting is displacing spot procurement for LNG and hydrogen carriers. Petrochemical buyers seek 10-15 year supply agreements to underpin project finance for upstream liquefaction investments. This shift is visible in Incheon terminal negotiations, where volume commitments now precede infrastructure FID.
South Korea Oil and Gas Market Segmentation
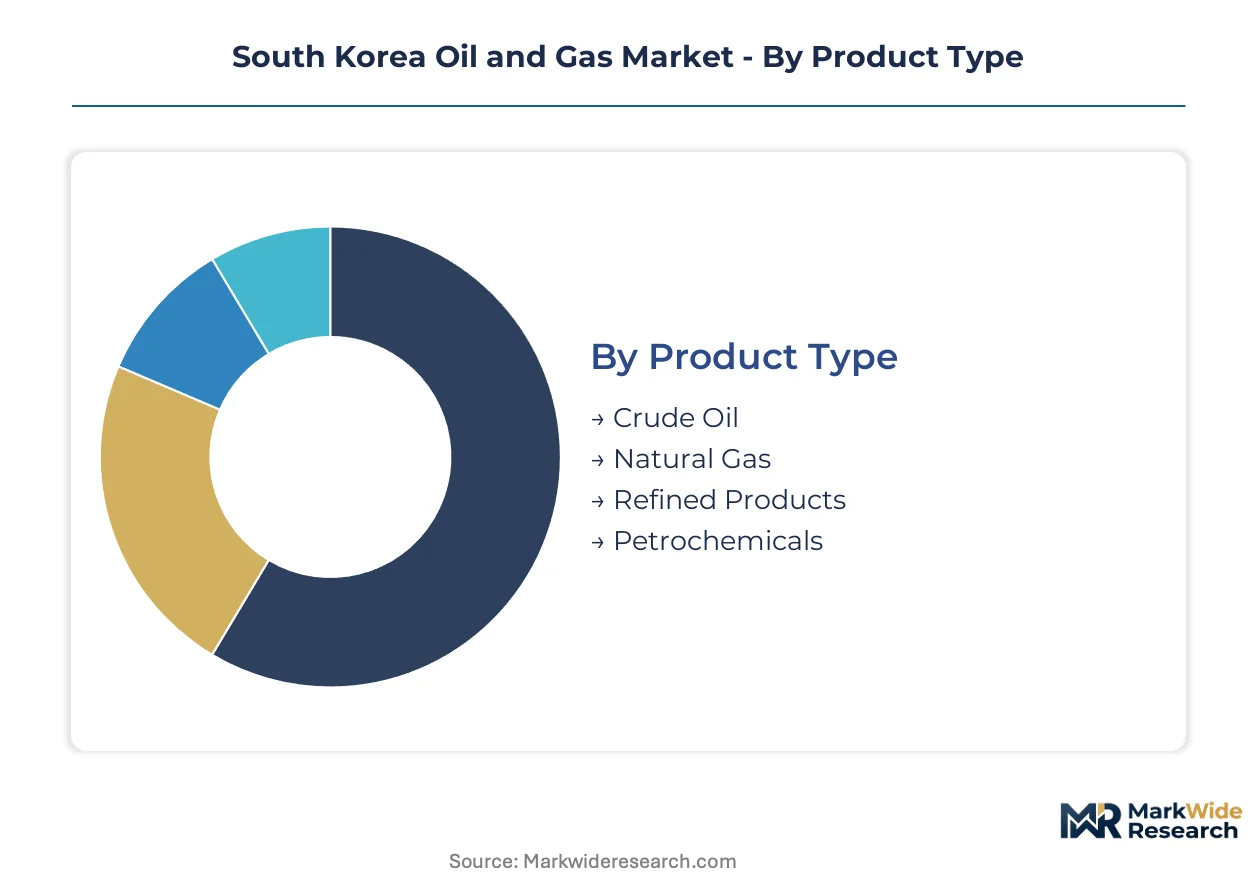
South Korea's oil and gas market segmentation reveals how import dependency and downstream conversion capacity shape commercial flows. Each dimension exposes distinct operational constraints and investment priorities across the value chain.
Product Type:
Cost tier differentiation separates commodity feedstocks from higher-margin derivative outputs in South Korean refining economics.
- Crude Oil:Imported barrels with API gravities between 32 and 38 degrees dominate feedstock intake. Ulsan-Busan refining corridor complexes process the majority of domestic crude throughput, constrained by Middle Eastern benchmark pricing and freight volatility.
- Petrochemicals:Aromatics, olefins, and polymer chains capture the widest margin spreads across the value chain. Yeosu cluster steam crackers concentrate demand for naphtha feedstock as hydrogen-blending mandates reshape fuel specifications.
- Refined Products:Ultra-low sulfur diesel and gasoline meeting sub-10 ppm specifications serve transportation and industrial markets.
- Natural Gas:Methane-rich molecules exceeding 85 percent content feed power generation and residential heating through KOGAS-mandated infrastructure.
Petrochemicals commands the established base. The steepest expansion runs through natural gas as hydrogen carrier conversion accelerates.
End User:
Application concentration varies sharply between bulk industrial offtake and fragmented residential demand patterns.
- Industrial:Petrochemical manufacturers, steel producers, and chemical processors absorb the largest volume blocks. Hydrogen economy roadmaps from METI are redirecting fuel specifications toward ammonia co-firing trials.
- Transportation:Marine bunkering and road fuel consumption face the steepest compliance curves under draft enforcement rules requiring 20 percent hydrogen-blended fuel.
- Power Generation:Baseload gas turbines and emerging ammonia co-firing capacity anchor LNG procurement.
- Residential:District heating networks and direct consumption represent the most price-sensitive demand segment.
Industrial offtake anchors revenue stability. Transportation applications are climbing the fastest amid regulatory compression on conventional fuels.
Delivery Mode:
Volume scale and infrastructure maturity determine which channels dominate South Korean energy logistics.
- LNG Carriers:Specialized cryogenic vessels handle near-total natural gas imports through Incheon and Tongyeong receiving terminals. Japanese power utilities are emerging as anchor demand partners for blue ammonia export positioning.
- Pipelines:Domestic distribution networks connect regasification facilities to industrial clusters and urban demand centers.
- Tankers:Crude oil and refined product movements depend on VLCC and product tanker availability at Korean ports.
- Rail:Limited inland distribution serves remote industrial sites lacking pipeline connectivity.
LNG carriers command the established base. Pipeline expansion is gaining share fastest as hydrogen blending infrastructure retrofits advance.
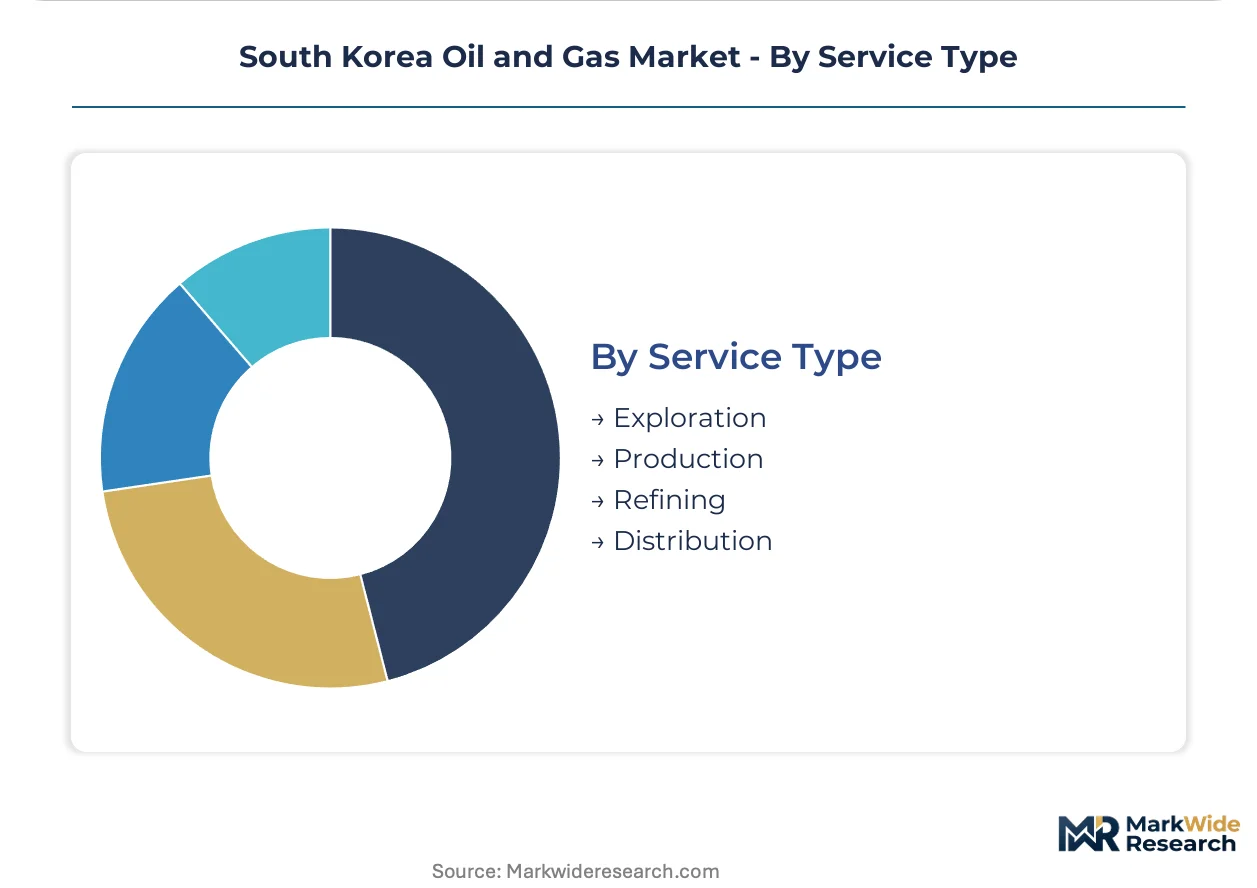
Service Type:
Customer type and margin structure separate capital-intensive upstream activities from operational downstream services.
- Refining:Integrated complexes at Ulsan and Yeosu sustain margin capture across cracking, aromatics, and polymer chains. Digital twin deployment is compressing optimization cycles from weeks to hours.
- Distribution:Storage terminals, retail networks, and wholesale logistics face MFDS compliance standardization that elevates operational barriers.
- Exploration:Near-zero domestic production limits this segment to marginal offshore blocks and international joint ventures.
- Production:Minimal indigenous output constrains activity to enhanced recovery from mature fields.
Refining commands the established base. Distribution services are expanding most quickly as hydrogen infrastructure standards extend permitting timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical manufacturers dominate procurement across South Korea's industrial corridor, with hydrogen-blending mandates from the Ministry of Trade, Industry and Energy redirecting capital toward dual-fuel infrastructure.
Seoul Capital Area
Corporate headquarters and trading desks concentrate energy procurement decisions for the national market. MFDS oversight of industrial chemical safety elevates compliance costs for distributors serving the metropolitan demand base. The Incheon LNG receiving terminals anchor import logistics for the northern demand cluster.
Busan-Ulsan
Integrated refining and petrochemical complexes process the majority of domestic crude throughput along this southeastern corridor. METI-coordinated hydrogen economy roadmaps mandate ammonia co-firing trials at heavy industrial facilities. Ulsan complex operators deploy digital twin platforms to compress yield optimization cycles.
Daegu-Gyeongbuk
Steel producers and chemical processors absorb large volume blocks of natural gas and refined products. KOGAS-mandated infrastructure standards extend permitting timelines for pipeline expansions into this inland industrial zone. Daegu-based engineering firms face scarcity of MFDS-certified hazard analysis practitioners.
Daejeon-Sejong
Government energy policy formulation centers on this administrative hub, with regulator offices shaping enforcement timelines for hydrogen blending requirements. The Korea National Oil Corporation maintains strategic petroleum reserve coordination functions. Research institutes pilot carbon capture integration concepts for downstream deployment.
Gwangju-Honam
The Yeosu petrochemical cluster generates concentrated CO2 streams from steam cracking operations. Blue ammonia export positioning leverages proximity to southwestern maritime terminals. Industrial gas processors negotiate offtake agreements for sequestration projects serving Japanese power utility demand.
South Korea Oil and Gas Market Competitive Landscape
Channel-controlling players compete with product-specialist players across South Korea's downstream-heavy market structure. State-affiliated entities dominate strategic reserve infrastructure and LNG import terminals, while private refiners anchor integrated petrochemical operations. Two strategic archetypes prevail: vertically integrated energy conglomerates with refining-petrochemical-chemicals chains, and specialized gas distributors with captive regional networks. Competitive moves concentrate on hydrogen infrastructure partnerships and digital twin technology licensing rather than capacity expansion.
Within the integrated conglomerate tier, SK Energy and GS Caltex Corp occupy positions exemplifying refining-petrochemical integration across the Ulsan-Busan corridor. Korea National Oil Corporation represents the state-buffer archetype, controlling strategic petroleum reserve infrastructure that positions the entity as a supply volatility shock absorber. These three anchors illustrate how market structure privileges incumbent scale and regulatory relationships over new entry.
| Leading Market Players |
|---|
| SK Energy |
| GS Caltex Corp |
| Korea National Oil Corporation (KNOC) |
| POSCO International |
| SK Innovation |
| Korea Gas Corporation (KOGAS) |
| Hyundai Oilbank Co., Ltd |
| SK Gas |
| S-Oil Corporation |
| Others |
Value Network & Pricing Analysis
Overcapacity signals across Middle Eastern refining hubs are compressing regional benchmark differentials and forcing Korean importers to renegotiate term contract structures. This utilization slack ripples through freight volatility premiums and inventory financing costs, reshaping how domestic processors manage working capital cycles.
Pricing Analysis
Cost-plus contracts indexed to Dubai-Oman crude benchmarks dominate term procurement for Korean refiners, with sulfur differentials and freight adjustments layered as monthly variable components. Price differentiation separates ultra-low sulfur diesel from standard grades through MFDS certification tiers and KOGAS-mandated infrastructure compliance. Pricing pressure stems from hydrogen retrofit capital requirements that clash with residual hydrocracker depreciation schedules. Industrial petrochemical buyers exhibit lowest price sensitivity due to feedstock proximity premiums, while residential heating distributors face margin compression from regulated tariff ceilings.
Supply Chain Analysis
Upstream feedstock sourcing draws from Saudi Arabia, Kuwait, and Iraq as primary crude suppliers, with Qatari LNG and Australian coal seam gas anchoring natural gas molecules. Naphtha, methane-rich LNG, and hydrogen carriers represent critical input dependencies for downstream conversion. Single-source vulnerability concentrates in VLCC charter availability through the Strait of Hormuz chokepoint. Distribution runs through KOGAS-mandated regasification terminals at Incheon and Tongyeong, with pipeline networks feeding the Ulsan-Busan industrial corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Korea oil and gas market functions as a defensive-moat structure where regulatory entrenchment through MFDS certification and KOGAS infrastructure standards creates prohibitive switching costs for downstream buyers.
For Market Incumbents: Entrench position through dual-fuel burner retrofit partnerships with domestic shipbuilders ahead of METI hydrogen enforcement timelines. Deepen backward integration into blue ammonia production at Incheon LNG terminals to capture Japanese utility offtake. Secure MFDS-certified process safety engineering talent through captive training pipelines to defend against wage-premium escalation. For New Entrants and Emerging Players: Pursue carbon capture integration contracts at Yeosu cluster steam crackers where concentrated CO2 streams enable sequestration economics without greenfield infrastructure. Target digital twin licensing opportunities for mid-scale refiners lacking SK Energy-scale simulation platforms. Lead with predictive maintenance value propositions that compress unplanned outage frequency for second-tier operators. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among LNG terminal operators with 10-15 year offtake agreements underpinning regasification capacity financing. Long-term viability centers on hydrogen carrier conversion positioning rather than residual crude refining exposure. Monitor electrolyzer partnership announcements between Korean shipbuilders and Ulsan complex operators as inflection signal for infrastructure capital redeployment.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Infrastructure Retrofit | Enables compliance with METI hydrogen-blending mandates ahead of enforcement deadlines. |
| Blue Ammonia Export Positioning | Leverages Incheon LNG terminals to supply Japanese power utility hydrogen carrier demand. |
| Digital Twin Platform Licensing | Compresses yield optimization cycles for refiners lacking SK Energy-scale simulation capabilities. |
| Carbon Capture Integration | Captures concentrated CO2 streams from Yeosu steam crackers for industrial gas processor offtake. |
| Strategic Petroleum Reserve Expansion | Strengthens KNOC buffer capacity against Middle Eastern supply volatility and freight disruption. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this study. Refinery operations directors, KOGAS infrastructure planners, petrochemical procurement leads, and MFDS compliance officers provided operational perspective. Secondary sources include Korea Customs Service trade data, KNOC strategic reserve disclosures, METI hydrogen roadmap publications, and KOGAS infrastructure standards documentation. Bottom-up segment sizing and top-down macroeconomic triangulation were applied throughout.
Calibration against historical capacity utilization rates and import dependency ratios shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user application, delivery mode, and service category. CAGRs were derived through regression analysis of feedstock price differentials and downstream margin capture trends. Hydrogen blending mandate enforcement timelines and LNG terminal permitting cycles served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Middle Eastern crude benchmark differentials or Korean won-US dollar exchange rates would shift the trajectory. Forecasts reflect documented assumptions regarding METI enforcement pace and KOGAS infrastructure completion schedules. Quarterly review of hydrogen retrofit project announcements and LNG offtake contract volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Microbial Enhanced Oil Recovery Market
Oil & Gas
United States Coiled Tubing Market
Oil & Gas
United States Onshore Drilling Fluid Market
Oil & Gas
Oil and Gas Security Services Market
Oil & Gas
Modular Gas Processing Plants Market
Oil & Gas
Digital Oil Field Technology Market
Oil & Gas
Saudi Arabia Drilling Rigs Market
Oil & Gas
Algeria Oil and Gas Downstream Market
Oil & Gas
Liner Hanger System Market
Oil & Gas
Qatar Oilfield Chemicals Market
Oil & Gas
Zonal Isolation Market
Oil & Gas
Europe Seismic Services Market
Oil & Gas
Coiled Tubing Services Market
Oil & Gas
GCC Oil and Gas Separation Market
Oil & Gas
Russian Federation Oil and Gas Midstream Market
Oil & Gas
Australia LNG Bunkering Market