
 Corrugated Open-Head Drums Market | 2026-2036
Corrugated Open-Head Drums Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Open-Head Drums Market Outlook
Market Context
Buyer concentration among North American chemical processors is pivoting toward integrated drum-service contracts that bundle packaging with logistics. Greif leverages its closed-loop reconditioning network to lock in multi-year supply agreements with refiners. Mauser Packaging Solutions anchors its position through steel drum refurbishment capabilities that lower per-use costs for hazardous material shippers. Sonoco Products Company differentiates via fiber drum formulations engineered for moisture-sensitive agricultural chemicals.
Technical Definition and Segment Structure
Corrugated open-head drums are cylindrical shipping containers with removable lids, constructed from layered fiberboard, steel, or polymer composites, typically rated for 30 to 200 gallons and engineered to UN performance standards for solids and hazardous liquids. These drums serve chemical manufacturers, food processors, and pharmaceutical compounders that require top-loading access for viscous or granular materials. Steel drums capture the dominant margin pool in hazardous chemical logistics, while fiber drums gain share in food-grade and agricultural applications where moisture barriers and cost efficiency matter. Plastic drums, molded from high-density polyethylene, are displacing steel in non-hazardous liquid segments where corrosion resistance and reduced tare weight cut freight costs.
Regulatory Framework
The EPA regulates drum integrity for hazardous waste containment under RCRA subtitle C, while DOT enforces UN performance testing for all drums entering interstate commerce. OSHA mandates drum handling protocols that favor designs with reinforced chimes and ergonomic closure systems. Stakeholders must monitor how state-level extended producer responsibility laws reshape drum recovery economics.
Market Dynamics
Integrated drum-service contracts are compressing traditional spot purchasing as chemical processors bundle packaging with logistics and reconditioning services. Buyers now demand cradle-to-grave accountability for UN-certified containers, forcing suppliers to build closed-loop recovery networks rather than sell single-use units.
Growth Catalysts
- UN Performance Certification Mandates:DOT shipping standards now require rigorous drop, stack, and leakproof testing for all drums entering interstate commerce. Chemical manufacturers in the United States are upgrading container fleets to meet these specifications, creating pull for certified open-head designs.
- Gulf Coast Petrochemical Expansion:Refinery capacity additions along the Texas-Louisiana corridor are generating concentrated demand for hazardous material containment. Drum suppliers are positioning fabrication facilities near Beaumont and Lake Charles to shorten delivery cycles.
- Moisture-Barrier Fiberboard Formulations:Agricultural chemical processors are adopting multi-layer fiber drums with vapor-deposited aluminum coatings. These containers protect hygroscopic crop protection compounds during humid Gulf Coast storage seasons.
Market Restraints
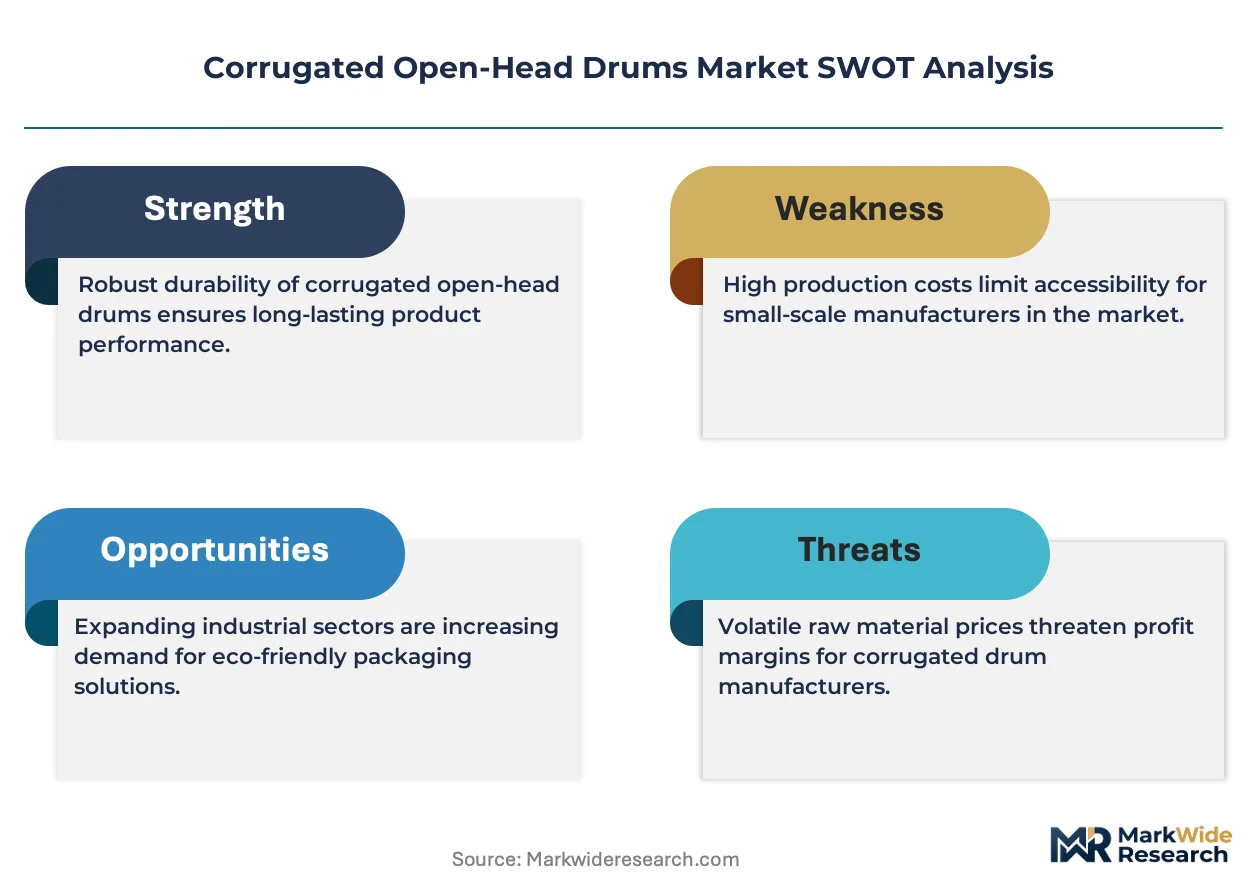
- Steel Sheet Input Volatility:Cold-rolled steel prices fluctuate with scrap metal arbitrage and energy costs, compressing margin predictability for drum fabricators. Producers cannot fully pass through material swings due to multi-year contract structures with refiners.
- Single-Source Concentration in Linerboard:High-performance kraft liner for fiber drums depends on a narrow supplier base concentrated in the southeastern United States. Any mill downtime disrupts drum production schedules for agricultural chemical packagers.
- HDPE Substitution in Non-Hazardous Liquids:High-density polyethylene drums are capturing share in food-grade and cosmetic applications where corrosion resistance and reduced tare weight cut freight costs. Steel drum producers face permanent volume displacement in these segments.
Strategic Opportunities
- Extended Producer Responsibility Tailwinds:California and Oregon are implementing container recovery mandates that reward closed-loop drum reconditioning. Service providers can capture fees for collection, cleaning, and recertification under these frameworks.
- Pharmaceutical Active Ingredient Packaging:Contract manufacturing organizations handling potent compounds require single-use fiber drums with integrated containment systems. This application commands premium pricing and long-term supply agreements.
- Digital Tracking Convergence:RFID-enabled drum fleets combined with blockchain provenance records are enabling pharmaceutical shippers to meet FDA track-and-trace requirements. Technology integrators can embed sensors during drum fabrication.
Industry Challenges
- UN Certification Timeline Compression:New drum designs require 6-12 months of laboratory testing and DOT approval before commercial deployment. Product development cycles strain engineering resources and delay revenue recognition.
- Reconditioning Facility Permitting:EPA RCRA permits for hazardous waste drum cleaning involve multi-year approval processes and community impact reviews. Capacity expansion faces regulatory friction even where demand justifies investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Open-Head Drums Market |
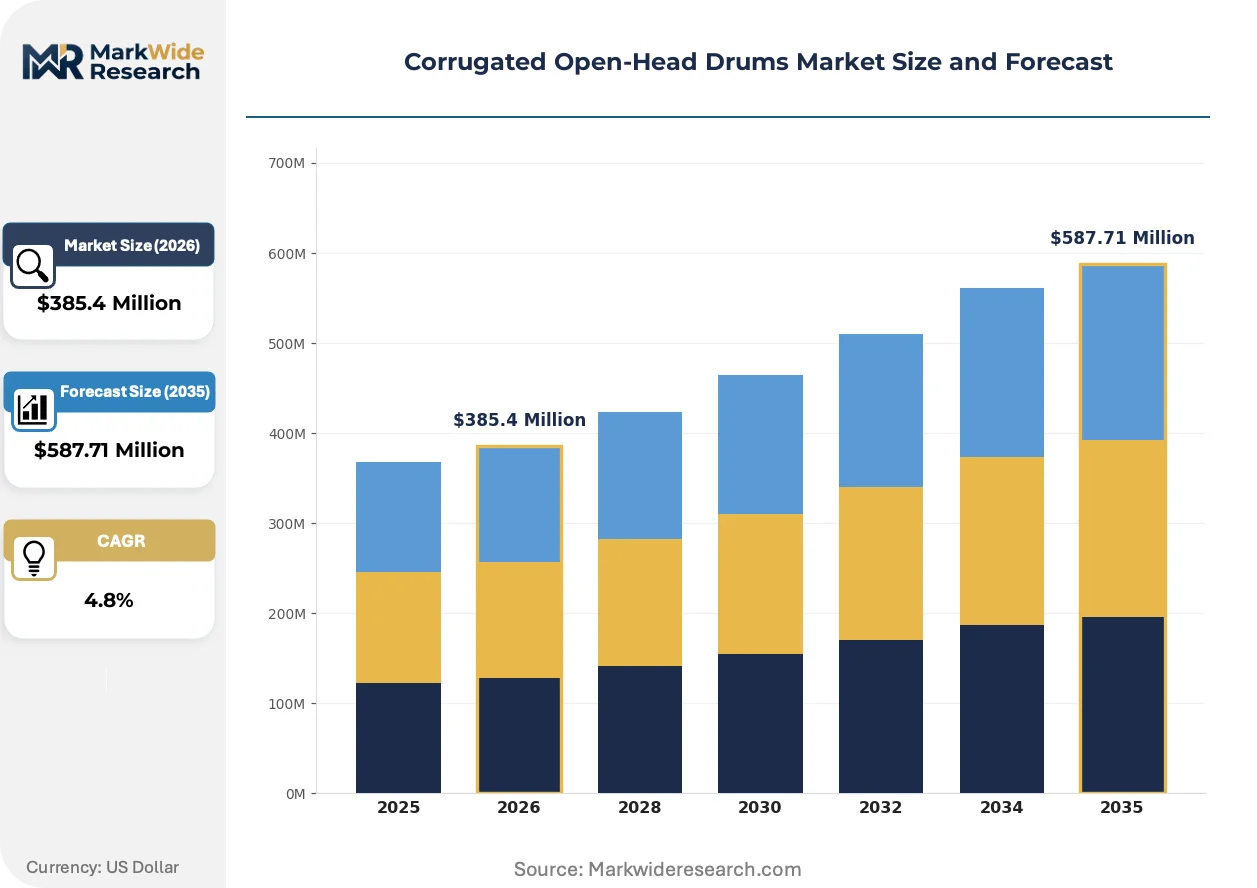
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $587.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Drums, Steel Drums, Fiber Drums, Composite Drums Material: Polyethylene, Steel, Fiberboard, Aluminum End User: Chemicals, Food & Beverage, Pharmaceuticals, Agriculture Capacity: 30 Gallons, 55 Gallons, 100 Gallons, 200 Gallons |
| Companies Covered | Greif, Sonoco Products Company, Mauser Packaging Solutions, Schutz Container Systems, DS Smith plc, Mondi Group, WestRock Company, International Paper Company, Smurfit Kappa Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Open-Head Drums Market Strategic Shifts
Material substitution and regulatory digitization are converging to redefine drum performance standards and service delivery models across North American chemical logistics.
Multi-layer fiberboard with vapor-deposited aluminum barriers is absorbing moisture protection duties previously assigned to steel containers. Agricultural chemical packagers in the Mississippi Delta are adopting these drums at accelerating rates for fungicide and herbicide shipments. The technology is absorbing volume from coated steel drums in applications where corrosion resistance matters less than weight reduction.
EPA hazardous waste manifest digitization mandates are forcing drum fabricators to embed scannable identifiers and lot-tracking capabilities. The industrial consequence is a shift toward smart-container contracts where drum suppliers guarantee data interoperability with shipper ERP systems. Pharmaceutical compounders in New Jersey and Massachusetts are most affected, requiring serialization that extends from drum manufacture through final disposal.
Chemical processors are consolidating vendor lists and awarding multi-year integrated contracts that bundle drum supply with reverse logistics and reconditioning. Independent drum distributors are being displaced by direct manufacturer relationships with dedicated account teams. This pattern is most visible among Gulf Coast refiners seeking single-source accountability for hazardous material containment compliance.
Corrugated Open-Head Drums Market Segmentation
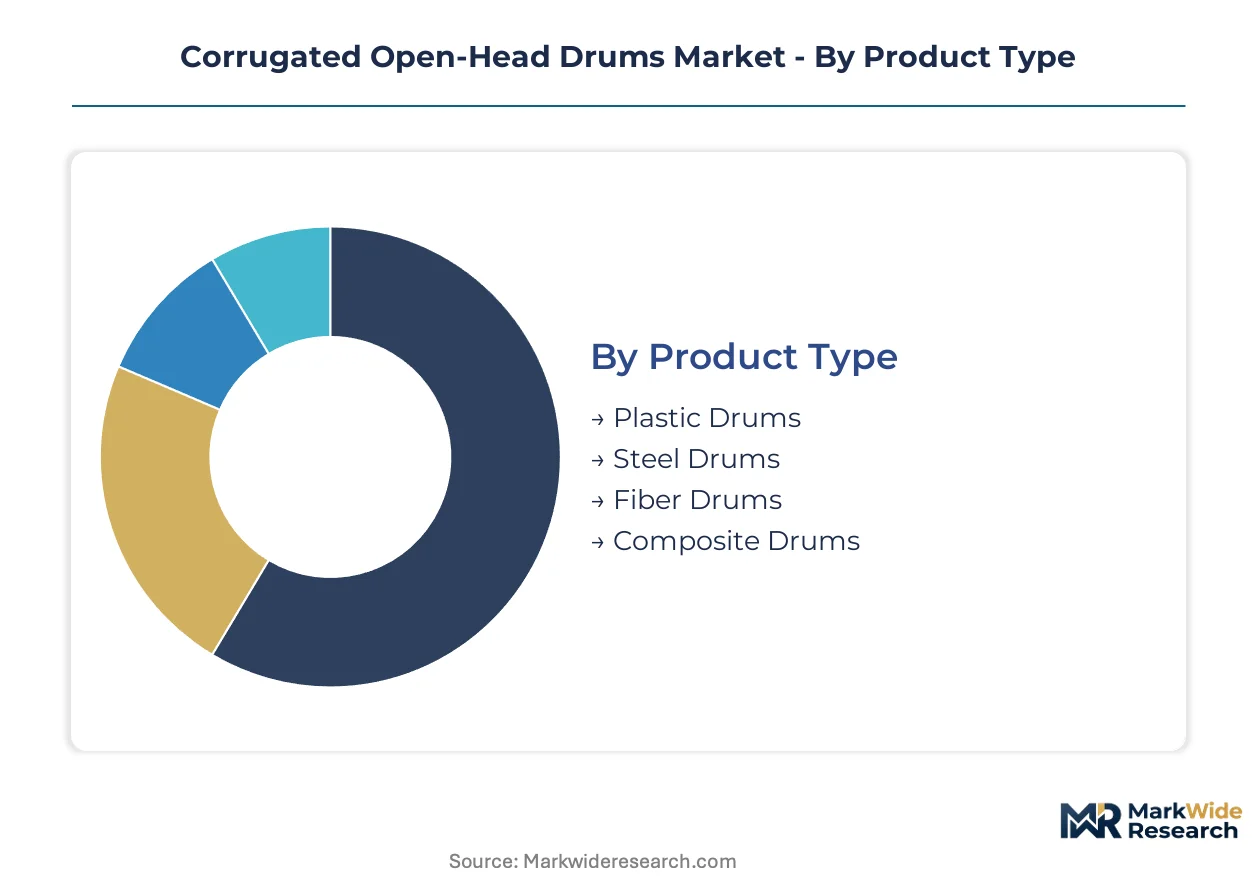
Drum specification varies sharply across chemical, food, and pharmaceutical supply chains. UN certification requirements and material compatibility rules force buyers into rigid segment selection. Suppliers must align fabrication capacity with the capital intensity and volume profiles of each category.
Product Type:
Steel drum fabrication demands the heaviest capital outlay for corrugation presses and seam welding equipment. Fiber drum lines require lower fixed investment but carry higher raw material exposure to linerboard supply volatility.
- Steel Drums:Cold-rolled steel construction with reinforced chimes and gasketed closures dominates hazardous chemical logistics. Gulf Coast petrochemical processors specify these for RCRA-regulated waste streams and DOT interstate shipments.
- Fiber Drums:Multi-layer kraft fiberboard with optional vapor-deposited aluminum barriers serves moisture-sensitive agricultural chemicals. Mississippi Delta distributors are converting volume from steel for fungicide and herbicide shipments where weight reduction cuts freight spend.
- Plastic Drums:HDPE blow-molded construction displaces steel in food-grade and cosmetic liquid applications.
- Composite Drums:Hybrid steel-fiber or plastic-steel laminates address niche UN-certification requirements.
Most installed capacity flows through Steel Drums. Expansion is steepest in Fiber Drums.
Material:
Raw material selection locks in performance characteristics and regulatory compliance pathways from the point of drum fabrication.
- Steel:Cold-rolled sheet with epoxy phenolic or lined coatings provides structural integrity for hazardous liquids. Beaumont-area refiners specify steel for sulfuric acid and caustic soda containment under EPA RCRA subtitle C.
- Fiberboard:High-performance kraft liner from southeastern US mills forms the structural shell of agricultural chemical containers. Vapor-deposited aluminum coatings add moisture barriers without steel's tare weight penalty.
- Polyethylene:HDPE resin offers corrosion resistance and reduced weight for non-hazardous liquids.
- Aluminum:Lightweight metal drums serve specialized pharmaceutical and food applications.
Steel commands the dominant share of material throughput. Fiberboard is climbing the fastest on agricultural chemical demand.
End User:
End-use concentration determines certification tier, service model, and pricing structure across the drum supply base.
- Chemicals:Petrochemical processors and specialty chemical manufacturers drive volume for UN-certified hazardous material containers. Integrated drum-service contracts bundle supply with reconditioning and reverse logistics.
- Pharmaceuticals:Contract manufacturing organizations handling potent active ingredients require single-use fiber drums with integrated containment. FDA track-and-trace mandates push demand toward RFID-enabled smart containers.
- Food & Beverage:Processors specify food-grade HDPE or lined steel for edible oils and syrups.
- Agriculture:Crop protection compounders favor moisture-barrier fiber drums for humid storage conditions.
Chemical end users absorb the largest share of drum shipments. Pharmaceuticals show the steepest expansion trajectory on serialization requirements.
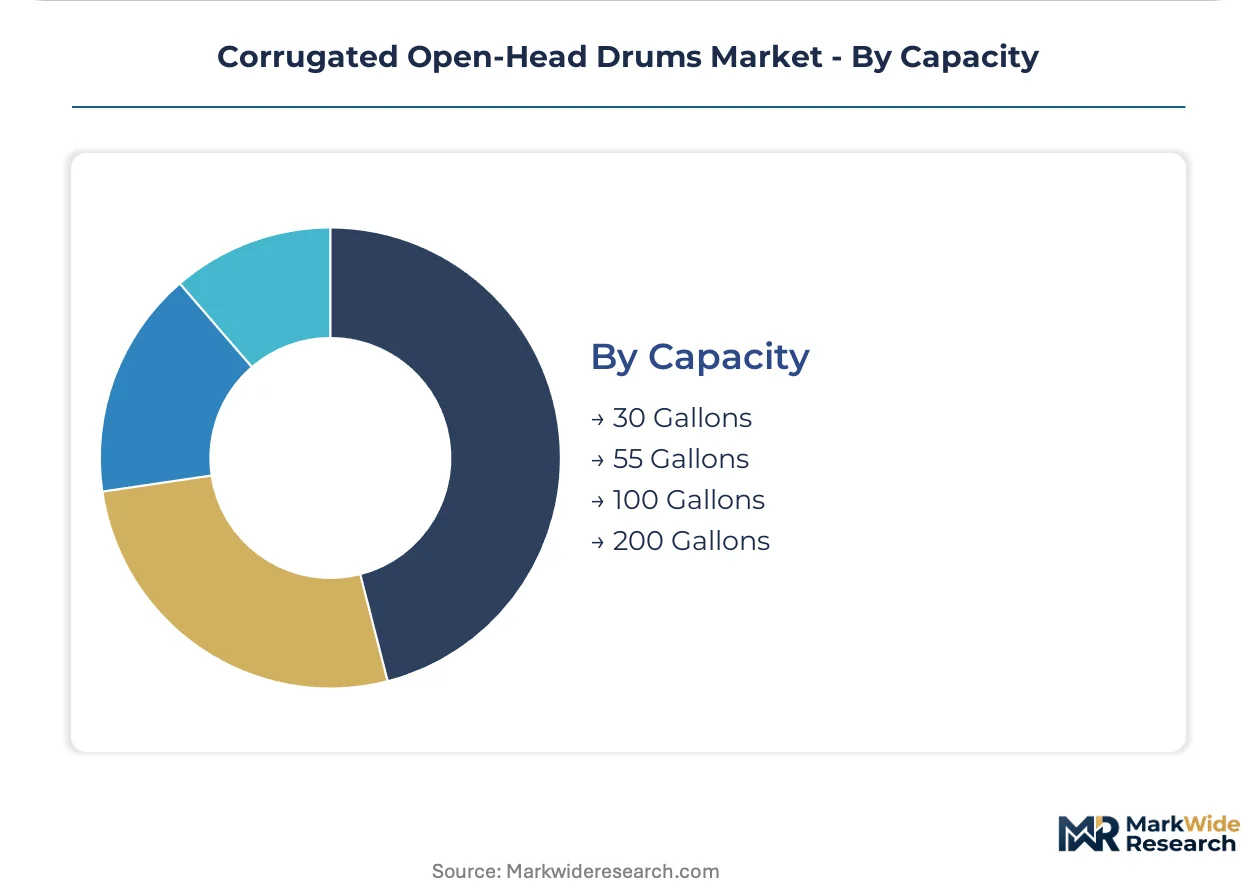
Capacity:
Volume standardization enables interchangeability across chemical logistics networks while creating economies in fabrication and reconditioning.
- 55 Gallons:The dominant specification for chemical and petroleum product shipments. DOT regulations and UN performance testing protocols are optimized around this capacity tier.
- 30 Gallons:Compact format for specialty chemicals and pharmaceutical intermediates. New Jersey compounders specify this capacity for potent active ingredient shipments requiring limited batch sizes.
- 100 Gallons:Intermediate volume for bulk liquid food ingredients.
- 200 Gallons:Maximum standard capacity for non-hazardous liquids and semi-solids.
Most drum fleets operate at the 55-gallon specification. 30-gallon formats are expanding most quickly on pharmaceutical demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's chemical logistics sector demands higher UN-certified drum volumes than France's agricultural packaging base, yet both markets operate under distinct regulatory pressures that shape supplier strategies.
United States
Gulf Coast petrochemical corridors around Beaumont and Lake Charles drive concentrated demand for hazardous material containment. EPA RCRA subtitle C regulations mandate drum integrity standards for waste streams, forcing fabricators to maintain certified production lines. Texas refiners are consolidating vendor lists toward integrated drum-service contracts that bundle supply with reverse logistics.
Germany
Ruhr Valley chemical processors and Bavarian pharmaceutical compounders anchor European demand for precision-engineered containers. ECHA REACH compliance requirements govern material compatibility declarations for drums entering chemical supply chains. Ludwigshafen-area producers are specifying smart-container formats with embedded traceability to meet EU serialization mandates.
China
Yangtze River Delta chemical manufacturers and Pearl River Delta export processors generate volume for both domestic-use and international-shipment drums. NMPA regulations align with UN performance testing protocols for pharmaceutical packaging exports. Shanghai-area fabricators are expanding moisture-barrier fiberboard capacity to serve agricultural chemical producers in Jiangsu province.
India
Gujarat's specialty chemical belt and Maharashtra's pharmaceutical clusters drive drum procurement for hazardous and hygroscopic materials. CDSCO track-and-trace requirements are pushing contract manufacturers toward serialized container formats. Mumbai-Pune corridor distributors are converting from steel to vapor-deposited aluminum barrier drums for humid-season crop protection shipments.
Brazil
São Paulo state's agrochemical formulators and Rio Grande do Sul food processors split demand between fiber and HDPE drum specifications. ANVISA pharmaceutical packaging regulations require documentation chains for active ingredient shipments. Campinas-area logistics providers are building closed-loop recovery networks to serve extended producer responsibility frameworks under discussion in federal legislation.
Corrugated Open-Head Drums Market Competitive Environment
North American producers anchor one tier; European fiberboard specialists hold differentiated positions in moisture-barrier applications. The vendor base clusters around three strategic archetypes: integrated steel-fabrication conglomerates with reconditioning networks, fiber drum specialists leveraging linerboard supply relationships, and diversified packaging multinationals with cross-material portfolios. Competitive positioning hardens through multi-year service contracts and geographic proximity to petrochemical demand corridors. Momentum concentrates in backward integration into linerboard supply and captive reconditioning facility expansion.
Among North American fabricators, Greif and Mauser Packaging Solutions exemplify the integrated-service archetype, while Sonoco Products Company occupies a position within fiber-specialist tiering. These entities represent contrasting strategic postures: steel-centric reconditioning networks versus engineered fiberboard formulations for agricultural chemical protection. Their collective positioning illustrates how supplier selection criteria have shifted from unit pricing toward cradle-to-grave accountability and regulatory compliance guarantees.
| Leading Market Players |
|---|
| Greif |
| Sonoco Products Company |
| Mauser Packaging Solutions |
| Schutz Container Systems |
| DS Smith plc |
| Mondi Group |
| WestRock Company |
| International Paper Company |
| Smurfit Kappa Group |
| Others |
Value Chain & Pricing Dynamics
Captive reconditioning networks anchor both supply security and pricing power for drum fabricators serving Gulf Coast petrochemical processors. Greif and Mauser Packaging Solutions leverage backward integration into closed-loop recovery systems to lock in multi-year service contracts that bundle container supply with reverse logistics, insulating margin structures from spot-market volatility in cold-rolled steel and linerboard inputs.
Pricing Analysis
Capacity additions in Texas and Louisiana are reshaping price floors for UN-certified steel drums as regional fabrication density intensifies competition for refinery contracts. Three-tier pricing structure across premium UN-certified, standard industrial-grade, and economy non-hazardous tiers reflects differentiation by certification level and after-sales reconditioning bundling. Cost compression in standard-grade steel drums is intensifying because multi-year contract structures prevent full pass-through of scrap metal arbitrage swings. Agricultural chemical packagers in the Mississippi Delta show highest price sensitivity, while pharmaceutical contract manufacturers accept premium positioning for single-use containment systems.
Supply Chain Analysis
Domestic-content mandates for federal procurement and Buy America provisions are reshaping sourcing patterns for steel sheet and fiberboard liner inputs. Drum fabrication draws from cold-rolled steel mills concentrated in Indiana and Ohio, high-performance kraft linerboard from southeastern US pulp operations, and HDPE resin from Gulf Coast petrochemical complexes. Single-source vulnerability in linerboard supply creates disruption risk for agricultural chemical packagers dependent on moisture-barrier fiber drums. Distribution runs through direct manufacturer relationships with integrated service contracts displacing independent drum distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily because regulatory tightening around hazardous waste containment perpetually refreshes demand for certified replacement fleets.
For Market Incumbents: Deploy captive reconditioning capacity as the primary defensive lever. Expand EPA RCRA-permitted cleaning facilities near Beaumont and Lake Charles to capture extended producer responsibility fees under California and Oregon recovery mandates. HDPE substitution in food-grade liquids threatens permanent volume displacement; counter by deepening fiberboard formulation R&D for agricultural chemical moisture protection. For New Entrants and Emerging Players: E-commerce-enabled direct procurement platforms offer the most viable entry vector. Target pharmaceutical contract manufacturing organizations in New Jersey and Massachusetts requiring serialized single-use fiber drums with integrated containment systems. White-space exists in RFID-enabled smart-container integration for FDA track-and-trace compliance, with go-to-market anchored through technology partnerships rather than fabrication assets. For Investors and Strategic Acquirers: Roll-up economics work for regional reconditioning specialists because fragmented EPA permitting creates local monopoly positions. Five-to-ten-year viability rests on regulatory tailwinds for closed-loop recovery rather than commodity drum fabrication. Watch for state-level extended producer responsibility legislation as the inflection signal determining recovery fee capture rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Linerboard Supply | Captive kraft fiber sourcing insulates agricultural drum margins from southeastern mill downtime. |
| EPA RCRA Reconditioning Facility Expansion | Permitted cleaning capacity near Gulf Coast refiners captures closed-loop service contract premiums. |
| RFID-Enabled Smart Container Development | Serialized drum fleets meet FDA pharmaceutical track-and-trace mandates for New Jersey compounders. |
| Moisture-Barrier Fiberboard Formulation Investment | Vapor-deposited aluminum coatings displace coated steel in Mississippi Delta fungicide shipments. |
| Long-Term Integrated Service Agreements | Cradle-to-grave contracts with Texas refiners bundle supply with reverse logistics and recertification. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from drum fabrication plant managers, petrochemical procurement leads at Gulf Coast refiners, agricultural chemical distribution channel partners, and EPA regulatory compliance officers. Secondary validation drew from DOT hazardous materials shipping data, EPA RCRA enforcement records, ACC chemical industry reports, and SEC 10-K disclosures from listed packaging conglomerates. Bottom-up demand modeling triangulated against top-down macroeconomic indicators.
Segment-weighting approaches distributed volume and value projections across material type, end-use industry, and regional production hub clusters throughout the forecast period. CAGRs derived from historical shipment trajectories, capacity expansion announcements, and regulatory mandate implementation timelines. Industry-specific inputs included UN certification approval lag times and EPA reconditioning facility permitting duration assumptions.
The model assumes a particular technology adoption path; alternative pathways for moisture-barrier fiberboard displacement of steel drums would alter the outlook. Forecasts embed assumptions around DOT enforcement intensity and state extended producer responsibility adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Collapsible Food Packaging Containers Market
Containers
Foldable Container Market
Containers
Twist Up Stick Container Market
Containers
Wet Wipes Canister Market
Containers
PP Container Liner Market
Containers
Dual-Ovenable Trays and Containers Market
Containers
Spout Containers Market
Containers
Single Wall Jars Market
Containers
APAC Container Technology Market
Containers
Tin Containers Market
Containers
Rotomolded Containers Market
Containers
EMEA Container Technology Market
Containers
Global Food Storage Container Market
Containers
Die Cut Display Container Market
Containers
Snap-Lock Container Market
Containers
Stainless Steel Cask Market