
 Crane Mats Market | 2026-2036
Crane Mats Market Size, Share, and Industry Trends Forecast 2026-2036
Crane Mats Market Analysis
Multi-source procurement is repositioning how crane mat buyers manage supply risk across North American energy corridors. Quality Mat Company anchors its position through captive hardwood mills in the Appalachian basin. Viking Mat differentiates via composite-blend R&D that extends mat lifespan in coastal salt-air environments. Beasley Group dominates the Gulf Coast rental channel, leveraging a fleet-tracking system that controls inventory turns across Louisiana and Texas job sites.
Crane mats are load-distribution platforms engineered from laminated hardwood, steel-reinforced timber, or fiber-reinforced polymer composites, typically rated for ground-bearing pressures between 200 and 1,000 pounds per square inch to prevent rutting and soil compaction beneath crawler cranes and heavy transport. Their primary purpose is creating stable, temporary roadways and work pads across unstable terrain including wetlands, muskeg, and loose fill. Composite material types are capturing margin pools as oilfield operators seek longer service intervals and reduced transport weight, while wood segments sustain volume leadership in utility transmission projects where first cost governs procurement. Deployment method insights reveal temporary onshore installations generating the highest turnover frequency, though permanent marine applications in port expansion yield superior per-unit profitability.
OSHA ground-stability standards and EPA stormwater runoff rules under the National Pollutant Discharge Elimination System are elevating product certification requirements and reshaping vendor qualification criteria for federal and state infrastructure contracts. The Army Corps of Engineers wetland crossing permits are mandating specific hardwood species and minimum thickness thresholds that constrain supplier flexibility. Buyers must monitor how emerging composite recycling protocols and state-level extended producer responsibility frameworks will alter total-cost calculations across material categories.
Market Dynamics
Composite mat technology is compressing replacement cycles across energy infrastructure corridors while EPA wetland mandates force hardwood specification upgrades that constrain supplier flexibility in federal contracting channels.
Growth Catalysts
- Wind turbine transport corridors:Great Plains states are expanding mat procurement volumes as nacelle and blade components require stabilized access roads across agricultural terrain.
- OSHA ground-stability standards:Federal safety mandates for crawler crane operations on unstable soils are elevating certified mat deployment as a non-negotiable site-preparation cost.
- Laminated oak specifications:Army Corps of Engineers wetland crossing permits are mandating minimum thickness thresholds that lock in premium hardwood demand for marsh-crossing projects.
Market Restraints
- Appalachian hardwood supply concentration:Captive mill ownership in the eastern timber basin creates geographic dependency that amplifies weather-related harvest disruptions.
- Steel-reinforced timber cost volatility:Fluctuating steel rod and plate prices inject margin unpredictability into hybrid mat manufacturing.
- Fiber-reinforced polymer technical ceiling:Current composite formulations face load-bearing pressure limitations below 600 PSI that exclude heavy-lift crawler applications.
Strategic Opportunities
- Permian Basin drilling pad density:Texas oilfield operators are consuming record mat volumes for multi-well pad construction in loose caliche soils.
- Composite recycling protocols:Emerging state-level extended producer responsibility frameworks will reward suppliers with closed-loop material recovery capabilities.
- Rental fleet digitization:GPS-enabled inventory tracking systems are opening margin expansion in contractor equipment pooling models across Louisiana job sites.
Industry Challenges
- EPA certification timeline compression:Stormwater runoff compliance under NPDES is extending vendor qualification periods for federal infrastructure bids.
- Composite-wood hybrid engineering:Cross-material design expertise remains scarce among legacy timber engineers and polymer specialists alike.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crane Mats Market |
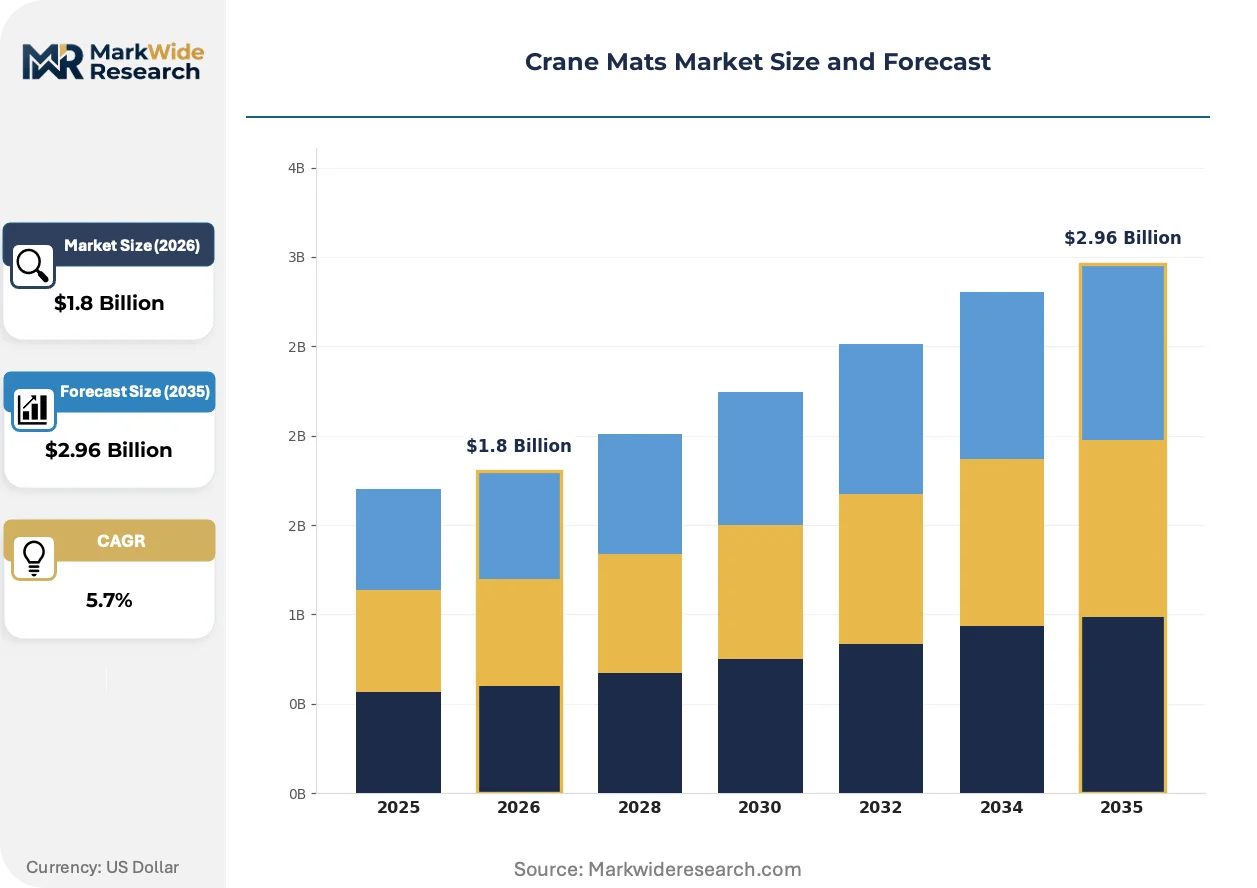
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wood, Composite, Steel, Plastic Application: Construction, Oil & Gas, Marine, Utilities Deployment Method: Onshore, Offshore, Temporary, Permanent End User: Contractors, Government, Oil Companies, NGOs |
| Companies Covered | Beasley Group, Buckeye Mats, Quality Mat Company, Spartan Composites, Viking Mat, Bridgestone Corporation, Ritter Forest Products, DICA, ESCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crane Mats Market Emerging Trajectories
Material science advances and regulatory stringency are converging to redefine performance benchmarks across temporary access infrastructure, with digital fleet management emerging as a parallel vector of competitive differentiation.
Fiber-reinforced polymer composite mats is overtaking laminated hardwood in coastal salt-air environments where moisture degradation accelerates timber replacement. Offshore wind construction contractors in the Gulf of Mexico are specifying hybrid composite platforms for jack-up barge support. This material transition is overtaking traditional oak procurement in marine applications and compressing supplier margins on untreated timber stockpiles.
EPA wetland protection rules under the Clean Water Act are mandating thicker certified barriers for marsh-crossing projects. The regulatory burden is elevating product certification requirements and disqualifying uncertified vendors from Army Corps permitting channels. Hardwood mat producers with third-party chain-of-custody documentation are capturing federal contract preference in Texas and Louisiana coastal zones.
Rental-channel consolidation is compressing equipment pooling decisions into centralized procurement desks at major energy contractors. Fleet-tracking telemetry is displacing manual inventory reconciliation across multi-state job site networks. This behavioral shift is most visible in Texas, where Permian Basin drilling pad contractors are outsourcing mat logistics to specialized rental operators with real-time availability dashboards.
Crane Mats Market Segmentation
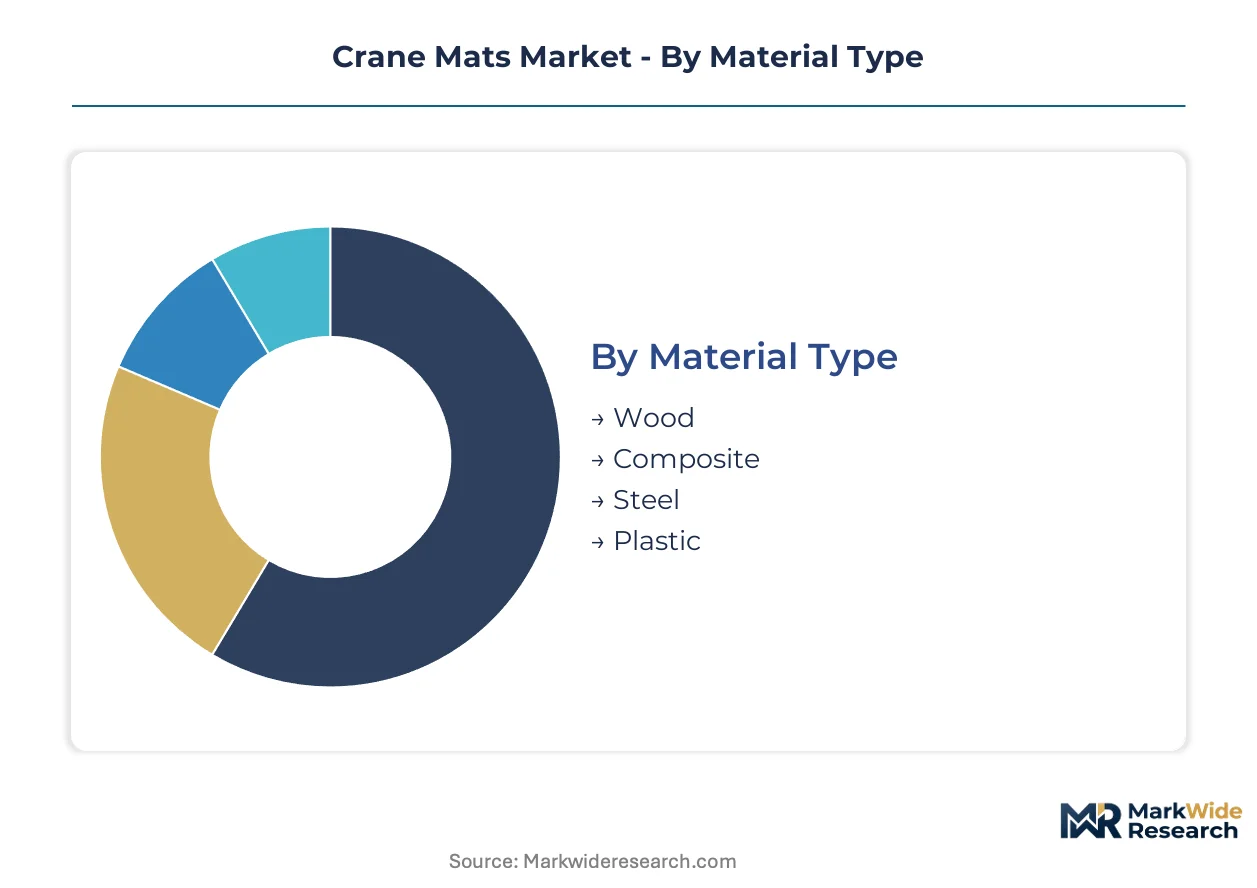
Crane mat buyers segment procurement across material durability, terrain severity, and contract duration to balance first cost against total lifecycle expenditure. Specification choices cascade through EPA compliance, OSHA ground-stability mandates, and site-specific load-bearing requirements.
Material Type:
Upgrade cycles differ sharply across material categories, with coastal corrosion and wetland immersion forcing premature retirement of untreated stock.
- Wood:Laminated oak and mixed hardwood platforms dominate utility transmission corridors where first-cost procurement governs bidding. Army Corps wetland permits in Texas and Louisiana mandate minimum thickness thresholds that lock in premium hardwood demand for marsh-crossing infrastructure.
- Composite:Fiber-reinforced polymer formulations extend service intervals in salt-air environments and reduce transport weight for offshore wind contractors. Gulf of Mexico jack-up barge operators are specifying hybrid composite platforms as moisture degradation accelerates timber replacement cycles.
- Steel:Steel-reinforced timber hybrids inject margin unpredictability from fluctuating rod and plate prices, constraining adoption to heavy-lift crawler applications exceeding 600 PSI ground-bearing pressure.
- Plastic:Recycled polymer blends serve light-duty access roads in agricultural terrain where load requirements stay below 200 PSI.
Volume placements concentrate in Wood; the faster expansion belongs to Composite.
Application:
Cost tier stratification separates speculative drilling budgets from federally funded infrastructure with rigid certification requirements.
- Construction:Wind turbine transport corridors across the Great Plains consume stabilized access roads for nacelle and blade components. OSHA ground-stability standards elevate certified mat deployment as non-negotiable site-preparation expenditure.
- Oil & Gas:Permian Basin multi-well pad construction in loose caliche soils drives record mat procurement volumes. Texas drilling contractors outsource logistics to rental operators with real-time availability dashboards.
- Marine:Port expansion projects yield superior per-unit profitability through permanent installations requiring corrosion-resistant specifications.
- Utilities:First-cost governance dominates transmission line construction where temporary access needs outlast equipment depreciation schedules.
Revenue contribution peaks in Oil & Gas; the steepest expansion trajectory runs through Construction.
Deployment Method:
Customer type determines ownership versus rental preference, with capital-constrained contractors favoring operational expenditure models.
- Onshore:Temporary onshore installations generate highest turnover frequency across agricultural and developed terrain. Fleet-tracking telemetry displaces manual inventory reconciliation across multi-state job site networks.
- Offshore:Permanent marine applications in port expansion and offshore wind construction yield superior per-unit profitability through extended depreciation horizons.
- Temporary:Short-duration rentals dominate drilling pad preparation where site mobility requirements prevent capital tie-up in owned inventory.
- Permanent:Long-horizon installations anchor specialized composite procurement for jack-up barge support infrastructure.
Turnover velocity concentrates in Temporary; margin expansion favors Permanent.
End User:
Supply concentration in Appalachian hardwood mills shapes vendor qualification timelines across federal and private procurement channels.
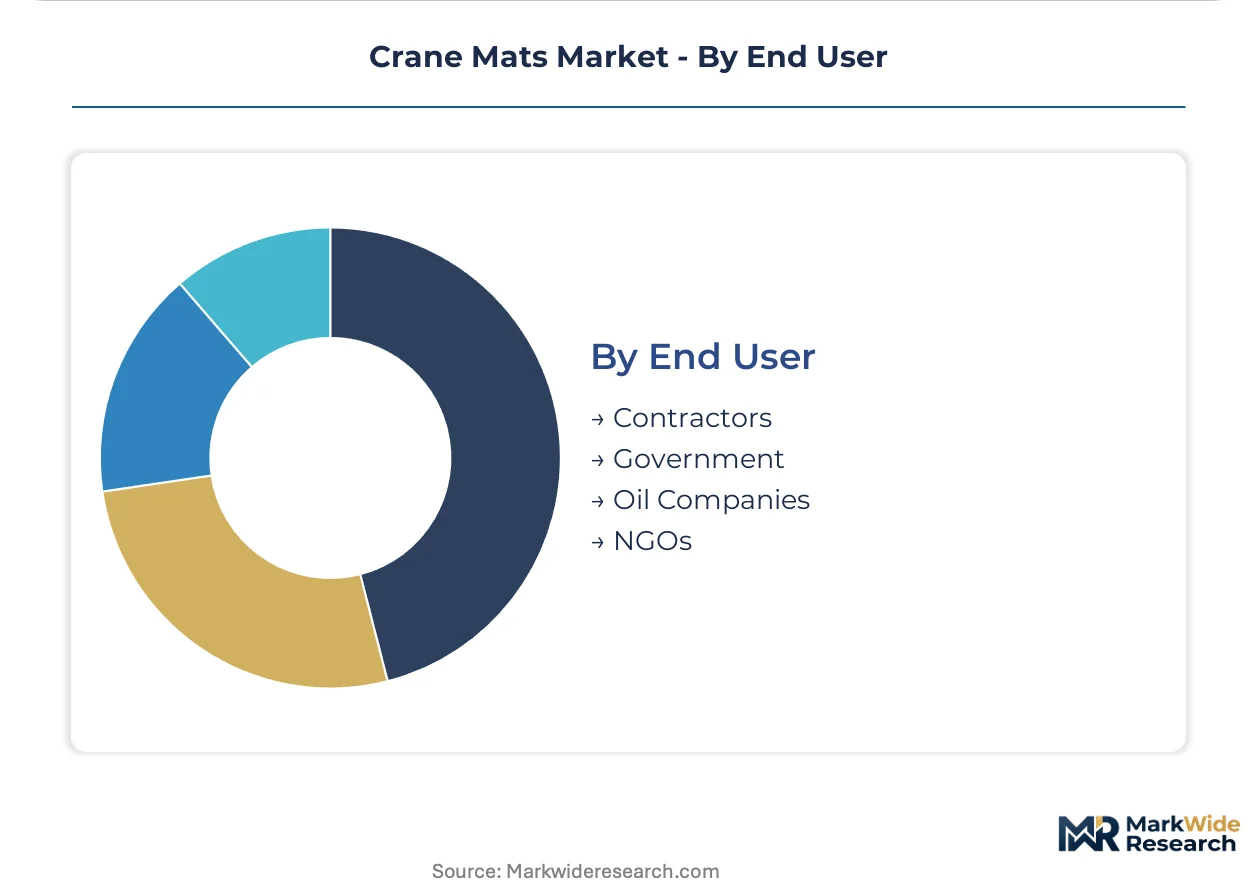
- Contractors:Energy infrastructure builders consolidate equipment pooling decisions into centralized procurement desks with GPS-enabled inventory tracking systems.
- Government:Federal infrastructure bids face extended vendor qualification periods under NPDES stormwater compliance and Army Corps wetland crossing permits.
- Oil Companies:Integrated operators in the Permian Basin consume record mat volumes while outsourcing logistics to specialized rental channels.
- NGOs:Conservation-focused organizations drive demand for certified chain-of-custody documentation in sensitive ecological corridors.
Procurement volume concentrates in Oil Companies; compliance complexity peaks with Government.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Appalachian hardwood forests anchor raw-material supply for North American mat fabrication, while regulatory divergence across federal jurisdictions shapes procurement patterns in energy corridors.
United States
Permian Basin drilling pad construction and Great Plains wind turbine transport corridors drive mat procurement volumes. EPA wetland protection rules under the Clean Water Act mandate thicker certified hardwood barriers for marsh-crossing projects. Texas and Louisiana coastal zones concentrate rental fleet operations with GPS-enabled inventory tracking.
Canada
Muskeg terrain access for oil sands operations and utility transmission line construction sustains hardwood mat demand. Federal Species at Risk Act provisions constrain harvest timing in boreal forest concessions. Alberta and Saskatchewan energy corridors host specialized rental operators serving seasonal extraction schedules.
Germany
Offshore wind construction in the North Sea and Baltic drives composite mat specification for jack-up barge support. REACH chemical regulations govern fiber-reinforced polymer formulations used in marine environments. Hamburg and Bremerhaven port clusters anchor fabrication capacity for Baltic Sea energy infrastructure.
China
Dual carbon policy targets accelerate composite mat substitution in coastal wind farm construction. MIIT industrial standards for temporary access infrastructure elevate product certification thresholds. Yangtze River Delta manufacturing clusters supply fiber-reinforced platforms for Southeast Asian export markets.
Brazil
Pre-salt offshore drilling and Amazon basin energy transport corridors create dual demand centers. ANVISA industrial safety regulations govern crawler crane ground-stability equipment deployment. Rio de Janeiro and São Paulo logistics hubs coordinate mat procurement for deepwater exploration campaigns.
Crane Mats Market Vendor Landscape
Strategic partnerships dominate the current landscape as fabricators seek to secure captive hardwood supply and composite R&D capabilities. The vendor base organizes around three tiers: integrated hardwood mill owners, composite technology specialists, and rental fleet operators with telemetry-enabled logistics. Two archetypes define competitive positioning: Appalachian basin producers leveraging vertical timber control, and Gulf Coast rental channels optimizing inventory turns through digitized fleet management. Portfolio diversification into hybrid composite-wood engineering and geographic expansion into Permian Basin job sites represent the dominant competitive vectors.
Within the integrated hardwood tier, Quality Mat Company and Ritter Forest Products exemplify producers with captive mill ownership in the Appalachian basin. Viking Mat and Spartan Composites occupy positions within the composite technology specialist archetype, while Beasley Group anchors the rental fleet operator segment with Gulf Coast concentration. These three company groupings represent distinct strategic postures: upstream timber control, material science differentiation, and logistics optimization through fleet telemetry.
| Leading Market Players |
|---|
| Beasley Group |
| Buckeye Mats |
| Quality Mat Company |
| Spartan Composites |
| Viking Mat |
| Bridgestone Corporation |
| Ritter Forest Products |
| DICA |
| ESCO Corporation |
| Others |
Supply Flow & Price Mechanics
Appalachian oak feedstock moves through captive mill networks into three-tier pricing structures that separate certified wetland-grade inventory from untreated construction stock and economy-grade mixed hardwood. Laminated timber costs cascade into project bids through Army Corps certification premiums, while composite transport savings from reduced weight reshape total-cost calculations for Gulf Coast offshore contractors.
Pricing Analysis
Warranty and service-bundling arrangements differentiate rental fleet operators from direct-sale manufacturers, with GPS-enabled logistics and site-deployment support packaged into per-day rates. Three-tier pricing structure across premium, standard, and economy levels separates Army Corps-certified wetland mats from OSHA-compliant construction grades and uncertified agricultural access panels. Cost compression in standard-grade wood segments is intensifying because steel-reinforced timber hybrids face volatile rod and plate input costs. Drilling contractors in the Permian Basin exhibit highest price sensitivity due to pad-density economics, while offshore wind developers prioritize corrosion-resistant composite performance over first-cost procurement.
Supply Chain Analysis
Domestic-content mandates under the Buy American Act reshape federal infrastructure sourcing toward Appalachian basin producers with third-party chain-of-custody documentation. Raw material supply concentrates in the United States, Canada, and Germany, with laminated oak draws from eastern hardwood forests, fiber-reinforced polymers rest on German REACH-compliant resin formulations, and steel reinforcement hinges on North American rod production. Single-source vulnerability runs through Appalachian mill ownership concentration exposed to weather-related harvest disruptions. Distribution runs through rental fleet operators with telemetry-enabled inventory management across Texas and Louisiana job site networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA wetland certification timelines and composite R&D capital requirements are forcing timber-only producers toward acquisition or exit, consolidating vendor tiers around integrated hardwood-composite capabilities.
For Market Incumbents: Deepen captive hardwood supply control through Appalachian basin mill acquisitions while accelerating hybrid composite-wood engineering investments to defend against pure polymer specialists. Lock in Army Corps pre-qualification status before NPDES stormwater compliance extends vendor review periods for federal bids. For New Entrants and Emerging Players: Conservation-focused NGOs and state-level extended producer responsibility frameworks represent underserved procurement channels demanding certified chain-of-custody documentation. Enter through composite recycling protocol partnerships that close material loops for coastal salt-air applications, leveraging technical differentiation against legacy timber incumbents. For Investors and Strategic Acquirers: Composite R&D patent filings exceeding hardwood engineering publications is the leading indicator that material transition is accelerating past timber volume leadership. Target rental fleet operators with GPS-enabled logistics platforms serving Permian Basin density, watching for inflection when federal infrastructure spending shifts toward marine and offshore wind composite specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hardwood Mills | Captive Appalachian oak supply secures Army Corps certification capacity for wetland project bids. |
| Hybrid Composite-Wood R&D Partnership | Cross-material engineering addresses 600 PSI load-bearing gaps excluding heavy-lift crawler applications. |
| GPS-Enabled Fleet Telemetry Deployment | Real-time inventory tracking compresses turnaround across Louisiana and Texas multi-site networks. |
| Closed-Loop Composite Recycling Program | State-level extended producer responsibility frameworks reward material recovery capabilities with contract preference. |
| Army Corps Pre-Qualification Investment | Third-party chain-of-custody documentation captures federal infrastructure preference in coastal zones. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across mat procurement directors at Permian Basin drilling contractors, rental fleet operations managers in Louisiana, composite R&D leads at marine engineering firms, and hardwood mill procurement heads in Appalachia. Bottom-up volume triangulation against top-down energy infrastructure expenditure patterns validated segment-level estimates.
Data-stream reconciliation across material type, application severity, deployment duration, and end-user procurement authority dimensions shaped projections across the analysis window. CAGRs derived from segmented demand elasticity modeling incorporating EPA regulatory enforcement trajectories, OSHA ground-stability mandate expansion, and wind turbine transport corridor development schedules.
Revisions become necessary when Army Corps wetland permit thresholds shift, composite load-bearing formulations breach 600 PSI technical ceilings, or Appalachian hardwood harvest disruptions exceed seasonal norms. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Crawler Crane Market
Material Handling Equipment
Asia-Pacific Conveyors Market
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Air/Pneumatic Balancers Market
Material Handling Equipment
Tree Milling Machine Market
Material Handling Equipment
Electric Single Beam Crane Market
Material Handling Equipment
Cherry Picker Crane Market
Material Handling Equipment
Hi Lift Jack Market
Material Handling Equipment
Portable Loading Ramps Market
Material Handling Equipment
Circular Stacker and Reclaimer Market
Material Handling Equipment
Europe Conveyors Market
Material Handling Equipment
Sifter Fitment Market
Material Handling Equipment
Canada Forklift Market
Material Handling Equipment
Hydraulic Hose and Fittings Market
Material Handling Equipment
Conveyor Belt Market
Material Handling Equipment
Loader Crane Market