
 Europe Non-Alcoholic Wine and Beer Market | 2026-2036
Europe Non-Alcoholic Wine and Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Non-Alcoholic Wine and Beer Market Intelligence
Multi-source ingredient procurement is rebalancing toward captive malt and hop supply contracts among large European brewers. Heineken N.V. anchors its non-alcoholic portfolio through dedicated brewing facilities in the Netherlands and Spain. Royal Swinkels Family Brewers leverages its family-owned supply chain to control raw material quality across low-alcohol variants. Carlsberg Group competes through specialized yeast strains that preserve flavor at sub-alcohol thresholds.
Europe non-alcoholic wine and beer comprises fermented beverages where alcohol content is reduced below standard thresholds through vacuum distillation, reverse osmosis, or arrested fermentation, typically yielding products under 0.5% ABV for beer and 0.5% to 1.2% ABV for wine alternatives. These products serve commercial and social consumption occasions where consumers seek sensory ritual without intoxication, particularly in hospitality and retail channels where moderation trends have institutionalized dedicated shelf space. Non-alcoholic beer leads volume throughput due to established brewing infrastructure and consumer familiarity, while sparkling wine commands premium positioning through champagne-method de-alcoholization processes that preserve effervescence structure. The keg packaging segment sustains margin pools in on-premise accounts where draft systems reduce per-unit packaging costs and support higher throughput economics.
EU REACH compliance governs processing aids and filtration materials used in de-alcoholization equipment, while EFSA labeling standards dictate how producers communicate nutritional and alcohol content claims across member states. Germany's BfR and France's DGCCRF enforce additional national thresholds for residual alcohol that shape formulation decisions and cross-border distribution eligibility. Stakeholders must monitor pending EU-wide harmonization of low-alcohol definitions that could consolidate or fragment market access rules across the continent.
Market Dynamics
The EU's updated F-Gas Regulation is compressing production timelines as brewers and vintners retool de-alcoholization equipment to meet tighter emissions standards, forcing capital reallocation across fermentation and distillation infrastructure.
Growth Catalysts
- REACH compliance modernization:ECHA's streamlined processing aid approvals are reducing formulation barriers for novel filtration materials used in vacuum distillation systems.
- Wellness-oriented social consumption:Young adult demand in Germany and the Netherlands is institutionalizing dedicated non-alcoholic beverage menus in hospitality venues.
- Reverse osmosis membrane efficiency:Advances in selective permeability technology are lowering energy requirements for alcohol separation below 0.5% ABV thresholds.
Market Restraints
- Residual alcohol threshold fragmentation:Germany's BfR and France's DGCCRF maintain divergent maximum limits, complicating cross-border formulation standardization.
- Hop and malt supply concentration:Large brewers have locked captive contracts, constraining independent producers' access to quality raw materials.
- Flavor preservation technical ceiling:Current arrested fermentation methods struggle to replicate ester profiles in wine alternatives above sparkling categories.
Strategic Opportunities
- Spain's underpenetrated on-premise channel:Draft keg systems in Andalusian and Catalan hospitality markets remain below Northern European penetration rates.
- CSRD-aligned sustainability reporting:The EU Corporate Sustainability Reporting Directive creates procurement preference for de-alcoholization processes with verified carbon footprints.
- Hybrid fermentation-arrested technologies:Converging biological and mechanical methods are opening premium positioning for complex wine alternatives.
Industry Challenges
- Specialized yeast strain cultivation expertise:Breweries lack in-house microbiology capacity to develop proprietary sub-threshold fermentation cultures.
- De-alcoholization equipment certification timelines:EFSA's evolving nutritional claim standards delay product launch schedules by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Non-Alcoholic Wine and Beer Market |
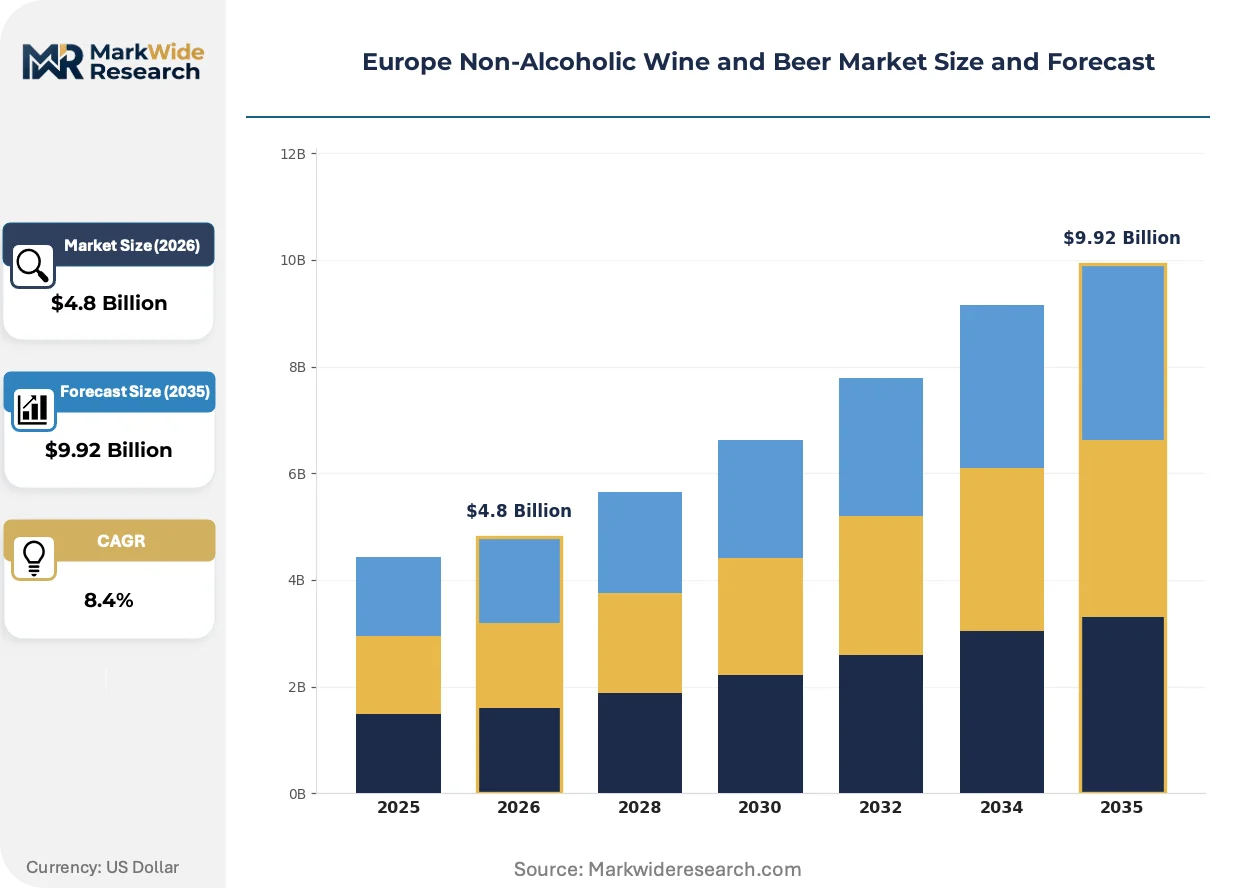
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Alcoholic Beer, Sparkling Wine, Non-Alcoholic Spirits, Low-Alcohol Wine Packaging Type: Bottle, Can, Tetra Pak, Keg Distribution Channel: Retail, Online, Supermarket, Convenience Store Consumer Age Group: Millennials, Generation X, Baby Boomers, Gen Z |
| Companies Covered | Diageo, Royal Swinkels Family Brewers, Anheuser-Busch InBev, Big Drop Brewing Company Limited, Bayerische Staatsbrauerei Weihenstephan, Heineken N.V., LVMH (Moët Hennessy), Efes Beverage Group, Carlsberg Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Non-Alcoholic Wine and Beer Market Strategic Shifts & Innovations
Production technology and regulatory frameworks are rewriting competitive boundaries as de-alcoholization methods mature and EU sustainability mandates harden compliance requirements across the value chain.
Spinning cone column distillation is rewriting energy economics in large-scale production. Netherlands-based brewing facilities have adopted this vacuum technology to reduce thermal degradation of volatile aromatic compounds. The method is compressing per-unit production costs for sub-0.5% ABV lagers while preserving mouthfeel characteristics previously lost to heat-based processes.
EFSA's harmonized labeling standards for low-alcohol claims are reshaping formulation transparency requirements. Producers must now substantiate nutritional equivalence assertions through standardized testing protocols. Sparkling wine alternatives face the steepest compliance burden as effervescence preservation claims require documented champagne-method verification.
Young adult consumers in Germany and the United Kingdom are rotating toward occasion-based purchasing rather than brand loyalty. Retailers are responding with curated moderation-focused shelf sets that displace traditional category management. Hospitality venues in Amsterdam and Berlin are deploying dedicated non-alcoholic sommelier roles to guide selection.
Europe Non-Alcoholic Wine and Beer Market Segmentation
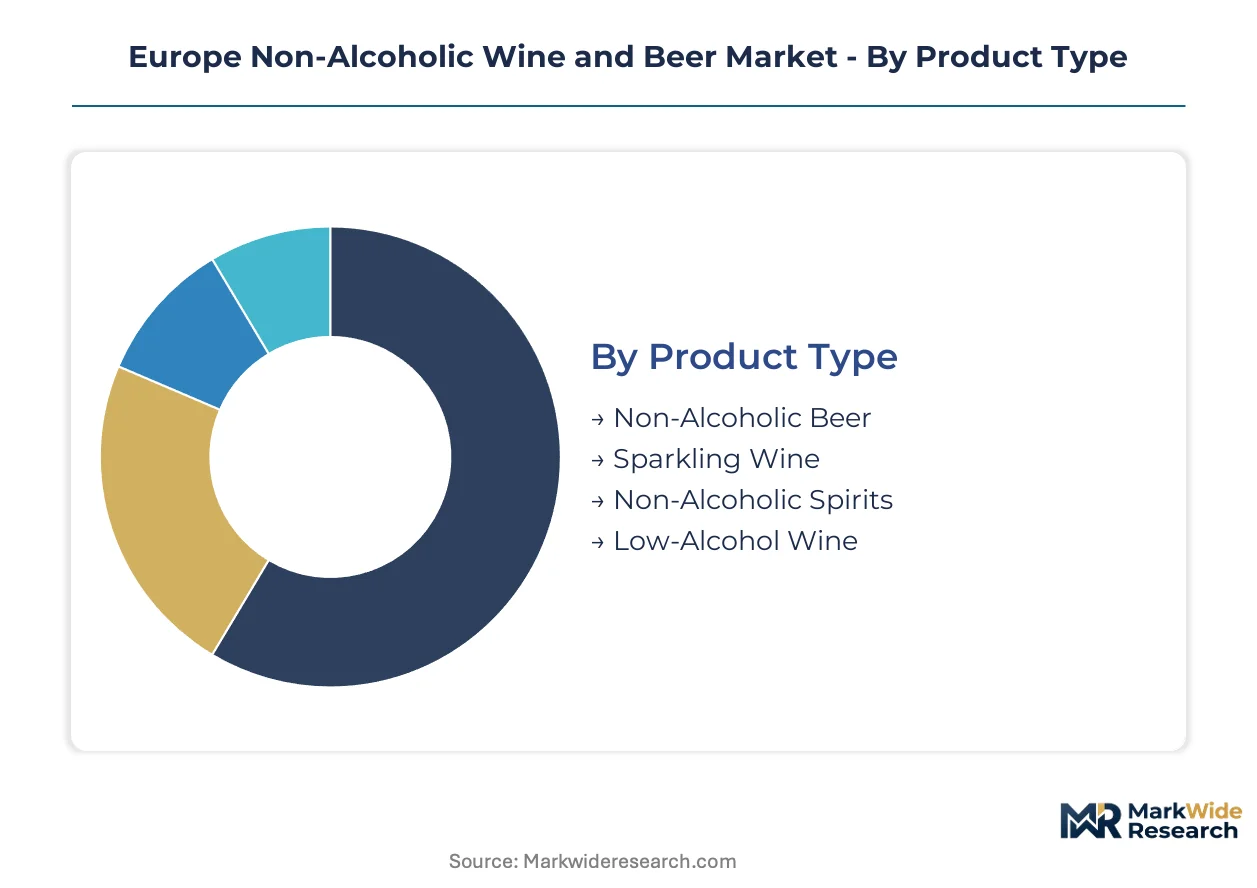
Segmentation in Europe's non-alcoholic wine and beer market reveals how capital deployment, regulatory thresholds, and channel economics concentrate value across distinct product and packaging configurations. Understanding these divides exposes where formulation investments yield margin protection versus volume capture.
Product Type:
Capital intensity varies sharply across this category, with de-alcoholization technology requirements and fermentation infrastructure demands creating tiered barriers to entry.
- Non-Alcoholic Beer:Vacuum distillation and arrested fermentation systems dominate production, with spinning cone column investments running into eight-figure euro commitments for commercial-scale facilities. German and Dutch brewers concentrate demand here, driven by hospitality venue procurement for dedicated draft lines and wellness-oriented social consumption occasions.
- Sparkling Wine:Champagne-method de-alcoholization preserves effervescence structure through precise pressure-controlled membrane separation, requiring specialized equipment that smaller producers cannot access. Spanish and Italian demand clusters around premium positioning in on-premise accounts where sommelier-guided selection justifies price premiums.
- Non-Alcoholic Spirits:Botanical extraction and flavor reconstruction without ethanol base demands iterative R&D cycles and sensory panel validation.
- Low-Alcohol Wine:Still wine alternatives face technical ceilings in ester profile replication, constraining expansion beyond basic table wine positioning.
Non-alcoholic beer absorbs the bulk of installed capacity; sparkling wine is expanding most quickly.
Packaging Type:
Channel economics and consumption occasion fragmentation are rebalancing investment priorities across material formats and dispensing systems.
- Bottle:Glass remains the default for wine alternatives and premium beer positioning, with lightweighting investments reducing transport costs while preserving shelf presence in retail environments. German supermarkets anchor volume here, though sustainability pressures from the EU Green Deal are accelerating scrutiny of embodied carbon in glass production.
- Can:Aluminum formats are capturing share in outdoor and convenience-oriented consumption, with inline printing technology enabling small-batch craft positioning that resonates with Amsterdam and Berlin's young adult demographics seeking moderation without ritual sacrifice.
- Tetra Pak:Aseptic carton systems serve value-tier beer in Southern European markets where ambient distribution reduces cold chain costs.
- Keg:Stainless steel dispensing systems sustain margin pools in on-premise accounts, with per-unit packaging cost reductions supporting higher throughput economics in Dutch and British hospitality venues.
Bottle formats retain the greatest installed base; can packaging is climbing the fastest among new capacity additions.
Distribution Channel:
Regulatory compliance burdens and margin structures are concentrating producer attention on channel-specific formulation and labeling investments.
- Retail:Dedicated shelf space for moderation-focused sets requires slotting fee negotiations and EFSA-compliant nutritional claim substantiation, with British and German multiples leading category management institutionalization.
- Online:Direct-to-consumer platforms bypass traditional wholesale markups but face fragmented national alcohol shipping regulations that complicate cross-border fulfillment.
- Supermarket:Volume concentration here demands price competitiveness that favors scaled producers with captive malt supply contracts.
- Convenience Store:Impulse-oriented purchasing patterns favor single-serve can formats and recognizable brand marks over craft positioning.
Supermarket channels command the greatest volume throughput; online distribution is gaining share fastest among emerging routes to market.
Consumer Age Group:
Occasion-based purchasing patterns and wellness narrative receptiveness are segmenting marketing investment and product development priorities.
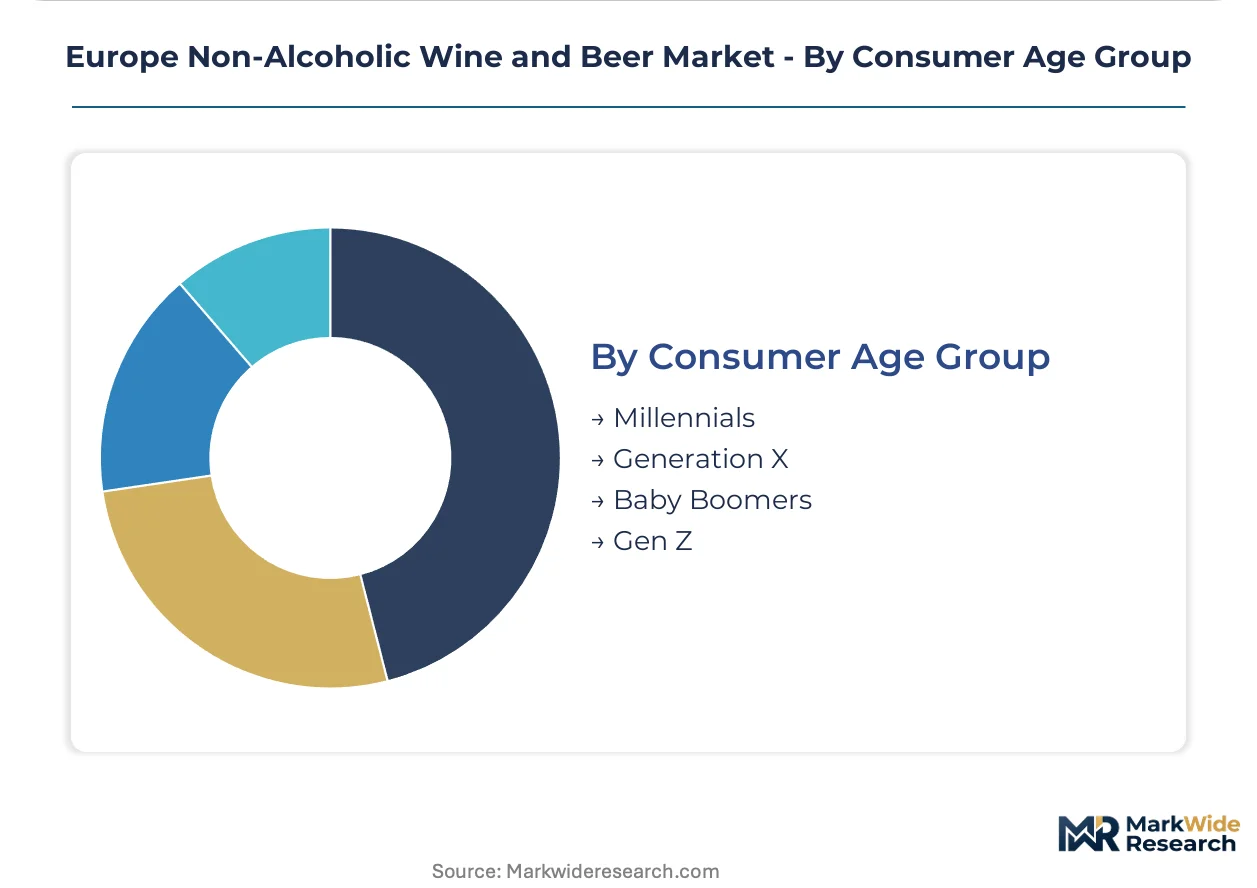
- Millennials:This cohort institutionalized moderation as social signal, driving hospitality venue adoption of dedicated non-alcoholic menus in London and Berlin.
- Gen Z:Digital-native discovery patterns favor curated online platforms and influencer-validated brands over legacy brewery portfolios.
- Generation X:Health-transition motivations dominate, with medical consultation and fitness integration supporting premium price acceptance.
- Baby Boomers:Medical necessity and medication interaction concerns sustain demand for wine alternatives in traditional consumption occasions.
Millennials represent the largest addressable base; Gen Z is expanding most quickly as legal drinking age entry coincides with moderation trend institutionalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malt and hop cultivation in Bavaria and Baden-Württemberg anchors Central European supply security for de-alcoholization facilities. The regional market concentrates where brewing heritage intersects with wellness-oriented consumption infrastructure.
Germany
Dedicated non-alcoholic draft lines in Berlin and Munich hospitality venues drive on-premise volume. BfR residual alcohol thresholds shape cross-border formulation decisions for producers seeking federal distribution eligibility. Bavarian brewing clusters around Munich and Ingolstadt host specialized arrested fermentation facilities serving domestic and export markets.
Netherlands
Rotterdam-Amsterdam logistics corridors enable efficient raw material throughput for large-scale vacuum distillation operations. REACH compliance modernization through ECHA streamlines processing aid approvals for novel filtration materials. Dutch facilities in Zoeterwoude and 's-Hertogenbosch lead spinning cone column adoption for thermal-sensitive aromatic preservation.
Spain
Sparkling wine alternatives command premium positioning in Barcelona and Madrid on-premise accounts where sommelier-guided selection justifies price premiums. DGCCRF-aligned labeling standards from neighboring France influence formulation transparency requirements for cross-border producers. Catalan and Andalusian hospitality markets show underpenetrated draft keg systems relative to Northern European benchmarks.
United Kingdom
Millennial-driven moderation trends in London institutionalize dedicated non-alcoholic beverage menus across hospitality venues. EFSA nutritional claim substantiation requirements govern slotting fee negotiations with British supermarket multiples. Southeast England retail clusters pioneer curated moderation-focused shelf sets displacing traditional category management.
France
Champagne-method de-alcoholization expertise in Reims and Épernay preserves effervescence structure for premium wine alternatives. DGCCRF enforces national residual alcohol thresholds divergent from German BfR standards, complicating unified formulation strategies. Île-de-France hospitality networks in Paris integrate dedicated non-alcoholic sommelier roles for occasion-based consumer guidance.
Europe Non-Alcoholic Wine and Beer Market Key Industry Players
Global majors compete with regional champions across production technology and distribution reach. The vendor base organizes around scale-driven brewing conglomerates, family-owned supply chain specialists, and craft-positioned innovators. Three archetypes dominate: integrated multinationals with captive malt contracts, heritage family brewers leveraging vertical control, and agile craft specialists exploiting occasion-based purchasing shifts. Competitive moves concentrate on M&A for de-alcoholization technology access and strategic partnerships for hospitality channel penetration.
Among integrated brewing conglomerates, Heineken N.V. and Carlsberg Group occupy positions exemplifying multinational scale advantages in specialized yeast strain development and dedicated facility investment. Royal Swinkels Family Brewers represents the family-owned archetype where supply chain control supports quality consistency across low-alcohol variants. These three entities anchor the competitive structure through divergent strategic postures around technology licensing versus in-house capability building.
| Leading Market Players |
|---|
| Diageo |
| Royal Swinkels Family Brewers |
| Anheuser-Busch InBev |
| Big Drop Brewing Company Limited |
| Bayerische Staatsbrauerei Weihenstephan |
| Heineken N.V. |
| LVMH (Moët Hennessy) |
| Efes Beverage Group |
| Carlsberg Group |
| Others |
Cost & Logistics Intelligence
Large-scale German and Dutch hospitality procurement consortia command substantial volume leverage, compressing margins for producers lacking captive malt contracts or dedicated de-alcoholization facilities. Price formation in Europe's non-alcoholic wine and beer market hinges on the divergence between premium champagne-method positioning and value-tier arrested fermentation supply.
Pricing Analysis
After-sales technical support and sommelier training programs are increasingly unbundled from base product pricing, with hospitality venues paying separately for draft system maintenance and staff certification. Three-tier pricing structure across premium, standard, and economy levels separates champagne-method sparkling wine alternatives from vacuum-distilled lagers and basic arrested fermentation table wines. Cost compression in the standard tier is intensifying because EFSA labeling compliance delays extend product launch cycles and inflate working capital requirements. Independent craft producers exhibit the highest price sensitivity, while integrated brewing conglomerates with captive supply chains maintain pricing discretion through volume scale advantages.
Supply Chain Analysis
Dual-sourcing mandates from British and German supermarket multiples require producers to qualify at least two distinct malt suppliers and separate membrane filtration equipment vendors, complicating procurement standardization. Raw material sourcing draws from Bavarian hop cultivation regions, Dutch barley processing facilities, and Spanish grape concentrate suppliers. Supply chain risk centers on single-source vulnerability in specialized yeast strain cultivation, where proprietary microbiology capabilities concentrate among three integrated brewing groups. Distribution runs through Rotterdam-Amsterdam logistics corridors for Northern European markets and overland trucking networks for Southern European penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's non-alcoholic wine and beer market is consolidating around producers with captive de-alcoholization technology and compliant labeling infrastructure, as EFSA harmonization delays and REACH modernization costs force sub-scale operators toward exit or acquisition.
For Market Incumbents: Deepen backward integration into specialized yeast strain development to preserve flavor profiles at sub-0.5% ABV thresholds, insulating against emerging craft competitors exploiting occasion-based purchasing shifts. Secure dedicated draft line placements in Amsterdam and Berlin hospitality venues before independent producers achieve spinning cone column scale. Prioritize CSRD-aligned carbon footprint verification to capture procurement preference from sustainability-mandated retail buyers. For New Entrants and Emerging Players: Spanish on-premise accounts in Andalusian and Catalan markets remain underserved by draft keg infrastructure, presenting white-space entry for keg-format specialists with localized distribution partnerships. Hybrid fermentation-arrested wine alternatives targeting premium positioning face limited incumbent R&D focus, creating penetration opportunity for technology-licensed challengers. Pursue direct-to-consumer platforms with influencer-validated brand narratives to bypass supermarket slotting fee barriers. For Investors and Strategic Acquirers: The window for entry favors family-owned brewers with vertical supply chain control and established hospitality channel relationships, as multinational conglomerates seek de-alcoholization capability through acquisition rather than greenfield development. Monitor EFSA's pending harmonization of low-alcohol definitions as the critical inflection signal; regulatory consolidation would accelerate margin compression for non-compliant producers and reward early standardization investments.| Strategic Initiative | Industry Significance |
|---|---|
| Spinning Cone Column Technology Licensing | Netherlands-based facilities reduce thermal degradation costs for sub-0.5% ABV lagers. |
| CSRD-Aligned Carbon Footprint Certification | Verified sustainability reporting unlocks procurement preference from EU-mandated retail buyers. |
| Specialized Yeast Strain Acquisition | Proprietary microbiology capabilities preserve ester profiles that arrested fermentation methods fail to replicate. |
| Draft Keg System Expansion in Spain | Underpenetrated Andalusian and Catalan hospitality markets offer margin protection through per-unit packaging cost reduction. |
| EFSA Nutritional Claim Pre-Substantiation | Early standardized testing protocol adoption compresses product launch timelines by 8-14 months. |
Research Approach
Multi-period observation of EFSA labeling standard evolution, REACH processing aid approval timelines, and hospitality venue procurement patterns anchored the trend analysis, supplemented by interviews with brewing technology directors, regulatory affairs specialists at ECHA, category buyers at German and British supermarket multiples, and supply chain managers at malt processing facilities. Secondary validation incorporated EU customs trade data, EFSA guidance document repositories, SEC filings from listed brewing conglomerates, and national hospitality industry association procurement surveys. Bottom-up volume modeling triangulated against top-down market sizing from production capacity assessments across Zoeterwoude, 's-Hertogenbosch, Munich, and Barcelona facilities.
Input-output matrices mapped de-alcoholization technology adoption rates against raw material cost trajectories and regulatory compliance expenditure patterns across the projection horizon. Segmentation dimensions included product type, packaging format, distribution channel, and consumer age cohort, with additional modeling of national residual alcohol threshold divergence effects. CAGRs were derived from installed capacity expansion schedules and per-capita consumption elasticity estimates. Industry-specific forecast inputs comprised spinning cone column energy efficiency curves and EFSA harmonization probability assessments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU-wide low-alcohol definition harmonization timing and F-Gas Regulation equipment retooling cost trajectories. Deviation in EFSA nutritional claim substantiation requirements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Energy Drinks Market
Non-Alcoholic Beverages
Lemonade Market
Non-Alcoholic Beverages
Pearl Milk Tea Market
Non-Alcoholic Beverages
North America Soy Beverages Market
Non-Alcoholic Beverages
North America Bottled Water Market
Non-Alcoholic Beverages
Europe Sports and Energy Drinks Market
Non-Alcoholic Beverages
US Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Vietnam Energy Drinks Market
Non-Alcoholic Beverages
Water Vending Machine Market
Non-Alcoholic Beverages
Soft Drinks Market
Non-Alcoholic Beverages
China Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Carbonated Ready-To-Drink Tea Market
Non-Alcoholic Beverages
Isotonic Drinks Market
Non-Alcoholic Beverages
Non-Alcoholic Spirits Market
Non-Alcoholic Beverages
Iced Tea Market
Non-Alcoholic Beverages
Non-Alcoholic Malt Beverages Market