
 Lawn and Gardening Consumables Market | 2026-2036
Lawn and Gardening Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Lawn and Gardening Consumables Market Intelligence
The European Union's Farm to Fork strategy, which mandates significant reductions in chemical pesticide use, is rebalancing demand toward bio-based and organic consumables. This shift creates opportunities for companies with strong biotechnology capabilities. Scotts Miracle-Gro leverages its dominant brand recognition and extensive retail distribution network in North America. In contrast, Bayer AG competes through its R&D pipeline in crop science, developing next-generation herbicides and fungicides for both agricultural and residential markets.
Lawn and gardening consumables encompass a range of chemical and biological products designed to enhance plant growth, control pests, and manage soil health. These formulations often include specific active ingredients like nitrogen-phosphorus-potassium (NPK) for fertilizers or glyphosate for non-selective herbicides, tailored for specific outcomes. Fertilizers and pesticides together represent the core product segments by value, driven by consistent residential and commercial application needs. While the residential use segment is mature, demand from commercial landscaping for specialized soil amendments is expanding rapidly.
Product registration and labeling are governed by stringent regulations, such as those enforced by the US Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA) under REACH. In Canada, Health Canada's Pest Management Regulatory Agency (PMRA) sets similar standards for safety and efficacy. These frameworks dictate permissible active ingredients and maximum residue limits, directly influencing product development. Navigating the divergent regulatory pathways for biopesticides versus conventional chemicals is a critical strategic decision for manufacturers.
Market Dynamics
The central force is the regulatory pivot towards sustainability, which conflicts with the performance legacy of conventional chemical formulations. This tension dictates product development pathways and competitive strategy for manufacturers globally.
Growth Catalysts
- Regulatory Mandates:The European Union's Green Deal and its Farm to Fork strategy accelerate the replacement of chemical pesticides with bio-based alternatives, creating demand for new formulations.
- Commercial Landscaping Growth:Rising investment in corporate campuses, public parks, and hospitality grounds expands the market for specialized soil amendments and professional-grade pest control products.
- Suburban Housing Density:A large and stable base of suburban homeowners, particularly in the United States, provides consistent demand for residential lawn fertilizers and weed control products.
Market Restraints
- Regulatory Fragmentation:Divergent and lengthy registration timelines for biopesticides versus conventional chemicals under frameworks like the EPA in the US and ECHA in Europe create market entry barriers.
- Input Cost Volatility:Manufacturer margins are exposed to price fluctuations in key raw materials like nitrogen, phosphorus, and potassium (NPK), which are tied to global commodity markets.
- Xeriscaping Adoption:The increasing adoption of low-water landscaping, especially in drought-prone regions, reduces the total addressable area requiring traditional fertilizers and turf care products.
Strategic Opportunities
- Precision Application Technology:Development of smart-dosing systems and drone-based application for commercial use offers a new value proposition centered on efficiency and reduced environmental runoff.
- Biostimulant Formulations:Expanding beyond basic nutrients into microbial soil enhancers and biostimulants that improve nutrient uptake and plant resilience presents a high-growth product category.
- Urban Gardening Markets:The rise of vertical and container gardening in dense urban centers, particularly in Asian cities, creates a new customer segment for small-format, specialized consumables.
Industry Challenges
- Complex Labeling Compliance:Adhering to disparate and evolving product labeling requirements from regulators like Health Canada's PMRA and the US EPA demands significant and continuous investment in compliance.
- Consumer Education Gap:Overcoming homeowner skepticism about the efficacy and application methods of organic and biological alternatives compared to familiar conventional chemicals is a primary marketing hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lawn and Gardening Consumables Market |
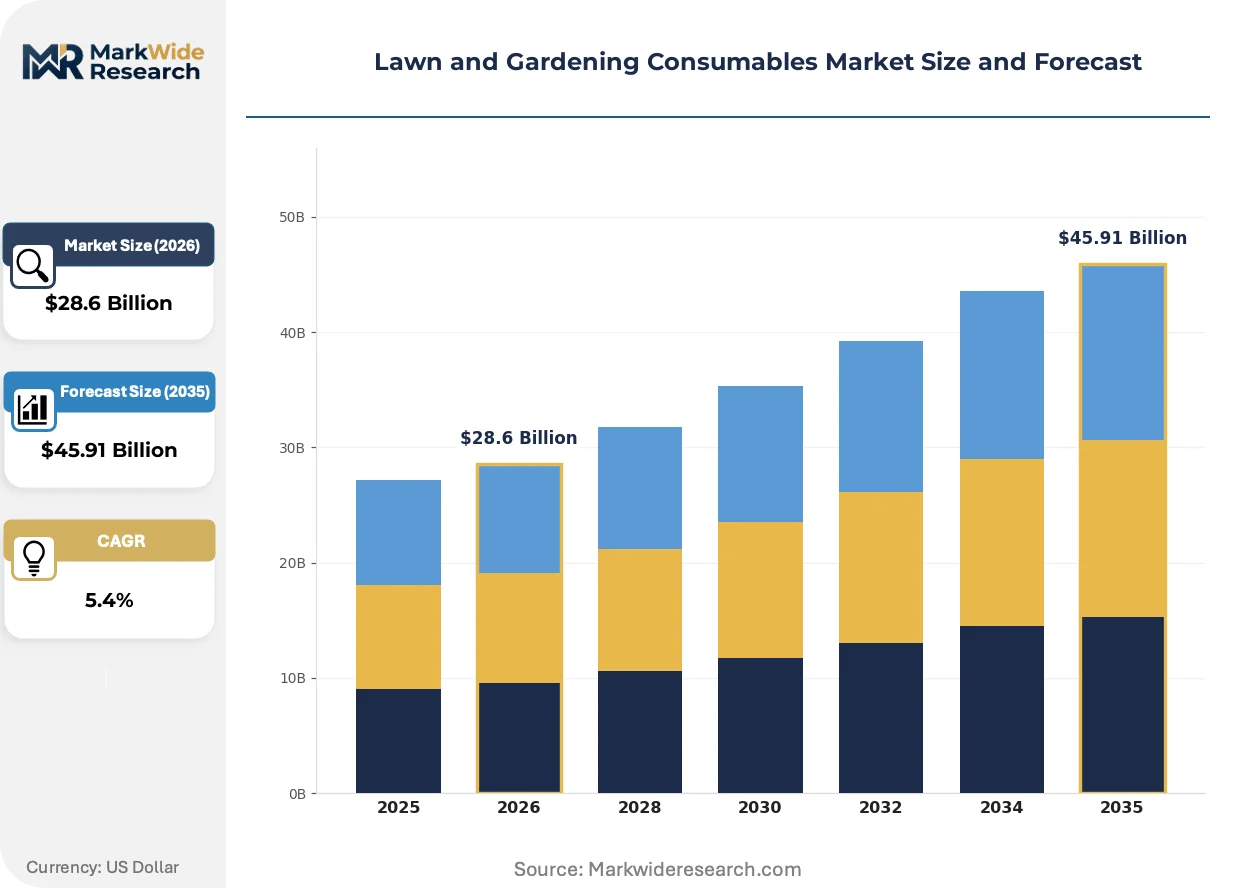
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $45.91 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fertilizers, Herbicides, Pesticides, Soil Amendments Application: Residential Use, Commercial Landscaping, Agricultural Fields, Public Parks Distribution Channel: Online Retail, Garden Centers, Home Improvement Stores, Wholesale Distributors Customer Type: Homeowners, Landscaping Companies, Agricultural Farmers, Institutional Buyers |
| Companies Covered | Scotts Miracle-Gro, Bayer AG, BASF SE, Syngenta AG, Corteva Agriscience, The Andersons Inc., Central Garden & Pet Company, Nutrien Ltd., Lebanon Seaboard Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lawn and Gardening Consumables Market Strategic Shifts & Innovations
Product innovation is pivoting from chemical potency to biological precision and sustainable delivery mechanisms. This evolution responds directly to new environmental regulations and a shift in consumer expectations toward eco-friendly lawn care solutions.
Smart-release fertilizer technology utilizes polymer coatings to control nutrient dissolution based on temperature and moisture. Commercial turf managers and golf courses are the primary adopters, seeking to maximize nutrient uptake and minimize runoff. This targeted delivery method is electrifying the professional segment by enabling precise, data-driven turf management programs.
The European Union's restrictions on neonicotinoid insecticides and glyphosate herbicides are a primary example of regulatory action reshaping product portfolios. This forces manufacturers to accelerate R&D in alternative active ingredients, including botanical oils and microbial agents. The residential pesticide segment is most impacted, with companies reformulating legacy products to maintain market access in the EU.
Subscription-based, direct-to-consumer (DTC) models for customized lawn care kits are gaining traction among homeowners. These services disrupt the traditional big-box retail channel by offering tailored fertilizer, seed, and soil amendment plans based on local climate and soil tests. This demand-side shift is most visible in the United States suburban market.
Lawn and Gardening Consumables Market Segmentation
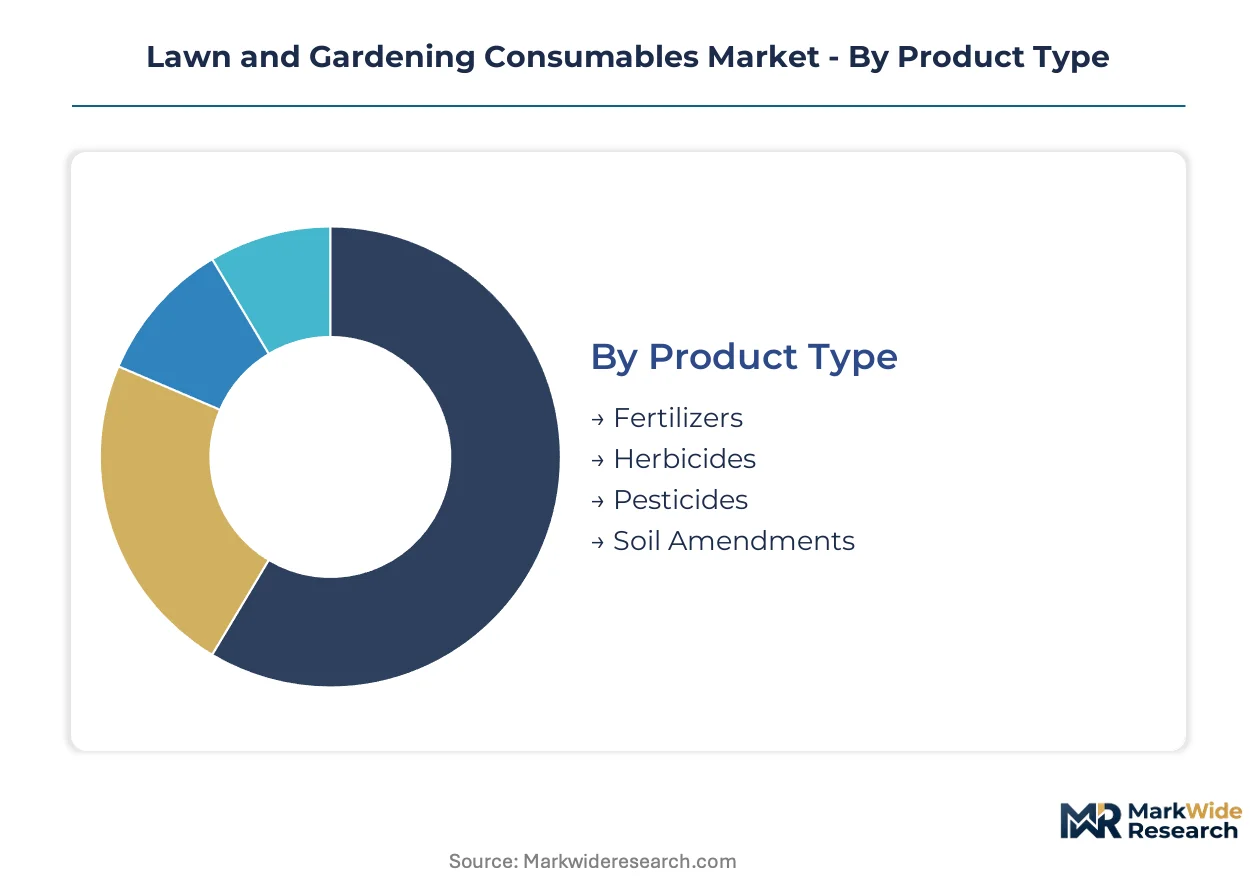
Market segmentation for lawn and gardening consumables reveals critical shifts in demand patterns and strategic priorities for manufacturers. Analyzing these distinct categories highlights how regulatory pressures and evolving consumer preferences drive product innovation and distribution strategies. Understanding these segments is essential for companies to tailor offerings and maintain competitive positioning.
Product Type:
The product type segmentation reflects distinct functional requirements and the upgrade/replacement cycles driven by regulatory changes.
- Fertilizers:These formulations supply essential plant nutrients like nitrogen, phosphorus, and potassium (NPK) to promote robust growth and improve soil fertility. Demand concentrates across both residential lawns and commercial turf applications, with smart-release technologies gaining traction for efficiency.
- Herbicides:Designed to control unwanted plant growth, herbicides include selective and non-selective chemistries, such as glyphosate-based products. Regulatory restrictions, particularly in the European Union, are accelerating demand for bio-based and alternative active ingredients.
- Pesticides:This category encompasses insecticides, fungicides, and other agents targeting pests and diseases, often containing active ingredients like neonicotinoids or botanical extracts. European Union restrictions on specific chemistries are forcing product reformulation in the residential segment.
- Soil Amendments:Products like compost, biochar, and microbial enhancers improve soil structure, water retention, and nutrient availability. Commercial landscaping projects increasingly specify specialized soil amendments to enhance plant health and reduce chemical inputs.
Fertilizers sits at the top of the volume ranking, with Soil Amendments climbing the fastest.
Application:
Application segments are differentiated by the scale of use and the complexity of product requirements, influencing formulation and delivery methods.
- Residential Use:This segment caters to individual homeowners for maintaining lawns, gardens, and ornamental plants, often involving smaller package sizes and ease-of-use formulations. Consistent demand emanates from the large suburban homeowner base in the United States.
- Commercial Landscaping:Professional landscaping companies require high-performance, specialized products for corporate campuses, sports fields, and public green spaces. Precision application technology and specialized soil amendments are critical for these large-scale operations.
- Agricultural Fields:Large-scale farming operations utilize specific consumables for crop protection, nutrient management, and soil health across vast areas. Companies like Bayer AG develop advanced herbicides and fungicides tailored for agricultural efficiency.
- Public Parks:Municipalities and public bodies manage these spaces, requiring effective pest and weed control solutions that often prioritize environmental safety and public health. Professional-grade products for turf management are frequently deployed.
Commercial Landscaping commands premium pricing, while Residential Use maintains broad accessibility.
Distribution Channel:
Distribution channels reflect varied customer preferences and procurement logistics, ranging from direct consumer access to bulk commercial supply.
- Online Retail:E-commerce platforms offer convenience and direct-to-consumer (DTC) subscription models for customized lawn care kits. This channel disrupts traditional retail by delivering tailored products directly to homeowners.
- Garden Centers:These specialized retail outlets provide expert advice, a curated selection of products, and often cater to gardening enthusiasts seeking premium or niche consumables. Local communities frequently rely on garden centers for specific plant care needs.
- Home Improvement Stores:Large retailers like Home Depot and Lowe's serve a broad customer base with a wide range of lawn and garden consumables. These stores offer accessibility and competitive pricing for common residential products.
- Wholesale Distributors:These entities supply bulk quantities of consumables to commercial landscaping companies, agricultural enterprises, and institutional buyers. Efficient logistics and large-scale inventory management are hallmarks of this channel.
Online Retail streamlines consumer access, while Wholesale Distributors ensure large-scale commercial supply.
Customer Type:
Customer types are distinguished by purchasing power, technical expertise, and specific requirements for product efficacy and application.
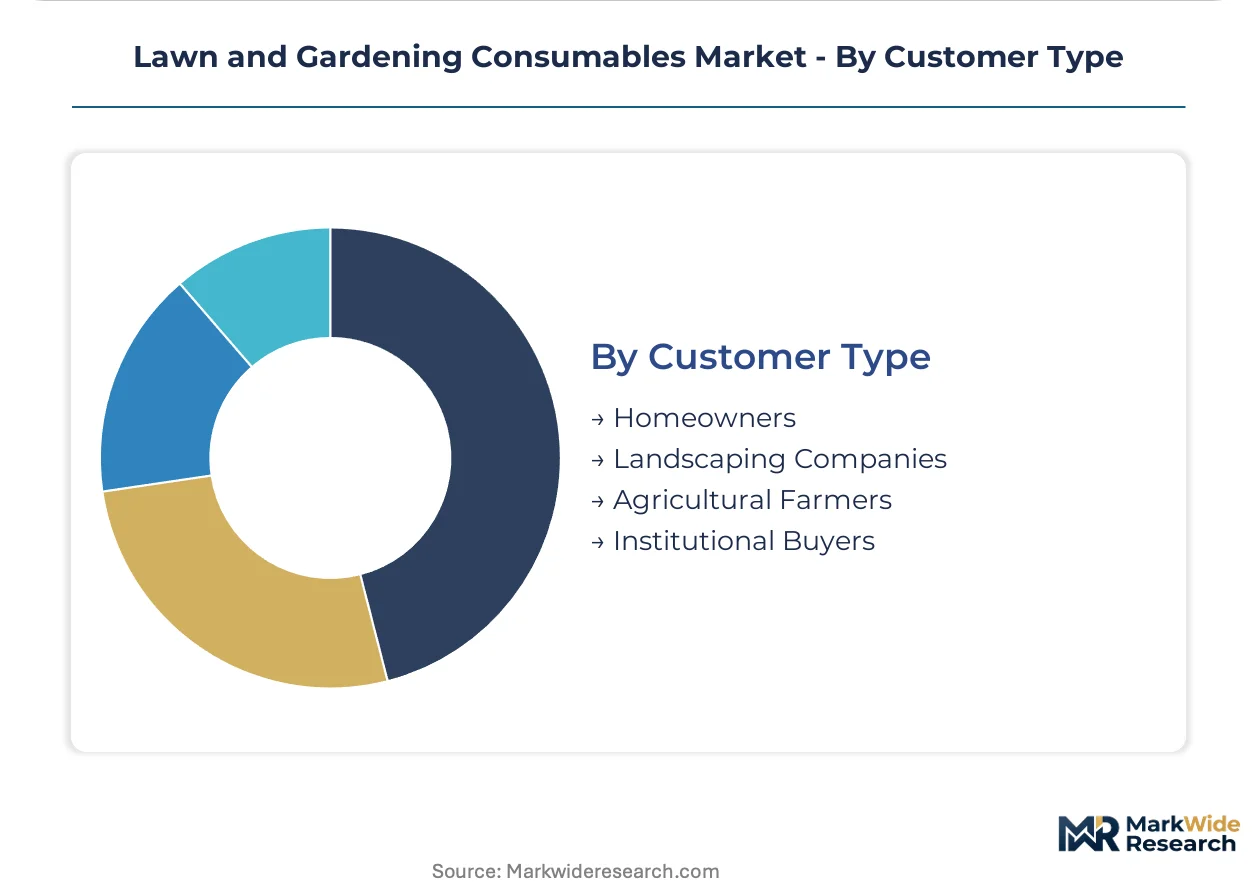
- Homeowners:This segment comprises individual property owners seeking products for personal lawn and garden maintenance, prioritizing ease of use and visible results. The United States suburban market represents a significant and stable demand base.
- Landscaping Companies:Professional firms manage outdoor spaces for commercial and residential clients, requiring high-performance, specialized products and efficient application methods. These companies often seek bulk purchasing and technical support from suppliers.
- Agricultural Farmers:Farmers purchase consumables for large-scale crop production, focusing on yield optimization, pest management, and soil fertility. Their purchasing decisions are often tied to crop cycles and specific agricultural regulations.
- Institutional Buyers:This category includes government agencies, educational institutions, and large property management groups responsible for extensive grounds. Their procurement often involves tenders and compliance with specific environmental standards.
Landscaping Companies represent a growing professional segment, while Homeowners form the market's foundational demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The lawn and gardening consumables market found early large-scale demand in regions with established suburban housing developments. Residential lawn maintenance and ornamental gardening practices created a consistent need for fertilizers and pest control solutions. This foundation has shaped demand patterns and regulatory responses across diverse geographies.
United States
Demand for lawn and gardening consumables in the United States stems from its vast suburban homeowner base. Homeowners consistently apply fertilizers and weed control products to maintain property aesthetics. The US Environmental Protection Agency (EPA) regulates permissible active ingredients for pesticides and herbicides. Large retail chains across the Midwest and Southeast facilitate broad product distribution.
Germany
German consumers and commercial landscapers increasingly prioritize eco-friendly alternatives for gardening. Stringent EU regulations, including the Green Deal, drive demand for bio-based formulations. The Rhine-Main region, a hub for chemical companies like BASF, focuses on R&D for sustainable plant protection.
Canada
Canadian homeowners and professional turf managers seek effective solutions for diverse climate conditions. Health Canada's Pest Management Regulatory Agency (PMRA) sets strict standards for product safety and efficacy. Agricultural regions in the Prairies and Ontario represent significant demand for specialized soil amendments.
France
French agricultural and residential markets are adapting to the EU's Farm to Fork strategy, which mandates pesticide reduction. This policy promotes the adoption of organic and biological pest control methods. Research clusters around Lyon and Paris are developing new biostimulant formulations.
Japan
Japanese urban gardening trends and precision agriculture practices create demand for specialized, efficient consumables. The Ministry of Agriculture, Forestry and Fisheries (MAFF) oversees product registration and quality standards. Horticultural centers in regions like Kanto are adopting advanced nutrient delivery systems.
Lawn and Gardening Consumables Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the lawn and gardening consumables market. This industry exhibits a tiered structure, with large multinational chemical companies alongside specialized biological solution providers. Strategic archetypes include integrated chemical giants, biotechnology innovators, and direct-to-consumer brand specialists. Companies pursue portfolio diversification and strategic partnerships to navigate evolving regulatory landscapes.
Within the integrated chemical giants tier, Bayer AG and BASF SE represent global players with extensive R&D pipelines for both conventional and next-generation formulations. Scotts Miracle-Gro, a prominent North American entity, exemplifies a brand-focused approach leveraging strong retail distribution. These companies navigate complex product registration processes across multiple jurisdictions. Their competitive strategies often involve reformulating existing products for market access and investing in sustainable alternatives.
| Leading Market Players |
|---|
| Scotts Miracle-Gro |
| Bayer AG |
| BASF SE |
| Syngenta AG |
| Corteva Agriscience |
| The Andersons Inc. |
| Central Garden & Pet Company |
| Nutrien Ltd. |
| Lebanon Seaboard Corporation |
| Others |
Cost & Logistics Intelligence
The European Union's Farm to Fork strategy gates both qualified supply and premium-tier pricing access for lawn and gardening consumables. This regulatory framework mandates a shift toward bio-based alternatives, creating a distinct market for compliant, often higher-priced, products.
Pricing Analysis
Per-unit transactional pricing dominates the lawn and gardening consumables market, though hybrid subscription models gain traction in direct-to-consumer channels. Brand premium from established players like Scotts Miracle-Gro and specialized formulations for commercial landscaping drive price differentiation. Pricing softness in conventional chemical segments stems from regulatory restrictions, particularly in Europe. Homeowners exhibit higher price sensitivity for basic lawn care, while commercial landscapers prioritize performance and specialized soil amendments.
Supply Chain Analysis
Dual-sourcing requirements are becoming more common for active ingredients, especially for bio-based alternatives. Supply of key raw materials like nitrogen, phosphorus, and potassium (NPK) concentrates in regions with established chemical production, such as China and parts of Europe. Botanical extracts and microbial agents often draw from specialized biotech clusters in Europe and North America. Commodity price volatility for NPK represents a structural risk. Distribution runs through a hybrid model, utilizing wholesale distributors for commercial clients and a mix of big-box retailers and online platforms for residential consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a margin-expansion story, driven by the shift towards premium bio-based formulations and efficiency gains from precision application technology.
For Market Incumbents: Anticipate continued regulatory pressure on conventional chemistries, particularly in the European Union. Diversify product portfolios by investing heavily in bio-based R&D and strategic acquisitions of biotechnology innovators. Reinforce retail channel control in North America to leverage established brand recognition. This proactive approach mitigates threats from emerging eco-friendly entrants and evolving consumer preferences.
For New Entrants and Emerging Players: The EU Green Deal in Europe opens a window for specialized bio-based formulations and precision application technologies. Target urban gardening markets in dense Asian cities with small-format, specialized consumables. Launch subscription-based, direct-to-consumer models in the United States suburban market, emphasizing tailored solutions and ease of use. This strategy allows penetration into underserved or newly created segments with high-value propositions.
For Investors and Strategic Acquirers: Roll-up economics work for specialized biotechnology innovators and precision agriculture technology firms because regulatory tailwinds create defensible niches. Focus on acquiring companies with strong intellectual property in biostimulants or microbial enhancers, which offer long-term viability over the next decade. A key signal to watch is the accelerated product registration and market approval timelines for novel biopesticides by the US EPA or European ECHA.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Bio-based Formulations | Addresses European Union Green Deal mandates for pesticide reduction. |
| Precision Application Technology Development | Enhances efficiency and reduces environmental impact for commercial landscapers. |
| Direct-to-Consumer Channel Expansion | Captures growing demand from US suburban homeowners for tailored solutions. |
| Strategic Partnerships with Biotech Firms | Accelerates portfolio diversification into organic and biological alternatives. |
| Investment in Regulatory Compliance Expertise | Navigates diverse US EPA and European ECHA frameworks for new products. |
Research Approach
Multiple input streams — primary interviews, secondary research, and quantitative modeling — were reconciled to build a comprehensive market view. Primary interviews engaged R&D directors, commercial landscaping managers, regulatory affairs specialists, and retail channel partners. Secondary data sources included regulatory documents from the US Environmental Protection Agency and European Chemicals Agency, industry association reports on NPK, and company financial filings. The approach employed both bottom-up and top-down triangulation to ensure data accuracy.
Historical data was cross-referenced with expert panel input to project market trajectories across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, distribution channel, customer type, and active ingredient chemistry. Compound annual growth rates were derived from historical trends and projected market shifts. Industry-specific forecast inputs included regulatory timelines for chemical bans and estimated adoption rates for biopesticides.
Revisions become necessary when unforeseen shifts in agricultural policy or raw material commodity prices materialize. Forecasts reflect underlying assumptions regarding technological advancements and consumer behavior. Deviation in regulatory enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
Bird House Market
Home & Garden
Outdoor Cooking Table Market
Home & Garden
Landscaping Products Market
Home & Garden
Residential Snow Blower Market
Home & Garden
Incense Market
Home & Garden
Landscaping and Gardening Service Market
Home & Garden
North America Flowerpots Market
Home & Garden
Aquarium Decor Market
Home & Garden
Christmas Decorations Market
Home & Garden
Global Hot Tub Market
Home & Garden
North America Floral Gifting Market
Home & Garden
Europe Robotic Lawn Mower Market
Home & Garden
Flower Box Market
Home & Garden
Wine Racks Market
Home & Garden
Europe Flower Pots Market
Home & Garden
Japan Flower Pots Market