
 North America Flowerpots Market | 2026-2036
North America Flowerpots Market Size, Share, and Industry Trends Forecast 2026-2036
North America Flowerpots Market Analytics
The North America flowerpots market is expanding along a widening gap between artisan ceramic collections and mass-produced polypropylene lines. THE HC COMPANIES, INC. leverages its injection-molding scale to dominate big-box garden center shelves. Bloem differentiates through color-stable resin formulations that resist UV degradation across desert climates. Crescent Garden Company anchors the premium self-watering segment with rotational-molded designs targeting commercial landscaping contracts.
North America flowerpots are horticultural containers engineered from thermoplastics, fired clay, or composite minerals, typically rated by drainage efficiency, wall thickness measured in millimeters, and freeze-thaw cycle tolerance. Their commercial purpose centers on root zone aeration, moisture regulation, and transplant mobility for ornamental and food crop cultivation. Plastic containers lead unit volume through cost efficiency in large-scale nursery operations, while ceramic commands margin concentration in direct-to-consumer channels. Online retailers represent the fastest-growing distribution vector as subscription plant services expand their fulfillment networks. Residential end users sustain the largest addressable base, though landscaping services generate higher per-project order values.
The EPA oversees recycled content claims under its Green Guides, while state-level California Air Resources Board rules restrict volatile organic compound emissions from decorative coatings on metal planters. Health Canada and PMRA jointly regulate pesticide migration from treated wood containers into edible plant applications, shaping material substitution patterns. Stakeholders must monitor evolving extended producer responsibility proposals in multiple jurisdictions that could mandate take-back programs for thermoplastic pots.
Market Dynamics
The EPA's recycled content mandates are compressing virgin polypropylene sourcing across injection-molding supply chains, forcing nursery suppliers to requalify resin formulations and retool mold designs mid-cycle.
Growth Catalysts
- California Air Resources Board VOC limits:Decorative coating restrictions on metal planters accelerate ceramic and uncoated composite substitution in premium residential channels.
- Subscription plant services:Direct-to-consumer fulfillment networks expand standardized container specifications, creating pull-through for lightweight thermoplastic designs.
- Desert climate UV exposure:Sun Belt states drive demand for color-stable resin technologies that outlast conventional polypropylene in Arizona and Nevada installations.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene pellet costs swing with natural gas liquid pricing, compressing margin predictability for high-volume nursery contracts.
- Chinese ceramic kiln concentration:Fired clay container sourcing clusters in Guangdong province, exposing US importers to tariff and shipping rate discontinuities.
- Freeze-thaw cycle tolerance gaps:Standard thermoplastic formulations crack below -15°C, excluding year-round outdoor use in northern tier states and Canadian provinces.
Strategic Opportunities
- Extended producer responsibility proposals:Pending state-level take-back mandates for thermoplastic pots create first-mover advantage for closed-loop recycling infrastructure.
- Self-watering reservoir convergence:Integration of sub-irrigation systems with rotational-molded containers opens commercial landscaping specification opportunities.
- Urban balcony gardening:Underpenetrated Canadian multi-unit residential towers represent whitespace for compact, stackable container systems.
Industry Challenges
- Resin requalification timelines:EPA Green Guides compliance documentation extends new material approval cycles by 8-14 months, delaying product launches.
- Mold cavitation retrofit costs:Transitioning injection lines to post-consumer recycled content requires capital outlays that mid-tier fabricators struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Flowerpots Market |
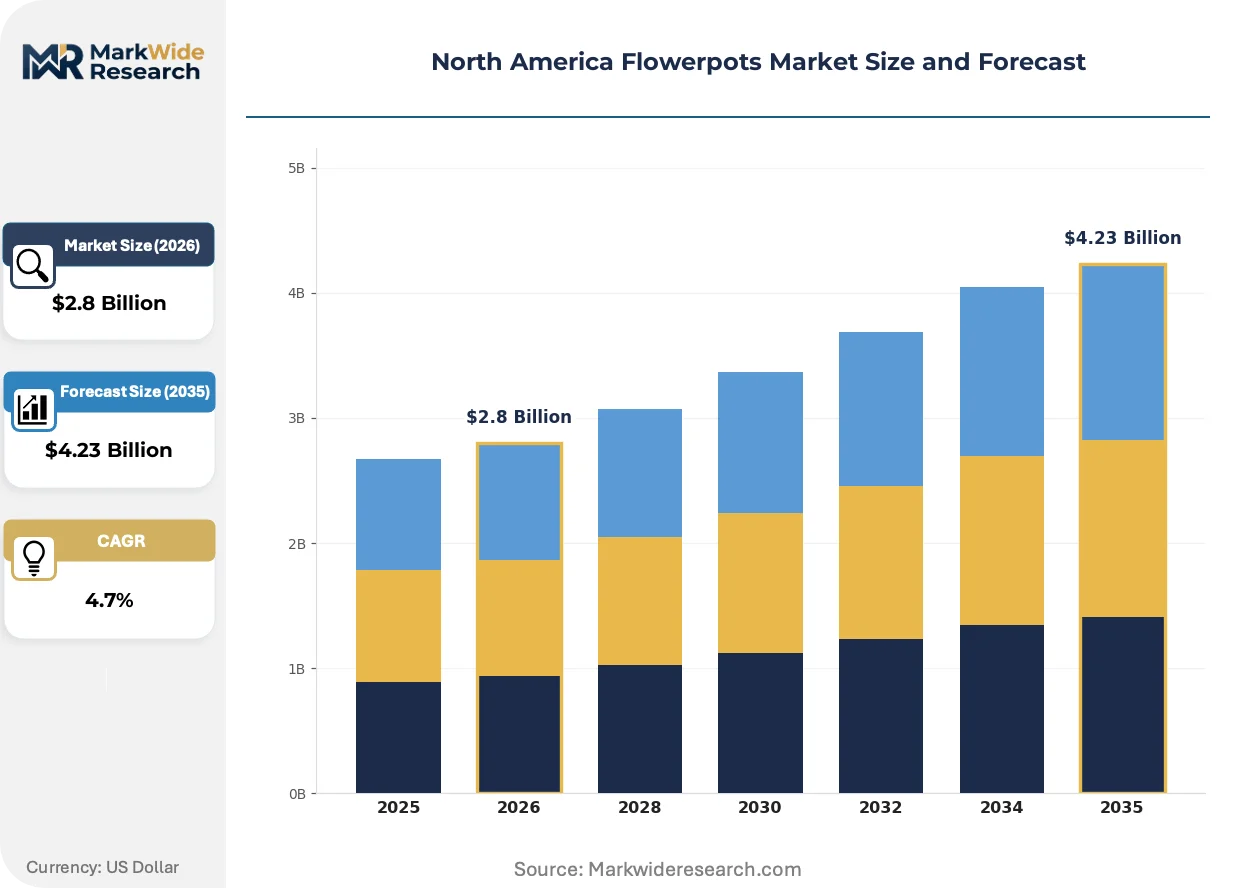
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Ceramic, Clay, Metal Size: Small, Medium, Large, Extra Large Distribution Channel: Online Retailers, Garden Centers, Home Improvement Stores, Supermarkets End User: Residential, Commercial, Landscaping Services, Nurseries |
| Companies Covered | THE HC COMPANIES, INC., Bloem, Crescent Garden Company, Mayne Inc., Tusco Products, Planters Unlimited, USA Planter, Potluck Color, Bright Farms, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Flowerpots Market Evolving Landscape
Material science advances and regulatory pressure on petroleum-derived inputs are converging to reshape container specifications across horticultural supply chains.
Biopolymer formulations derived from agricultural waste streams are electrifying R&D priorities at major resin compounders. Nursery operators in Oregon and Washington pilot these materials for short-cycle bedding plant sales. The technology is electrifying price compression in the standard thermoplastic tier as biopolymer production scales.
Health Canada and PMRA co-regulation of pesticide migration from treated wood containers is tightening material substitution protocols for edible crop cultivation. Commercial greenhouse operators face mandatory container replacement schedules for food-grade applications. The policy most affects Ontario and British Columbia vegetable propagation facilities, which are accelerating transitions to inert mineral composites.
Direct-to-plant subscription services are consolidating container procurement under single-source specifications, bypassing traditional garden center distribution. Millennials in Texas and Florida metro areas drive this channel shift toward curated, ready-to-display plant deliveries. The behavior concentrates demand for lightweight, shatter-resistant designs that survive last-mile handling.
North America Flowerpots Market Segmentation
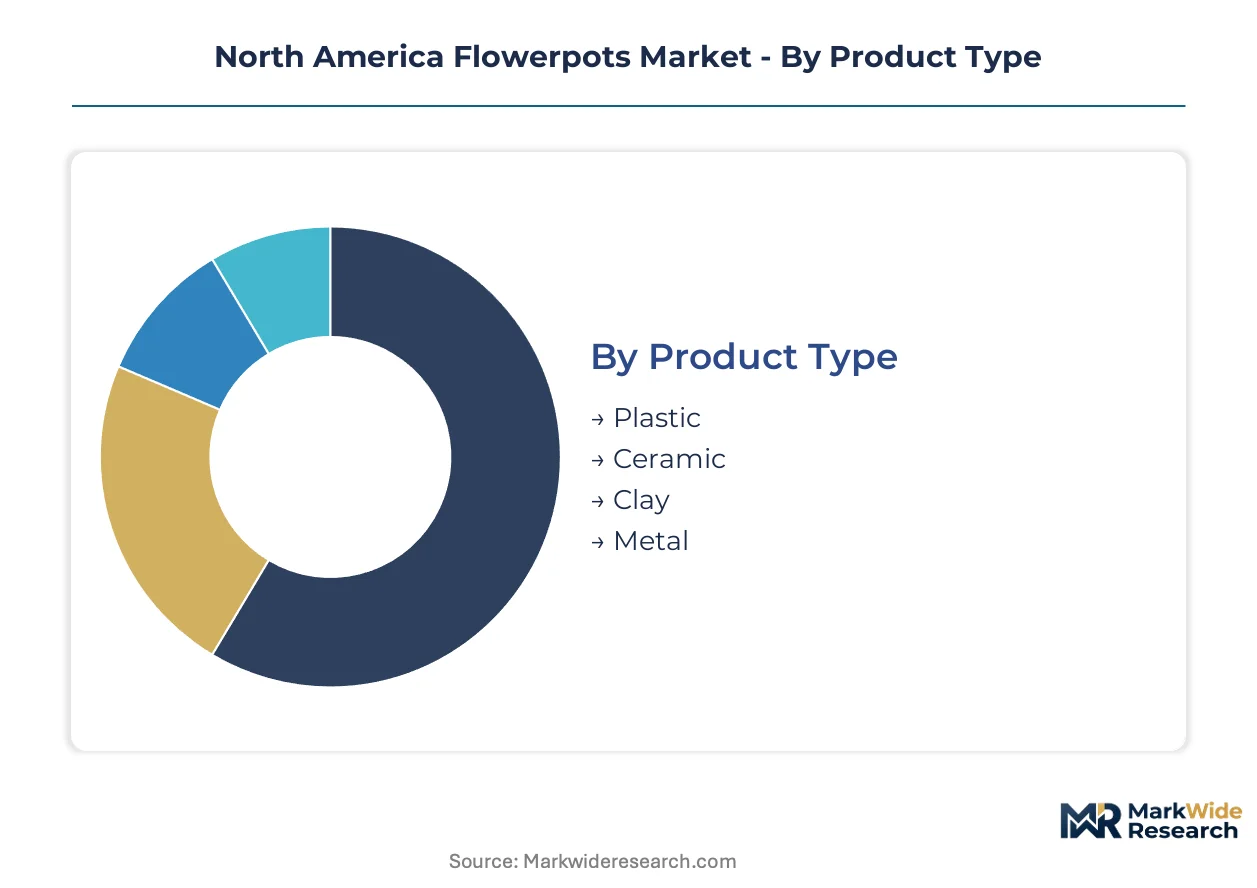
North American flowerpot procurement patterns fragment sharply across buyer sophistication, climate exposure, and fulfillment channel. Material specifications, sizing conventions, and distribution access create distinct competitive arenas with divergent margin structures and regulatory exposure.
Product Type:
Cost tier differentiation separates commodity nursery supply from premium residential curation.
- Plastic:Injection-molded polypropylene and polyethylene containers dominate unit economics through lightweight durability and stackable logistics. Demand concentrates in commercial nursery operations across Florida and Texas, where the EPA's recycled content mandates are forcing rapid resin reformulation and mold requalification cycles.
- Ceramic:Fired clay vessels command margin concentration in direct-to-consumer channels through aesthetic differentiation and freeze-thaw thermal mass. California Air Resources Board VOC restrictions on decorative coatings accelerate substitution toward unglazed terracotta in premium residential markets.
- Clay:Unglazed earthenware provides superior root zone breathability for moisture-sensitive species in humid Gulf Coast climates.
- Metal:Powder-coated aluminum and corten steel installations anchor commercial landscaping specifications for urban plazas and hospitality venues.
Volume sits with Plastic; growth tilts toward Ceramic.
Size:
Application scale determines structural requirements, drainage engineering, and handling equipment needs.
- Small:Sub-6-inch diameter containers serve herb cultivation and succulent propagation on constrained balconies. Demand clusters in Canadian multi-unit residential towers and dense Northeast metros where space scarcity drives vertical gardening adoption.
- Medium:6-to-12-inch specifications balance root development capacity with residential mobility for seasonal repositioning. Sun Belt states generate concentrated pull through extended outdoor living seasons and container vegetable gardening trends.
- Large:12-to-24-inch vessels accommodate specimen trees and perennial shrubs for permanent landscape installation.
- Extra Large:24-inch-plus containers require mechanical handling and engineered drainage for commercial hospitality and municipal streetscape contracts.
Medium formats carry the revenue base; Small formats are climbing the fastest.
Distribution Channel:
Customer type and purchase urgency shape channel selection and inventory depth requirements.
- Online Retailers:Subscription plant services and curated e-commerce platforms consolidate procurement under standardized lightweight specifications. Texas and Florida millennial demographics drive channel expansion through last-mile delivery optimization and shatter-resistant resin requirements.
- Garden Centers:Independent and chain nursery retailers maintain broad SKU breadth for immediate project fulfillment and seasonal impulse purchasing. Inventory concentration follows suburban sprawl patterns across Phoenix, Atlanta, and Dallas-Fort Worth corridors.
- Home Improvement Stores:Big-box hardware chains leverage private-label injection-molded lines for price-sensitive renovation and DIY segments.
- Supermarkets:Grocery floral departments capture convenience-driven annual and bedding plant sales with disposable thermoplastic disposables.
Garden Centers anchor current throughput; Online Retailers show the steepest expansion trajectory.
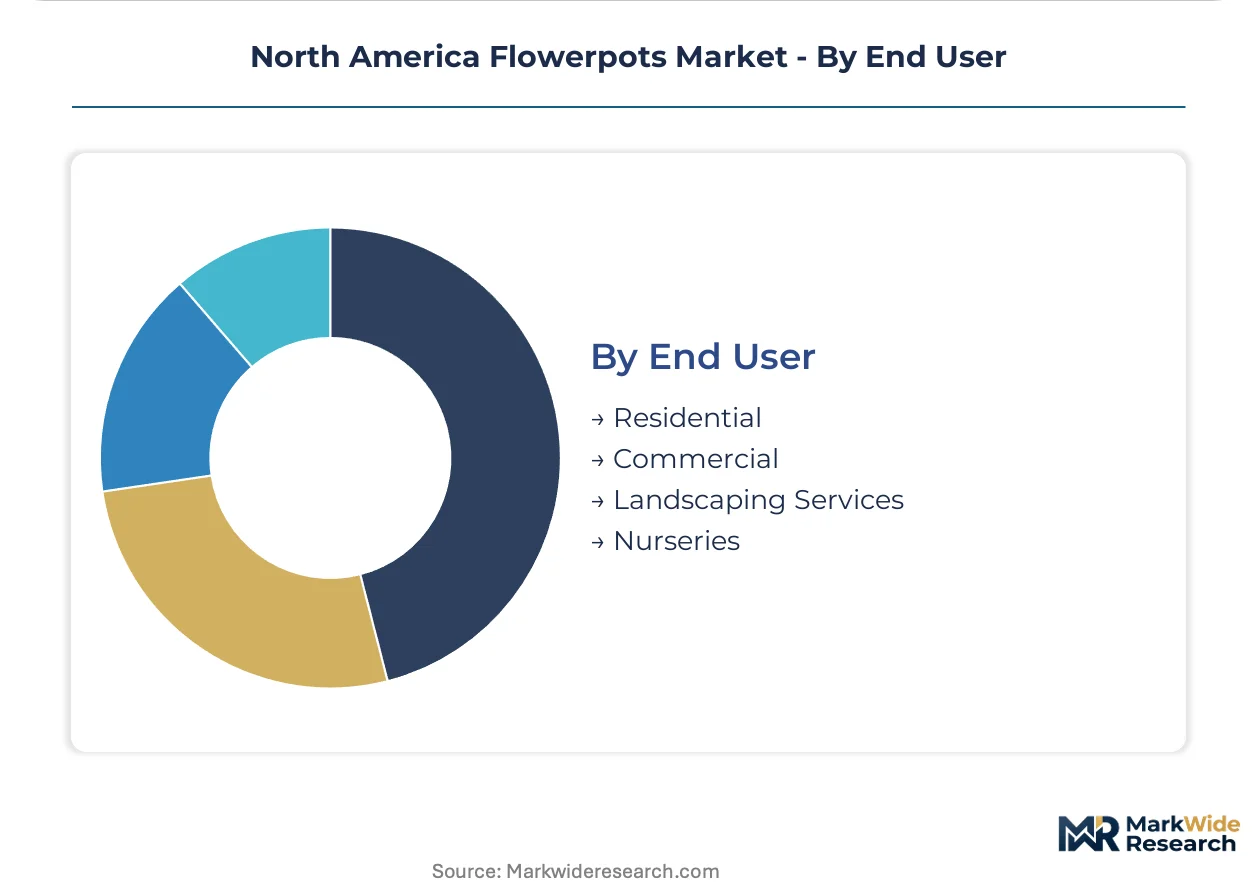
End User:
Project scale and repeat purchase frequency create divergent customer lifetime value profiles.
- Residential:Individual homeowners sustain the largest addressable base through discretionary gardening expenditure and seasonal decoration cycles. California, Arizona, and Nevada households generate above-average per-capita consumption through year-round growing seasons and outdoor entertainment culture.
- Commercial:Hospitality, healthcare, and corporate campus facilities procure through specification-driven contracts with durability and maintenance minimization priorities. Self-watering reservoir integration opens specification opportunities for rotational-molded designs in water-restricted jurisdictions.
- Landscaping Services:Professional installation contractors generate highest per-project order values through bulk procurement and recurring seasonal refresh programs.
- Nurseries:Production agriculture operations prioritize unit cost minimization and logistics efficiency for short-cycle bedding plant propagation.
Nurseries dominate unit volume; Commercial applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth corridor anchors North American flowerpot distribution through consolidated logistics hubs serving Sun Belt garden center networks.
United States
California's outdoor living culture and Arizona's desert climate UV exposure drive color-stable resin demand. EPA Green Guides compliance documentation extends new material approval cycles by 8-14 months, delaying product launches. Injection-molding operations cluster in Ohio and Illinois to serve Midwest nursery supply chains.
Canada
Multi-unit residential towers in Toronto and Vancouver generate whitespace for compact, stackable container systems. Health Canada and PMRA co-regulation of pesticide migration from treated wood containers tightens material substitution protocols for edible crop cultivation. British Columbia vegetable propagation facilities accelerate transitions to inert mineral composites.
Mexico
Expanding suburban communities around Mexico City and Monterrey adopt residential gardening practices. Mexican environmental regulations on plastic waste management are tightening, though enforcement varies by state. Manufacturing operations concentrate in Nuevo León to supply US border-state retail channels.
North America Flowerpots Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material technology and distribution channel access. The vendor base stratifies between injection-molding scale operators, color-stable resin specialists, and rotational-molded premium designers. Three archetypes dominate: big-box supply consolidators, direct-to-consumer subscription enablers, and commercial landscaping specification holders. Competitive moves concentrate on resin reformulation for EPA compliance and mold cavitation retrofits for recycled content integration.
Within the injection-molding scale tier, THE HC COMPANIES, INC. and Tusco Products exemplify volume-driven fabrication archetypes. Bloem occupies a position among color-technology specialists addressing Sun Belt UV degradation requirements. Crescent Garden Company anchors the premium self-watering segment with specification-grade designs targeting commercial landscaping contracts.
| Leading Market Players |
|---|
| THE HC COMPANIES, INC. |
| Bloem |
| Crescent Garden Company |
| Mayne Inc. |
| Tusco Products |
| Planters Unlimited |
| USA Planter |
| Potluck Color |
| Bright Farms |
| Others |
Value Network & Pricing Analysis
Captive resin compounding operations in Ohio and Illinois anchor supply positions for injection-molding scale players while insulating them from polypropylene pellet spot volatility that erodes margin predictability for outsourced competitors.
Pricing Analysis
Yield-based pricing anchors premium ceramic tiers where root-zone breathability and freeze-thaw thermal mass command aesthetic differentiation margins. Three-tier pricing structure across artisan collections, mid-grade resin lines, and disposable nursery supply separates buyers by project sophistication and repeat purchase frequency. Cost compression in standard thermoplastic tiers intensifies as EPA recycled content mandates force resin requalification investments. Commercial landscaping services show lowest price sensitivity through specification-driven procurement, while supermarket floral departments prioritize unit cost minimization above durability metrics.
Supply Chain Analysis
Freight cost exposure from Guangdong ceramic kiln concentration amplifies landed cost volatility for US importers facing tariff discontinuities and transpacific shipping rate swings. Raw material flows draw from Saudi petrochemical feedstocks for virgin polypropylene, post-consumer recycled resin streams from domestic collection programs, and kaolin clay deposits in Georgia and South Carolina. Single-source vulnerability clusters in Chinese firing operations for premium terracotta. Distribution runs through Dallas-Fort Worth consolidated hubs serving Sun Belt garden center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mold cavitation retrofit capacity bottlenecks prop pricing power for fabricators with capital access, compressing mid-tier competitors into margin-negative procurement cycles.
For Market Incumbents: Cement specification control through self-watering reservoir integration and rotational-molded commercial landscaping contracts. Accelerate backward integration into post-consumer recycled resin compounding to neutralize EPA Green Guides compliance timeline risk. Prioritize Ohio and Illinois capacity additions over outsourced Asian ceramic sourcing. For New Entrants and Emerging Players: Capture Canadian multi-unit residential whitespace with compact stackable systems engineered for Toronto and Vancouver balcony constraints. Target subscription plant service procurement consolidation through lightweight shatter-resistant resin designs optimized for last-mile handling. Lead with direct-to-consumer fulfillment partnerships bypassing legacy garden center distribution. For Investors and Strategic Acquirers: Exit pathways concentrate in platform roll-ups of color-stable resin specialists and rotational-molded premium designers serving water-restricted jurisdictions. Five-to-ten year viability favors operators with closed-loop recycling infrastructure ahead of pending state-level extended producer responsibility mandates. Monitor California Air Resources Board rulemaking velocity as inflection indicator for ceramic substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Resin Reformulation for EPA Compliance | Recycled content integration satisfies Green Guides documentation requirements for big-box retail shelf access. |
| Mold Cavitation Retrofit Investment | Post-consumer recycled content capability unlocks nursery contract eligibility under evolving procurement standards. |
| Self-Watering Reservoir Convergence | Sub-irrigation integration captures commercial landscaping specifications in Arizona and Nevada water-restricted jurisdictions. |
| Direct-to-Consumer Channel Development | Subscription plant service partnerships bypass traditional garden center margin stacking for Texas and Florida millennials. |
| Closed-Loop Recycling Infrastructure | Take-back program readiness creates first-mover positioning ahead of state-level extended producer responsibility enactment. |
Research Methodology
Trade association filings, EPA regulatory dockets, and resin compounder technical literature formed the secondary backbone, cross-referenced against primary interviews with nursery procurement directors, garden center category managers, rotational-molding operations leads, and commercial landscaping specification officers. Bottom-up triangulation validated shipment volumes against top-down demand modeling across material tiers and end-use segments.
Bottom-up volume builds aggregated nursery operator purchasing patterns, residential consumer panel data, and commercial landscaping contract values against top-down macroeconomic drivers. Segmentation dimensions spanned material technology, size format, distribution channel, and end-user archetype across the analysis window. CAGRs derived from logistic diffusion curves fitted to substitution dynamics between thermoplastic and ceramic demand pools, with UV degradation resistance premiums and freeze-thaw tolerance thresholds as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical feedstock volatility, Chinese ceramic tariff trajectories, and extended producer responsibility enactment timing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
US Garden Planter Market
Home & Garden
Outdoor Cooking Table Market
Home & Garden
Global Wind Chime Market
Home & Garden
Garage Organization and Storage Market
Home & Garden
Europe Robotic Lawn Mower Market
Home & Garden
United States Lawn Care Market
Home & Garden
Landscaping Products Market
Home & Garden
Asia-Pacific Bonsai Market
Home & Garden
Artificial Plants Market
Home & Garden
Artificial Flowers Market
Home & Garden
Landscaping and Gardening Service Market
Home & Garden
Christmas Decorations Market
Home & Garden
Wine Racks Market
Home & Garden
Aquarium LED Lighting Market
Home & Garden
United Kingdom Homeware Market
Home & Garden
Hedge Trimmer Market