
 Canada Baby Care Products Market | 2026-2036
Canada Baby Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Baby Care Products Market Insights
Health Canada's Natural Health Products (NHP) licensing is reorganizing competitive access for baby skincare and oral care entrants, forcing reformulation cycles that favor incumbents with established regulatory infrastructure. Procter & Gamble leverages its Ottawa-based regulatory affairs team to sustain rapid NHP approval throughput. Kimberly-Clark anchors its position through backward integration into absorbent core manufacturing for diaper lines sold coast-to-coast. Johnson & Johnson differentiates via pharmacist-channel relationships that control shelf placement in Shoppers Drug Mart and Rexall networks.
Canada baby care products encompass formulated goods engineered for infant dermal tolerance, typically specifying pH 4.5-6.5, hypoallergenic certification, and zero paraben or phthalate content, designed to cleanse, protect, or nourish skin during the first thirty-six months of life. Diapers and wipes command the largest revenue pool due to replenishment frequency, though organic-origin baby lotion captures the fastest margin expansion as parental willingness-to-pay for clean-label formulations rises. Online retail channels are displacing supermarket dominance in Ontario and Quebec, while baby specialty stores in Calgary and Edmonton sustain premium positioning through curated experiential merchandising.
Health Canada, the Canadian Food Inspection Agency, and provincial extended producer responsibility frameworks collectively govern ingredient safety, labeling accuracy, and post-consumer packaging recovery obligations. The NHP Directorate's tightened monograph compliance deadlines compress product development timelines, advantaging firms with captive toxicology and stability-testing laboratories. Stakeholders must monitor Health Canada's pending updates to the Cosmetic Ingredient Hotlist and assess whether Quebec's accelerated plastic-reduction mandates will force packaging format changes ahead of other provinces.
Market Dynamics
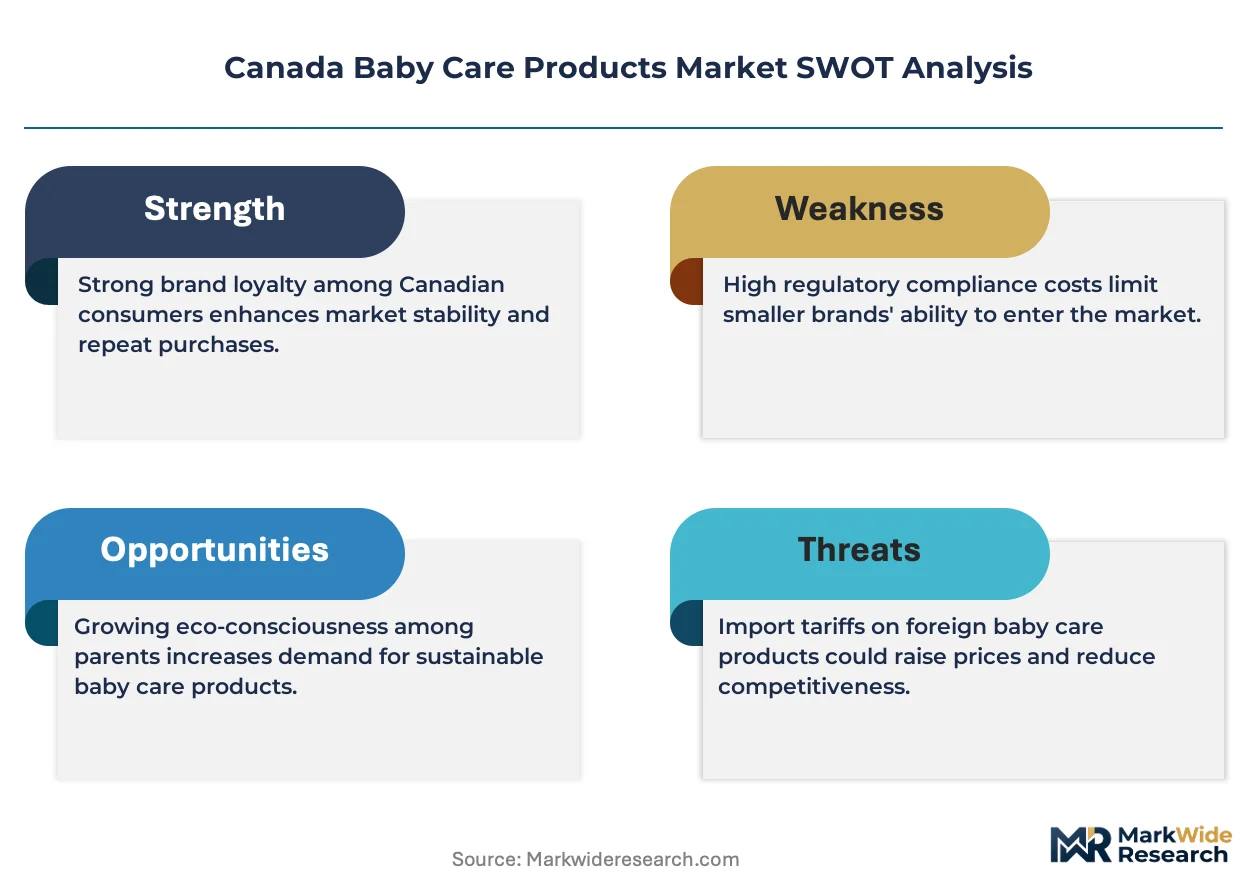
Health Canada's Natural Health Products Directorate is compressing product development timelines through tightened monograph compliance deadlines, forcing reformulation cycles that favor incumbents with captive toxicology and stability-testing laboratories over new entrants lacking regulatory infrastructure.
Growth Catalysts
- Quebec's accelerated plastic-reduction mandates:Provincial extended producer responsibility frameworks are creating first-mover advantages for brands with recyclable packaging formats, concentrating demand among sustainability-focused Millennial parents in Montreal and Quebec City corridors.
- Clean-label formulation chemistry:Advances in plant-derived emulsifiers and preservative systems are enabling paraben-free and phthalate-free certifications that command shelf placement premiums in Shoppers Drug Mart and Rexall networks.
- Premium retail corridor clustering:Specialty boutique density in Vancouver's Kitsilano and Toronto's Yorkville neighborhoods is concentrating high-margin organic-formula demand, validating experiential merchandising investments.
Market Restraints
- Absorbent core material concentration:Backward integration requirements for diaper manufacturing favor capital-intensive players, locking out mid-tier competitors dependent on third-party superabsorbent polymer supply from concentrated Asian producers.
- NHP licensing friction:Health Canada's multi-phase approval process for baby oral care and skincare products extends time-to-market by 18-24 months versus conventional cosmetic pathways, eroding first-mover returns.
- Private-label substitution pressure:Loblaw Companies and Metro Inc. are expanding controlled-brand baby lotion and wipe portfolios at 30-40% price discounts to national brands, compressing margin pools in mass retail channels.
Strategic Opportunities
- Alberta specialty retail whitespace:Calgary and Edmonton baby boutique clusters remain underpenetrated by curated organic-formula brands relative to Vancouver and Toronto saturation, offering experiential merchandising expansion potential.
- Pharmacist-channel certification leverage:Health Canada NHP registration enables behind-the-counter placement in Shoppers Drug Mart and Rexall networks, creating consultation-driven upsell environments for sensitive-skin formulations.
- Biodegradable wipe substrate convergence:Integration of cellulose-based fibers with water-soluble packaging films addresses Quebec's single-use plastic restrictions while differentiating premium diaper and wipe bundles.
Industry Challenges
- Toxicology testing capacity scarcity:Captive stability-testing laboratory investments are concentrating among top-three incumbents, forcing smaller entrants into 6-12 month queue delays at third-party Canadian contract research organizations.
- Provincial labeling fragmentation:Divergent French-language disclosure requirements between Quebec's Charter of the French Language and other provinces' bilingual standards are multiplying SKUs and complicating national distribution economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Baby Care Products Market |
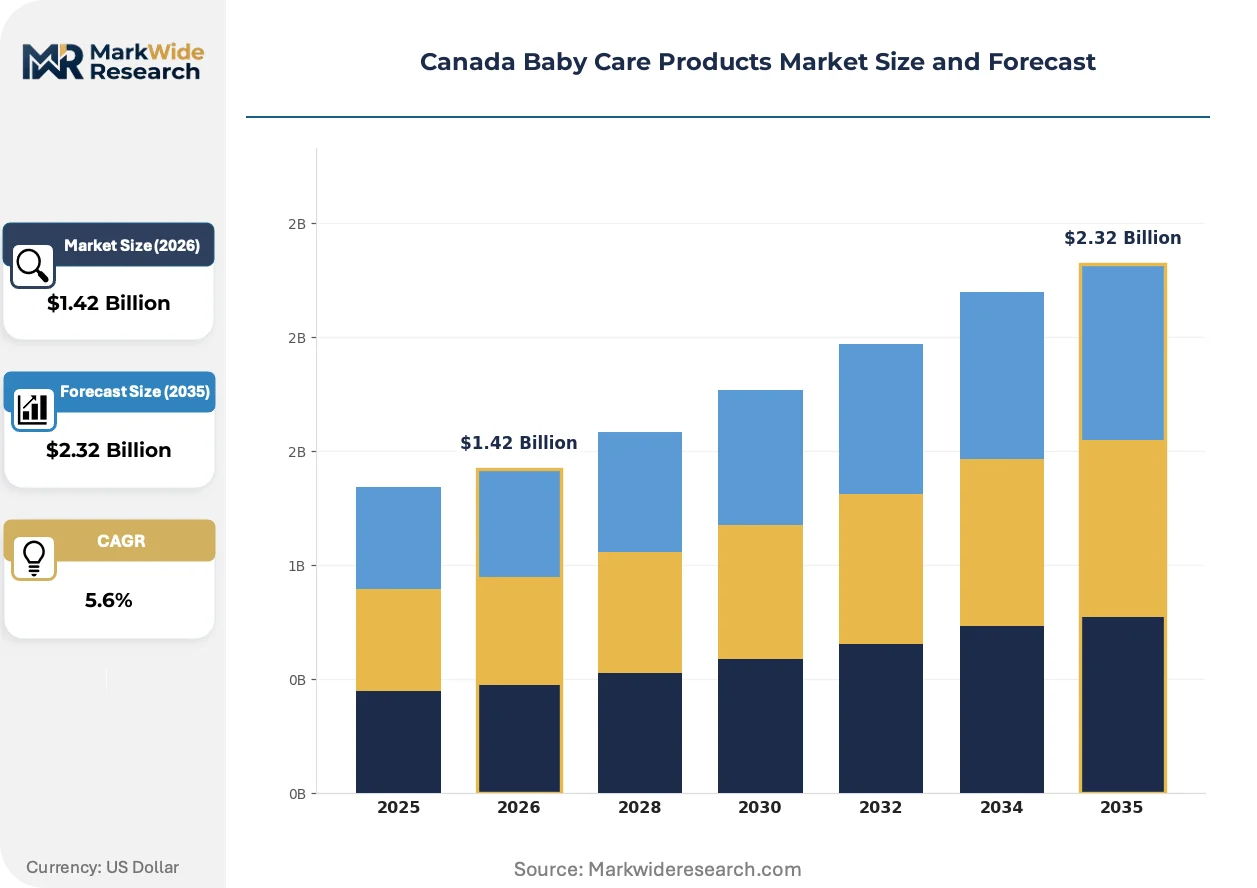
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.32 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diapers, Wipes, Baby Lotion, Baby Powder Age Group: Infants, Toddlers, Newborns, Pre-teens Distribution Channel: Online Retail, Supermarkets, Baby Specialty Stores, Pharmacies Product Origin: Organic, Natural, Conventional, Others |
| Companies Covered | Abbott, Kimberly-Clark, Johnson & Johnson, Artsana Group, Kenvue, Nestlé, Unilever, Beiersdorf, Procter & Gamble, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Baby Care Products Market Trends and Innovations
Formulation transparency and substrate material science are reshaping competitive differentiation in Canadian baby care, with regulatory compliance velocity and clean-label chemistry becoming inseparable from shelf access and parental trust formation.
Plant-derived preservative systems utilizing fermented lactobacillus extracts and rosemary oleoresin antioxidants are replacing synthetic paraben and phenoxyethanol chemistries in baby lotion and shampoo formulations. Ontario and British Columbia Millennial parents are adopting these alternatives at pace sufficient to force conventional reformulation across mass-market portfolios. This bifurcating the market into certified clean-label premiums and price-commoditized legacy formulations with shrinking distribution access.
Health Canada's pending updates to the Cosmetic Ingredient Hotlist are expanding prohibited and restricted substance categories for infant dermal products, with particular scrutiny on fragrance allergens and formaldehyde-releasing preservatives. Manufacturers with Ottawa-based regulatory affairs teams are accelerating pre-submission dossier preparation to secure NHP licensing ahead of compliance deadline compression. Baby skincare entrants lacking established Health Canada relationships face exclusion from pharmacist-channel placement in Rexall and Shoppers Drug Mart networks.
Subscription-based replenishment models are displacing supermarket stock-up purchasing for diapers and wipes among dual-income households in the Greater Toronto Area. Amazon.ca and Indigo's online platforms are capturing this shift through auto-delivery incentives, while baby specialty stores in Vancouver's Mount Pleasant cluster are responding with membership-based curated boxes bundling organic skincare with developmental toys. Channel fragmentation is most visible in Quebec, where provincial e-commerce fulfillment infrastructure lags Ontario and British Columbia, sustaining supermarket dominance in Montreal exurbs.
Canada Baby Care Products Market Segmentation
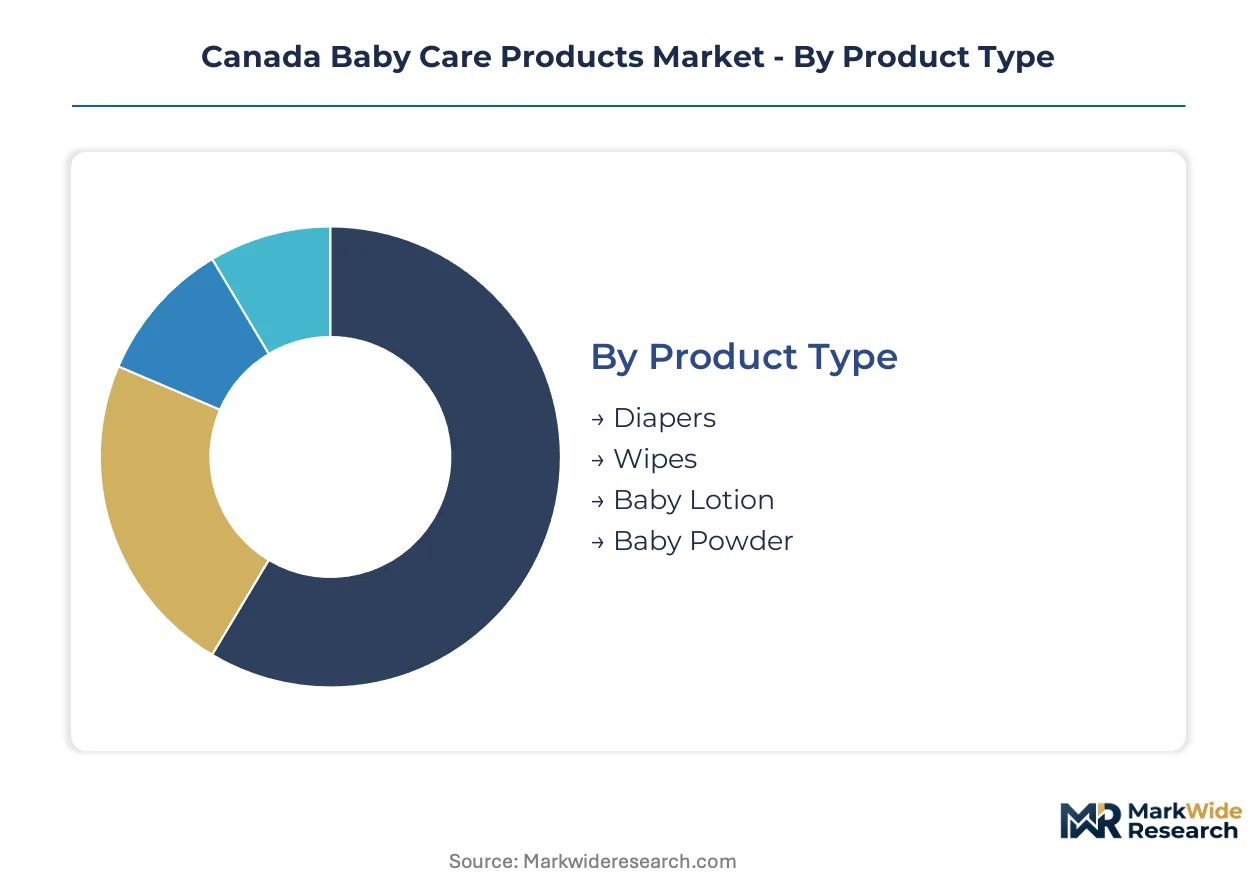
Product origin and channel configuration are reshaping competitive access in Canadian baby care, with clean-label premiums concentrating in urban corridor boutiques and regulatory compliance velocity determining mass retail shelf eligibility.
Product Type:
Domestic manufacturing anchors diaper and wipe supply chains through captive absorbent core production, while skincare formulations increasingly source botanical actives from international suppliers.
- Diapers:Engineered with superabsorbent polymer cores and breathable outer layers specifying wetness-indicator strips. Demand concentrates in mass retail channels across Ontario and Quebec, where replenishment frequency sustains volume leadership despite margin compression from private-label substitution.
- Wipes:Substrate construction spans cellulose-based biodegradable fibers to conventional spunlace nonwovens, with Quebec's plastic-reduction mandates forcing format innovation. Montreal and Vancouver parents are adopting water-soluble packaging films at pace sufficient to validate premium positioning.
- Baby Lotion:pH-buffered emulsions utilizing plant-derived preservatives.
- Baby Powder:Talc-free and cornstarch-based variants responding to Health Canada safety advisories.
Diapers command the established base. The steepest expansion runs through baby lotion.
Age Group:
Formulation tolerance requirements tighten across younger cohorts, driving certification premiums for newborn-specific portfolios while toddler segments sustain volume through lower price elasticity.
- Infants:Products specifying zero fragrance and minimal ingredient lists for dermal barrier development. Greater Toronto Area dual-income households are concentrating demand for subscription-based replenishment bundles combining skincare with developmental monitoring tools.
- Newborns:Hospital-discharge kit partnerships and pharmacist-channel placement in Shoppers Drug Mart networks. Vancouver's Kitsilano cluster shows highest willingness-to-pay for organic-origin newborn portfolios.
- Toddlers:Transition formats with expanded size ranges and activity-appropriate absorbency.
- Pre-teens:Adjacent personal care bridging baby and adult categories.
Newborn portfolios anchor pharmacist-channel relationships. Toddlers sustain the volume base through lower switching costs.
Distribution Channel:
Channel fragmentation accelerates between experiential boutique positioning and algorithmic replenishment convenience, with provincial fulfillment infrastructure determining online penetration depth.
- Online Retail:Auto-delivery incentives and subscription bundling capturing dual-income households in Ontario and British Columbia. Amazon.ca and Indigo platforms are displacing supermarket stock-up behavior for diapers and wipes.
- Baby Specialty Stores:Curated merchandising and consultation services in Calgary and Edmonton clusters. These underpenetrated markets offer whitespace for organic-formula brands saturated in Vancouver and Toronto.
- Supermarkets:Mass volume concentration in Quebec exurbs where e-commerce fulfillment lags other provinces.
- Pharmacies:Behind-the-counter placement enabled by Health Canada NHP registration, creating upsell environments for sensitive-skin formulations in Rexall networks.
Supermarkets retain the volume base. Online retail is climbing the fastest.
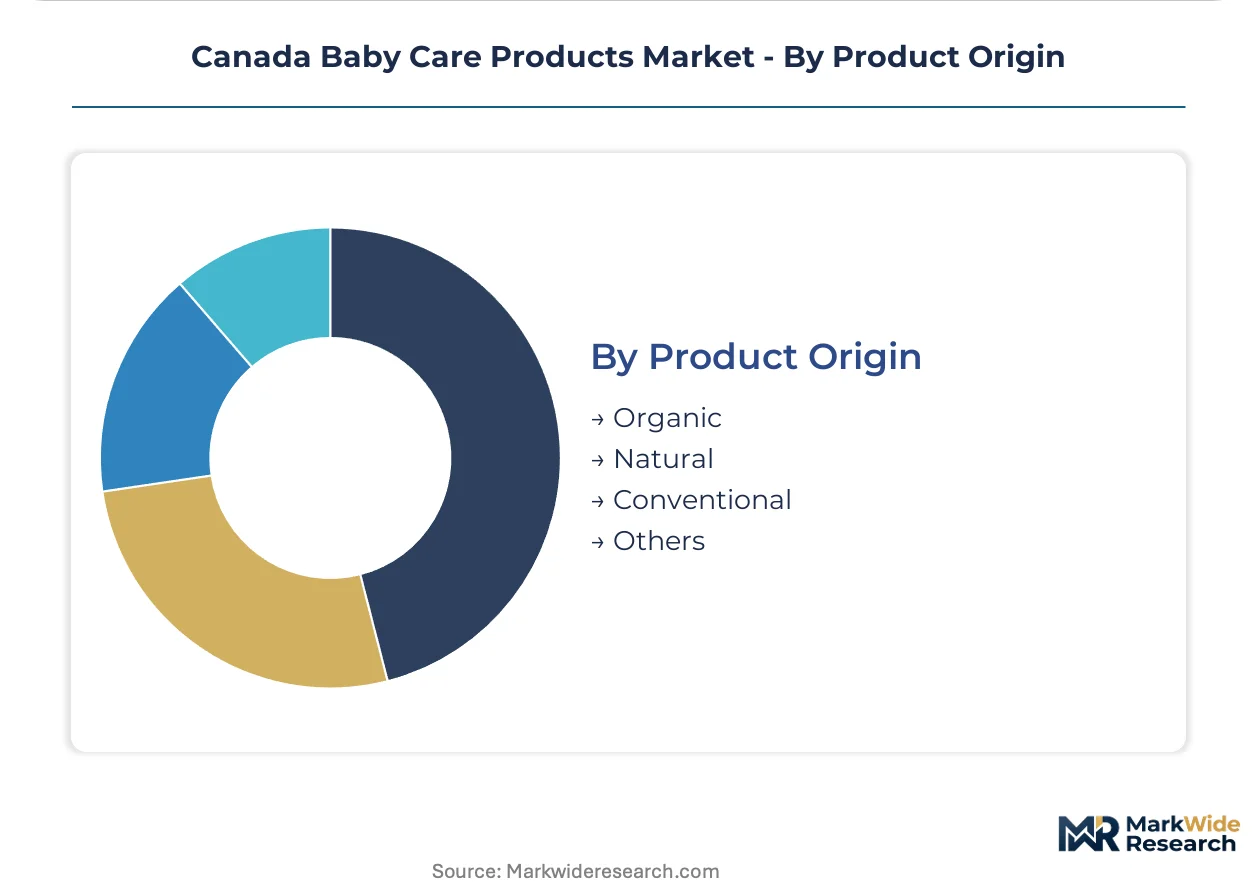
Product Origin:
Certification tiering is bifurcating shelf access, with organic and natural designations commanding placement premiums while conventional formulations face distribution constriction.
- Organic:Certified supply chains with documented ingredient provenance and third-party verification. Millennial parents in British Columbia and Ontario are expanding purchases at pace forcing conventional portfolio reformulation.
- Natural:Plant-derived positioning without full organic certification, capturing price-sensitive clean-label demand.
- Conventional:Legacy synthetic formulations facing shrinking distribution access in premium retail corridors.
- Others:Hybrid positioning and emerging certification schemes.
Conventional origin retains mass-market volume. Organic certification is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial and Gen Z parents in Ontario and British Columbia are expanding purchases of organic-formula and clean-label skincare items, driving regional demand concentration in urban retail corridors.
Ontario
Dual-income households in the Greater Toronto Area are adopting subscription-based replenishment models for diapers and wipes through Amazon.ca and Indigo platforms. Health Canada's Natural Health Products Directorate licensing requirements compress product development timelines for baby oral care entrants. Premium retail clustering in Toronto's Yorkville neighborhood validates experiential merchandising investments for organic-formula brands.
Quebec
Montreal and Quebec City corridors concentrate demand among sustainability-focused Millennial parents for recyclable packaging formats. Provincial extended producer responsibility frameworks and accelerated plastic-reduction mandates are creating first-mover advantages for compliant brands. E-commerce fulfillment infrastructure lags Ontario and British Columbia, sustaining supermarket dominance in Montreal exurbs.
British Columbia
Vancouver's Kitsilano and Mount Pleasant clusters show the highest willingness-to-pay for organic-origin newborn portfolios and curated specialty retail experiences. Health Canada's pending Cosmetic Ingredient Hotlist updates are driving pre-submission dossier preparation among established regulatory affairs teams. Specialty boutique density concentrates high-margin organic-formula demand ahead of national distribution economics.
Alberta
Calgary and Edmonton baby boutique clusters remain underpenetrated by curated organic-formula brands relative to Vancouver and Toronto saturation. Provincial regulations align with federal standards while offering whitespace for experiential merchandising expansion. Specialty store consultation services are capturing premium positioning opportunities in these underdeveloped markets.
Atlantic Canada
Smaller urban centers face distribution economics challenges from provincial labeling fragmentation between Quebec's Charter of the French Language and other provinces' bilingual standards. Health Canada NHP registration enables pharmacist-channel placement creating upsell environments. Regional demand concentrates through mass retail channels with limited specialty boutique penetration.
Canada Baby Care Products Market Competitive Landscape
Player mix skews toward multinational consumer goods conglomerates with established regulatory infrastructure and captive supply chain assets. Consolidation pressure favors incumbents possessing Ottawa-based regulatory affairs teams and backward integration into absorbent core manufacturing. Three archetypes dominate: vertically integrated diaper manufacturers with polymer supply control, pharmacist-channel skincare specialists with NHP licensing velocity, and private-label suppliers serving Loblaw and Metro networks. Competitive moves center on M&A to secure toxicology testing capacity and strategic partnerships for biodegradable substrate development.
Within the multinational conglomerate tier, Procter & Gamble, Kimberly-Clark, and Johnson & Johnson exemplify divergent strategic positioning. Procter & Gamble occupies a position anchored by regulatory throughput advantages in Health Canada approvals. Kimberly-Clark represents backward integration archetypes with captive absorbent core production. Johnson & Johnson sits within the pharmacist-channel certification tier leveraging relationships with Shoppers Drug Mart and Rexall networks.
| Leading Market Players |
|---|
| Abbott |
| Kimberly-Clark |
| Johnson & Johnson |
| Artsana Group |
| Kenvue |
| Nestlé |
| Unilever |
| Beiersdorf |
| Procter & Gamble |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four-month Health Canada NHP licensing queues concentrate pricing power among incumbents with captive toxicology laboratories, while private-label substitution at Loblaw and Metro networks compresses margin pools in mass retail channels. This lead-time asymmetry bifurcates the market into premium pharmacist-channel placements and commoditized supermarket tiers.
Pricing Analysis
Cost-plus contracts with polypropylene and superabsorbent polymer indexation dominate diaper procurement agreements between Kimberly-Clark and national retail banners. Price differentiation rests on NHP certification tier and organic-formula provenance, with pharmacist-channel placement commanding placement premiums at Shoppers Drug Mart. Cost compression in mass-market tiers intensifies because Metro Inc. and Loblaw Companies expand controlled-brand portfolios at thirty-to-forty-percent discounts to national brands. Mass retail channels exhibit highest price sensitivity; specialty boutiques in Vancouver's Kitsilano cluster show lowest.
Supply Chain Analysis
China and South Korea anchor superabsorbent polymer production for diaper cores, while Germany and Switzerland supply botanical actives for clean-label skincare formulations. Raw material dependencies center on petroleum-derived nonwoven substrates, cellulose-based biodegradable fibers, and plant-derived preservative systems. Single-source vulnerability concentrates in Asian superabsorbent polymer supply, exposing Canadian manufacturers to logistics chokepoints at Vancouver and Prince Rupert ports. Distribution runs through three-tier structures: direct-to-retailer for mass channels, specialty distributors for boutique clusters, and Amazon.ca fulfillment centers for subscription replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate substitution defense against private-label expansion at Loblaw and Metro networks, where controlled-brand baby lotion and wipe portfolios erode national brand volume.
For Market Incumbents: Shield pharmacist-channel relationships through accelerated Health Canada NHP dossier preparation to secure behind-the-counter placement at Rexall networks. Deepen backward integration into absorbent core manufacturing to offset polypropylene price volatility. These moves counter private-label substitution and third-party toxicology testing queue delays. For New Entrants and Emerging Players: Subscription-based replenishment service gaps in Quebec exurbs offer whitespace where e-commerce fulfillment lags Ontario and British Columbia infrastructure. Target Calgary and Edmonton baby boutique clusters for curated organic-formula placement, leveraging consultation-driven merchandising absent from mass retail. Pursue pharmacist-channel certification as primary go-to-market angle to bypass supermarket price compression. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational consumer goods parents divesting non-core baby care assets amid portfolio rationalization. Long-term viability centers on regulatory compliance velocity and clean-label chemistry capabilities over five-to-ten-year horizons. Monitor Health Canada Cosmetic Ingredient Hotlist updates as inflection signal for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| NHP Licensing Acceleration | Ottawa-based regulatory affairs teams secure pharmacist-channel placement ahead of compliance deadlines. |
| Biodegradable Substrate Integration | Cellulose-based fibers with water-soluble packaging address Quebec's plastic-reduction mandates. |
| Specialty Retail Expansion | Calgary and Edmonton boutique clusters offer underpenetrated whitespace for organic-formula brands. |
| Subscription Platform Development | Auto-delivery incentives capture dual-income household replenishment behavior in Greater Toronto Area. |
| Backward Integration Investment | Captive absorbent core production insulates against Asian superabsorbent polymer supply concentration. |
Research Methodology
The analysis maps diapers, wipes, skincare, and oral care sub-sectors, each validated through regulatory affairs directors, category buyers at Shoppers Drug Mart and Rexall, supply chain planners at Kimberly-Clark and Procter & Gamble, and boutique retail operators in Vancouver and Toronto. Primary interviews with brand managers and Health Canada compliance officers combined with secondary validation from Nielsen retail audit data, Health Canada NHP licensing databases, Environment and Climate Change Canada packaging regulations, and Statistics Canada import records. Bottom-up SKU-level volume builds triangulated against top-down provincial household expenditure estimates.
Consistency checks validated volume and value outputs against external benchmarks including retail channel shipment data and provincial birth rate projections across the analysis window. Segmentation dimensions modeled include product type, age group, distribution channel, and product origin certification tier. CAGRs derived from regression analysis of historical pricing trends and forward-looking elasticity assumptions for organic-formula demand. Industry-specific inputs incorporated Quebec's accelerated plastic-reduction compliance timelines and Health Canada monograph update schedules.
Underlying assumptions cover sustained Millennial and Gen Z preference for clean-label formulations, with deviation risk concentrated in Health Canada regulatory timeline compression and provincial extended producer responsibility enforcement intensity. Recalibration cycles align with material shifts in NHP licensing velocity and biodegradable substrate technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Silicone Baby Product Market
Baby Products
Baby and Toddler Feeding Products and Accessories Market
Baby Products
Baby Shoes Market
Baby Products
Electric Baby Nail Trimmer Market
Baby Products
Baby Feeding Bottles Market
Baby Products
Baby Walker Market
Baby Products
Baby Seat Liners Market
Baby Products
Baby High Chair Market
Baby Products
Baby Sleeping Bag Market
Baby Products
Italy Baby Care Products Market
Baby Products
United Arab Emirates Baby Care Products Market
Baby Products
Soft Sole Baby Shoes Market
Baby Products
Baby Personal Care Products Market
Baby Products
Sippy Cups Market
Baby Products
Baby Bedding Market
Baby Products
Baby Pacifier Thermometer Market