
 North America Smart Commercial Restroom Products Market | 2026-2036
North America Smart Commercial Restroom Products Market Size, Share, and Industry Trends Forecast 2026-2036
North America Smart Commercial Restroom Products Market Analytics
Healthcare Facilities is rotating share from traditional office buildings as the dominant buyer archetype for smart restroom installations. Zurn Industries leverages its vertical integration in sensor-actuated flush valves to sustain specification dominance across hospital networks. Sloan Valve Company anchors its position through R&D intensity in battery-free hydroelectric power technologies for touchless fixtures.
North America Smart Commercial Restroom Products encompass sensor-activated, electronically controlled fixtures and hygiene systems designed for high-traffic commercial environments, typically operating on voltages from 0.125 to 1.6 gallons per flush with infrared or capacitive proximity detection ranges of 4 to 24 inches. These systems automate water delivery, soap dispensing, and hand drying to reduce pathogen transmission and optimize utility consumption in facilities with 500 to 50,000 daily users. Touchless Faucets leads product type penetration due to shorter replacement cycles and lower installation complexity versus full smart toilet retrofits. IoT-Enabled technology captures expanding margin pools as facility managers prioritize usage analytics and predictive maintenance dashboards over standalone sensor functionality.
The EPA WaterSense program and DOE federal appliance standards shape minimum efficiency thresholds for smart fixtures sold across the United States, while Health Canada and PMRA guidelines influence cross-border product certification requirements for vendors serving Canadian healthcare and institutional markets. OSHA sanitation standards for workplace restrooms create compliance-driven replacement cycles that sustain baseline demand independent of aesthetic renovation cycles. Stakeholders must monitor how state-level water stress declarations in Arizona, Nevada, and Colorado will tighten permissible flow rates and accelerate obsolescence of first-generation sensor fixtures.
Market Dynamics
The EPA WaterSense program and state-level water stress declarations are compressing permissible flow rates for first-generation sensor fixtures, forcing facility managers into accelerated replacement cycles that favor IoT-enabled systems with predictive maintenance capabilities.
Growth Catalysts
- Healthcare infection control mandates:Hospital networks are specifying touchless sensor systems to meet Joint Commission accreditation standards and reduce nosocomial pathogen transmission in high-traffic clinical zones.
- California Title 24:The state's building energy efficiency standards mandate low-flow fixtures in new commercial construction, creating specification pull for smart flush valves and faucets across the Pacific Coast corridor.
- Battery-free hydroelectric power:Self-powered sensor technologies eliminate maintenance-intensive battery replacement programs, reducing total cost of ownership for facilities with 500 to 50,000 daily users.
Market Restraints
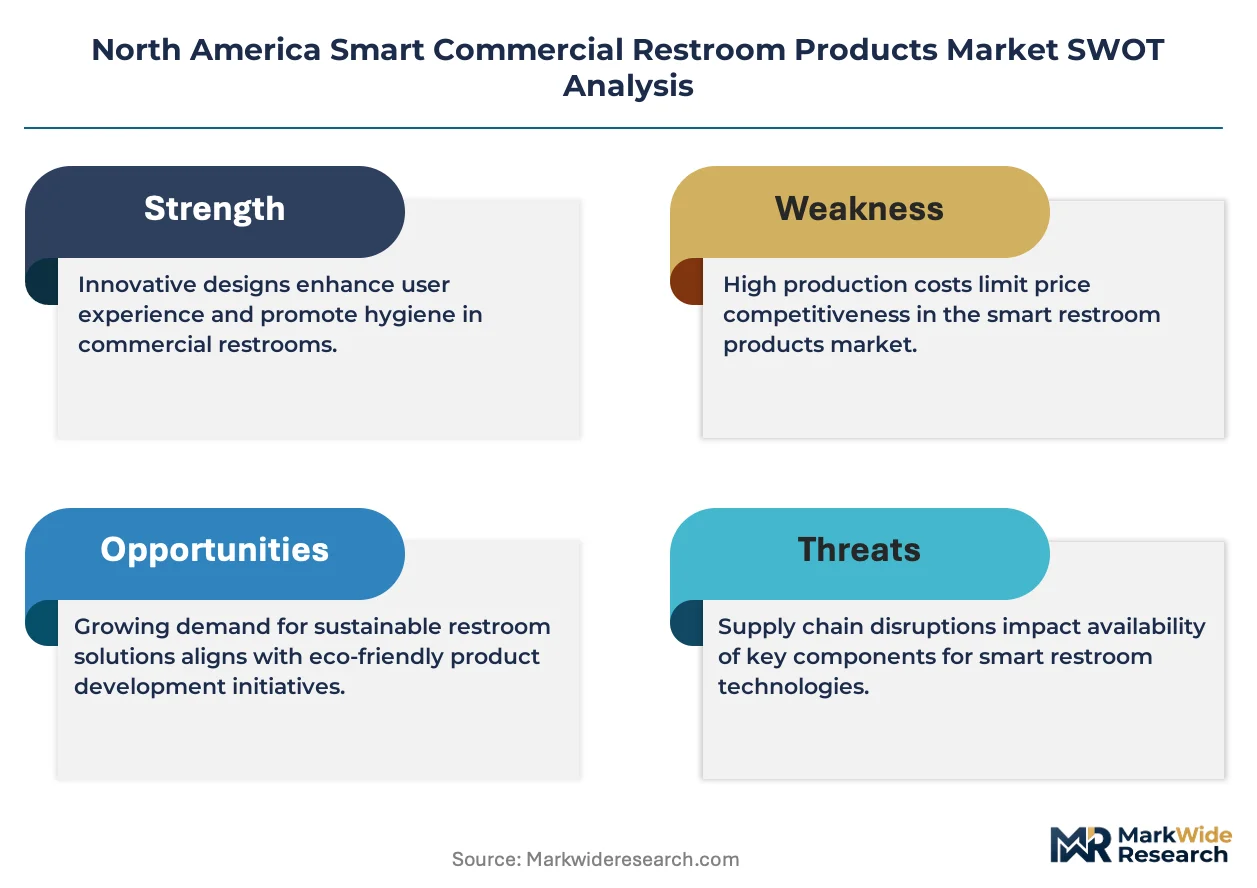
- Copper and semiconductor input volatility:Sensor-actuated valve assemblies rely on precision electronic components and brass alloys subject to commodity price swings that compress manufacturer margins.
- Legacy infrastructure incompatibility:First-generation sensor fixtures from the 2000-2015 installation wave lack standardized communication protocols, blocking seamless IoT retrofit without full fixture replacement.
- Texas municipal water rate structures:Flat-rate commercial pricing in Dallas-Fort Worth and Houston metro areas dilutes the payback calculus for water-efficient smart fixtures versus consumption-based billing markets.
Strategic Opportunities
- Arizona and Nevada water stress corridors:State-level drought declarations in Phoenix and Las Vegas commercial districts are tightening permissible gallons-per-flush thresholds ahead of federal mandates.
- Usage analytics unbundling:Facility management software platforms are integrating restroom sensor data into broader building automation dashboards, creating recurring revenue streams beyond hardware sales.
- LEED v4.1 certification pathways:The U.S. Green Building Council's water efficiency credits reward real-time monitoring capabilities that only IoT-enabled fixtures can document for project certification.
Industry Challenges
- Certification timeline compression:Health Canada and PMRA cross-border requirements add 8-14 months to product launch schedules for vendors serving Canadian healthcare and institutional markets.
- Interoperability fragmentation:Proprietary communication protocols between sensor manufacturers and building management systems force costly middleware development or locked-in supplier relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Smart Commercial Restroom Products Market |
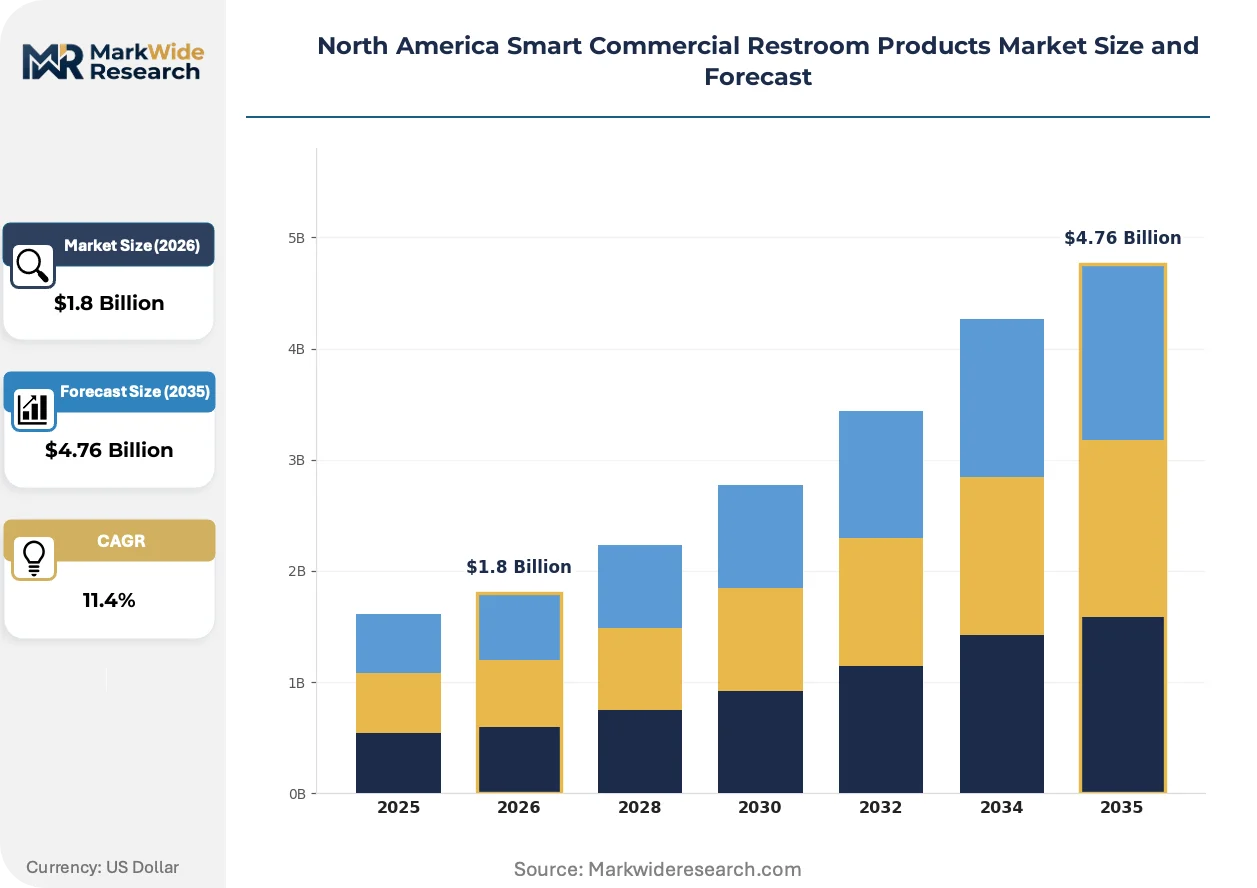
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Toilets, Touchless Faucets, Automatic Soap Dispensers, Smart Hand Dryers Technology: IoT-Enabled, Sensor-Based, Mobile App Integration, Cloud Connectivity End User: Commercial Buildings, Restaurants, Healthcare Facilities, Educational Institutions Installation: Retrofitting, New Construction, Modular Units, Custom Solutions |
| Companies Covered | Zurn Industries, Sloan Valve Company, Kimberly-Clark Worldwide, Moen, Kohler, Delta Faucet Company, American Standard, Toto, Chicago Faucet Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Smart Commercial Restroom Products Market Evolving Landscape
Three distinct vectors are restructuring competitive advantage in smart restroom systems: power autonomy eliminating maintenance burdens, regulatory ratcheting on flow rates, and procurement centralization favoring integrated facility management platforms over standalone hardware vendors.
Hydroelectric turbine micro-generators embedded in flush valve bodies are supplanting alkaline battery packs as the dominant power architecture for touchless fixtures. Hospital networks and airport authorities are specifying these self-powered systems to eliminate quarterly battery replacement programs across thousands of units. The shift is compressing aftermarket service revenue pools while expanding upfront specification premiums for manufacturers with captive turbine technology.
The EPA WaterSense program's draft specifications for sensor-activated commercial faucets are tightening maximum flow rate thresholds below current market averages. Fixture manufacturers serving the California and Texas commercial corridors are re-engineering solenoid valve orifices and aerator designs to maintain user experience perception at reduced volumes. This regulatory ratcheting is accelerating obsolescence of first-generation sensor products installed during the 2010-2018 building boom.
Integrated facility management platforms are consolidating procurement authority previously dispersed across maintenance, sustainability, and infection control departments. Large healthcare systems and multi-site retail operators are bundling restroom sensor data into enterprise-wide utility optimization contracts. The consolidation is most visible in Florida's hospital network consolidation and the Texas medical center corridor, where standardized specification across dozens of facilities favors vendors with API-ready IoT architectures.
North America Smart Commercial Restroom Products Market Segmentation
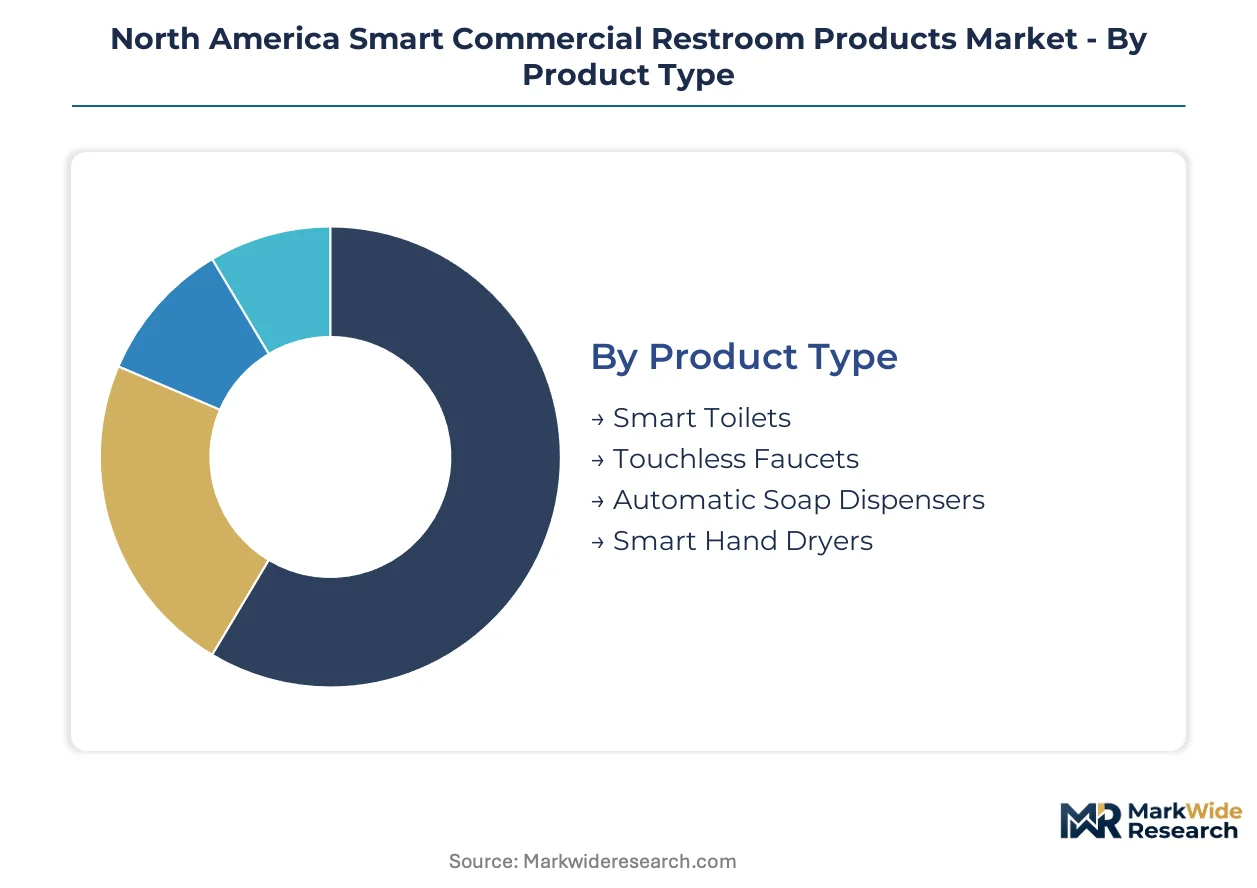
Smart commercial restroom procurement decisions fragment across technical specifications, infrastructure constraints, and regulatory compliance tiers. Facility managers weigh sensor accuracy thresholds against legacy plumbing compatibility when specifying across hospitals, airports, and Class-A office towers.
Product Type:
EPA WaterSense flow rate certifications and California Title 24 mandates create divergent specification tiers based on gallons-per-flush performance and sensor reliability standards.
- Touchless Faucets:Infrared proximity detection systems operating on 0.5 GPM flow rates dominate hospital network retrofits. Texas Medical Center and Florida hospital corridors specify these for Joint Commission infection control compliance, with shorter replacement cycles than full fixture overhauls.
- Smart Toilets:Integrated bowl-and-tank systems with capacitive seat sensors and dual-flush actuators command premium specification in California new construction. Los Angeles and San Francisco commercial towers prioritize these for LEED v4.1 water efficiency credits despite complex rough-in requirements.
- Automatic Soap Dispensers:Wall-mounted infrared units with refill monitoring sensors.
- Smart Hand Dryers:High-velocity turbine models with HEPA filtration and usage counters.
Touchless Faucets handles the majority of throughput; Smart Toilets is climbing the fastest on specification share.
Technology:
Power architecture and data transmission protocols separate procurement tiers for facilities with 500 versus 50,000 daily users.
- Sensor-Based:Standalone infrared or capacitive proximity systems without network connectivity anchor budget-driven retrofits in Texas and Florida municipal buildings. Dallas-Fort Worth school districts specify these where flat water rates dilute IoT payback calculations.
- IoT-Enabled:IP-connected fixtures with API-ready dashboards for predictive maintenance capture expanding specification in Arizona and Nevada water-stressed corridors. Phoenix and Las Vegas facility managers prioritize usage analytics for drought declaration compliance reporting.
- Mobile App Integration:Bluetooth-paired configuration tools for on-site technician adjustments.
- Cloud Connectivity:Enterprise-wide data aggregation for multi-site healthcare and retail operators.
Sensor-Based retains the largest installed base; IoT-Enabled shows the steepest expansion trajectory as water stress declarations tighten.
End User:
Accreditation standards and occupancy density create divergent replacement cycle velocities across facility archetypes.
- Healthcare Facilities:Hospital networks with 24-hour clinical throughput specify touchless sensor suites to meet OSHA sanitation standards and Joint Commission accreditation. Houston Methodist and Baylor Scott & White systems mandate battery-free hydroelectric power to eliminate maintenance-intensive battery programs across thousands of units.
- Commercial Buildings:Class-A office towers in Chicago and Atlanta commercial corridors drive specification for aesthetic integration and tenant amenity differentiation. Property managers prioritize low-profile sensor housings and finish-matched escutcheons over raw technical performance.
- Restaurants:Quick-service and full-service dining chains with high table-turn velocity.
- Educational Institutions:K-12 districts and university systems with seasonal occupancy fluctuations.
Healthcare Facilities commands the highest specification intensity; Commercial Buildings delivers the largest absolute volume.
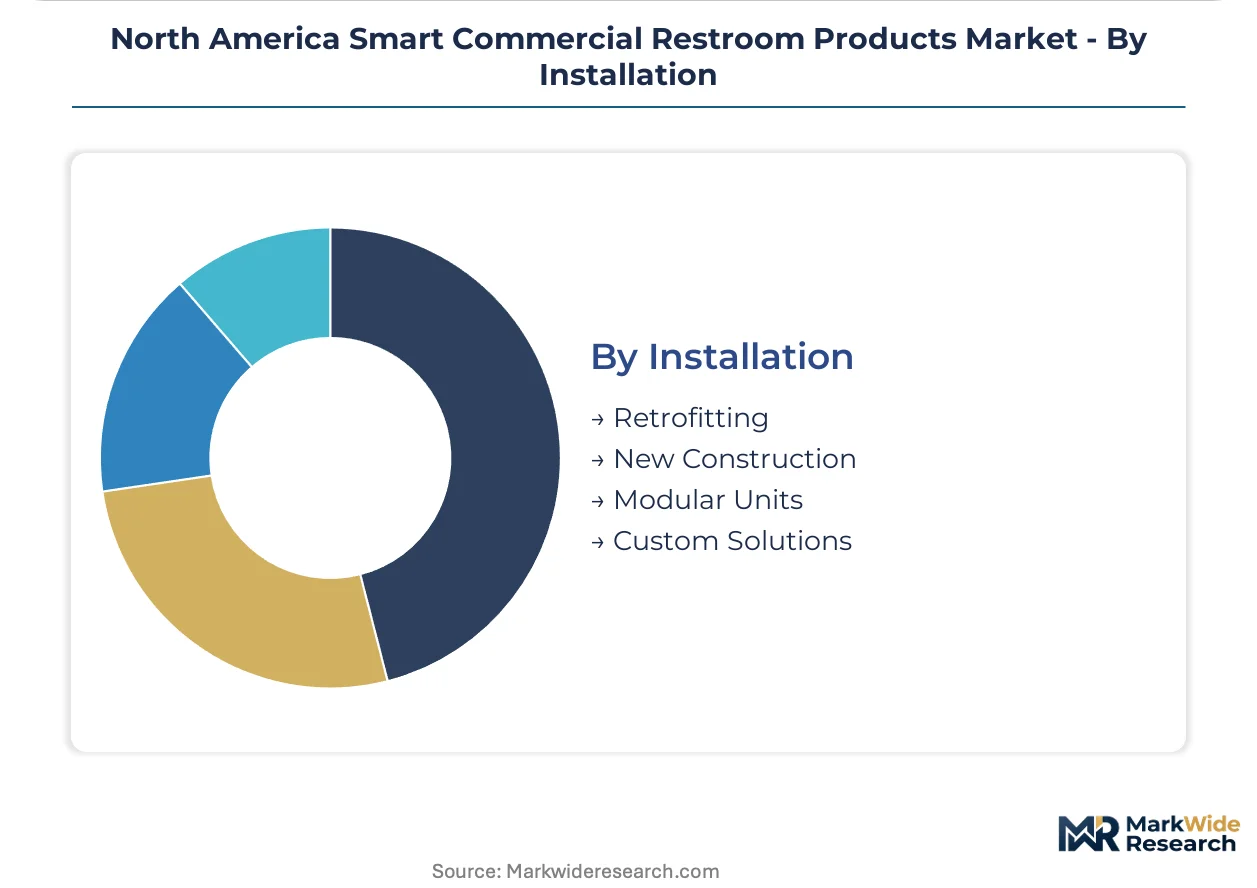
Installation:
Infrastructure age and construction timelines determine whether facilities pursue full replacement or incremental sensor retrofits.
- New Construction:Ground-up commercial and healthcare projects in California and Texas integrate smart rough-ins during MEP coordination. Title 24 compliance mandates and LEED certification pathways pull specification toward IoT-ready architectures with embedded power and data infrastructure.
- Retrofitting:Sensor-actuated valve replacement on existing flushometer bodies dominates Arizona and Nevada markets. Phoenix Sky Harbor and Las Vegas hospitality corridors pursue retrofit paths to avoid full bathroom closures during high-occupancy periods.
- Modular Units:Pre-plumbed restroom pods for rapid deployment in temporary or expansion scenarios.
- Custom Solutions:Architect-specified finishes and sensor ranges for flagship or heritage building restorations.
New Construction captures the premium specification tier; Retrofitting represents the fastest-growing deployment mode as water stress accelerates replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States manufacturers export smart commercial restroom systems to Canadian healthcare networks and Mexican hospitality developments. Cross-border specification flows concentrate in Great Lakes corridor distribution hubs serving Toronto and Vancouver medical center construction. Duty-free NAFTA-origin components sustain integrated North American supply chains for sensor-actuated valve assemblies.
United States
California Title 24 mandates and Texas municipal water stress declarations drive specification of low-flow sensor fixtures across Pacific Coast and Southwest commercial corridors. EPA WaterSense certification operates as the baseline threshold for federal procurement eligibility. Los Angeles and San Francisco Class-A office towers prioritize IoT-enabled architectures for LEED v4.1 documentation.
Canada
Health Canada and PMRA cross-border certification requirements extend product launch timelines for US-origin fixtures entering Toronto and Vancouver hospital networks. Canadian healthcare facilities specify touchless sensor suites to meet provincial infection control standards. Ontario's Golden Horseshoe corridor concentrates retrofit demand in aging institutional infrastructure.
Mexico
Mexico City and Monterrey commercial developments import US-manufactured sensor fixtures for hospitality and corporate campus construction. Mexican building codes adopt EPA WaterSense flow rate thresholds as reference standards for new commercial construction. Bajío Region automotive supplier campuses drive specification for high-traffic restroom infrastructure.
Arizona
State-level drought declarations in Phoenix and Tucson metropolitan areas compress permissible gallons-per-flush thresholds ahead of federal mandates. Arizona Department of Water Resources conservation programs incentivize IoT-enabled fixture specification for usage analytics compliance reporting. Scottsdale and Tempe resort hospitality corridors pursue accelerated retrofit cycles to maintain operational permits.
Nevada
Las Vegas hospitality and convention infrastructure specifies battery-free hydroelectric sensor systems to eliminate maintenance burdens across thousands of units. Southern Nevada Water Authority rebate programs accelerate replacement of first-generation sensor fixtures installed during the 2000-2010 building boom. Reno-Tahoe commercial districts follow similar conservation-driven procurement patterns.
North America Smart Commercial Restroom Products Market Competitive Landscape
Player mix skews toward vertically integrated plumbing fixture specialists with captive sensor technology capabilities. The vendor base concentrates around three strategic tiers: full-spectrum restroom system providers, component-specialized sensor manufacturers, and building automation platform integrators. Competitive dynamics center on specification capture through M&A-driven portfolio expansion and technology licensing partnerships for hydroelectric power architectures.
Within the integrated-systems tier, Zurn Industries and Sloan Valve Company exemplify specification dominance through vertical control over sensor-actuated valve production. Moen and Kohler occupy positions bridging consumer brand recognition with commercial specification channels. Delta Faucet Company and American Standard sit within the mid-market tier where price-competitive retrofit solutions concentrate procurement authority.
| Leading Market Players |
|---|
| Zurn Industries |
| Sloan Valve Company |
| Kimberly-Clark Worldwide |
| Moen |
| Kohler |
| Delta Faucet Company |
| American Standard |
| Toto |
| Chicago Faucet Company |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day lead times for brass alloy sensor housings concentrate upstream pricing power among North American foundries serving EPA WaterSense-certified fixture lines. This inventory compression amplifies margin pressure when copper commodity volatility intersects with healthcare procurement centralization.
Pricing Analysis
First-generation battery-powered sensor fixtures trade at 40-60% discounts to hydroelectric turbine-equipped next-generation units. Project-based transactional pricing dominates hospital network procurement, with EPA WaterSense certification tier and volume scale driving differentiation. Pricing pressure stems from semiconductor input cost volatility compressing manufacturer margins on mid-tier sensor-actuated valves. Municipal buyers in flat-rate water markets exhibit highest price sensitivity; integrated healthcare systems with enterprise sustainability mandates show lowest.
Supply Chain Analysis
United States and Mexico anchor precision brass casting and final assembly for sensor-actuated valve bodies. Taiwan and South Korea supply microcontroller chips and infrared proximity sensors. Raw material dependencies center on copper cathodes, zinc alloys, and lithium for legacy battery-powered units. Single-source vulnerability concentrates in semiconductor wafer fabrication for capacitive detection modules. Distribution runs through plumbing wholesaler networks and direct specification channels to hospital GPOs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent fixture manufacturers face substitution pressure from building automation platform integrators bundling restroom analytics into enterprise utility contracts. Defense requires strategic repositioning beyond standalone hardware sales.
For Market Incumbents: Consolidate specification authority through captive hydroelectric turbine technology and API-ready IoT architectures. Deepen backward integration into sensor micro-assembly to offset semiconductor cost volatility. Prioritize Joint Commission accreditation pathway investments to defend hospital network relationships against platform competitors. For New Entrants and Emerging Players: Anchor in Arizona and Nevada water-stressed corridors where drought declaration compliance creates specification urgency among facility managers underserved by legacy battery-powered retrofit specialists. Target retrofit deployment mode for municipal buildings with accelerated replacement cycles. Pursue usage analytics unbundling partnerships with facility management software platforms. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory ratchet play because EPA WaterSense flow rate tightening and state-level water stress declarations structurally accelerate replacement cycles independent of economic cyclicality. Acquisition targets should exhibit captive power-autonomy technology and cross-border Health Canada certification capabilities. Monitor Arizona and Nevada municipal water rate restructuring toward consumption-based billing as inflection signal for IoT-enabled fixture demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hydroelectric Power Technology Licensing | Battery-free turbine architectures eliminate maintenance burdens across hospital networks and airport authorities. |
| IoT Platform Integration Partnership | API-ready fixtures capture recurring revenue streams through facility management software dashboard integration. |
| Health Canada Certification Pathway Investment | PMRA cross-border requirements extend launch timelines; early certification captures Toronto and Vancouver hospital procurement. |
| LEED v4.1 Documentation Capability Development | Real-time water monitoring documentation secures specification in California and Texas commercial tower construction. |
| Brass Alloy Foundry Backward Integration | Captive supply of sensor housings insulates margins from copper commodity volatility and six-month lead time compression. |
Research Methodology
Initial hypotheses were tested against primary input from facility management directors, hospital procurement officers, plumbing contractor specification writers, and building automation integrators and refined through secondary validation against EPA WaterSense certification databases, California Title 24 compliance filings, hospital GPO contract repositories, and plumbing wholesaler inventory records. Bottom-up unit shipment estimates triangulated against top-down construction spending allocations across healthcare, commercial, and hospitality verticals.
Variance decomposition across product type, technology architecture, end-user facility archetype, and installation mode structured the analytical framework over the projection horizon. CAGRs derived from segment-level replacement cycle velocities, regulatory compliance mandate timelines, and water stress declaration trajectories. Forecast inputs incorporated Joint Commission accreditation standard revisions and state-level drought emergency declarations.
Material uncertainties — copper and semiconductor commodity price swings, municipal water rate restructuring timelines, cross-border certification delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding EPA WaterSense specification adoption curves and healthcare infection control mandate expansion. Recalibration cycles align with material shifts in state-level water stress declarations and federal appliance standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Natural Household Cleaners Market
Cleaning Equipment
Dry Laundry Detergents Market
Cleaning Equipment
Laundry Sanitizer Market
Cleaning Equipment
Commercial Cleaning Service Market
Cleaning Equipment
Laundry Detergent Market
Cleaning Equipment
Hand Cleaning Accessories Market
Cleaning Equipment
Furniture Polish Market
Cleaning Equipment
Brush Cleaner Market
Cleaning Equipment
Bathroom Mirror Wiper Market
Cleaning Equipment
Liquid Laundry Detergent Market
Cleaning Equipment
Global All Purpose Cleanser Market
Cleaning Equipment
Hand Wash Market
Cleaning Equipment
Contract Cleaning Services Market
Cleaning Equipment
Commercial Vacuum Cleaners Market
Cleaning Equipment
Commercial Laundry Detergent Market
Cleaning Equipment
Janitorial Service Market