
 Lawn and Garden Consumables Market | 2026-2036
Lawn and Garden Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Lawn and Garden Consumables Market Analysis
Subscription-based lawn care programs is pivoting how consumables reach end users, bundling seasonal fertilizer and pest control into recurring delivery models. Scotts Miracle-Gro leverages its direct-to-consumer platform to control replenishment cycles for homeowners. Central Garden & Pet Company anchors its market position through wholesale distributor relationships with independent garden centers. Bayer AG competes on R&D intensity in biological plant protection, extending its portfolio beyond synthetic chemistry.
Lawn and garden consumables encompass formulated chemical and biological inputs applied to turfgrass, ornamental plants, and landscape vegetation, including nitrogen-phosphorus-potassium blends, systemic insecticides, and selective herbicides with specified active ingredient concentrations. These products sustain plant health, suppress weed competition, and manage arthropod pests across managed green spaces. Fertilizers dominate value pools due to volume-driven replenishment cycles, while plant nutrients represents the fastest-growing category as precision application technologies gain traction. Residential application leads absolute consumption, though golf courses command premium pricing for specialized formulations with lower environmental impact profiles.
EPA registration requirements under FIFRA govern pesticide distribution and use in the United States, creating compliance barriers that favor established registrants with dedicated regulatory affairs capabilities. State-level restrictions on neonicotinoid applications in New York and California further fragment product availability and formulation strategies. The EU Green Deal's Farm to Fork targets, including pesticide reduction goals, are reshaping export-oriented formulation development for multinational suppliers. Stakeholders must monitor evolving state-level preemption battles and biologicals registration pathways to anticipate competitive repositioning.
Market Dynamics
Subscription bundling of seasonal consumables is restructuring how lawn care products reach residential end users, compressing traditional retail replenishment cycles while extending manufacturer control over household lifetime value.
Growth Catalysts
- Biologicals Registration Pathways:EPA's streamlined biopesticide review timelines under FIFRA are accelerating commercialization of microbial plant protection products, reducing time-to-market for fermentation-derived inputs.
- Year-Round Growing Seasons:Sun Belt metropolitan areas from Phoenix to Tampa sustain continuous application demand, eliminating seasonal revenue troughs that constrain northern distributors.
- Precision Application Technologies:Soil sensor networks and GPS-guided spreaders are enabling variable-rate fertilization, reducing waste while locking homeowners into proprietary consumable ecosystems.
Market Restraints
- Active Ingredient Supply Concentration:Chinese manufacturers dominate technical-grade glyphosate and neonicotinoid production, exposing formulators to tariff volatility and shipping disruptions.
- Neonicotinoid Restrictions:New York's Birds and Bees Protection Act and California's pending prohibition on ornamental applications are forcing portfolio restructuring toward alternative chemistries with shorter residual efficacy.
- Phosphorus Runoff Liability:Municipal watershed regulations in Chesapeake Bay and Great Lakes drainage basins are restricting fertilizer formulations, increasing compliance costs for lawn care services.
Strategic Opportunities
- Carbon Sequestration Credits:Turfgrass soil carbon protocols under development by Verra and Gold Standard could monetize lawn maintenance as climate mitigation, creating new revenue streams for property management firms.
- Direct-to-Consumer Platforms:Replenishment algorithms tied to local weather data and soil conditions are bypassing big-box retail, capturing margin previously lost to distributor markups.
- Biostimulant Convergence:Seaweed extract and humic acid formulations are merging with traditional NPK programs, opening premium positioning for products with organic certification.
Industry Challenges
- Regulatory Affairs Talent Scarcity:FIFRA registration expertise resides with a shrinking cohort of specialists, inflating salaries and extending product development timelines for mid-tier formulators.
- Legacy Equipment Compatibility:New low-dust and water-dispersible granule formulations require spreader recalibration, creating friction with established lawn service operator workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lawn and Garden Consumables Market |
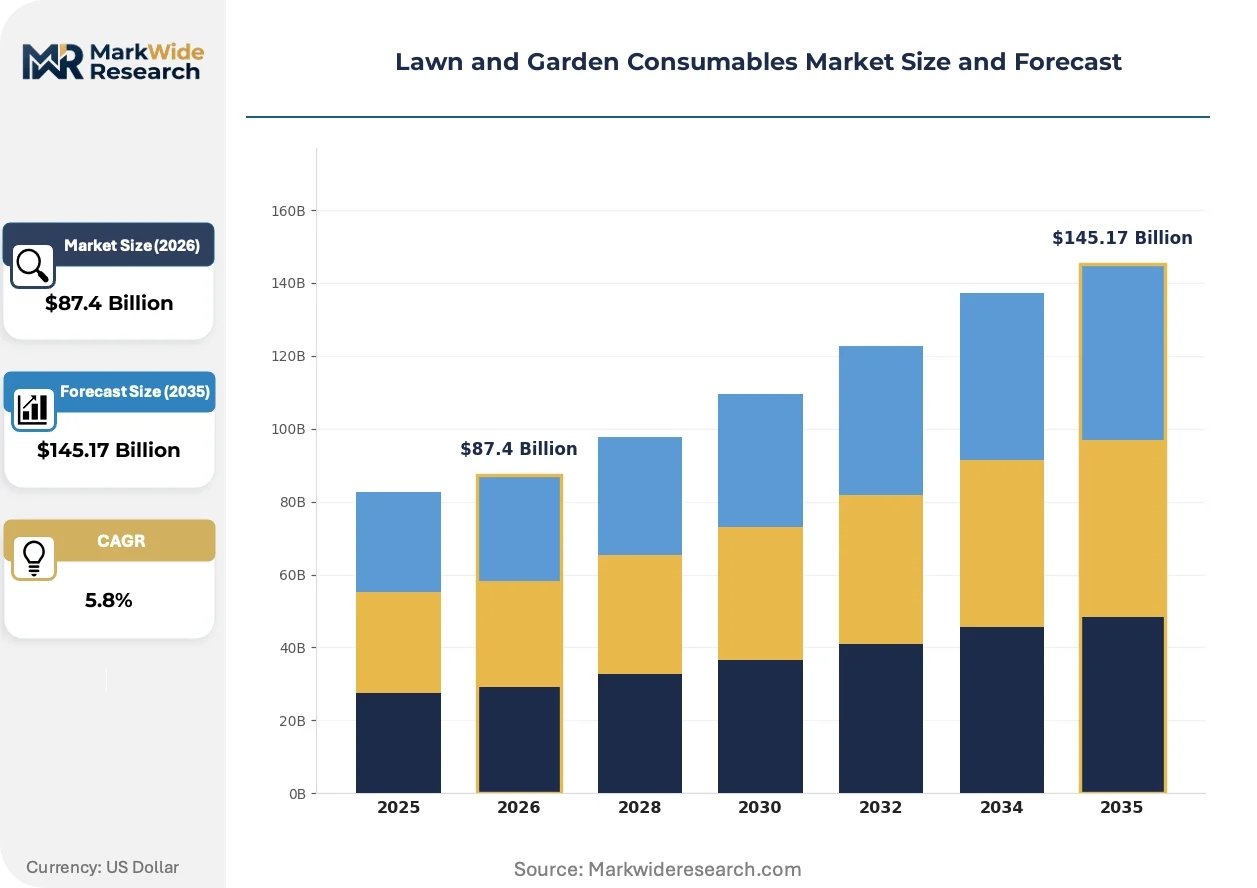
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $145.17 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fertilizers, Pesticides, Herbicides, Plant Nutrients Application: Residential, Commercial, Agricultural, Public Spaces End User: Homeowners, Landscapers, Garden Centers, Golf Courses Distribution Channel: Online Retail, Garden Supply Stores, Wholesale Distributors, Supermarkets |
| Companies Covered | Syngenta AG, Central Garden & Pet Company, Scotts Miracle-Gro, ICL Group, The Andersons Inc., Bayer AG, Corteva Agriscience, Pennington Seed Inc., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lawn and Garden Consumables Market Emerging Trajectories
Digital orchestration of application timing and product selection is displacing calendar-based lawn care rituals, embedding consumables within data-driven maintenance protocols that optimize inputs against environmental conditions.
Drone-based foliar application systems are overtaking ground-based spray equipment for large residential complexes and golf course maintenance. Superintendents at facilities exceeding 100 acres are adopting unmanned aerial platforms to treat fairway perimeters and rough areas with targeted herbicide doses. This technology is overtaking traditional boom sprayers by eliminating soil compaction while reducing labor costs and chemical exposure liability.
The EU Green Deal's Farm to Fork pesticide reduction targets are reshaping export-oriented formulation strategies for multinational suppliers. Active ingredient portfolios are pivoting toward biological and biorational chemistries to maintain European market access ahead of 2030 reduction milestones. Biological plant protection products face accelerated registration review in the United States as manufacturers anticipate similar pressure from EPA's endangered species consultations.
Homeowners are consolidating purchase decisions through subscription bundles that combine soil testing, customized fertilizer shipments, and pest alerts. This model is displacing episodic retail purchases at garden centers and home improvement chains. The shift is most visible in suburban developments across Texas, Florida, and Arizona where year-round growing seasons sustain continuous replenishment cycles and customer lifetime value calculations favor acquisition investment over transactional margins.
Lawn and Garden Consumables Market Segmentation
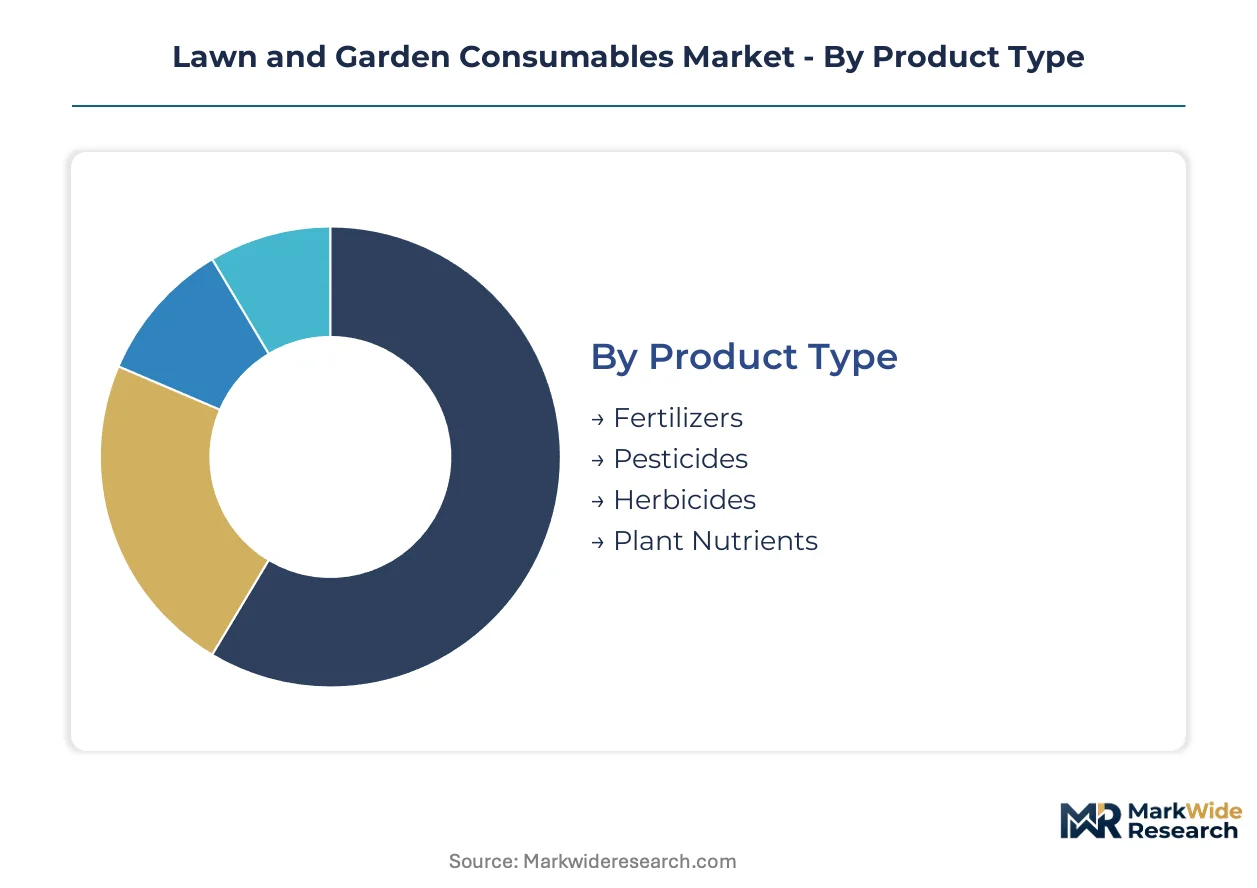
Product differentiation in lawn and garden consumables tracks closely with application intensity and regulatory exposure. Segmentation reveals where formulation complexity commands premium pricing versus commodity replenishment cycles.
Product Type:
Standardization dominates commodity fertilizers while biologicals and specialty chemistries demand customized formulation development.
- Fertilizers:Nitrogen-phosphorus-potassium blends constitute the volume foundation, with controlled-release polymer coatings enabling differentiated pricing. Demand concentrates in suburban residential developments across Sun Belt metropolitan areas where year-round application sustains continuous replenishment.
- Pesticides:Systemic and contact formulations target arthropod pests across turfgrass and ornamental applications. Golf courses in Florida, Arizona, and Texas command premium pricing for specialized formulations with reduced environmental impact profiles and shorter re-entry intervals.
- Herbicides:Selective and non-selective chemistries manage weed competition in managed landscapes.
- Plant Nutrients:Micronutrient blends and biostimulant-enhanced formulations address specific soil deficiencies.
Leading the category by volume: Fertilizers. Expanding most quickly: Plant Nutrients.
Application:
Revenue intensity inverses with acreage scale, as smaller high-value surfaces tolerate premium chemistry costs.
- Residential:Single-family homes and multi-unit properties drive absolute consumption volume through seasonal maintenance programs. Subscription bundling across Texas, Florida, and Arizona developments compresses traditional retail replenishment cycles while extending manufacturer control over household lifetime value.
- Commercial:Office parks, retail centers, and hospitality properties outsource maintenance to contracted services.
- Agricultural:Nursery operations and sod farms apply inputs at production scale with cost-minimized formulations.
- Public Spaces:Municipal parks and roadway verges face budget-constrained procurement with environmental compliance requirements.
Residential commands absolute volume. Commercial generates highest margin per treated acre.
End User:
Technical sophistication separates professional applicators from retail purchasers, driving channel and formulation divergence.
- Homeowners:DIY consumers purchase through retail and direct-to-consumer platforms with subscription algorithms tied to local weather data.
- Landscapers:Route-based service operators demand bulk packaging and equipment compatibility with existing spreader fleets.
- Garden Centers:Independent retailers anchor community-level distribution with seasonal inventory turns.
- Golf Courses:Superintendents at facilities exceeding 100 acres adopt precision application technologies including drone-based foliar systems for fairway perimeter treatment.
Homeowners represent the largest addressable population. Golf courses sustain the highest per-acre expenditure rates.
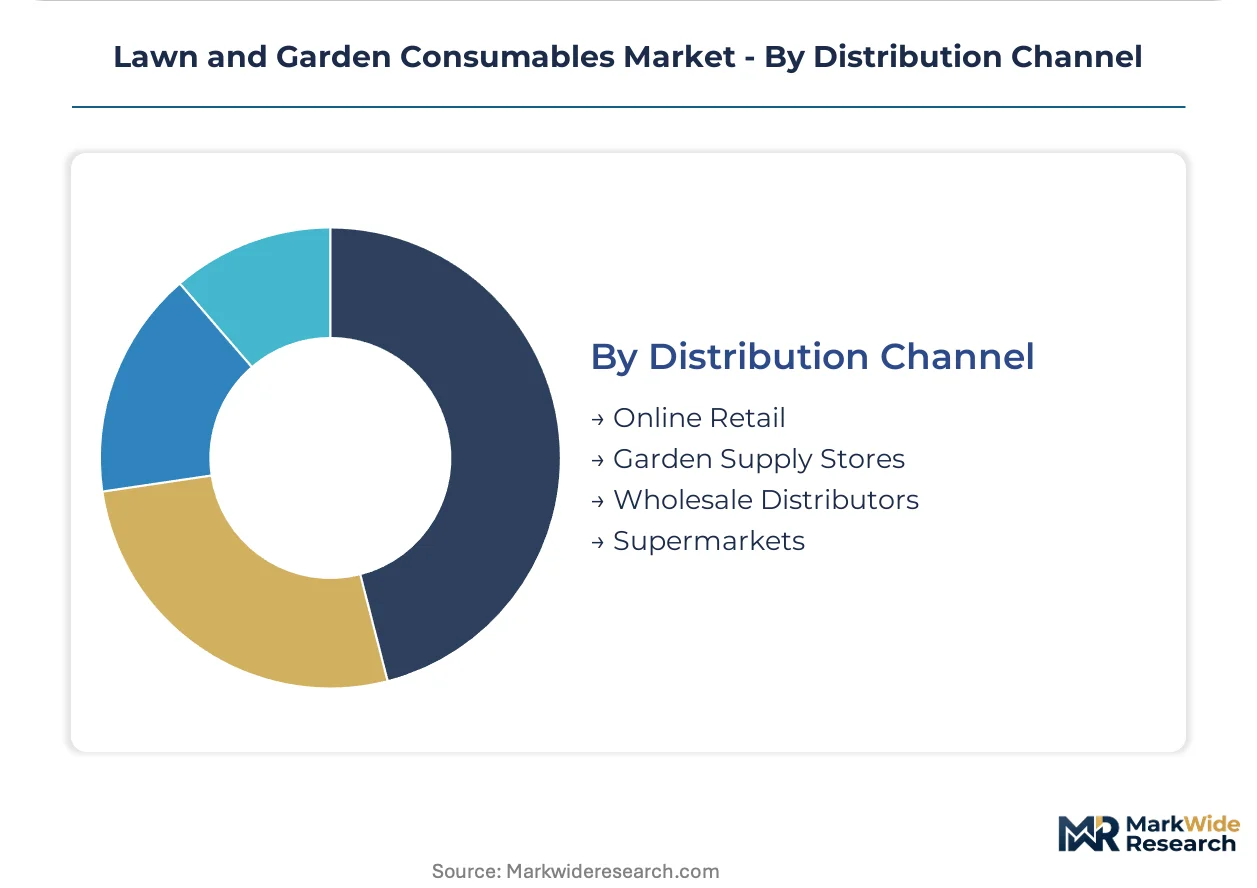
Distribution Channel:
Channel control determines margin capture and replenishment cycle ownership.
- Online Retail:Direct-to-consumer platforms bypass big-box retail markups through replenishment algorithms.
- Garden Supply Stores:Independent retailers provide localized expertise and seasonal merchandising.
- Wholesale Distributors:Central Garden & Pet Company and similar operators supply independent garden centers with inventory financing.
- Supermarkets:Mass merchants compete on price for commodity fertilizer and basic pest control SKUs.
Online retail is gaining share fastest. Wholesale distributors retain the broadest SKU breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates technical-grade active ingredient production for lawn and garden consumables, while the United States anchors end-use consumption through its sprawling suburban developments. This geographic split between upstream chemical manufacturing and downstream formulated product demand shapes trade flows and regulatory compliance burdens across the value chain.
United States
Sun Belt metropolitan areas from Phoenix to Tampa sustain year-round application demand for fertilizers and pest control products. The EPA's FIFRA registration requirements govern pesticide distribution, creating compliance barriers that favor established registrants with dedicated regulatory affairs teams. Scotts Miracle-Gro leverages its direct-to-consumer platform to control replenishment cycles for homeowners across Texas, Florida, and Arizona developments.
China
Technical-grade glyphosate and neonicotinoid production concentrates in Chinese chemical manufacturing hubs, exposing formulators to tariff volatility and shipping disruptions. The Ministry of Ecology and Environment enforces dual carbon goals that are reshaping energy-intensive fermentation processes for biological plant protection inputs. Zhejiang and Jiangsu provinces anchor the country's agrochemical export infrastructure.
Germany
Bayer AG competes on R&D intensity in biological plant protection from its German research base, extending portfolios beyond synthetic chemistry. The EU Green Deal's Farm to Fork pesticide reduction targets are accelerating formulation pivots toward microbial and biorational alternatives. BASF SE maintains its position through integrated crop science operations serving export markets.
Canada
Health Canada's PMRA regulates pesticide registration with timelines that often parallel EPA reviews, creating synchronized compliance windows for North American product launches. The Prairie Provinces sustain demand for turfgrass inputs across golf course and municipal park applications. Ontario's watershed protection rules restrict phosphorus formulations in Great Lakes drainage basins.
Australia
The Therapeutic Goods Administration and state-level environmental agencies govern agricultural chemical approvals with emphasis on waterway protection. Drought-resistant lawn varieties are shifting consumable demand toward soil moisture retention products and precision irrigation-compatible fertilizers. Sydney and Melbourne metropolitan areas concentrate residential landscaping service providers adopting subscription-based maintenance models.
Lawn and Garden Consumables Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the lawn and garden consumables sector, creating a tiered structure where integrated chemical manufacturers face specialized formulators and direct-to-consumer platforms. The market fragments across three strategic archetypes: multinational agrochemical conglomerates with biological R&D pipelines, regional formulators serving wholesale distributor networks, and digital-native platforms capturing household replenishment cycles. Dominant competitive moves include backward integration into active ingredient production and geographic expansion through distributor acquisitions in Sun Belt metropolitan markets.
Among multinational integrated players, Bayer AG and BASF SE exemplify the R&D-intensive archetype competing on biological plant protection portfolios, while Scotts Miracle-Gro occupies a position bridging formulated product manufacturing with direct-to-consumer platform control over homeowner replenishment cycles. These three companies anchor distinct competitive vectors: synthetic chemistry scale, biological innovation pipelines, and digital channel ownership.
| Leading Market Players |
|---|
| Syngenta AG |
| Central Garden & Pet Company |
| Scotts Miracle-Gro |
| ICL Group |
| The Andersons Inc. |
| Bayer AG |
| Corteva Agriscience |
| Pennington Seed Inc. |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
EU Green Deal pesticide reduction mandates gate qualified supply and premium-tier pricing access, forcing formulators to recertify biological alternatives while Sun Belt golf courses absorb elevated costs for compliant chemistries.
Pricing Analysis
Margin tightening in commodity fertilizer tiers reflects Chinese technical-grade oversupply and tariff volatility, while premium biological formulations command certification premiums through organic input standards. Three-tier pricing structure across premium, standard, and economy levels separates EPA-registered biologicals from conventional synthetics and private-label commodities. Residential homeowners in subscription programs show lowest price sensitivity; municipal public space procurement faces acute budget constraints.
Supply Chain Analysis
Direct-to-consumer platforms handle replenishment algorithms for Sun Belt homeowners, bypassing wholesale distributor markups. Technical-grade glyphosate and neonicotinoid production concentrates in China, with fermentation-derived biologicals anchored in German and US manufacturing hubs. Active ingredient supply draws from Zhejiang province chemical clusters and Jiangsu fermentation facilities. Tariff exposure on Chinese technical imports threatens margin stability. Distribution runs through wholesale networks serving independent garden centers and direct platforms capturing household lifetime value.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around regulatory compliance capabilities, with FIFRA registration expertise scarcity forcing mid-tier formulators toward acquisition or exit.
For Market Incumbents: Extend biological R&D pipelines to preempt EU Green Deal export restrictions, while securing captive supply of fermentation-derived active ingredients through backward integration into contract manufacturing partnerships. Centralize regulatory affairs talent in Washington DC corridors to compress EPA review timelines against emerging competitors. For New Entrants and Emerging Players: Municipal golf course superintendents represent an underserved buyer archetype seeking drone-compatible, low-reentry-interval formulations without legacy equipment retrofit costs. White-space concentration sits in precision application technology bundling across Arizona and Florida developments. Direct platform entry with soil sensor-integrated subscription models bypasses entrenched wholesale relationships. For Investors and Strategic Acquirers: EPA endangered species consultation acceleration is the leading indicator that biological registration timelines will compress, rewarding early portfolio positioning. Five-to-ten-year viability favors formulators with dual synthetic-biological capabilities and established Sun Belt distribution density. Target regional formulators with captive regulatory affairs specialists and distributor relationships in Texas metropolitan markets.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Formulation Pipeline Expansion | Secures EU market access ahead of Farm to Fork pesticide reduction milestones. |
| Direct-to-Consumer Platform Acquisition | Captures homeowner replenishment cycles and proprietary soil data assets. |
| Regulatory Affairs Capability Buildup | Compresses FIFRA registration timelines against talent-scarce competitors. |
| Drone Application Technology Partnership | Locks in golf course and large residential complex demand with precision foliar systems. |
| Backward Integration into Fermentation Manufacturing | Reduces dependency on Chinese technical-grade supply and tariff exposure. |
Methodological Framework
EPA registration databases, customs trade records, and SEC 10-K filings formed the secondary backbone, cross-referenced with primary interviews involving lawn care service operators, golf course superintendents, wholesale distributor procurement leads, and biological R&D directors. Bottom-up and top-down triangulation validated consumption estimates across application segments.
Bottom-up modeling anchored volume projections in treated acreage expansion and application intensity trends, while top-down analysis cross-checked value pools against disclosed revenue segments of listed formulators. Segmentation dimensions included product type tier, end-use intensity, buyer technical sophistication, and regional regulatory cluster. CAGRs derived from historical trajectory analysis and policy impact assessment across the projection horizon, incorporating neonicotinoid restriction timelines and biological registration pathway acceleration.
Revisions become necessary when EPA registration review timelines extend materially, Chinese export tariff regimes shift, or EU Green Deal implementation accelerates beyond baseline assumptions. Forecasts reflect documented assumptions on policy implementation velocity and substitution elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
Garage Organization and Storage Market
Home & Garden
Asia-Pacific Bonsai Market
Home & Garden
Artificial Flowers Market
Home & Garden
Global Wind Chime Market
Home & Garden
North America Flowerpots Market
Home & Garden
Global Motorized and Smart Awnings Market
Home & Garden
Europe Robotic Lawn Mower Market
Home & Garden
United States Lawn Care Market
Home & Garden
Landscaping Services Market
Home & Garden
Candle Market
Home & Garden
Landscaping Products Market
Home & Garden
Incense Market
Home & Garden
US Garden Planter Market
Home & Garden
Preserved Flowers Market
Home & Garden
Landscaping and Gardening Service Market
Home & Garden
Flowerpots and Planters Market