
 Europe Flower Pots Market | 2026-2036
Europe Flower Pots Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Flower Pots Market Foresight
Asset-light leasing models for commercial landscaping fleets are reshaping competitive entry barriers in the European flower pot sector. Keter Group leverages its vertically integrated resin compounding operations to control raw material quality across multiple plant locations. Lechuza differentiates through self-watering technology leadership, sustaining premium positioning in the indoor segment. Scheurich anchors its competitive stance via decades of ceramic firing expertise concentrated in German manufacturing facilities.
Europe flower pots constitute rigid containers engineered from thermoplastic resins, fired clay, or metal alloys, typically ranging from 0.5 to 50 liters in volumetric capacity, designed for root containment and moisture retention in ornamental and edible plant cultivation. Plastic vessels dominate volume throughput due to injection molding scalability and logistics efficiency, though ceramic alternatives command margin concentration in design-led retail channels. The residential end use segment leads absolute consumption, while commercial applications including hospitality terrace outfitting and municipal greening programs represent the fastest-growing demand pool. Distribution runs through garden center networks in Germany and the Netherlands, with online channels capturing incremental share among urban apartment dwellers seeking convenience.
REACH compliance governs chemical substance registration in polymer formulations, while the EU Green Deal mandates recycled content thresholds that manufacturers must integrate into virgin plastic streams. ECHA substance restrictions on specific plasticizers and heavy metal pigments directly shape permissible material specifications for colored and glazed products. Stakeholders must monitor evolving extended producer responsibility frameworks and packaging waste directives that will determine cost structures and material qualification pathways.
Market Dynamics
The EU Green Deal's recycled content mandates are forcing resin compounders to requalify virgin plastic streams, compressing formulation flexibility while elevating post-consumer resin procurement costs across German and Italian manufacturing bases.
Growth Catalysts
- Urban Balcony Gardening:German and Dutch metropolitan households are converting limited outdoor space into intensive cultivation zones, driving vessel turnover rates in sub-5-liter capacity tiers.
- REACH Chemical Registration:ECHA's substance authorization protocols are screening out non-compliant imports, creating protected demand pools for verified European manufacturers.
- Self-Watering Technology:Capillary irrigation systems embedded in polymer vessels are extending plant survival windows for time-constrained urban consumers, commanding measurable price premiums.
Market Restraints
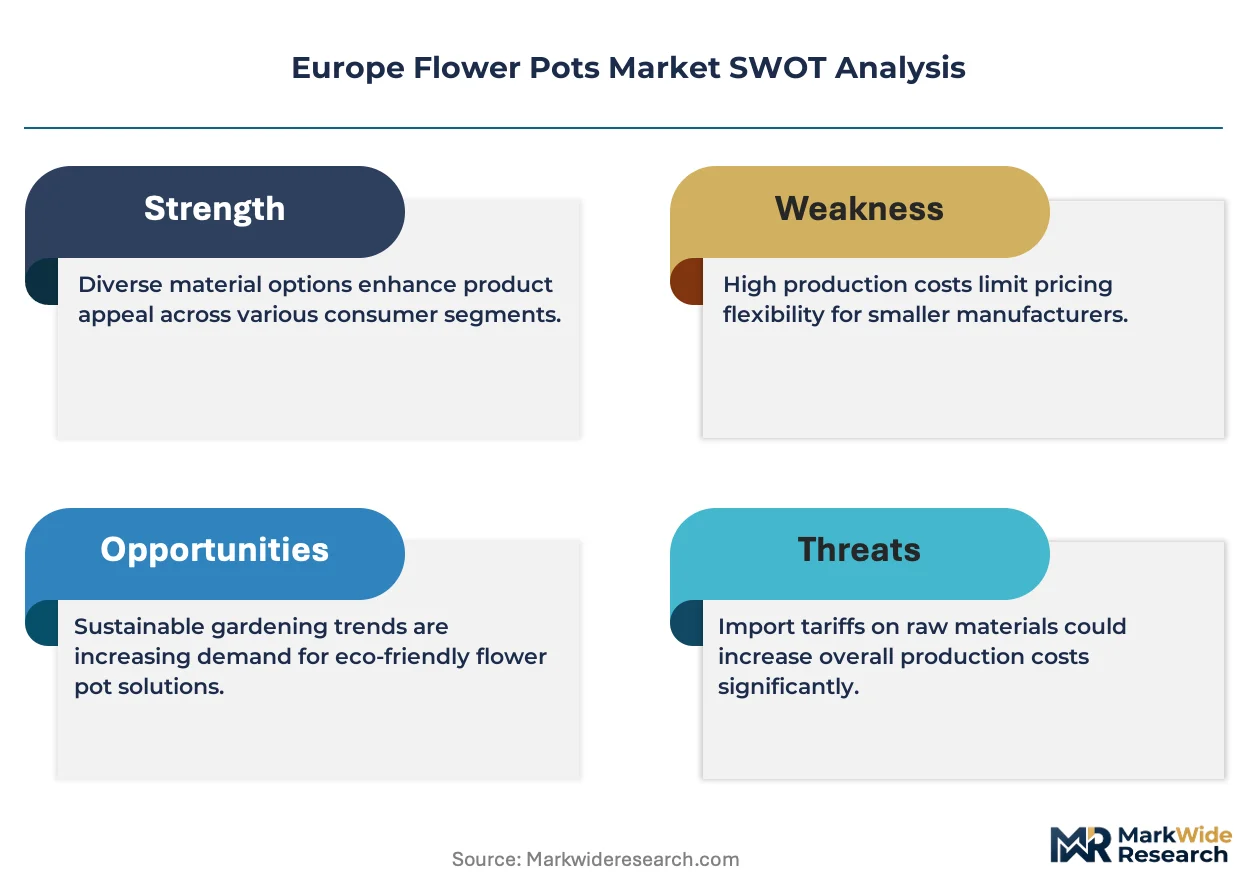
- Natural Gas Cost Volatility:Ceramic kiln operations in German manufacturing clusters face input cost instability that compresses firing margins during winter demand peaks.
- Post-Consumer Resin Supply Concentration:Qualified recycled polymer streams concentrate among Dutch and Belgian compounders, creating single-source dependency for compliant formulations.
- Extended Producer Responsibility:Evolving packaging waste directives in France and Italy impose compliance cost layers that smaller terracotta specialists cannot absorb without pricing exclusion.
Strategic Opportunities
- Eastern European Underpenetration:Polish and Romanian urban residential segments show minimal self-watering vessel adoption, presenting first-mover positioning for technology-anchored entrants.
- Hospitality Terrace Outfitting:Commercial outdoor dining spaces in Spain and Portugal require weather-resistant large-format containers with lease-return logistics, an emerging application category.
- CSRD Reporting Alignment:Corporate sustainability disclosure requirements are redirecting B2B procurement toward suppliers with verified circular material credentials, favoring prepared manufacturers.
Industry Challenges
- Color Matching Expertise Gap:Ceramic glazing operations require specialized mineral pigment chemistry knowledge that retiring German workforce cohorts possess but younger hires lack.
- Injection Mold Retooling Cycles:Shifting between virgin and recycled resin formulations demands capital-intensive screw and barrel modifications that strain mid-cap producer balance sheets.
- REACH Pre-Registration Timelines:Novel bio-based polymer additives face 18-24 month ECHA evaluation windows that delay product launches behind competitor timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Flower Pots Market |
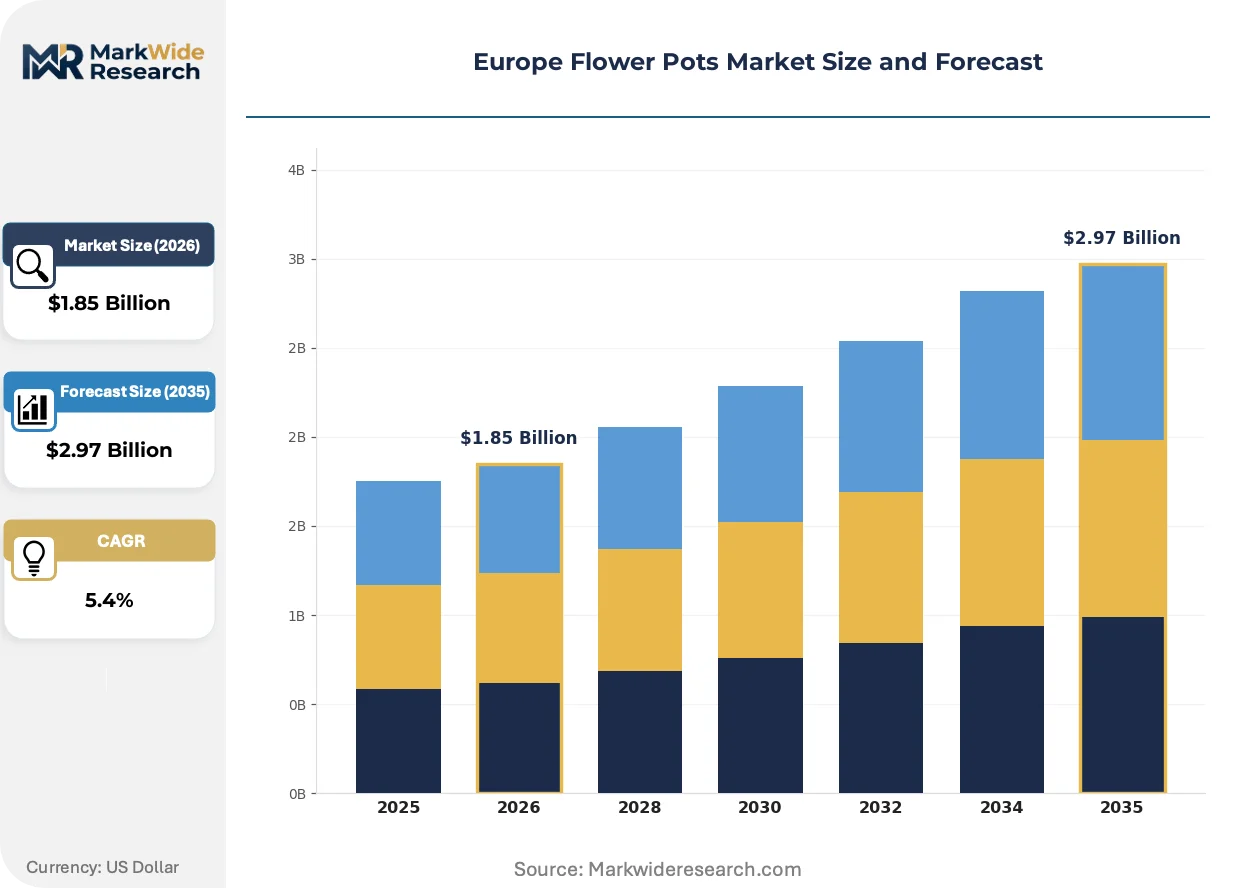
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Ceramic, Metal, Glass End Use: Residential, Commercial, Gardening, Indoor Size: Small, Medium, Large, Extra Large Distribution Channel: Online, Retail Stores, Wholesale, Garden Centers |
| Companies Covered | Keter Group, Lechuza, Scheurich, Yorkshire Flowerpots, Stefanplast, elho, Deroma Group, Prosperplast, Pöppelmann, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Flower Pots Market Shifts & Advancements
Material science convergence with regulatory pressure is compressing traditional competitive advantages in vessel manufacturing, while distribution channel fragmentation creates new access pathways for specialized entrants.
Bio-composite formulations integrating agricultural waste fibers with thermoplastic binders are collapsing the performance gap between petroleum-derived polymers and structural ceramics. Dutch compounders are scaling hemp-flax reinforced polypropylene for German garden center private labels. The technology is collapsing virgin resin volume requirements in mid-tier decorative segments where structural load demands remain modest.
EU Green Deal recycled content thresholds are mandating minimum post-consumer resin incorporation across all polymer vessel categories by the decade's midpoint. Manufacturers must revalidate injection molding parameters and color stability under degraded feedstock conditions. French mass-market retailers are imposing compliance verification ahead of regulatory deadlines, squeezing non-adapted suppliers from shelf space allocation.
Direct-to-consumer subscription models for seasonal plant-and-vessel pairings are displacing traditional garden center foot traffic among Dutch and Belgian apartment dwellers. Urban consumers prioritize convenience curation over hands-on selection, compressing brand loyalty to incumbent retailers. Paris and Amsterdam show the strongest penetration of this channel shift, with Milan and Barcelona following at 12-18 month lag intervals.
Europe Flower Pots Market Segmentation
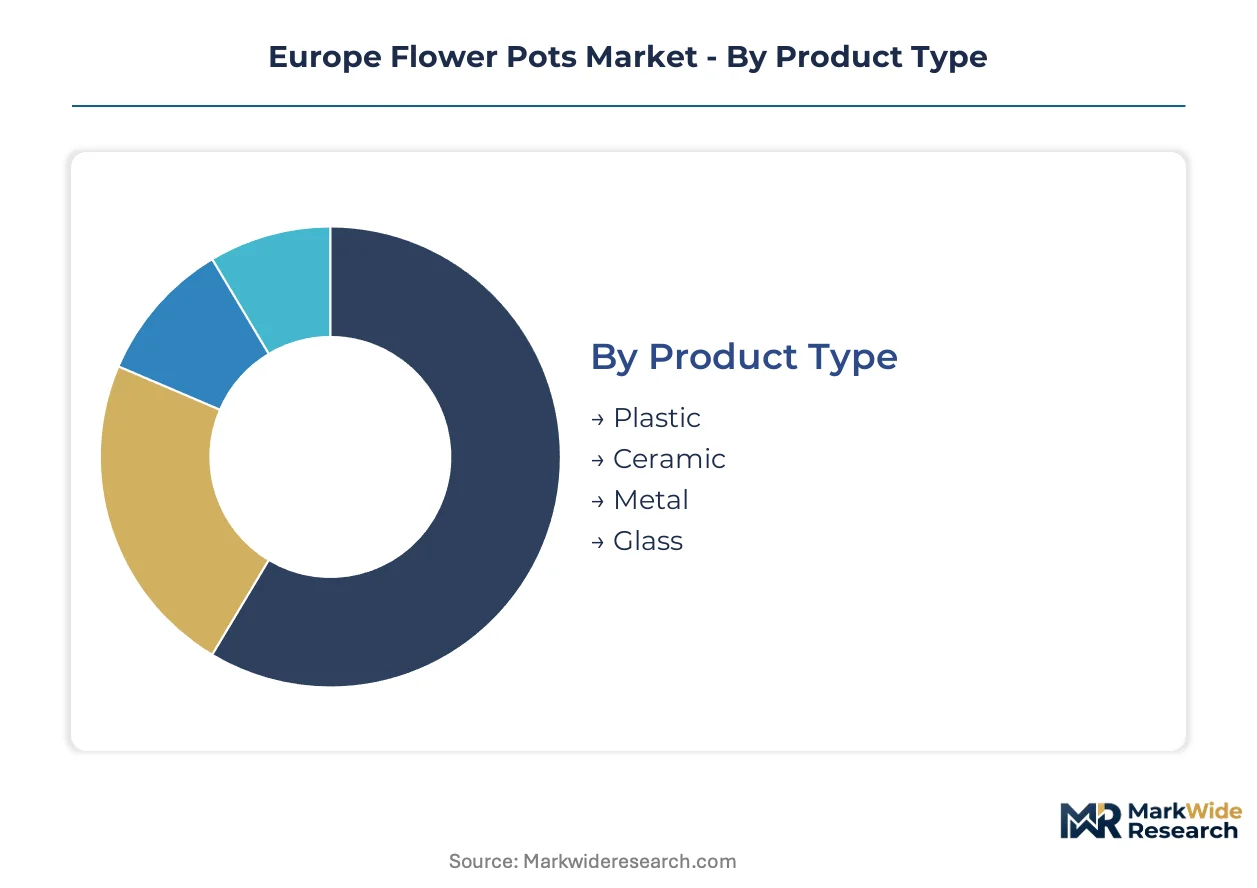
Segmentation in the Europe Flower Pots Market reveals distinct procurement rhythms across material types and use contexts. Cycle times vary dramatically—plastic vessels in commercial landscaping turn over seasonally, while premium ceramic pieces in residential courtyards persist for decades. Understanding these velocity differentials shapes inventory strategy and margin capture across manufacturer portfolios.
Product Type:
Turnover velocity diverges sharply across material categories, with thermoplastic vessels cycling fastest due to breakage and seasonal replacement, while fired clay products exhibit extended replacement horizons.
- Plastic:Injection-molded polypropylene and polyethylene formulations dominate volumetric throughput across German and Dutch distribution networks. German metropolitan balcony gardeners replace sub-5-liter vessels annually, driving consistent replenishment demand through garden center channels.
- Ceramic:Fired clay vessels, including terracotta and glazed stoneware, command sustained premium positioning in French and Italian terrace cultivation traditions. Italian courtyard owners prioritize frost-resistant majolica finishes, accepting 3-5x unit price multiples over polymer alternatives for aesthetic permanence.
- Metal:Powder-coated aluminum and corten steel containers serve commercial hospitality installations requiring weather resilience. Spanish terrace outfitters specify drainage-engineered metal vessels for lease-return fleet programs.
- Glass:Borosilicate and tempered glass vessels occupy niche indoor propagation segments. Dutch hydroponic enthusiasts drive limited but consistent demand for transparent root-visibility designs.
Plastic anchors the volume base while ceramic gains share at the steepest rate among premium-positioned urban consumers.
End Use:
Application context determines performance specifications, with commercial deployments demanding lease-return logistics and residential purchases prioritizing aesthetic integration.
- Residential:Private household procurement spans balcony, terrace, and courtyard installations across German and French urban zones. Paris apartment dwellers concentrate demand in self-watering sub-10-liter formats that minimize maintenance intervals.
- Commercial:Hospitality, corporate campus, and municipal greening programs require durable large-format vessels with standardized replacement logistics. Portuguese outdoor dining terraces drive emerging demand for weather-resistant fleet leasing arrangements.
- Gardening:Dedicated cultivation enthusiasts pursue specialized propagation and container vegetable production. Dutch urban agriculture participants favor modular systems enabling seasonal crop rotation.
- Indoor:Interior ornamental placement emphasizes design coherence with residential furnishings. Milan design-led consumers drive preference for minimalist ceramic and composite vessels matching contemporary interior palettes.
Residential commands absolute volume while commercial applications expand most quickly through hospitality sector procurement.
Size:
Volumetric capacity segments align with plant maturity stages and spatial constraints, from seedling propagation to mature tree containment.
- Small:Sub-5-liter vessels serve herb cultivation, succulent display, and seedling starting. German balcony gardeners cycle these units fastest, replacing seasonally.
- Medium:5-15 liter capacities accommodate patio tomatoes, ornamental shrubs, and mixed container arrangements. French terrace traditions concentrate demand in this tier for mixed floral displays.
- Large:15-30 liter vessels support dwarf fruit trees, substantial ornamental specimens, and commercial installation requirements. Italian courtyard cultivation sustains premium ceramic procurement in this capacity range.
- Extra Large:30+ liter containers serve mature tree containment, commercial landscape focal points, and municipal greening. Spanish hospitality terrace outfitters specify these formats for immediate visual impact.
Medium sizes dominate unit volume while extra large formats climb the fastest through commercial sector adoption.
Distribution Channel:
Channel selection reflects customer convenience priorities and purchase deliberation intensity, with digital platforms capturing time-constrained urban segments.
- Online:E-commerce platforms and direct-to-consumer subscriptions capture Dutch and Belgian apartment dwellers prioritizing curated convenience over tactile selection. Amsterdam shows strongest penetration of plant-and-vessel subscription services.
- Retail Stores:Mass-market and specialty retailers serve immediate-need purchasers and gift-buying occasions. German garden center chains maintain dominant foot traffic through experiential merchandising.
- Wholesale:B2B procurement channels supply commercial landscaping contractors and hospitality fleet operators. Polish commercial developers source large-format vessels through regional wholesale distributors.
- Garden Centers:Specialist horticultural retailers provide expert consultation and premium product access. Italian independent garden centers sustain terracotta specialist positioning through ceramic firing expertise.
Retail stores anchor the volume base while online channels gain share at the steepest rate among urban millennial and Gen-Z demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan balcony gardeners and terrace cultivators concentrate procurement power across German, French, and Italian urban corridors, with Dutch distribution hubs mediating supply chain flows.
Germany
Berlin and Hamburg apartment dwellers drive sub-5-liter self-watering vessel demand through intensive balcony cultivation. REACH chemical registration protocols screen non-compliant imports, protecting domestic manufacturers. The Rhine-Ruhr manufacturing cluster hosts resin compounding and ceramic firing operations serving mass-market and premium segments.
France
Parisian terrace traditions sustain premium ceramic procurement in glazed stoneware and frost-resistant majolica finishes. Extended producer responsibility frameworks under evolving packaging waste directives impose compliance cost layers on smaller terracotta specialists. The Île-de-France region anchors design-led retail channel concentration for ornamental vessel distribution.
Italy
Courtyard cultivation in Milan and Rome maintains demand for large-format ceramic vessels with 3-5x price multiples over polymer alternatives. EU Green Deal recycled content mandates are redirecting manufacturer material strategies toward post-consumer resin integration. The Emilia-Romagna ceramic district sustains specialized glazing expertise for premium export markets.
Netherlands
Amsterdam and Rotterdam apartment dwellers show strongest penetration of direct-to-consumer plant-and-vessel subscription services. ECHA substance restrictions on specific plasticizers shape permissible material specifications for colored polymer products. Dutch compounders concentrate qualified recycled polymer streams, creating single-source dependencies for compliant formulations.
Spain
Barcelona and Madrid hospitality terrace outfitters drive emerging demand for weather-resistant large-format containers with lease-return logistics. CSRD reporting alignment requirements redirect B2B procurement toward suppliers with verified circular material credentials. The Mediterranean coastal corridor hosts commercial landscaping fleet operations serving outdoor dining expansion.
Europe Flower Pots Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tiering. The vendor base organizes around resin compounders with captive material supply, ceramic firing specialists with decades of expertise concentration, and technology-anchored innovators with self-watering irrigation systems. Strategic moves concentrate on portfolio diversification into bio-composite formulations and geographic expansion toward underpenetrated Eastern European markets.
Within the vertically integrated resin segment, Keter Group exemplifies upstream control over raw material quality across multiple plant locations. Lechuza occupies a position as technology-anchored innovator with self-watering system leadership. Scheurich anchors the ceramic specialist tier through concentrated firing expertise in German manufacturing facilities.
| Leading Market Players |
|---|
| Keter Group |
| Lechuza |
| Scheurich |
| Yorkshire Flowerpots |
| Stefanplast |
| elho |
| Deroma Group |
| Prosperplast |
| Pöppelmann |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp barge freight corridors transmit natural gas cost volatility directly into German ceramic kiln operations, compressing firing margins while amplifying price spreads between polymer vessels from Dutch compounders and terracotta from Italian Emilia-Romagna specialists.
Pricing Analysis
Natural gas-indexed cost-plus contracts dominate ceramic procurement between Italian firing facilities and French retail buyers, with three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on frost-resistance certification and glazing complexity rather than raw material grade. Pricing pressure stems from REACH compliance testing costs that smaller terracotta workshops cannot absorb. Mass-market German balcony gardeners exhibit highest price sensitivity, while Milan design-led consumers accept substantial premiums for aesthetic permanence.
Supply Chain Analysis
Tariff exposure between Dutch resin compounders and German injection molders dominates supply chain risk assessments for polymer vessel categories. Manufacturing concentrates in Germany, Italy, and the Netherlands, with raw material streams drawing from Belgian post-consumer resin processors and Emilia-Romagna clay deposits. Feedstock hinges on qualified recycled polymer availability from Dutch-Belgian compounders. Distribution runs through German garden center networks and Dutch direct-to-consumer subscription platforms serving apartment-dwelling segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-and-vessel subscription services expand faster than hardware turnover among Dutch and Belgian urban consumers, converting one-time transactions into recurring revenue streams with superior retention economics.
For Market Incumbents: Insulate ceramic margin positions by securing long-term clay supply agreements with Emilia-Romagna quarry operators before competitor consolidation. Accelerate self-watering technology R&D to defend against Lechuza's irrigation system dominance in premium indoor segments. REACH pre-registration timelines for novel bio-based additives represent the critical regulatory threat requiring dedicated compliance investment. For New Entrants and Emerging Players: Polish and Romanian urban residential segments with minimal self-watering vessel adoption represent the most penetrable entry point for technology-anchored challengers. Commercial hospitality terrace outfitting in Barcelona and Madrid offers fleet leasing arrangements with lease-return logistics as differentiated service attach. Direct-to-consumer subscription models bypass entrenched German garden center channel control. For Investors and Strategic Acquirers: EU Green Deal recycled content mandates reshape the acquisition landscape by elevating compounders with verified post-consumer resin credentials above virgin resin specialists. Five-to-ten year viability favors targets with backward integration into resin compounding or captive ceramic firing expertise. Monitor ECHA substance restriction announcements for inflection signals on formulation requalification costs.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Consumer Resin Integration | EU Green Deal compliance secures shelf space with French mass-market retailers ahead of regulatory deadlines. |
| Self-Watering Technology Licensing | Capillary irrigation patents command measurable price premiums from time-constrained urban consumers. |
| Eastern European Distribution Expansion | Polish and Romanian garden center networks remain underpenetrated by premium vessel categories. |
| Hospitality Fleet Leasing Programs | Spanish and Portuguese outdoor dining terraces require weather-resistant containers with standardized logistics. |
| Ceramic Glazing Expertise Acquisition | Retiring German workforce cohorts possess mineral pigment chemistry knowledge that younger hires lack. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the European flower pot value chain, including garden center category managers, resin compounding technical directors, ceramic firing facility operators, hospitality procurement leads, and municipal greening program coordinators. Secondary validation drew from ECHA substance registration databases, EU packaging waste directive filings, German garden center association trade statistics, and Dutch e-commerce platform transaction data. Bottom-up vessel volume estimates triangulated against top-down material consumption figures from polymer and clay trade associations.
Calibration against historical growth patterns across material type, end use, and distribution channel segments anchored the projection framework. Segmentation dimensions modeled include product material, application context, volumetric capacity tier, and regional regulatory cluster. CAGRs were derived from regression analysis of correlated demand drivers including urban household formation rates and hospitality sector expansion indices. Forecast inputs incorporated REACH compliance cost trajectories and recycled resin availability curves from Dutch-Belgian compounder capacity announcements.
Practitioners should monitor ECHA substance restriction proposals and EU Green Deal implementation timelines for early signals of formulation requalification burdens. Forecasts reflect assumptions about recycled resin supply elasticity and natural gas price normalization that material cost volatility could revise. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
Aquarium LED Lighting Market
Home & Garden
Residential Snow Blower Market
Home & Garden
Preserved Flowers Market
Home & Garden
Global Hot Tub Market
Home & Garden
Bird House Market
Home & Garden
Lawn and Garden Water Equipment Market
Home & Garden
Electric Lawn Mower Market
Home & Garden
North America Flowerpots Market
Home & Garden
United Kingdom Homeware Market
Home & Garden
Hedge Trimmer Market
Home & Garden
Artificial Plants and Flowers Market
Home & Garden
Gardening Pots Market
Home & Garden
Europe Robotic Lawn Mower Market
Home & Garden
Asia-Pacific Bonsai Market
Home & Garden
Japan Flower Pots Market
Home & Garden
Flexible Garden Hoses Market