
 Flower Box Market | 2026-2036
Flower Box Market Size, Share, and Industry Trends Forecast 2026-2036
Flower Box Market Foresight
Recycled corrugated fiberboard is realigning cost structures across the flower box supply chain as brands abandon single-use plastic formats. Alyeska Farms leverages its Pacific Northwest sourcing network to secure FSC-certified pulp inputs at scale. The Bouqs Company differentiates through direct-to-consumer subscription logistics that minimize intermediate packaging layers. Johnston's Quality Flowers anchors its wholesale position with custom-printed rigid boxes for event florists.
A flower box is a rigid or semi-rigid container engineered to protect, display, and hydrate cut stems or potted plants during transit and retail presentation, typically incorporating moisture-resistant liners, ventilation apertures, and structural ribs rated for stacking loads of 15–25 kg. Cardboard boxes dominate unit volume in floral retailer and online marketplace channels due to printability and kerbside recyclability, while luxury gift boxes command disproportionate margin pools in corporate gifting services where unboxing experience determines repeat purchase rates. Wooden crates sustain niche demand among specialty boutiques targeting farmhouse and rustic design style preferences.
EPA guidelines on recycled content thresholds and the EU Green Deal packaging rules are tightening compliance costs for plastic container formats while accelerating fiber-based innovation budgets. FDA indirect food contact standards for moisture-barrier coatings shape liner material selection for boxes destined to hospitality sector customers. Stakeholders must monitor whether California's extended producer responsibility framework and Germany's Verpackungsgesetz amendments will force redesign cycles faster than converter R&D timelines can accommodate.
Market Dynamics
Recycled corrugated fiberboard is displacing single-use plastic formats across the flower box supply chain as EU Green Deal packaging rules and EPA recycled content thresholds tighten compliance costs for polymer-based containers.
Growth Catalysts
- EU Green Deal packaging sustainability rules:The framework mandates fiber-based substrates for floral retail packaging, accelerating converter R&D budgets toward moisture-resistant liner innovations.
- Residential balcony gardening:Urban households in dense metropolitan clusters drive demand for compact, stackable containers with integrated hydration systems.
- Germany:Verpackungsgesetz amendments strengthen extended producer responsibility, forcing brand owners to redesign toward kerbside-recyclable formats.
Market Restraints
- FSC-certified pulp input costs:Pacific Northwest sourcing constraints create price volatility for converters dependent on certified fiber supply chains.
- Moisture-barrier coating compliance:FDA indirect food contact standards limit liner material selection for hospitality sector boxes, extending qualification timelines.
- Rigid plastic substitution threat:Polypropylene formats retain cost advantages in high-volume wholesale channels where unboxing experience carries lower premium weight.
Strategic Opportunities
- Corporate gifting services:Luxury rigid boxes with custom-printed exteriors command disproportionate margin pools where unboxing experience determines repeat purchase rates.
- Event florist channel:Direct-to-consumer subscription logistics minimize intermediate packaging layers, reducing material intensity per stem delivered.
- Farmhouse design preference segment:Wooden crates sustain niche demand among specialty boutiques targeting rustic aesthetic positioning.
Industry Challenges
- California extended producer responsibility framework:State-level redesign mandates are outpacing converter R&D cycle timelines for moisture-resistant fiber formulations.
- Stacking load certification:Structural ribs rated for 15–25 kg loads require specialized testing protocols that extend new product introduction schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flower Box Market |
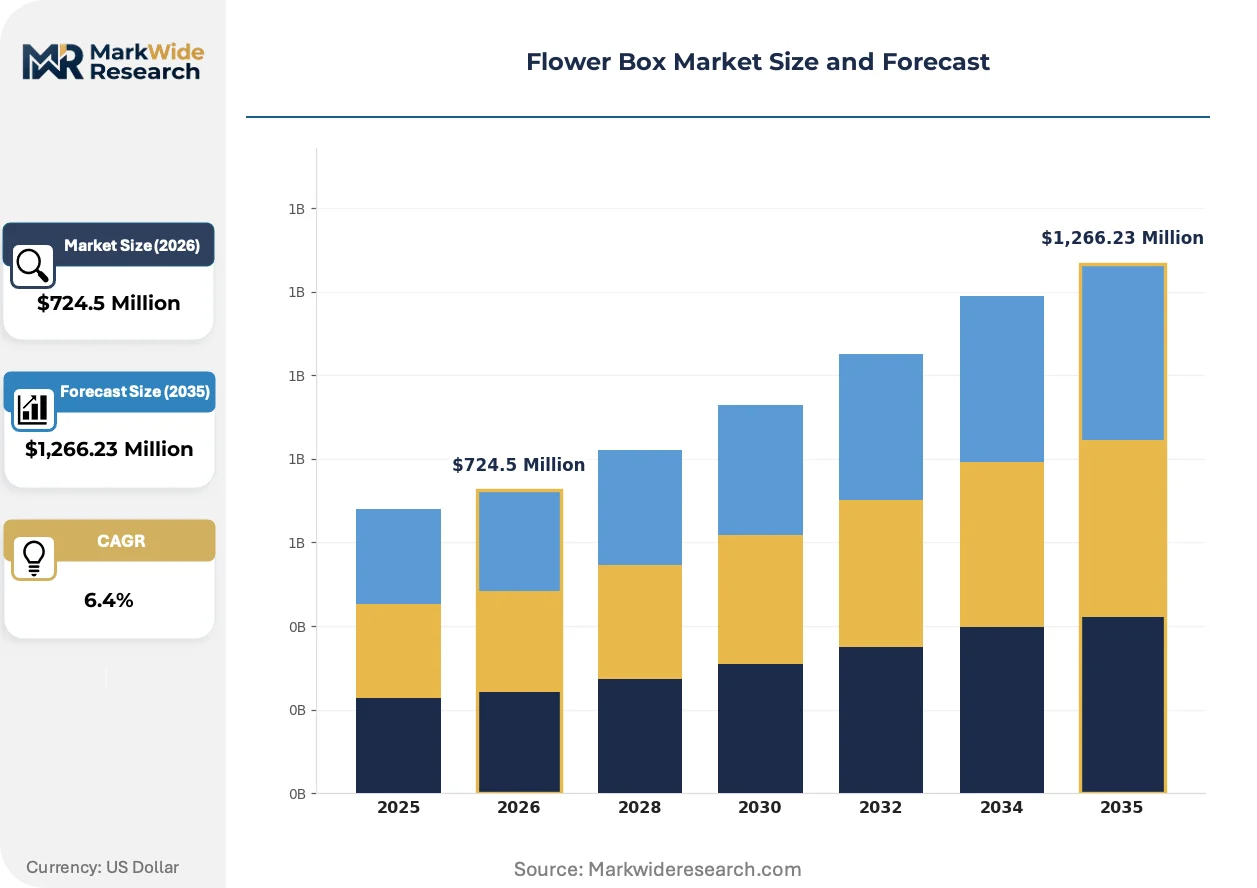
| Market Size in 2026 | $724.5 Million |
| Market Size in 2035 | $1,266.23 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardboard Boxes, Wooden Crates, Plastic Containers, Luxury Gift Boxes Design Style: Minimalist, Vintage, Rustic, Modern Chic Distribution Channel: Floral Retailers, Online Marketplaces, Specialty Boutiques, Corporate Gifting Services Customer Type: Individual Consumers, Event Planners, Hospitality Sector, Corporate Buyers |
| Companies Covered | Alyeska Farms, Johnston's Quality Flowers, The Bouqs Company, Roberts Floral & Gifts, Wood's Flowers and Gifts, UrbanStems, Shady Vines Floral Co., Tycoon Packaging, STEMZ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flower Box Market Shifts & Advancements
Fiber-based material science and regulatory compliance frameworks are compressing design cycles while reshaping competitive positioning across premium and mass-market channels.
Plantable seed-embedded cardboard is absorbing end-of-life disposal costs for direct-to-consumer floral subscriptions. Urban millennial households in Berlin and Amsterdam adopt these formats at accelerating rates. The technology is absorbing landfill diversion liabilities that previously burdened municipal waste systems.
REACH restrictions on perfluorinated moisture barriers are forcing liner material pivots toward bio-based coatings. German converters face reformulation costs exceeding prior capex allocations for barrier technologies. The event florist segment responds by consolidating supplier relationships with fiber specialists holding ECHA pre-registration dossiers.
Subscription box procurement now favors single-source converters capable of integrated print, cut, and fulfillment services. Traditional wholesale distributors lose share to vertically integrated packaging partners. This concentration is most visible in Netherlands logistics hubs serving Benelux e-commerce fulfillment networks.
Flower Box Market Segmentation
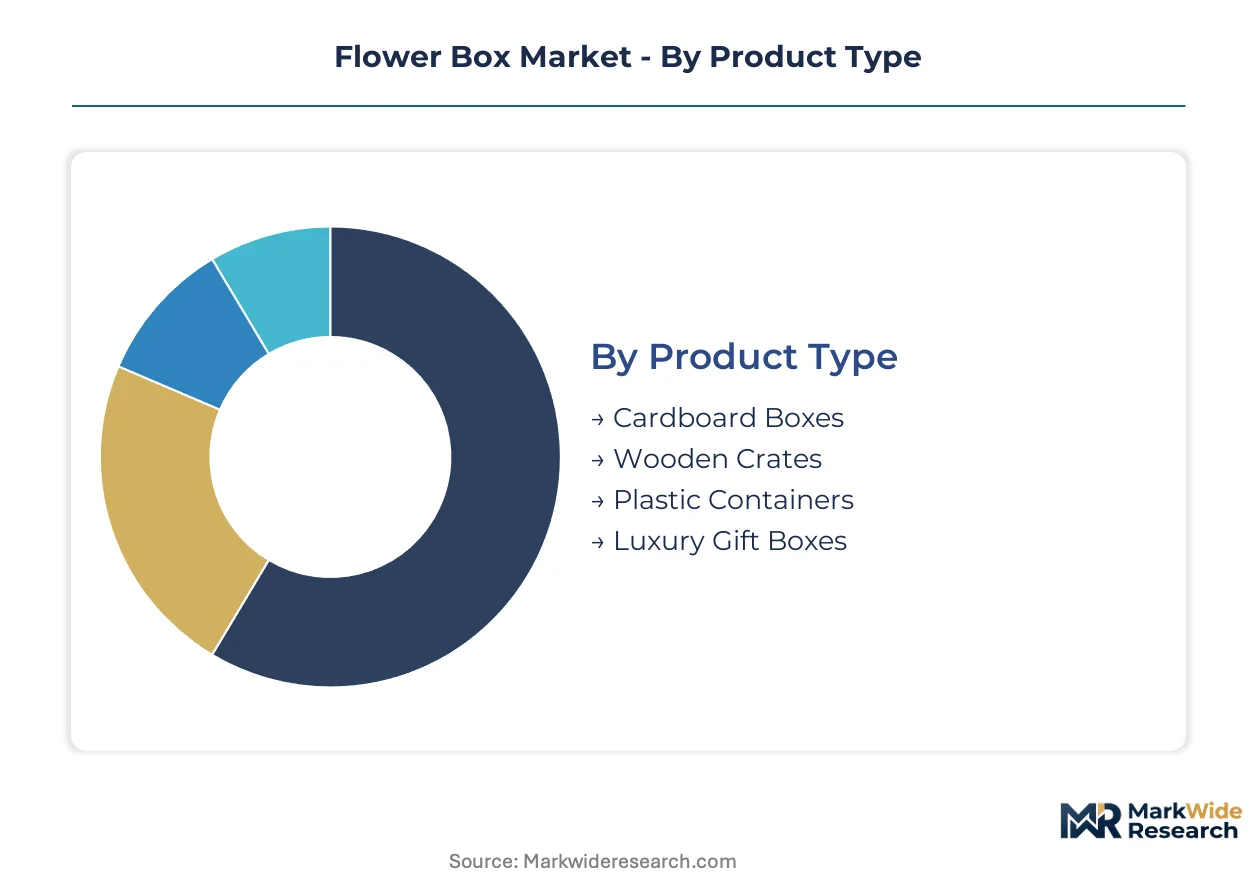
Flower box segmentation reflects divergent pressure points across protection requirements, aesthetic positioning, and regulatory compliance. Material choices and channel strategies fragment the competitive landscape into distinct margin pools with incompatible operational models.
Product Type:
Customization depth spans commodity-grade corrugated through bespoke rigid formats, with moisture resistance and print fidelity defining the standardization spectrum.
- Cardboard Boxes:Recycled corrugated fiberboard with moisture-resistant liners dominates unit volume through kerbside recyclability and high-resolution print compatibility. Demand concentrates in floral retailers and online marketplaces where EU Green Deal packaging rules accelerate displacement of polymer alternatives.
- Luxury Gift Boxes:Rigid paperboard with magnetic closures and custom-foil exteriors command disproportionate margin pools in corporate gifting services where unboxing experience determines repeat purchase rates. German event planners specify these formats for premium hospitality sector deliveries.
- Wooden Crates:FSC-certified pine and cedar constructions sustain niche positioning among specialty boutiques targeting farmhouse design preferences in Pacific Northwest markets.
- Plastic Containers:Polypropylene formats retain cost advantages in high-volume wholesale channels despite tightening EPA recycled content thresholds and extended producer responsibility liabilities.
Leading the category by volume: Cardboard Boxes. Expanding most quickly: Luxury Gift Boxes.
Design Style:
Stylistic positioning maps directly to customer lifetime value tiers, with heritage aesthetics anchoring premium pricing and clean minimalism capturing urban density constraints.
- Minimalist:Unbleached kraft surfaces with single-color logos reduce material intensity and print costs. Berlin and Amsterdam urban millennial households adopt these formats for balcony gardening applications at accelerating rates.
- Rustic:Distressed wood grains and galvanized metal accents align with farmhouse design preferences in specialty boutique channels. This segment absorbs landfill diversion liabilities through seed-embedded biodegradable substrates.
- Modern Chic:Matte laminates and geometric die-cuts target hospitality sector procurement specifications in metropolitan clusters.
- Vintage:Antique typography and sepia-toned imagery serve event florist channel requirements for wedding and anniversary occasion packaging.
Leading the category by volume: Minimalist. Climbing the fastest: Rustic.
Distribution Channel:
Channel concentration determines packaging complexity, with direct-to-consumer logistics favoring integrated fulfillment partnerships over traditional wholesale intermediaries.
- Online Marketplaces:Subscription box procurement now favors single-source converters capable of integrated print, cut, and fulfillment services. Netherlands logistics hubs serving Benelux e-commerce networks exhibit the most visible consolidation.
- Corporate Gifting Services:Custom-printed rigid boxes with moisture-barrier compliance for hospitality sector customers require extended FDA indirect food contact qualification timelines.
- Floral Retailers:Kerbside-recyclable formats with ventilation apertures and structural ribs rated for stacking loads dominate brick-and-mortar replenishment cycles.
- Specialty Boutiques:Wooden crates and plantable seed-embedded cardboard absorb end-of-life disposal costs previously burdening municipal waste systems.
Leading the category by volume: Floral Retailers. Gaining share fastest: Online Marketplaces.
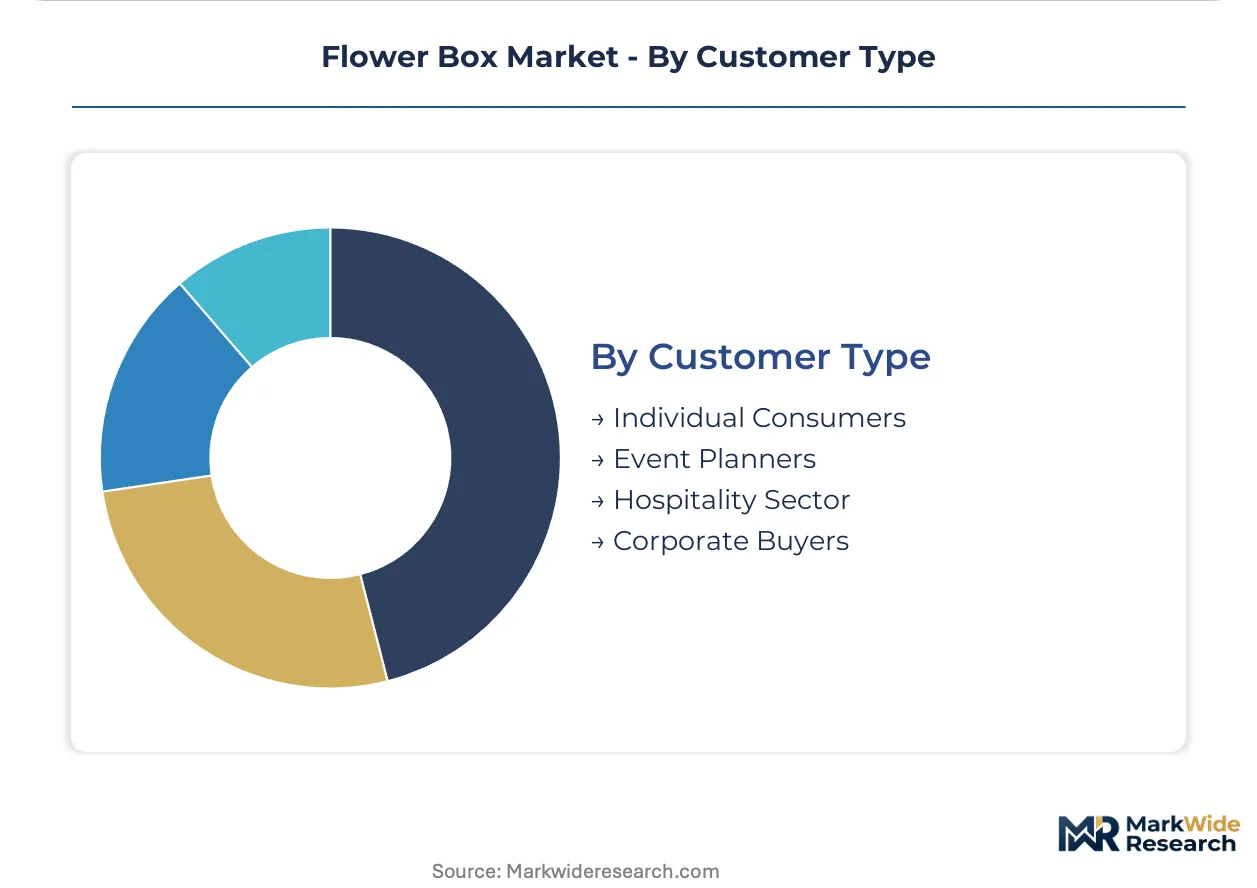
Customer Type:
Procurement authority and volume scale create divergent technical requirements, with institutional buyers prioritizing compliance documentation and individual consumers responsive to sustainability signaling.
- Corporate Buyers:Custom-printed exteriors with brand-aligned color matching and magnetic closure systems dominate procurement specifications. REACH restrictions on perfluorinated moisture barriers force liner material pivots toward bio-based coatings with ECHA pre-registration dossiers.
- Hospitality Sector:FDA indirect food contact standards for moisture-barrier coatings shape material selection and extend supplier qualification timelines for event florist channel deliveries.
- Event Planners:Consolidated supplier relationships with fiber specialists holding German Verpackungsgesetz compliance documentation reduce redesign cycle risks.
- Individual Consumers:Direct-to-consumer subscription logistics minimize intermediate packaging layers, reducing material intensity per stem delivered in residential balcony gardening applications.
Leading the category by volume: Individual Consumers. Steepest expansion trajectory: Corporate Buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in the Netherlands and Germany's Ruhr Valley concentrate converter capacity near Benelux distribution hubs. Tax incentives for sustainable packaging R&D accelerate fiber-based innovation clusters across Northern Europe.
Germany
Verpackungsgesetz amendments strengthen extended producer responsibility for floral retail packaging. Berlin's urban millennial households drive demand for minimalist kraft formats in balcony gardening applications. The Ruhr Valley converter cluster specializes in moisture-resistant liner innovations for EU Green Deal compliance.
Netherlands
Randstad logistics hubs serve Benelux e-commerce fulfillment networks with integrated print-cut-fulfillment services. REACH restrictions on perfluorinated moisture barriers force liner reformulation toward bio-based coatings. Amsterdam specialty boutiques absorb seed-embedded cardboard formats for landfill diversion.
United States
California's extended producer responsibility framework outpaces converter R&D timelines for moisture-resistant fiber formulations. EPA recycled content thresholds tighten compliance costs for plastic container formats. Pacific Northwest sourcing networks secure FSC-certified pulp inputs for sustainable packaging converters.
United Kingdom
Corporate gifting services in London command premium pricing for custom-printed rigid boxes with magnetic closures. CSRD disclosure requirements shape procurement specifications for hospitality sector packaging. Midlands converter clusters specialize in event florist channel deliveries with FDA-compliant moisture barriers.
France
Île-de-France event planners consolidate supplier relationships with fiber specialists holding ECHA pre-registration dossiers. ANSM guidelines on indirect food contact standards extend qualification timelines for hospitality sector boxes. Paris luxury retail channels drive demand for bespoke rigid formats with foil exteriors.
Flower Box Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with direct-to-consumer subscription players capturing margin pools that wholesale distributors cannot access. The vendor base organizes around three archetypes: Pacific Northwest pulp-integrated converters, vertically integrated fulfillment partners, and boutique rigid-box specialists. Capacity expansion and strategic partnerships dominate competitive moves as regulatory timelines compress design cycles.
Among Pacific Northwest-based operators, Alyeska Farms anchors the pulp-integrated tier through FSC-certified sourcing networks. The Bouqs Company occupies a position within the subscription-logistics archetype, minimizing intermediate packaging layers. Johnston's Quality Flowers exemplifies the wholesale-specialist segment with custom-printed capabilities for event florists.
| Leading Market Players |
|---|
| Alyeska Farms |
| Johnston's Quality Flowers |
| The Bouqs Company |
| Roberts Floral & Gifts |
| Wood's Flowers and Gifts |
| UrbanStems |
| Shady Vines Floral Co. |
| Tycoon Packaging |
| STEMZ |
| Others |
Supply & Pricing Matrix
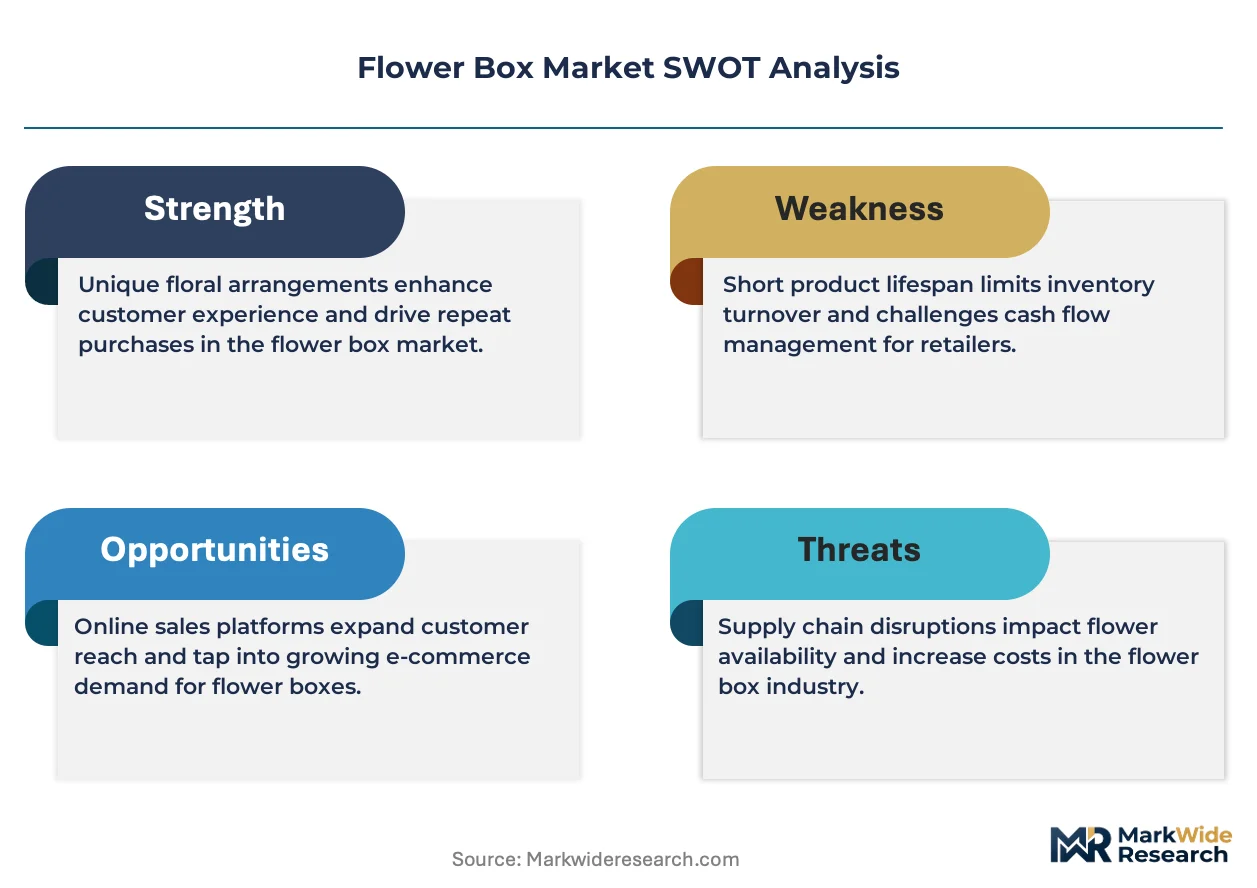
FSC-certified pulp input indices cascade through converter cost structures into three distinct pricing tiers for floral packaging. Pacific Northwest fiber sourcing volatility compresses margins at the commodity corrugated tier while accelerating premium capture in rigid-box segments.
Pricing Analysis
Short lead-time premiums of 15-25% apply to custom-printed rigid boxes for event florist channels, while spot inventory of standard kraft corrugated trades at volume discounts. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified rigid formats from recycled corrugated and polypropylene wholesale containers. Pricing pressure stems from REACH-mandated liner reformulation costs that German converters pass through selectively. Corporate gifting services show least price sensitivity; high-volume wholesale distributors face greatest margin compression.
Supply Chain Analysis
FSC-certified pulp supply rests on Pacific Northwest sourcing networks, German Ruhr Valley converter clusters, and Netherlands logistics hubs. Raw material dependencies span moisture-resistant liner substrates, bio-based barrier coatings, and magnetic closure hardware. Single-source vulnerability concentrates in ECHA-registered coating specialists facing REACH reformulation timelines. Distribution runs through vertically integrated print-cut-fulfillment partners serving Benelux e-commerce networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over FSC-certified pulp inputs and direct-to-consumer fulfillment infrastructure determines margin capture. Players are pursuing backward integration into certified fiber supply chains as the decisive upstream lever.
For Market Incumbents: Lock in Pacific Northwest pulp sourcing through long-term offtake agreements with FSC-certified mills before Verpackungsgesetz amendments tighten supply. Consolidate Netherlands logistics partnerships to defend against subscription-logistics entrants. Prioritize ECHA pre-registration dossiers for bio-based coating formulations to outpace REACH compliance deadlines.
For New Entrants and Emerging Players: Plantable seed-embedded cardboard technology offers a technology-first wedge into Amsterdam and Berlin urban millennial segments with minimal incumbent presence. Target specialty boutique channels in farmhouse design preferences where wooden crate demand outpaces supply. Pursue direct-to-consumer subscription logistics partnerships rather than wholesale distributor relationships.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated converters with captive FSC-certified fiber supply and integrated fulfillment capabilities. Acquisition targets should demonstrate compliance documentation for EU Green Deal packaging rules and FDA indirect food contact standards. Watch California extended producer responsibility framework implementation as the inflection signal for forced redesign cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into FSC-Certified Pulp Supply | Captive fiber sourcing insulates against Pacific Northwest price volatility and Verpackungsgesetz supply constraints. |
| Integrated Print-Cut-Fulfillment Service Launch | Netherlands logistics hubs serving Benelux e-commerce networks favor single-source converters over wholesale distributors. |
| Bio-Based Moisture Barrier Certification | ECHA pre-registration dossiers for REACH-compliant coatings unlock hospitality sector procurement specifications. |
| Direct-to-Consumer Subscription Logistics Partnership | Minimizing intermediate packaging layers captures margin pools inaccessible to traditional wholesale channel players. |
| Seed-Embedded Biodegradable Substrate Development | Landfill diversion liability absorption attracts Amsterdam and Berlin urban millennial households at accelerating rates. |
Research Methodology
Independent corroboration across converter procurement directors, floral retailer category managers, and event florist channel buyers underwrites the qualitative findings. Primary interviews with FSC-certified pulp sourcing specialists, Netherlands logistics hub operators, and German Verpackungsgesetz compliance officers combined with secondary validation from EU Green Deal regulatory filings, EPA recycled content guidelines, and ECHA REACH restriction dossiers. Bottom-up demand modeling and top-down supply capacity assessment triangulate volume estimates.
Comparable historical periods anchored the projection framework across the analysis window. Segmentation dimensions modeled include material substrate tier, design style positioning, distribution channel complexity, and customer procurement authority. CAGRs derived from regression analysis against macroeconomic indicators and regulatory implementation timelines. Industry-specific forecast inputs incorporate FSC-certified pulp price index trajectories and EU Green Deal packaging rule compliance cost curves.
Several conditions sit outside the modeled scope, including unforeseen raw material supply disruptions, accelerated California extended producer responsibility implementation, and breakthrough moisture-barrier coating technologies. Forecasts reflect documented assumptions about regulatory timelines and substitution elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
Outdoor Cooking Table Market
Home & Garden
Lawn and Garden Consumables Market
Home & Garden
Global Wind Chime Market
Home & Garden
Flowerpots and Planters Market
Home & Garden
Christmas Decorations Market
Home & Garden
Global Hot Tub Market
Home & Garden
United Kingdom Homeware Market
Home & Garden
Landscaping and Gardening Service Market
Home & Garden
Gardening Pots Market
Home & Garden
Preserved Flowers Market
Home & Garden
Europe Robotic Lawn Mower Market
Home & Garden
United States Landscaping Market
Home & Garden
Candle Market
Home & Garden
Flexible Garden Hoses Market
Home & Garden
US Garden Planter Market
Home & Garden
North America Floral Gifting Market