
 Europe Robotic Lawn Mower Market | 2026-2036
Europe Robotic Lawn Mower Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Robotic Lawn Mower Market Intelligence
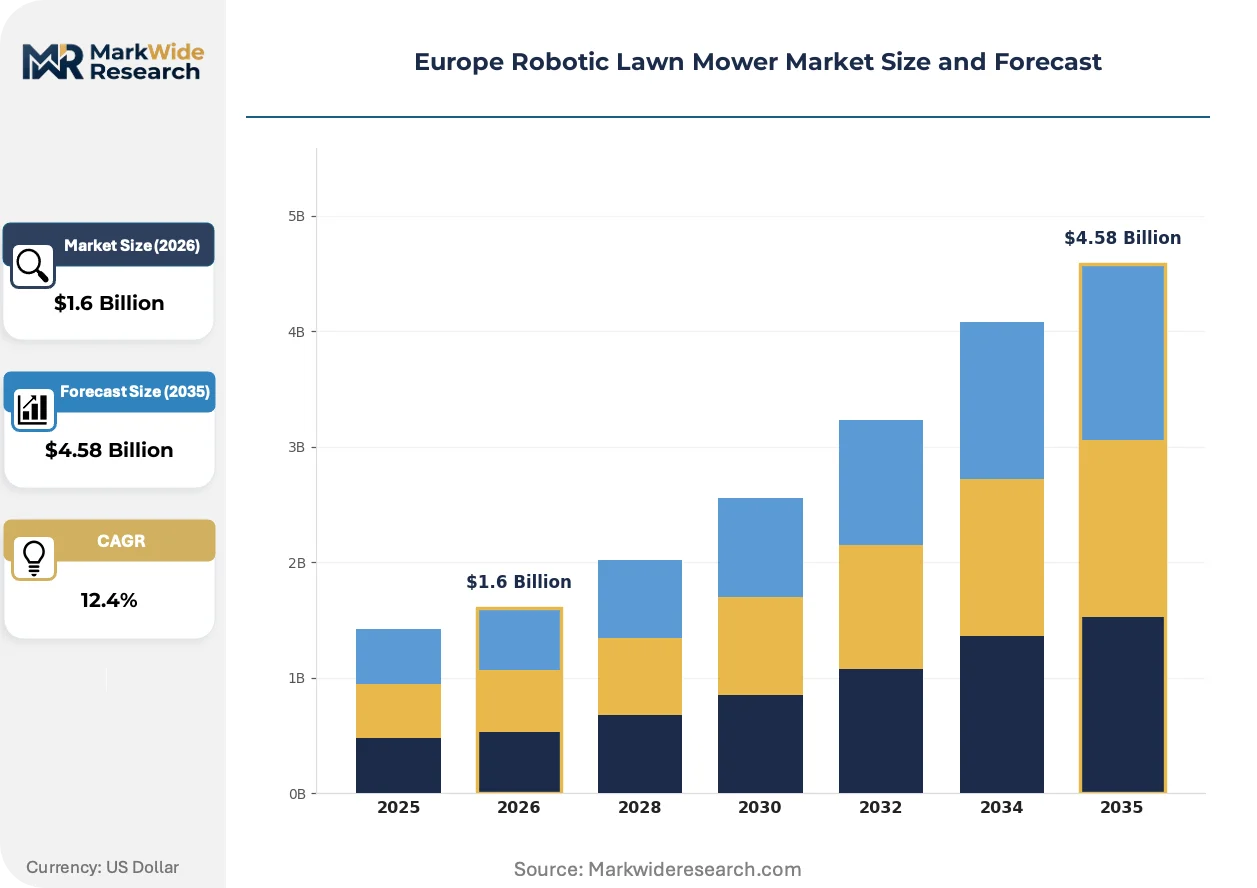
Software-as-a-service subscriptions for enhanced navigation and security features are repositioning the value proposition from a one-time hardware sale to recurring revenue models in the European market. Husqvarna Group leverages its extensive dealer network and brand recognition across Europe to capture a significant share of the premium residential segment. Robert Bosch GmbH competes through technology integration, linking its mowers to a broader smart home ecosystem. Meanwhile, STIHL specializes in durable, professional-grade models targeting landscaping firms.
A robotic lawn mower is an autonomous device designed to automatically cut lawn grass within a defined area in Europe. Most units operate using a perimeter wire for boundary detection and are powered by rechargeable lithium-ion batteries, returning to a docking station for charging. Within the technology segment, GPS and camera-based navigation systems are gaining share over traditional boundary wire-dependent models. The residential end-user category dominates sales volume, while the professional segment, serving sports facility maintenance, offers higher margins per unit.
All robotic mowers sold in the European Union must comply with CE marking requirements, demonstrating conformity with health, safety, and environmental protection standards. The EU's RoHS directive restricts hazardous substances in electronic components, while the upcoming EU AI Act will impose new risk management obligations on autonomous systems. Manufacturers must now decide whether to develop AI capabilities in-house to comply with new regulations or partner with specialized technology providers.
Market Dynamics
The transition from a one-time hardware sale to a recurring revenue model represents the central structural force in the European robotic lawn mower market. This shift is driven by the integration of software-as-a-service subscriptions for advanced navigation and security features.
Growth Catalysts
- Urban Greening Policies:Municipal regulations across Europe promoting noise reduction and zero-emission maintenance in residential zones and public spaces create a direct incentive for adopting quiet, battery-powered robotic mowers over conventional gasoline models.
- Smart Home Integration:The expansion of connected home ecosystems, particularly in affluent households in Germany and the Nordic countries, fuels demand for mowers that can be managed and automated through a central smart home platform.
- Battery Technology Advancement:Continuous improvements in the energy density and cost-effectiveness of lithium-ion batteries enable manufacturers to offer longer runtimes and faster charging cycles, making the devices more practical for a wider range of garden sizes.
Market Restraints
- High Initial Capital Outlay:The significant upfront cost of a robotic mower compared to a traditional push or ride-on mower remains a primary barrier to entry for many households in Europe, limiting mass-market penetration.
- Boundary Wire Dependency:Many existing models rely on a physical perimeter wire for navigation, which is often complex and labor-intensive to install and can be easily damaged, creating a significant usability friction point for consumers.
- Regulatory Compliance Burden:The forthcoming EU AI Act imposes new, stringent risk management and data governance obligations on autonomous systems, potentially increasing development costs and time-to-market for manufacturers, especially smaller ones.
Strategic Opportunities
- Eastern Europe Expansion:Markets in countries like Poland and the Czech Republic, with rising disposable incomes and a strong culture of garden ownership, represent a significant, underpenetrated growth opportunity for robotic mower manufacturers.
- Professional Landscaping Services:Developing specialized, durable models for commercial applications such as maintaining sports fields, corporate campuses, or public parks opens a high-margin B2B market segment beyond the residential sector.
- AI-Powered Fleet Management:The convergence of computer vision with 5G connectivity enables the creation of subscription-based fleet management platforms for landscaping companies, offering remote diagnostics, optimized scheduling, and autonomous operation of multiple units.
Industry Challenges
- AI Compliance Expertise:A shortage of software engineers and data scientists with specific expertise in developing and validating AI systems to meet the rigorous transparency and safety standards of the EU AI Act presents a key talent bottleneck.
- Smart Home Interoperability:Ensuring seamless integration and consistent performance across the fragmented landscape of smart home platforms and standards prevalent in Europe poses a persistent technical challenge for device manufacturers.
- Cybersecurity Vulnerabilities:As mowers become more connected and reliant on software, protecting them from hacking, data theft, and unauthorized control becomes a critical operational challenge, requiring constant vigilance and software updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Robotic Lawn Mower Market |
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $4.58 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact, Standard, Professional, Heavy-Duty, Autonomous Technology: LiDAR, GPS, Ultrasonic Sensors, Infrared Sensors, Camera-Based End User: Residential, Landscaping Firms, Property Management, Sports Facility Maintenance Distribution Channel: Online Retailers, Specialty Stores, Direct Sales, Hardware Chains, Garden Centers |
| Companies Covered | Belrobotics, Zucchetti Centro Sistemi, Husqvarna Group, GGP STIGA, STIHL, Robert Bosch GmbH, Deere & Company, Kress Robotics, AL-KO Gardentech, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Robotic Lawn Mower Market Strategic Shifts & Innovations
The evolution from simple perimeter-based automation to intelligent, vision-guided autonomy is reshaping the product landscape. This transformation is driven by advancements in onboard processing, sensor fusion, and AI-based navigation, fundamentally changing how the devices interact with their environment.
Camera and GPS-based navigation systems provide the core technology for next-generation wire-free mowers. The premium residential and professional segments are adopting these systems, valuing the enhanced flexibility and simplified setup they offer. This sensor fusion technology is electrifying the product category, transforming it from a fixed-perimeter tool into a dynamic, adaptable landscaping asset capable of mapping and navigating complex environments autonomously.
The EU AI Act introduces a comprehensive regulatory framework for artificial intelligence systems. This legislation mandates rigorous risk assessment, data quality management, and human oversight for high-risk AI applications, which will include advanced autonomous mowers. Manufacturers developing proprietary AI navigation are most affected, now needing to build robust compliance and documentation processes directly into their product development lifecycle to secure market access within the European Union.
Subscription-based service models are altering consumer purchasing behavior in the European market. This shift disrupts the traditional one-time hardware transaction, replacing it with recurring revenue streams tied to software-enabled features like advanced anti-theft tracking, intelligent weather-based mowing schedules, and multi-zone management. This trend is most visible in digitally mature markets such as the Netherlands and Scandinavia, where consumers readily adopt service-oriented technology purchasing.
Europe Robotic Lawn Mower Market Segmentation
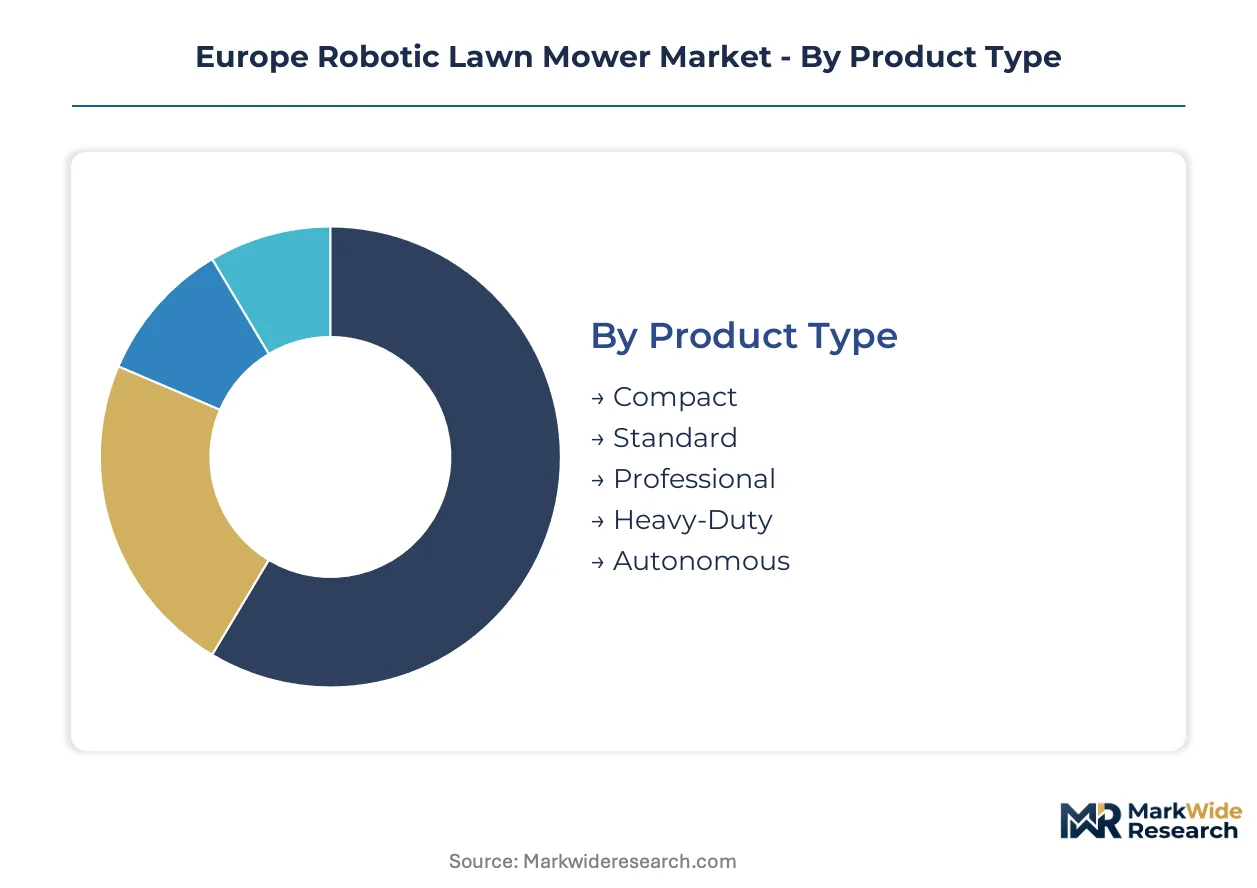
Understanding the Europe robotic lawn mower market requires a detailed segmentation analysis, revealing how diverse product types, technologies, end-user needs, and distribution channels influence purchasing decisions. This breakdown illustrates the specific value propositions driving adoption across European consumers and businesses.
Product Type:
European consumers and professional users prioritize different performance characteristics and garden sizes when selecting a robotic lawn mower product type.
- Professional:These models feature robust construction, larger battery capacities, and advanced fleet management capabilities for demanding commercial use. Demand concentrates among landscaping firms and sports facility maintenance providers in Germany and the Nordic countries, driven by operational efficiency requirements.
- Autonomous:Autonomous robotic mowers integrate advanced AI, computer vision, and sensor fusion for wire-free navigation and dynamic obstacle avoidance. This technology is gaining traction in premium residential segments and commercial applications across Western Europe, offering enhanced flexibility and simplified installation.
- Compact:Designed for smaller urban gardens, these mowers offer basic perimeter-wire operation and cost-effectiveness for European city dwellers.
- Standard:These mid-range models cater to average-sized residential lawns, balancing features and price for a broad European consumer base.
- Heavy-Duty:Built for extensive areas like large estates or public parks, heavy-duty mowers provide extended runtime and durability for European property managers.
Standard models lead on scale; Autonomous models lead on momentum.
Technology:
The underlying technology determines a robotic mower's navigation precision, installation complexity, and overall cost for European buyers.
- Camera-Based:These systems utilize computer vision for real-time environment mapping, obstacle detection, and wire-free navigation, offering high adaptability. Demand is accelerating in the premium residential and professional segments across Europe, driven by ease of setup and advanced feature integration.
- GPS:GPS-enabled mowers define boundaries and navigate using satellite signals, reducing reliance on physical perimeter wires. This technology finds strong adoption in larger residential properties and commercial settings in countries like Germany, valuing flexibility and precise area management.
- LiDAR:LiDAR technology provides highly accurate 3D mapping for complex environments, primarily used in high-end professional European models.
- Ultrasonic Sensors:These sensors detect obstacles using sound waves, serving as a cost-effective safety and navigation component in many entry-level European mowers.
- Infrared Sensors:Infrared sensors provide basic obstacle avoidance and boundary detection, commonly integrated into more affordable European robotic lawn mower designs.
GPS and Camera-Based technologies are expanding most quickly, transforming mower capabilities across the European market.
End User:
Different end-user categories in Europe possess distinct requirements for mower size, durability, and operational features.
- Residential:Individual homeowners constitute the largest segment, seeking convenience, quiet operation, and smart home integration for their private gardens. This segment drives volume sales across all European regions, particularly in urban areas with smaller lawns.
- Landscaping Firms:These professional businesses require robust, high-capacity mowers with fleet management capabilities for efficient service delivery. Demand is strong in countries like France and the UK, where commercial landscaping is a significant industry.
- Property Management:Property managers oversee common areas and large residential complexes, demanding reliable and scalable mowing solutions across their European portfolios.
- Sports Facility Maintenance:This segment requires specialized mowers for precise cutting on athletic fields and golf courses, prioritizing accuracy and turf health in European venues.
Residential users represent the largest consumer base, while Landscaping Firms seek specialized, high-margin solutions.
Distribution Channel:
The preferred distribution channel for European robotic lawn mowers often reflects consumer purchasing habits, product complexity, and required after-sales support.
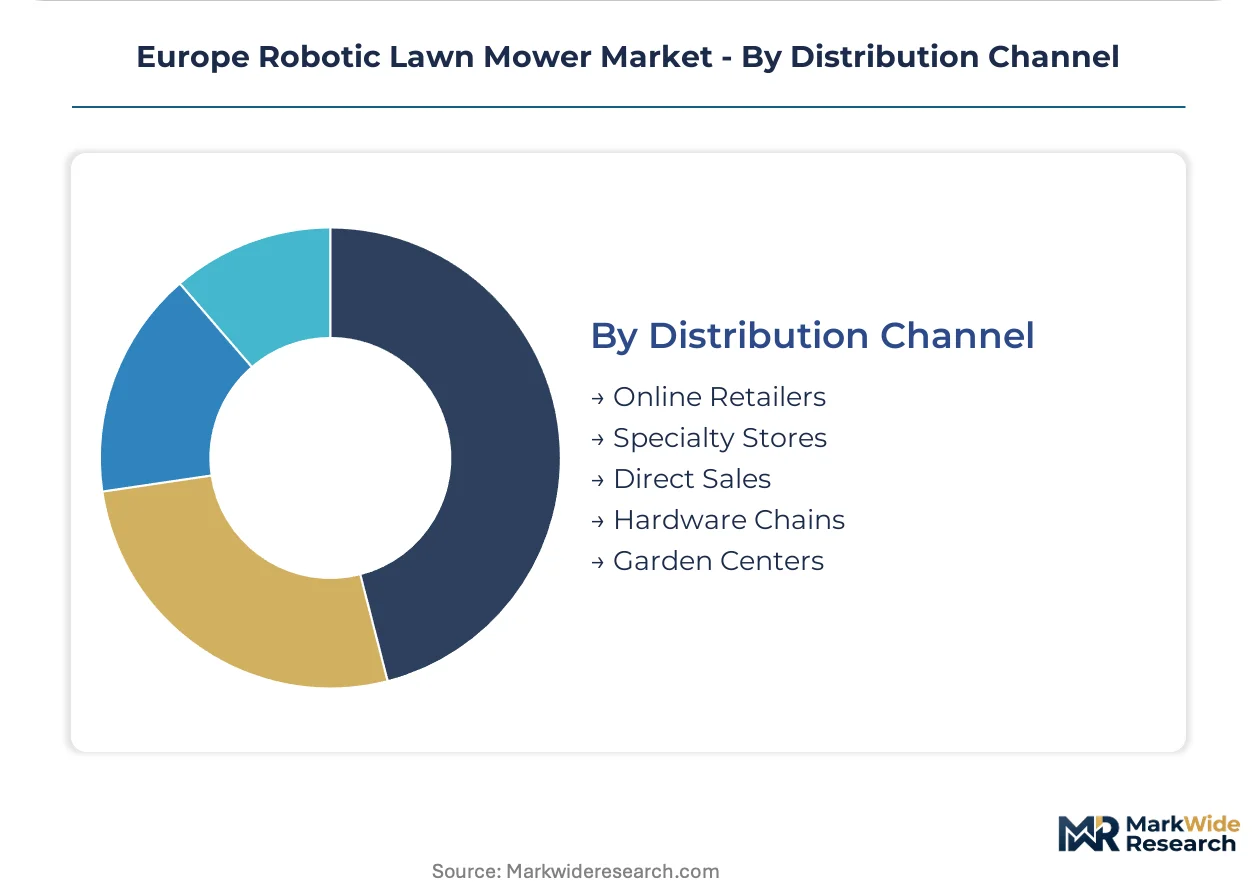
- Online Retailers:E-commerce platforms offer convenience, competitive pricing, and broad product selection, appealing to digitally savvy European consumers. This channel is gaining significant share, especially for standard and compact residential models, driven by direct-to-consumer strategies.
- Specialty Stores:These outlets provide expert advice, installation services, and dedicated after-sales support for complex or premium robotic mower systems. They cater to a discerning customer base across Europe, particularly for professional and advanced residential units.
- Direct Sales:Manufacturers directly engage large commercial clients or offer bespoke solutions, bypassing intermediaries for specific European B2B transactions.
- Hardware Chains:Large retail chains offer a convenient purchasing option for entry-level and standard residential mowers, reaching a wide European audience.
- Garden Centers:These centers provide a localized retail experience, often bundling sales with landscaping services for residential customers in various European countries.
Online Retailers are rapidly expanding their reach, while Specialty Stores maintain their position for higher-value sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Sweden lead European adoption of robotic lawn mowers, driven by affluent households and early technology embrace. Other European countries are rapidly catching up, fueled by urbanization and smaller garden sizes. This regional dynamic shapes market development across the continent.
Germany
Germany exhibits strong demand for robotic mowers from affluent households with private gardens. The country's strict noise pollution regulations encourage quiet electric alternatives. Munich and Stuttgart show high concentrations of smart home integration, boosting demand for connected devices.
France
France sees rising residential adoption, particularly in urban areas, due to convenience and green space maintenance. French municipal policies promoting eco-friendly landscaping support battery-powered mowers. Paris and Lyon are experiencing growth in professional landscaping services requiring advanced robotic solutions.
Netherlands
The Netherlands demonstrates high consumer readiness for subscription-based models and smart home integration. Dutch environmental policies favor zero-emission garden equipment, driving market expansion. Amsterdam and Utrecht feature digitally mature consumers readily adopting service-oriented technology.
Sweden
Sweden remains a pioneer in robotic mower adoption, with a high penetration rate in residential segments. Swedish government initiatives for smart city development encourage autonomous outdoor solutions. Stockholm and Gothenburg are hubs for early technology adopters and advanced system integration.
Poland
Poland represents a significant growth opportunity for robotic mowers, driven by increasing disposable incomes. The country's expanding middle class and growing interest in garden ownership fuel demand. Warsaw and Krakow are emerging markets for compact and standard residential models.
Europe Robotic Lawn Mower Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the European robotic lawn mower market. The competitive landscape features a mix of established garden equipment manufacturers and technology-focused innovators. This market structure shows a tiered approach, with premium, mid-range, and entry-level offerings catering to diverse consumer needs. Strategic partnerships, portfolio diversification, and continuous technological innovation are common competitive moves among these players to maintain relevance and expand their footprint.
Specialists in different segments, such as Husqvarna Group, exemplify market leadership through extensive dealer networks and strong brand recognition across Europe, particularly in the premium residential category. Robert Bosch GmbH occupies a position leveraging broad smart home integration capabilities, linking its mowers to a wider ecosystem of connected devices. STIHL represents the professional-grade segment, focusing on durable models tailored for demanding landscaping firms and commercial applications. These companies anchor various market niches, from premium residential solutions to high-margin commercial operations, shaping product development and market expectations through their distinct strategic approaches.
| Leading Market Players |
|---|
| Belrobotics |
| Zucchetti Centro Sistemi |
| Husqvarna Group |
| GGP STIGA |
| STIHL |
| Robert Bosch GmbH |
| Deere & Company |
| Kress Robotics |
| AL-KO Gardentech |
| Others |
Cost & Logistics Intelligence
EU Green Deal mandates for zero-emission garden equipment gate qualified supply and elevate premium-tier pricing access in the European robotic lawn mower market. Manufacturers face increased compliance costs for advanced battery and AI components.
Pricing Analysis
Capacity additions in Asian manufacturing hubs are reshaping price floors for entry-level robotic mowers. The European market primarily features a hybrid pricing model, combining upfront hardware sales with recurring software-as-a-service subscriptions. Price differentiation stems from established brand premium and advanced feature integration like AI navigation. Pricing pressure intensifies for standard models due to consumer initial capital outlay, making residential consumers of compact models highly price-sensitive. In contrast, professional firms prioritize operational efficiency and specialized performance, exhibiting lower price sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with Asian suppliers for critical electronic components and lithium-ion batteries. The European robotic mower supply chain draws heavily from manufacturing hubs in China and Germany for various sub-assemblies, including microcontrollers and specialized sensors. A structural risk arises from evolving EU regulatory restrictions, particularly the EU AI Act, impacting autonomous system components. Distribution runs through a hybrid model, balancing high-volume online retailers with specialized stores offering installation and after-sales support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European robotic lawn mower market presents a clear margin-expansion story. This trajectory is driven by the shift towards subscription-based software services, transforming one-time hardware sales into recurring revenue streams.
For Market Incumbents:Anchor existing dealer networks and brand recognition to defend premium residential market share against new technology entrants. Invest heavily in in-house AI development to comply with the EU AI Act and differentiate advanced navigation systems. This approach counters the threat of commoditization from lower-cost models. Leveraging control over distribution channels serves as a critical lever.
For New Entrants and Emerging Players:Smart home integrators represent a strategic channel partner for new entrants. Target the Eastern Europe residential market, particularly Poland and the Czech Republic, where garden ownership is rising and market penetration is low. Focus on offering subscription-based, wire-free autonomous models with simplified installation as a key go-to-market angle. This addresses the significant usability friction point of traditional boundary wires.
For Investors and Strategic Acquirers:Valuations sit cheapest among compact and standard model manufacturers lacking strong software integration. The market offers long-term viability over the next decade, driven by increasing urbanization and labor cost pressures in Europe. Target mid-sized technology specialists with proprietary AI navigation and robust software platforms as acquisition archetypes. The signal to watch is the rate of adoption of wire-free models in the premium residential segment.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop In-house AI Compliance Expertise | Ensures market access within the European Union by meeting rigorous EU AI Act standards for autonomous mowers. |
| Expand Subscription-based SaaS Offerings | Repackages revenue models from one-time hardware sales to recurring streams, enhancing customer lifetime value in Europe. |
| Target Eastern Europe Market Expansion | Captures growth opportunities in Poland and the Czech Republic, driven by rising disposable incomes and garden ownership. |
| Integrate with Fragmented Smart Home Ecosystems | Addresses interoperability challenges, boosting demand among affluent households in Germany and the Nordic countries. |
| Invest in Advanced Battery Technology | Extends runtime and improves charging cycles, making robotic mowers more practical for diverse European garden sizes. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with extensive secondary validation. Primary stakeholders included product development executives, landscaping firm owners, specialty store managers, and smart home integrators. Secondary data encompassed EU regulatory reports, industry association publications, and financial filings of key players. This approach allowed for robust bottom-up and top-down triangulation of market data.
The forecast window was anchored to historical reference periods, establishing a baseline for future projections across the modeling period. Segmentation dimensions modeled included product type, technology, end-user, distribution channel, and key European geographies. Compound Annual Growth Rates were derived through regression analysis and expert consensus. Industry-specific inputs included battery technology advancements and EU AI Act compliance timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to evolving EU regulations and raw material supply chain disruptions. These forecasts reflect underlying assumptions about consumer adoption rates and technological innovation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
United Kingdom Homeware Market
Home & Garden
Lawn and Gardening Consumables Market
Home & Garden
Christmas Decorations Market
Home & Garden
Landscaping Services Market
Home & Garden
North America Flowerpots Market
Home & Garden
Flexible Garden Hoses Market
Home & Garden
Preserved Flowers Market
Home & Garden
Aquarium Decor Market
Home & Garden
US Garden Planter Market
Home & Garden
Artificial Plants Market
Home & Garden
Global Wind Chime Market
Home & Garden
Flower Box Market
Home & Garden
Lawn and Garden Water Equipment Market
Home & Garden
Incense Market
Home & Garden
Electric Lawn Mower Market
Home & Garden
United States Landscaping Market