
 Landscaping Products Market | 2026-2036
Landscaping Products Market Size, Share, and Industry Trends Forecast 2026-2036
Landscaping Products Market Intelligence
Consolidation among municipal buyers and the rise of large-scale commercial property managers is realigning procurement patterns across the industry. Home Depot leverages its national footprint and integrated supply chain to dominate retail distribution. Heidelberg Materials anchors bulk supply for hardscape and aggregate segments through its quarry and ready-mix network. ecoDynamics differentiates by specializing in sustainable soil and organic amendments for environmentally certified projects.
Landscaping products encompass living and non-living materials used to modify outdoor terrain, including plants selected for USDA hardiness zones, engineered soils with specified pH and porosity profiles, hand and power tools rated by torque and blade specifications, and controlled-release fertilizers formulated for seasonal nutrient delivery. These products serve to enhance aesthetic value, manage stormwater runoff, and maintain ecological balance across built environments. Plants and soil together occupy the largest margin pool due to repeat purchase frequency and seasonal replenishment cycles, while tools sustain premium pricing through durability branding and warranty differentiation. The irrigation application segment is gaining structural importance as drought-responsive technologies displace conventional sprinkler systems in water-stressed municipalities.
EPA fertilizer labeling standards under the Federal Insecticide, Fungicide, and Rodenticide Act shape product formulation and interstate commerce, while OSHA workplace safety rules govern equipment manufacturing and commercial landscaping operations. State-level water restrictions in California, Arizona, and Texas are forcing manufacturers to redesign irrigation products for efficiency certification. Stakeholders must monitor how evolving municipal procurement standards for low-impact development will reshape product specifications and vendor qualification requirements.
Market Dynamics
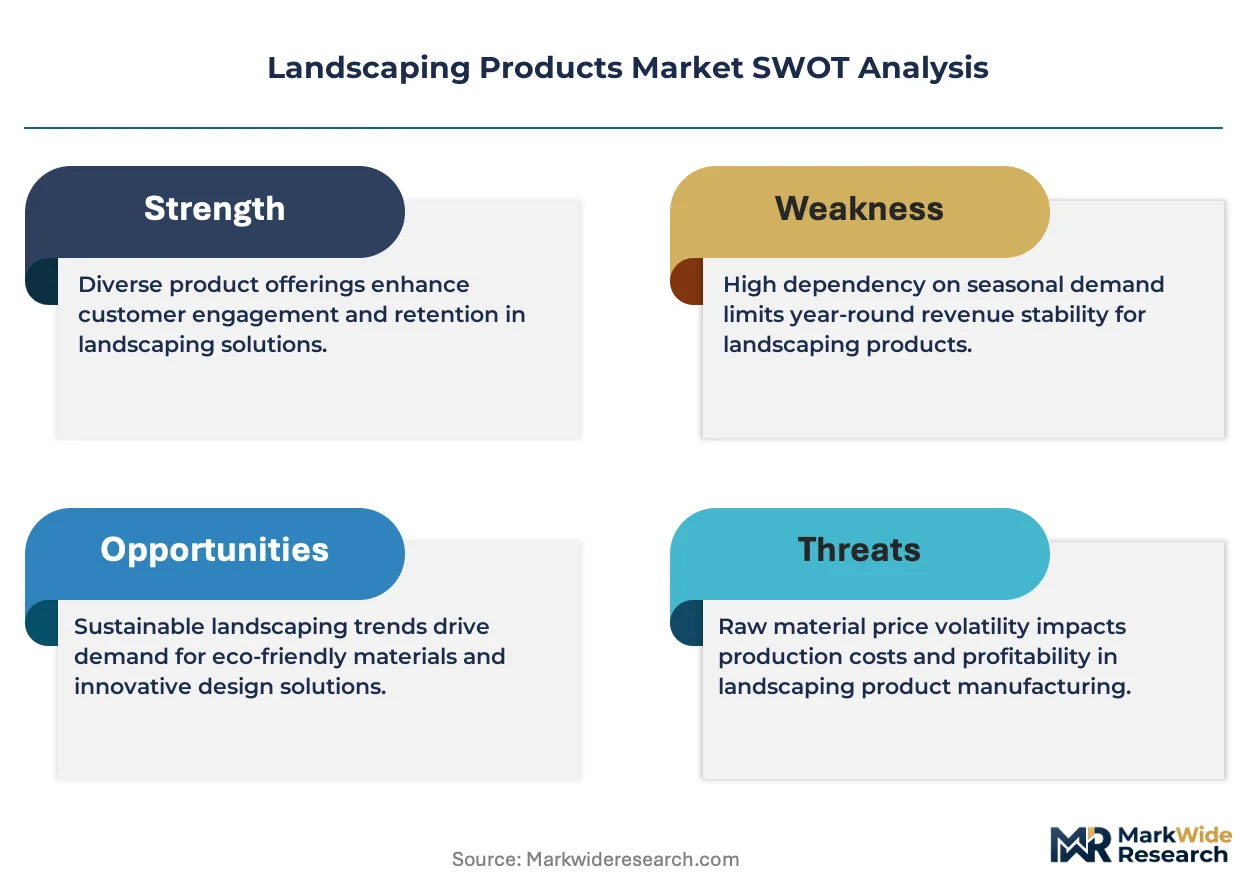
Water-use restrictions across Sun Belt states are compressing demand toward drought-tolerant product lines and forcing irrigation manufacturers to redesign for efficiency certification. EPA fertilizer runoff rules and municipal procurement standards for low-impact development are simultaneously reshaping formulation requirements and vendor qualification criteria.
Growth Catalysts
- EPA WaterSense Certification:Municipal rebate programs in Arizona, Texas, and California accelerate replacement of conventional sprinkler systems with smart irrigation controllers. Commercial property managers now specify efficiency-labeled products as standard procurement practice.
- Suburban Outdoor Living Investment:Residential property owners in North American suburbs are expanding hardscape and living space installations. Deck, patio, and outdoor kitchen projects drive repeat purchases of engineered soils and decorative aggregates.
- Controlled-Release Fertilizer Chemistry:Polymer-coated and stabilized nitrogen formulations reduce application frequency while complying with state-level nutrient management plans. Golf course and sports turf managers prioritize these products for labor cost containment.
Market Restraints
- Peat Moss Supply Concentration:Canada supplies over 90% of North American horticultural peat. Harvest moratoria in Manitoba and Quebec provinces constrain growing medium formulation flexibility and inflate input costs for soil blenders.
- Steel and Aluminum Price Volatility:Hand tool and power equipment manufacturers face margin compression from commodity metal fluctuations. Tariff exposure on Chinese-sourced components amplifies cost uncertainty for mid-tier brands.
- Technical Limitation of Battery Runtime:Cordless outdoor power equipment lacks sufficient energy density for full-day commercial landscaping operations. Gasoline-powered alternatives retain dominance in municipal and large-scale maintenance contracts.
Strategic Opportunities
- Urban Heat Island Mitigation Mandates:Chicago, Los Angeles, and Miami zoning codes now require vegetated surfaces on new commercial construction. Green roof and living wall specifications create demand for lightweight engineered growing media.
- Soil Sensor and IoT Convergence:Moisture and nutrient monitoring hardware integrates with cloud-based irrigation scheduling platforms. Landscape maintenance contractors adopt subscription-enabled predictive watering to differentiate service offerings.
- Direct-to-Contractor E-Commerce:Specialized distributors bypass traditional two-step distribution by serving commercial landscapers through mobile-optimized ordering platforms. Bulk aggregate and amendment purchases shift toward digital procurement with scheduled jobsite delivery.
Industry Challenges
- Skilled Equipment Technician Shortage:Diagnostic and repair expertise for computerized irrigation controllers and battery-powered tools lags behind product complexity. Manufacturers expand in-house training programs to offset dealer service capacity constraints.
- Organic Input Certification Timelines:OMRI and state organic program approvals for new soil amendments require 18-24 month review cycles. Product development pipelines misalign with seasonal selling windows.
- Legacy System Integration Friction:Smart irrigation retrofits encounter compatibility gaps with existing valve wiring and hydraulic zones. Installation contractors absorb unexpected labor costs when upgrading decades-old infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Landscaping Products Market |
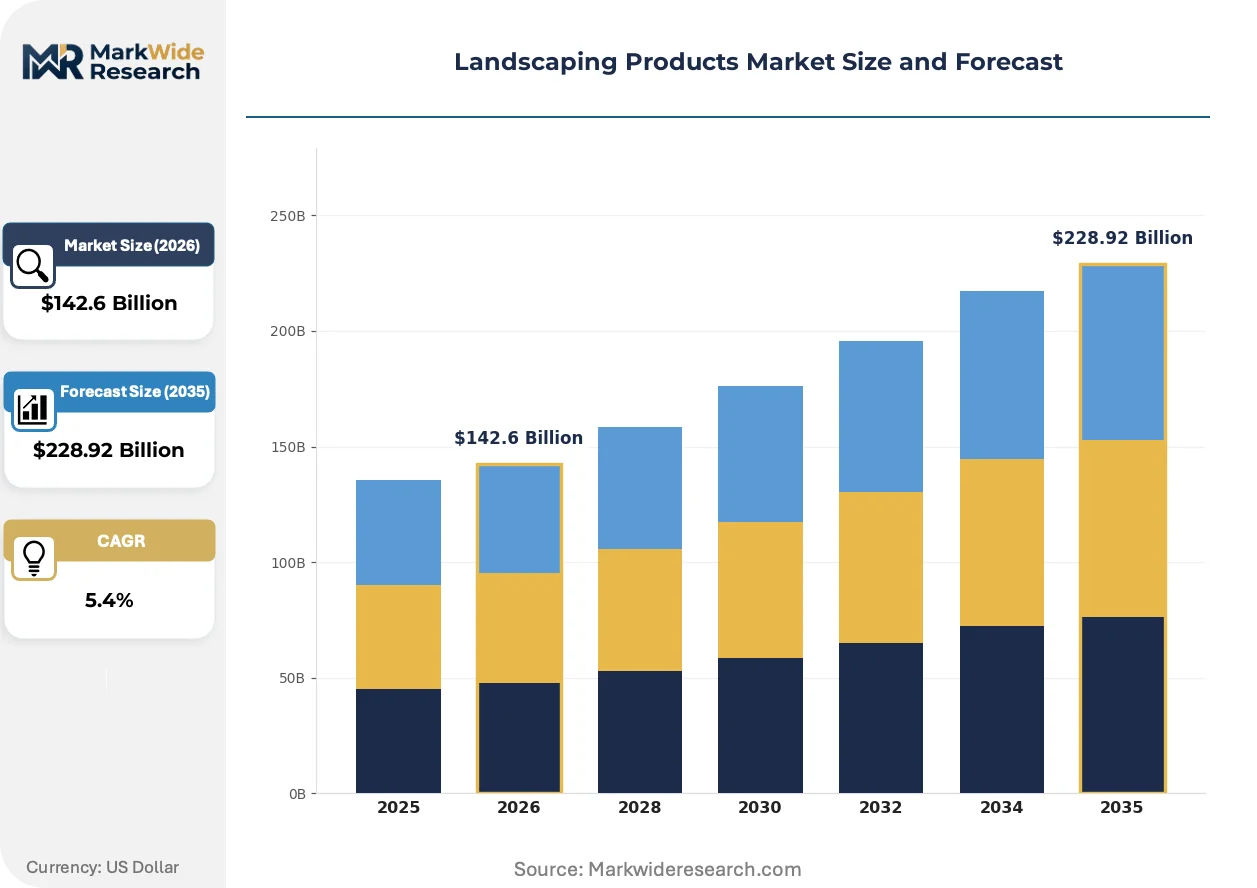
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $228.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plants, Soil, Tools, Fertilizers End User: Residential, Commercial, Municipal, Institutional Distribution Channel: Online, Retail, Wholesale, Garden Centers Application: Gardening, Lawn Care, Landscape Design, Irrigation |
| Companies Covered | Griffon Corporation Inc., Kafka Granite LLC, Home Depot, Henri Studio, Haddonstone, Heidelberg Materials, The QUIKRETE Companies, ecoDynamics, Oldcastle APG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Landscaping Products Market Strategic Shifts & Innovations
Product development trajectories center on water efficiency compliance, biological input substitution, and digital connectivity for maintenance automation. Manufacturers are repositioning around regulatory thresholds rather than performance differentiation alone.
Precision soil moisture sensing is converging with cloud-based weather data integration to enable predictive irrigation scheduling. Large-scale commercial property managers and municipal parks departments adopt these systems fastest, driven by utility rebate eligibility and staff reduction targets. The technology compresses demand for conventional timer-based controllers and shifts margin toward hardware-software bundled offerings.
California's Model Water Efficient Landscape Ordinance and similar statutes in Nevada and Colorado now mandate soil moisture sensors or evapotranspiration-based controllers for new construction and renovation permits exceeding specified square footage. Manufacturers must redesign product lines to achieve certification under multiple state testing protocols simultaneously. The irrigation application segment bears the heaviest compliance burden, with specification writers increasingly disqualifying non-certified alternatives from bid pools.
Consolidation among municipal buyers and institutional property managers concentrates purchasing power into fewer decision-makers with standardized specification templates. National account contracts with integrated facility services firms displace fragmented local procurement for maintenance supplies. The Sun Belt states exhibit this pattern most acutely, where year-round growing seasons justify dedicated procurement staff and centralized vendor management systems.
Landscaping Products Market Segmentation
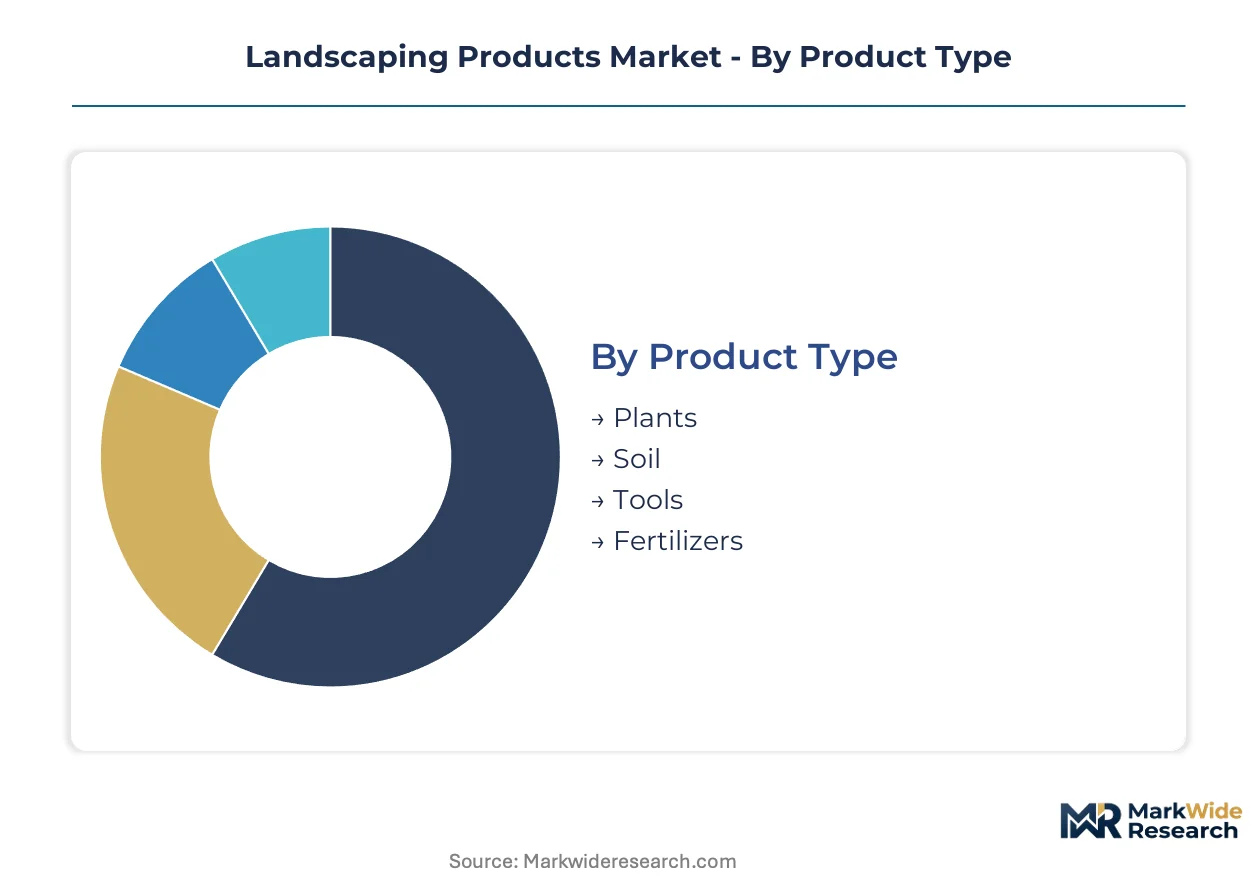
Segmentation in landscaping products reveals divergent margin structures and procurement rhythms across living materials, durable equipment, and chemical inputs. Product type determines replenishment frequency and seasonality, while end-user classification exposes sharply different specification authority and contract scale.
Product Type:
Customization intensity varies from commodity bulk soils to precision-engineered growing media with specified porosity and pH profiles.
- Plants:Nursery stock selected for USDA hardiness zones and drought tolerance ratings dominates suburban retrofit demand in Texas, Arizona, and California. Sun Belt municipalities specify native and adaptive species for water-restricted medians and park renovations.
- Soil:Engineered blends with controlled drainage characteristics command premium positioning for green roof and stormwater bioretention installations. Chicago, Los Angeles, and Miami zoning mandates now require lightweight growing media for vegetated surface minimums on commercial construction.
- Tools:Hand and power equipment rated by torque, blade specifications, and battery platform compatibility serve differentiated customer tiers.
- Fertilizers:Controlled-release and stabilized nitrogen formulations reduce application frequency while meeting state nutrient management compliance.
Most installed capacity flows through Plants. Expansion is steepest in Soil.
End User:
Contract scale and specification authority separate fragmented residential decision-making from centralized municipal procurement.
- Residential:Suburban property owners in North American Sun Belt states drive repeat purchases for outdoor living expansions including decks, patios, and outdoor kitchens. EPA WaterSense rebate eligibility shapes irrigation controller selection.
- Commercial:Large-scale property managers consolidate vendor relationships through national account contracts with integrated facility services firms. Standardized specification templates displace fragmented local procurement for maintenance supplies.
- Municipal:Parks departments and public works agencies concentrate purchasing power through centralized procurement staff and vendor management systems. Year-round growing seasons in southern states justify dedicated specification resources.
- Institutional:University and healthcare campuses maintain specialized grounds management with sustainability certification requirements.
Commercial buyers capture the deepest volume discounts. Municipal procurement is climbing the fastest.
Distribution Channel:
Channel selection tracks order size, delivery urgency, and technical support requirements across the customer base.
- Online:Direct-to-contractor platforms enable mobile-optimized ordering with scheduled jobsite delivery for bulk aggregate and amendment purchases. Commercial landscapers bypass traditional two-step distribution for efficiency.
- Retail:National home improvement chains leverage integrated supply chains and geographic footprint for residential project materials. Seasonal merchandising drives impulse purchases of living plants and decorative hardscape.
- Wholesale:Specialized distributors serve commercial accounts with volume pricing and technical specification support.
- Garden Centers:Independent retailers provide localized plant varieties and hands-on customer service for hobbyist gardeners.
Retail channels move the highest transaction volume. Online platforms are gaining share fastest.
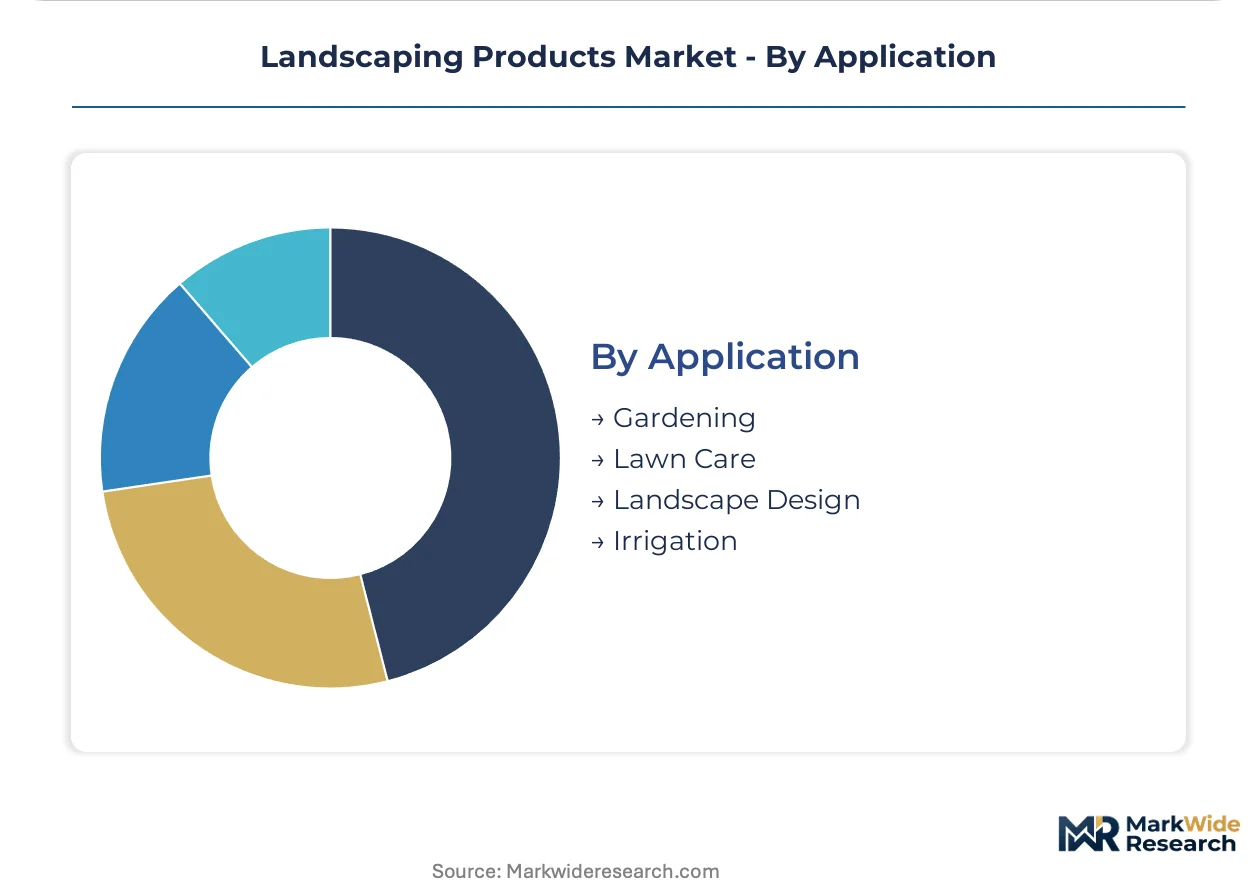
Application:
Water efficiency compliance and automation potential differentiate mature maintenance categories from technology-adopting irrigation systems.
- Gardening:Ornamental and edible plant cultivation drives seasonal replenishment of living materials and soil amendments. Hobbyist and semi-professional segments sustain garden center traffic.
- Lawn Care:Turf maintenance contracts for sports facilities and residential properties sustain demand for fertilizers and mowing equipment. Golf course managers prioritize controlled-release formulations for labor cost containment.
- Landscape Design:Hardscape installation and outdoor living construction projects generate one-time bulk purchases of aggregates, engineered soils, and decorative materials.
- Irrigation:Smart controllers with soil moisture sensing and cloud-based weather integration displace conventional timer-based systems. California, Nevada, and Colorado statutes mandate efficiency-certified equipment for permits exceeding specified square footage.
Lawn Care maintains the largest installed base. Irrigation is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates residential outdoor living investment while Canada dominates peat moss supply for North American soil blenders. Germany anchors European engineered hardscape exports. Australia and the United Kingdom represent distinct regulatory environments for water-efficient landscaping mandates.
United States
Suburban property owners in Texas, Arizona, and California drive repeat purchases for deck and patio expansions. EPA WaterSense certification requirements shape municipal rebate programs for smart irrigation controllers. The Sun Belt corridor from Phoenix to Miami concentrates demand for drought-tolerant nursery stock and native plant specifications.
Canada
Manitoba and Quebec peat harvest operations supply over 90 percent of North American horticultural growing medium inputs. Provincial harvest moratoria constrain formulation flexibility for soil blenders. Ontario-based distributors anchor cross-border supply chains serving US Midwest commercial landscaping contractors.
Germany
Engineered hardscape manufacturers export precision-cut aggregates and decorative stone across European markets. REACH chemical regulations and CE marking requirements shape fertilizer and soil amendment formulation standards. The North Rhine-Westphalia industrial cluster concentrates production of polymer-coated controlled-release fertilizers.
Australia
Water restrictions in New South Wales and Victoria accelerate displacement of conventional sprinkler systems with soil moisture-sensing technologies. State-level plumbing codes mandate efficiency certification for irrigation equipment in new commercial construction. Sydney and Melbourne metropolitan councils specify lightweight engineered soils for green roof installations.
United Kingdom
Hobbyist gardeners sustain garden center traffic for ornamental and edible plant cultivation. Environment Agency nutrient management regulations constrain fertilizer application rates for sports turf and golf course maintenance. The Southeast England nursery corridor supplies container-grown stock for domestic landscape design projects.
Landscaping Products Market Key Industry Players
North American producers anchor the retail distribution tier; European specialists hold premium positioning in engineered hardscape segments. The vendor base separates into consolidated national chains, bulk material suppliers with captive quarry networks, and sustainability-certified niche formulators. Three archetypes dominate: integrated home improvement retailers, vertically integrated aggregate producers, and organic amendment specialists. Competitive moves concentrate on national account contract consolidation and efficiency certification portfolio expansion.
Within the integrated retail tier, Home Depot exemplifies geographic footprint leverage and supply chain integration. Heidelberg Materials occupies a position representing bulk hardscape and aggregate supply through quarry and ready-mix networks. ecoDynamics sits within the sustainability-certified specialist archetype, anchoring organic amendment positioning for environmentally certified projects.
| Leading Market Players |
|---|
| Griffon Corporation Inc. |
| Kafka Granite LLC |
| Home Depot |
| Henri Studio |
| Haddonstone |
| Heidelberg Materials |
| The QUIKRETE Companies |
| ecoDynamics |
| Oldcastle APG |
| Others |
Cost & Logistics Intelligence
EPA WaterSense rebate programs in Arizona, Texas, and California are compressing demand toward certified smart irrigation controllers, forcing manufacturers to absorb certification testing costs while distributors consolidate procurement around efficiency-labeled portfolios. This specification tightening concentrates purchasing power among large-scale commercial property managers and municipal buyers, reshaping margin distribution across supply tiers.
Pricing Analysis
Capacity additions in China and Vietnam are reshaping price floors for battery-powered outdoor equipment and metal hand tools. Three-tier pricing structure across premium, standard, and economy levels separates professional-grade torque-rated equipment with extended warranties from entry-level consumer tools. Cost compression in the standard tier is intensifying because tariff exposure on Chinese-sourced aluminum and steel components amplifies input volatility. Municipal buyers exhibit the lowest price sensitivity due to rebate eligibility and specification mandates, while residential hobbyists drive volume through seasonal promotional cycles.
Supply Chain Analysis
Single-source vulnerability sits with Canadian peat moss harvesters supplying over ninety percent of North American horticultural growing medium inputs. Manufacturing draws from China for battery cells and injection-molded plastics, Mexico for aluminum extrusions, and Canada for peat and engineered wood fibers. Tariff exposure on Chinese-sourced components presents the dominant structural risk for mid-tier equipment brands. Distribution runs through integrated home improvement chains for residential volume, specialized distributors for commercial specification support, and direct-to-contractor platforms for bulk aggregate and amendment procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Landscaping Products Market reads as a late-cycle quality story where municipal procurement standards and EPA efficiency mandates are concentrating demand around certified, durable equipment and engineered growing media with documented performance specifications.
For Market Incumbents: Extend certification portfolios across multiple state testing protocols simultaneously to maintain bid pool eligibility as California, Nevada, and Colorado statutes harden efficiency mandates. Deepen upstream control over peat-alternative substrate formulations to offset Canadian harvest moratoria constraining input flexibility. Prioritize national account contract consolidation with integrated facility services firms displacing fragmented local procurement. For New Entrants and Emerging Players: Launch via direct-to-contractor e-commerce platforms serving commercial landscapers with mobile-optimized ordering and scheduled jobsite delivery, bypassing traditional two-step distribution. Target lightweight engineered growing media for green roof installations in Chicago, Los Angeles, and Miami where zoning mandates now require vegetated surface minimums. Differentiate through soil sensor and IoT convergence offerings with subscription-enabled predictive watering. For Investors and Strategic Acquirers: Asymmetric upside sits with sustainability-certified organic amendment specialists holding OMRI-approved formulations for environmentally certified institutional projects. Long-term viability favors archetypes with captive raw material positions or proprietary polymer-coated fertilizer chemistry. Watch for inflection when municipal procurement standards for low-impact development reshape vendor qualification requirements and consolidate specification authority.| Strategic Initiative | Industry Significance |
|---|---|
| Efficiency Certification Portfolio Expansion | Multi-state WaterSense and EPA compliance maintains bid pool access for irrigation manufacturers. |
| Backward Integration into Peat Alternatives | Coconut coir and composted bark sourcing reduces Canadian supply concentration risk for soil blenders. |
| Direct-to-Contractor Platform Launch | Digital procurement with scheduled delivery captures commercial landscaper volume from traditional distribution. |
| Soil Sensor and IoT Convergence | Hardware-software bundled offerings shift margin from conventional timer-based controllers in municipal parks. |
| National Account Contract Consolidation | Integrated facility services partnerships displace fragmented local procurement for maintenance supplies. |
Research Approach
Bottom-up residential and commercial property modeling reconciled against top-down quarry network and nursery stock tracking forms the analytical core. Primary interviews with municipal procurement officers, commercial property managers, irrigation contractors, soil blender plant managers, and garden center operators combined with secondary validation from EPA WaterSense certification databases, state-level nutrient management plan filings, customs and trade data on peat and fertilizer imports, and SEC 10-K disclosures from listed building materials firms. Triangulation across these sources anchored volume and value estimates.
Input-output matrices mapped product-type demand against end-user procurement rhythms and distribution channel throughput across the projection horizon. Segmentation dimensions modeled include product type, end-user classification, application, and distribution channel, with regional regulatory clusters capturing state-level water restriction severity. CAGRs derived from trend-line extrapolation of replacement cycles, rebate program adoption curves, and construction permit data, cross-referenced against hardscape and aggregate production capacity announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained drought conditions accelerating water-use restrictions or prolonged peat harvest moratoria constraining growing medium formulation. Forecasts reflect documented assumptions about rebate program continuity, municipal procurement standard evolution, and battery energy density improvement trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
North America Flowerpots Market
Home & Garden
Landscaping and Gardening Service Market
Home & Garden
Candle Market
Home & Garden
Aquarium Decor Market
Home & Garden
Artificial Flowers Market
Home & Garden
Lawn and Garden Consumables Market
Home & Garden
Global Wind Chime Market
Home & Garden
United Kingdom Homeware Market
Home & Garden
Global Motorized and Smart Awnings Market
Home & Garden
Bird House Market
Home & Garden
North America Floral Gifting Market
Home & Garden
Europe Robotic Lawn Mower Market
Home & Garden
Wine Racks Market
Home & Garden
Flowerpots and Planters Market
Home & Garden
Outdoor Cooking Table Market
Home & Garden
Landscaping Services Market